
 Global Whole Genome Sequencing (WGS) Market | 2026-2036
Global Whole Genome Sequencing (WGS) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Whole Genome Sequencing (WGS) Market Foresight
Reference-grade accuracy thresholds is unwinding the competitive baseline across the WGS landscape. Illumina sustains dominant manufacturing scale in high-throughput short-read systems. Pacific Biosciences differentiates through long-read fidelity for complex structural variant detection. Oxford Nanopore leverages portable, real-time sequencing architectures that extend field-deployable applications.
Whole genome sequencing denotes the comprehensive determination of an organism's complete DNA sequence, typically achieving coverage depths exceeding 30x for clinical-grade variant calling using massively parallel or single-molecule detection chemistries. Its primary commercial purpose centers on identifying pathogenic mutations, pharmacogenomic markers, and somatic alterations to inform diagnostic, therapeutic, and research decisions. Reagents and consumables capture the largest recurring revenue pool as instrument-installed bases expand. Cancer genomics applications are outpacing genetic disease research in absolute growth velocity. Cloud-based deployment models are displacing on-premise infrastructure among mid-tier academic centers seeking elastic compute access.
FDA guidance documents on NGS-based oncology panels and germline variant classification shape product development timelines and clinical validation requirements in the United States. EMA's In Vitro Diagnostic Regulation and CE marking pathways govern commercial access across European member states, while China's NMPA accelerates review channels for innovative sequencing instruments. Stakeholders must monitor evolving payer coverage determinations and data governance standards as clinical WGS transitions from research subsidy to reimbursed standard of care.
Market Dynamics
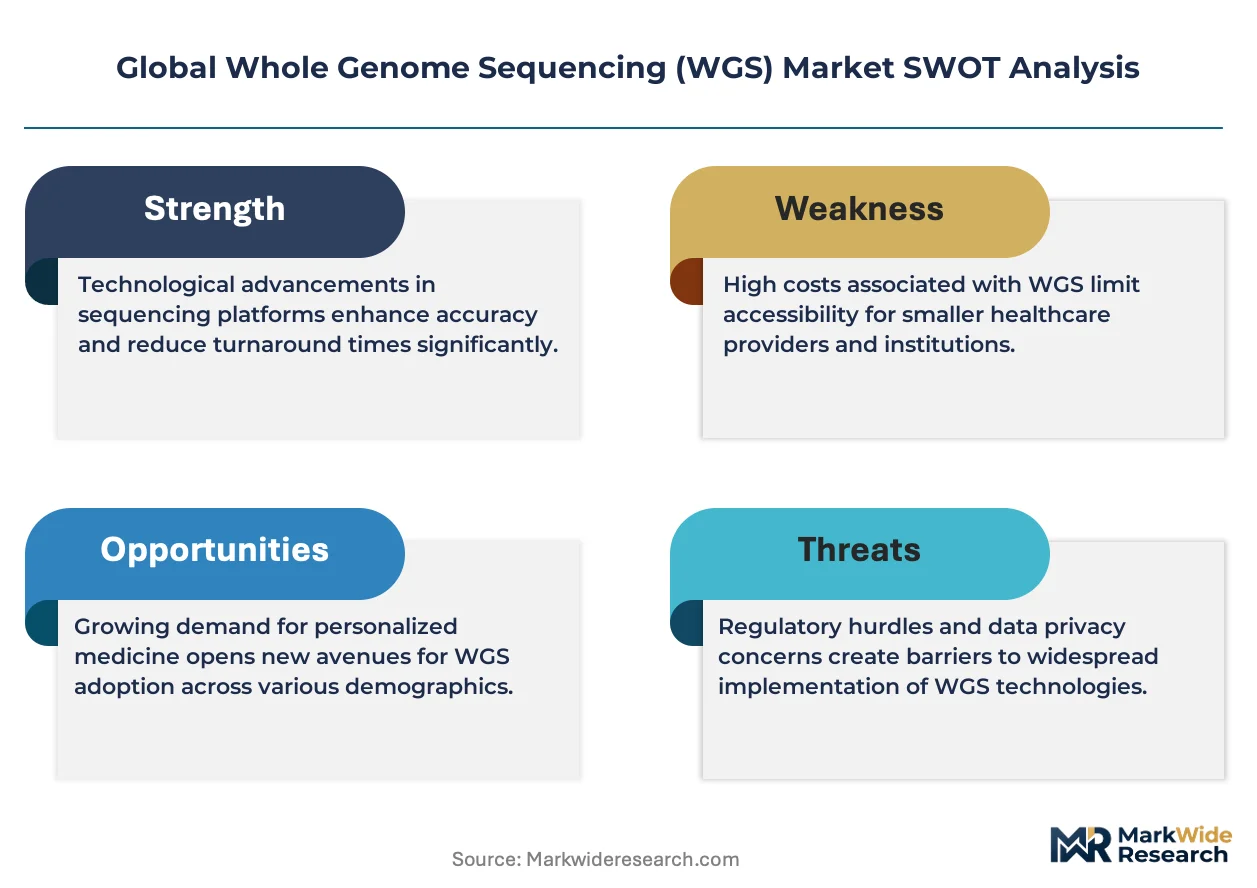
Reference-grade accuracy thresholds are compressing competitive differentiation as short-read, long-read, and real-time platforms converge on clinical-grade variant detection. This technical convergence is forcing vendors to compete on workflow integration and total cost per genome rather than raw chemistry performance alone.
Growth Catalysts
- Reimbursement clarity from FDA guidance:The agency's NGS-based oncology panel frameworks are clarifying coverage pathways for clinical diagnostic laboratories, reducing commercial uncertainty for test developers.
- Cancer genomics demand acceleration:Oncology applications are outpacing inherited disease research in absolute expansion velocity as oncologists integrate somatic profiling into treatment selection.
- Cloud infrastructure elasticity:Mid-tier academic centers are migrating from on-premise compute clusters to elastic cloud architectures, lowering capital barriers to high-throughput analysis.
Market Restraints
- Reagent supply concentration:Critical sequencing chemistries and flow cell manufacturing remain concentrated among a limited supplier base, creating vulnerability to production disruptions.
- EMA In Vitro Diagnostic Regulation friction:The MDR transition is extending CE marking timelines for novel sequencing instruments, delaying European commercial launches.
- Technical substitution from targeted panels:Exome and gene panel tests offer sufficient diagnostic yield for many clinical indications at lower per-sample cost than WGS.
Strategic Opportunities
- Underpenetrated hospital networks in India:The country's PLI scheme for medical devices is attracting sequencing infrastructure investment as private hospital chains build molecular pathology capabilities.
- Pharmacogenomic integration:Drug-gene interaction databases are expanding, creating white space for preemptive genotyping programs in health systems.
- Convergence of AI and variant interpretation:Machine learning classifiers are automating variant pathogenicity scoring, compressing analysis timelines for clinical reporting.
Industry Challenges
- Bioinformatics talent scarcity:Clinical laboratories face acute shortages of variant scientists capable of bridging wet-lab sequencing and diagnostic reporting.
- HIPAA compliance complexity:Cloud-based genomic data architectures require rigorous access controls and audit trails, extending implementation timelines for US health systems.
- Legacy LIS integration friction:Connecting sequencing pipelines to established laboratory information systems demands custom middleware development, inflating deployment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Whole Genome Sequencing (WGS) Market |
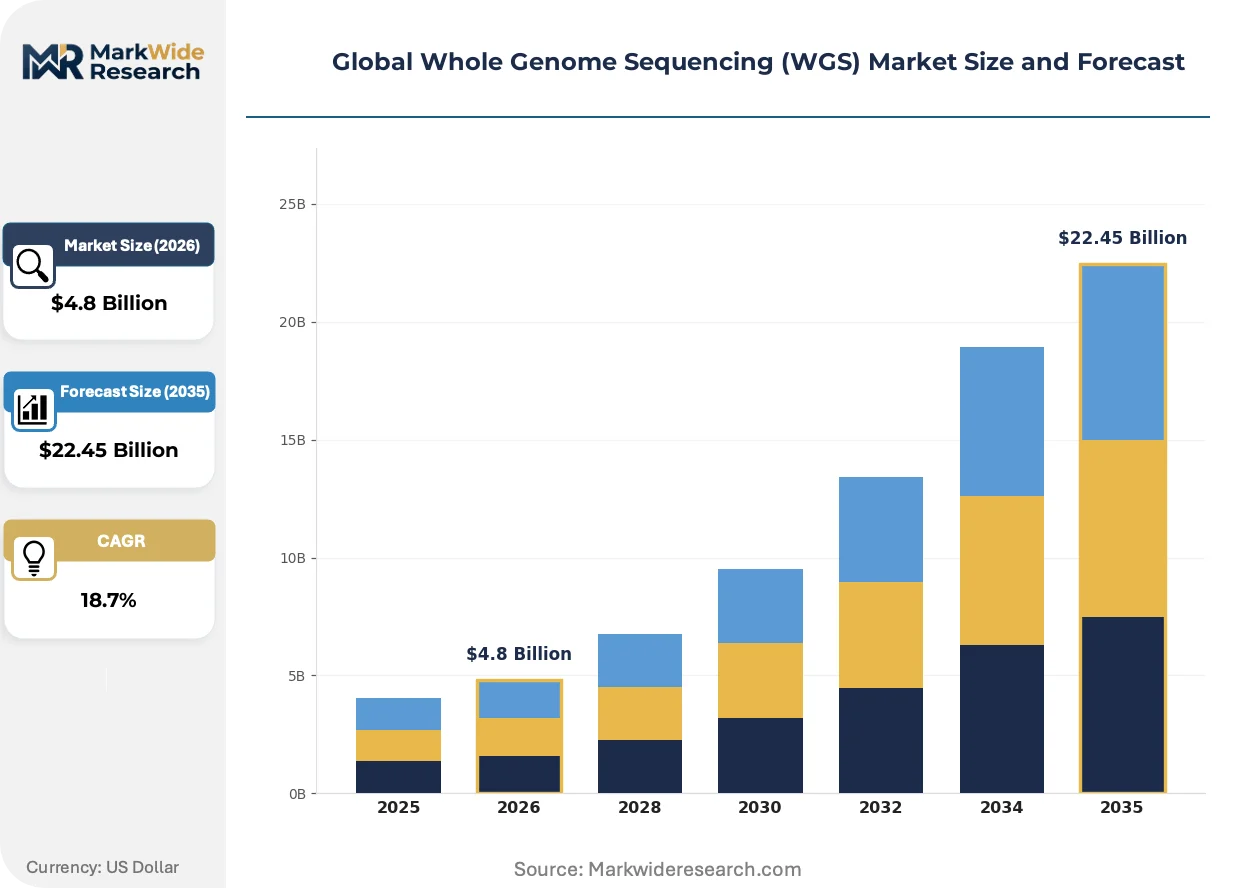
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analytical Instruments, Reagents, Consumables, Software Platforms, Services Application: Genetic Disease Research, Cancer Genomics, Microbial Genomics, Agricultural Biotechnology, Evolutionary Biology End User: Research Institutions, Biopharmaceutical Companies, Diagnostic Laboratories, Academic Centers, Government Agencies Deployment Model: On-Premise, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Oxford Nanopore, Ultima Genomics, Illumina, Danaher Corporation, 10x Genomics, Thermo Fisher Scientific, Agilent Technologies, Bio-Rad Laboratories, Pacific Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Whole Genome Sequencing (WGS) Market Shifts & Advancements
Platform diversification is fragmenting the technical consensus that once favored centralized high-throughput installations. Vendors now compete across distributed, point-of-care, and cloud-native architectures simultaneously.
Long-read sequencing chemistry is fragmenting the structural variant detection landscape. Pacific Biosciences' HiFi reads and Oxford Nanopore's duplex sequencing are achieving Q30+ accuracy for complex genomic rearrangements. Pediatric genetics centers and cancer diagnostic laboratories are adopting these platforms for cases where short-read ambiguity limits clinical resolution. The technology is fragmenting the prior assumption that short-read dominance would persist across all application categories.
China's NMPA has established accelerated review channels for innovative sequencing instruments, compressing regulatory timelines for domestic manufacturers. This policy shift is enabling faster product iteration cycles and earlier commercial access for novel chemistries. Multinational vendors are responding by expanding local clinical validation partnerships and manufacturing presence to qualify for these expedited pathways.
Hospital procurement committees are consolidating vendor relationships through multi-year sequencing service contracts rather than instrument purchases. Academic medical centers and integrated delivery networks are negotiating bundled reagent, software, and bioinformatics support agreements. This purchasing pattern shift is most pronounced in the United States, where health system consolidation has concentrated buying power among a limited number of IDN procurement functions.
Global Whole Genome Sequencing (WGS) Market Segmentation
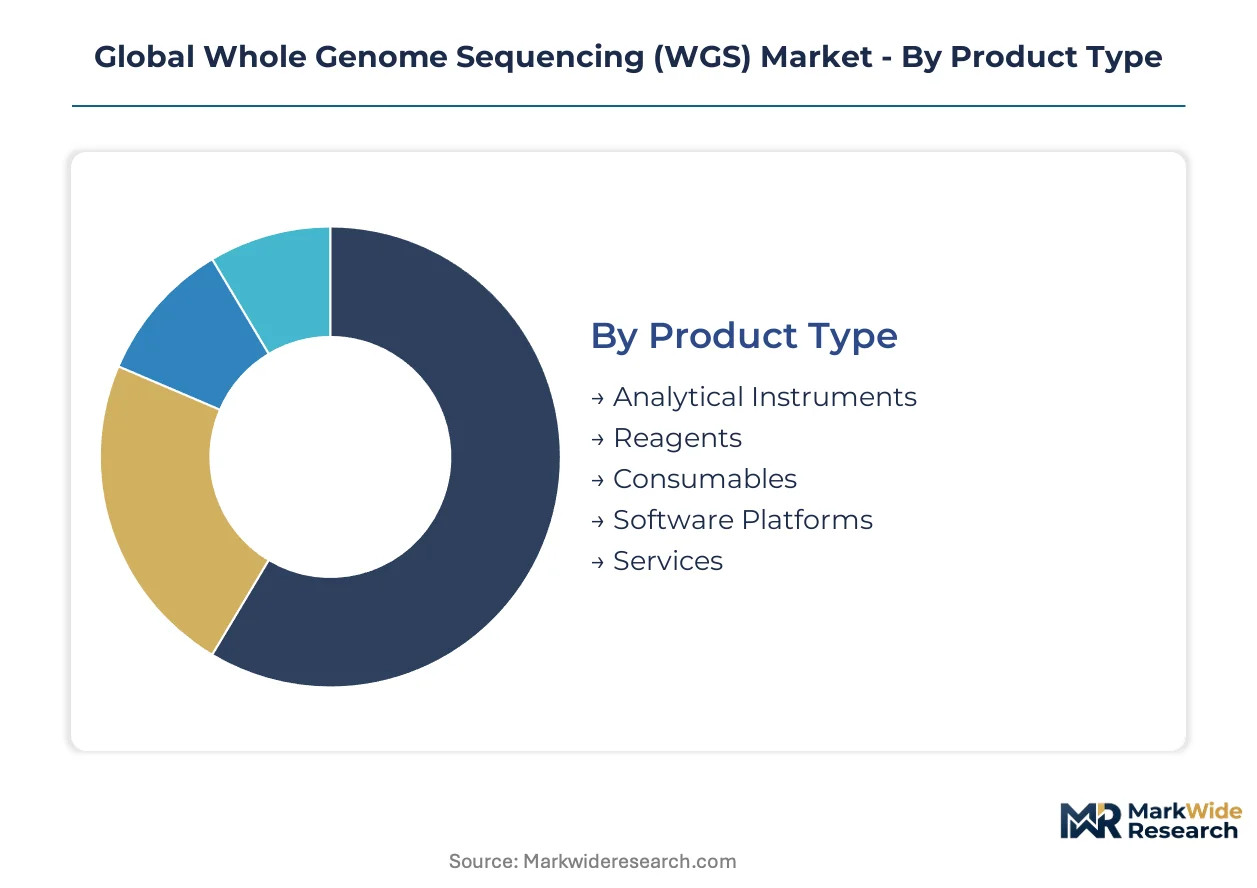
Segmentation in whole genome sequencing reveals how regulatory pathways, cost structures, and compute architectures fragment demand across customer types. Product mix and deployment choices diverge sharply between reimbursed clinical workflows and grant-funded research programs.
Product Type:
FDA's NGS-based oncology panel guidance and EMA's MDR implementation create divergent compliance burdens across product categories, shaping where vendors concentrate development resources.
- Reagents and Consumables:Flow cells, library preparation kits, and sequencing chemistries constitute the recurring revenue anchor as installed instrument bases expand. Clinical diagnostic laboratories in the United States drive disproportionate volume as private payer coverage for somatic profiling broadens.
- Analytical Instruments:High-throughput sequencers, sample preparation systems, and quality control platforms require capital-intensive validation against FDA-recognized standards. China's NMPA accelerated review channels are compressing commercialization timelines for domestic manufacturers seeking to challenge entrenched suppliers.
- Software Platforms:Variant calling pipelines, interpretation interfaces, and laboratory information system connectors automate diagnostic reporting workflows.
- Services:Contract sequencing, bioinformatics analysis, and clinical interpretation support lower capital barriers for mid-tier academic centers.
Established volume favors reagents and consumables; emerging adoption favors software platforms.
Application:
Cancer genomics commands premium pricing per sample while microbial and agricultural applications compete on throughput scale and operational cost efficiency.
- Cancer Genomics:Somatic mutation profiling, circulating tumor DNA analysis, and minimal residual disease monitoring guide therapeutic selection in oncology practice. United States health systems are integrating WGS into precision medicine programs as CMS and commercial payers clarify coverage determinations.
- Genetic Disease Research:Rare disease diagnosis, carrier screening, and newborn sequencing programs leverage WGS for comprehensive variant detection. Academic medical centers in Germany and France are building national infrastructure for undiagnosed disease networks under EMA-aligned quality frameworks.
- Microbial Genomics:Pathogen surveillance, antimicrobial resistance profiling, and outbreak tracing support public health applications.
- Agricultural Biotechnology:Crop improvement, livestock breeding, and food safety testing apply genomic selection in agritech value chains.
- Evolutionary Biology:Comparative genomics, population genetics, and conservation biology research utilize WGS for phylogenetic reconstruction.
Clinical reimbursement anchors cancer genomics volume; research subsidy sustains evolutionary biology demand.
End User:
Procurement authority concentrates differently across customer types, with integrated delivery networks consolidating vendor relationships while government agencies fragment purchasing across grant cycles.
- Diagnostic Laboratories:CLIA-certified and CAP-accredited facilities perform clinical-grade WGS for patient care, requiring rigorous quality management systems. United States commercial laboratories are scaling automated workflows as FDA guidance clarifies analytical validation expectations for germline and somatic testing.
- Research Institutions:Genome centers, core facilities, and collaborative consortia pursue discovery-scale sequencing with flexible turnaround requirements. The NIH All of Us Research Program is driving infrastructure investment at designated sites across multiple states.
- Biopharmaceutical Companies:Drug developers apply WGS for biomarker discovery, patient stratification, and companion diagnostic development.
- Academic Centers:University-affiliated hospitals balance research and clinical missions with hybrid funding models.
- Government Agencies:Public health laboratories, defense research programs, and environmental monitoring initiatives deploy WGS for surveillance applications.
Diagnostic laboratories concentrate the highest per-sample value; research institutions drive absolute sequencing volume.
Deployment Model:
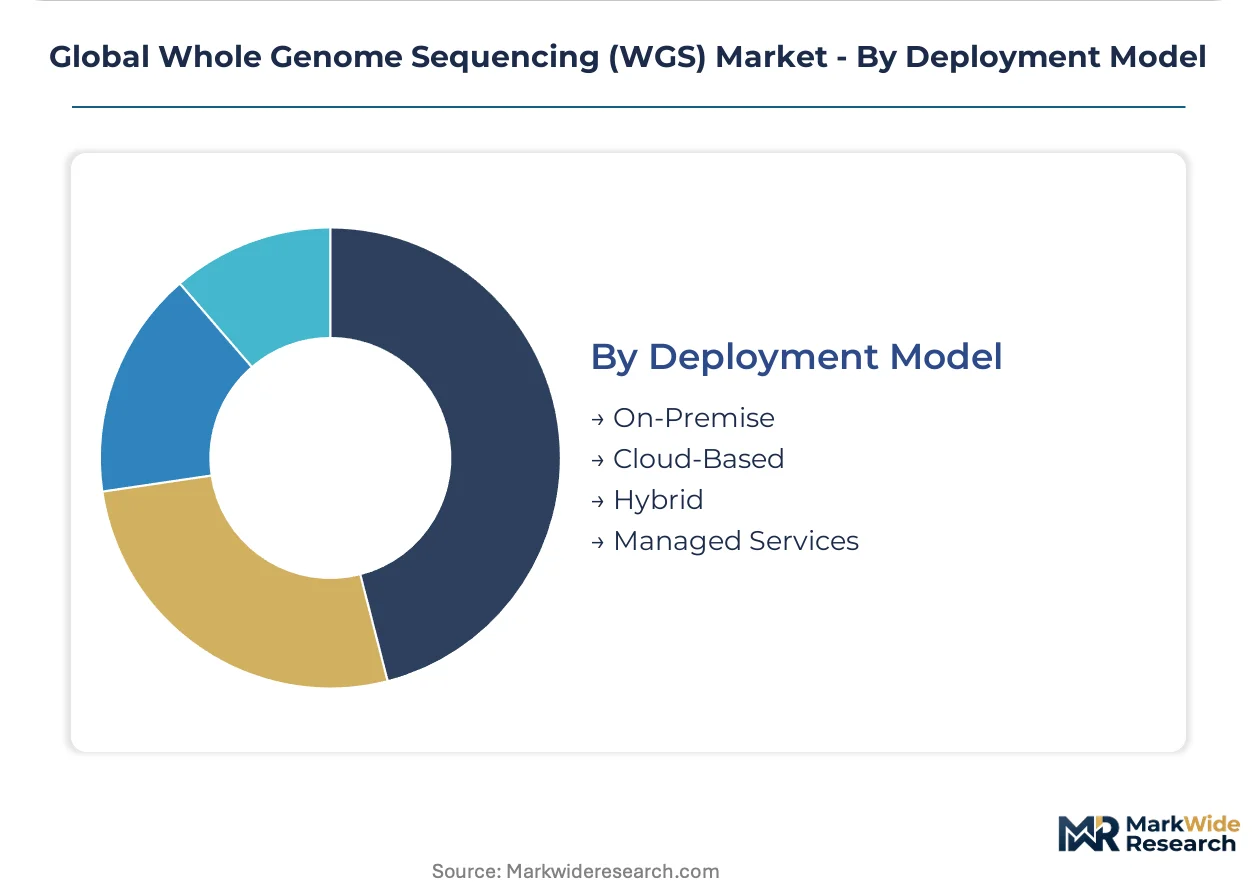
HIPAA compliance complexity and data residency requirements create friction for cloud migration among United States health systems, sustaining hybrid architectures.
- Cloud-Based:Elastic compute access, managed bioinformatics pipelines, and subscription-based variant interpretation tools reduce capital barriers for mid-tier customers. Academic centers in the United Kingdom and Netherlands are adopting cloud-native architectures as GDPR-aligned data governance frameworks mature.
- On-Premise:Local infrastructure maintains physical control over sensitive genomic data and minimizes network dependency for high-throughput operations. United States health systems with established HIPAA compliance programs favor on-premise deployments for clinical WGS.
- Hybrid:Split architectures process raw data locally while leveraging cloud for secondary analysis and long-term storage.
- Managed Services:Outsourced sequencing and analysis bundles transfer operational risk to specialized providers.
On-premise retains clinical data gravity; cloud-based gains fastest among research customers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland demonstrate the lowest price elasticity, prioritizing analytical validation and regulatory compliance over per-sample cost. Indian hospital networks exhibit the highest sensitivity, driving procurement toward bundled service contracts and phased instrument deployment.
United States
The NIH All of Us Research Program and expanding CMS coverage determinations sustain infrastructure investment across academic medical centers. FDA guidance on NGS-based oncology panels clarifies analytical validation requirements for CLIA-certified laboratories. The Boston-Cambridge corridor concentrates biopharma sequencing demand, while Texas Medical Center anchors clinical diagnostic scale.
China
NMPA accelerated review channels compress regulatory timelines for domestic instrument manufacturers seeking to challenge incumbent suppliers. The country's dual carbon goals influence energy-intensive data center placement for genomic analysis. Yangtze River Delta cities host the highest concentration of contract sequencing providers serving agricultural biotechnology clients.
Germany
EMA's MDR implementation extends CE marking timelines, delaying commercial launches for novel sequencing platforms. Academic medical centers in Heidelberg and Munich build national infrastructure for undiagnosed disease networks. Bavaria's precision medicine clusters integrate WGS into statutory health insurance reimbursement pathways.
India
The PLI scheme for medical devices attracts sequencing infrastructure investment as private hospital chains build molecular pathology capabilities. CDSCO regulatory harmonization with ICH standards accelerates clinical trial applications for companion diagnostics. Maharashtra's hospital networks lead adoption of cloud-based variant interpretation tools.
United Kingdom
Genomics England's 100,000 Genomes Program established clinical WGS within NHS reimbursement frameworks. GDPR-aligned data governance frameworks mature, enabling cloud-native architectures at academic centers in Cambridge and Oxford. The London-Oxford-Cambridge triangle concentrates bioinformatics talent for variant interpretation services.
Global Whole Genome Sequencing (WGS) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Short-read platform specialists dominate high-throughput manufacturing scale and installed base expansion. Long-read and real-time sequencing innovators differentiate on structural variant resolution and field-deployable architectures. Partnerships with cloud infrastructure providers and academic medical centers represent the dominant competitive moves for market access.
Among the established platform developers, Illumina anchors the high-throughput short-read tier, Pacific Biosciences exemplifies long-read fidelity specialization, and Oxford Nanopore occupies the portable real-time sequencing position. These three entities represent the core technology archetypes—centralized scale, complex variant resolution, and distributed deployment—that structure vendor competition across clinical and research segments.
| Leading Market Players |
|---|
| Oxford Nanopore |
| Ultima Genomics |
| Illumina |
| Danaher Corporation |
| 10x Genomics |
| Thermo Fisher Scientific |
| Agilent Technologies |
| Bio-Rad Laboratories |
| Pacific Biosciences |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day flow cell lead times concentrate pricing power among incumbent reagent manufacturers while forcing mid-tier laboratories into multi-year bundled contracts that lock in consumable costs. This inventory pressure reinforces vendor stickiness as clinical customers face validation burdens that deter switching.
Pricing Analysis
After-sales reagent and consumable revenue streams drive lifetime customer value far beyond initial instrument placement. Pricing stratifies across premium, standard, and economy tiers based on analytical validation depth and regulatory certification grade, with FDA-recognized test systems commanding substantial premiums over research-use-only configurations. Cost compression in the mid-tier research segment is intensifying because cloud-native bioinformatics alternatives reduce total workflow expenditure. Academic centers in India exhibit the highest price sensitivity, while German diagnostic laboratories prioritize compliance over per-sample cost.
Supply Chain Analysis
Port congestion on transpacific trade lanes elevates inbound logistics costs for flow cells and sequencing chemistries manufactured in the United States and Singapore. Critical supply concentrates in California, Massachusetts, and the United Kingdom for instrument assembly, while specialty polymer and enzyme production draws from Switzerland and Germany. Single-source vulnerability pervades high-sensitivity optical component sourcing. Distribution runs through authorized distributor networks serving CLIA-certified laboratories and direct-to-hospital contracts for integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reagent and consumable attach rates now expand faster than hardware placements as clinical laboratories prioritize predictable per-sample economics over capital ownership. This service-attach dynamic reorients vendor strategy toward recurring revenue capture.
For Market Incumbents: Secure exclusive multi-year reagent supply agreements with major integrated delivery networks before emerging long-read platforms achieve clinical-grade accuracy thresholds. Deepen backward integration into flow cell polymer manufacturing to mitigate single-source optical component risk. Invest in HIPAA-compliant cloud infrastructure partnerships to defend against cloud-native entrants targeting mid-tier academic centers.
For New Entrants and Emerging Players: Anchor in India's private hospital network expansion under the PLI scheme for medical devices, where molecular pathology capabilities remain underpenetrated and price sensitivity drives preference for phased instrument deployment. Target cloud-based variant interpretation services as the most penetrable segment, leveraging GDPR-aligned data governance frameworks in the United Kingdom and Netherlands to establish reference sites.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native bioinformatics sub-segments as elastic compute access reduces infrastructure ownership requirements. Viable acquisition targets include specialized variant interpretation software vendors with established clinical laboratory integrations. Monitor FDA guidance expansion beyond oncology panels into germline rare disease as the inflection signal for reimbursement clarity acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | CMS coverage determinations for somatic profiling anchor clinical volume expansion in United States health systems. |
| Hospital System Partnership | Bundled service contracts with integrated delivery networks consolidate vendor relationships and lock in reagent revenue streams. |
| CE Marking Pathway | EMA MDR compliance enables European commercial access for novel sequencing platforms in German precision medicine clusters. |
| Software Companion Development | AI-powered variant interpretation tools compress diagnostic reporting timelines for clinical laboratories facing bioinformatics talent scarcity. |
| Regulatory Approval Pathway | NMPA accelerated review channels compress commercialization timelines for domestic manufacturers in China's Yangtze River Delta. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA guidance documents, EMA MDR implementation records, and CMS coverage determination databases. Primary interviews engaged sequencing platform developers, CLIA-certified laboratory directors, hospital procurement managers, and bioinformatics pipeline architects. Secondary validation drew from NIH program disclosures, NMPA registration filings, and GPO contract databases. Bottom-up instrument shipment analysis and top-down healthcare expenditure triangulation cross-verify volume estimates.
Segmentation dimensions modeled span product type, application category, end-user archetype, and deployment architecture across the analysis window. Cancer genomics, genetic disease research, microbial surveillance, and agricultural biotechnology represent the application segments tracked. CAGRs derive from instrument installed base expansion curves, reagent consumption per system, and cloud service subscription trajectories. Forecast inputs incorporate regulatory timeline assumptions for FDA, EMA, and NMPA pathways.
Decision-makers should treat outputs as directional under assumptions of sustained reimbursement clarity and stable reagent supply concentration; material deviation would warrant model refresh. Regulatory delays, supply disruptions, or substitution by targeted panels could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Global Digital PCR Market
Genomics
Animal Genetics Market
Genomics
Europe Cancer Biomarkers Market
Genomics
Pharmacogenomic (Pgx) Testing Market
Genomics
Next Generation Genomics Market
Genomics
Europe Hereditary Cancer Testing Market
Genomics
Latin America Next Generation Sequencing Market
Genomics
Prenatal Genetic Testing Market
Genomics
Single-Cell Omics Market
Genomics
Europe Whole Exome Sequencing Market
Genomics
Next Generation Molecular Assay Market
Genomics
North America Microarray Market
Genomics
Global Microarray Analysis Market
Genomics
Non Invasive Prenatal Testing (NIPT) Market
Genomics
Forensic Genomics Market
Genomics
Apolipoprotein Test Market