
 Cancer-Focused Genetic Testing Services Market | 2026-2036
Cancer-Focused Genetic Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Cancer-Focused Genetic Testing Services Market Outlook
A capital-intensity divergence between players is bifurcating competitive dynamics across the Cancer-Focused Genetic Testing Services Market. Illumina, Inc. leverages its vertically integrated sequencing platform to dominate instrument and consumable supply chains. Thermo Fisher Scientific, Inc. sustains broad laboratory service networks that anchor clinical and research demand simultaneously. Guardant Health, Inc. specializes in liquid biopsy workflows, differentiating through minimal residual disease monitoring capabilities.
Cancer-focused genetic testing services encompass molecular diagnostic procedures that analyze DNA, RNA, and protein biomarkers to identify oncogenic mutations, hereditary cancer syndromes, and treatment response predictors using technologies such as next-generation sequencing with read depths exceeding 500x for clinical-grade variant detection. These services guide precision oncology decisions including targeted therapy selection, clinical trial matching, and hereditary risk stratification. Next-generation sequencing and comprehensive genomic profiling represent the fastest-expanding service categories as multi-gene panels displace single-analyte testing in academic medical centers. Liquid biopsy approaches are gaining share in treatment monitoring applications where tissue re-biopsy proves impractical, though tissue-based comprehensive genomic profiling retains higher reimbursement in Medicare-covered indications.
FDA oversight of laboratory-developed tests and CLIA certification requirements shape operational compliance costs and market access conditions for service providers operating in the United States. The Centers for Medicare & Medicaid Services determines coverage policies that directly influence test utilization in hospital and diagnostic laboratory settings. Stakeholders must monitor evolving payer evidence requirements for comprehensive genomic profiling as Medicare Advantage plans and commercial insurers tighten prior authorization criteria for molecular diagnostic services.
Market Dynamics
Comprehensive genomic profiling is displacing single-analyte testing in academic medical centers, compressing reimbursement timelines while expanding clinical utility. This technology shift concentrates purchasing power among health systems capable of integrating multi-gene panels into precision oncology workflows.
Growth Catalysts
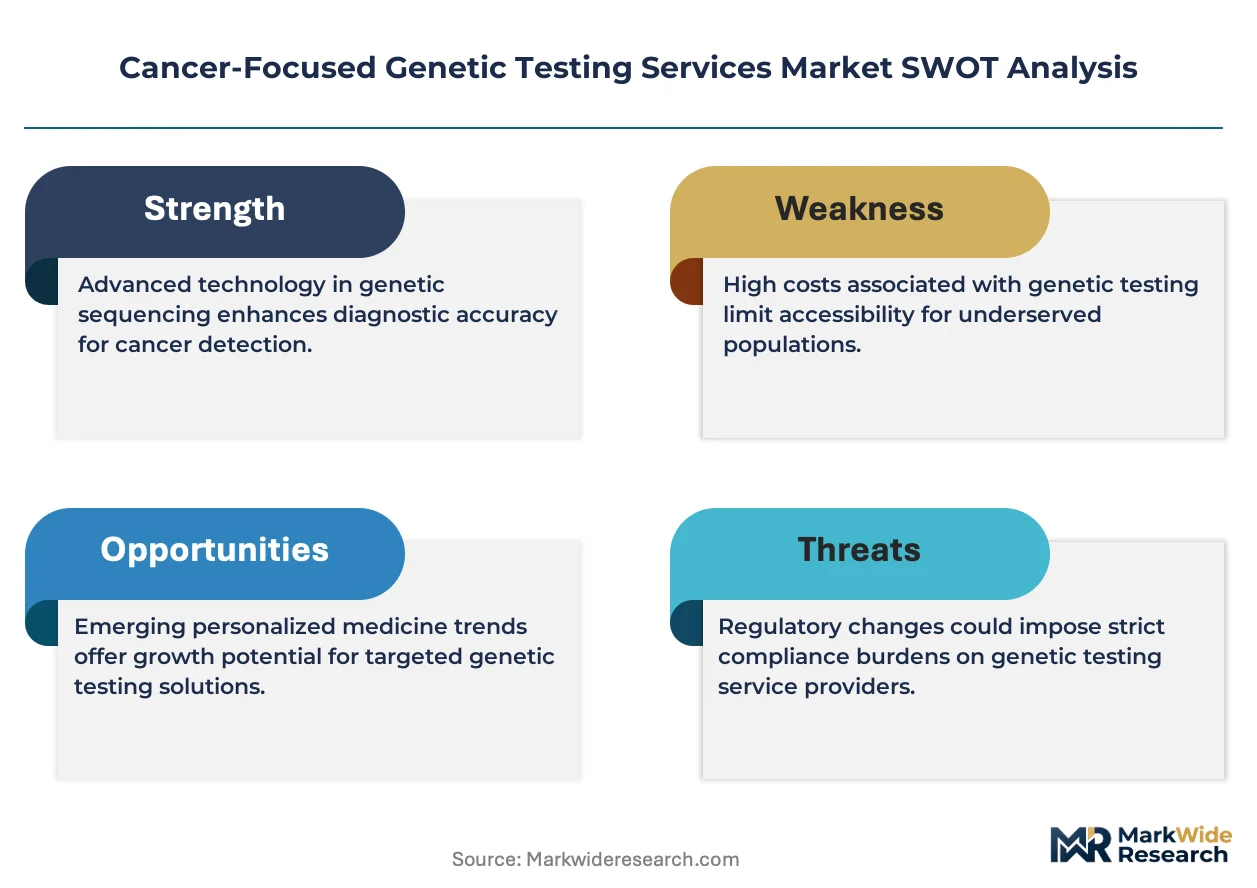
- FDA Laboratory-Developed Test Oversight:The FDA's expanding regulatory framework for LDTs is creating compliance standards that favor established laboratories with quality management infrastructure, accelerating consolidation among service providers.
- Liquid Biopsy Technology Maturation:Circulating tumor DNA detection methods are enabling treatment monitoring applications where tissue re-biopsy proves impractical, particularly in lung and colorectal oncology settings.
- Medicare Advantage Prior Authorization:Concentrated payer coverage in the United States is standardizing evidence requirements for molecular diagnostic services, streamlining utilization pathways for comprehensive genomic profiling.
Market Restraints
- Sequencing Platform Concentration:Illumina's dominance in instrument and consumable supply chains creates vendor lock-in risks for diagnostic laboratories dependent on proprietary reagent ecosystems.
- Reimbursement Compression:Medicare's National Coverage Determination process imposes lengthy evidence-generation requirements that delay market access for novel multi-gene panels.
- Variant Interpretation Bottleneck:Shortages of board-certified molecular pathologists and clinical laboratory geneticists constrain report turnaround times for complex genomic findings.
Strategic Opportunities
- Minimal Residual Disease Monitoring:Post-treatment surveillance applications for circulating tumor DNA represent underpenetrated clinical utility beyond initial diagnosis and therapy selection.
- Clinical Trial Matching Platforms:Integration of genomic profiling data with precision oncology trial enrollment systems creates value-added service differentiation for academic medical centers.
- International Laboratory Accreditation:ISO 15189 certification expansion enables service providers to access European and Asia-Pacific markets with harmonized quality standards.
Industry Challenges
- Bioinformatics Pipeline Validation:CLIA certification requirements for variant calling algorithms demand substantial computational infrastructure investment and ongoing software quality assurance.
- Interoperability with Electronic Health Records:Integration of structured genomic reports into hospital information systems requires customized HL7 FHIR implementations that strain IT resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cancer-Focused Genetic Testing Services Market |
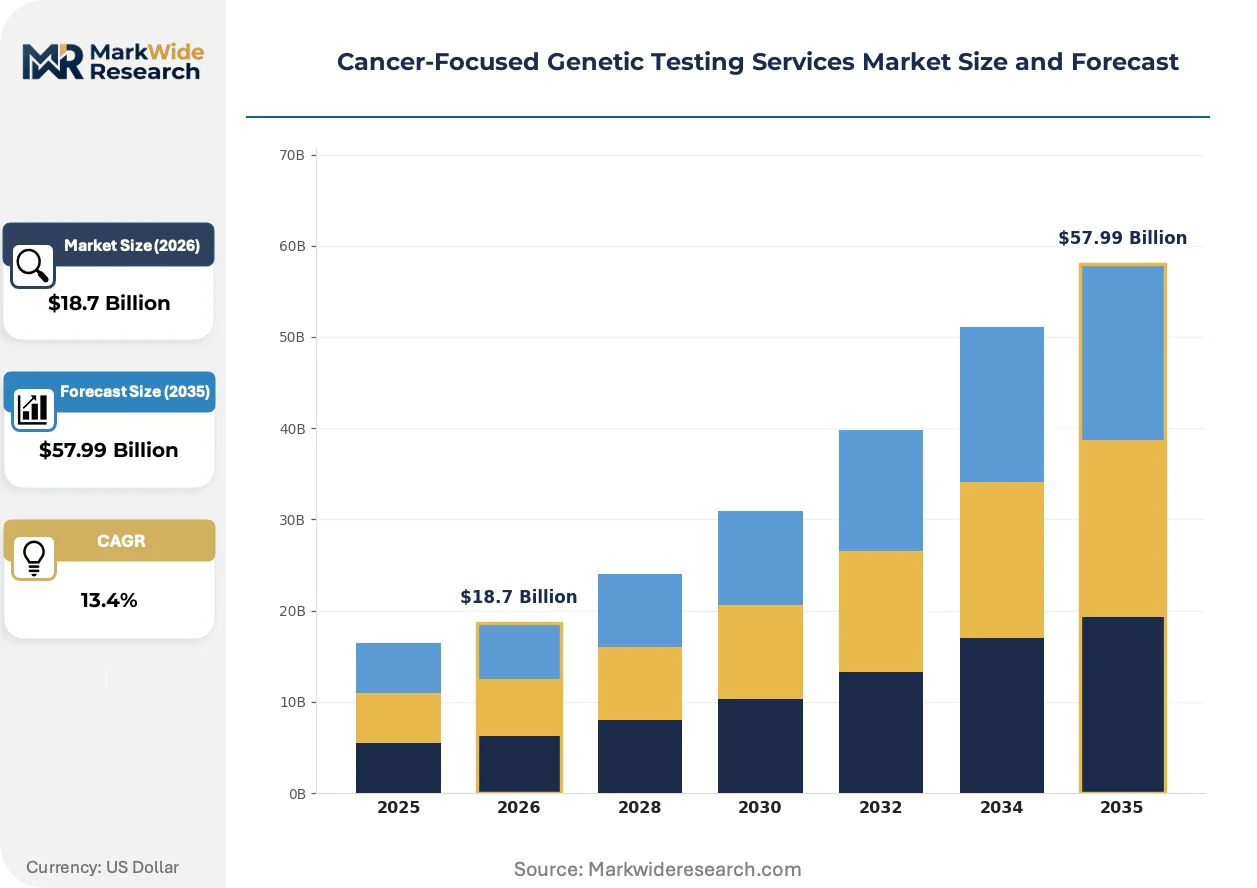
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $57.99 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: BRCA Testing, Comprehensive Genomic Profiling, Targeted Gene Panels, Liquid Biopsy End User: Hospitals, Diagnostic Laboratories, Research Institutions, Oncologists Sample Type: Blood Sample, Saliva Sample, Tissue Sample, FFPE Samples Data Analysis Method: Whole Exome Sequencing, Next-Generation Sequencing, Sanger Sequencing, Bioinformatics Analysis |
| Companies Covered | Illumina, Inc., Thermo Fisher Scientific, Inc., F. Hoffmann-La Roche Ltd., Myriad Genetics, Inc., Invitae Corporation, Quest Diagnostics Incorporated, Guardant Health, Inc., NeoGenomics Laboratories, Inc., Laboratory Corporation of America Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cancer-Focused Genetic Testing Services Market Strategic Shifts
Next-generation sequencing workflows are fragmenting into distinct service tiers based on turnaround time and analytical depth. This specialization is creating divergent competitive strategies among clinical laboratories and technology vendors.
Comprehensive genomic profiling using hybrid capture-based next-generation sequencing with read depths exceeding 500x enables detection of copy number alterations, microsatellite instability, and tumor mutational burden from single specimen submissions. Academic medical centers in the United States are adopting these multi-gene panels for newly diagnosed advanced cancers at accelerating rates. The technology is bifurcating service provider capabilities between high-complexity reference laboratories and rapid-turnaround community hospital labs.
The FDA's phased implementation of premarket review requirements for high-risk laboratory-developed tests is reshaping operational compliance costs for molecular diagnostic services. This regulatory expansion imposes quality system documentation and analytical validation standards previously applied primarily to in vitro diagnostic devices. Comprehensive genomic profiling services for solid tumor indications face the most significant evidentiary burdens under the proposed framework.
Oncology care teams are consolidating molecular test ordering authority within specialized tumor boards and precision medicine committees. This concentration of decision-making is displacing individual physician-initiated testing patterns in integrated health systems. The United States exhibits the most pronounced shift toward centralized genomic stewardship, with Medicare Advantage plans reinforcing prior authorization requirements for out-of-network laboratory services.
Cancer-Focused Genetic Testing Services Market Segmentation
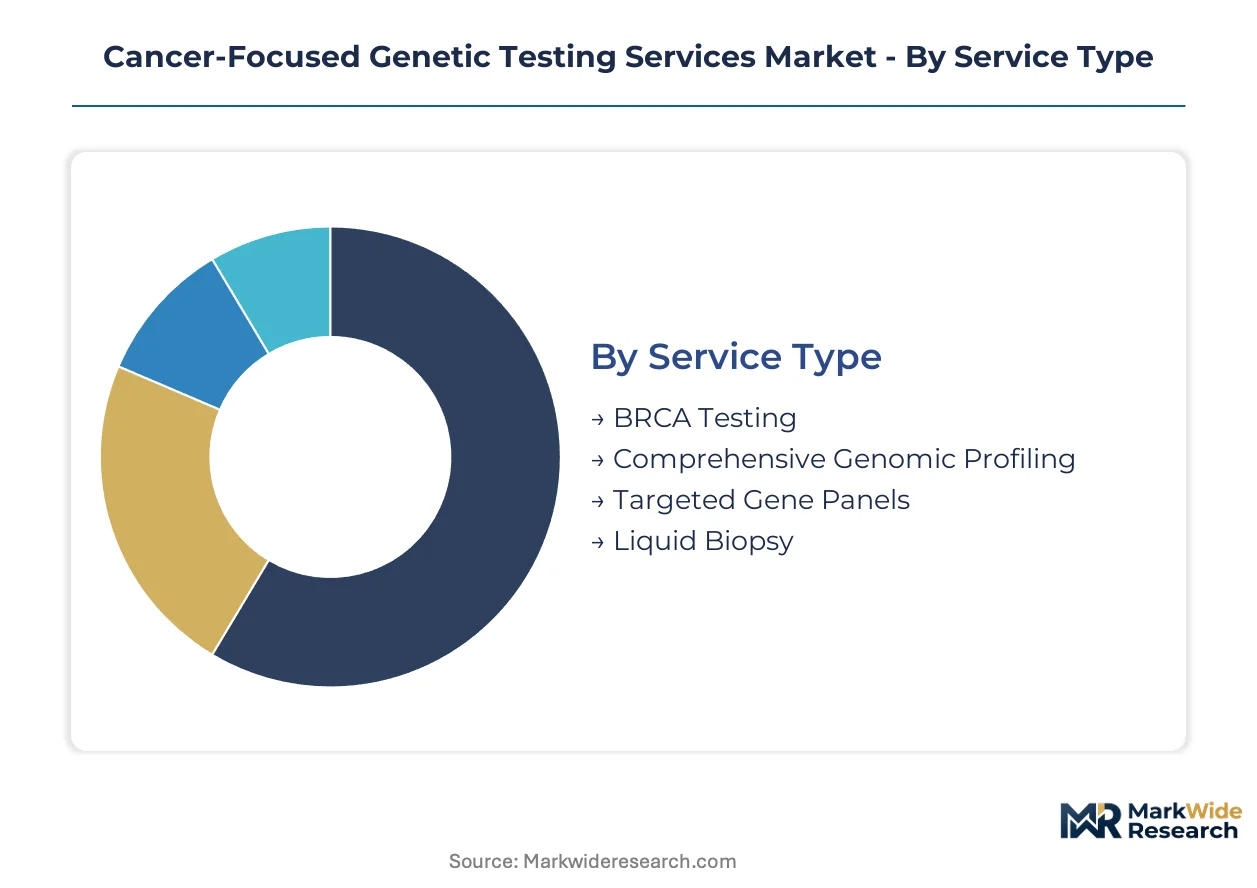
Segmentation in cancer-focused genetic testing services reveals distinct competitive arenas where technology maturity, reimbursement pathways, and clinical utility intersect differently. Understanding these boundaries enables precise positioning for laboratories navigating FDA oversight and payer consolidation pressures.
Service Type:
Substitution pressure intensifies between single-gene assays and multi-gene panels as Medicare Advantage plans tighten prior authorization for lower-complexity tests.
- Comprehensive Genomic Profiling:Multi-gene panels analyzing DNA, RNA, and protein biomarkers with read depths exceeding 500x for clinical-grade variant detection. Academic medical centers in the United States concentrate purchasing power here as integrated health systems consolidate molecular test ordering authority within precision medicine committees.
- Liquid Biopsy:Circulating tumor DNA detection methods enabling treatment monitoring where tissue re-biopsy proves impractical, particularly in lung and colorectal oncology settings. Guardant Health and similar specialists differentiate through minimal residual disease monitoring capabilities beyond initial diagnosis.
- BRCA Testing:Hereditary cancer syndrome screening for breast and ovarian cancer risk stratification.
- Targeted Gene Panels:Focused mutation detection for specific oncogenic pathways with faster turnaround times.
Comprehensive Genomic Profiling retains volume leadership; Liquid Biopsy holds the steepest expansion curve.
End User:
Cost tier stratification separates high-complexity reference laboratories from rapid-turnaround community hospital labs based on instrumentation investment and bioinformatics infrastructure.
- Hospitals:Integrated delivery networks with captive pathology departments and precision oncology committees. The United States exhibits pronounced centralization of genomic stewardship as oncology care teams displace individual physician-initiated testing patterns.
- Diagnostic Laboratories:Independent and health system-affiliated labs processing specimens from multiple ordering sites. CLIA certification requirements and FDA laboratory-developed test oversight reshape operational compliance costs differentially across this tier.
- Research Institutions:Academic centers generating evidence for novel biomarker clinical validation.
- Oncologists:Individual practitioners and group practices with direct patient relationships.
Hospitals command the highest specimen volumes; Diagnostic Laboratories face the most acute margin compression from sequencing platform concentration.
Sample Type:
Application-specific requirements drive divergence between invasive tissue acquisition and non-invasive alternatives where tumor heterogeneity concerns differ.
- Tissue Sample:Solid tumor biopsies yielding highest DNA quality for comprehensive genomic profiling with established Medicare reimbursement pathways. Academic medical centers prioritize these specimens for newly diagnosed advanced cancers despite procedural risks.
- Blood Sample:Circulating tumor DNA sources for liquid biopsy workflows with expanding clinical utility in treatment monitoring. Lung and colorectal oncology settings concentrate adoption where serial sampling enables dynamic response assessment.
- Saliva Sample:Non-invasive collection for hereditary cancer syndrome screening.
- FFPE Samples:Archival formalin-fixed paraffin-embedded tissue for retrospective analysis.
Tissue Sample maintains reimbursement primacy; Blood Sample expands most quickly into surveillance applications.
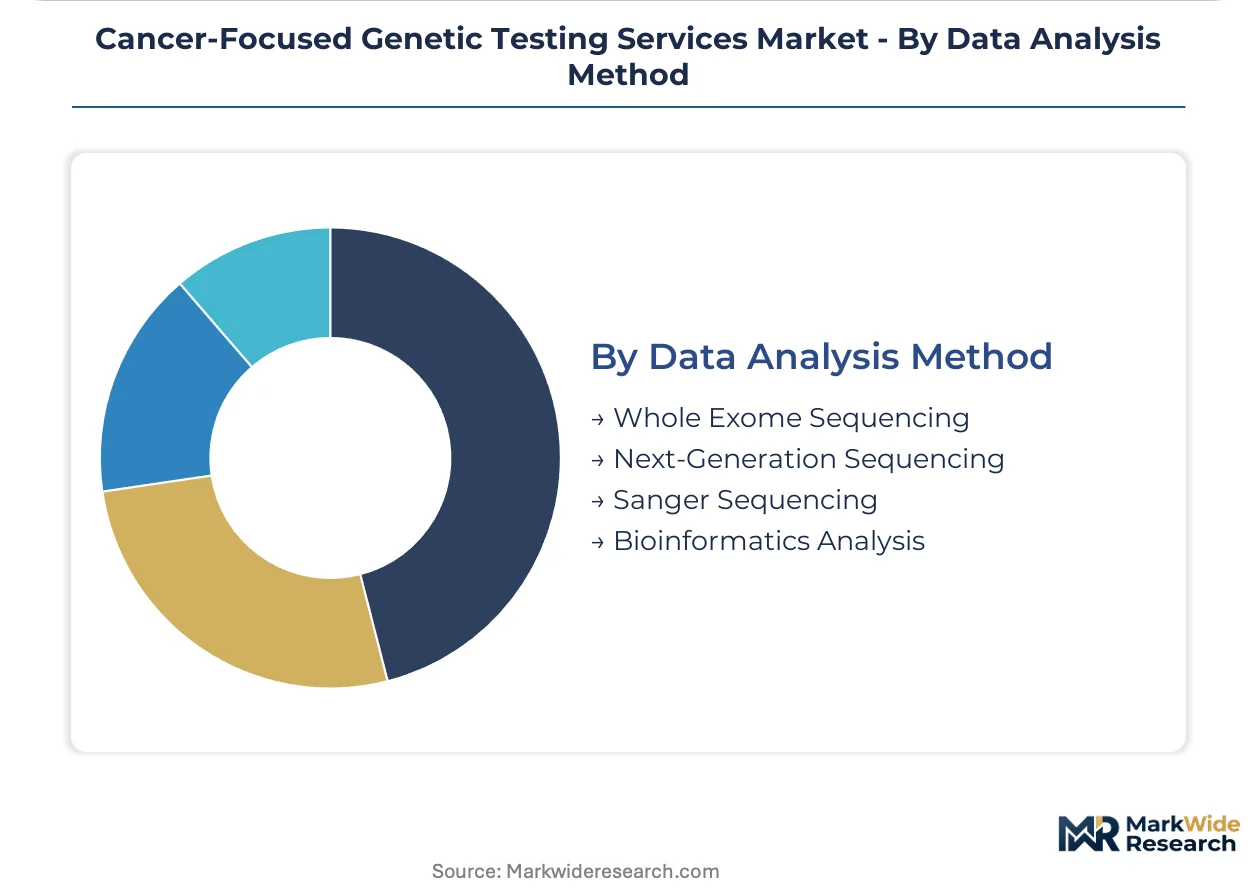
Data Analysis Method:
Supply concentration in sequencing instrumentation creates vendor lock-in risks that differentiate service provider capabilities based on platform ecosystem commitments.
- Next-Generation Sequencing:Hybrid capture-based workflows with read depths exceeding 500x enabling detection of copy number alterations, microsatellite instability, and tumor mutational burden. Illumina's vertically integrated platform dominates instrument and consumable supply chains for this category.
- Bioinformatics Analysis:Variant calling algorithms and clinical interpretation pipelines requiring CLIA certification and substantial computational infrastructure investment. Shortages of board-certified molecular pathologists constrain report turnaround times for complex genomic findings.
- Whole Exome Sequencing:Broader genomic coverage for research and undiagnosed cancer syndrome investigation.
- Sanger Sequencing:Targeted confirmation of variants identified through higher-throughput methods.
Next-Generation Sequencing anchors current service revenue; Bioinformatics Analysis represents the fastest-growing cost center as laboratories scale computational infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while European laboratories absorb compressed reimbursement rates under centralized health technology assessment frameworks. Germany and the United Kingdom maintain secondary volume positions through specialized oncology networks. Asia-Pacific expansion depends on harmonized accreditation standards and private payer infrastructure development.
United States
Medicare Advantage prior authorization and FDA laboratory-developed test oversight concentrate purchasing power within integrated health systems. The Centers for Medicare & Medicaid Services determines coverage policies that directly influence test utilization in hospital settings. The Boston-Cambridge corridor anchors precision oncology research translation with Guardant Health and Foundation Medicine operating reference laboratories.
Germany
Statutory health insurance funds and the Federal Joint Committee (G-BA) regulate molecular diagnostic reimbursement through health technology assessment procedures. The country's national pharmaceutical regulator, the Federal Institute for Drugs and Medical Devices, oversees in vitro diagnostic conformity assessment. The Munich and Heidelberg clusters concentrate academic medical center adoption of comprehensive genomic profiling for solid tumor indications.
United Kingdom
The National Institute for Health and Care Excellence evaluates genomic test clinical utility for National Health Service commissioning. Genomics England's 100,000 Genomes Project established infrastructure for rare disease and cancer whole genome sequencing integration. The Cambridge-London corridor hosts reference laboratories serving NHS England's Genomic Medicine Service.
Japan
The Ministry of Health, Labour and Welfare's Central Social Insurance Medical Council sets reimbursement prices for companion diagnostics and genomic profiling. The Pharmaceuticals and Medical Devices Agency reviews next-generation sequencing-based oncology tests under accelerated approval pathways. The Kanto region surrounding Tokyo concentrates diagnostic laboratory capacity and pharmaceutical industry demand.
China
The National Medical Products Administration regulates next-generation sequencing-based diagnostic products through innovation review channels. Provincial medical insurance bureaus pilot coverage expansion for molecular diagnostics in cancer treatment. The Yangtze River Delta region, centered on Shanghai and Suzhou, hosts the highest concentration of clinical testing laboratories and biopharmaceutical research facilities.
Cancer-Focused Genetic Testing Services Market Competitive Environment
Concentration sits with vertically integrated sequencing platform providers and specialized liquid biopsy laboratories. Three strategic archetypes dominate: instrument and consumable suppliers anchoring supply chain control, comprehensive service networks spanning clinical and research demand, and focused liquid biopsy specialists differentiating through minimal residual disease monitoring. Competitive moves center on strategic partnerships with pharmaceutical developers and bioinformatics pipeline acquisitions.
Among platform-integrated suppliers, Illumina, Inc. and Thermo Fisher Scientific, Inc. occupy positions representing instrument ecosystem dominance and broad laboratory service network scale respectively. Guardant Health, Inc. exemplifies the liquid biopsy specialist archetype with minimal residual disease surveillance capabilities. These three companies anchor the competitive structure through distinct vertical positioning rather than direct segment overlap.
| Leading Market Players |
|---|
| Illumina, Inc. |
| Thermo Fisher Scientific, Inc. |
| F. Hoffmann-La Roche Ltd. |
| Myriad Genetics, Inc. |
| Invitae Corporation |
| Quest Diagnostics Incorporated |
| Guardant Health, Inc. |
| NeoGenomics Laboratories, Inc. |
| Laboratory Corporation of America Holdings |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with Illumina anchor supply access and price visibility for high-throughput sequencing laboratories, locking in reagent pricing tiers while insulating against consumable cost volatility under FDA laboratory-developed test oversight frameworks in the United States.
Pricing Analysis
The customization-premium spread separates configured-to-order comprehensive genomic profiling from standard liquid biopsy panels, with academic medical centers absorbing premium pricing for multi-gene panels with read depths exceeding 500x while community hospitals face cost compression on rapid-turnaround targeted assays. Medicare Advantage prior authorization standardizes evidence requirements, intensifying price sensitivity among diagnostic laboratories dependent on thin margins. Pricing pressure stems from sequencing platform concentration as Illumina's proprietary reagent ecosystems constrain vendor switching options.
Supply Chain Analysis
The United States and China anchor sequencing instrument manufacturing and clinical testing laboratory capacity respectively, with San Diego and Suzhou hosting concentrated production and service operations. Supply chains draw from specialized semiconductor components for optical detection systems, synthetic oligonucleotides for capture probes, and clinical-grade reagents for specimen preparation. Single-source vulnerability concentrates in Illumina's instrument and consumable ecosystems, creating lock-in risks for diagnostic laboratories. Distribution runs through health system procurement committees and GPO contracts that consolidate purchasing power among integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Cancer-Focused Genetic Testing Services Market represents high-growth disruption as FDA laboratory-developed test oversight phases in premarket review requirements, reshaping compliance costs and competitive positioning for molecular diagnostic services.
For Market Incumbents: Consolidate quality management infrastructure investments ahead of FDA premarket review implementation, capturing laboratories lacking analytical validation documentation capabilities. Deepen backward integration into bioinformatics pipeline development to constrain turnaround times amid board-certified molecular pathologist shortages. Anchor hospital system partnerships through precision medicine committee relationships before Medicare Advantage prior authorization tightens out-of-network exclusions. For New Entrants and Emerging Players: Lead with minimal residual disease monitoring capabilities in post-treatment surveillance applications, the most underpenetrated clinical utility beyond initial diagnosis. Target community hospital laboratories lacking in-house comprehensive genomic profiling infrastructure, offering rapid-turnaround liquid biopsy workflows as a service layer. Differentiate through HL7 FHIR-native electronic health record integration that strains IT resources at incumbent reference laboratories. For Investors and Strategic Acquirers: Specialized liquid biopsy laboratories with CLIA-certified circulating tumor DNA platforms present acquisition targets with defendable technology moats in lung and colorectal oncology settings. Long-term viability hinges on Medicare coverage determination timing for multi-gene panels. Watch for FDA final guidance on laboratory-developed test categorization as the inflection signal for consolidation velocity among service providers.| Strategic Initiative | Industry Significance |
|---|---|
| Bioinformatics Pipeline Acquisition | CLIA certification for variant calling algorithms accelerates report turnaround times amid pathologist shortages. |
| Hospital System Partnership | Precision medicine committee relationships secure specimen volume under Medicare Advantage prior authorization tightening. |
| ISO 15189 Certification Expansion | Harmonized quality standards enable European and Asia-Pacific market access beyond United States revenue concentration. |
| Pharmaceutical Developer Collaboration | Clinical trial matching platforms create value-added differentiation for academic medical center reference laboratories. |
| Minimal Residual Disease Platform Launch | Post-treatment surveillance applications expand addressable market beyond initial diagnosis and therapy selection. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with molecular pathologists, laboratory directors at academic medical centers, diagnostic laboratory operations executives, payer policy specialists at Medicare Advantage plans, and pharmaceutical precision oncology leads. Secondary validation drew from FDA 510(k) and PMA filings, CMS National Coverage Determination records, Clinical Laboratory Improvement Amendments certification databases, and hospital procurement contract disclosures. Bottom-up specimen volume modeling and top-down service revenue estimates were triangulated across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions including service type complexity tier, end-user integration level, sample type invasiveness profile, and data analysis method computational intensity. CAGRs were derived from regression-based trend extrapolation calibrated to Medicare coverage expansion trajectories and pharmaceutical companion diagnostic approval velocities. Forecast inputs incorporated health system consolidation patterns and board-certified molecular pathologist supply projections.
The analysis sits within stated boundaries; outcomes outside FDA laboratory-developed test oversight implementation timelines or Medicare Advantage prior authorization stabilization would require recalibration. Forecasts reflect assumptions regarding sequencing platform ecosystem continuity and reimbursement pathway durability. Recalibration cycles align with material shifts in regulatory guidance publication and payer evidence requirement changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Genomic Biomarkers Market
Genomics
Global Molecular Cytogenetics Market
Genomics
DNA Gene Chip Market
Genomics
Next-Generation Sequencing Data Analysis Market
Genomics
Whole Genome Amplification Market
Genomics
Microbiome Sequencing Market
Genomics
Global Microbiome Sequencing Services Market
Genomics
DNA Diagnostics Market
Genomics
North America Whole Exome Sequencing Market
Genomics
United States DNA Sequencing Products Market
Genomics
Global NGS Sample Preparation Market
Genomics
Middle East and Africa Whole Exome Sequencing Market
Genomics
Latin America Next Generation Sequencing Market
Genomics
Dna Polymerase Market
Genomics
Global Gene Amplification Technologies Market
Genomics
DNA Methylation Market