
 Global Next-Generation Building Energy Management Systems Market | 2026-2036
Global Next-Generation Building Energy Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Next-Generation Building Energy Management Systems Market Foresight
Subscription-based software platforms is recalibrating how vendors monetize building energy management, shifting capital expenditure into recurring revenue streams. Siemens AG leverages deep automation heritage to anchor its position in hardware controller integration. Schneider Electric SE differentiates through end-to-end software platforms that unify HVAC control with occupancy analytics. Honeywell International Inc. competes on sensor density and edge-computing architectures that reduce cloud dependency.
Next-generation building energy management systems integrate IoT sensors, cloud-native software platforms, and machine learning algorithms to optimize HVAC, lighting, and demand response in real time, typically processing thousands of data points per building daily to reduce energy consumption. Software platforms command the largest revenue share as building operators prioritize centralized dashboards over point solutions. Machine learning applications within data analytics tools represent the fastest-expanding segment, driven by predictive maintenance and automated fault detection that cut operational expenditure.
The EU Green Deal and F-Gas Regulation in Europe, alongside EPA energy efficiency guidelines and state-level building codes in the United States, are mandating granular energy monitoring and retrofit timelines that directly expand addressable demand. China's GB standards and dual carbon goals enforce similar building efficiency benchmarks, creating compliance-driven procurement cycles across all three markets. Stakeholders must monitor how tightening interoperability standards affect vendor lock-in risks and procurement flexibility.
Market Dynamics
Subscription-based software platforms are recalibrating vendor monetization models, shifting capital expenditure into recurring revenue streams while hardware margins compress under commoditization pressure from Asian controller manufacturers.
Growth Catalysts
- EU Green Deal mandates:Building retrofit timelines and granular energy monitoring requirements in Europe are accelerating compliance-driven procurement cycles for integrated BEMS platforms.
- Machine learning algorithms:Predictive maintenance and automated fault detection capabilities within analytics tools are cutting operational expenditure for commercial complex operators.
- China's dual carbon goals:GB standards enforcement and building efficiency benchmarks are creating mandated replacement cycles for aging energy infrastructure in tier-one cities.
Market Restraints
- Semiconductor supply concentration:Edge-computing controller production depends on concentrated Asian foundry capacity, creating input volatility for sensor-dense architectures.
- Copper and rare earth pricing:HVAC control hardware faces persistent input cost pressure from commodity markets, squeezing hardware-centric vendor margins.
- Interoperability standard gaps:Fragmented communication protocols between legacy BACnet systems and cloud-native platforms create technical integration barriers.
Strategic Opportunities
- India's Smart Cities Mission:Urban infrastructure digitization programs are opening white-space demand for scalable BEMS deployments in commercial and municipal buildings.
- Outcome-based energy performance contracts:Energy service companies are adopting shared-savings models that align vendor compensation with verified consumption reductions.
- Digital twin convergence:Integration of building information modeling with real-time sensor data is creating new service layers for predictive simulation and scenario planning.
Industry Challenges
- Systems integration expertise:Deployment of unified HVAC-occupancy-analytics platforms requires scarce cross-functional engineering talent combining OT and IT skill sets.
- Cybersecurity certification timelines:IEC 62443 compliance for connected building systems extends product development cycles and raises qualification costs for vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Next-Generation Building Energy Management Systems Market |
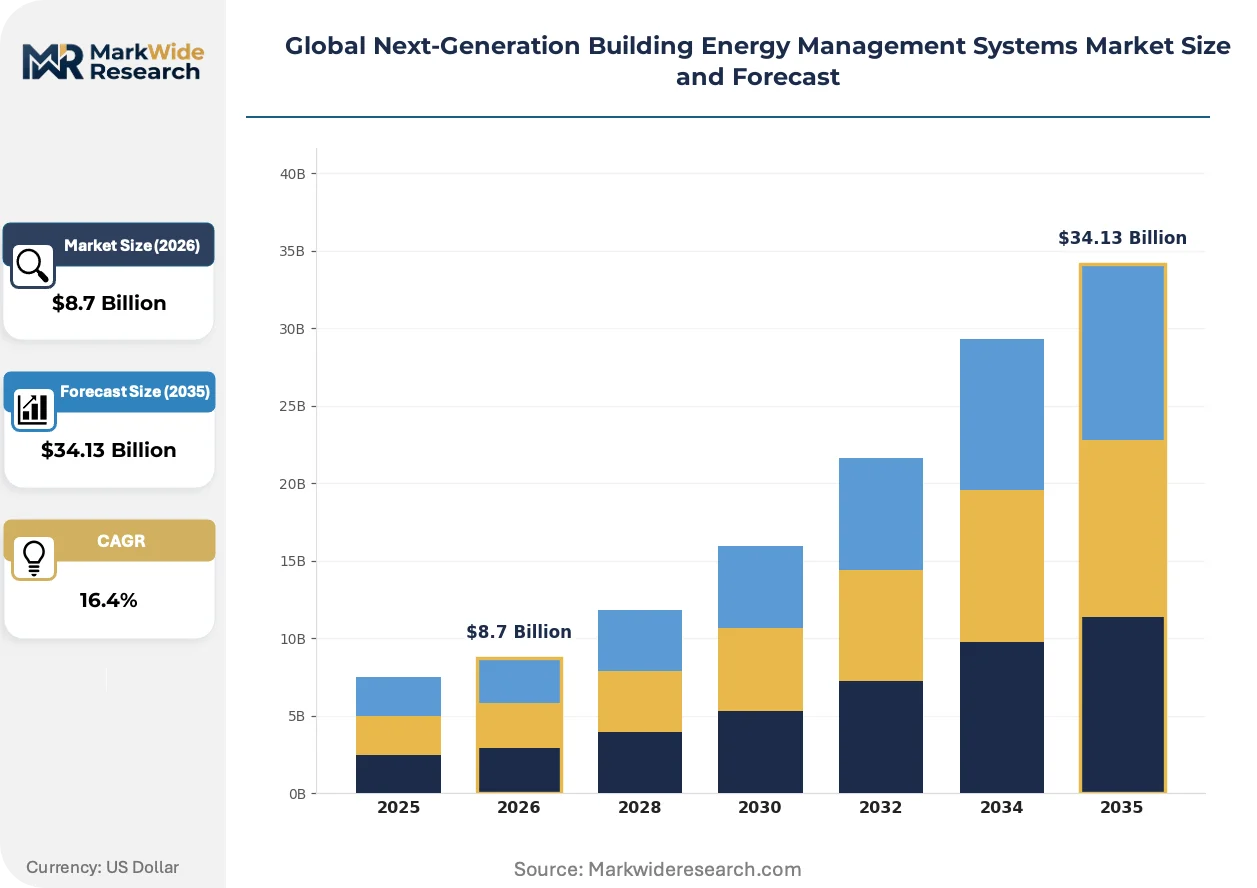
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Platform, Hardware Controller, Sensor Devices, Data Analytics Tools, Communication Module Technology: IoT Integration, Cloud Computing, Artificial Intelligence, Machine Learning, Big Data Analytics Application: Energy Optimization, HVAC Control, Lighting Management, Security Monitoring, Occupancy Analytics, Demand Response End User: Commercial Complexes, Educational Institutions, Government Facilities, Data Centers, Hospitality Establishments |
| Companies Covered | Siemens AG, ABB, Schneider Electric SE, Eaton Corporation, IBM Corporation, Honeywell International Inc., Johnson Controls International, Emerson Electric Company, General Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Next-Generation Building Energy Management Systems Market Shifts & Advancements
Edge-computing architectures are redistributing data processing loads away from cloud dependencies, while machine learning applications migrate toward localized inference engines that reduce latency and bandwidth costs for real-time building optimization.
Digital twin technology is consolidating building energy modeling capabilities by merging static architectural data with dynamic operational telemetry. Large commercial real estate investment trusts are deploying these platforms across multi-site portfolios to standardize performance benchmarking. This convergence is consolidating previously siloed design-phase and operations-phase software markets into unified lifecycle platforms.
The EPA's energy efficiency guidelines and state-level building codes in the United States are mandating automated demand response capabilities and sub-metering granularity. These rules are forcing equipment upgrades in Class A office buildings ahead of lease renewal cycles. Property managers in California and New York are responding by pre-qualifying BEMS vendors against utility incentive program requirements.
Building operators are bundling energy management procurement with broader facilities management outsourcing contracts, compressing standalone BEMS sales cycles. Integrated service providers are capturing this budget consolidation by embedding software subscriptions within multi-year hard services agreements. This pattern is most visible in Germany's commercial real estate sector, where property service conglomerates are internalizing energy optimization as a retained function.
Global Next-Generation Building Energy Management Systems Market Segmentation
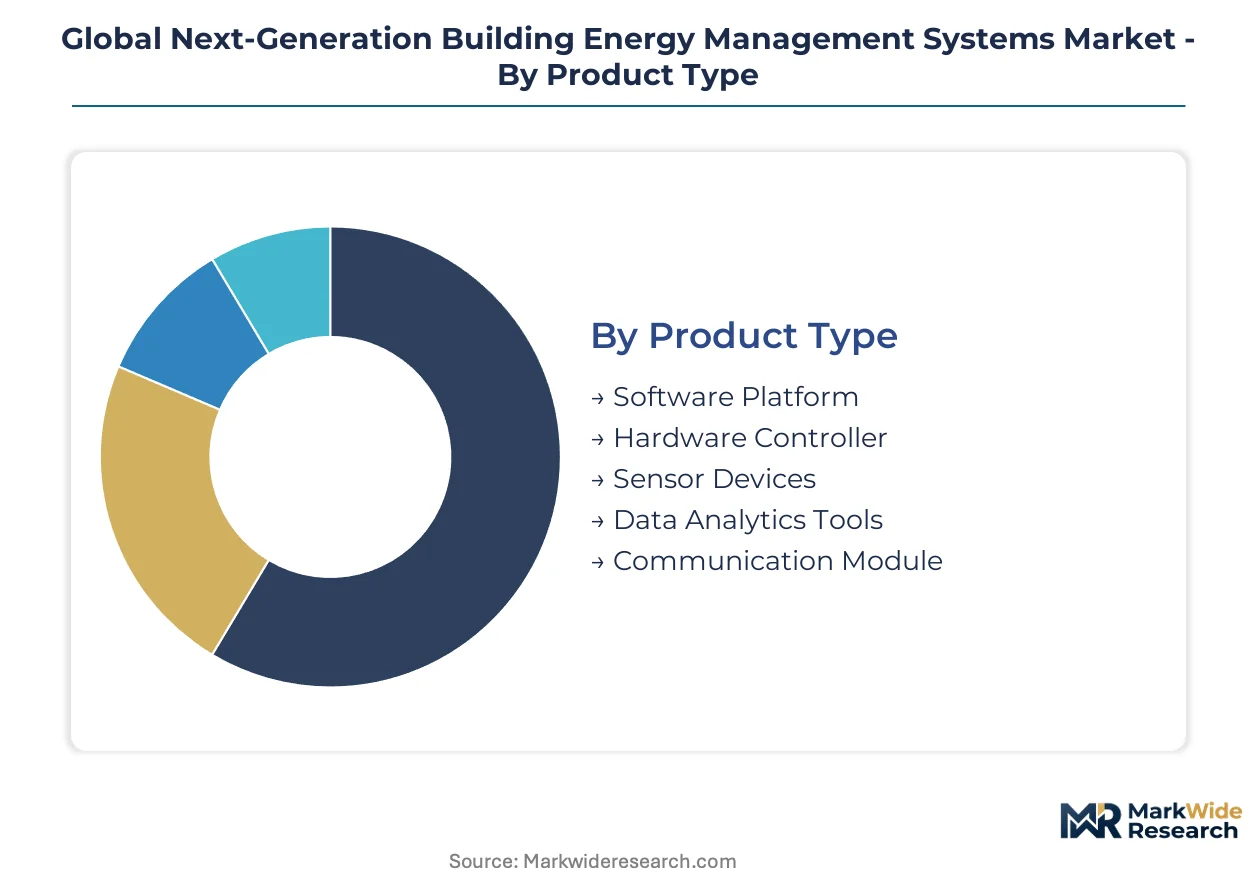
Segmentation in next-generation building energy management systems reveals how procurement priorities split between capital-intensive hardware and recurring software subscriptions. The structure also exposes which technology layers command pricing power versus which face commoditization pressure from Asian manufacturers.
Product Type:
Software platforms capture premium pricing through recurring revenue models, while hardware controllers compete on volume with compressed margins.
- Software Platform:Cloud-native dashboards centralize HVAC, lighting, and occupancy data into unified control interfaces. Demand concentrates in Germany and the United States where commercial real estate investment trusts prioritize portfolio-wide standardization over point solutions. Schneider Electric anchors this segment through end-to-end platform integration.
- Hardware Controller:Edge-computing devices process sensor data locally to reduce cloud dependency and latency. Procurement in China focuses on cost-optimized units for mass retrofit programs, while US buyers emphasize cybersecurity-hardened architectures. Honeywell International competes on sensor density and localized inference capabilities.
- Sensor Devices:Temperature, occupancy, and air quality monitors generate the raw data streams feeding optimization algorithms.
- Data Analytics Tools:Machine learning applications for predictive maintenance and automated fault detection cut operational expenditure for facility managers.
- Communication Module:BACnet and cloud-native protocol bridges resolve interoperability gaps between legacy building systems and modern platforms.
Mature deployment sits with hardware controllers. Newer deployment is concentrated in software platforms.
Technology:
Artificial intelligence and machine learning layers differentiate premium offerings, while IoT integration provides the foundational connectivity enabling all other functions.
- IoT Integration:Sensor networks and connectivity protocols form the backbone infrastructure collecting thousands of data points per building daily. Mass rollouts in China's tier-one cities and India's Smart Cities Mission drive volume demand for standardized IoT architectures.
- Cloud Computing:Centralized data processing and storage enable remote monitoring across distributed building portfolios. US commercial complexes favor hybrid architectures balancing cloud analytics with local redundancy requirements under EPA cybersecurity guidelines.
- Artificial Intelligence:Rule-based automation engines execute predefined optimization strategies without human intervention.
- Machine Learning:Self-improving algorithms adapt HVAC and lighting control based on historical occupancy patterns and weather data.
- Big Data Analytics:Cross-building benchmarking and pattern recognition tools serve multi-site operators in Germany's property service conglomerates.
Volume deployment clusters around IoT integration. Premium deployment is expanding fastest in machine learning.
Application:
Energy optimization and HVAC control absorb the majority of procurement budgets, while demand response capabilities gain traction under utility incentive programs.
- Energy Optimization:Real-time load balancing and consumption forecasting reduce utility expenditure across entire building portfolios. California and New York property managers pre-qualify vendors against state-level automated demand response mandates.
- HVAC Control:Heating, ventilation, and air conditioning automation represents the largest addressable application by installed base. Retrofit timelines under the EU Green Deal and F-Gas Regulation accelerate replacement cycles in Germany, France, and Italy.
- Lighting Management:Daylight harvesting and occupancy-based dimming cut electricity consumption in commercial complexes.
- Security Monitoring:Integrated access control and surveillance systems share infrastructure with energy management networks.
- Occupancy Analytics:Space utilization data informs lease renewal negotiations and workplace redesign decisions.
- Demand Response:Automated load curtailment during grid peak events generates revenue through utility incentive programs.
Established deployment dominates HVAC control. Emerging deployment is accelerating in demand response.
End User:
Commercial complexes generate the largest revenue concentration, while data centers impose the most stringent performance requirements.
- Commercial Complexes:Class A office buildings and mixed-use developments prioritize tenant comfort alongside energy cost reduction. Germany's property service conglomerates bundle BEMS procurement within multi-year facilities management contracts, compressing standalone sales cycles.
- Data Centers:Mission-critical cooling and power reliability requirements drive investment in redundant sensor networks and sub-second fault detection. China's GB standards enforcement creates compliance-driven replacement cycles for aging infrastructure in tier-one cities.
- Educational Institutions:University campuses and K-12 districts leverage grant funding for sustainability demonstrations.
- Government Facilities:Federal and municipal buildings face mandated efficiency targets under executive orders and procurement guidelines.
- Hospitality Establishments:Hotels optimize guest room energy use while maintaining comfort standards across variable occupancy.
Scale deployment concentrates in commercial complexes. Performance-critical deployment sits with data centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardware controller fabrication concentrates in Asian manufacturing clusters, while software platform consumption and systems integration services concentrate in Western Europe and North America. This geographic split shapes procurement patterns, with European and US buyers prioritizing cybersecurity certification and cloud-native architectures while Asian markets emphasize cost-optimized mass deployment.
United States
Class A office buildings in California and New York drive demand for automated demand response capabilities under state-level building codes. EPA energy efficiency guidelines mandate sub-metering granularity that accelerates BEMS procurement ahead of lease renewal cycles. Property managers in the Pacific Northwest pre-qualify vendors against utility incentive program requirements.
Germany
Commercial real estate investment trusts retrofit aging building stock under EU Green Deal retrofit timelines. The F-Gas Regulation enforces granular energy monitoring mandates that expand addressable demand for integrated platforms. Property service conglomerates in North Rhine-Westphalia bundle BEMS procurement within multi-year facilities management contracts.
China
Tier-one cities enforce GB standards compliance and dual carbon goals that mandate building efficiency benchmarks. MIIT oversees smart meter rollouts that create mass replacement cycles for aging energy infrastructure. Yangtze River Delta municipalities deploy cost-optimized hardware controllers for commercial complex retrofits.
India
The Smart Cities Mission opens white-space demand for scalable BEMS deployments in commercial and municipal buildings. CEA guidelines promote urban infrastructure digitization programs across state-level jurisdictions. Maharashtra and Karnataka lead pilot deployments in IT park and special economic zone clusters.
France
Commercial complexes in Île-de-France adopt HVAC-occupancy-analytics platforms under EU Green Deal enforcement. The country's national building efficiency regulator mandates granular monitoring requirements that align with F-Gas Regulation compliance. Auvergne-Rhône-Alpes hosts systems integration specialists serving cross-border projects into Switzerland and Italy.
Global Next-Generation Building Energy Management Systems Market Competitive Landscape
Top-tier vendors anchor integrated platform supply, while mid-tier specialists compete on hardware volume and regional service density. Siemens AG, Schneider Electric SE, and Honeywell International Inc. occupy positions that span both software and hardware layers. Three strategic archetypes dominate: automation heritage conglomerates, end-to-end software platform providers, and sensor-dense edge-computing specialists. Competitive moves concentrate on strategic partnerships for interoperability certification and portfolio diversification into digital twin services.
Among automation heritage conglomerates, Siemens AG represents the hardware controller integration archetype, while Schneider Electric SE exemplifies end-to-end software platform positioning. Honeywell International Inc. sits within the sensor density and edge-computing specialist tier. These three entities collectively illustrate how vendor positioning splits between capital-intensive hardware margins and recurring software subscription models.
| Leading Market Players |
|---|
| Siemens AG |
| ABB |
| Schneider Electric SE |
| Eaton Corporation |
| IBM Corporation |
| Honeywell International Inc. |
| Johnson Controls International |
| Emerson Electric Company |
| General Electric Company |
| Others |
Supply & Pricing Matrix
Copper futures on the London Metal Exchange and rare earth oxide benchmarks from Chinese spot markets cascade through controller fabrication costs into three-tier pricing structures across premium, standard, and economy levels. Procurement managers in Germany's commercial real estate sector absorb these input shifts through multi-year facilities management contracts that bundle hardware and software subscriptions.
Pricing Analysis
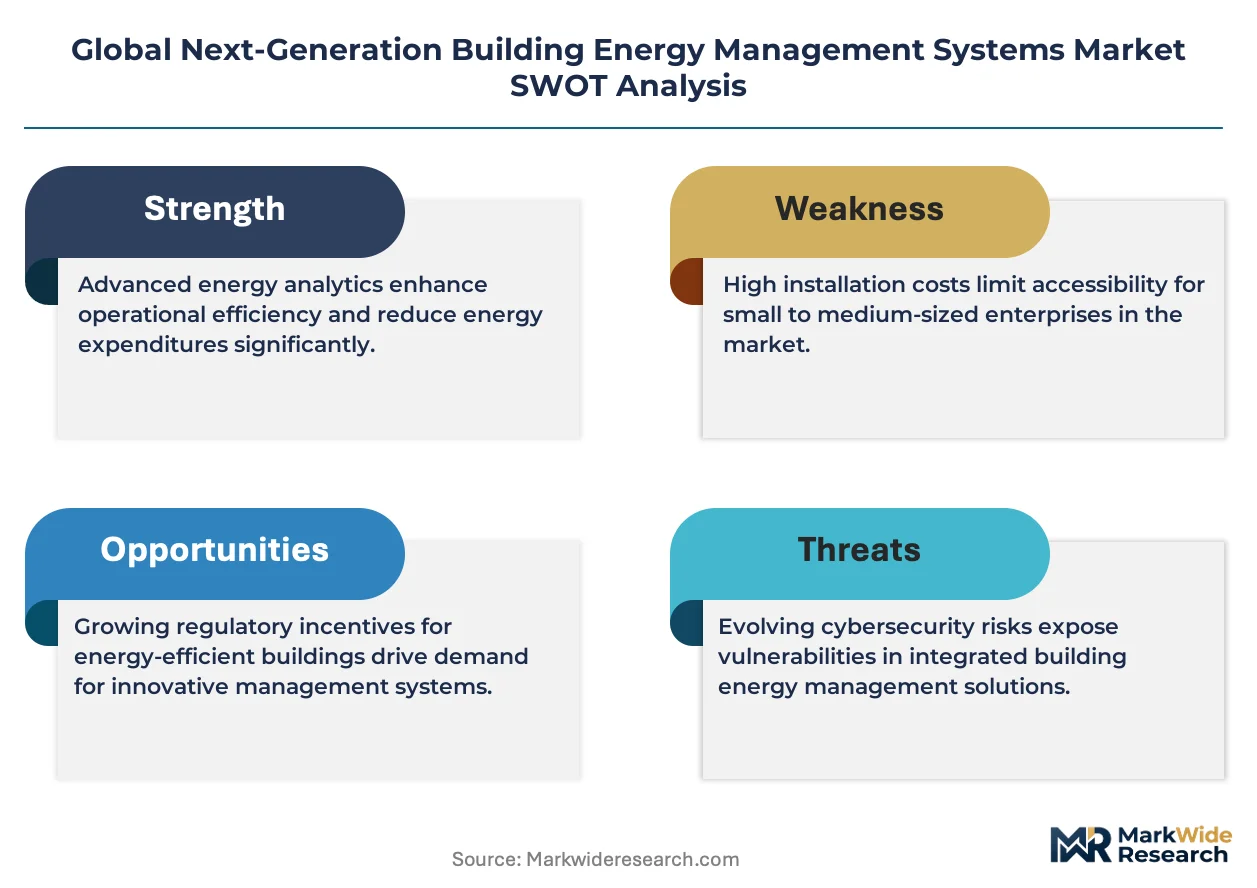
Margin tightening in hardware controllers reflects persistent commodity cost pressure from Asian foundry capacity constraints. Three-tier pricing structure across premium, standard, and economy levels stratifies by cybersecurity certification grade and sensor density specifications. Cost-down pressure on edge-computing units accelerates because Chinese tier-one city retrofit programs prioritize volume procurement. Data center operators exhibit the least price sensitivity due to mission-critical reliability requirements, while municipal buyers in India's Smart Cities Mission drive the hardest commercial terms.
Supply Chain Analysis
Regional distribution centers in the Yangtze River Delta, North Rhine-Westphalia, and Texas anchor hub-and-spoke patterns for hardware controller fulfillment. Controller production draws from concentrated semiconductor foundry capacity in Taiwan and South Korea, with rare earth magnet supply tethered to Chinese processing facilities. Single-source vulnerability in advanced sensor MEMS fabrication creates exposure to export licensing restrictions. Distribution runs through property service conglomerates in Germany and utility-aligned channel partners in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive sensor manufacturing and cloud-native software development distinguishes winners from margin-compressed hardware assemblers. Players securing upstream control over edge-computing chip supply and downstream ownership of facilities management contracts capture durable pricing power.
For Market Incumbents: Cement platform stickiness through backward integration into sensor manufacturing and exclusive certification partnerships with Germany's property service conglomerates. Schneider Electric's end-to-end software positioning demonstrates how unified HVAC-occupancy-analytics platforms defend against point-solution disaggregation. Prioritize IEC 62443 compliance investment to extend qualification moats. For New Entrants and Emerging Players: Capture white-space demand in India's Smart Cities Mission by targeting IT park clusters in Maharashtra and Karnataka with cost-optimized IoT architectures. Outcome-based energy performance contracts offer the most penetrable entry path, aligning vendor compensation with verified consumption reductions through shared-savings models that bypass incumbent procurement relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier systems integration specialists with OT-IT cross-functional engineering talent in France's Auvergne-Rhône-Alpes cluster. Long-term viability hinges on digital twin service layer development merging building information modeling with real-time sensor telemetry. Watch for inflection when utility incentive program pre-qualification thresholds tighten in California and New York.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Service Layer Development | Merges static BIM data with dynamic operational telemetry for predictive simulation across multi-site portfolios. |
| Backward Integration into Sensor Manufacturing | Captures margin from MEMS fabrication and reduces exposure to Asian foundry capacity volatility. |
| IEC 62443 Cybersecurity Certification | Extends product development timelines but creates qualification barriers against uncertified competitors. |
| Outcome-Based Energy Performance Contracts | Aligns vendor compensation with verified consumption reductions through shared-savings models. |
| Smart Cities Mission Partnership | Opens scalable deployment pathways in India's municipal and commercial building digitization programs. |
Research Methodology
Multi-period observation of EU Green Deal retrofit timelines, F-Gas Regulation enforcement patterns, and China's GB standards compliance rates anchored the trend analysis, supplemented by interviews with facilities management directors, building automation engineers, commercial real estate investment trust sustainability officers, and utility demand response program managers. Secondary validation drew from EPA energy efficiency guideline filings, EIA commercial building consumption surveys, MIIT smart meter rollout disclosures, and SEC 10-K hardware margin disclosures. Bottom-up project pipeline aggregation triangulated against top-down regulatory mandate sizing.
The input-output matrix framed demand as a function of compliance-driven replacement cycles, utility incentive program expansion, and software subscription conversion rates across the projection horizon. Segmentation dimensions modeled include product type, technology layer, application function, and end-user vertical. CAGRs derived from fitted adoption curves incorporating regulatory deadline clustering and technology cost reduction trajectories. Forecast inputs included semiconductor foundry capacity utilization rates and copper price volatility indices.
The model holds under stable regulatory enforcement timelines and commodity price bands; deviation in trade policy restrictions or cybersecurity certification delays would shift hardware controller availability and software platform deployment rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
AI Water Heater Market
Energy Management Systems
North America Energy Management Systems Market
Energy Management Systems
Meter Data Management System Market
Energy Management Systems
Portable Air Cooler Market
Energy Management Systems
Smart Programmable Thermostat Market
Energy Management Systems
Saudi Arabia Portable Air Conditioner Market
Energy Management Systems
Data Center Power Management Market
Energy Management Systems
Mobile Metering System Market
Energy Management Systems
Intelligent PDU Market
Energy Management Systems
Noise Mitigation System Market
Energy Management Systems
Cooling Management System Market
Energy Management Systems
Smart HVAC Controls Market
Energy Management Systems
Airflow Management Market
Energy Management Systems
Smart Utilities Management Market
Energy Management Systems
US Energy Management Systems Market
Energy Management Systems
AI-Driven Lighting Controls Market