
 Portable Air Cooler Market | 2026-2036
Portable Air Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Air Cooler Market Outlook
Market Context
Evaporative cooling technology is tilting toward honeycomb pad architectures with variable-speed DC motors, replacing traditional fiber pad systems. Symphony Limited leverages backward integration into plastic component molding to protect margins on mini cooler lines. Honeywell International Inc. competes through channel control in North American big-box retail, while Havells India Ltd. dominates domestic distribution with captive service networks across tier-two cities.
Technical Definition and Segment Structure
A portable air cooler is a mobile evaporative cooling device that draws warm ambient air through water-saturated cooling media—typically cellulose honeycomb pads with 70-90% saturation efficiency—to produce cooled, humidified air output measured in cubic feet per minute. Its primary commercial purpose is spot cooling in dry climates where refrigeration-based air conditioning proves economically or electrically impractical. The product type dimension shows evaporative coolers anchoring volume while tower coolers capture premium positioning in compact urban residential spaces. Among end users, event organizers represent the fastest-growing category as temporary outdoor cooling infrastructure becomes non-negotiable for hospitality and sports programming.
Regulatory Frame and Outlook
The US Department of Energy and India's Bureau of Energy Efficiency set minimum performance standards that filter low-efficiency imports from mass-market shelves. Europe's Ecodesign Directive and REACH chemical compliance raise cost barriers for pad material suppliers serving export-oriented manufacturers. Stakeholders must monitor how refrigerant-phaseout timelines in parallel cooling categories redirect R&D budgets toward evaporative efficiency gains.
Market Dynamics
The portable air cooler market is being restructured by the US Department of Energy's escalating minimum efficiency standards, which are systematically filtering low-performance evaporative units from mass-market distribution and forcing manufacturers toward honeycomb pad architectures with DC motor integration.
Growth Catalysts
- Extreme heat adaptation:Grid instability across India drives residential uptake of low-power cooling alternatives as primary air conditioning substitutes in tier-two and tier-three urban clusters.
- Event infrastructure mandates:Temporary outdoor cooling has become non-negotiable for hospitality and sports programming, accelerating procurement cycles among event organizers.
- REACH chemical compliance:European pad material regulations raise cost barriers for export-oriented manufacturers, creating protected domestic markets for compliant producers.
Market Restraints
- Climate dependency ceiling:Evaporative cooling effectiveness collapses above 70% relative humidity, restricting addressable markets to arid and semi-arid zones.
- Cellulose pad supply concentration:Honeycomb cooling media production clusters in select Asian manufacturing hubs, exposing buyers to input volatility and extended lead times.
- Refrigeration substitution threat:Falling inverter AC prices in developing markets erode the economic case for evaporative cooling in middle-income households.
Strategic Opportunities
- India's Bureau of Energy Efficiency star labeling:Compliance differentiation creates premium positioning for five-star rated units in price-sensitive residential segments.
- Solar-DC convergence:Integration with photovoltaic off-grid systems opens rural electrification corridors where grid-connected cooling remains unreliable.
- Commercial rental channel expansion:Equipment-as-a-service models for construction sites and outdoor venues bypass capital expenditure barriers for intermittent users.
Industry Challenges
- Cross-functional engineering scarcity:Simultaneous competence in thermal physics, DC motor control, and IoT integration remains concentrated among a narrow specialist cohort.
- Multi-jurisdiction certification timelines:Parallel efficiency testing protocols across the US DOE, India's BEE, and EU Ecodesign extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Air Cooler Market |
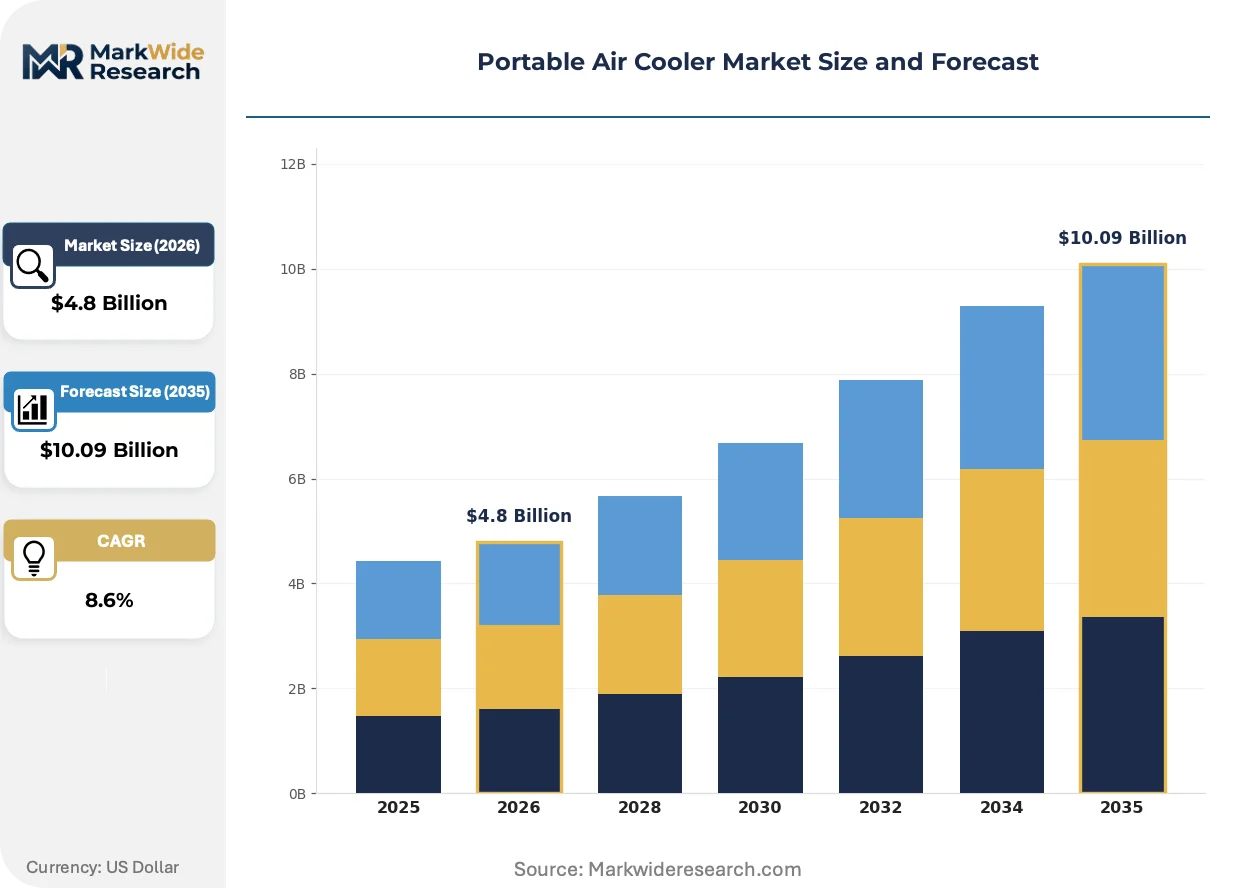
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Evaporative Coolers, Mini Coolers, Tower Coolers, Window Coolers End User: Residential Users, Commercial Users, Industrial Users, Event Organizers Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors Cooling Capacity: 1000-3000 CFM, 3000-5000 CFM, 5000-7000 CFM, 7000+ CFM |
| Companies Covered | Symphony Limited, The Whirlpool Corporation, Honeywell International Inc., NewAir, Bajaj Electricals Ltd, Hessaire, Havells India Ltd., Panasonic Corporation, Portacool, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Air Cooler Market Strategic Shifts
Product architecture is compressing around integrated smart control systems and variable-speed drive technology, while regulatory fragmentation across major economies forces parallel development tracks rather than unified global platforms.
Honeycomb cellulose pad systems with 70-90% saturation efficiency are collapsing the performance gap between portable evaporative units and entry-level refrigerated air conditioning in dry climate zones. Event organizers and construction site managers are adopting these systems at accelerating pace for spot cooling applications. The technology is collapsing price resistance among commercial buyers who previously dismissed evaporative cooling as inadequate for professional use.
India's Bureau of Energy Efficiency has implemented mandatory star rating standards for evaporative air coolers, creating a two-tier market split between compliant and non-compliant manufacturers. Domestic producers have responded by backward integrating into plastic component molding to protect margins on mini cooler lines. The regulation is concentrating volume among integrated manufacturers while import-dependent assemblers retreat to unregulated rural distribution channels.
Buying committees at commercial end-users are unbundling after-sales service from equipment procurement, creating standalone service contract markets that alter vendor economics. Traditional distributors with captive technician networks retain advantage in tier-two Indian cities where third-party service density remains thin. This pattern is most visible in Maharashtra and Gujarat states, where commercial penetration of portable cooling has outpaced service infrastructure buildout.
Portable Air Cooler Market Segmentation
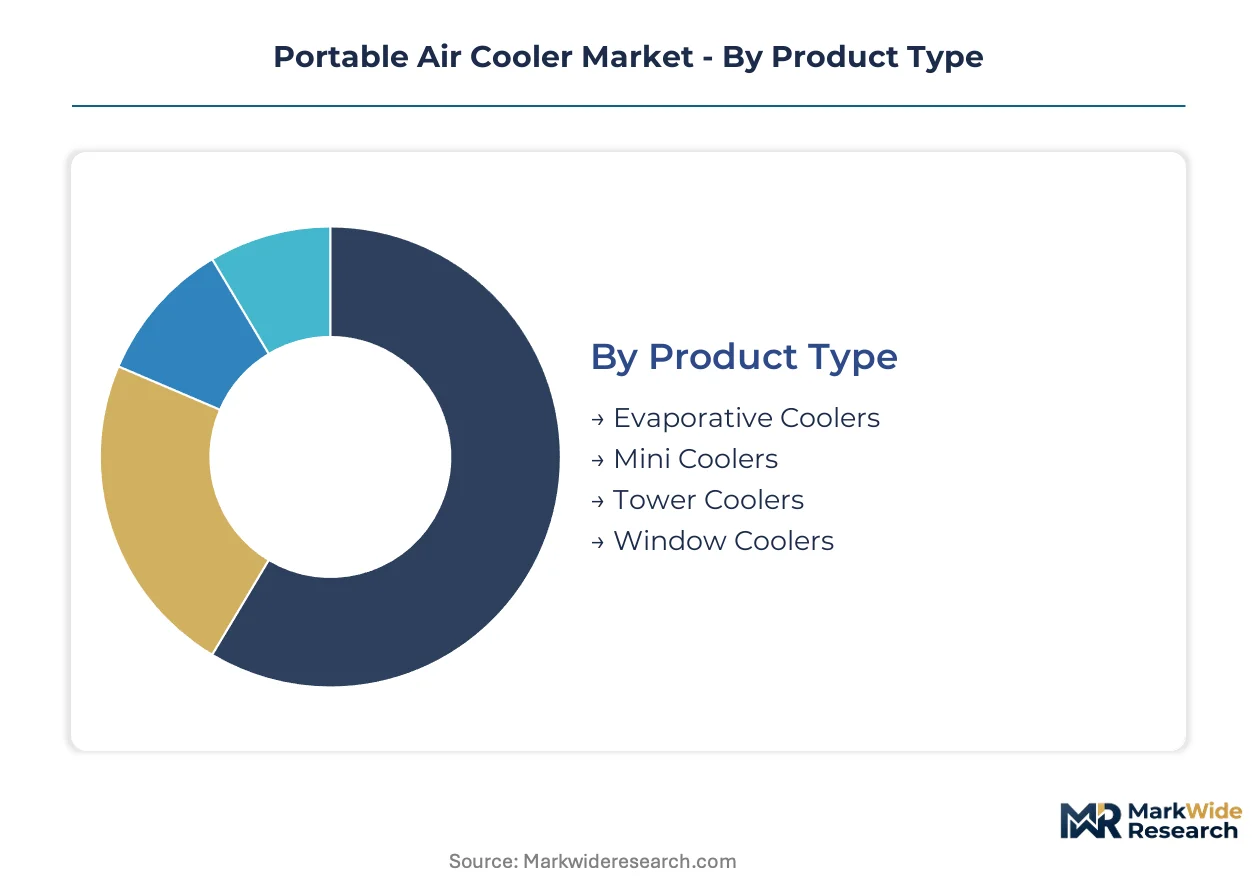
Segmentation in the portable air cooler market reveals divergent replacement cycles and margin structures across product architectures. Understanding these patterns allows manufacturers to allocate R&D and channel investments toward segments with optimal velocity and profitability profiles.
Product Type:
Replacement cycles stretch from 3-4 years for mini coolers to 7-10 years for window-mounted units, creating distinct inventory and service revenue models for each tier.
- Evaporative Coolers:Cellulose honeycomb pad systems with 70-90% saturation efficiency dominate this core category. Demand concentrates in Indian residential markets where grid instability drives preference for low-power cooling alternatives over refrigerated air conditioning.
- Tower Coolers:Vertical form factors with compact footprints capture premium positioning in dense urban residential spaces. Mumbai and Delhi apartment complexes show strongest uptake where floor space constraints override absolute cooling capacity requirements.
- Mini Coolers:Portable units under 20 liters capacity serve desk-side spot cooling in small commercial settings.
- Window Coolers:Fixed-installation units trade mobility for higher airflow capacity and structural durability.
Evaporative coolers anchor the volume base while tower coolers gain share at the steepest rate.
End User:
Procurement authority and specification complexity vary sharply across buyer types, from individual household decision-making to formal tender processes at industrial sites.
- Event Organizers:Temporary outdoor cooling infrastructure has become non-negotiable for hospitality and sports programming. Stadium operators and wedding venue managers in Rajasthan and Gujarat drive accelerating procurement cycles for rental and purchase models.
- Residential Users:Individual households in tier-two and tier-three Indian cities deploy portable coolers as primary cooling substitutes. BEE star rating compliance now filters purchase decisions in price-sensitive segments.
- Commercial Users:Small retail shops and restaurants require spot cooling for customer zones and kitchen areas.
- Industrial Users:Factory floor cooling and worker rest area climate control operate under capital expenditure approval workflows.
Residential users provide the installed base foundation while event organizers expand most quickly.
Distribution Channel:
Channel economics split between high-velocity online transactions and service-embedded offline relationships with divergent margin capture potential.
- Offline Retail:Electronics chains and appliance stores in Indian tier-two cities bundle installation and annual maintenance contracts. Captive technician networks in Maharashtra and Gujarat states create switching costs that protect vendor economics.
- Online Retail:E-commerce platforms compress discovery-to-purchase timelines for replacement buyers. Amazon and Flipkart dominate volume in metro markets where consumers prioritize price transparency over hands-on evaluation.
- Direct Sales:Manufacturer-owned channels serve large commercial accounts with customized specifications.
- Distributors:Regional wholesalers extend reach into rural markets beyond direct retail coverage.
Offline retail secures the margin pool while online retail scales fastest in absolute transaction volume.
Cooling Capacity:
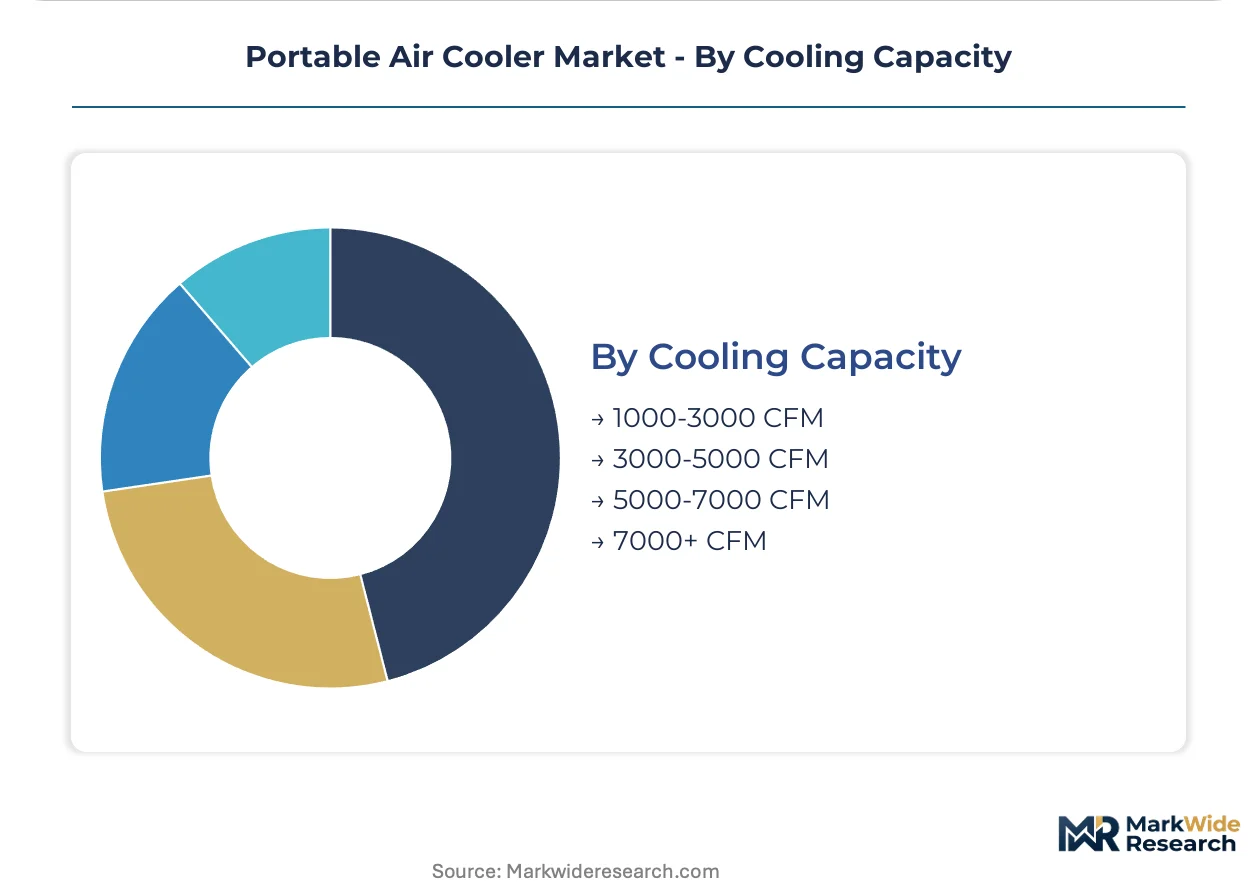
Capacity tiering aligns with square footage coverage requirements and power consumption trade-offs that vary by climate zone and grid reliability.
- 3000-5000 CFM:Mid-range output serves 200-400 square foot residential and small commercial spaces. This bracket captures the highest shipment volumes in Indian urban markets where typical apartment dimensions cluster within this coverage zone.
- 1000-3000 CFM:Entry-level output targets single-room cooling in budget-constrained households. Rajasthan and interior Maharashtra show concentration where evaporative efficiency matters most.
- 5000-7000 CFM:High-output units cover large open-plan commercial areas and small industrial bays.
- 7000+ CFM:Maximum capacity segment serves warehouse-scale applications and outdoor event cooling infrastructure.
3000-5000 CFM units dominate shipment volume while 5000-7000 CFM brackets climb fastest in commercial penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Event organizers and construction site managers concentrate procurement authority across arid climate zones, with residential buyers in grid-unstable regions driving volume displacement from refrigerated air conditioning.
India
Rajasthan and Gujarat households deploy portable coolers as primary cooling substitutes amid extreme heat waves and unreliable grid infrastructure. The Bureau of Energy Efficiency's mandatory star rating standards filter purchase decisions toward five-star certified units. Symphony Limited anchors manufacturing in Gujarat with backward integration into plastic component molding for mini cooler lines.
United States
Stadium operators and wedding venue managers in Arizona and Texas drive accelerating procurement for temporary outdoor cooling infrastructure. The Department of Energy's escalating minimum efficiency standards filter low-performance evaporative units from mass-market distribution. Honeywell International Inc. exercises channel control through big-box retail partnerships in Southwestern metropolitan markets.
United Arab Emirates
Hospitality developers in Dubai and Abu Dhabi specify portable cooling for outdoor event spaces and construction worker rest areas. The country's national energy efficiency regulator enforces cooling performance standards aligned with Gulf Cooperation Council harmonization. Equipment rental channels expand fastest in Sharjah's industrial zones where intermittent users bypass capital expenditure barriers.
Australia
Mining site managers in Western Australia and Queensland procure high-capacity units for worker accommodation cooling in remote locations. The national standards body maintains evaporative cooling efficiency protocols under the Equipment Energy Efficiency program. Manufacturing input sourcing concentrates in Melbourne's industrial suburbs where cellulose pad distributors maintain regional warehousing.
Germany
Outdoor festival organizers in Bavaria and North Rhine-Westphalia face REACH chemical compliance requirements for cooling pad materials. The Ecodesign Directive raises cost barriers for import-dependent assemblers serving European markets. Industrial equipment rental networks in Hamburg and Munich metropolitan areas capture commercial procurement through equipment-as-a-service contracts.
Portable Air Cooler Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market strata. The vendor base organizes around three strategic archetypes: integrated manufacturers with captive component supply, multinational electronics conglomerates with retail network dominance, and regional specialists with service-embedded distribution. Competitive moves concentrate on backward integration into cooling media production and geographic expansion through distributor acquisition in tier-two Indian cities.
Within the integrated manufacturing tier, Symphony Limited and Havells India Ltd. exemplify players with captive supply chains and domestic distribution depth. Honeywell International Inc. occupies a position representing multinational channel control through North American retail partnerships. Bajaj Electricals Ltd. anchors the electrical goods conglomerate archetype with cross-category brand recognition in Indian consumer markets.
| Leading Market Players |
|---|
| Symphony Limited |
| The Whirlpool Corporation |
| Honeywell International Inc. |
| NewAir |
| Bajaj Electricals Ltd |
| Hessaire |
| Havells India Ltd. |
| Panasonic Corporation |
| Portacool |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Indian cellulose honeycomb pad manufacturing is compressing input costs for domestic assemblers while simultaneously eroding supplier pricing power across export-oriented tiers. This utilization dynamic is forcing tier-one manufacturers toward backward integration into plastic component molding to defend margin structures on mini cooler lines.
Pricing Analysis
Cost-plus contracts indexed to cellulose pulp commodity benchmarks dominate procurement between pad suppliers and cooler assemblers. Price differentiation hinges on BEE star certification tier and captive service network coverage, with five-star rated units commanding premium positioning in Maharashtra and Gujarat. Pricing pressure stems from falling inverter AC prices in developing markets. Residential buyers in tier-three cities exhibit highest price sensitivity, while event organizers prioritize reliability over unit economics.
Supply Chain Analysis
Export-control regimes under India's DGFT restrict technology transfer for DC motor control systems, fragmenting component sourcing strategies. Honeycomb cooling media production clusters in India, China, and Vietnam, while variable-speed motor controllers draw from South Korean and Taiwanese semiconductor fabs. Single-source vulnerability concentrates in cellulose pad supply where three Asian hubs control capacity. Distribution runs through electronics chains in tier-two Indian cities that bundle installation and annual maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The portable air cooler market represents a high-growth disruption as mandatory BEE star labeling and DOE efficiency standards simultaneously reshape competitive entry barriers and procurement criteria across multiple geographies.
For Market Incumbents: Pre-empt refrigeration substitution threats by accelerating DC motor and IoT control integration before inverter AC prices compress the economic case for evaporative cooling in middle-income households. Backward integration into honeycomb pad production secures input cost stability against cellulose pulp volatility. Channel control through captive technician networks in tier-two cities creates switching costs that protect vendor economics from online retail price transparency. For New Entrants and Emerging Players: Establish a beachhead in commercial rental channels for construction sites and outdoor venues where equipment-as-a-service models bypass capital expenditure barriers for intermittent users. Solar-DC convergence applications in rural electrification corridors offer white-space penetration where grid-connected cooling remains unreliable. Target procurement committees at stadium operators and wedding venue managers through performance-based cooling guarantees rather than unit sales. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across mini cooler manufacturing as plastic component molding automation reduces labor content per unit. Long-term viability favors integrated manufacturers with captive supply chains over import-dependent assemblers retreating to unregulated rural channels. Watch BEE compliance enforcement intensity as the signal indicating whether premium positioning for five-star rated units sustains or collapses toward commoditization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cooling Media | Captive honeycomb pad production insulates Symphony Limited from cellulose pulp price volatility. |
| DC Motor and Smart Control Integration | Variable-speed drive technology collapses performance gaps with entry-level refrigerated air conditioning. |
| Commercial Rental Channel Expansion | Equipment-as-a-service models unlock procurement from construction sites and outdoor venues. |
| BEE Five-Star Certification Investment | Compliance differentiation creates premium positioning in price-sensitive residential segments. |
| Solar-DC System Convergence | Photovoltaic integration opens rural electrification corridors beyond grid-connected cooling reach. |
Study Parameters
A spread of perspectives from plant engineers at cooling media manufacturers, procurement leads at electronics retail chains, regulatory affairs specialists at BEE and DOE, and aftermarket service heads converged on the working assumptions. Secondary validation drew from customs trade data, Bureau of Energy Efficiency star rating registries, SEC filings of listed appliance manufacturers, and Equipment Energy Efficiency program disclosures. Bottom-up shipment data triangulated against top-down capacity estimates across Indian, Chinese, and Vietnamese manufacturing hubs.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation across product architecture, end-user procurement authority, distribution channel economics, and cooling capacity tier. CAGRs derived from fitted growth curves applied to replacement cycle patterns and penetration rate assumptions. Forecast inputs incorporated grid instability indices for Indian states and inverter AC price elasticity estimates for middle-income household segments.
Stress conditions across cellulose pulp commodity bands, BEE enforcement intensity, and DC motor controller availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding climate zone concentration and regulatory harmonization timelines. Material shifts in inverter AC cost curves or REACH chemical compliance scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Building Energy Management Systems (BEMS) Market
Energy Management Systems
United Arab Emirates Portable Air Conditioning Market
Energy Management Systems
Wi-Fi Smart Thermostat Market
Energy Management Systems
Noise Mitigation System Market
Energy Management Systems
Airflow Management Market
Energy Management Systems
North America Residential Lighting Control System Market
Energy Management Systems
Smart Climate Control Market
Energy Management Systems
Asia-Pacific Energy Management System Market
Energy Management Systems
Africa Digital Showers Market
Energy Management Systems
Chemical Control Systems Market
Energy Management Systems
Shared Power Bank Market
Energy Management Systems
IoT Smart Gas Meter Market
Energy Management Systems
EV Smart HVAC System Market
Energy Management Systems
Global Variable Air Volume (VAV) System Market
Energy Management Systems
IoT Energy Management Market
Energy Management Systems
Energy Management in Data Centers Market