
 Smart Programmable Thermostat Market | 2026-2036
Smart Programmable Thermostat Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Programmable Thermostat Market Insights
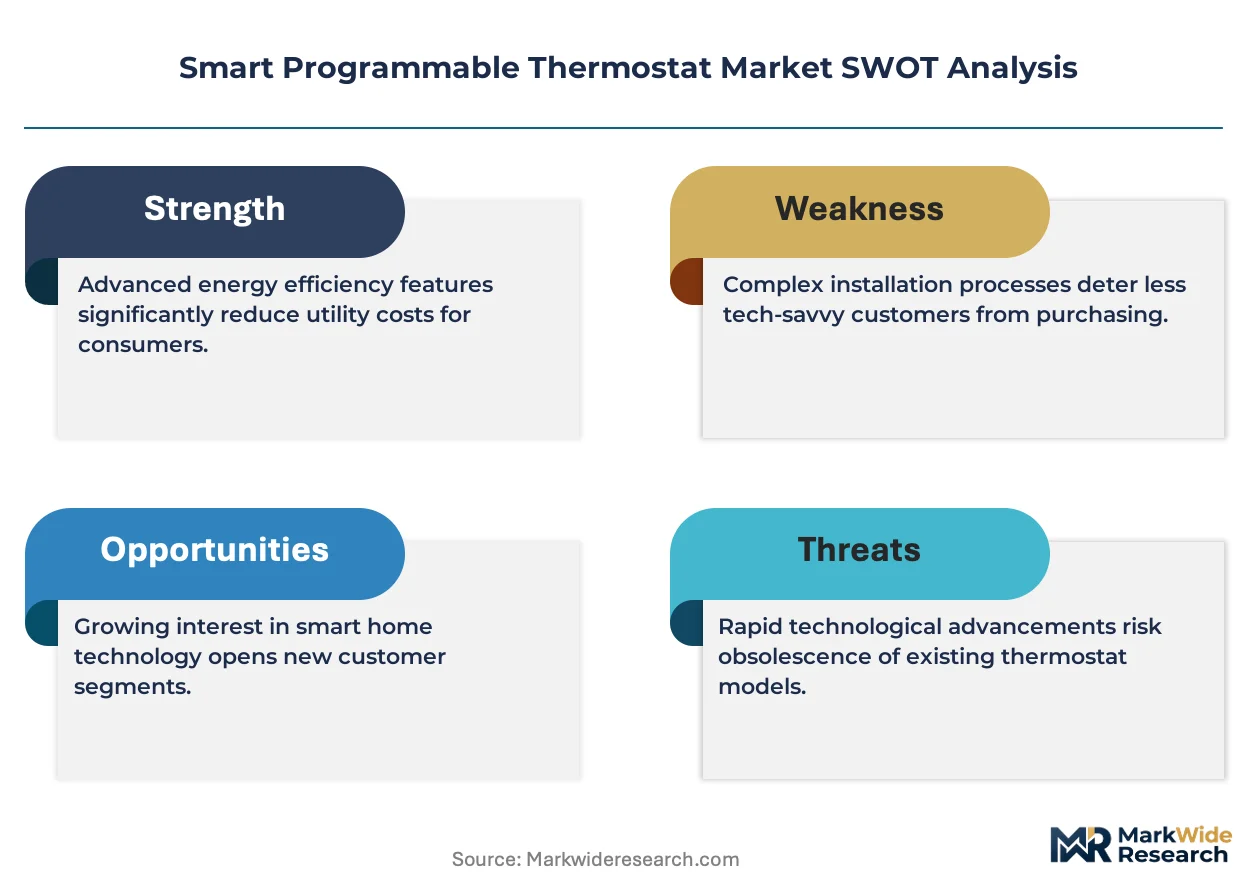
Aftermarket service revenue is fragmenting across device ecosystems as manufacturers bundle energy management subscriptions with hardware sales. Alphabet leverages its Google Nest platform to anchor recurring software income through utility partnership integrations. Honeywell International competes through its Resideo spin-off by sustaining professional installer channel control across North American HVAC service networks. Schneider Electric dominates commercial building automation by extending BMS-compatible thermostat lines that occupy premium specification tiers.
A smart programmable thermostat is a digitally controlled environmental regulation device incorporating temperature sensors, relay switches, and network connectivity modules to automate heating, ventilation, and air conditioning cycles based on occupancy patterns and external weather data. Wi-Fi Thermostats lead volume shipments due to their compatibility with existing residential broadband infrastructure and minimal installation complexity. Learning Thermostats capture disproportionate margin pools through AI-driven predictive algorithms that reduce HVAC runtime. Cloud-Connected technology segments are expanding fastest as utilities deploy virtual power plant programs requiring real-time load curtailment signals.
The US Department of Energy partners with EPA under ENERGY STAR certification frameworks to mandate minimum connectivity standards that shape product eligibility for federal rebate programs. The EU F-Gas Regulation and Ecodesign Directive collectively force thermostat manufacturers to integrate heat pump optimization protocols for European market access. Stakeholders must monitor whether emerging building performance standards in California and New York will mandate interoperable demand response APIs as a condition of code compliance.
Market Dynamics
Utility-sponsored demand response programs are restructuring procurement channels by converting individual thermostat sales into bulk volume contracts negotiated between manufacturers and electricity providers, compressing hardware margins while locking in multi-year service revenue streams.
Growth Catalysts
- Inflation Reduction Act rebates:The US IRA's consumer incentives for smart home energy upgrades accelerate hardware replacement cycles among cost-conscious homeowners seeking immediate payback periods.
- Heat pump optimization mandates:The EU F-Gas Regulation and Ecodesign Directive compel thermostat manufacturers to integrate compressor control protocols for European market access, expanding addressable product lines.
- Virtual power plant deployment:Cloud-connected thermostats enable real-time load curtailment for grid balancing, creating new procurement pull from electricity distributors managing peak demand events.
Market Restraints
- Semiconductor supply concentration:Wi-Fi and Bluetooth module sourcing remains concentrated among a limited supplier base in East Asia, exposing production schedules to geopolitical logistics disruptions.
- Installation skill barriers:Low-voltage wiring compatibility with legacy HVAC systems requires certified technician intervention, constraining direct-to-consumer channel penetration for complex multi-zone configurations.
- Interoperability fragmentation:Proprietary smart home protocols from competing ecosystem vendors create integration friction that delays purchasing decisions among multi-brand households.
Strategic Opportunities
- Commercial building automation gaps:Mid-sized office and retail properties remain underpenetrated by connected climate controls, offering expansion paths for BMS-compatible thermostat lines.
- Heat pump retrofit acceleration:European and North American electrification mandates are creating replacement demand for thermostats capable of managing variable-speed compressor operation.
- Utility partnership channels:Direct procurement relationships with electricity providers bypass traditional retail markups while securing guaranteed installation volumes through rebate-aggregated programs.
Industry Challenges
- Cybersecurity certification timelines:UL 2900 and IEC 62443 compliance requirements for connected devices extend product development cycles and increase pre-launch validation costs.
- Legacy HVAC integration complexity:Pneumatic and proprietary control systems in aging commercial buildings demand custom gateway hardware that erodes standard product margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Programmable Thermostat Market |
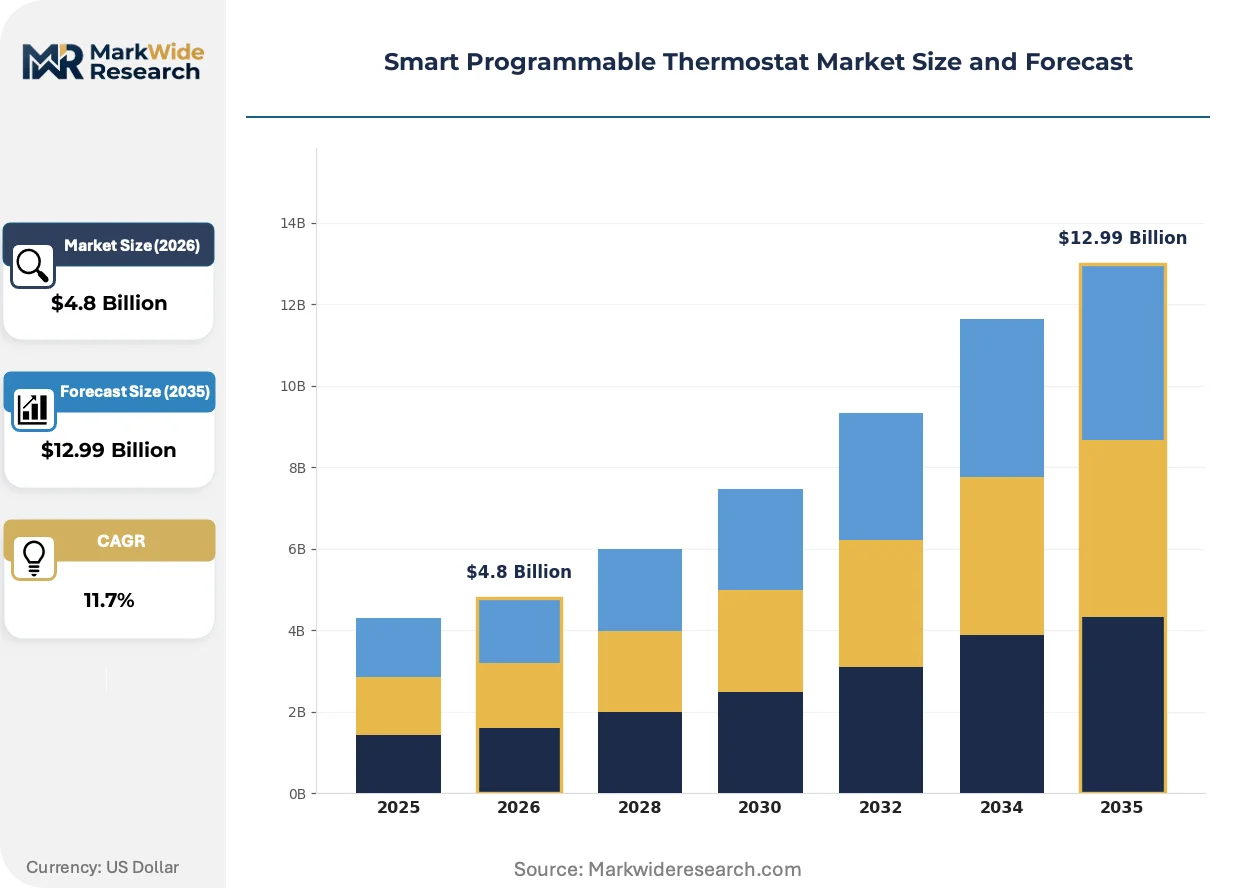
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wi-Fi Thermostats, Learning Thermostats, Smart Radiator Valves, Zigbee Thermostats Technology: Home Automation, Cloud-Connected, Voice-Activated, Mobile App Controlled Installation: DIY Installation, Professional Installation, Retrofits, New Construction End User: Residential Buildings, Commercial Properties, Industrial Facilities, Education Institutions |
| Companies Covered | Alphabet (Google Nest), ecobee, Honeywell International, Emerson Electric, Resideo Technologies, Johnson Controls, Carrier Corporation, Lennox International, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Programmable Thermostat Market Trends and Innovations
Artificial intelligence inference at the network edge is compressing the latency between occupancy detection and climate response, enabling predictive HVAC cycling that reduces runtime without sacrificing comfort thresholds.
Machine learning algorithms embedded directly in thermostat hardware are collapsing the distinction between programmable schedules and real-time adaptive control. Residential adopters in utility-sponsored markets are receiving these capabilities through over-the-air firmware updates. The technology is collapsing energy waste from anticipatory pre-conditioning by correlating occupancy probability with calendar integration and geofencing signals.
The US EPA's ENERGY STAR certification framework now mandates minimum connectivity standards as a condition of rebate eligibility, forcing hardware redesigns among budget-tier manufacturers. Industrial consequence includes the phase-out of standalone programmable models lacking Wi-Fi modules. Residential retrofit segments in California and New York are responding by accelerating replacement timelines ahead of anticipated building performance standard tightening.
Subscription bundling is displacing standalone hardware transactions as the dominant commercial model. Professional installer networks and utility direct channels are capturing buyers who previously purchased through retail. This shift concentrates most visibly in United States markets where demand response program enrollment ties hardware subsidies to multi-year service commitments.
Smart Programmable Thermostat Market Segmentation
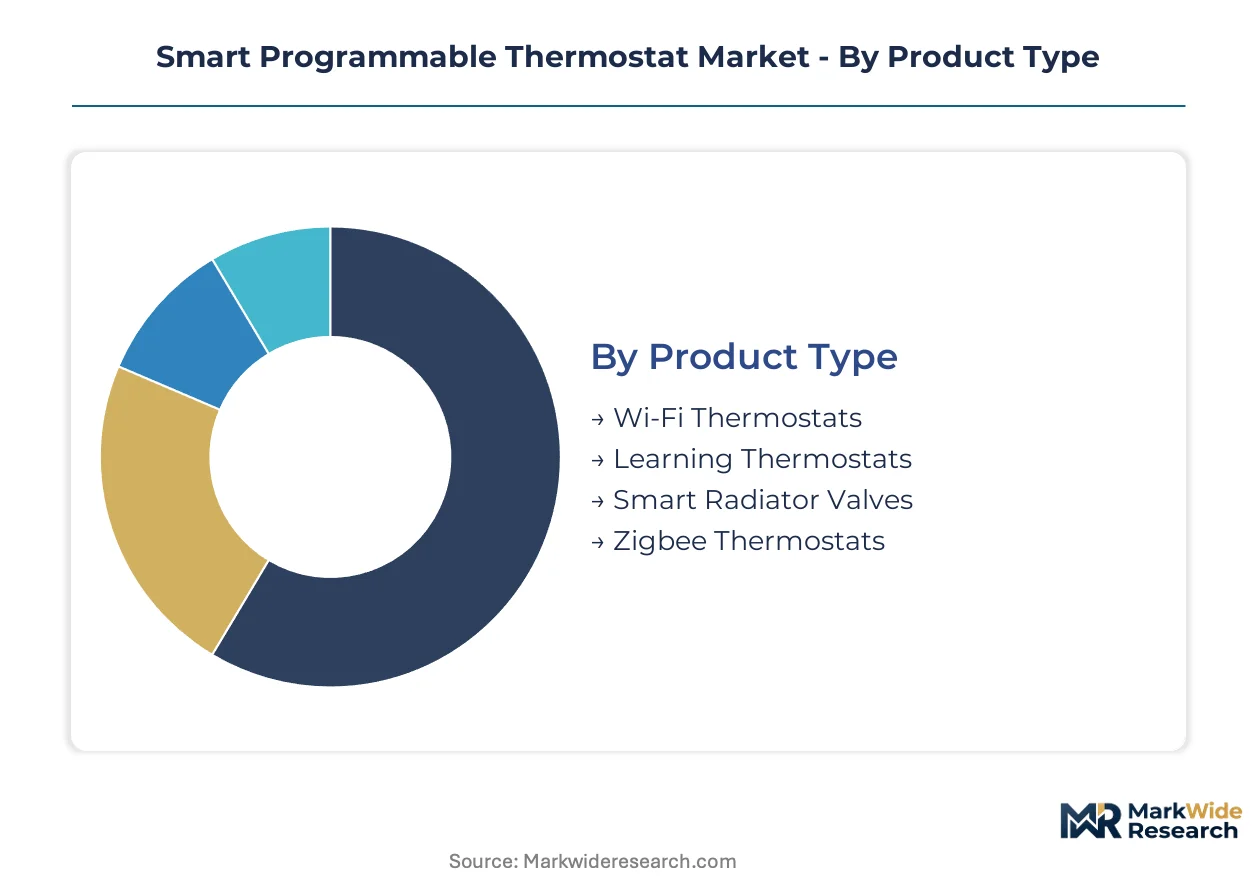
Smart programmable thermostat segmentation reveals how hardware specifications, connectivity protocols, and installation requirements fragment addressable demand across radically different buyer workflows. Product architecture choices directly determine channel economics, from mass-market retail through utility bulk procurement to certified technician networks.
Product Type:
Mature Wi-Fi-based devices anchor volume shipments while emerging AI-enabled learning systems capture premium positioning.
- Wi-Fi Thermostats:These devices integrate standard IEEE 802.11 connectivity modules enabling remote temperature adjustment through residential broadband infrastructure. Demand concentrates among US homeowners participating in utility-sponsored demand response programs where rebate eligibility requires internet-connected hardware. Installation simplicity drives direct-to-consumer channel penetration.
- Learning Thermostats:Embedded machine learning algorithms analyze occupancy patterns and weather data to autonomously optimize HVAC cycling schedules. These systems command margin premiums in California and New York metro markets where building performance standards tighten and energy cost sensitivity runs highest among affluent households.
- Smart Radiator Valves:Zone-level temperature controllers for hydronic heating systems, prevalent in European retrofit applications.
- Zigbee Thermostats:Low-power mesh network devices targeting integrated smart home ecosystems with local hub dependency.
Wi-Fi Thermostats retain volume leadership; Learning Thermostats hold the steepest expansion curve.
Technology:
Cost tier stratification separates cloud-dependent subscription models from standalone automation systems with limited connectivity.
- Home Automation:Local protocol-based systems integrating with broader smart home ecosystems through Z-Wave or Zigbee hubs. Demand clusters among early adopter households in Germany and the Netherlands where multi-vendor interoperability ranks as a purchase priority.
- Cloud-Connected:Continuous internet-dependent architectures enabling real-time load curtailment signals for virtual power plant programs. US electricity distributors in Texas and California drive procurement through direct manufacturer partnerships that aggregate installation volumes.
- Voice-Activated:Hands-free control interfaces leveraging natural language processing for temperature adjustments.
- Mobile App Controlled:Smartphone-dependent interfaces requiring no dedicated hub hardware, dominant in entry-tier pricing bands.
Cloud-Connected systems are climbing the fastest as utility procurement accelerates; Home Automation maintains installed base dominance.
Installation:
Customer type fragmentation splits between technically confident consumers and buyers requiring certified technician intervention.
- DIY Installation:Battery-powered or two-wire configurations compatible with standard HVAC systems and supported by manufacturer video guidance. This segment expands among single-family homeowners in the US Southeast where contractor availability lags replacement demand.
- Professional Installation:Low-voltage wiring and multi-zone control configurations requiring EPA Section 608 certified technician handling. Commercial properties and heat pump retrofits in the US Northeast and Pacific Northwest generate concentrated demand through Resideo and independent HVAC service networks.
- Retrofits:Replacement installations into existing buildings with legacy control infrastructure.
- New Construction:Pre-wired installations during building development with integrated smart home specification.
Professional Installation captures the highest value per unit; DIY Installation is expanding most quickly through retail and direct-to-consumer channels.
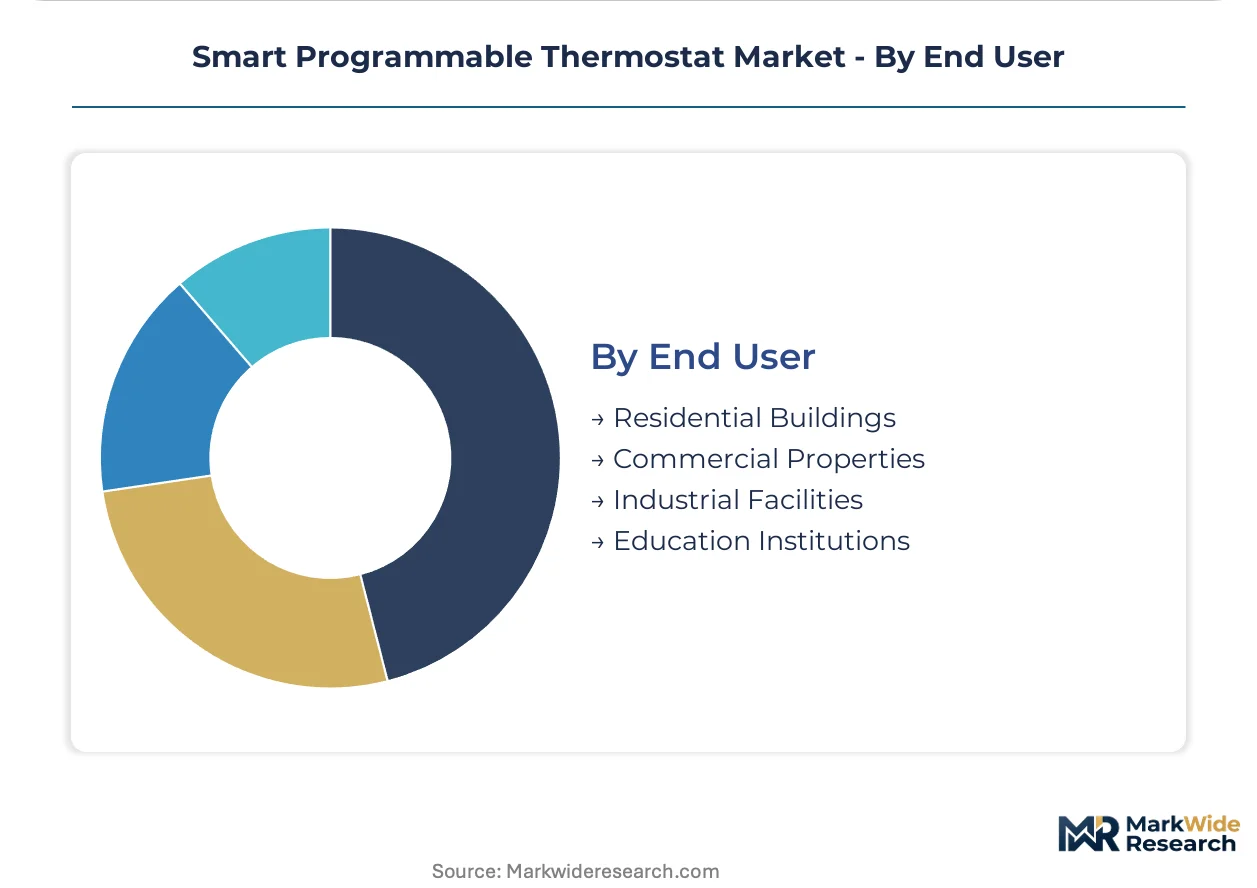
End User:
Application maturity varies sharply between saturated residential replacement cycles and underpenetrated commercial automation gaps.
- Residential Buildings:Single and multi-family dwellings where homeowners prioritize energy cost reduction and rebate capture. The US Inflation Reduction Act's consumer incentives accelerate hardware turnover in suburban markets across Texas, Florida, and Arizona where cooling loads dominate utility bills.
- Commercial Properties:Office, retail, and hospitality facilities requiring building management system integration and centralized facility control. Mid-sized properties in France and Italy remain underpenetrated, offering expansion paths for BMS-compatible thermostat lines from Schneider Electric and Siemens.
- Industrial Facilities:Manufacturing and warehouse environments with specialized environmental control requirements.
- Education Institutions:K-12 and university campuses with deferred maintenance backlogs and centralized procurement processes.
Residential Buildings retain volume leadership; Commercial Properties hold the steepest expansion curve as building automation standardizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in North American and European manufacturing clusters where utility partnerships and regulatory mandates accelerate hardware deployment cycles. The United States dominates procurement volumes through IRA-linked rebate programs. Germany and France anchor European specification standards through Ecodesign and F-Gas enforcement.
United States
Utility-sponsored demand response programs in Texas and California drive bulk procurement through direct manufacturer partnerships. The Inflation Reduction Act's consumer rebates compress payback periods for homeowners in cooling-dominated markets. The Dallas-Fort Worth metro cluster hosts concentrated HVAC distribution networks serving the Southeast replacement cycle.
Germany
Heat pump retrofit mandates under the EU F-Gas Regulation create replacement demand for compressor-optimized thermostats. The national building energy efficiency framework tightens specification requirements for connected climate controls. The Rhine-Ruhr industrial corridor anchors distribution logistics for Central European retrofit contractors.
France
Mid-sized commercial properties in Île-de-France remain underpenetrated by building management system integration. The national low-carbon transition strategy mandates smart metering compatibility for rebate-eligible installations. The Lyon-Grenoble corridor concentrates HVAC service networks serving alpine climate zones with high heating loads.
United Kingdom
Net-zero building standards in London and Southeast England accelerate replacement of standalone programmable models. Ofgem's smart meter rollout creates infrastructure for real-time tariff optimization features. The Manchester-Leeds corridor hosts installer networks capturing northern England's social housing retrofit programs.
China
Dual carbon policy targets drive building automation procurement in commercial property development. MIIT connectivity standards shape product certification for smart home ecosystem integration. The Yangtze River Delta manufacturing cluster produces Wi-Fi modules supplying regional thermostat assembly operations.
Smart Programmable Thermostat Market Competitive Landscape
Technology conglomerates and specialized climate control manufacturers split the market across divergent channel strategies. Platform-anchored players bundle subscription services with hardware to capture recurring revenue streams. HVAC-incumbent specialists leverage installer network relationships to defend specification positions in commercial retrofits. Consolidation pressure intensifies as utility procurement contracts favor vendors with multi-year service infrastructure.
Within the platform-ecosystem tier, Alphabet and ecobee exemplify software-forward positioning through utility partnership integrations. Honeywell International and its Resideo spin-off occupy the professional-installer channel, anchoring specification control across North American service networks. Johnson Controls and Schneider Electric represent the building-automation incumbent archetype, extending BMS-compatible lines into premium commercial tiers.
| Leading Market Players |
|---|
| Alphabet (Google Nest) |
| ecobee |
| Honeywell International |
| Emerson Electric |
| Resideo Technologies |
| Johnson Controls |
| Carrier Corporation |
| Lennox International |
| Schneider Electric |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Wi-Fi module fabrication across the Yangtze River Delta is compressing component costs while concentrating bargaining power among thermostat assemblers who can guarantee volume throughput to semiconductor foundries.
Pricing Analysis
The US Inflation Reduction Act dictates the pricing tier structure by tying rebate eligibility to ENERGY STAR certification thresholds. Three-tier pricing structure across premium, standard, and economy levels separates learning thermostats with AI-enabled optimization from basic Wi-Fi models and uncertified legacy devices. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because utility bulk procurement contracts squeeze hardware margins in exchange for multi-year service commitments. Residential homeowners participating in demand response programs exhibit the highest price sensitivity, while commercial facility managers prioritize BMS integration over unit cost.
Supply Chain Analysis
Export controls on advanced wireless communication chipsets limit flows from specific East Asian suppliers to North American assembly operations. Manufacturing concentrates in China, Mexico, and Vietnam, with the latter serving as a rerouting hub for tariff-sensitive component flows. Raw material dependencies include lithium for battery-backed units, copper for low-voltage wiring harnesses, and rare earth elements for sensor magnets. Single-source vulnerability in Bluetooth module sourcing exposes production schedules to geopolitical logistics disruptions. Distribution runs through HVAC wholesaler networks in North America and electrical supply chains in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Utility partnership subscriptions are expanding faster than hardware shipments, converting transactional thermostat sales into recurring energy management revenue streams that improve customer lifetime value metrics.
For Market Incumbents: Entrench specification control by deepening certified technician channel relationships across Resideo and independent HVAC service networks. Acquire cloud-software capabilities to defend against platform-anchored competitors like Alphabet who bundle AI-driven optimization with hardware subsidies. Prioritize UL 2900 cybersecurity certification investment to meet tightening procurement standards from electricity distributors. For New Entrants and Emerging Players: Build out heat pump optimization expertise to capture European retrofit demand under F-Gas Regulation mandates. Target mid-sized commercial properties in France and Italy where BMS integration gaps remain widest. Pursue direct utility partnership channels that bypass retail markups and aggregate installation volumes through rebate-aggregated programs. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-connected thermostat vendors with active utility demand response enrollments. Long-term viability favors platforms that can sustain service attach rates across hardware replacement cycles. Monitor virtual power plant deployment velocity in Texas and California as the inflection indicator for procurement pull intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Utility Partnership Integration | Direct procurement relationships with electricity distributors lock in multi-year service revenue streams through ENERGY STAR-mandated rebate programs. |
| Heat Pump Optimization Development | Compressor control protocol integration secures European market access under Ecodesign Directive and F-Gas Regulation enforcement. |
| Cybersecurity Certification Investment | UL 2900 and IEC 62443 compliance extends product development timelines but qualifies hardware for utility-sponsored procurement channels. |
| Professional Installer Network Expansion | Resideo and independent HVAC service relationships defend specification positions in commercial retrofits with legacy control complexity. |
| AI Inference Hardware Integration | Edge-computing capabilities embedded in thermostat hardware enable predictive HVAC cycling that commands margin premiums in California and New York markets. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with thermostat manufacturers, utility demand response program managers, HVAC installation contractors, and building automation specifiers; and secondary validation through EPA ENERGY STAR certification databases, FERC demand response filings, EU Ecodesign regulatory texts, and customs trade records for Wi-Fi module imports. Bottom-up shipment estimates by product type and connectivity protocol were triangulated against top-down utility procurement contract values.
Forecast inputs include technology adoption curves across residential and commercial end uses, regulatory enforcement timelines for heat pump optimization mandates, and virtual power plant deployment schedules by regional grid operators. Segmentation dimensions modeled span product architecture, connectivity dependency, installation complexity, and end-use application. CAGRs were derived from slope analysis of replacement cycle acceleration and rebate program enrollment trajectories. Industry-specific inputs incorporate IRA rebate uptake rates and EU F-Gas Regulation compliance deadlines.
Stress conditions across semiconductor supply availability, utility program funding continuity, and cybersecurity certification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology cost curves. Material shifts in federal rebate appropriations or export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Smart Cooling Systems Market
Energy Management Systems
AI Water Heater Market
Energy Management Systems
IoT Energy Management Market
Energy Management Systems
Building Energy Management Solution Market
Energy Management Systems
Global Digital Thermostats Market
Energy Management Systems
Meter Data Management System Market
Energy Management Systems
Global Smart Air Conditioning Market
Energy Management Systems
Intelligent PDU Market
Energy Management Systems
Portable Air Cooler Market
Energy Management Systems
Shared Power Bank Market
Energy Management Systems
Southeast Asia Cooling Systems Market
Energy Management Systems
AI-Driven Lighting Controls Market
Energy Management Systems
Energy Management in Data Centers Market
Energy Management Systems
Smart Air Cleaners Market
Energy Management Systems
IoT Smart Gas Meter Market
Energy Management Systems
Smart Climate Control Market