
 Meter Data Management System Market | 2026-2036
Meter Data Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Meter Data Management System Market Intelligence
The shift toward Software-as-a-Service (SaaS) and leasing models is fragmenting the competitive landscape, lowering entry barriers for specialized software vendors. Siemens leverages its extensive utility relationships and integrated hardware-software portfolio to maintain its position. In contrast, Oracle specializes in cloud-based data management and analytics platforms, competing on software functionality. Itron sustains its market presence through its deep expertise in metering hardware and associated network communication technologies.
A Meter Data Management System is a software platform acting as a central repository for data from advanced metering infrastructure. The system performs validation, estimation, and editing (VEE) on raw meter reads to ensure data quality for billing and grid optimization. Cloud-based deployment models are rapidly displacing on-premises systems, offering lower capital expenditure and enhanced scalability for utilities. Among solutions, analytics services represent the fastest-growing segment as energy retailers use data for new applications and efficiency gains.
Data privacy regulations like Europe's GDPR and various US state laws govern how customer energy data is handled and stored by utilities. Standards from the IEC and the US-based NIST define interoperability and security protocols, shaping system design and market access. System providers must decide between offering complete end-to-end platforms or specializing in analytics modules for a multi-vendor environment.
Market Dynamics
The central dynamic shaping the Meter Data Management System market is the architectural shift from on-premise data storage to scalable, cloud-based platforms. This transition is driven by regulatory pressure for grid modernization and the need to process unprecedented data volumes from smart meters.
Growth Catalysts
- Regulatory Mandates:Frameworks like the EU Green Deal and national smart grid missions in India compel utilities to adopt MDMS for verifying energy efficiency gains and enabling dynamic pricing models.
- Grid Modernization Programs:Utilities across North America are investing heavily in Advanced Metering Infrastructure (AMI), which requires a sophisticated MDMS backend to validate, store, and analyze the resulting data streams for grid optimization.
- Demand for Analytics:Energy retailers are leveraging MDMS data to develop new customer services, such as personalized energy-saving recommendations and demand-response programs, creating a direct link between data management and revenue generation.
Market Restraints
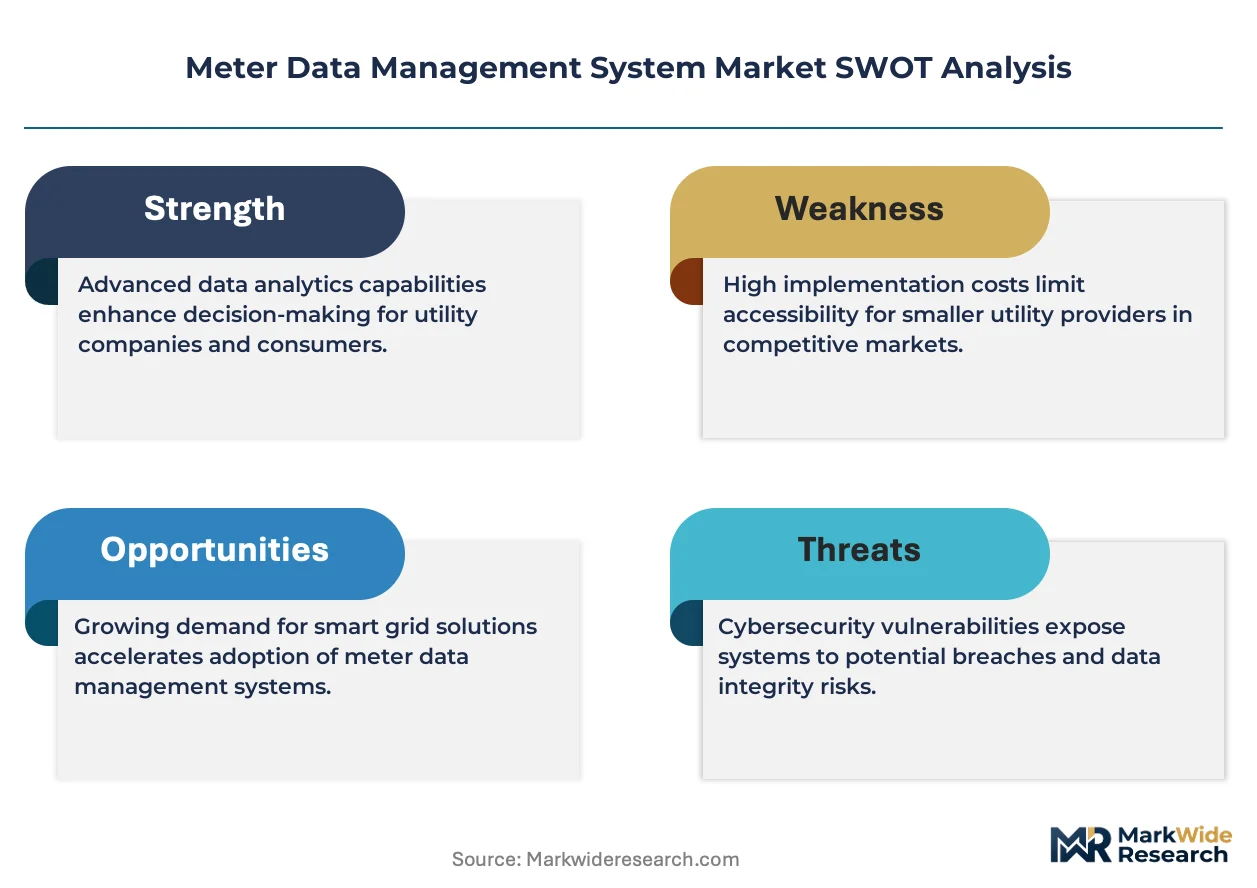
- High Upfront and Integration Costs:The total cost of ownership, including software licensing, system integration with legacy platforms like CIS, and employee training, presents a significant financial hurdle for smaller utilities and cooperatives.
- Data Interoperability Challenges:A lack of universal adherence to standards from bodies like the IEC can lead to vendor lock-in and create costly complexities when integrating components from different suppliers in a multi-vendor environment.
- Cybersecurity and Privacy Risks:The centralization of granular energy consumption data makes MDMS a high-value target for cyberattacks, requiring continuous and substantial investment in advanced security measures to comply with regulations like GDPR.
Strategic Opportunities
- Expansion into Water and Gas Utilities:The MDMS model is transferable to the water and gas sectors, which are in earlier phases of smart metering rollouts, particularly in markets like Australia and the Middle East.
- Edge Computing Integration:Embedding analytics capabilities within data concentrators or at the grid edge presents an opportunity to offer new real-time services, such as preemptive outage detection and localized load balancing.
- Electric Vehicle Charging Data Management:The rapid growth of EV charging infrastructure generates vast amounts of session and consumption data, creating a new, specialized segment for MDMS platforms to manage billing, grid impact, and charger utilization.
Industry Challenges
- Skilled Workforce Gap:Utilities struggle to attract and retain data scientists and IT specialists with the necessary expertise to manage MDMS platforms and develop analytics applications, limiting the return on software investment.
- Legacy System Integration Complexity:Interfacing a modern MDMS with decades-old operational technologies and billing systems is a major technical and operational hurdle, often leading to project delays and budget overruns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meter Data Management System Market |
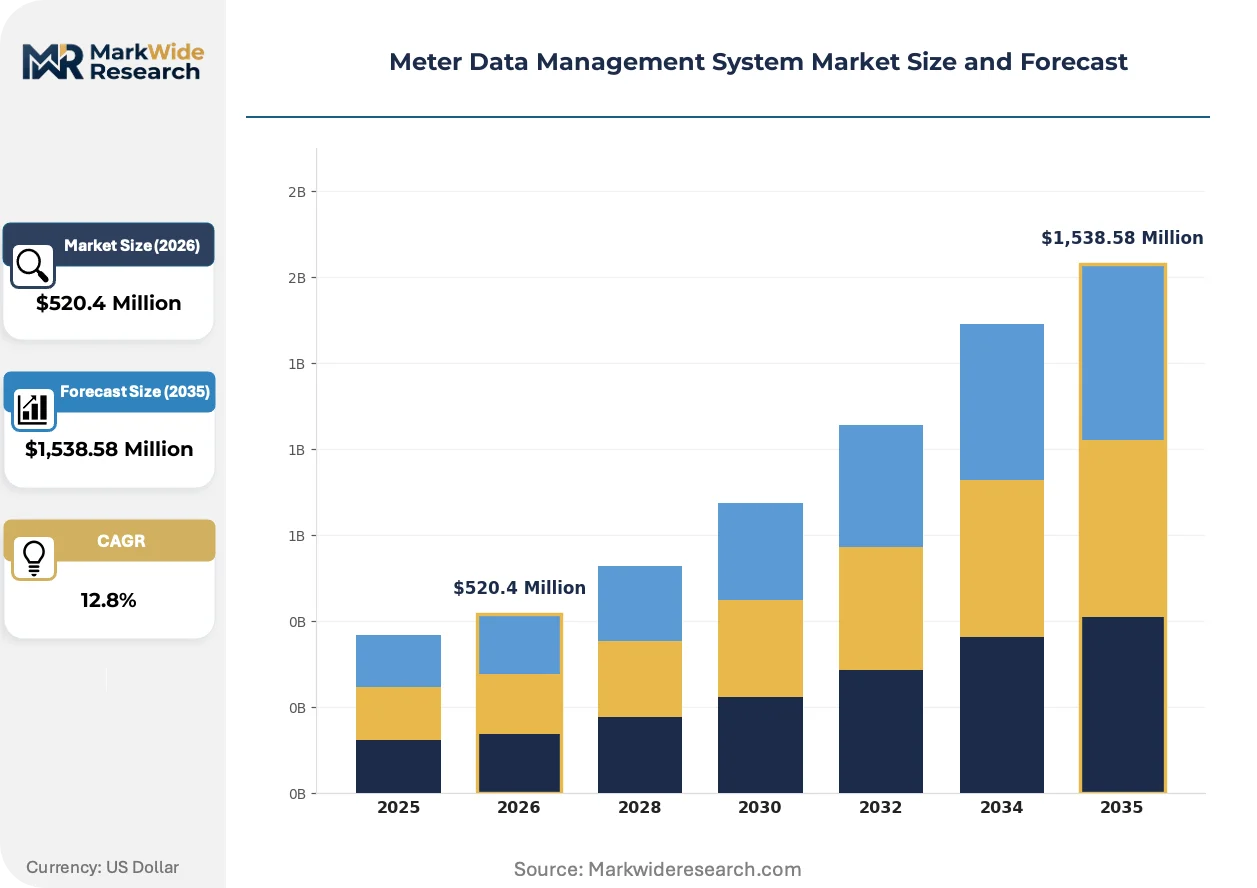
| Market Size in 2026 | $520.4 Million |
| Market Size in 2035 | $1,538.58 Million |
| CAGR (2026 – 2036) | 12.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Virtual End User: Utilities, Energy Retailers, Government Agencies, Industrial Facilities Solution: Data Integration, Analytics Services, Reporting Tools, Security Solutions Technology: Smart Meters, IoT Devices, Communication Networks, Data Management Software |
| Companies Covered | Siemens, ABB, Landis+Gyr, Eaton, Honeywell, Itron, Schneider Electric, Kamstrup, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meter Data Management System Market Strategic Shifts & Innovations
The market's evolution is defined by the move toward cloud-native architectures and the unbundling of software capabilities. This shift prioritizes data accessibility and analytical agility over simple data collection, fundamentally changing utility operational models and vendor relationships.
Cloud-native MDMS platforms built on microservices architecture are gaining traction. Utilities are adopting these solutions to achieve greater scalability, reduce capital expenditure on hardware, and accelerate deployment timelines compared to traditional systems. This architectural approach is rendering obsolete the monolithic, on-premises software that demanded lengthy and disruptive "rip-and-replace" upgrade cycles tied to specific hardware.
Europe's General Data Protection Regulation (GDPR) directly influences system design and functionality. The regulation mandates stringent controls on the handling of personal energy consumption data, forcing MDMS providers to incorporate "privacy by design" principles. Consequently, vendors targeting the EU market must now offer advanced features for data anonymization and consent management, turning regulatory compliance into a competitive differentiator.
Utilities are increasingly adopting a "best-of-breed" procurement strategy, moving away from single-vendor, end-to-end system purchases. This change disrupts the incumbent model, as utilities now combine a core MDMS from one provider with specialized analytics or customer-facing applications from niche software vendors. This trend is most visible in deregulated energy markets in North America and parts of Europe, where competitive pressures drive a search for functional advantages.
Meter Data Management System Market Segmentation
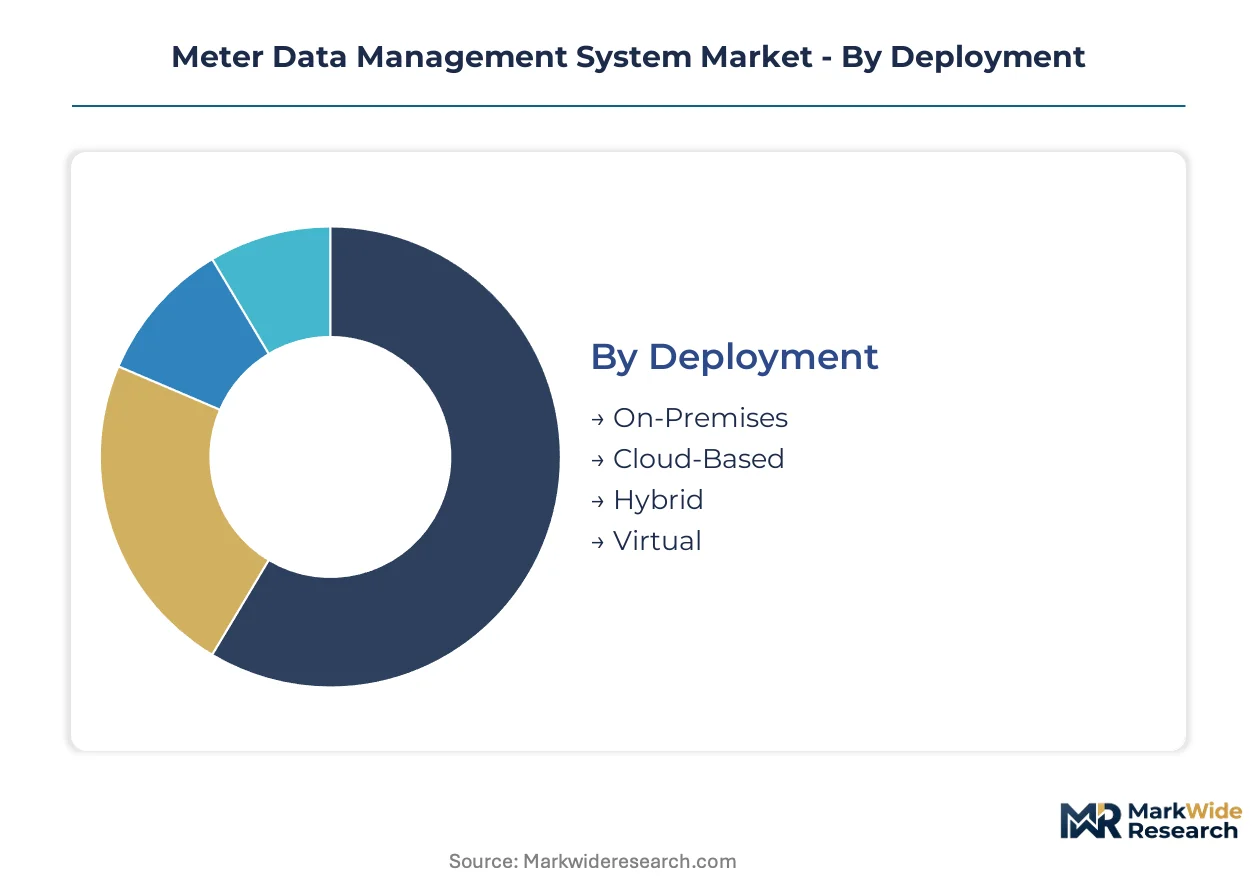
The Meter Data Management System market is segmented to reflect the diverse technological components, deployment models, and end-user applications driving its evolution. This granular breakdown helps stakeholders understand where investment is concentrating and how different functionalities contribute to overall market growth.
Deployment:
MDMS deployment models significantly impact the ongoing support and maintenance requirements for utilities, influencing vendor service strategies.
- Cloud-Based:This model offers remote accessibility and managed services, reducing the need for extensive in-house IT support. Demand concentrates among smaller utilities seeking lower capital expenditure and faster deployment in markets like India.
- On-Premises:This model requires significant in-house IT infrastructure and dedicated personnel for maintenance and upgrades. It remains prevalent among large utilities with established data centers and stringent security protocols.
- Hybrid:This approach combines local infrastructure with cloud resources, balancing data control with scalability for specific utility workloads.
- Virtual:This model utilizes virtualized servers within existing data centers, enhancing resource utilization for MDMS operations.
On-Premises holds the largest share; momentum sits with Cloud-Based solutions.
End User:
Different end-user segments leverage Meter Data Management System capabilities for distinct operational and strategic objectives.
- Utilities:These entities deploy MDMS as a core component of their grid modernization efforts, handling vast volumes of smart meter data for billing, network operations, and outage management. Demand is strong in North America for AMI data processing.
- Energy Retailers:These companies utilize MDMS data for developing new customer services, personalized energy-saving recommendations, and demand-response programs. This segment drives demand for advanced analytics in deregulated markets.
- Government Agencies:These organizations employ MDMS for energy policy monitoring, regulatory compliance, and managing public infrastructure consumption.
- Industrial Facilities:These facilities use MDMS to optimize their own energy consumption, manage peak demand, and reduce operational costs.
Utilities represent the foundational demand for MDMS, while energy retailers are driving significant innovation in data utilization.
Solution:
The various MDMS solution components offer distinct value propositions, ranging from foundational data handling to advanced insights.
- Analytics Services:These services provide deep insights from meter data, enabling utilities to forecast demand, detect anomalies, and optimize grid performance. This segment is expanding most quickly as energy retailers seek new revenue streams.
- Data Integration:This component connects the MDMS with other utility systems like Customer Information Systems (CIS) and Geographic Information Systems (GIS). Seamless integration ensures data flow and operational efficiency across the utility infrastructure.
- Reporting Tools:These tools generate customizable reports on energy consumption, billing, and system performance for various stakeholders.
- Security Solutions:These solutions protect sensitive energy consumption data from cyber threats and ensure compliance with privacy regulations like Europe's GDPR.
Foundational data integration remains critical, but analytics services are experiencing the steepest expansion trajectory.
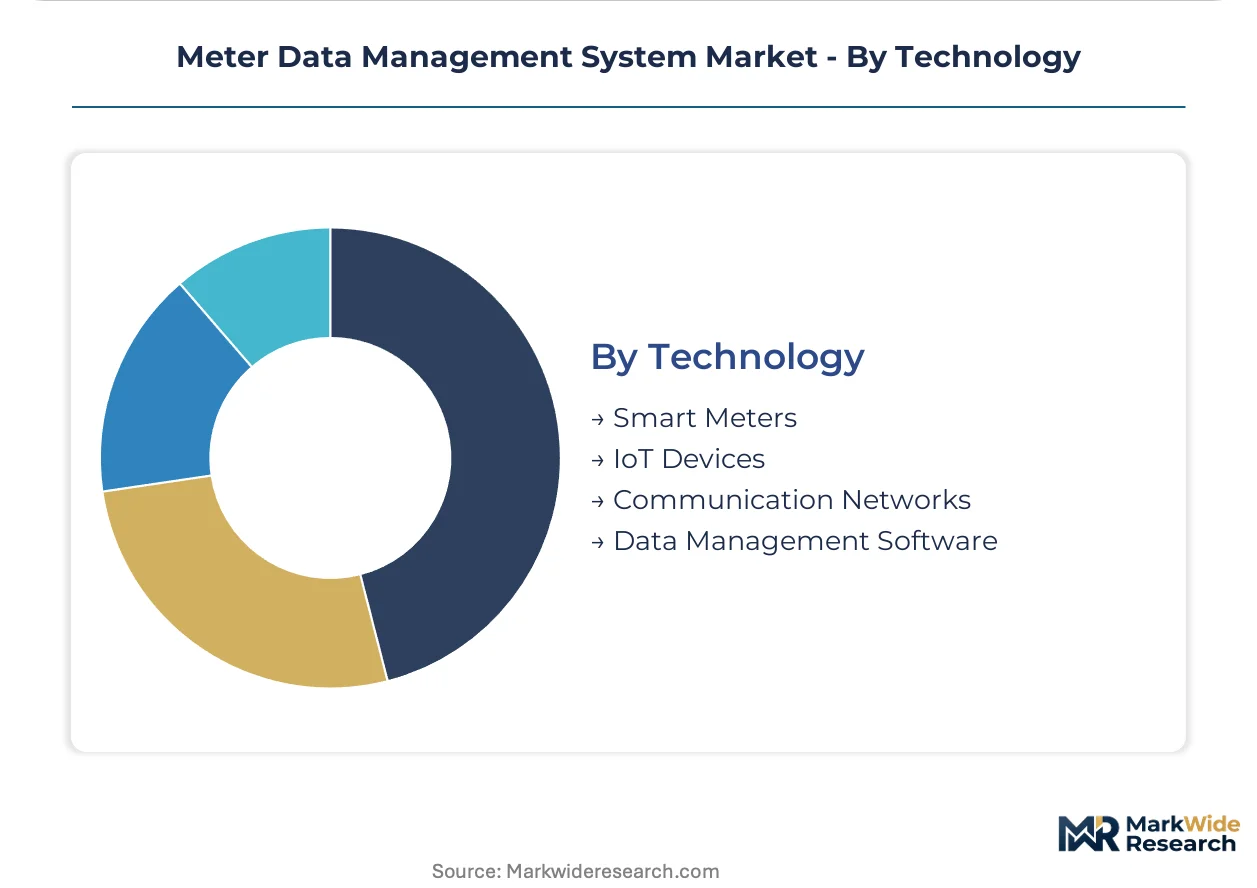
Technology:
MDMS functionality relies on an ecosystem of underlying technologies, each with varying levels of maturity and supplier concentration.
- Data Management Software:This software forms the core of the MDMS, performing validation, estimation, and editing (VEE) on raw meter reads. The platform ensures data quality for billing and grid optimization.
- Smart Meters:These devices act as the primary source of granular energy consumption data, transmitting reads at regular intervals. Their widespread deployment is a prerequisite for effective MDMS implementation globally.
- IoT Devices:These include sensors and smart grid devices that feed additional operational data into the MDMS for enhanced situational awareness.
- Communication Networks:These networks provide the infrastructure for transmitting meter data from smart meters and IoT devices to the central MDMS.
Data management software anchors the system's intelligence, while smart meters provide the essential data input.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utilities across various regions represent the primary buyer archetype for Meter Data Management Systems, driving demand for advanced data processing capabilities. These entities invest in MDMS to manage vast volumes of smart meter data from grid modernization initiatives. Energy retailers also contribute significantly by leveraging MDMS data for new customer services and efficiency gains.
United States
Demand for MDMS in the United States stems from extensive Advanced Metering Infrastructure (AMI) rollouts and grid modernization programs. The Federal Energy Regulatory Commission (FERC) encourages smart grid investments, necessitating robust data management. Utilities in California are deploying MDMS to optimize grid operations and enhance reliability.
India
India's MDMS market experiences significant growth through government-led smart grid projects and national energy efficiency missions. The Central Electricity Authority (CEA) mandates smart meter deployments, requiring sophisticated back-end systems. Major cities like Delhi are implementing MDMS to manage burgeoning energy demand and reduce losses.
Germany
German utilities adopt MDMS to comply with the EU Green Deal's energy efficiency targets and support renewable energy integration. The Federal Network Agency (Bundesnetzagentur) oversees smart meter gateway deployment, ensuring data security. Companies in Bavaria invest in MDMS to manage distributed energy resources and optimize local grids.
Australia
Australia presents opportunities for MDMS expansion, particularly in the water and gas sectors, which are in earlier phases of smart metering. The Australian Energy Market Commission (AEMC) regulates meter data access, promoting market efficiency. Utilities in Sydney explore MDMS to manage smart water networks and improve resource management.
United Arab Emirates
The United Arab Emirates invests in smart city initiatives and diversified energy infrastructure, creating new MDMS demand. The Dubai Electricity and Water Authority (DEWA) implements smart grid strategies, requiring comprehensive data management. Abu Dhabi entities leverage MDMS for advanced utility billing and demand-side management.
Meter Data Management System Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a fragmented competitive landscape in the Meter Data Management System market. This structure sees large hardware-software integrators vying with agile, cloud-native software vendors, lowering entry barriers for specialized providers. Strategic archetypes include integrated solution providers, specialized analytics firms, and hardware-centric network communication experts. Companies pursue strategic partnerships for interoperability and portfolio diversification to capture new market segments, especially in emerging applications.
Specialists in cloud-based data management, such as Oracle, exemplify the software-centric approach, emphasizing advanced analytics and scalable platforms for utilities. Conversely, Itron represents a hardware-rooted archetype, leveraging deep expertise in metering devices and associated network communication technologies to maintain its market presence. Siemens, a German-based engineering conglomerate, occupies a position as an integrated end-to-end solution provider, combining extensive hardware and software offerings for comprehensive utility management. These players navigate a market where core MDMS functionality increasingly unbundles from specialized analytics modules.
| Leading Market Players |
|---|
| Siemens |
| ABB |
| Landis+Gyr |
| Eaton |
| Honeywell |
| Itron |
| Schneider Electric |
| Kamstrup |
| Oracle |
| Others |
Cost & Logistics Intelligence
Silicon Valley's concentration of software development talent directly influences the cost structure of advanced Meter Data Management System platforms. This talent pool dictates the pace of innovation and the premium associated with specialized software functionality.
Pricing Analysis
Cost-plus contracts, often indexed to software development labor rates in specific regions, influence MDMS project pricing. The dominant pricing model leans towards SaaS-tiered subscriptions for cloud solutions and project-based licensing for on-premises deployments. Price differentiation arises from the level of customization required and the inclusion of advanced analytics features. Pricing pressure stems from the increasing competition among specialized software vendors, especially for foundational data management. Smaller utilities exhibit higher price sensitivity, seeking lower capital expenditure solutions.
Supply Chain Analysis
The upstream supply for MDMS platforms draws heavily from specialized software libraries and semiconductor components essential for smart meters. Geographic supply concentration for MDMS intellectual property and hardware manufacturing resides primarily in the United States, India, and Germany. A significant supply chain risk involves the skilled workforce gap, particularly for data scientists and IT specialists capable of managing complex MDMS platforms. Distribution runs through direct sales channels to large utilities and strategic partnerships with system integrators for multi-vendor environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Meter Data Management System market presents a fragmentation opportunity as utilities shift towards "best-of-breed" procurement strategies. This demand-side shift creates numerous niches for specialized analytics and customer-facing applications.
For Market Incumbents: Entrench existing utility relationships by offering integrated end-to-end solutions, bundling core MDMS with advanced analytics modules. Consolidate market share through strategic acquisitions of niche cloud-native software vendors to counter the threat from specialized analytics firms. Investment in interoperability standards and comprehensive cybersecurity features provides a critical lever against data privacy concerns. Deepen vertical integration into hardware and communication networks to maintain a competitive edge.
For New Entrants and Emerging Players: Pursue specialized analytics modules for electric vehicle charging data management, targeting grid operators and EV service providers. Target underpenetrated water and gas utilities in Australia and the Middle East with cloud-based MDMS solutions. Small to mid-sized utilities seeking lower capital expenditure and faster deployment represent a highly penetrable segment. A value-based pricing model tied to demonstrated energy efficiency gains offers a compelling go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as an infrastructure-enabling software play because grid modernization and data-driven energy management are irreversible trends. Acquisition targets should be agile cloud-native software vendors specializing in AI-driven analytics or edge computing integration. Valuation should prioritize recurring revenue models and proven scalability. The signal to watch is the acceleration of regulatory mandates for dynamic pricing and real-time grid optimization, indicating expanded MDMS utility.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-driven anomaly detection modules | Enhances grid reliability for utilities by identifying unusual consumption patterns or equipment malfunctions. |
| Expand cloud-native MDMS offerings | Reduces capital expenditure for smaller utilities and accelerates deployment timelines in competitive markets. |
| Form partnerships with EV charging network operators | Captures new revenue streams from managing electric vehicle session and consumption data. |
| Acquire specialized firms in edge computing | Embeds real-time analytics closer to the grid edge, enabling preemptive outage detection for operators. |
| Target water and gas utility sectors | Diversifies revenue streams into markets with nascent smart metering rollouts, particularly in Australia. |
Research Approach
A standing panel of utility planning officers, software architects, energy retailers, and regulatory compliance specialists provided ongoing calibration for market sizing and trend validation. This primary input was triangulated with extensive secondary research, including regulatory filings from FERC and CEA, industry association reports, and technology vendor whitepapers. Both bottom-up analysis of installed base and top-down market projections informed the data approach.
Scenario-bracketing around optimistic, baseline, and conservative adoption rates informed the quantitative forecast across the analysis window. The model segmented the market by deployment type, end-user, solution component, technology, and regional regulatory frameworks. Compound annual growth rates were derived from historical growth patterns and projected smart meter deployment rates. Grid modernization investment served as a key forecast input.
Macroeconomic conditions sit as an overlay; deviation in global energy prices or national smart grid funding would shift the trajectory. Forecasts reflect assumptions on regulatory stability and technology adoption rates. Quarterly review of smart meter penetration and utility capital expenditure is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
AI-Driven Lighting Controls Market
Energy Management Systems
Global Data Center Energy Management Solution Market
Energy Management Systems
Smart Climate Control Market
Energy Management Systems
Evaporative Air Cooler Market
Energy Management Systems
North America Residential Lighting Control System Market
Energy Management Systems
USA and Canada Portable Air Conditioner Market
Energy Management Systems
Cooling Management System Market
Energy Management Systems
Southeast Asia Cooling Systems Market
Energy Management Systems
Wi-Fi Smart Thermostat Market
Energy Management Systems
Smart Water Cooler Market
Energy Management Systems
Building Energy Management Systems (BEMS) Market
Energy Management Systems
North America Home Energy Management System (HEMS) Market
Energy Management Systems
Chemical Control Systems Market
Energy Management Systems
AI Water Heater Market
Energy Management Systems
United Arab Emirates Portable Air Conditioning Market
Energy Management Systems
Intelligent Digital Meter Market