
 Mobile Metering System Market | 2026-2036
Mobile Metering System Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Metering System Market Analytics
The EU Green Deal is pivoting European utilities toward real-time consumption visibility. Landis+Gyr leverages its manufacturing scale across Central European hubs to supply AMI-ready endpoints. Kamstrup competes on ultrasonic measurement accuracy for district heating applications. Siemens anchors its position through backward integration into communications modules and cloud analytics platforms.
A mobile metering system comprises portable or vehicle-mounted instrumentation that measures resource consumption at variable locations using radio-frequency or cellular telemetry, typically achieving accuracy classes of 0.2S to 2.0 per IEC 62053. These systems enable utilities to audit unmetered connections, verify billing disputes, and monitor temporary construction sites without fixed infrastructure deployment. Smart meter product lines capture the deepest margin pools where firmware-over-the-air and edge analytics justify premium positioning. RFID technology segments retain cost advantages in asset-tracking use cases across construction and industrial fleets. Utilities as an end-user category dominate volume, though residential pilot programs for prepaid mobile metering show the steepest trajectory in emerging service territories.
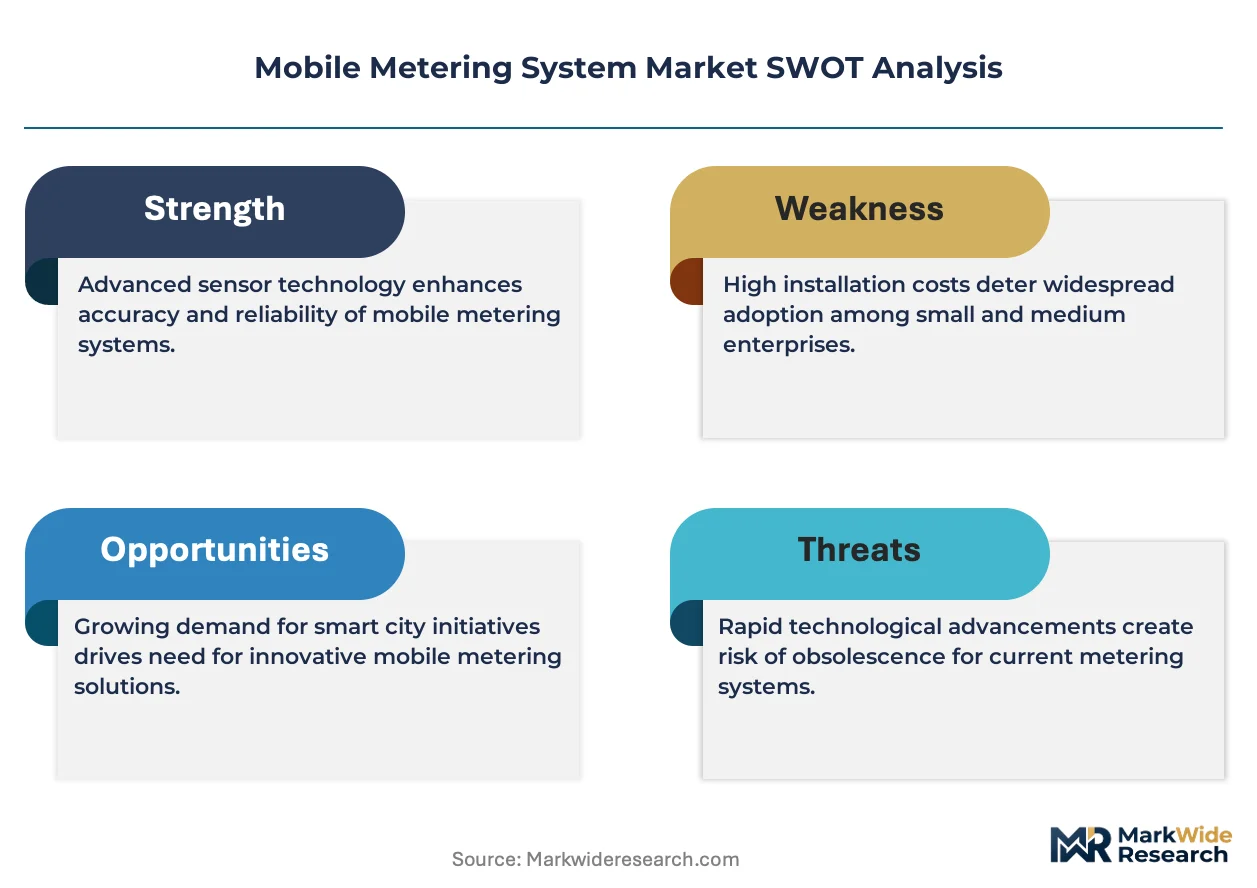
FERC Order 2222 in the United States enables distributed resource aggregation that rewards granular mobile metering at grid edge nodes. EMA and national regulators across EU member states enforce MID certification for billing-grade devices, creating compliance barriers for non-certified suppliers. China's NMPA-equivalent metrology administration mandates pattern approval for all commercial metering instruments sold domestically. Stakeholders must weigh certification costs against the revenue permanence that regulatory compliance secures in each target jurisdiction.
Market Dynamics
Cellular telemetry is compressing installation cycles for mobile metering fleets, collapsing the historical trade-off between measurement accuracy and deployment flexibility that fixed infrastructure once enforced.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant-tracking mandates in HVAC servicing fleets are expanding mobile metering into leak detection and compliance documentation workflows across member states.
- Cellular LPWAN:NB-IoT and LTE-M modules are cutting per-connection costs for temporary construction site monitoring, enabling pay-per-use models that fixed AMI cannot match.
- German municipal retrofit programs:District heating operators are deploying ultrasonic mobile endpoints to audit legacy thermal substations without full infrastructure replacement.
Market Restraints
- Semiconductor supply concentration:RF transceiver and precision ADC sourcing clusters in Taiwan and South Korea create vulnerability for device manufacturers with limited second-source qualification.
- MID certification timelines:EU member state metrology approvals average 14-18 months, freezing product launch windows for billing-grade instruments.
- Optical meter substitution:Static electricity and magnetic tamper resistance in ultrasonic designs still underperforms against mature electromechanical alternatives in high-abuse environments.
Strategic Opportunities
- Prepaid mobile pilots:Emerging service territories in sub-Saharan Africa and Southeast Asia are testing vehicle-mounted vending units for electricity and water credit disbursement.
- HVAC refrigerant convergence:A2L and CO2 transition protocols are forcing service fleets to consolidate leak detection, charging, and compliance logging into single mobile platforms.
- Channel rental models:Equipment-as-a-service offerings through industrial distributors are lowering capital barriers for mid-size utilities and construction contractors.
Industry Challenges
- Metrology firmware validation:Pattern approval authorities in Germany, France, and Italy require exhaustive regression testing for over-the-air updates, stretching release engineering capacity.
- Legacy AMI protocol fragmentation:DLMS/COSEM, M-Bus, and proprietary utility stacks force mobile vendors to maintain multiple radio personalities per SKU, complicating inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Metering System Market |
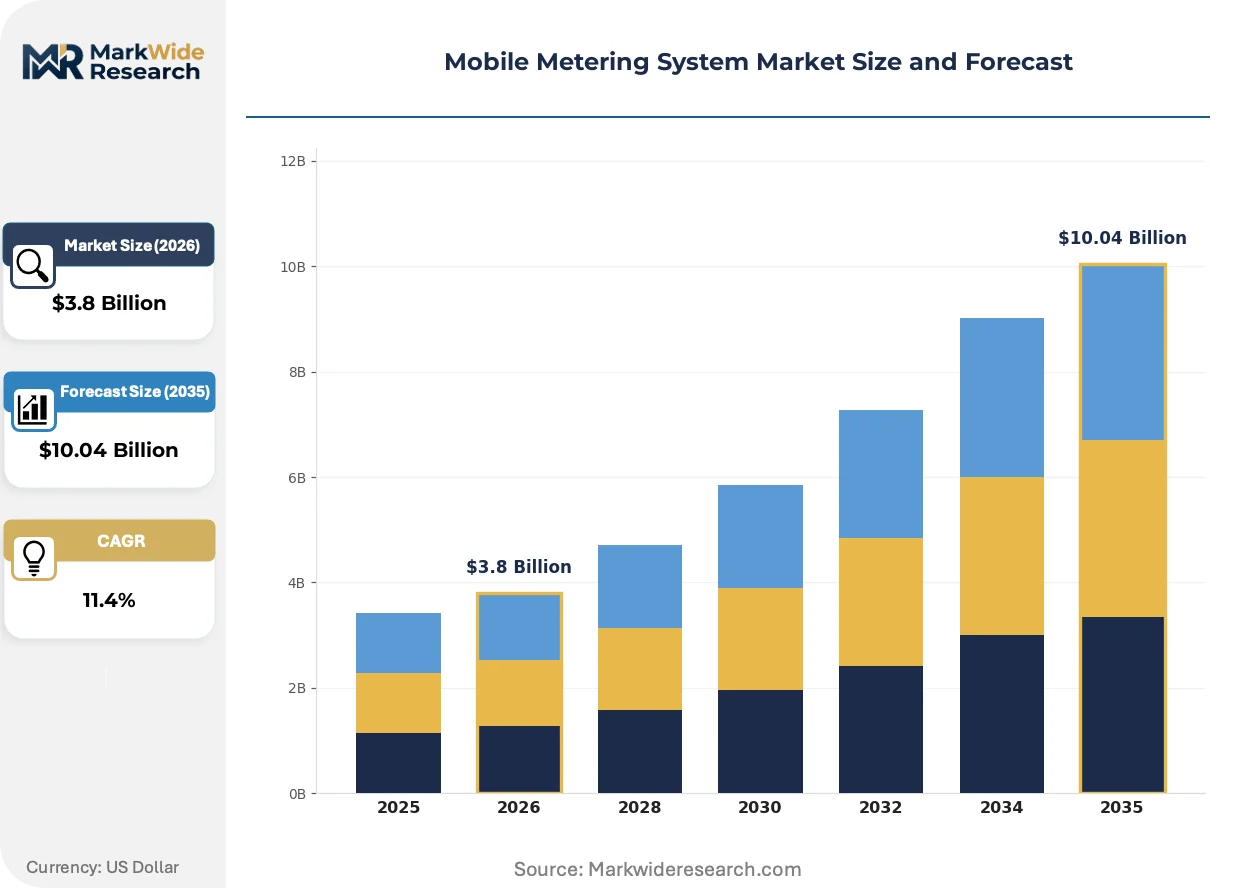
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Meter, Digital Meter, Analog Meter, Prepaid Meter Technology: RFID, Bluetooth, Zigbee, Wi-Fi End User: Utilities, Construction, Industrial, Residential Installation: Fixed Installation, Mobile Installation, Temporary Setup, Remote Monitoring |
| Companies Covered | Itron, Landis+Gyr, Honeywell International, Siemens, Schneider Electric, Badger Meter, ABB, Kamstrup, Aclara Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Metering System Market Evolving Landscape
Edge computing is redistributing analytics from cloud platforms to vehicle-mounted gateways, enabling real-time anomaly detection during mobile audit routes without persistent connectivity.
Ultrasonic flow measurement is unifying liquid, gas, and thermal energy metering into single hardware platforms through broadband signal processing and interchangeable transducer heads. Water utilities in drought-prone regions of Spain and Australia are adopting these multi-fluid endpoints for consolidated fleet management. The technology is unifying procurement categories that historically required separate device inventories, compressing supplier base complexity for large metering programs.
EPA methane emissions rules and state-level refrigerant management codes in the US are mandating documented leak rates and repair timelines for commercial HVAC systems. Service contractors must now deploy calibrated instrumentation with tamper-evident data logging to satisfy enforcement audits. Mobile metering vendors are integrating GPS tagging and blockchain-anchored timestamps to create defensible compliance records for facility operators.
Utility procurement committees are unbundling hardware acquisition from data platform subscriptions, treating mobile metering as an operational expenditure rather than capital project. Municipal water authorities in California and Texas are piloting per-audit pricing with third-party fleet operators, shifting asset ownership risk to service providers. This reconfiguration is most visible in North American markets where municipal budget constraints and IRA-funded efficiency programs create demand for flexible deployment models.
Mobile Metering System Market Segmentation
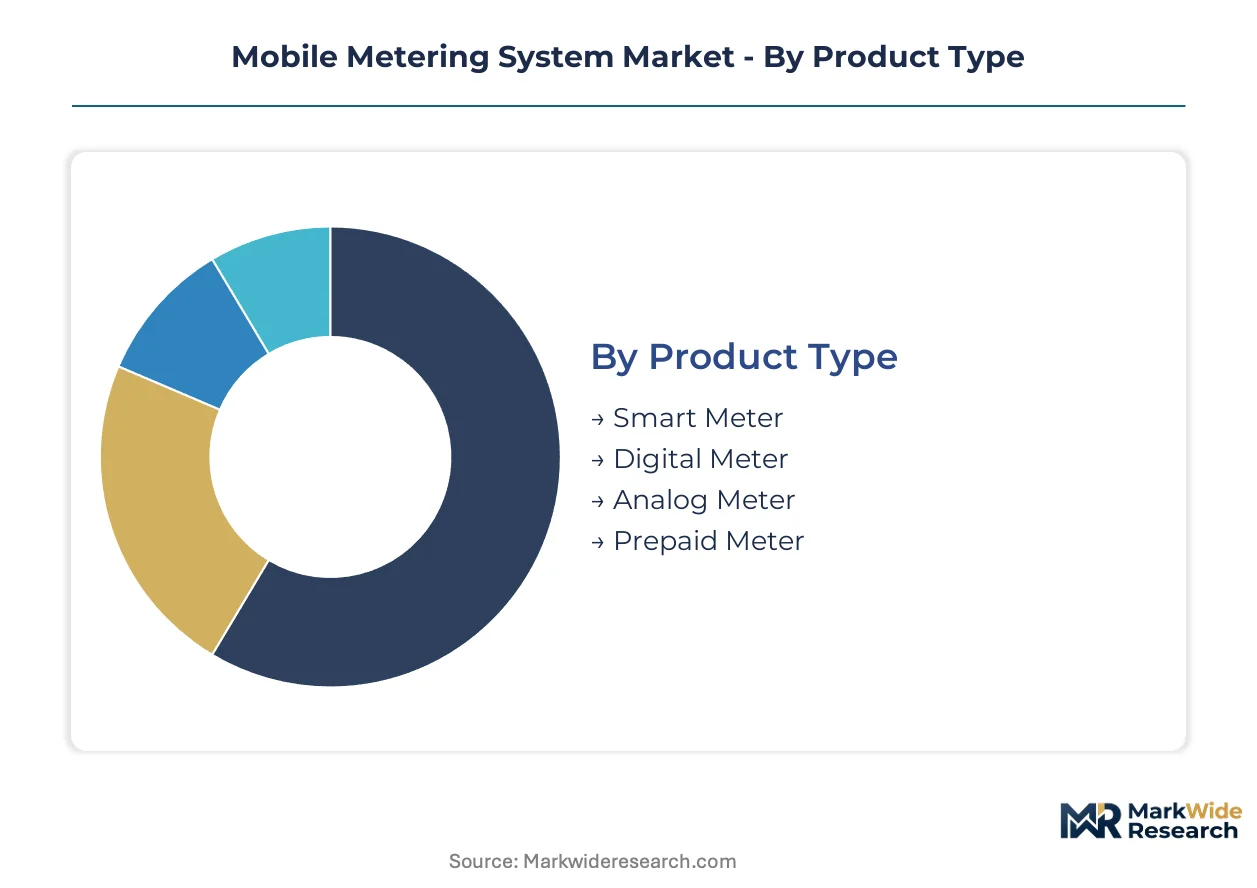
Segmentation in mobile metering systems reveals how procurement patterns diverge between capital-intensive utility rollouts and flexible service-contractor deployments. Understanding these divides shapes vendor positioning on certification depth, connectivity modularity, and ownership-model economics.
Product Type:
Measurement sophistication and firmware programmability define the product hierarchy, with premium tiers commanding recurring platform revenue.
- Smart Meter:Embedded cellular modems and edge analytics engines enable real-time consumption visibility and over-the-air configuration updates. German municipal utilities and California water districts prioritize these endpoints for AMI-backhaul integration and demand-response signaling.
- Prepaid Meter:Vehicle-mounted vending units with token-dispensing or mobile-money interfaces are gaining traction in sub-Saharan African and Southeast Asian pilot programs where billing collection infrastructure remains sparse.
- Digital Meter:LCD-display units with local data logging serve audit and verification workflows without full smart-grid connectivity.
- Analog Meter:Electromechanical designs persist in high-tamper-risk environments where magnetic and static resistance outweighs precision requirements.
Smart meters lead on scale; prepaid meters lead on momentum.
Technology:
Radio-layer choices trade range against power budget and spectrum licensing costs, with LPWAN variants reshaping total-cost-of-ownership calculations for fleet operators.
- RFID:Passive and active radio-frequency identification enables asset tracking and non-powered meter reading across construction yards and industrial facilities. European HVAC service fleets leverage RFID for refrigerant cylinder traceability under EU F-Gas Regulation mandates.
- Bluetooth:Short-range protocols support technician smartphone pairing for configuration and diagnostics without cellular data charges.
- Zigbee:Mesh networking suits dense urban deployments where self-healing connectivity offsets individual node failures.
- Wi-Fi:High-bandwidth links accommodate firmware updates and buffered data offload at depots and service centers.
RFID dominates installed base volume; Bluetooth climbs fastest on technician-productivity gains.
End User:
Customer archetypes diverge sharply on procurement authority, with utilities centralizing technical specification and contractors prioritizing rental flexibility.
- Utilities:Municipal water and electricity authorities drive volume through multi-year AMI tenders requiring MID certification and decade-long service life guarantees. German district heating operators exemplify this segment's demand for ultrasonic accuracy and thermal substation audit capability.
- Construction:General contractors and project developers require temporary metering for site power and water allocation without permanent infrastructure commitment.
- Industrial:Manufacturing facilities deploy mobile endpoints for sub-metering energy-intensive processes and validating utility billing disputes.
- Residential:Individual consumers participate in prepaid pilot programs and home energy management trials, though direct purchase remains minimal.
Utilities anchor procurement volume; construction expands most quickly on project-cyclical demand.
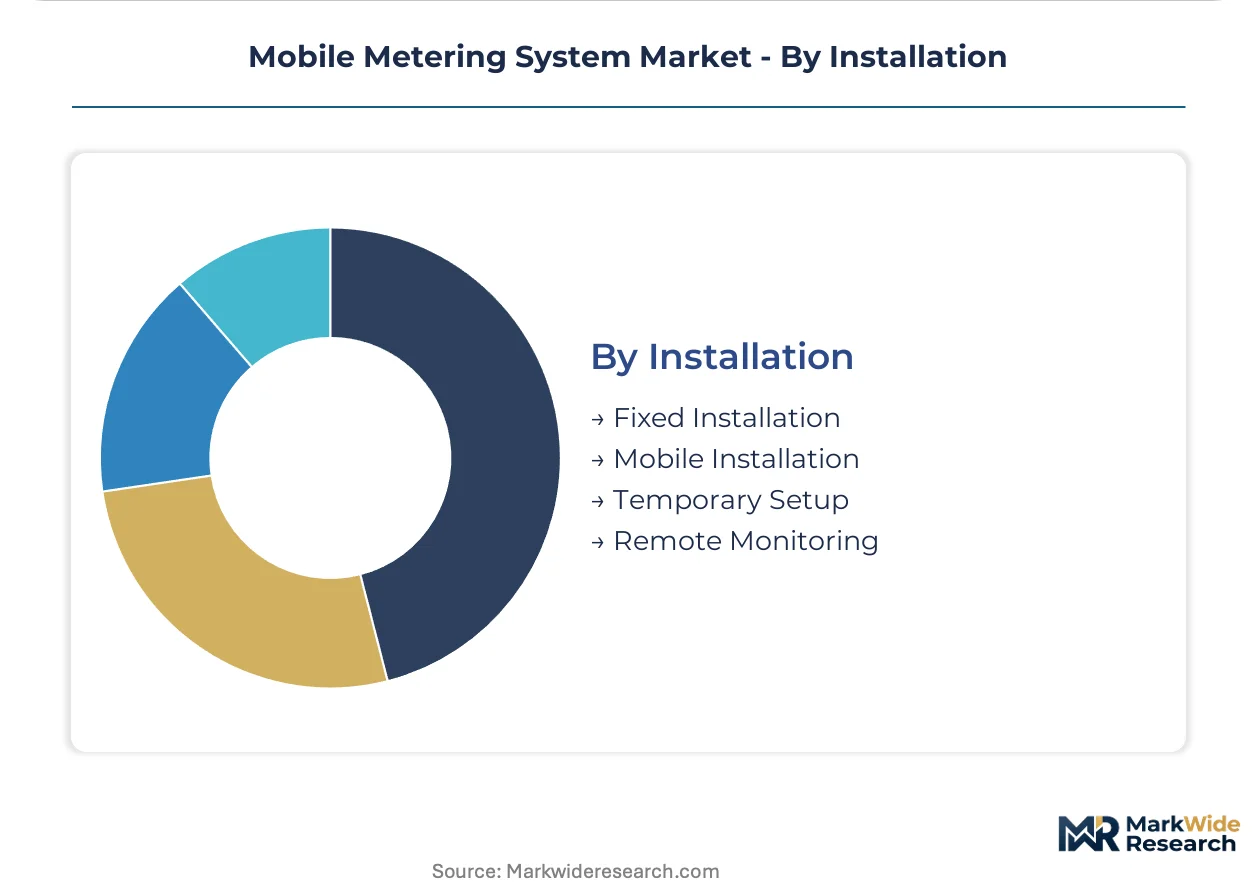
Installation:
Deployment modality determines capital recovery timelines and shapes vendor business model choices between equipment sale and managed service provision.
- Mobile Installation:Vehicle-mounted or portable instrumentation enables measurement at variable locations without fixed infrastructure. California and Texas municipal water authorities are piloting per-audit pricing with third-party fleet operators, transferring asset ownership risk to service providers.
- Remote Monitoring:Cloud-connected telemetry allows centralized oversight of dispersed endpoints, supporting compliance documentation for EPA methane rules and state-level refrigerant management codes.
- Fixed Installation:Permanent mounting at established connection points serves traditional billing-grade metering with pattern-approved accuracy classes.
- Temporary Setup:Rapid-deployment configurations address construction phases, events, and emergency response scenarios.
Mobile installation leads on operational flexibility; remote monitoring gains share fastest on regulatory documentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mobile metering infrastructure first achieved commercial scale in Germany's municipal utility sector during the early smart grid expansion. The technology spread through European district heating networks before cellular telemetry enabled flexible deployment models in water-scarce regions worldwide.
Germany
District heating operators in North Rhine-Westphalia and Bavaria deploy ultrasonic mobile endpoints to audit legacy thermal substations without full infrastructure replacement. The EU F-Gas Regulation mandates refrigerant-tracking documentation that HVAC service fleets satisfy with portable metering platforms. Landis+Gyr maintains manufacturing capacity across Central European hubs to supply AMI-ready endpoints for municipal retrofit programs.
United States
California and Texas municipal water authorities pilot per-audit pricing with third-party fleet operators, shifting asset ownership risk to service providers. FERC Order 2222 enables distributed resource aggregation that rewards granular mobile metering at grid edge nodes. EPA methane emissions rules and state-level refrigerant management codes mandate documented leak rates for commercial HVAC systems in Texas and California metropolitan clusters.
China
The national metrology administration mandates pattern approval for all commercial metering instruments sold domestically, creating compliance barriers for non-certified suppliers. NMPA-equivalent regulators enforce exhaustive testing protocols for billing-grade devices. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta produce cellular LPWAN modules that compress installation cycles for mobile metering fleets across domestic utilities.
Australia
Water utilities in drought-prone regions accelerate deployment of cellular-connected flow meters for unmetered connection audits and temporary construction site monitoring. State-level environmental regulators enforce consumption visibility requirements that mobile endpoints satisfy without fixed infrastructure commitment. Sydney and Melbourne metropolitan utilities consolidate procurement categories through multi-fluid ultrasonic platforms that measure liquid, gas, and thermal energy.
Spain
Municipal water authorities in arid southern provinces adopt vehicle-mounted metering for agricultural irrigation audits and billing dispute verification. The EU Green Deal pivots Spanish utilities toward real-time consumption visibility through cellular telemetry. Barcelona and Madrid utility districts test prepaid mobile pilots for construction site power allocation without permanent meter installation.
Mobile Metering System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and firmware programmability. The vendor base organizes into three tiers: multinational industrial conglomerates with backward integration into communications modules, specialized metrology houses with ultrasonic accuracy advantages, and regional fabricators competing on unit cost for non-billing applications. Consolidation pressures concentrate among mid-scale European specialists seeking scale to amortize MID certification investments. Dominant competitive moves include strategic partnerships for cloud analytics integration and geographic expansion through equipment-as-a-service rental models.
Among European-based metrology specialists, Kamstrup occupies a position exemplifying ultrasonic measurement accuracy for district heating applications. Landis+Gyr represents the multinational conglomerate archetype with manufacturing scale across Central European hubs. Siemens anchors the integrated systems tier through in-house production of communications modules and cloud analytics platforms. These three entities collectively illustrate the competitive spectrum from specialized accuracy to full-stack integration.
| Leading Market Players |
|---|
| Itron |
| Landis+Gyr |
| Honeywell International |
| Siemens |
| Schneider Electric |
| Badger Meter |
| ABB |
| Kamstrup |
| Aclara Technologies |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap metrology specialists in Germany and Switzerland anchor premium pricing through multi-generational certification relationships with BNetzA and METAS authorities, while their supply behavior favors captive foundry partnerships over spot-market component sourcing. This ownership pattern concentrates pricing power in billing-grade segments where MID pattern approval creates artificial scarcity, forcing municipal utilities to absorb cost premiums for audit-grade traceability.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates AMI-integrated smart meters from digital audit units and analog electromechanical designs. Price differentiation rests on certification depth and firmware programmability, with MID-certified endpoints commanding substantial premiums over non-billing instruments. Pricing pressure stems from municipal budget constraints in California and Texas pilot programs, where per-audit rental models compress hardware margins. Construction contractors exhibit highest price sensitivity, while German district heating operators prioritize accuracy guarantees over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Tier 1 utilities now mandate qualified second sources for RF transceivers and precision ADCs, forcing vendors to maintain parallel supplier relationships despite qualification costs. Manufacturing concentrates in Germany, Taiwan, and South Korea, with cellular LPWAN module production anchored in the Yangtze River Delta. Raw material dependencies include silicon wafers, lithium primary cells, and engineered polymer housings. Single-source vulnerability in precision ADC fabrication creates exposure for billing-grade instrument manufacturers. Distribution runs through industrial distributors and direct utility procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with procurement committees unbundling hardware from data platforms and prioritizing firmware-over-the-air capability as a baseline specification. Demand is shifting toward premium specifications where edge analytics and real-time anomaly detection justify operational expenditure treatment.
For Market Incumbents: Anchor defensive positioning through backward integration into communications modules and cloud analytics platforms, mirroring Siemens' integrated systems architecture. Deepen certification moats by accelerating MID pattern approval for ultrasonic multi-fluid endpoints ahead of EU F-Gas Regulation expansion. Prioritize R&D investment in edge computing gateways to offset substitution risk from optical meter alternatives in high-abuse environments. For New Entrants and Emerging Players: Capture white-space in prepaid mobile vending units for sub-Saharan African and Southeast Asian pilot programs, where billing collection infrastructure gaps create penetrable demand. Target construction contractor segments with equipment-as-a-service rental models through industrial distributors, exploiting municipal budget constraints in California and Texas. Lead with technician-productivity value propositions using Bluetooth smartphone pairing to bypass cellular data cost objections. For Investors and Strategic Acquirers: Industrial conglomerates seeking smart grid portfolio completeness are the most active acquirer in this space, with Schneider Electric and Honeywell International representing archetypal strategic buyers. Long-term viability centers on firmware platform economics recurring revenue streams over hardware replacement cycles. Acquisition target archetype: mid-scale European specialists with MID certification assets and district heating application expertise. Watch for inflection in German municipal retrofit program acceleration as signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifying liquid, gas, and thermal measurement into single hardware platforms compresses supplier base complexity for Sydney and Melbourne utilities. |
| Backward Integration | In-house production of NB-IoT communications modules insulates Landis+Gyr from RF transceiver supply concentration in Taiwan and South Korea. |
| Geographic Expansion | Equipment-as-a-service rental models through industrial distributors lower capital barriers for mid-size Texas and California water authorities. |
| Regulatory Certification Investment | Accelerated MID pattern approval for ultrasonic endpoints secures billing-grade positioning under EU F-Gas Regulation expansion mandates. |
| Strategic Partnership | Cloud analytics alliances enable real-time anomaly detection for EPA methane compliance documentation in Texas metropolitan HVAC service fleets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility procurement managers, HVAC service fleet operators, district heating network engineers, and metrology certification authorities with secondary validation. Secondary sources included EU member state metrology institute filings, FERC Order 2222 implementation dockets, EPA methane emissions rulemaking records, and customs data for cellular LPWAN module trade flows. Bottom-up endpoint shipment estimates triangulated against top-down utility capex disclosures.
Segment-weighting approaches applied product type, technology layer, end-user archetype, and installation modality dimensions across the modeling period. CAGRs derived from regression analysis of historical deployment trajectories in Germany and California against regulatory mandate timelines. Industry-specific forecast inputs incorporated EU F-Gas Regulation compliance deadlines and IRA-funded efficiency program allocations for municipal water authorities.
Semiconductor supply disruption, MID certification timeline delays, and optical meter substitution acceleration are the dominant revision risks to the outlook. Deviation in EU member state metrology approval processing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Shared Power Bank Market
Energy Management Systems
AI-Driven Lighting Controls Market
Energy Management Systems
EV Smart HVAC System Market
Energy Management Systems
Global Smart Air Conditioning Market
Energy Management Systems
Asia-Pacific Energy Management System Market
Energy Management Systems
Smart Utilities Management Market
Energy Management Systems
Global Personal Cooling Device Market
Energy Management Systems
District Cooling Market
Energy Management Systems
Smart Climate Control Market
Energy Management Systems
Building Energy Management Solution Market
Energy Management Systems
Europe Advanced Distribution Management System Market
Energy Management Systems
Cooling Management System Market
Energy Management Systems
North America Home Energy Management System (HEMS) Market
Energy Management Systems
US Energy Management Systems Market
Energy Management Systems
Southeast Asia Cooling Systems Market
Energy Management Systems
Airflow Management Market