
 Global Neurovascular Embolization Devices (Neurology) Market | 2026-2036
Global Neurovascular Embolization Devices (Neurology) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Neurovascular Embolization Devices (Neurology) Market Foresight
Modular procedure kits bundling coils, microcatheters, and access accessories is repositioning purchasing decisions away from standalone device procurement toward integrated system contracts. Stryker leverages its broad neurovascular portfolio to anchor hospital supply agreements across stroke and aneurysm service lines. Medtronic competes through specialized flow-diversion technology leadership, while Penumbra differentiates with aspiration-system integration that extends its footprint in thrombectomy-adjacent procedures.
Global neurovascular embolization devices encompass implantable and injectable systems—metallic coils, liquid embolic polymers, detachable balloons, and intracranial stents—engineered for vessel occlusion or flow modulation under fluoroscopic guidance, typically delivered via 0.014-inch microcatheters through transfemoral or transradial access. These devices arrest hemorrhage, reduce arteriovenous shunting, or devascularize tumors by inducing controlled thrombosis within target vasculature. Coil platforms occupy the largest installed base among product type segments, reflecting decades of clinical validation and broad interventionalist familiarity, while liquid embolics represent the fastest-growing category as Onyx and nBCA formulations penetrate arteriovenous malformation and tumor indications previously managed surgically. Endovascular delivery mode dominates procedure volume, though hybrid operating suites combining open surgical access with endovascular capability are capturing complex cases that resist purely catheter-based approaches.
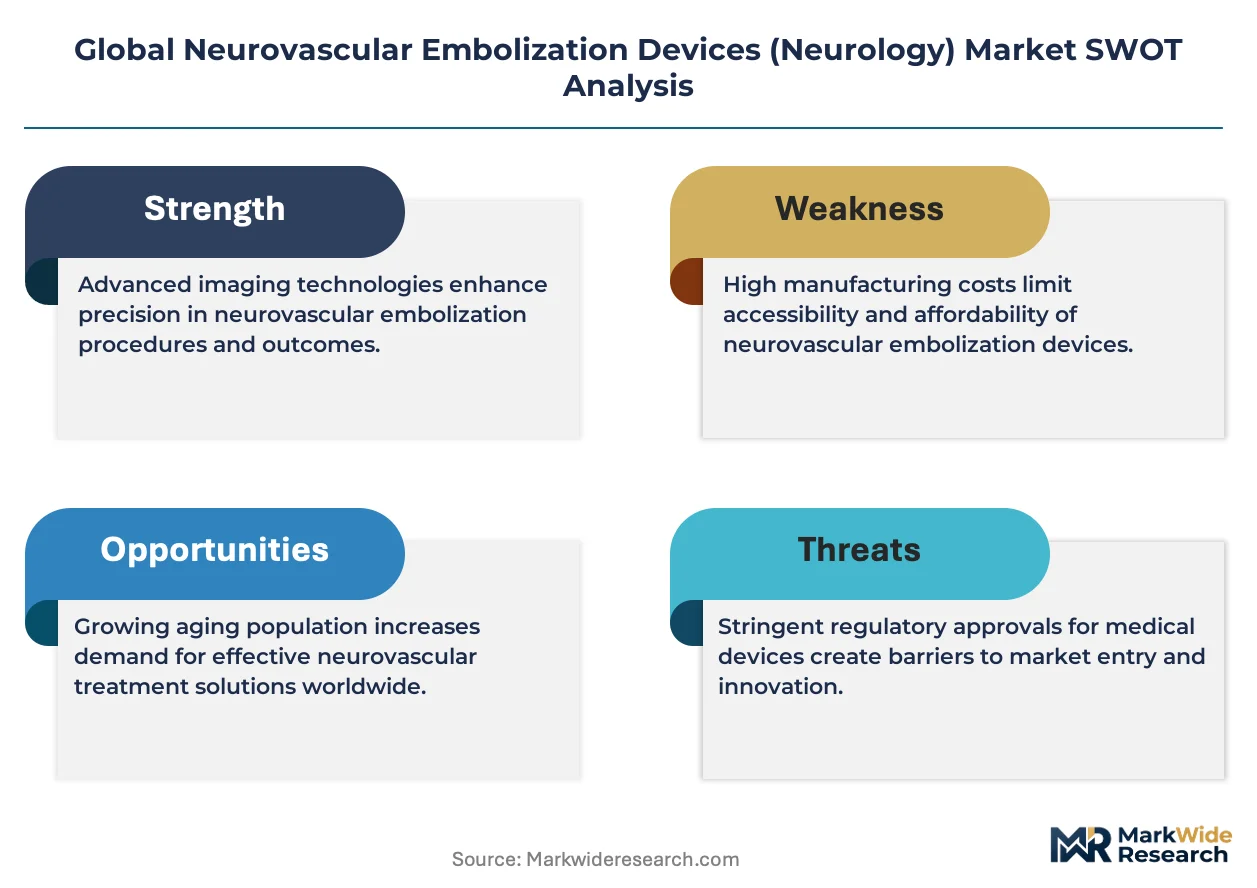
FDA premarket notification and PMA pathways, coupled with EU MDR technical documentation requirements and Japan PMDA shonin approval processes, shape product development timelines and predicate device selection for multinational manufacturers. These frameworks elevate clinical evidence thresholds, particularly for novel embolic materials and bioresorbable constructs, effectively filtering market entry to well-capitalized developers with established regulatory infrastructure. Stakeholders must monitor how real-world evidence mandates under FDA's CDRH digital health guidance and EU MDR post-market surveillance obligations reshape the cost structure of maintaining legacy device registrations alongside next-generation platforms.
Market Dynamics
Catheter-based aneurysm treatment volumes are compressing open surgical alternatives as stroke centers in tertiary hospitals scale endovascular service lines, fundamentally restructuring how hospitals procure neurointerventional systems.
Growth Catalysts
- FDA breakthrough device designation:The pathway accelerates premarket review for coil and flow-diverter platforms, compressing time-to-market for novel embolic constructs.
- Japan's specialized neuroradiology training programs:PMDA-aligned credentialing pipelines expand the interventionalist pool, enabling procedure adoption in metropolitan stroke centers.
- Metallic coil platforms:Decades of fluoroscopic delivery validation and broad physician familiarity sustain installed base expansion across transfemoral access protocols.
Market Restraints
- Platinum and nitinol input volatility:Coil and stent manufacturing depend on concentrated precious metal supply chains subject to price fluctuation.
- EU MDR technical documentation requirements:Post-market surveillance obligations and clinical evidence thresholds elevate registration maintenance costs for legacy devices.
- Surgical clipping substitution:Complex wide-neck aneurysms and failed endovascular cases revert to open microsurgical alternatives with established durability data.
Strategic Opportunities
- India's underpenetrated arteriovenous malformation segment:CDSCO regulatory pathways and private hospital infrastructure investment create whitespace for liquid embolic penetration.
- Hybrid operating suite convergence:Endovascular capability combined with open surgical access captures complex cases resisting purely catheter-based approaches.
- Integrated system contracts:Bundled coil-microcatheter-accessory procurement models displace standalone device purchasing in United States integrated delivery networks.
Industry Challenges
- Neurointerventionalist training pipeline:Specialized fellowship slots lag procedure volume growth, constraining service line expansion in community hospital settings.
- Bioresorbable construct validation timelines:FDA PMA pathway evidence requirements extend development cycles for next-generation embolic materials beyond traditional metallic platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Neurovascular Embolization Devices (Neurology) Market |
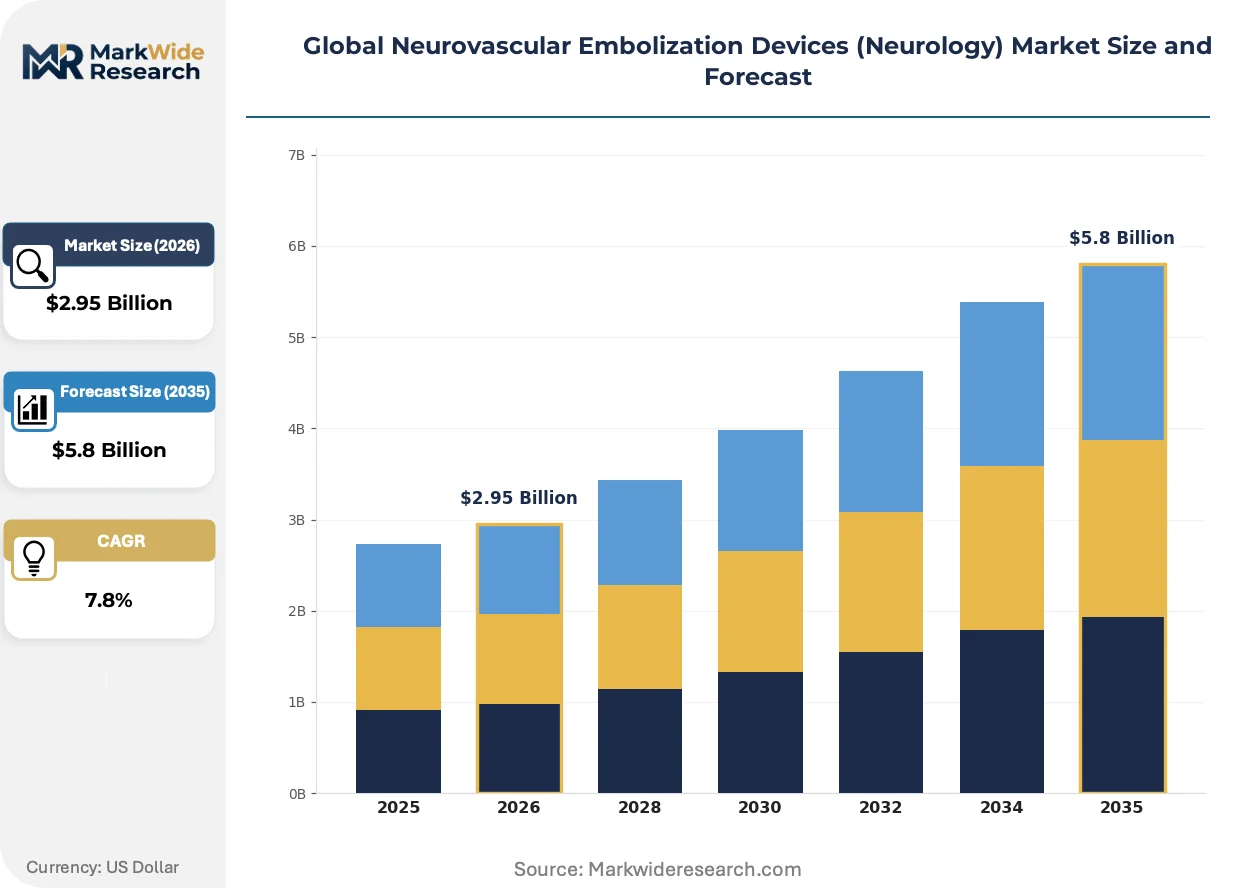
| Market Size in 2026 | $2.95 Billion |
| Market Size in 2035 | $5.8 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coils, Detachable Balloons, Liquid Embolics, Stents Delivery Mode: Endovascular, Surgical, Hybrid, Transcatheter End User: Hospitals, Ambulatory Surgical Centers, Clinics, Specialty Centers Application: Intracranial Aneurysms, Arteriovenous Malformations, Tumor Embolization, Ischemic Stroke |
| Companies Covered | Stryker, Medtronic, Johnson & Johnson, Terumo Corporation, Penumbra, MicroVention, B. Braun Melsungen AG, Boston Scientific Corporation, Merit Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Neurovascular Embolization Devices (Neurology) Market Shifts & Advancements
Product architecture and regulatory evidence frameworks are actively restructuring competitive position in neurovascular embolization, with technology modularity and real-world data mandates compressing traditional development paradigms.
Flow-diverter stent technology is modularizing into platform-agnostic delivery systems compatible with multiple microcatheter specifications. Tertiary stroke centers in Germany and Japan are standardizing on these flexible configurations to reduce inventory complexity. The shift is compressing proprietary ecosystem lock-in that previously anchored hospital supply agreements.
EU MDR post-market surveillance obligations are elevating clinical evidence thresholds for novel embolic materials. Manufacturers must maintain legacy device registrations alongside next-generation platform submissions, restructuring quality assurance resource allocation. Bioresorbable coil constructs face the steepest compliance burden under this framework.
Hospital buying committees are consolidating neurovascular procurement into multi-year integrated system contracts spanning stroke and aneurysm service lines. Standalone device vendors face displacement by portfolio-anchored suppliers offering bundled coil-microcatheter-accessory configurations. The pattern concentrates in United States integrated delivery networks with centralized supply chain authority.
Global Neurovascular Embolization Devices (Neurology) Market Segmentation
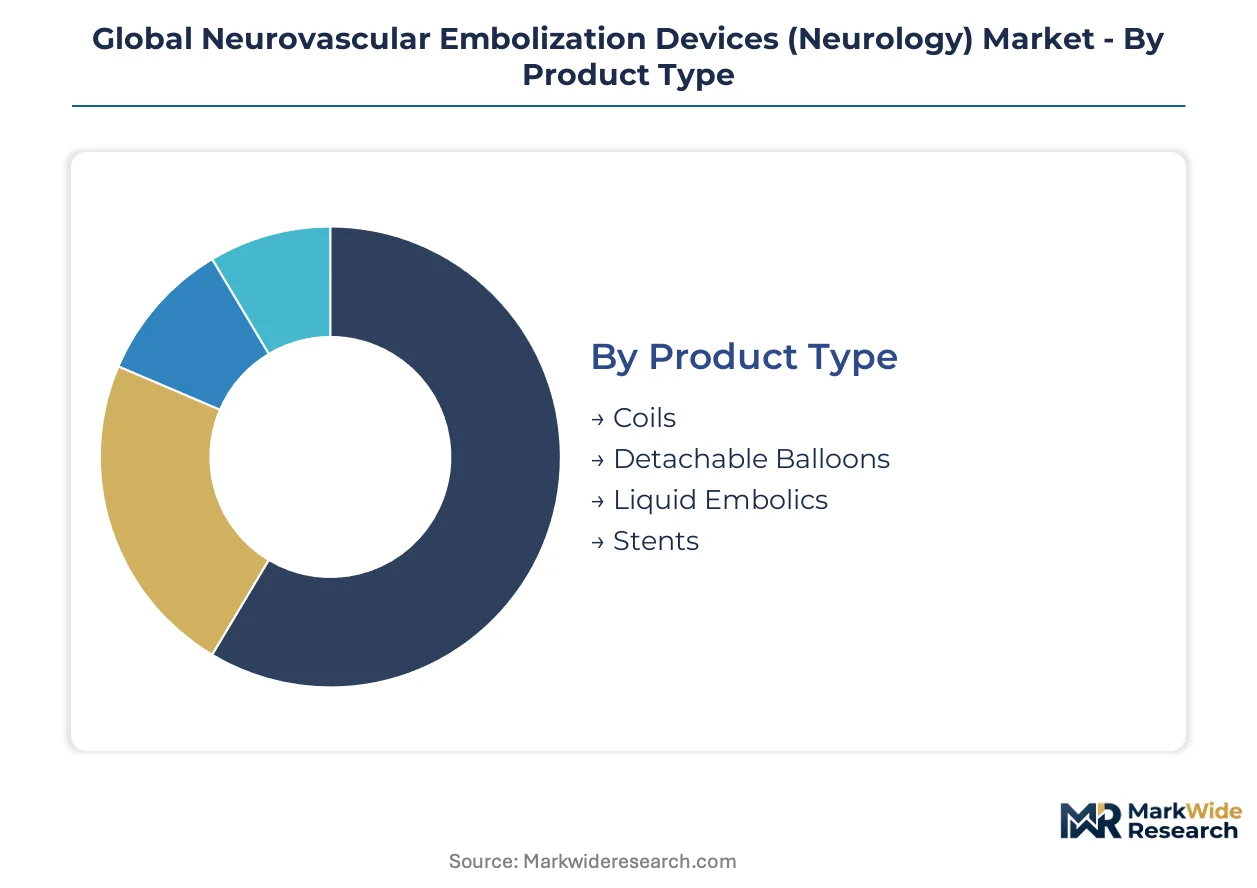
Device selection in neurovascular embolization hinges on lesion morphology, access route feasibility, and institutional capability matrices. Procurement committees weight installed base familiarity against emerging platform economics when segmenting capital allocation across service lines.
Product Type:
Metallic platforms command volume share while polymer formulations capture premium positioning in complex malformation cases.
- Coils:Platinum-titanium alloys deliver controlled thrombosis through 0.014-inch microcatheter compatibility. Demand concentrates in United States tertiary stroke centers where transfemoral protocols dominate aneurysm service lines and reimbursement clarity supports high-volume deployment.
- Liquid Embolics:Ethylene-vinyl alcohol copolymers and n-butyl cyanoacrylate formulations penetrate arteriovenous malformation indications through controlled injection viscosity. Penetration is climbing the fastest in German and Japanese metropolitan clusters where specialized neuroradiology training enables precise delivery technique.
- Detachable Balloons:Latex and silicone constructs enable temporary flow occlusion in fistula management.
- Stents:Nitinol flow-diverters modulate hemodynamics across wide-neck aneurysm geometries.
Mature deployment sits with coils. Newer deployment is concentrated in liquid embolics.
Delivery Mode:
Catheter-based protocols anchor procedure economics while hybrid configurations capture reimbursement premiums for complex cases.
- Endovascular:Transfemoral and transradial access routes deliver devices through 6-French guiding catheters under fluoroscopic navigation. Volume concentrates in hospital systems with dedicated biplane angiography suites and 24/7 stroke team activation protocols.
- Hybrid:Operating suite convergence combines surgical exposure with endovascular capability for giant aneurysms and failed primary interventions. Adoption is expanding most quickly in United States academic medical centers where capital investment in hybrid infrastructure aligns with service line differentiation strategies.
- Surgical:Direct vascular access enables device placement in anatomically unfavorable lesions.
- Transcatheter:Specialized microcatheter platforms enable distal territory navigation.
Established infrastructure favors endovascular protocols. Capital expansion targets hybrid capability.
End User:
Acute care settings absorb device volume while outpatient migration pressures reimbursement design.
- Hospitals:Comprehensive stroke centers maintain neuroradiology fellowship programs, biplane angiography suites, and neurocritical care units. Device procurement authority centralizes in supply chain committees spanning aneurysm and stroke service lines.
- Ambulatory Surgical Centers:Selective aneurysm and diagnostic angiography cases migrate to outpatient settings where procedure bundling and reduced overhead improve margin profiles. Expansion is gaining share fastest in United States markets with commercial payer contracts enabling site-of-service flexibility.
- Clinics:Diagnostic referral and post-procedure monitoring functions concentrate patient flow.
- Specialty Centers:Dedicated cerebrovascular institutes concentrate high-complexity caseloads.
Device volume anchors in hospital stroke centers. Site-of-service shift targets ambulatory surgical centers.
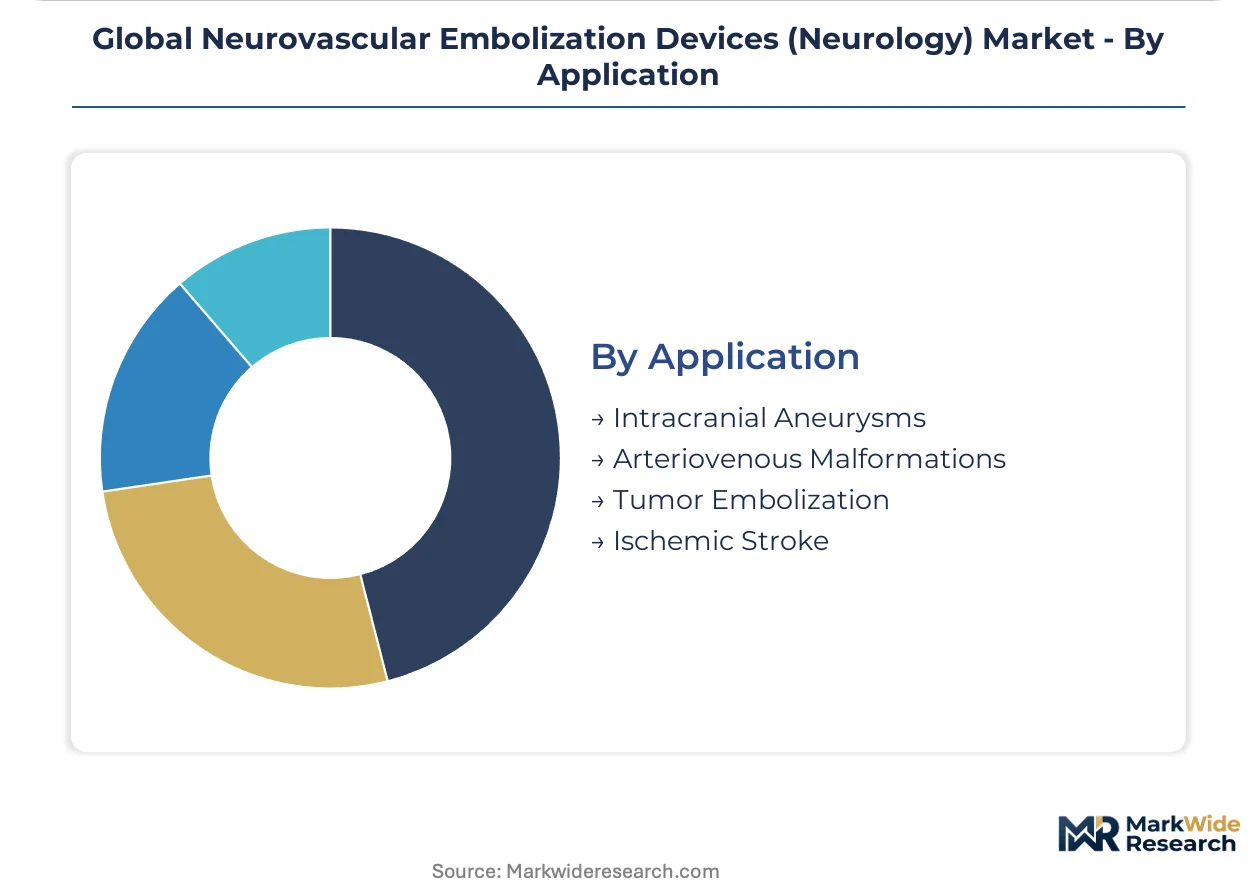
Application:
Hemorrhagic indications dominate device consumption while ischemic pathways expand thrombectomy-adjacent opportunities.
- Intracranial Aneurysms:Saccular and fusiform morphologies drive coil and flow-diverter utilization across anterior and posterior circulation territories. Procedure volume concentrates in Japan and Germany where screening protocols and aging demographics expand treatable patient pools.
- Ischemic Stroke:Mechanical thrombectomy creates downstream embolization demand for tandem lesions and rescue scenarios. Growth is accelerating most quickly in United States comprehensive stroke centers where door-to-device metrics and payer quality incentives expand eligible patient identification.
- Arteriovenous Malformations:Congenital shunt lesions require staged embolization prior to surgical or radiosurgical management.
- Tumor Embolization:Pre-operative devascularization reduces intraoperative bleeding in meningioma and juvenile nasopharyngeal angiofibroma cases.
Revenue concentration rests with intracranial aneurysms. Steepest expansion trajectory belongs to ischemic stroke adjacencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device production concentrates in precision manufacturing hubs while procedure consumption clusters in tertiary stroke centers with specialized neuroradiology infrastructure. Germany and Japan export coil and flow-diverter platforms to markets lacking domestic medtech capabilities. The United States absorbs the highest absolute device volume through comprehensive stroke center networks.
United States
Comprehensive stroke centers in Boston, Houston, and Los Angeles drive coil and liquid embolic consumption through 24/7 neurointerventional team activation. FDA breakthrough device designations compress premarket review timelines for novel embolic constructs. The Cleveland Clinic and Mayo Clinic anchor hybrid operating suite adoption for complex aneurysm cases.
Germany
Specialized neuroradiology training programs at Heidelberg and Munich university hospitals expand the interventionalist pool treating wide-neck aneurysms. EU MDR technical documentation requirements elevate clinical evidence thresholds for bioresorbable coil registrations. The Baden-Württemberg medical technology cluster around Tübingen and Freiburg hosts precision nitinol stent manufacturing.
Japan
Aging demographics and cerebral aneurysm screening protocols expand treatable patient pools in Tokyo and Osaka metropolitan stroke centers. PMDA shonin approval processes align with specialized credentialing pipelines for neurointerventionalists. The Kobe and Osaka medical device manufacturing corridor supplies platinum-titanium coil platforms across Asia-Pacific.
India
Private hospital infrastructure investment in Mumbai and Delhi creates whitespace for liquid embolic penetration in arteriovenous malformation segments. CDSCO regulatory pathways for neurointerventional products accelerate market entry for multinational manufacturers. Hyderabad and Bengaluru emerging as catheter-based procedure training hubs for South Asian interventionalists.
Switzerland
Swissmedic approval processes and precision engineering capabilities support flow-diverter stent development for complex cerebrovascular geometries. The Basel-Zurich medtech corridor concentrates nitinol processing and microcatheter manufacturing expertise. University Hospital Zurich anchors European clinical validation trials for next-generation embolic materials.
Global Neurovascular Embolization Devices (Neurology) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across coil, liquid embolic, and flow-diverter segments. The vendor base stratifies into three tiers: portfolio-anchored hospital suppliers, technology-differentiated niche players, and regional distributors serving price-sensitive markets. Dominant competitive moves include integrated system contracting that bundles coils with microcatheters and access accessories, plus strategic partnerships that secure precious metal supply chains for platinum and nitinol inputs.
Among diversified medtech conglomerates, Stryker and Medtronic occupy positions as portfolio-anchored suppliers capable of spanning stroke and aneurysm service lines through bundled procurement agreements. Penumbra exemplifies the technology-differentiated specialist archetype, with its aspiration-system integration extending footprint in thrombectomy-adjacent procedures. These three companies represent the competitive poles around which supply agreements and technology licensing arrangements currently organize.
| Leading Market Players |
|---|
| Stryker |
| Medtronic |
| Johnson & Johnson |
| Terumo Corporation |
| Penumbra |
| MicroVention |
| B. Braun Melsungen AG |
| Boston Scientific Corporation |
| Merit Medical Systems |
| Others |
Supply & Pricing Matrix
Platinum spot price volatility cascades through coil manufacturing cost structures, compressing margins at the OEM tier while forcing hospital procurement committees toward multi-year volume commitments that lock in price bands against metal input swings.
Pricing Analysis
Cost-down pressure on standard-grade coils accelerates because United States integrated delivery networks are consolidating purchasing authority across stroke and aneurysm service lines. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated flow-diverters from CE-marked legacy platforms and unbranded regional alternatives. Price differentiation hinges on PMDA shonin approval status and biplane angiography suite compatibility. Community hospital buyers exhibit highest price sensitivity, while academic medical centers absorb premium positioning for complex case capability.
Supply Chain Analysis
Device refurbishment flows remain minimal given sterility requirements and single-use regulatory classifications, though platinum recovery from explanted coils is gaining traction in German and Japanese tertiary centers. Manufacturing concentrates in Switzerland, Germany, and Japan for precision nitinol stent fabrication and platinum-titanium coil winding. Raw material dependencies center on South African platinum group metals, Australian titanium sponge, and Chinese rare earth elements for catheter braiding. Single-source vulnerability concentrates in nitinol shape-memory alloy suppliers serving the Tübingen and Kobe medical device clusters. Distribution runs through GPO contracts in the United States, direct hospital agreements in Germany, and specialized neuroradiology distributors in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized interventionalist training slots constrain procedure volume expansion, propping device pricing power as hospitals compete for limited neurointerventional team coverage.
For Market Incumbents: Extend portfolio-anchored supply agreements into ambulatory surgical center networks before site-of-service migration accelerates. Deepen backward integration into platinum wire drawing to offset South African supply concentration. Defensive priority centers on locking liquid embolic formulary status ahead of nBCA generic entry. For New Entrants and Emerging Players: The mid-tier price-point gap between Stryker's integrated bundles and regional coil distributors creates entry space for modular microcatheter-compatible platforms. Target India's private hospital infrastructure investment in Mumbai and Delhi for liquid embolic penetration. Go-to-market angle should emphasize CDSCO-aligned regulatory pathways and train-the-trainer partnerships with Hyderabad-based interventionalist education hubs. For Investors and Strategic Acquirers: Distressed-cycle entries favor bioresorbable coil developers with EU MDR technical documentation already filed in Switzerland and Germany. Long-term viability rests on FDA PMA pathway completion for next-generation embolic materials. Watch for PMDA shonin approval timeline compression as the inflection signal for Japanese market access premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates premarket review timelines for novel coil platforms, compressing competitor response windows. |
| CE Marking Pathway Under EU MDR | Elevates clinical evidence thresholds, filtering market entry to well-capitalized developers with established regulatory infrastructure. |
| Hospital System Partnership | Secures multi-year integrated system contracts spanning stroke and aneurysm service lines, displacing standalone device vendors. |
| Software Companion Development | Enables real-world evidence capture under FDA CDRH digital health guidance, supporting post-market surveillance obligations. |
| Reimbursement Strategy | Aligns device procurement with CMS quality incentives and commercial payer site-of-service flexibility policies. |
Research Methodology
Multi-period observation of catheter-based aneurysm treatment volumes and coil platform installed base expansion anchored the trend analysis, supplemented by interviews with neuroradiology fellowship directors, hospital supply chain managers, GPO contracts specialists, and PMDA regulatory consultants. Secondary validation drew from FDA 510(k) and PMA filings, EUDAMED device registrations, Japan Ministry of Health stroke center accreditation data, and hospital procurement database extracts. Bottom-up procedure volume modeling triangulated against top-down manufacturer revenue disclosures.
Segment-weighting across product type, delivery mode, end user, and application dimensions structured the analytical framework over the projection horizon. CAGRs derived from logistic diffusion curves fitted to tertiary stroke center expansion rates and interventionalist training pipeline outputs. Industry-specific forecast inputs incorporated platinum price index trajectories and EU MDR post-market surveillance cost assumptions.
Inputs from PMDA shonin approval databases and CDSCO neurointerventional product registrations were available through the study window; gaps in real-world evidence submission timelines for bioresorbable constructs introduce uncertainty bands around next-generation platform adoption curves. Forecasts reflect documented assumptions regarding reimbursement clarity persistence and training program expansion rates. Practitioners should monitor FDA breakthrough designation award velocity and hybrid operating suite capital investment announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Moyamoya Disease Market
Neurology
Frontotemporal Disorders Treatment Market
Neurology
Cerebral Spinal Fluid (CSF) Management Market
Neurology
Cervical Dystonia Treatment Market
Neurology
Tourette Syndrome Market
Neurology
Vertebrobasilar Insufficiency Treatment Market
Neurology
Mild Traumatic Brain Injury Treatment Market
Neurology
Idiopathic Intracranial Hypertension Therapeutics Market
Neurology
Neurodegenerative Disease Treatment Market
Neurology
North America Neurology Monitoring Market
Neurology
Global Sciatica Treatment Market
Neurology
Global Acoustic Neuroma Market
Neurology
Transverse Myelitis Treatment Market
Neurology
Cerebral Aneurysm Management Market
Neurology
Diabetic Neuropathy Market
Neurology
Benign Positional Vertigo Treatment Market