
 Mild Traumatic Brain Injury Treatment Market | 2026-2036
Mild Traumatic Brain Injury Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Mild Traumatic Brain Injury Treatment Market Outlook
Hospital procurement channels for mTBI diagnostics is fragmenting as point-of-care testing displaces centralized laboratory routing. Medtronic leverages its neurosurgical installed base to sustain service contracts across tier-one trauma centers. Abbott Laboratories differentiates through handheld biomarker platforms that occupy emergency department workflow slots. BrainScope competes on rapid electroencephalographic assessment, positioning its disposable electrode arrays against capital-intensive imaging alternatives.
Mild traumatic brain injury treatment encompasses pharmacological interventions, physical rehabilitation modalities, and diagnostic technologies designed to detect cellular-level neural disruption following closed-head trauma. Functional parameters include Glasgow Coma Scale scoring of 13-15, loss of consciousness under 30 minutes, and post-traumatic amnesia resolving within 24 hours, with therapeutic goals centered on preventing secondary neuronal injury cascades. Medication categories command the deepest margin pools due to chronic prescribing patterns in recovery-phase patients, while diagnostic tools represent the fastest-expanding segment as sideline and battlefield screening protocols proliferate. Rehabilitation equipment sustains steady replacement demand across outpatient clinics, though home care channels are accelerating as telehealth-integrated physical therapy platforms gain reimbursement traction.
FDA 510(k) pathways and the Centers for Medicare & Medicaid Services coverage determinations shape commercial viability for novel mTBI diagnostics and therapeutics in the United States, while ISO 13485 quality management standards govern export manufacturing compliance for device manufacturers. The Department of Defense blast-injury research program and NCAA concussion safety mandates collectively steer R&D investment toward objective biomarker quantification rather than symptom-reporting dependence. Stakeholders must monitor evolving reimbursement codes for digital therapeutic platforms and decide whether to build proprietary biomarker panels or license validated protein assays from academic medical centers.
Market Dynamics
Hospital emergency departments are compressing diagnostic turnaround times from hours to minutes, forcing device manufacturers to abandon capital-intensive imaging platforms in favor of disposable, point-of-care formats that slot directly into triage workflows.
Growth Catalysts
- NCAA Concussion Safety Mandates:Collegiate athletics programs across the United States must deploy objective biomarker protocols, creating institutional demand for rapid sideline screening technologies that bypass symptom-dependent assessments.
- Department of Defense Blast-Injury Research:Military funding streams prioritize neurodiagnostic platforms capable of battlefield deployment, accelerating FDA clearance timelines for ruggedized, portable electroencephalographic devices.
- Telehealth-Integrated Physical Therapy:Remote rehabilitation platforms are capturing reimbursement codes previously reserved for clinic-based modalities, expanding addressable demand into home care channels.
Market Restraints
- Biomarker Assay Validation Costs:Academic medical centers control proprietary protein panels, forcing commercial developers into expensive licensing arrangements or protracted independent validation studies.
- ISO 13485 Compliance Burden:Device manufacturers targeting export markets face quality management audits that extend production timelines and elevate working capital requirements.
- Symptom-Reporting Dependency:Glasgow Coma Scale scoring and patient-reported outcome measures remain entrenched in clinical workflows, creating friction against objective neurodiagnostic adoption.
Strategic Opportunities
- Underserved Pediatric Populations:Youth sports leagues lack standardized concussion protocols, presenting white space for disposable diagnostic formats priced for high school and amateur athletic budgets.
- Digital Therapeutic Reimbursement:CMS coverage determinations for cognitive rehabilitation software are expanding, enabling prescription-model monetization previously unavailable to app-based interventions.
- Biomarker-Imaging Fusion:Convergence of handheld blood-based assays with portable EEG arrays enables multi-modal diagnostic panels that command premium pricing against single-technology competitors.
Industry Challenges
- Neuroimaging Specialist Shortage:Radiologist interpretation of computed tomography scans for mTBI cases faces capacity constraints, creating bottlenecks that point-of-care devices must circumvent without sacrificing accuracy.
- 510(k) Predicate Device Navigation:FDA clearance pathways require demonstration of substantial equivalence to existing neurodiagnostics, complicating novel biomarker platform submissions lacking established comparators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mild Traumatic Brain Injury Treatment Market |
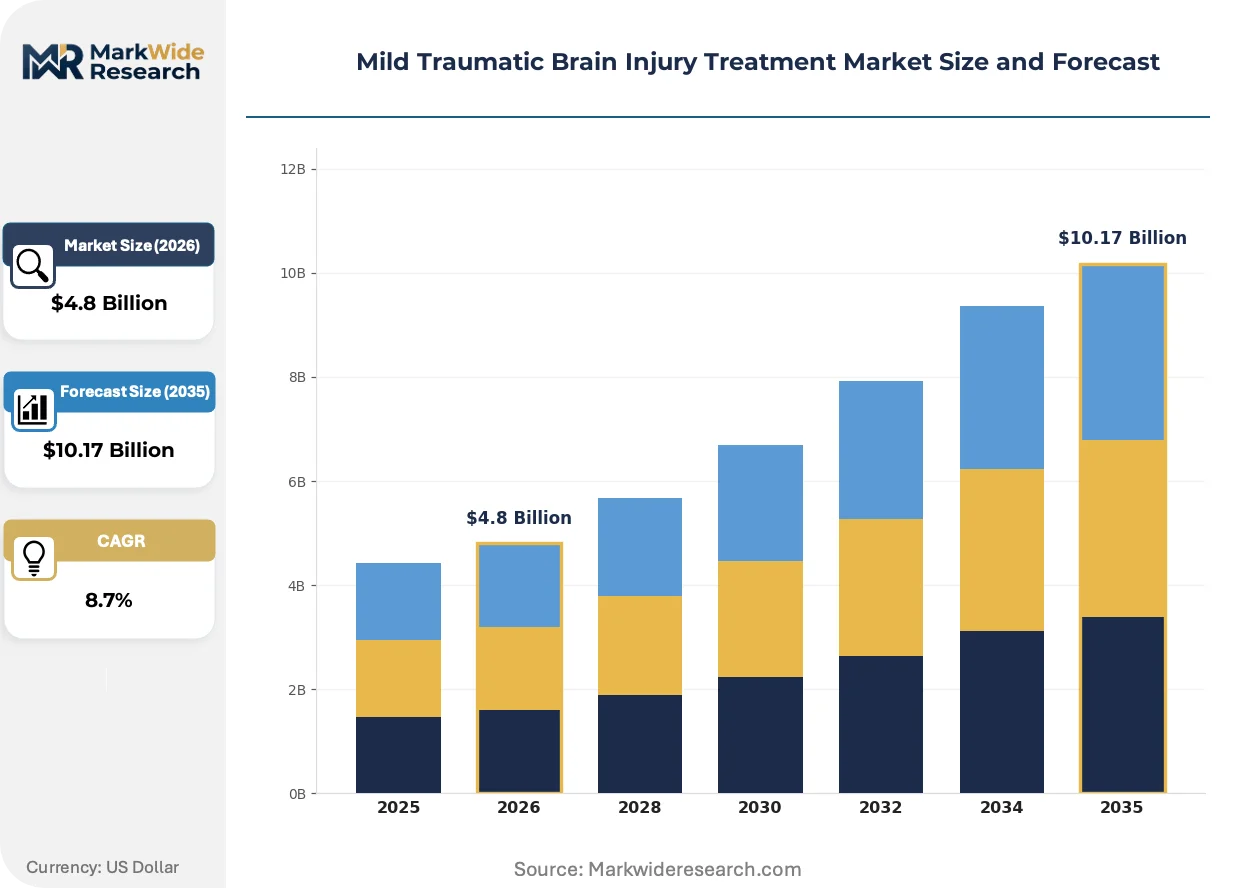
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medication, Rehabilitation Equipment, Diagnostic Tools, Neuroprotective Agents Delivery Mode: Oral, Intravenous, Topical, Inhalation End User: Hospitals, Outpatient Clinics, Rehabilitation Centers, Home Care Treatment Stage: Acute Phase, Recovery Phase, Long-term Care, Follow-up |
| Companies Covered | NeuroVive Pharmaceutical AB, TEVA Pharmaceutical Industries Ltd., Integra LifeSciences Corporation, Medtronic, Neuren Pharmaceuticals Ltd., Abbott Laboratories, Hope Biosciences, BrainScope Company, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mild Traumatic Brain Injury Treatment Market Strategic Shifts
Neurodiagnostic hardware is miniaturizing while software layers extract clinical-grade signals from consumer-grade sensors, collapsing the cost floor for objective concussion assessment and democratizing access beyond specialist centers.
Handheld electroencephalographic arrays with disposable electrodes are rendering obsolete capital-intensive magnetic resonance imaging and computed tomography routing for suspected mTBI cases in emergency departments. Hospital systems in the United States are piloting these devices in tier-one trauma centers, with procurement committees prioritizing formats that integrate directly with electronic health record systems. The structural consequence is a compression of neurodiagnostic service contracts toward per-test disposable economics rather than multi-year imaging equipment leases.
The FDA's expanding use of the 510(k) De Novo pathway for novel neurodiagnostic devices is compressing premarket submission timelines for biomarker-based platforms. Manufacturers are responding by front-loading clinical validation studies to satisfy substantial equivalence requirements, redirecting R&D budgets from hardware engineering toward regulatory affairs staffing. Diagnostic segments with predicate device density are experiencing accelerated competitive entry, while entirely novel technology categories face extended review cycles.
Athletic trainers and combat medics are displacing physician-dependent concussion protocols with operator-independent screening tools that require minimal training. This behavioral shift is most visible in United States military field operations and NCAA Division I programs, where staffing constraints and liability exposure drive preference for objective, documented assessments over clinical judgment alone. Device manufacturers are responding by embedding automated interpretation algorithms that reduce operator skill requirements to basic device handling.
Mild Traumatic Brain Injury Treatment Market Segmentation
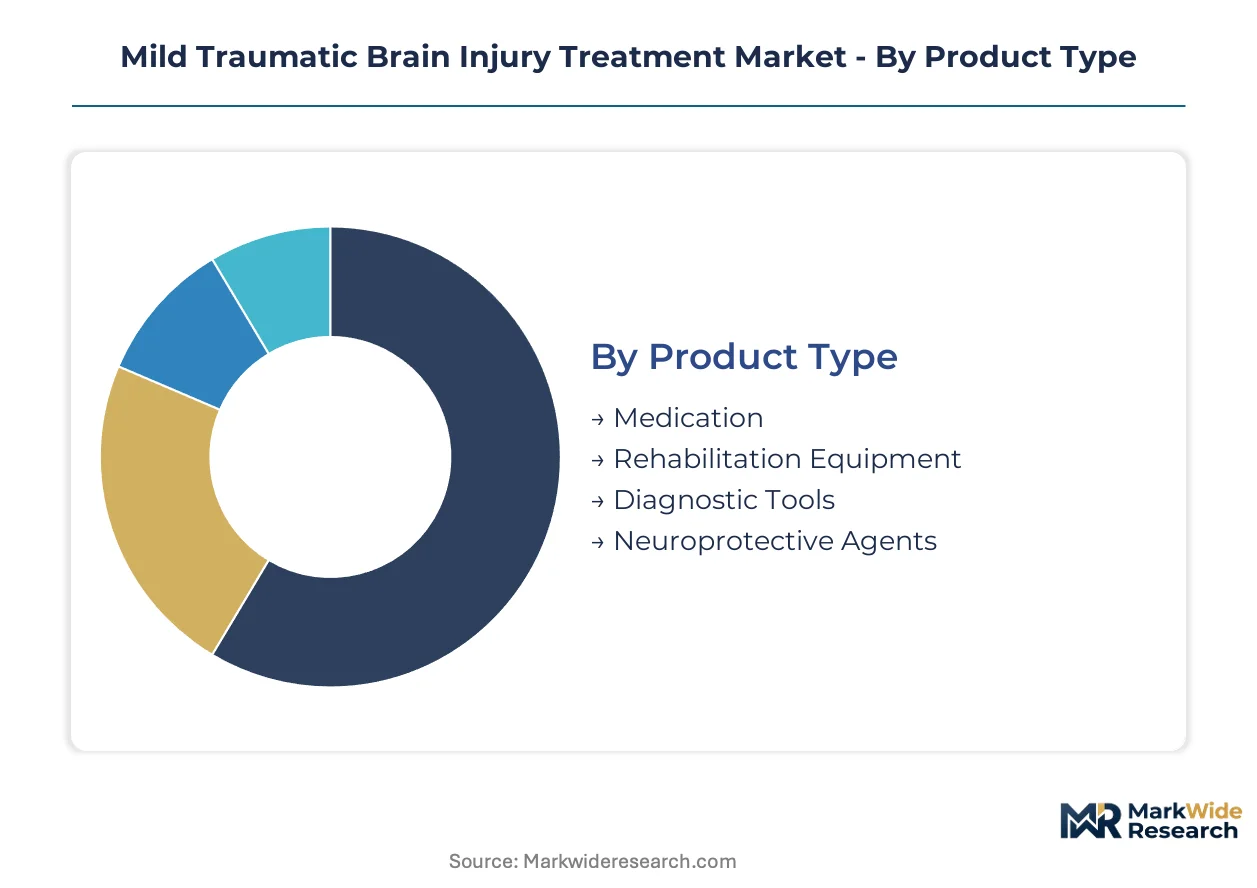
Segmentation in mTBI treatment reveals divergent margin structures and service intensity requirements across product and delivery categories. Hospital procurement committees weight capital equipment differently than disposable diagnostics, while reimbursement pathways fragment addressable demand across acute and recovery-phase interventions.
Product Type:
After-sales service intensity varies sharply across product categories, with rehabilitation equipment demanding multi-year maintenance contracts and diagnostic tools shifting toward per-test disposable economics.
- Medication:Chronic prescribing patterns in recovery-phase patients sustain recurring revenue streams. Hospital formularies in the United States prioritize neuroprotective agents with established FDA clearance, while European EMA pathways favor biosimilar competition.
- Diagnostic Tools:Handheld biomarker platforms and portable EEG arrays compress diagnostic turnaround from hours to minutes. NCAA concussion protocols and Department of Defense battlefield screening mandates concentrate demand for ruggedized, operator-independent formats.
- Rehabilitation Equipment:Balance training systems and cognitive therapy workstations require specialized technician calibration.
- Neuroprotective Agents:Experimental compounds targeting secondary neuronal injury cascades occupy preclinical pipelines.
By volume, Medication leads. By growth pace, Diagnostic Tools are climbing the fastest.
Delivery Mode:
Cost tier differentiation separates acute intervention formats from chronic maintenance therapies, with intravenous delivery commanding premium pricing in emergency settings.
- Oral:Tablet and capsule formulations dominate recovery-phase maintenance prescribing. United States retail pharmacy channels capture volume through 90-day supply authorizations, while CMS reimbursement codes favor generic substitution.
- Intravenous:Hospital emergency departments administer neuroprotective infusions during the acute window. Tier-one trauma centers in the United States stock lyophilized formulations with extended shelf stability for mass casualty readiness.
- Topical:Transdermal patches for symptom management occupy niche prescribing.
- Inhalation:Aerosolized delivery mechanisms remain investigational for blood-brain barrier penetration.
By installed base, Oral formulations dominate. By revenue per dose, Intravenous delivery commands premium positioning.
End User:
Customer type fragmentation channels identical products through divergent procurement workflows, with hospital systems negotiating enterprise contracts against clinic spot purchasing.
- Hospitals:Emergency departments and neurosurgical units consolidate purchasing through group purchasing organizations. Medtronic and Abbott Laboratories compete for service contract renewals across tier-one trauma centers in the United States.
- Rehabilitation Centers:Outpatient physical therapy clinics drive equipment replacement cycles. Telehealth-integrated platforms are capturing reimbursement codes previously reserved for facility-based modalities.
- Outpatient Clinics:Sports medicine practices concentrate in collegiate athletics corridors.
- Home Care:Remote patient monitoring devices expand addressable demand beyond clinical settings.
By absolute expenditure, Hospitals lead. By expansion trajectory, Home Care channels are gaining share fastest.
Treatment Stage:
Maturity gradients separate established acute-phase protocols from emerging long-term care interventions, with FDA clearance density highest in early-window therapeutics.
- Acute Phase:Neurodiagnostic assessment and neuroprotective intervention within 24 hours of injury. Department of Defense blast-injury research programs prioritize objective biomarker quantification over symptom-reporting dependence.
- Recovery Phase:Cognitive rehabilitation and physical therapy sustain six-to-twelve-month intervention windows. Digital therapeutic platforms are securing CMS coverage determinations for prescription-model monetization.
- Long-term Care:Persistent post-concussive symptom management occupies expanding clinical attention.
- Follow-up:Structured reassessment protocols remain inconsistently implemented across health systems.
By protocol standardization, Acute Phase leads. By unmet need expansion, Long-term Care presents the steepest growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance pathways and Department of Defense research funding anchor the United States as the dominant geography for mTBI diagnostic commercialization, while EMA regulatory frameworks and national health technology assessment programs shape European market entry strategies.
United States
NCAA concussion safety mandates and military blast-injury research programs drive institutional procurement of objective neurodiagnostic platforms. FDA 510(k) pathways compress premarket timelines for portable electroencephalographic devices. Boston and San Diego medical technology clusters concentrate development activity for ruggedized battlefield screening formats.
Germany
Automotive industry occupational health programs and professional sports league medical standards sustain demand for sideline assessment technologies. EMA quality management requirements and BfArM medical device regulations govern commercialization pathways. Munich and Heidelberg academic medical centers anchor biomarker validation partnerships with commercial developers.
Japan
Aging population concussion protocols and corporate wellness screening programs expand addressable demand beyond traditional trauma settings. PMDA medical device approval frameworks and JIS quality standards structure market entry requirements. Tokyo and Osaka metropolitan hospital systems pilot telehealth-integrated rehabilitation platforms for remote patient monitoring.
United Kingdom
NHS England technology appraisal programs and sports governing body medical guidelines steer procurement toward cost-effective diagnostic formats. MHRA regulatory oversight and NICE health technology assessments determine reimbursement eligibility. London and Manchester trauma networks consolidate purchasing through specialized neurosciences commissioning groups.
Australia
Australian Defence Force blast-injury research and professional rugby league concussion protocols generate institutional demand for objective screening tools. TGA medical device registration requirements and Medicare Benefits Schedule coverage determinations shape commercial viability. Melbourne and Sydney academic hospitals lead clinical validation studies for handheld biomarker platforms.
Mild Traumatic Brain Injury Treatment Market Competitive Environment
Diversified medical technology conglomerates and specialized neurodiagnostic developers split the market across capital equipment and disposable diagnostic formats. The vendor base organizes into three strategic archetypes: integrated hospital supply contractors leveraging neurosurgical installed bases, handheld platform specialists capturing emergency department workflow slots, and biomarker assay developers navigating academic licensing arrangements. Dominant competitive moves include strategic partnerships with trauma center networks and portfolio diversification into telehealth-integrated rehabilitation modalities.
Among diversified medical technology conglomerates, Medtronic and Abbott Laboratories occupy positions anchored by existing hospital service contracts and point-of-care platform development. BrainScope exemplifies the specialized neurodiagnostic archetype, representing the portable electroencephalographic segment competing against capital-intensive imaging alternatives. These three companies illustrate the competitive tension between installed-base leverage and disruptive workflow integration.
| Leading Market Players |
|---|
| NeuroVive Pharmaceutical AB |
| TEVA Pharmaceutical Industries Ltd. |
| Integra LifeSciences Corporation |
| Medtronic |
| Neuren Pharmaceuticals Ltd. |
| Abbott Laboratories |
| Hope Biosciences |
| BrainScope Company |
| GE Healthcare |
| Others |
Value Chain & Pricing Dynamics
Disposable electrode array manufacturing concentrates in Malaysian electronics corridors and Shenzhen component clusters, feeding margin pools downstream to FDA-cleared device assemblers who command per-test pricing premiums against capital-intensive imaging alternatives. This upstream concentration in Southeast Asian contract manufacturing directly shapes how neurodiagnostic vendors structure service economics across tier-one trauma centers.
Pricing Analysis
United States emergency departments absorb 40-60% price premiums over European hospital systems for identical handheld EEG platforms, reflecting FDA clearance costs and Department of Defense procurement subsidies. Pricing stratifies across premium, standard, and economy tiers based on biomarker panel breadth and EHR integration depth. Cost compression in standard-tier devices is intensifying because BrainScope and Abbott Laboratories are racing to occupy identical workflow slots. Academic medical centers exhibit highest price sensitivity due to constrained research budgets, while military field procurement shows lowest sensitivity given blast-injury research program funding.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk planning for disposable electrode arrays and handheld device components. Manufacturing draws from Malaysia, Mexico, and Vietnam for final assembly, with silicon wafer fabrication resting on Taiwan and South Korea. Single-source vulnerability concentrates in proprietary biomarker reagents controlled by Boston and Heidelberg academic medical centers. Distribution runs through group purchasing organization contracts at hospital systems, with spot purchasing at outpatient sports medicine clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mTBI treatment market is experiencing high-growth disruption as FDA 510(k) De Novo pathways compress neurodiagnostic clearance timelines from years to months, enabling point-of-care formats to displace centralized laboratory routing.
For Market Incumbents: Build installed-base moats through multi-year service contracts that embed disposable diagnostic replenishment into neurosurgical equipment leases. Medtronic and Abbott Laboratories should deepen backward integration into proprietary biomarker assay development to circumvent academic licensing costs. The emerging threat is BrainScope's rapid EEG assessment capturing emergency department workflow slots previously reserved for capital equipment vendors. For New Entrants and Emerging Players: Build out pediatric and youth sports league channels where standardized concussion protocols remain underdeveloped, creating white space for ruggedized, lower-cost disposable formats. The most penetrable segment is high school and amateur athletic budgets underserved by NCAA-mandated premium platforms. A direct-to-athletic-trainer go-to-market angle bypasses hospital procurement committee friction. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed neurodiagnostic platform specialists holding FDA-cleared EEG devices but lacking rehabilitation modality diversification. Long-term viability hinges on telehealth-integrated physical therapy reimbursement expansion over a five-to-ten year window. The acquisition target archetype is handheld biomarker developers with validated protein panels. The signal to watch is CMS coverage determination timing for digital therapeutic platforms.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) De Novo Submission | Accelerates market entry for novel biomarker platforms against predicate-dependent competitors. |
| Hospital System Partnership | Locks in multi-year service contracts through GPO negotiations at tier-one trauma centers. |
| Biomarker-Imaging Fusion Development | Commands premium pricing by combining handheld blood assays with portable EEG arrays. |
| Telehealth Platform Integration | Captures CMS reimbursement codes for remote cognitive rehabilitation previously reserved for clinics. |
| Academic Medical Center Licensing | Secures proprietary protein panel access without protracted independent validation studies. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with emergency department directors, neurosurgical service line administrators, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, CMS coverage determinations, hospital procurement databases, and NCAA concussion protocol documentation. Bottom-up triangulation across device shipment estimates and top-down reconciliation against pharmaceutical prescribing patterns anchored market sizing.
Forecast inputs considered medication, diagnostic tools, rehabilitation equipment, and neuroprotective agents across oral, intravenous, topical, and inhalation delivery modes. Modeled dimensions included treatment stage segmentation, end-user channel fragmentation, and regional regulatory cluster variations. CAGRs were derived from segment-level growth differential analysis incorporating NCAA mandate implementation timelines and Department of Defense research funding trajectories.
Stress conditions across FDA clearance timeline compression, biomarker assay validation costs, and telehealth reimbursement code expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about protocol standardization velocity and military procurement continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Pediatric Neurology Device Market
Neurology
Global Neurology Clinical Trials Market
Neurology
Neurocognitive Assessment and Rehabilitation Market
Neurology
Global Neuromarketing Market
Neurology
Spain Neurology Devices Market
Neurology
United States Neurology Devices Market
Neurology
Neurology Devices Market
Neurology
North America Neurology Devices Market
Neurology
Chordoma Disease Market
Neurology
UAE Neurology Devices Market
Neurology
Vocal Cord Paralysis Market
Neurology
Neuropsychiatric Disorders and Treatment Market
Neurology
Movement Disorder Market
Neurology
Cerebral Spinal Fluid (CSF) Management Market
Neurology
Optic Neuritis Treatment Market
Neurology
Global Acoustic Neuroma Market