
 Transverse Myelitis Treatment Market | 2026-2036
Transverse Myelitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Transverse Myelitis Treatment Market Outlook
Specialized immunoglobulin formulations is reorganizing competitive priorities among manufacturers. Pfizer leverages its plasma-derived product infrastructure to sustain supply security for intravenous immunoglobulin therapies. Biogen specializes in neuroimmunology development pipelines, while Novartis anchors its position through hospital-centric distribution channels for high-acuity neurological interventions.
Transverse myelitis treatment encompasses acute immunomodulatory and chronic rehabilitative interventions targeting spinal cord inflammation, typically involving high-dose corticosteroid pulse therapy, plasmapheresis, or immunoglobulin infusion to halt autoimmune-mediated neural tissue damage. Corticosteroids retain the largest installed base among product types due to immediate availability and standardized emergency protocols, though plasma exchange captures expanding share in steroid-refractory presentations where rapid antibody clearance proves decisive. Intravenous administration routes dominate acute settings, while subcutaneous delivery gains traction in maintenance immunosuppression regimens.
FDA oversight through its Center for Biologics Evaluation and Research shapes plasma-derived product manufacturing standards, while EMA's orphan medicinal product framework influences European development incentives for rare neuroimmune conditions. The EU AI Act and FDA's evolving guidance on real-world evidence are reshaping post-market surveillance expectations for immunotherapy safety monitoring. Stakeholders must weigh regulatory divergence between US and European approval pathways when prioritizing clinical trial geography and manufacturing qualification strategies.
Market Dynamics
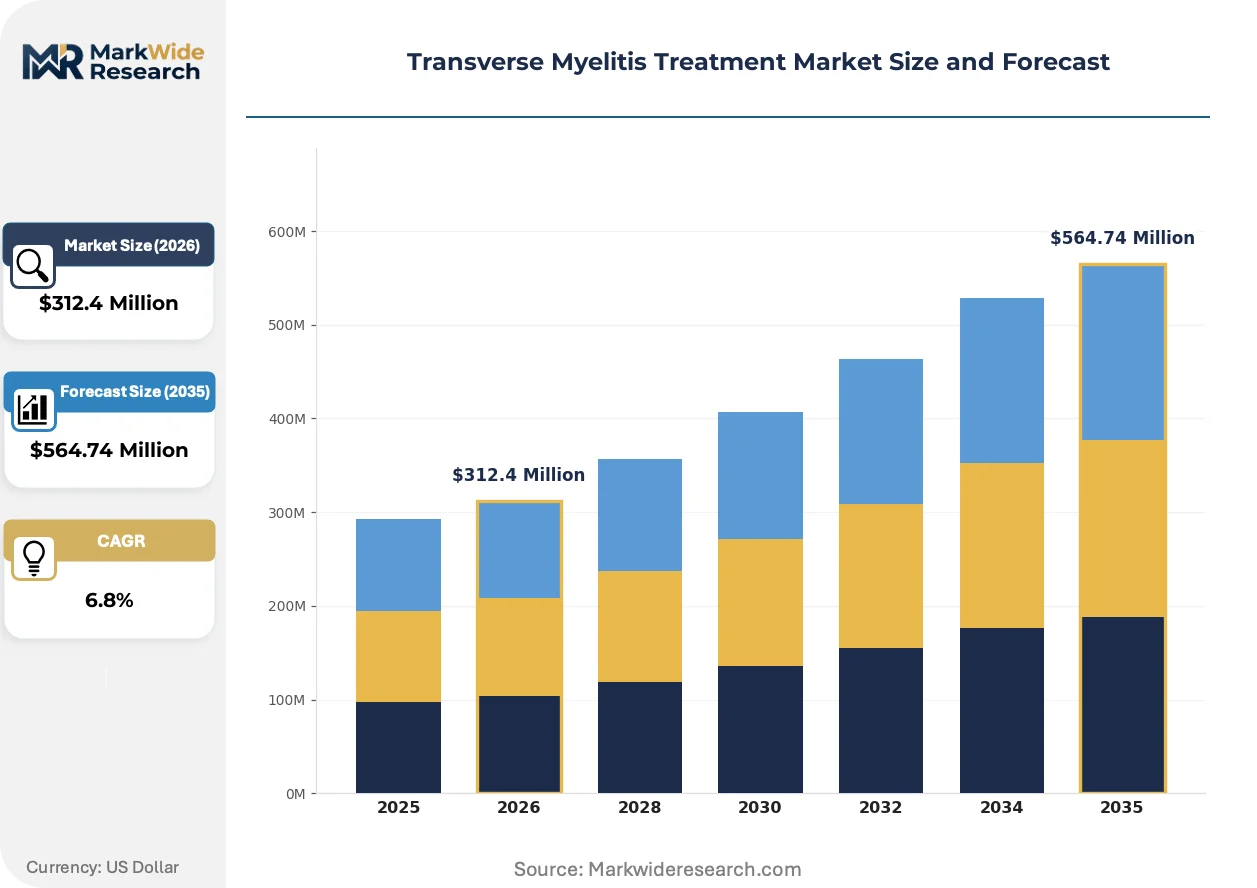
Hospital-based neurology departments are expanding plasma exchange protocols for steroid-refractory transverse myelitis cases, while FDA orphan drug designations compress development timelines for rare neuroimmune therapies. This dual pressure reshapes competitive positioning among plasma-derived product manufacturers and specialized immunoglobulin formulators.
Growth Catalysts
- FDA Orphan Drug Pathway:The FDA's orphan drug designation accelerates clinical trial timelines and extends market exclusivity for developers targeting rare neuroimmune indications, incentivizing portfolio entry.
- Academic Medical Center Expansion:Tertiary referral networks in the United States are consolidating transverse myelitis cases into specialized centers, concentrating demand for high-acuity interventions.
- Plasma Exchange Protocol Standardization:Emergency department protocols now incorporate plasmapheresis as second-line therapy for acute presentations, expanding addressable procedure volumes beyond corticosteroid monotherapy.
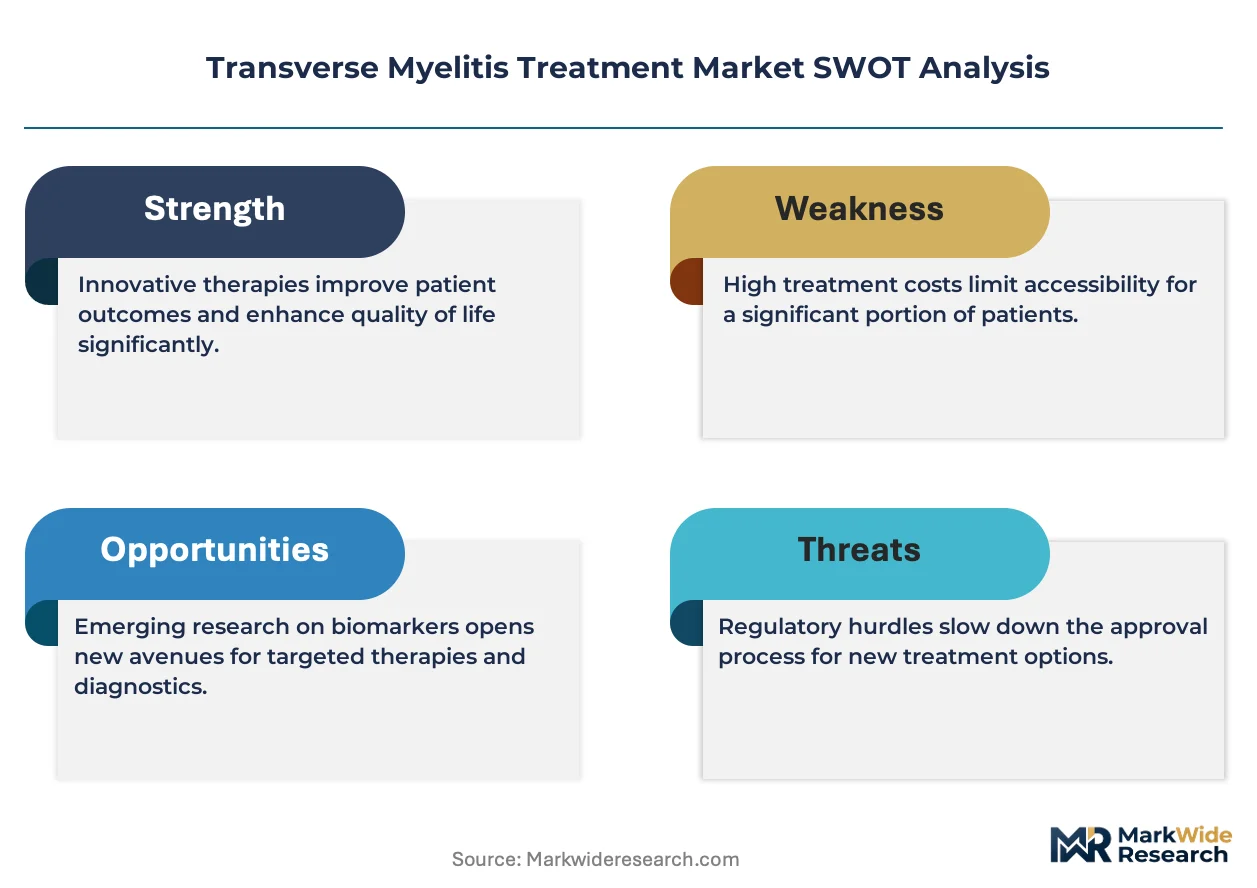
Market Restraints
- Plasma Supply Concentration:Fractionation capacity concentrates among a limited supplier base, creating vulnerability to collection center disruptions and donor availability fluctuations.
- EMA Orphan Framework Variability:Divergent European Medicines Agency incentive structures across member states complicate pan-European trial design and reimbursement negotiations.
- High-Dose Corticosteroid Substitution:Immediate availability and standardized emergency protocols for methylprednisolone pulse therapy limit plasma exchange penetration in first-line acute settings.
Strategic Opportunities
- Subcutaneous Maintenance Regimens:Home-based immunoglobulin delivery models reduce hospital dependency and capture chronic-phase patient volumes currently managed through infusion centers.
- Real-World Evidence Integration:FDA guidance evolution on post-market surveillance creates pathways for label expansion based on registry data and expanded access programs.
- Rehabilitative Service Bundling:Integration of acute immunomodulation with specialized spinal cord rehabilitation protocols offers margin capture across the care continuum.
Industry Challenges
- Neuroimmunology Specialist Scarcity:Fellowship-trained clinicians capable of diagnosing atypical transverse myelitis presentations remain concentrated at academic centers, limiting community hospital protocol adoption.
- Biologics Manufacturing Qualification:Plasma-derived product facilities require multi-year FDA Center for Biologics Evaluation and Research certification cycles, constraining capacity expansion responsiveness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transverse Myelitis Treatment Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Plasma Exchange, Immunosuppressants, Intravenous Immunoglobulin End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Settings Administration Route: Intravenous, Oral, Subcutaneous, Intramuscular Therapy Area: Neurology, Immunology, Emergency Medicine, Physical Therapy |
| Companies Covered | Sanofi, Pfizer, Biogen, Teva Pharmaceutical Industries, AstraZeneca, Novartis, Merck, Eli Lilly and Company, Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transverse Myelitis Treatment Market Strategic Shifts
Specialized immunoglobulin formulations are reorganizing manufacturer priorities, while regulatory frameworks on both sides of the Atlantic reshape post-market surveillance expectations for immunotherapy safety monitoring.
Subcutaneous immunoglobulin delivery technology is decomposing the traditional hospital-centric infusion model for chronic neuroimmune maintenance. Patients with stabilized transverse myelitis are adopting home-based administration systems at accelerating rates. This shift compresses hospital pharmacy revenue capture while expanding manufacturer direct-to-patient service infrastructure.
The EU AI Act and FDA's evolving real-world evidence guidance are reshaping post-market surveillance expectations for immunotherapy safety monitoring. Automated adverse event detection systems must now integrate algorithmic transparency requirements into pharmacovigilance workflows. High-acuity neurological interventions face the steepest compliance adjustment costs due to small patient populations and limited historical datasets.
Consolidation of case volumes into designated referral centers is altering procurement patterns for plasma exchange equipment and disposables. Hospital systems are negotiating enterprise contracts with fractionators rather than maintaining multiple supplier relationships. This concentration is most visible in the United States, where academic medical centers anchor clinical trial recruitment and drive protocol standardization across affiliated community hospitals.
Transverse Myelitis Treatment Market Segmentation
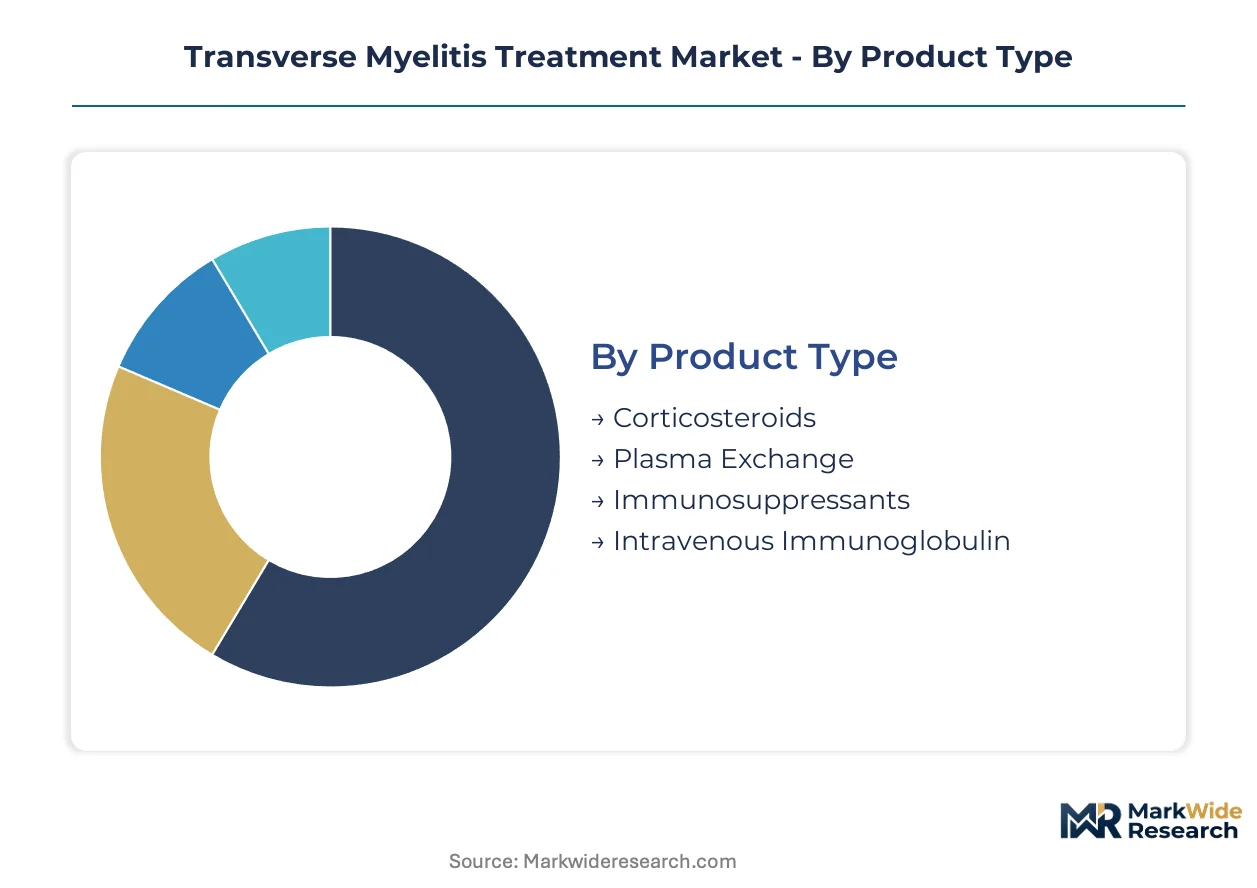
Transverse myelitis treatment segmentation reveals divergent supply chain architectures across acute and chronic care phases. Product type and administration route configurations determine whether therapies deploy through hospital-based emergency protocols or migrate toward home-based maintenance models.
Product Type:
Corticosteroids anchor domestic hospital formularies with immediate availability, while plasma exchange and immunoglobulin therapies depend on concentrated fractionation capacity that concentrates supply security planning among a limited supplier base.
- Corticosteroids:High-dose methylprednisolone pulse therapy constitutes the emergency standard of care, administered through standardized hospital protocols. Demand concentrates in United States academic medical centers and tertiary referral networks where rapid intervention protocols are most developed.
- Plasma Exchange:Therapeutic plasmapheresis clears circulating autoantibodies in steroid-refractory presentations. Adoption is expanding fastest in hospital neurology departments that have invested in apheresis infrastructure and trained specialized nursing staff.
- Immunosuppressants:Azathioprine and mycophenolate mofetil serve maintenance-phase patients requiring long-term disease modulation.
- Intravenous Immunoglobulin:Plasma-derived pooled immunoglobulin targets antibody-mediated neural tissue damage through immunomodulatory mechanisms.
Corticosteroids hold the largest share; momentum sits with plasma exchange as second-line protocol standardization advances.
End User:
Cost tier stratification separates high-acuity intervention sites from lower-intensity maintenance venues, with reimbursement differentials driving patient migration across the care continuum.
- Hospitals:Emergency departments and inpatient neurology units manage acute presentations through corticosteroid pulses and plasma exchange. Volume concentrates at academic medical centers with neuroimmunology fellowship programs and established apheresis capabilities.
- Rehabilitation Centers:Specialized spinal cord rehabilitation facilities capture post-acute patients requiring intensive physical and occupational therapy. These centers are expanding fastest as bundled payment models incentivize coordinated care across the treatment timeline.
- Clinics:Outpatient neurology practices monitor stabilized patients and titrate maintenance immunosuppression.
- Home Care Settings:Subcutaneous immunoglobulin delivery and nursing-supported medication administration serve mobility-limited chronic-phase patients.
Hospitals dominate value capture; rehabilitation centers are climbing the fastest as care coordination incentives intensify.
Administration Route:
Application context dictates route selection, with acute neural tissue protection requiring immediate bioavailability and chronic maintenance prioritizing patient autonomy and adherence sustainability.
- Intravenous:Delivers rapid serum concentration peaks essential for acute immunomodulation in emergency settings. Demand concentrates in hospital infusion centers and emergency departments where vascular access and monitoring infrastructure are immediately available.
- Subcutaneous:Home-based immunoglobulin administration systems reduce hospital dependency for chronic maintenance patients. This route is expanding most quickly among stabilized patients with reliable caregiver support or self-administration training.
- Oral:Corticosteroid tapers and maintenance immunosuppressants enable outpatient disease management.
- Intramuscular:Limited applications include specific immunoglobulin formulations and depot corticosteroid preparations.
Intravenous retains the largest installed base; subcutaneous delivery shows the steepest expansion trajectory as home infusion infrastructure matures.
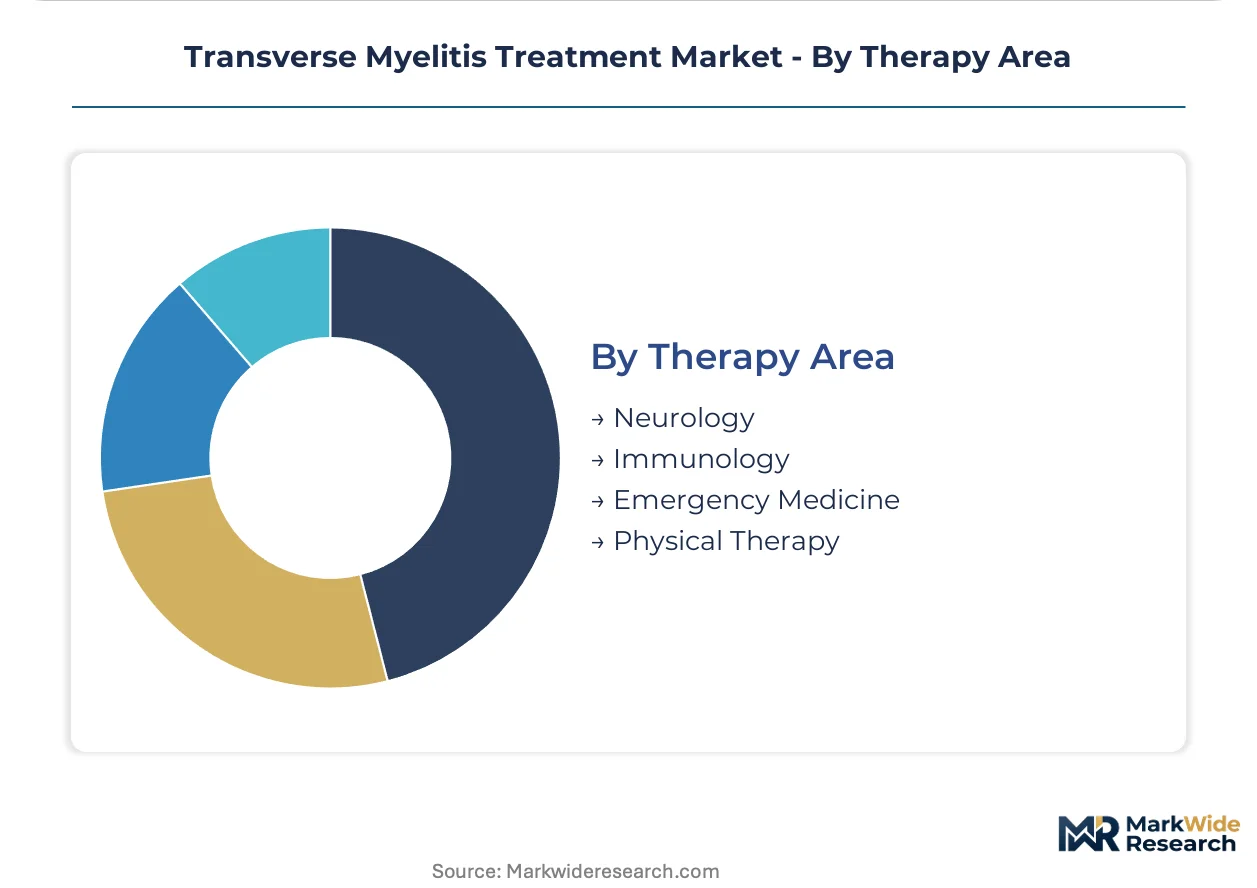
Therapy Area:
Customer type specialization determines protocol authority, with neurology departments controlling acute intervention decisions while physical therapy extends functional recovery timelines.
- Neurology:Fellowship-trained neuroimmunologists direct diagnostic workup and acute immunomodulatory selection. Case volume concentrates at United States academic medical centers with dedicated demyelinating disease clinics and active clinical trial portfolios.
- Physical Therapy:Specialized spinal cord rehabilitation protocols address ambulation, bowel and bladder function, and adaptive equipment training. This discipline is gaining share fastest as evidence accumulates for early intensive rehabilitation in incomplete spinal cord injuries.
- Immunology:Rheumatology and allergy-immunology consultants assist in complex autoimmune differential diagnosis.
- Emergency Medicine:Frontline providers initiate corticosteroid protocols and coordinate specialist consultation.
Neurology commands the largest share; physical therapy is expanding most quickly as functional outcomes data drives referral pattern shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasma-derived product flows concentrate among a limited supplier base, creating import dependency for fractionated immunoglobulin in markets lacking domestic collection infrastructure. Export capacity clusters in the United States and Western Europe, where fractionation facilities anchor supply security for neuroimmunology indications.
United States
Academic medical centers in Boston, Baltimore, and San Francisco drive protocol standardization for plasma exchange in steroid-refractory cases. FDA orphan drug designation compresses development timelines for rare neuroimmune therapies, incentivizing domestic clinical trial placement. The NIH Rare Diseases Clinical Research Network concentrates patient recruitment at tertiary referral hubs.
Germany
Specialized neurology departments at Charité Berlin and Heidelberg University Hospital anchor European apheresis protocol development. EMA orphan medicinal product framework provides fee waivers and protocol assistance for rare disease developers. Bavarian biotech clusters host plasma fractionation facilities serving Central European demand.
Japan
PMDA's Sakigake designation system accelerates review timelines for innovative neuroimmunology therapies. Tokyo and Osaka academic hospitals concentrate the country's limited neuroimmunology specialist workforce. Domestic plasma collection remains insufficient, creating reliance on imported immunoglobulin products.
United Kingdom
NHS England's Highly Specialised Services framework centralizes transverse myelitis care at designated neuroscience centers in London, Oxford, and Cambridge. MHRA post-Brexit regulatory autonomy enables tailored approval pathways for plasma-derived products. Scottish National Health Service operates independent procurement for immunoglobulin therapies.
India
CDSCO's orphan drug regulations remain underdeveloped, limiting formal incentives for rare neuroimmune indications. Apollo Hospitals and AIIMS Delhi anchor private and public sector neuroimmunology capacity. Maharashtra and Karnataka host emerging clinical trial sites targeting plasma exchange protocol adaptation for resource-limited settings.
Transverse Myelitis Treatment Market Competitive Environment
Listed leaders compete with private specialists across plasma-derived product manufacturing and neuroimmunology development pipelines. Market structure consolidates around fractionation capacity holders and specialized immunoglobulin formulators, with tiered competition separating integrated plasma collectors from therapy-focused developers. Three archetypes dominate: plasma infrastructure owners, neuroimmunology specialists, and diversified pharmaceutical conglomerates. Capacity expansion and strategic partnerships represent the dominant competitive moves, as manufacturers secure long-term supply agreements with hospital systems.
Within the plasma infrastructure tier, Pfizer leverages its fractionation network to sustain supply security for intravenous immunoglobulin therapies. Biogen occupies a position exemplifying neuroimmunology specialization, with development pipelines targeting demyelinating conditions. Novartis anchors the diversified conglomerate archetype through hospital-centric distribution channels for high-acuity neurological interventions.
| Leading Market Players |
|---|
| Sanofi |
| Pfizer |
| Biogen |
| Teva Pharmaceutical Industries |
| AstraZeneca |
| Novartis |
| Merck |
| Eli Lilly and Company |
| Roche |
| Others |
Value Chain & Pricing Dynamics
Fractionation facility qualification timelines stretching 36 to 48 months concentrate supply security planning among incumbent plasma collectors and directly inflate immunoglobulin procurement premiums for hospital systems lacking long-term offtake agreements. This lead-time rigidity anchors pricing power with established manufacturers while compressing margins for buyers caught in spot-market exposure during collection center disruptions.
Pricing Analysis
Hospital procurement teams anchor contract-based long-term offtake pricing for plasma-derived immunoglobulin therapies. Price differentiation hinges on FDA Center for Biologics Evaluation and Research certification tier and volume scale commitments, with academic medical centers commanding preferential rates through enterprise agreements. Cost compression in steroid-refractory second-line therapies is intensifying because plasma exchange protocol standardization expands addressable volumes. Community hospitals exhibit highest price sensitivity due to limited apheresis infrastructure and constrained pharmacy budgets.
Supply Chain Analysis
The United States and Germany anchor plasma fractionation capacity for immunoglobulin therapies serving neuroimmunology indications. Manufacturing rests on plasma collection center networks, apheresis equipment components, and specialized cold-chain logistics infrastructure. Single-source vulnerability concentrates in fractionation facility certification cycles, where multi-year FDA and EMA qualification timelines prevent rapid capacity response. Distribution runs through hospital-centric pharmacy networks and direct-to-patient home infusion services for maintenance-phase subcutaneous delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The transverse myelitis treatment market is recovering from cyclical plasma supply constraints as donor collection volumes normalize post-pandemic and fractionators reinvest in capacity expansion.
For Market Incumbents: Compound plasma collection infrastructure through backward integration into donor center networks and captive fractionation capacity in the United States and Germany. Secure long-term hospital system partnerships before subcutaneous home delivery models displace infusion center revenue. Prioritize FDA Center for Biologics Evaluation and Research certification maintenance as regulatory scrutiny on plasma-derived product safety intensifies. For New Entrants and Emerging Players: Lead with specialized immunoglobulin formulations targeting steroid-refractory presentations where plasma exchange adoption is climbing fastest. Home-based subcutaneous maintenance regimens represent the most penetrable segment, with patient self-administration training programs offering a differentiated go-to-market angle against incumbent hospital-centric distribution. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates seeking to divest non-core plasma infrastructure amid neuroimmunology pipeline refocusing. Long-term viability favors fractionation-integrated specialists with established FDA orphan drug designation track records. Monitor EMA orphan medicinal product framework harmonization progress across member states as an inflection indicator for European market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Capacity Expansion | Secures supply security for immunoglobulin therapies amid donor availability volatility. |
| FDA Orphan Drug Designation Pathway | Accelerates clinical trial timelines and extends market exclusivity for rare neuroimmune indications. |
| Subcutaneous Delivery Technology Investment | Captures chronic-phase patient volumes migrating from hospital infusion to home-based administration. |
| Academic Medical Center Partnership | Anchors clinical trial recruitment and protocol standardization across tertiary referral networks. |
| Real-World Evidence Registry Development | Supports FDA label expansion through post-market surveillance data from expanded access programs. |
Study Parameters
Initial hypotheses were tested against primary input from neuroimmunology fellowship directors, hospital pharmacy procurement managers, plasma fractionation executives, and regulatory affairs specialists at FDA and EMA, and refined through secondary validation against FDA orphan drug designation databases, ClinicalTrials.gov recruitment records, EMA orphan medicinal product registers, and hospital procurement contract filings. Bottom-up patient volume estimates and top-down fractionation capacity analysis were triangulated to constrain forecast variance.
Variance decomposition across the projection horizon isolates contributions from acute versus chronic therapy phases, intravenous versus subcutaneous administration route shifts, and hospital versus home care setting migration. CAGRs were derived from segmented patient population modeling and therapy penetration assumptions. Forecast inputs incorporate plasma collection center capacity expansion announcements and FDA Center for Biologics Evaluation and Research inspection cadence trends.
The analysis sits within stated boundaries; outcomes outside sustained plasma donor recruitment rates and stable regulatory approval timelines would require recalibration. Forecasts reflect assumptions on neuroimmunology specialist workforce concentration and hospital apheresis infrastructure investment trajectories. Recalibration cycles align with material shifts in FDA real-world evidence guidance evolution and EMA orphan framework incentive harmonization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Canada Neurology Devices Market
Neurology
Tourette Syndrome Market
Neurology
CNS Therapeutics Market
Neurology
Chile Neurology Devices Market
Neurology
Acute Repetitive Seizures Market
Neurology
Traumatic Brain Injuries Assessment Market
Neurology
Moyamoya Disease Market
Neurology
Neurocognitive Assessment and Rehabilitation Market
Neurology
Central Nervous System Lymphoma Treatment Market
Neurology
Cluster Headache Syndrome Market
Neurology
Narcolepsy Treatment Market
Neurology
Asia-Pacific Neurology Monitoring Market
Neurology
Neurology Devices Market
Neurology
Global Lambert-Eaton Myasthenic Syndrome Treatment Market
Neurology
Europe Neurology Monitoring Market
Neurology
Coma Diagnosis and Treatment Market