
 Global Network Transformation Market | 2026-2036
Global Network Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Network Transformation Market Foresight
Enterprise buyer concentration in telecommunications and financial services is rebalancing toward cloud-native procurement models. Cisco Systems leverages extensive channel partnerships to sustain router and switch dominance across legacy refresh cycles. Huawei Technologies anchors 5G infrastructure deployment in Asia-Pacific markets despite trade restrictions. Juniper Networks specializes in AI-driven automation for data center modernization, differentiating against broader portfolio competitors.
Network transformation encompasses the architectural migration from hardware-centric infrastructure to software-defined, virtualized, and automated network environments operating at sub-50 millisecond latency thresholds for edge workloads. Software-defined networking and network function virtualization constitute the technical backbone, enabling policy-driven traffic management across distributed compute fabrics. Cloud-native deployment models capture the fastest expansion trajectory as containerized network functions replace monolithic appliances. AI-driven automation concentrates margin pools through predictive operations and autonomous remediation capabilities.
FCC spectrum allocation rules in the United States, EU GDPR data sovereignty requirements, and China's MIIT cybersecurity standards collectively shape vendor product roadmaps and cross-border market access conditions. ETSI NFV specifications and 3GPP 5G standards further constrain interoperability claims and certification timelines. Stakeholders must monitor regulatory divergence between data localization mandates and cloud-native architectures when selecting deployment models.
Market Dynamics
Cloud-native procurement models are compressing traditional hardware refresh cycles across telecommunications and financial services, forcing vendors to restructure channel economics and service delivery architectures.
Growth Catalysts
- EU AI Act compliance mandates:European financial institutions must overhaul data governance infrastructure, accelerating edge deployment investments and automated policy enforcement systems.
- Industrial automation clusters in Germany:Manufacturing concentration around Stuttgart and Munich is driving private 5G network buildouts and low-latency edge computing procurement.
- Containerized network functions:Kubernetes-orchestrated network services are replacing monolithic appliances, enabling horizontal scaling and DevOps integration for enterprise IT teams.
Market Restraints
- Semiconductor supply concentration:Advanced networking silicon fabrication concentrates in Taiwan, creating single-source vulnerability for merchant switch and router vendors.
- GDPR data localization requirements:Cross-border data flow restrictions complicate multi-tenant cloud architectures and increase compliance overhead for global enterprises.
- Optical component input volatility:Rare earth processing bottlenecks in China affect coherent optics pricing and availability for long-haul transmission upgrades.
Strategic Opportunities
- India's smart city infrastructure:Municipal digital transformation programs under the Ministry of Housing and Urban Affairs are creating demand for integrated fiber and edge compute deployments.
- AI-driven predictive operations:Convergence of machine learning inference at the network edge with real-time telemetry streams enables autonomous remediation and new managed service revenue pools.
- Open RAN policy incentives:FCC spectrum auction conditions and O-RAN Alliance certification pathways are accelerating disaggregated radio access network procurement by tier-two carriers.
Industry Challenges
- Intent-based networking skill scarcity:Enterprise IT organizations lack personnel proficient in Python-based network automation and YANG data modeling for programmable infrastructure.
- Multi-vendor interoperability certification:ETSI NFV and 3GPP Release 17 compliance testing extends product launch timelines and strains engineering resources.
- Brownfield integration complexity:Legacy MPLS and TDM infrastructure in incumbent telcos resists seamless migration to SD-WAN overlays without service disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Network Transformation Market |
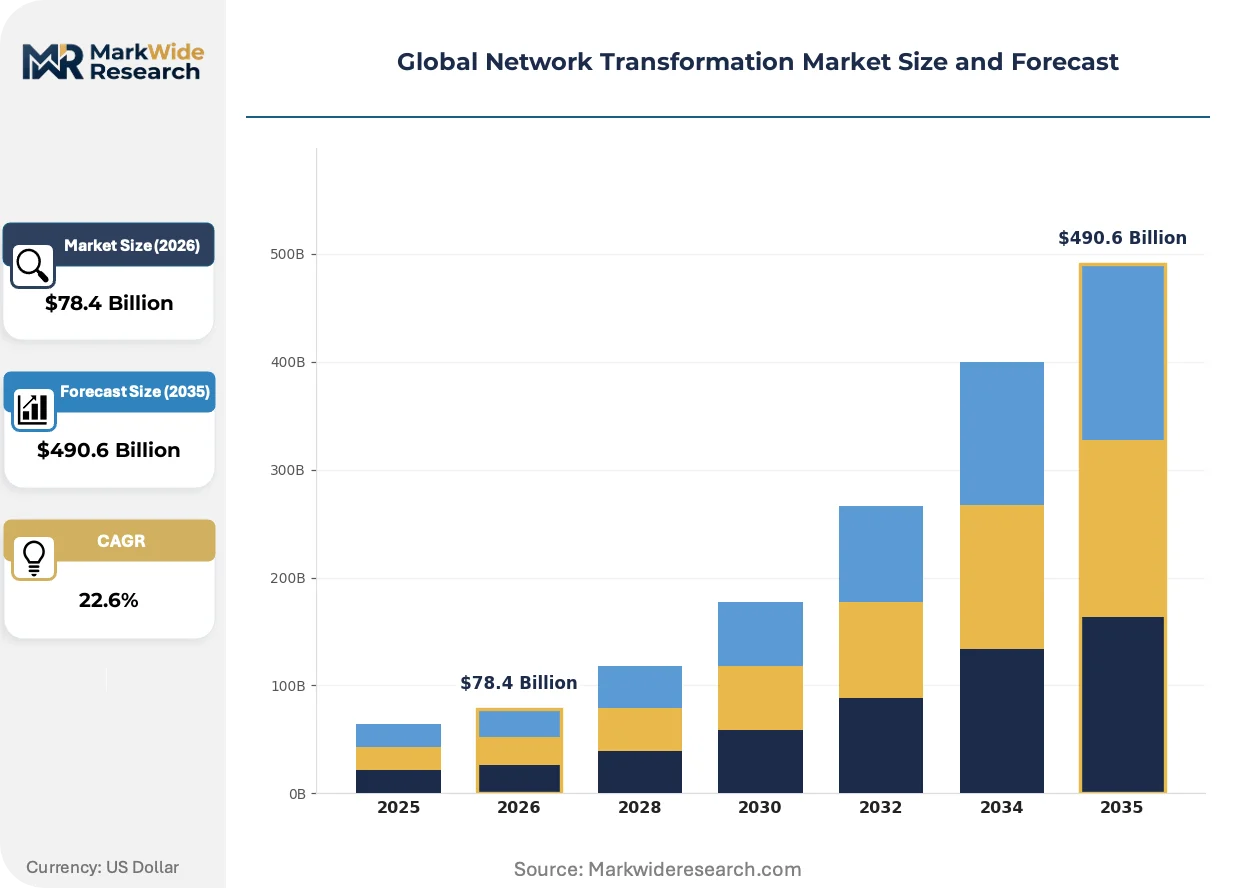
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $490.6 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Native, On-Premises, Hybrid, Edge Technology: Software-Defined Networking, Network Function Virtualization, 5G, AI-Driven Automation, SD-WAN Use Case: Data Center Modernization, IoT Connectivity, Enhanced Security, Enterprise Network Optimization, Content Delivery Networks Industry Vertical: Telecommunications, Financial Services, Manufacturing, Government, Education |
| Companies Covered | Cisco Systems, Juniper Networks, Hewlett Packard Enterprise, Huawei Technologies, IBM, NEC Corporation, Intel Corporation, Ericsson, Fujitsu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Network Transformation Market Shifts & Advancements
Artificial intelligence is penetrating network operations layers, converting reactive troubleshooting into predictive systems that anticipate failure modes before service degradation occurs.
Intent-based networking software is automating policy translation across heterogeneous infrastructure estates. Large financial services institutions in Singapore and London are deploying these systems to compress provisioning intervals from weeks to minutes. The technology is automating compliance verification against regulatory frameworks, reducing audit preparation overhead for GDPR and PCI-DSS requirements.
ETSI zero-touch network and service management specifications are mandating autonomous lifecycle operations for 5G core deployments. European operators must implement closed-loop automation to satisfy certification requirements for network slicing services. German industrial users of private 5G networks are prioritizing vendors with demonstrated ZSM compliance to minimize operational staffing.
Consumption-based licensing for network functions is displacing perpetual appliance purchases in mid-market enterprise segments. Managed security service providers in the United States are bundling SASE components into per-seat subscriptions, capturing customers who previously bought firewalls and WAN optimization hardware outright. This shift concentrates purchasing authority with CFOs and procurement functions rather than network engineering teams.
Global Network Transformation Market Segmentation
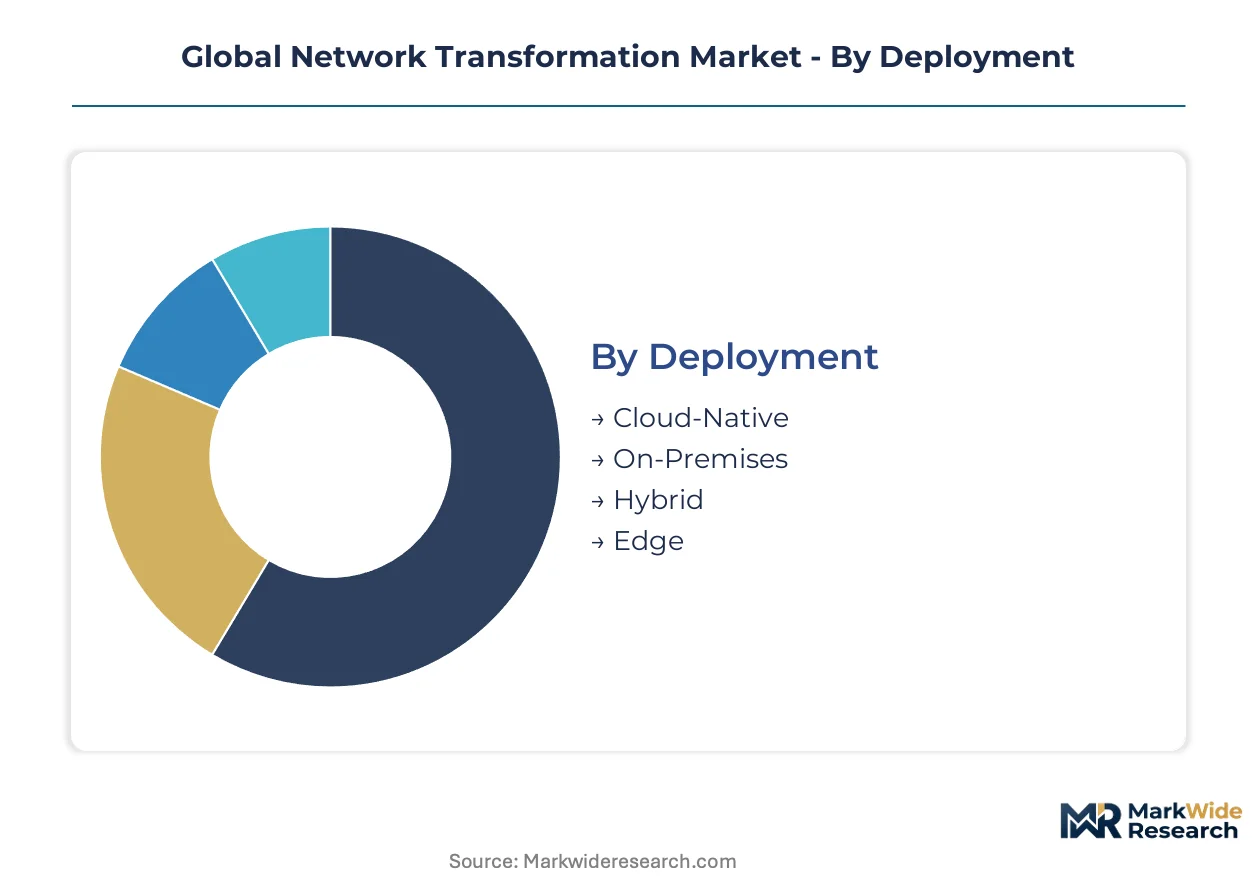
Network transformation procurement varies sharply by deployment model, technology stack, and regulatory exposure. Buyers prioritize latency thresholds, compliance architectures, and brownfield integration complexity when segmenting vendor evaluations.
Deployment:
Capital intensity and data sovereignty requirements drive deployment model selection across enterprise segments.
- Cloud-Native:Containerized network functions orchestrated through Kubernetes enable horizontal scaling and DevOps integration. Financial services institutions in Singapore and London are prioritizing this model to compress provisioning intervals and automate GDPR compliance verification.
- Hybrid:Split architectures maintain sensitive workloads on-premises while bursting traffic to public cloud fabrics. German automotive manufacturers around Stuttgart favor hybrid deployments to satisfy both production latency requirements and IT governance mandates.
- On-Premises:Dedicated hardware appliances persist in regulated environments requiring physical audit trails and air-gapped security zones.
- Edge:Distributed compute nodes positioned within 50 milliseconds of endpoints support industrial automation and real-time inference workloads.
Cloud-Native leads on scale; Edge leads on momentum.
Technology:
Technology selection hinges on existing infrastructure maturity and staff automation proficiency.
- AI-Driven Automation:Machine learning inference layered onto telemetry streams converts reactive troubleshooting into predictive operations. Large financial services deployments in London are compressing mean-time-to-resolution through autonomous remediation capabilities.
- Software-Defined Networking:Centralized control planes decouple traffic management from physical forwarding hardware. Telecommunications operators in India leverage SDN to provision smart city fiber infrastructure through programmatic interfaces.
- 5G:Radio access network virtualization enables network slicing for differentiated service tiers.
- Network Function Virtualization:Virtualized appliances replace proprietary hardware for routing, firewalling, and load balancing functions.
- SD-WAN:Overlay architectures aggregate multiple transport links with application-aware path selection.
Software-Defined Networking dominates installed base; AI-Driven Automation climbs the fastest.
Use Case:
Operational pain points and compliance deadlines shape use case prioritization within IT budgets.
- Enterprise Network Optimization:WAN consolidation and application performance management reduce operational overhead while supporting cloud migration timelines. Financial services procurement cycles are accelerating as institutions overhaul data governance infrastructure for EU AI Act compliance.
- Data Center Modernization:Spine-leaf architectures and intent-based networking automate policy translation across heterogeneous estates. Singaporean banks deploy these systems to reduce audit preparation overhead for PCI-DSS requirements.
- Enhanced Security:Zero-trust segmentation and SASE integration protect distributed workforces.
- IoT Connectivity:Massive device onboarding and protocol translation support industrial sensor deployments.
- Content Delivery Networks:Caching hierarchies and traffic optimization reduce origin load for media streaming.
Enterprise Network Optimization captures the largest addressable spend; Data Center Modernization shows the steepest expansion trajectory.
Industry Vertical:
Regulatory exposure and automation maturity create divergent buying behaviors across sectors.
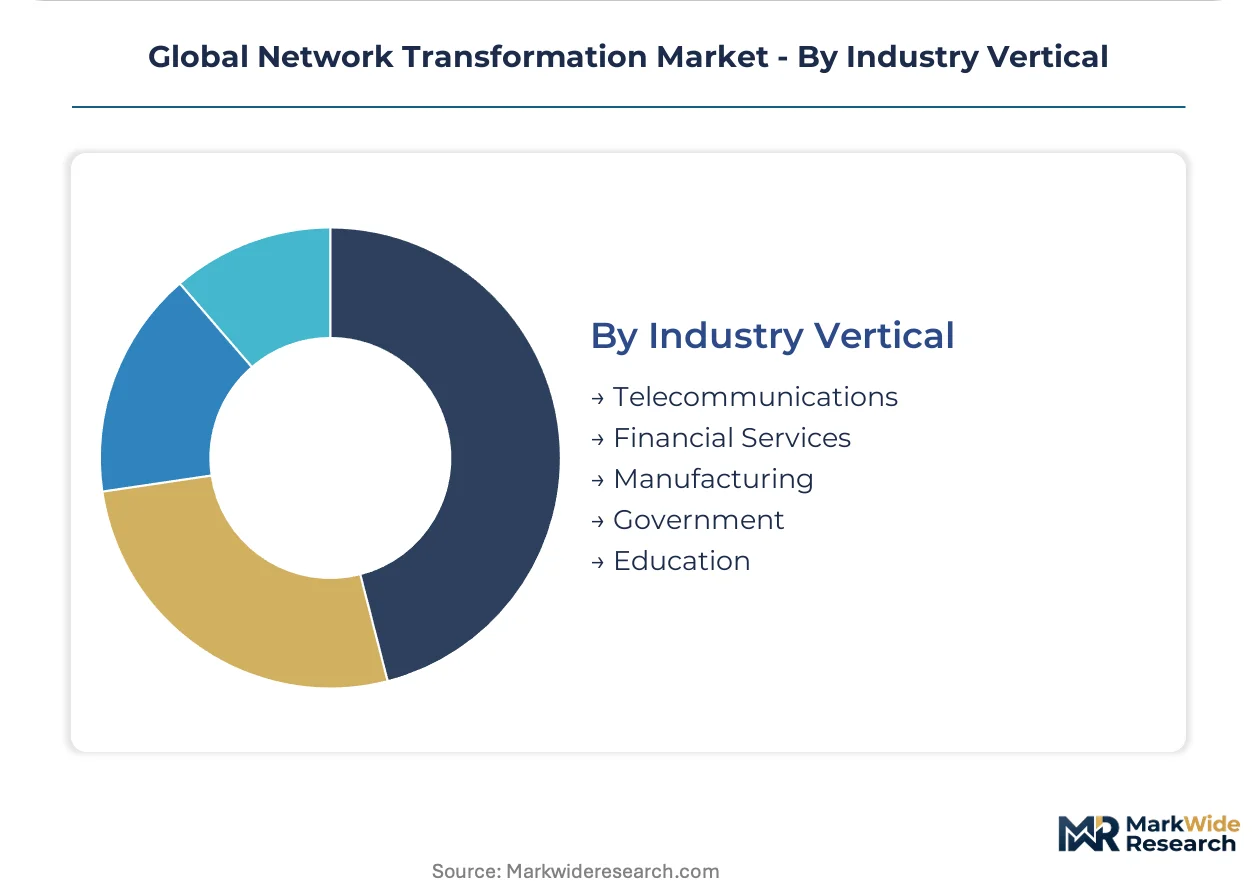
- Telecommunications:5G core buildouts and Open RAN disaggregation dominate capital allocation. FCC spectrum auction conditions are accelerating procurement by tier-two carriers seeking O-RAN Alliance certification pathways.
- Financial Services:GDPR data sovereignty requirements and EU AI Act mandates compel infrastructure overhauls. Edge deployment investments and automated policy enforcement systems are concentrating procurement authority with CFO functions.
- Manufacturing:Private 5G networks and low-latency edge computing support industrial automation clusters.
- Government:Municipal digital transformation programs create demand for integrated fiber and compute deployments.
- Education:Campus network refresh cycles prioritize cloud-managed Wi-Fi and security service edge bundles.
Telecommunications leads on absolute investment volume; Financial Services leads on compliance-driven urgency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial automation clusters outpace France in edge deployment velocity, while India's smart city programs generate procurement volumes rivaling mature European markets.
United States
FCC spectrum auction conditions and Open RAN policy incentives accelerate disaggregated radio access network procurement by tier-two carriers. Financial services institutions in New York and Chicago compress hardware refresh cycles under cloud-native procurement mandates. The SEC's cybersecurity disclosure rules compound infrastructure overhaul urgency for publicly traded enterprises.
Germany
EU AI Act compliance deadlines and GDPR data sovereignty requirements compel edge deployment investments across financial services. Manufacturing concentration around Stuttgart and Munich drives private 5G network buildouts for industrial automation clusters. ETSI zero-touch network management specifications mandate autonomous lifecycle operations for certified vendors.
India
Municipal digital transformation programs under the Ministry of Housing and Urban Affairs create demand for integrated fiber and edge compute deployments. TRAI's regulatory framework for data localization shapes multi-tenant cloud architecture decisions. Smart city infrastructure in Maharashtra and Karnataka concentrates procurement authority with state-level IT departments.
China
MIIT cybersecurity standards and dual carbon goals constrain cross-border market access while accelerating domestic 5G core buildouts. State-directed investment in Yangtze River Delta data centers prioritizes AI-driven network automation. Shenzhen and Beijing anchor merchant silicon development for switch and router vendors serving Asia-Pacific markets.
Singapore
Monetary Authority of Singapore operational resilience guidelines force financial institutions to overhaul data governance infrastructure. Containerized network functions orchestrated through Kubernetes enable horizontal scaling for regional banking headquarters. The city-state's submarine cable landing stations attract content delivery network investments from global streaming platforms.
Global Network Transformation Market Competitive Landscape
United States producers anchor one tier; Chinese specialists hold infrastructure deployment positions despite trade restrictions. Market structure concentrates around three strategic archetypes: legacy hardware incumbents with channel-intensive distribution, cloud-native challengers with DevOps-integrated delivery, and semiconductor vendors with captive silicon supply. Dominant competitive moves include portfolio diversification into AI-driven automation layers and strategic partnerships with hyperscale cloud operators.
Within the legacy infrastructure tier, Cisco Systems and Juniper Networks exemplify divergent specialization paths—one sustaining router dominance through extensive channel partnerships, the other concentrating AI-driven automation for data center modernization. Huawei Technologies occupies a distinct geographic position, anchoring 5G deployment across Asia-Pacific markets. These three vendors collectively represent the spectrum of competitive positioning: channel scale, technical specialization, and regional market capture.
| Leading Market Players |
|---|
| Cisco Systems |
| Juniper Networks |
| Hewlett Packard Enterprise |
| Huawei Technologies |
| IBM |
| NEC Corporation |
| Intel Corporation |
| Ericsson |
| Fujitsu |
| Others |
Supply & Pricing Matrix
Captive silicon integration among merchant switch and router vendors anchors both supply security and margin structure across network transformation procurement. Vendors with in-house semiconductor development command pricing power against competitors tethered to Taiwan foundry allocations, while FCC spectrum auction conditions in the United States and EU AI Act compliance deadlines in Europe concentrate buyer willingness-to-pay around certified, low-latency edge solutions.
Pricing Analysis
Capacity additions in China's Yangtze River Delta data center corridor are reshaping price floors for AI-driven network automation components. Three-tier pricing structure across premium, standard, and economy levels separates vendors with ETSI zero-touch certification from commodity SD-WAN providers. Cost compression in mid-market SD-WAN subscriptions is intensifying because hyperscale cloud operators bundle connectivity into compute contracts. Tier-two telecommunications carriers exhibit highest price sensitivity; financial services institutions in Singapore and London show lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
ETSI NFV certification and 3GPP Release 17 compliance testing gate market access for network function virtualization suppliers. Advanced networking silicon fabrication concentrates in Taiwan, South Korea, and the United States, while rare earth processing for coherent optics feeds from China. Single-source vulnerability in merchant switch ASICs creates supply chain risk for vendors without captive foundry relationships. Distribution runs through channel partners serving legacy refresh cycles and direct DevOps-integrated sales for cloud-native deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Network transformation functions as a stable compounder, with regulatory compliance mandates across the EU AI Act and GDPR generating recurring infrastructure overhaul demand that sustains vendor revenue visibility.
For Market Incumbents: Lock in channel control over legacy refresh cycles while accelerating AI-driven automation layer development to defend against cloud-native challengers. Prioritize ETSI zero-touch network management certification investments to satisfy German industrial automation procurement requirements. Vertical integration into merchant silicon design reduces Taiwan foundry dependency exposure. For New Entrants and Emerging Players: Mid-market manufacturing clusters in India's Maharashtra and Karnataka represent underserved buyer archetypes seeking private 5G network buildouts without incumbent telco complexity. Target municipal digital transformation programs under India's Ministry of Housing and Urban Affairs with integrated fiber-edge compute bundles. Deploy consumption-based licensing models to bypass capital budget approval friction. For Investors and Strategic Acquirers: Roll-up economics work for DevOps-integrated network automation specialists because enterprise IT organizations lack Python-based network automation and YANG data modeling proficiency. Platform consolidation across intent-based networking software vendors captures recurring managed service revenue pools. Watch Open RAN policy incentive acceleration at the FCC as inflection indicator for tier-two carrier procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Automation Layer Development | Predictive operations capabilities satisfy EU AI Act compliance mandates for European financial institutions. |
| ETSI Zero-Touch Certification Investment | Autonomous lifecycle operations certification unlocks German industrial automation cluster procurement. |
| Captive Silicon Supply Integration | In-house semiconductor development reduces Taiwan foundry concentration risk for merchant switch vendors. |
| DevOps-Integrated Delivery Model | Kubernetes-orchestrated network functions capture cloud-native procurement from containerized infrastructure buyers. |
| Open RAN Alliance Certification Pathway | O-RAN compliance enables tier-two carrier procurement under FCC spectrum auction incentive conditions. |
Research Methodology
Multiple input streams — executive interviews with network engineering directors, procurement officers at financial services institutions, channel partner principals, and telecommunications infrastructure planners — were reconciled against SEC filings, hyperscaler capex disclosures, ETSI specification documents, and 3GPP release databases. Bottom-up deployment model sizing and top-down vendor revenue triangulation validated segmentation splits across cloud-native, hybrid, on-premises, and edge architectures.
Data-stream reconciliation anchored the analytical framework across the projection horizon, modeling technology stack adoption curves, use case penetration by vertical, and regional regulatory cluster effects. CAGRs were derived from deployment velocity differentials and infrastructure refresh cycle compression patterns. Forecast inputs incorporated TRAI data localization framework impacts in India and MIIT cybersecurity standard evolution in China alongside spectrum auction timing in the United States.
Inputs from primary stakeholder interviews and secondary regulatory databases were available through the study window; gaps in real-time private 5G network deployment metrics introduce uncertainty bands around industrial automation cluster forecasts. Forecasts reflect documented assumptions regarding EU AI Act enforcement timing and semiconductor supply normalization trajectories. A model refresh is warranted upon material change in FCC Open RAN policy incentive structures or ETSI zero-touch certification mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
Digital Transformation Market
Digital Transformation
Automotive Digital Transformation Market
Digital Transformation
UAE Digital Transformation Market
Digital Transformation
SQL Server Transformation Market
Digital Transformation
UK Digital Transformation Market
Digital Transformation
Saudi Arabia Digital Transformation Market
Digital Transformation
APAC Digital Transformation Market
Digital Transformation
Canada Digital Transformation Market
Digital Transformation
Digital Platform Scale Market
Digital Transformation
Middle East Digital Transformation Market
Digital Transformation
Telco Transformation Market
Digital Transformation
Malaysia Digital Transformation Market
Digital Transformation
Europe Digital Transformation Market
Digital Transformation
Germany Digital Transformation Market
Digital Transformation
MENA Digital Transformation Market
Digital Transformation
Contact Center Transformation Market