
 Contact Center Transformation Market | 2026-2036
Contact Center Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
Contact Center Transformation Market Intelligence
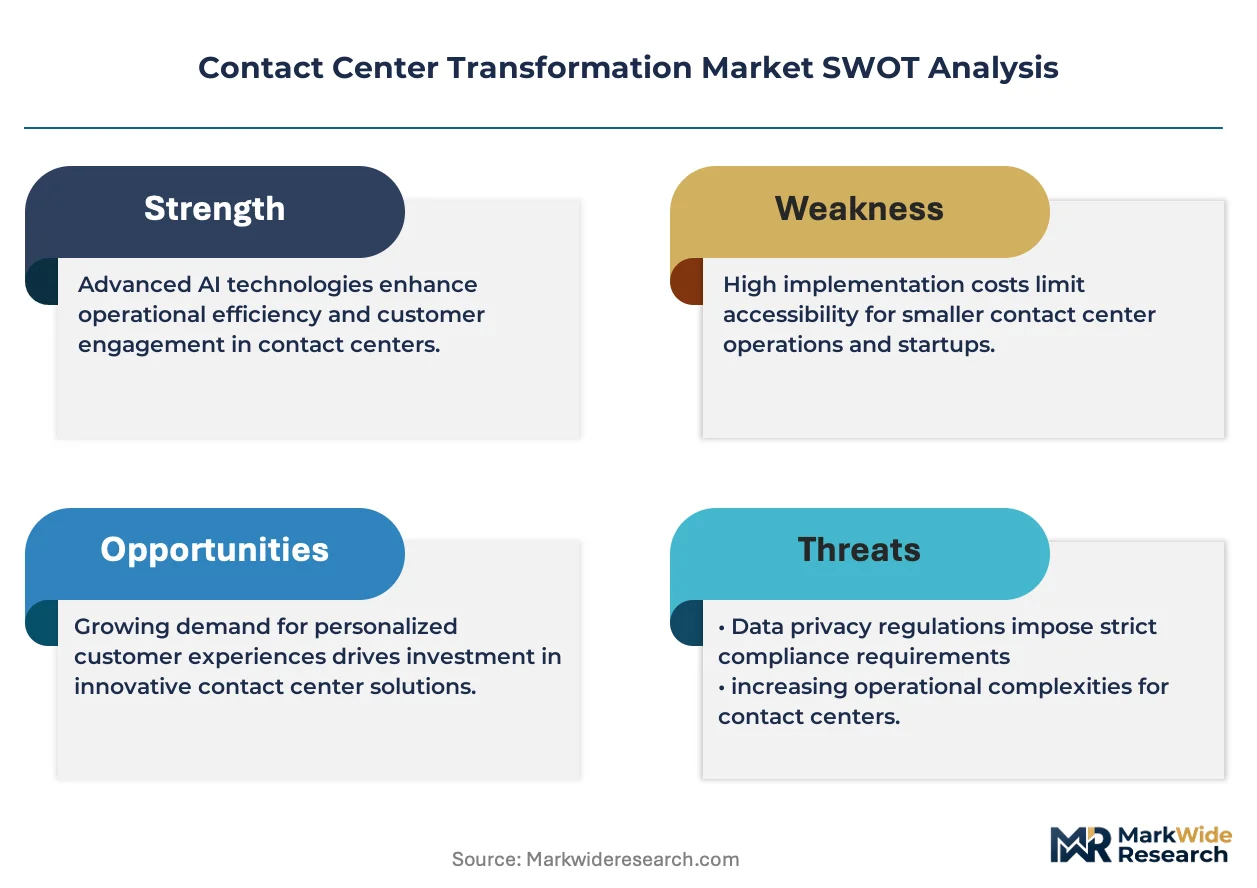
Enterprise buyer concentration is realigning as mid-market retailers and healthcare networks fragment across cloud-native platforms while Fortune 500 clients consolidate procurement with fewer full-stack vendors. NICE Systems Inc. leverages advanced analytics engines to anchor compliance-sensitive financial services deployments. Genesys Telecommunications Laboratories Inc. competes through omnichannel orchestration capabilities that span voice, digital, and asynchronous messaging channels. Five9 Inc. specializes in AI-infused workforce optimization tools that reduce agent attrition in high-volume operations.
Contact center transformation encompasses the architectural overhaul of customer engagement infrastructure through cloud migration, artificial intelligence integration, and channel unification, typically involving API-driven connectivity between CRM systems, telephony stacks, and real-time analytics layers. The primary purpose is to reduce cost-per-interaction while elevating customer satisfaction scores through predictive routing and sentiment-aware automation. Cloud deployment models now capture the dominant margin pool as enterprises abandon capital-intensive on-premises PBX estates for elastic consumption models. AI technology segments command premium pricing due to scarcity of trained conversational design talent and GPU inference costs. Omnichannel integration across voice, chat, and social messaging represents the fastest-growing capability investment as younger demographics reject voice-first resolution paths.
FCC regulations govern telemarketing consent and robocall mitigation in the United States, forcing vendors to embed real-time authentication and opt-out management into platform architectures. GDPR and the EU AI Act impose cross-border constraints on emotion recognition algorithms and biometric voiceprint storage, raising compliance costs for multinational deployments. HIPAA obligations in healthcare verticals mandate encrypted call recording with granular access auditing, shaping product roadmaps for Avaya Inc. and Cisco Systems Inc. Stakeholders must monitor evolving algorithmic accountability standards as regulatory fragmentation between Washington, Brussels, and Beijing threatens to Balkanize cloud contact center architectures.
Market Dynamics
Cloud-native architectures are compressing vendor consolidation cycles as enterprises abandon on-premises PBX estates for elastic consumption models, forcing incumbent telephony providers to restructure pricing and service delivery.
Growth Catalysts
- EU AI Act compliance mandates:Financial services institutions across Germany, France, and Italy are accelerating platform replacements to meet algorithmic transparency requirements for automated customer interactions.
- GPU inference cost reductions:Cloud providers are passing hardware efficiency gains to enterprise buyers, lowering barriers for real-time sentiment analysis and predictive routing deployments.
- Healthcare network consolidation:United States hospital systems are unifying patient engagement infrastructure under single-vendor contracts to satisfy HIPAA encrypted call recording obligations.
Market Restraints
- Scarce conversational AI talent:Trained dialogue designers command premium compensation, inflating implementation costs for natural language processing deployments.
- Telephony stack lock-in:Legacy circuit-switched infrastructure in Japanese and South Korean enterprises creates friction for API-driven CRM integration.
- Cross-border data sovereignty:China's data localization requirements fragment cloud architectures for multinational contact center operators.
Strategic Opportunities
- India's BPO modernization wave:Domestic IT services firms are replacing aging voice infrastructure with omnichannel platforms to capture higher-margin analytics contracts.
- Asynchronous messaging convergence:WhatsApp Business API and Apple Business Chat integration is opening new service channels for retail and hospitality verticals.
- Brazilian healthcare digitization:ANVISA telemedicine guidelines are mandating recorded consultation capabilities that drive contact center investment.
Industry Challenges
- Agent attrition in high-volume operations:Workforce optimization tools require six-month calibration periods before delivering measurable retention improvements.
- Biometric voiceprint litigation exposure:Illinois BIPA and Texas biometric privacy laws create class-action liability for platforms storing caller voice signatures.
- Legacy CRM API incompatibility:Decades-old customer databases in insurance and utilities sectors resist real-time data synchronization with modern routing engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contact Center Transformation Market |
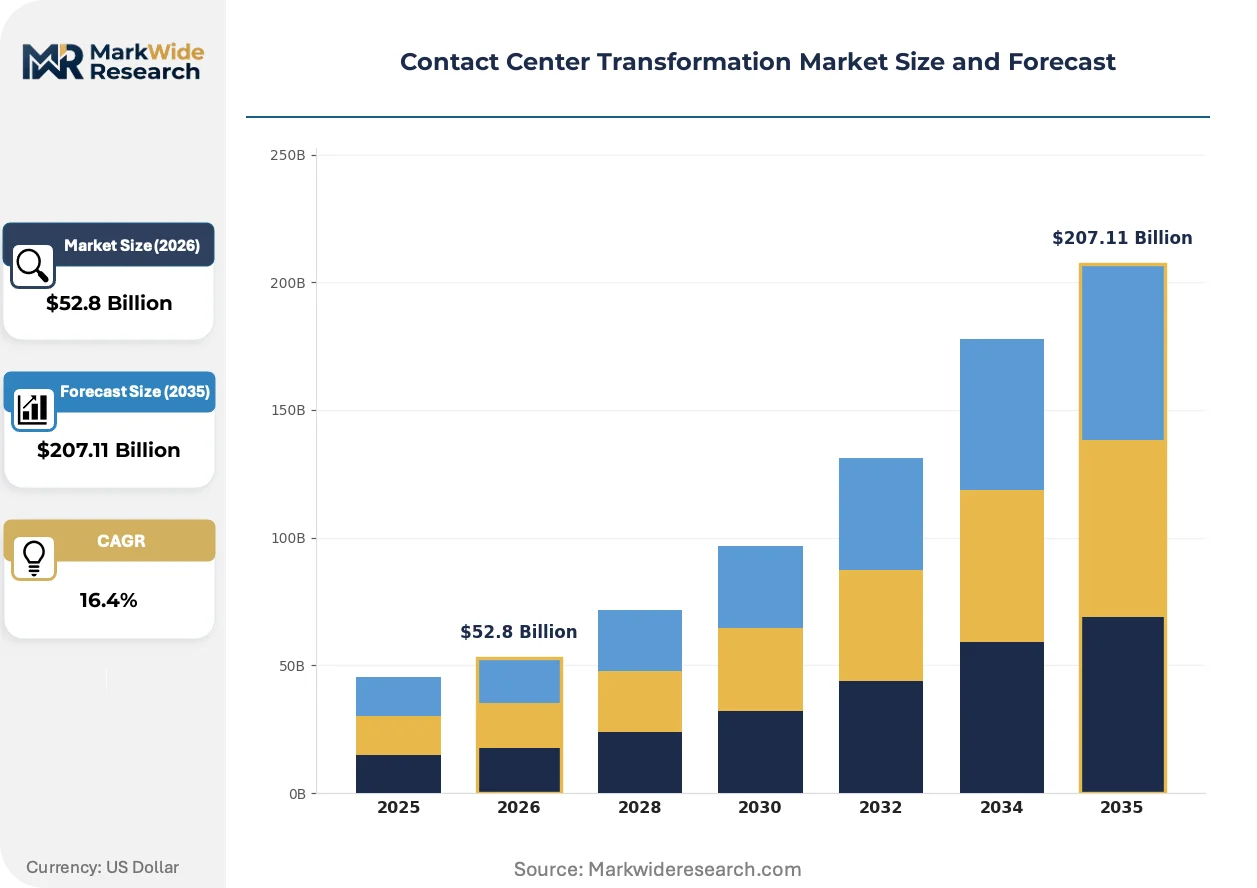
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $207.11 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: AI, Cloud, Omnichannel, VoIP Service Type: Consulting, Integration, Support, Managed Services End User: Telecommunications, Retail, Healthcare, Financial Services Deployment: On-premises, Cloud-based, Hybrid, Virtual |
| Companies Covered | Five9 Inc., Genesys Telecommunications Laboratories Inc., NICE Systems Inc., RingCentral Inc., 8x8 Inc., Avaya Inc., Enghouse Interactive Inc., Talkdesk, Cisco Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contact Center Transformation Market Strategic Shifts & Innovations
Real-time analytics layers are embedding directly into customer engagement workflows, compressing the gap between interaction capture and actionable intelligence. This architectural shift is redrawing competitive boundaries between pure-play software vendors and telecommunications carriers.
Large language models are converging with proprietary industry knowledge bases to enable domain-specific resolution without human escalation. Healthcare payers in the United States are deploying these systems for claims status inquiries, reducing average handle time by eliminating scripted menu navigation. The technology is converging with existing workforce management platforms to dynamically adjust staffing forecasts based on predicted conversation complexity.
The EU AI Act's emotion recognition prohibitions are forcing vendors to strip sentiment-scoring features from European deployments. Financial services contact centers in France and the Netherlands are replacing biometric authentication with behavioral analytics that comply with algorithmic accountability standards. Retail banks are responding by investing in agent-assisted co-pilot tools that preserve human oversight of customer-facing AI outputs.
Subscription-based platform economics are displacing perpetual license arrangements in mid-market buyer segments. United Kingdom insurance brokers and German automotive dealerships are negotiating consumption-aligned contracts that tie vendor fees to resolved interaction volumes. This reconfiguration is most visible in the United States, where private equity-backed contact center roll-ups are standardizing on single-stack cloud platforms to simplify vendor management and reduce integration overhead.
Contact Center Transformation Market Segmentation
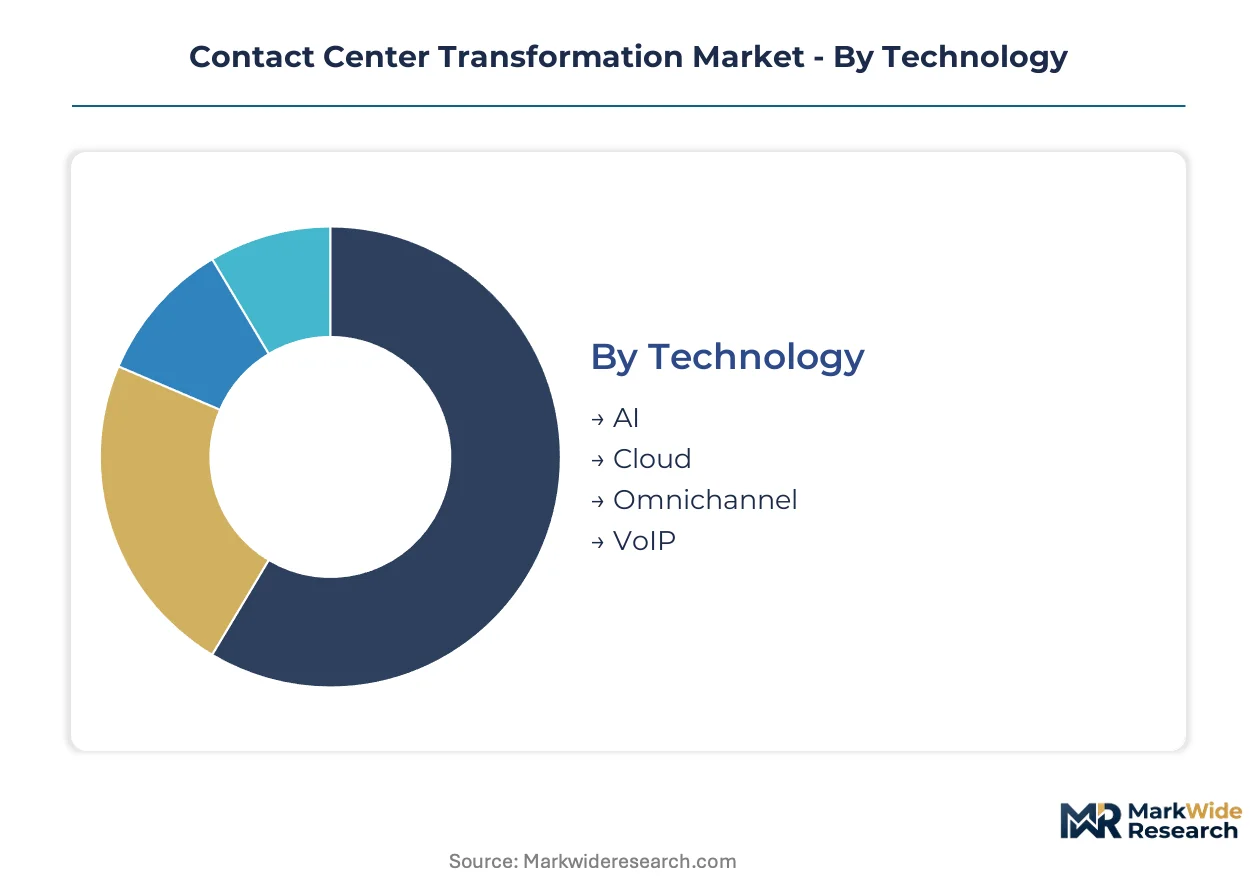
Technology architecture determines vendor selection criteria and procurement timelines across the contact center transformation landscape. Deployment models reshape margin structures while end-user verticals impose compliance-driven feature requirements.
Technology:
AI inference engines and cloud-native orchestration layers define competitive differentiation in platform procurement decisions.
- AI:Large language models power conversational automation for claims status and billing inquiries. United States healthcare payers deploy these systems to compress average handle time by eliminating scripted menu navigation. GPU cost reductions from cloud providers are accelerating enterprise adoption.
- Cloud:Elastic consumption models displace capital-intensive on-premises PBX estates. United States enterprise buyers dominate procurement volume as modernization budgets concentrate in North American operations.
- Omnichannel:Unified voice, chat, and social messaging orchestration. WhatsApp Business API integration opens service channels for retail and hospitality verticals seeking asynchronous resolution paths.
- VoIP:Packet-switched telephony infrastructure with API-driven CRM connectivity. Legacy circuit-switched estates in Japanese and South Korean enterprises create migration friction.
Cloud leads on scale; AI leads on momentum.
Service Type:
Professional services intensity varies by buyer maturity and legacy system complexity.
- Consulting:Strategic roadmap development for architectural overhaul and vendor selection. Financial services institutions across Germany, France, and Italy engage consultants for EU AI Act compliance alignment.
- Integration:API connectivity between CRM systems, telephony stacks, and analytics layers. Decades-old customer databases in insurance and utilities sectors resist real-time synchronization.
- Support:Ongoing technical maintenance and platform optimization. Mid-market retailers negotiate consumption-aligned contracts tying fees to resolved interaction volumes.
- Managed Services:Full operational outsourcing of contact center infrastructure. India's domestic IT services firms adopt these arrangements to capture higher-margin analytics contracts.
Integration commands the highest project value; managed services is climbing the fastest.
End User:
Vertical-specific compliance obligations shape platform feature roadmaps and certification requirements.
- Telecommunications:High-volume subscriber support with real-time authentication mandates. FCC robocall mitigation rules force embedded opt-out management.
- Retail:AI-powered self-service deployments across North American operations with seasonal demand elasticity requirements.
- Healthcare:HIPAA-encrypted call recording with granular access auditing. United States hospital systems unify patient engagement under single-vendor contracts.
- Financial Services:Algorithmic transparency requirements under EU AI Act. French and Dutch contact centers replace biometric authentication with behavioral analytics.
Financial services drives premium pricing; healthcare is expanding most quickly.
Deployment:
Infrastructure location determines data sovereignty exposure and capital commitment structure.
- On-premises:Captive hardware estates with full operational control. Japanese and South Korean enterprises maintain legacy investments resisting cloud migration.
- Cloud-based:Dominant margin pool as elastic consumption displaces perpetual licenses. Private equity-backed United States contact center roll-ups standardize on single-stack platforms.
- Hybrid:Split workloads across owned and leased infrastructure. Multinational operators deploy hybrid architectures to satisfy China's data localization requirements.
- Virtual:Software-defined infrastructure with geographic flexibility. Brazil's ANVISA telemedicine guidelines mandate recorded consultation capabilities.
Cloud-based leads on scale; hybrid is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States modernization budgets dwarf German compliance-driven replacements, while India's BPO sector races to capture analytics contracts from aging voice infrastructure. Cloud migration velocity varies sharply by regulatory environment and legacy system age.
United States
Enterprise contact center budgets concentrate in healthcare networks and private equity-backed roll-ups seeking single-stack standardization. FCC robocall mitigation rules mandate real-time authentication and embedded opt-out management in platform architectures. Texas and Florida host major healthcare payer operations deploying AI-infused workforce optimization tools.
Germany
Financial services institutions accelerate platform replacements to satisfy EU AI Act algorithmic transparency requirements for automated customer interactions. BaFin supervisory guidance shapes procurement criteria for sentiment-scoring and biometric authentication features. Frankfurt's banking cluster drives premium consulting engagements for compliance-aligned architectural roadmaps.
India
Domestic IT services firms replace aging voice infrastructure with omnichannel platforms to capture higher-margin analytics contracts from multinational clients. TRAI regulations govern telemarketing consent frameworks for outbound operations. Bengaluru and Hyderabad anchor delivery centers specializing in cloud-native workforce management deployments.
Brazil
Healthcare digitization accelerates as ANVISA telemedicine guidelines mandate recorded consultation capabilities driving contact center investment. Domestic hospital systems unify patient engagement infrastructure under vendor contracts with encrypted archiving features. São Paulo's private hospital networks lead procurement of virtual deployment models for geographic flexibility.
Japan
Legacy circuit-switched infrastructure in major enterprises creates sustained friction for API-driven CRM integration and cloud migration. METI industrial policy encourages gradual digital transformation rather than rip-and-replace approaches. Tokyo-based financial institutions maintain hybrid architectures splitting workloads across owned and leased infrastructure.
Contact Center Transformation Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered procurement segments. Cloud-native architectures compress vendor consolidation cycles as elastic consumption models displace perpetual licenses. Three archetypes dominate: full-stack platform vendors, AI-specialized workforce optimization providers, and telecommunications carriers with bundled service offerings. M&A activity concentrates among private equity-backed roll-ups standardizing on single-vendor stacks, while strategic partnerships proliferate between cloud hyperscalers and vertical specialists.
Within the full-stack platform tier, Genesys Telecommunications Laboratories Inc., NICE Systems Inc., and Five9 Inc. exemplify contrasting strategic positioning. The California-based Genesys entity occupies a position emphasizing omnichannel orchestration breadth, while the Israeli-registered NICE Systems Inc. anchors compliance-sensitive financial services deployments through analytics engines. Five9 Inc., a Delaware corporation, represents the AI-infused workforce optimization archetype targeting high-volume operations with attrition-reduction tooling.
| Leading Market Players |
|---|
| Five9 Inc. |
| Genesys Telecommunications Laboratories Inc. |
| NICE Systems Inc. |
| RingCentral Inc. |
| 8x8 Inc. |
| Avaya Inc. |
| Enghouse Interactive Inc. |
| Talkdesk |
| Cisco Systems Inc. |
| Others |
Cost & Logistics Intelligence
GPU cloud compute spot pricing indices cascade through contact center transformation vendor cost structures, compressing AI inference margins for platform providers while enabling consumption-based pricing tiers for enterprise buyers across North American and European deployments.
Pricing Analysis
Capacity additions in hyperscale cloud regions are reshaping price floors for AI-enabled contact center platforms. Subscription-based SaaS tiers dominate procurement, with price differentiation anchored in GPU inference allocation and HIPAA compliance certification levels. Pricing pressure stems from cloud provider hardware efficiency gains passing through to enterprise buyers. Mid-market retailers exhibit highest price sensitivity, while financial services institutions in Germany and France accept premium tiers for EU AI Act compliance features.
Supply Chain Analysis
Regional distribution centers for cloud infrastructure concentrate in the United States, Ireland, and Singapore, creating hub-and-spoke patterns for enterprise platform delivery. NVIDIA GPU supply and subsea fiber cable capacity constitute critical input dependencies. Single-source vulnerability in advanced AI chip fabrication from Taiwan Semiconductor Manufacturing Company creates supply chain risk. Distribution runs through direct hyperscaler marketplaces and value-added reseller networks serving vertical specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU AI Act compliance costs in Frankfurt and Paris run substantially above United States deployment economics, creating margin expansion opportunities for vendors with modular regulatory feature sets.
For Market Incumbents: Extend platform consolidation through embedded compliance engines that algorithmic transparency mandates in Germany, France, and Italy require. Acquire conversational AI design boutiques to address scarce dialogue talent threatening implementation timelines. Vertical integration into GPU inference infrastructure reduces cloud provider dependency and protects margins against hyperscaler pricing aggression. For New Entrants and Emerging Players: Begin with asynchronous messaging orchestration for Brazil's ANVISA-mandated telemedicine consultation recording, where incumbent platform penetration remains shallow. Target India's domestic IT services firms replacing aging voice infrastructure with omnichannel analytics platforms. Lead with WhatsApp Business API integration as the primary go-to-market wedge against full-stack incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with workforce optimization specialists possessing calibrated attrition-reduction algorithms for high-volume healthcare and retail operations. Long-term viability hinges on recurring revenue concentration and vertical-specific compliance certification depth. Monitor GPU cost curve inflection as the decisive signal for AI feature adoption acceleration versus platform commoditization.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies CRM, telephony, and analytics layers for FCC robocall compliance in United States healthcare networks. |
| Acquisition of Specialist Firm | Captures scarce conversational AI design talent pools in Bengaluru and Hyderabad delivery centers. |
| Geographic Expansion | Establishes EU AI Act-compliant deployment nodes in Frankfurt and Amsterdam for financial services procurement. |
| Strategic Partnership | Aligns with cloud hyperscalers to secure preferential GPU inference pricing for sentiment analysis features. |
| Product Launch | Introduces agent-assisted co-pilot tools preserving human oversight under French and Dutch algorithmic accountability standards. |
Research Approach
Direct dialogue with contact center operations directors, cloud procurement officers, conversational AI design leads, and HIPAA compliance auditors grounded qualitative findings, supplemented by FCC regulatory filings, EU AI Act implementation guidance, hyperscaler capex disclosures, and hospital system RFP databases. Bottom-up deployment volume estimates triangulated against top-down enterprise IT spending benchmarks.
Segmented outputs across cloud, AI, omnichannel, and VoIP technology architectures, consulting through managed services delivery models, and healthcare, financial services, retail, and telecommunications end-user verticals structured the analytical framework. CAGRs derived from elasticity-adjusted adoption curves incorporating GPU cost reduction trajectories and regulatory compliance deadline effects.
Several conditions sit outside the modeled scope, including geopolitical fragmentation of cloud architectures under China's data localization requirements and biometric voiceprint litigation exposure under Illinois BIPA. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
Telco Transformation Market
Digital Transformation
MENA Digital Transformation Market
Digital Transformation
Digital Transformation in Healthcare Market
Digital Transformation
Global Digital Workplace Transformation Service Market
Digital Transformation
Europe Digital Transformation Market
Digital Transformation
ASEAN Digital Transformation Market
Digital Transformation
UAE Digital Transformation Market
Digital Transformation
China Digital Transformation Market
Digital Transformation
Malaysia Digital Transformation Market
Digital Transformation
Colombia Digital Transformation Market
Digital Transformation
Automotive Digital Transformation Market
Digital Transformation
Qatar Digital Transformation Market
Digital Transformation
South East Asia Digital Transformation Market
Digital Transformation
Digital Platform Scale Market
Digital Transformation
Poland Digital Transformation Market
Digital Transformation
Spain Digital Transformation Market