
 UAE Digital Transformation Market | 2026-2036
UAE Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Digital Transformation Market Insights
Artificial intelligence silicon is hardening as the primary compute substrate replacing legacy x86 architectures in UAE enterprise data centers. Microsoft Corporation leverages its Azure sovereign cloud partnership with G42 Holding AI Cloud Computing Company L.L.C. to anchor hyperscale capacity inside the Emirates. Oracle Corporation sustains database-to-cloud migration pipelines through its Dubai-based engineering labs. Amazon Web Services, Inc. competes via its Bahrain-adjacent UAE region for latency-sensitive financial services workloads.
UAE Digital Transformation encompasses the migration of business processes, customer interfaces, and operational systems from analog or legacy digital formats to cloud-native, AI-augmented, and API-driven architectures, typically requiring multi-tenant infrastructure with sub-50 millisecond latency guarantees and ISO 27001-certified data residency. Its primary purpose is to reduce operational expenditure while enabling real-time decision automation across distributed workforces. Cloud Computing dominates current procurement volumes as the foundational layer, while Artificial Intelligence represents the fastest-expanding margin pool as sovereign AI factories attract federal R&D capital. Hybrid Cloud deployment models capture the largest share of enterprise tenders due to financial sector compliance requirements.
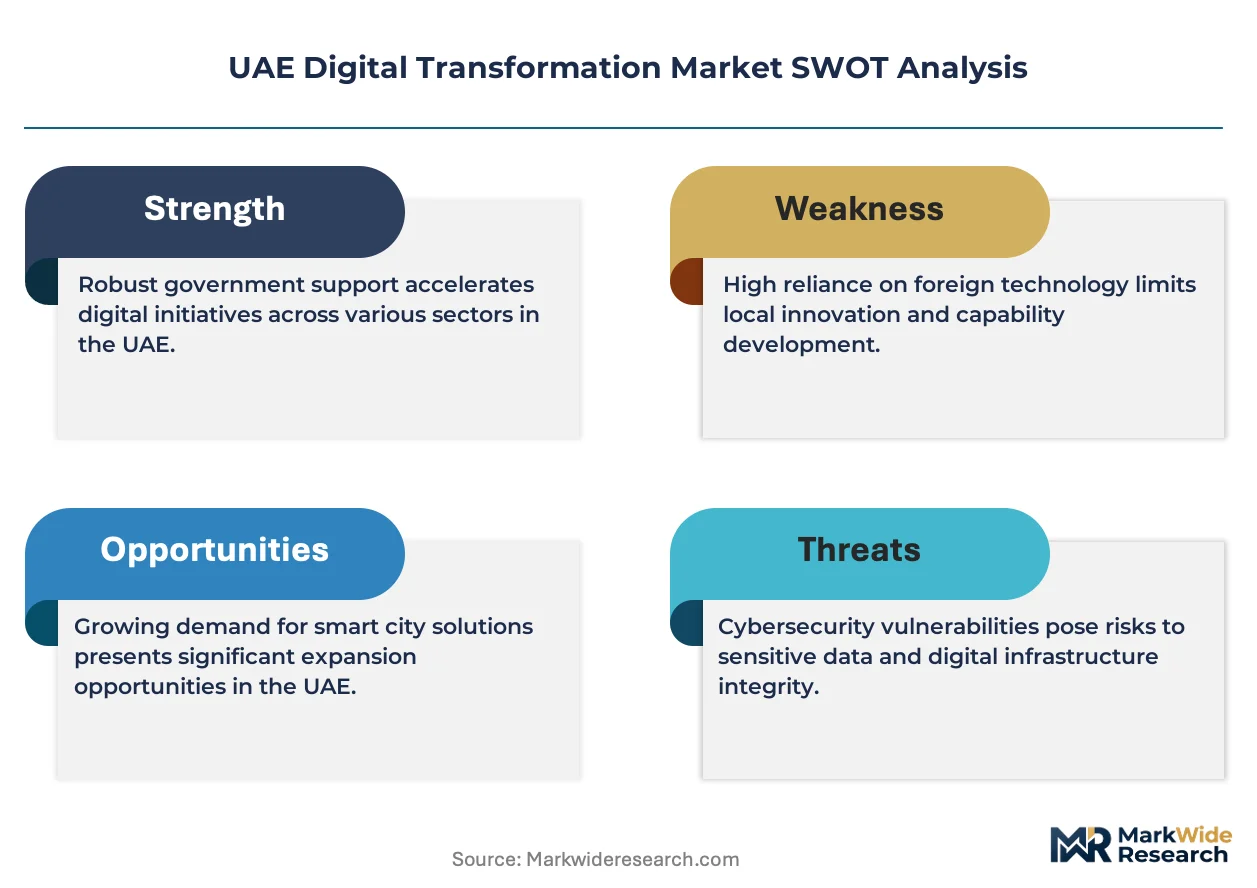
MOHAP and the UAE Central Bank jointly enforce health data localization and open-banking API standards that mandate on-shore infrastructure, directly shaping vendor qualification criteria. The National In-Country Value program and federal smart governance mandates redirect technology budgets toward domestic capability building. Stakeholders must monitor how Abu Dhabi's Advanced Technology Research Council reshapes procurement rules for sovereign AI training clusters.
Market Dynamics
Federal smart governance mandates and the National In-Country Value program are redirecting technology budgets toward domestic capability building, compressing procurement cycles for sovereign cloud infrastructure while elevating data residency requirements above cost considerations.
Growth Catalysts
- MOHAP Health Data Localization:Joint enforcement with the UAE Central Bank mandates on-shore infrastructure for health and financial data, directly expanding demand for ISO 27001-certified domestic data centers.
- Abu Dhabi AI-Dedicated Free Zones:Concentrated demand creation through sovereign cloud infrastructure attracts hyperscale investment and federal R&D capital allocation.
- Financial Services Open-Banking APIs:Real-time payment infrastructure requirements from the UAE Central Bank accelerate cloud-native platform procurement across retail and wholesale banking.
Market Restraints
- Specialized AI Silicon Supply Concentration:GPU and custom accelerator procurement depends on a narrow supplier base, exposing UAE data center operators to allocation delays and prioritization tiers.
- Dual-Use Technology Export Controls:US and EU restrictions on advanced semiconductor shipments create uncertainty for sovereign AI training cluster procurement timelines.
- Legacy System Integration Debt:Financial sector mainframe-to-cloud migration requires parallel runtime environments, inflating transitional operational expenditure before decommissioning.
Strategic Opportunities
- Ras Al Khaimah and Northern Emirates:Lower land and power costs create arbitrage for disaster recovery and tier-2 workload expansion outside Abu Dhabi-Dubai concentration.
- Edge Computing for Industrial IoT:ADNOC and Emirates Global Aluminium operational technology convergence with IT systems demands sub-10 millisecond latency infrastructure at refinery and smelter sites.
- Federal AI Procurement Framework:The Advanced Technology Research Council's sovereign AI training cluster specifications favor vendors with domestic engineering presence and Arabic large language model development capability.
Industry Challenges
- Cloud-Native Architecture Skills Scarcity:Kubernetes platform engineering and FinOps cost optimization expertise remains concentrated among contractors, inflating project delivery timelines for federal entities.
- Cross-Border Data Transfer Certification Complexity:Adequacy determinations with EU GDPR and emerging ASEAN frameworks require legal-technical dual expertise rarely available in single consultancies.
- Hybrid Cloud Operational Fragmentation:Split-stack management across on-premises VMware, Azure sovereign regions, and AWS Bahrain-adjacent zones multiplies monitoring and security policy orchestration overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Digital Transformation Market |
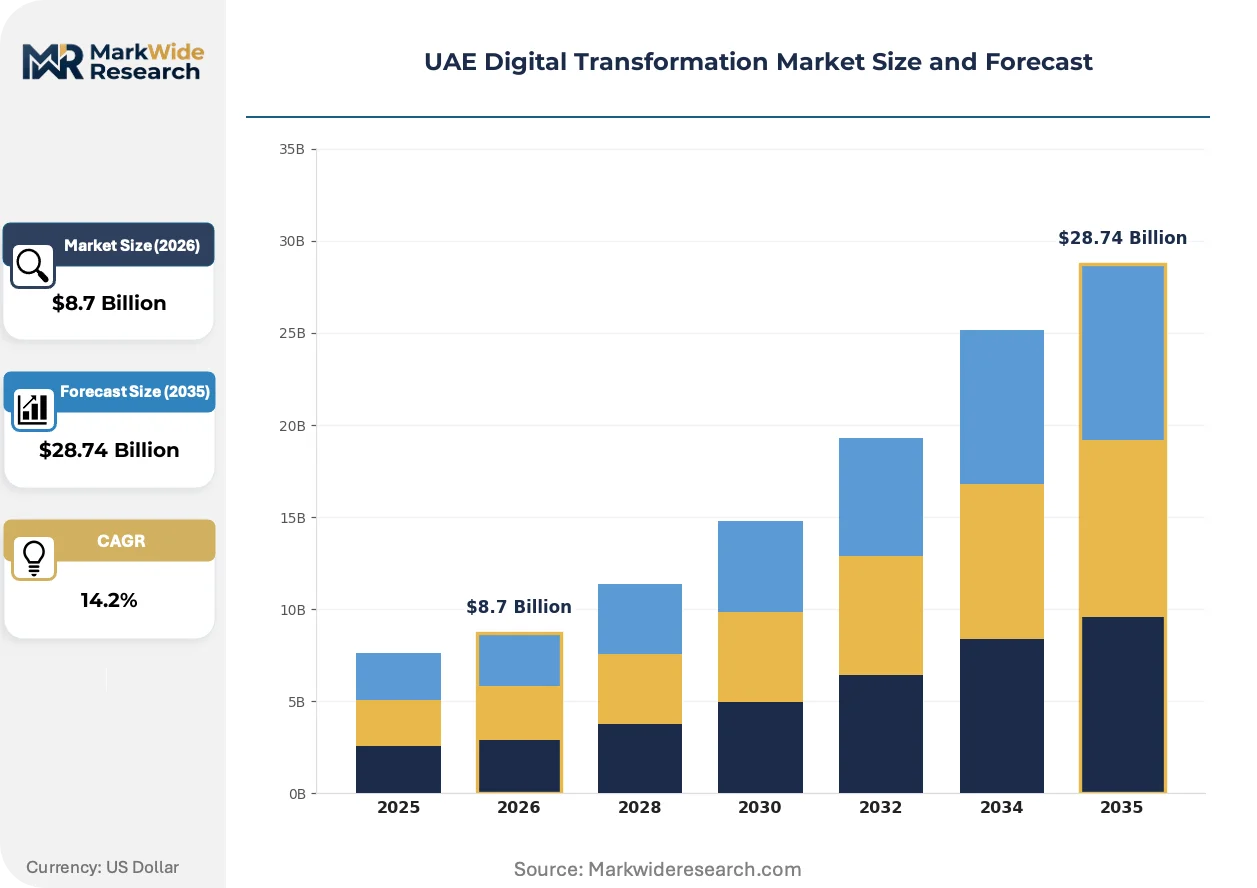
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud Computing, Artificial Intelligence, IoT, Blockchain Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Industry Vertical: Healthcare, Retail, Finance, Education End User: SMEs, Large Enterprises, Government, Non-Profit |
| Companies Covered | Microsoft Corporation, IBM Corporation, Oracle Corporation, G42 Holding AI Cloud Computing Company L.L.C., SquareOne Technologies, Accenture plc, Amazon Web Services, Inc., e& enterprise Holdings RSC L.L.C., Cisco Systems, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Digital Transformation Market Trends and Innovations
Compute substrate specialization and procurement model restructuring are compressing vendor qualification timelines while elevating sovereign data residency from compliance checkbox to architectural design principle across federal tenders.
Custom AI accelerators from Cerebras, SambaNova, and domestic G42 partnerships are electrifying training cluster procurement by delivering 10x throughput per watt against legacy x86-GPU combinations. ADNOC's subsurface imaging workloads and the Advanced Technology Research Council's Arabic foundation model initiatives are adopting these architectures within 18-month refresh cycles. This substrate shift is compressing hyperscaler negotiation leverage and fragmenting compute procurement across specialized silicon vendors.
MOHAP's health data localization enforcement, operational since 2023, now requires patient record systems to maintain primary data storage within UAE territorial boundaries with no failover to secondary regions outside federal jurisdiction. Hospital information system vendors must re-architect multi-tenant SaaS offerings to satisfy this mandate, disqualifying legacy global cloud deployments from public sector tenders. Private healthcare operators in Dubai Healthcare City are responding through sovereign cloud partnerships rather than self-managed infrastructure builds.
Subscription-based platform consumption with committed use discounts is displacing perpetual license and professional services bundles across federal and semi-government entities. Etisalat and du enterprise divisions are unbundling connectivity from cloud brokerage, creating standalone managed services units competing directly with hyperscale direct sales teams. This unbundling is most visible in Dubai's smart city infrastructure tenders, where network-agnostic cloud procurement now dominates RFP evaluation criteria.
UAE Digital Transformation Market Segmentation
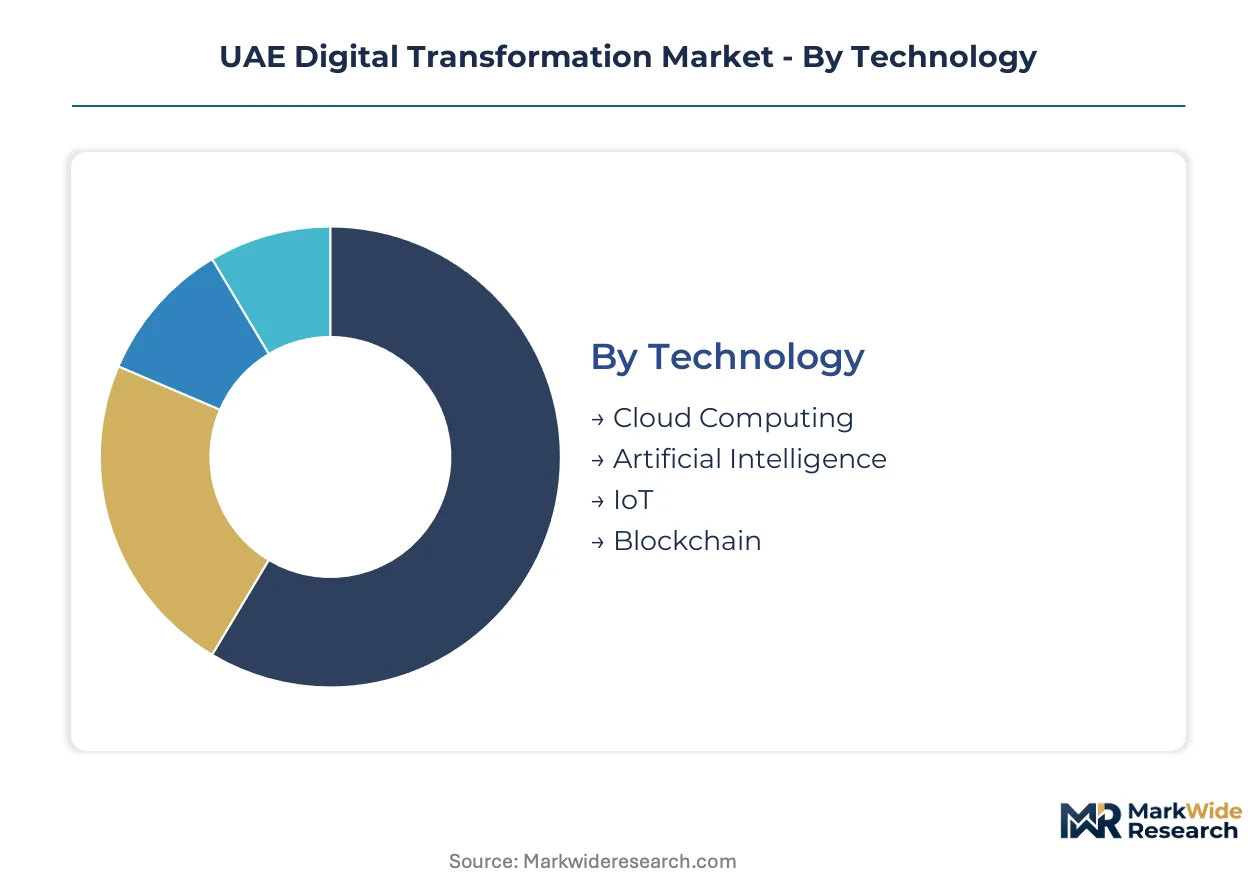
UAE Digital Transformation procurement patterns diverge sharply across integration depths. Standalone technology deployments dominate federal tenders, while embedded systems integration accelerates in industrial and financial verticals requiring real-time operational convergence.
Technology:
Cloud-native platforms anchor standalone infrastructure procurement, whereas AI and IoT segments increasingly embed within operational technology stacks across energy and manufacturing.
- Cloud Computing:Multi-tenant infrastructure with sub-50 millisecond latency guarantees and ISO 27001-certified data residency forms the foundational compute layer. Abu Dhabi sovereign cloud zones and Dubai Internet City hyperscale regions concentrate demand from federal entities and financial institutions facing MOHAP and Central Bank localization mandates.
- Artificial Intelligence:Sovereign AI training clusters with custom accelerator architectures from Cerebras and SambaNova displace legacy x86-GPU combinations. The Advanced Technology Research Council's Arabic foundation model initiatives and ADNOC subsurface imaging workloads drive procurement of 10x throughput-per-watt silicon within compressed refresh cycles.
- IoT:Industrial sensor networks and edge gateways embed within operational technology convergence projects.
- Blockchain:Distributed ledger platforms support trade finance and supply chain traceability applications.
Cloud Computing leads volumes today; Artificial Intelligence is gaining share fastest.
Deployment Model:
Cost tier stratification separates capex-intensive on-premises builds from opex-optimized consumption models, with compliance premiums reshaping mid-tier selections.
- Hybrid Cloud:Split-stack architectures spanning on-premises VMware, Azure sovereign regions, and AWS Bahrain-adjacent zones capture the largest tender share. Financial sector mainframe-to-cloud migration requirements and parallel runtime environments during transitional periods inflate operational expenditure before legacy decommissioning.
- Public Cloud:Subscription-based platform consumption with committed use discounts displaces perpetual license bundles across semi-government entities. Etisalat and du enterprise divisions unbundle connectivity from cloud brokerage, creating standalone managed services units competing with hyperscale direct sales.
- Private Cloud:Dedicated infrastructure satisfies health data localization and open-banking API standards.
- On-Premises:Self-managed data centers persist in defense and critical infrastructure sectors.
Hybrid Cloud dominates current procurement; Public Cloud exhibits the steepest expansion trajectory.
Industry Vertical:
Application-specific regulatory pressure and operational technology convergence dictate vertical selection priorities, with compliance-heavy sectors commanding premium infrastructure specifications.
- Finance:Real-time payment infrastructure and open-banking API standards from the UAE Central Bank accelerate cloud-native platform procurement. Retail and wholesale banking institutions mandate on-shore infrastructure with sub-50 millisecond latency for transaction processing and regulatory reporting.
- Healthcare:MOHAP enforcement since 2023 requires patient record systems to maintain primary data storage within UAE territorial boundaries. Hospital information system vendors re-architect multi-tenant SaaS offerings, disqualifying legacy global cloud deployments from public sector tenders.
- Retail:E-commerce platforms and omnichannel fulfillment drive demand for elastic compute.
- Education:Smart campus initiatives and remote learning infrastructure expand digital service delivery.
Finance leads vertical spending; Healthcare shows the most rapid policy-induced growth.
End User:
Customer type determines procurement channel access and contract structure complexity, with government tenders imposing domestic capability requirements that reshape vendor qualification.
- Government:Federal smart governance mandates and the National In-Country Value program redirect technology budgets toward domestic capability building. Sovereign cloud infrastructure procurement compresses vendor qualification timelines while elevating data residency above cost considerations in evaluation criteria.
- Large Enterprises:ADNOC and Emirates Global Aluminium operational technology convergence demands sub-10 millisecond latency infrastructure at refinery and smelter sites. Edge computing for industrial IoT creates specialized procurement outside Abu Dhabi-Dubai concentration zones.
- SMEs:Managed service consumption and bundled cloud brokerage lower barriers to platform adoption.
- Non-Profit:Grant-funded digital service delivery prioritizes cost optimization over performance specifications.
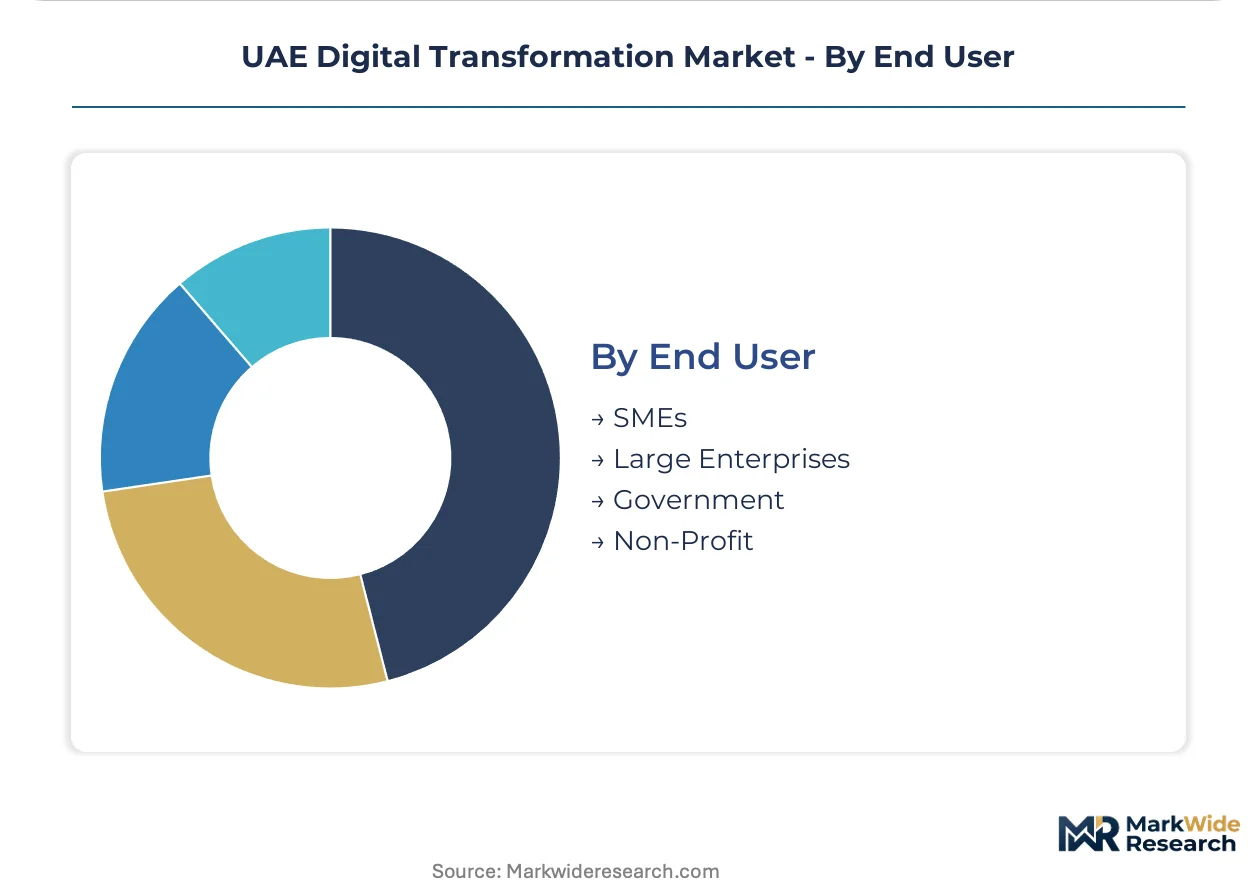
Government anchors procurement volumes; Large Enterprises are expanding fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai Internet City anchors procurement volumes as hyperscale cloud regions concentrate federal and financial sector demand. Abu Dhabi's sovereign AI zones redirect R&D capital toward domestic capability building.
Dubai
Smart city infrastructure tenders and network-agnostic cloud procurement dominate municipal technology budgets. MOHAP health data localization mandates require hospital information system vendors to re-architect multi-tenant SaaS offerings. Dubai Healthcare City operators pursue sovereign cloud partnerships rather than self-managed infrastructure builds.
Abu Dhabi
The Advanced Technology Research Council's sovereign AI training cluster specifications attract custom accelerator architectures from specialized silicon vendors. Federal smart governance mandates elevate data residency above cost considerations in procurement evaluation criteria. Masdar City and Khalifa Industrial Zone concentrate hyperscale data center investment.
Sharjah
Educational technology procurement accelerates through smart campus initiatives and remote learning infrastructure expansion. The emirate's national university system drives demand for elastic compute platforms. University City and Sharjah Research Technology and Innovation Park host domestic cloud brokerage services.
Northern Emirates
Ras Al Khaimah's lower land and power costs create arbitrage for disaster recovery and tier-2 workload expansion. Ajman and Fujairah industrial zones attract edge computing deployments for manufacturing operational technology convergence. Federal programs redirect technology budgets toward domestic capability building outside the Abu Dhabi-Dubai concentration.
UAE Digital Transformation Market Competitive Landscape
Global majors compete with regional champions across sovereign cloud infrastructure and AI accelerator procurement. Microsoft Corporation and Amazon Web Services anchor hyperscale capacity through dedicated UAE regions, while G42 Holding AI Cloud Computing Company L.L.C. exemplifies domestic capability building under National In-Country Value program mandates. Three archetypes dominate: hyperscale cloud operators with sovereign partnerships, domestic AI infrastructure specialists, and systems integrators managing hybrid cloud transitions. Competitive moves concentrate on strategic partnerships with federal entities and geographic expansion into Northern Emirates edge locations.
Within the hyperscale operator tier, Microsoft Corporation and Amazon Web Services occupy positions shaped by Azure sovereign cloud partnerships and Bahrain-adjacent latency optimization. Among domestic specialists, G42 Holding AI Cloud Computing Company L.L.C. exemplifies the AI infrastructure archetype through sovereign training cluster development. These three entities represent the competitive tension between global platform reach and federal mandates for domestic engineering presence.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Oracle Corporation |
| G42 Holding AI Cloud Computing Company L.L.C. |
| SquareOne Technologies |
| Accenture plc |
| Amazon Web Services, Inc. |
| e& enterprise Holdings RSC L.L.C. |
| Cisco Systems, Inc. |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed hyperscale operators and private-equity-rolled-up managed service providers anchor UAE digital infrastructure supply, translating federal localization mandates into pricing premiums for ISO 27001-certified domestic data centers while compressing margins on commodity cloud brokerage.
Pricing Analysis
Input-cost pass-through from specialized AI silicon procurement dominates pricing dynamics across sovereign cloud deployments. Subscription-based platform consumption with committed use discounts displaces perpetual license bundles, with three-tier pricing structure across premium sovereign-cloud, standard hybrid, and economy public-cloud levels. Price differentiation hinges on data residency certification tier and after-sales managed service bundling. Pricing pressure stems from GPU allocation delays and dual-use technology export controls tightening specialized accelerator supply. Federal government tenders exhibit lowest price sensitivity due to National In-Country Value program mandates, while SME segments drive hardest negotiation on connectivity-unbundled cloud brokerage.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from ADNOC and Emirates Global Aluminium for edge computing infrastructure, while systems integrators and cloud brokers serve mid-market procurement. Geographic supply concentration centers on Taiwan and South Korea for advanced GPU and custom AI accelerator fabrication, with USA-based Cerebras and SambaNova feeding sovereign training cluster demand. Raw material dependencies include high-bandwidth memory modules, specialized cooling systems, and subsea fiber optic cable capacity. Single-source vulnerability in advanced semiconductor lithography equipment creates procurement timeline uncertainty. Distribution runs through Etisalat and du enterprise divisions competing with hyperscale direct sales teams across federal and semi-government tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE Digital Transformation Market functions as a stable compounder anchored by irreversible federal mandates for sovereign data residency and domestic capability building under the National In-Country Value program.
For Market Incumbents: Hedge against custom AI accelerator vendor fragmentation by diversifying silicon partnerships beyond legacy x86-GPU combinations. Cultivate Arabic large language model development capabilities to meet Advanced Technology Research Council procurement specifications. Lock in long-term capacity reservations with Taiwan and South Korea foundries before allocation tiering hardens.
For New Entrants and Emerging Players: Systems integrators with Kubernetes platform engineering expertise represent the most penetrable channel into federal digital transformation tenders. Target Ras Al Khaimah and Northern Emirates for disaster recovery and tier-2 workload expansion where land and power costs create arbitrage. Pursue edge computing deployments at ADNOC refinery and Emirates Global Aluminium smelter sites demanding sub-10 millisecond latency infrastructure.
For Investors and Strategic Acquirers: Valuations sit cheapest among domestic cloud brokerage specialists unbundling connectivity from managed services. Long-term viability rests on federal smart governance mandate durability and sovereign AI factory R&D capital allocation continuity. Watch Advanced Technology Research Council procurement rule revisions for sovereign AI training clusters as the primary inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | Microsoft Azure's G42 alliance anchors hyperscale capacity inside UAE territorial boundaries. |
| Custom AI Accelerator Procurement | Cerebras and SambaNova deployments displace legacy x86-GPU combinations in ADNOC subsurface imaging. |
| Health Data Localization Compliance | MOHAP mandates force hospital information system vendors to re-architect multi-tenant SaaS offerings. |
| Edge Computing Infrastructure Buildout | Sub-10 millisecond latency deployments at refinery and smelter sites converge operational technology with IT. |
| Managed Services Unit Unbundling | Etisalat and du enterprise divisions create standalone cloud brokerage competing with hyperscale direct sales. |
Research Methodology
Multiple input streams — primary interviews with federal procurement officers and hyperscale cloud platform engineers, secondary validation through UAE Central Bank open-banking API documentation and MOHAP health data localization circulars, and customs data on specialized semiconductor imports — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged CTOs at semi-government entities, IT procurement officers at Dubai Healthcare City operators, integration specialists managing hybrid cloud transitions, and channel partners within Etisalat and du enterprise divisions. Secondary sources encompassed SEC filings from listed hyperscalers, Advanced Technology Research Council sovereign AI cluster specifications, and federal tender databases tracking National In-Country Value program compliance.
Data-stream reconciliation across deployment model, industry vertical, and end-user type dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level build-ups validated against aggregate market sizing. Modeled inputs included cloud-native platform procurement volumes from federal smart governance mandates, AI accelerator shipment schedules subject to dual-use export controls, and edge computing latency requirements from industrial operational technology convergence projects.
Revisions become necessary when dual-use technology export controls tighten, specialized AI silicon allocation tiers shift, or federal procurement rules for sovereign AI training clusters undergo restructuring. Forecasts reflect assumptions around National In-Country Value program continuity and health data localization enforcement durability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
Digital Transformation Market
Digital Transformation
Digital Platform Scale Market
Digital Transformation
China Digital Transformation Market
Digital Transformation
Qatar Digital Transformation Market
Digital Transformation
APAC Digital Transformation Market
Digital Transformation
Telco Transformation Market
Digital Transformation
Contact Center Transformation Market
Digital Transformation
SQL Server Transformation Market
Digital Transformation
Innovation Management Market
Digital Transformation
Saudi Arabia Digital Transformation Market
Digital Transformation
Global Design Thinking Market
Digital Transformation
Workspace Transformation Market
Digital Transformation
Netherlands Digital Transformation Market
Digital Transformation
Canada Digital Transformation Market
Digital Transformation
Retail Digital Transformation Market
Digital Transformation
Brazil Digital Transformation Market