
 Europe Digital Transformation Market | 2026-2036
Europe Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Digital Transformation Market Insights
Mid-sized manufacturers are unwinding decades of reliance on on-premises infrastructure and redirecting capital toward cloud-native architectures. Siemens AG leverages its industrial software stack to anchor factory-floor digitization across German automotive suppliers. Capgemini SE competes on systems-integration depth, while SAP SE sustains dominance in ERP-to-cloud migration pathways for European multinationals.
Digital transformation encompasses the integration of cloud computing, artificial intelligence, and Internet of Things technologies into core business processes to enable real-time data orchestration and automated decision-making. Cloud-based deployment is displacing legacy on-premises stacks as latency-sensitive workloads shift to edge nodes, while AI and Big Data Analytics capture the fastest expansion in solution-type spending. Manufacturing and BFSI verticals concentrate margin pools due to stringent compliance requirements and high transaction volumes.
The EU AI Act, GDPR, and CE marking frameworks collectively elevate data governance and algorithmic transparency to pre-qualification criteria for vendor selection. EMA guidelines on digital health records and ECHA chemical-tracking mandates extend compliance burdens into operational technology layers. Stakeholders must monitor regulatory divergence between EU harmonized standards and member-state implementation timelines when allocating platform development resources.
Market Dynamics
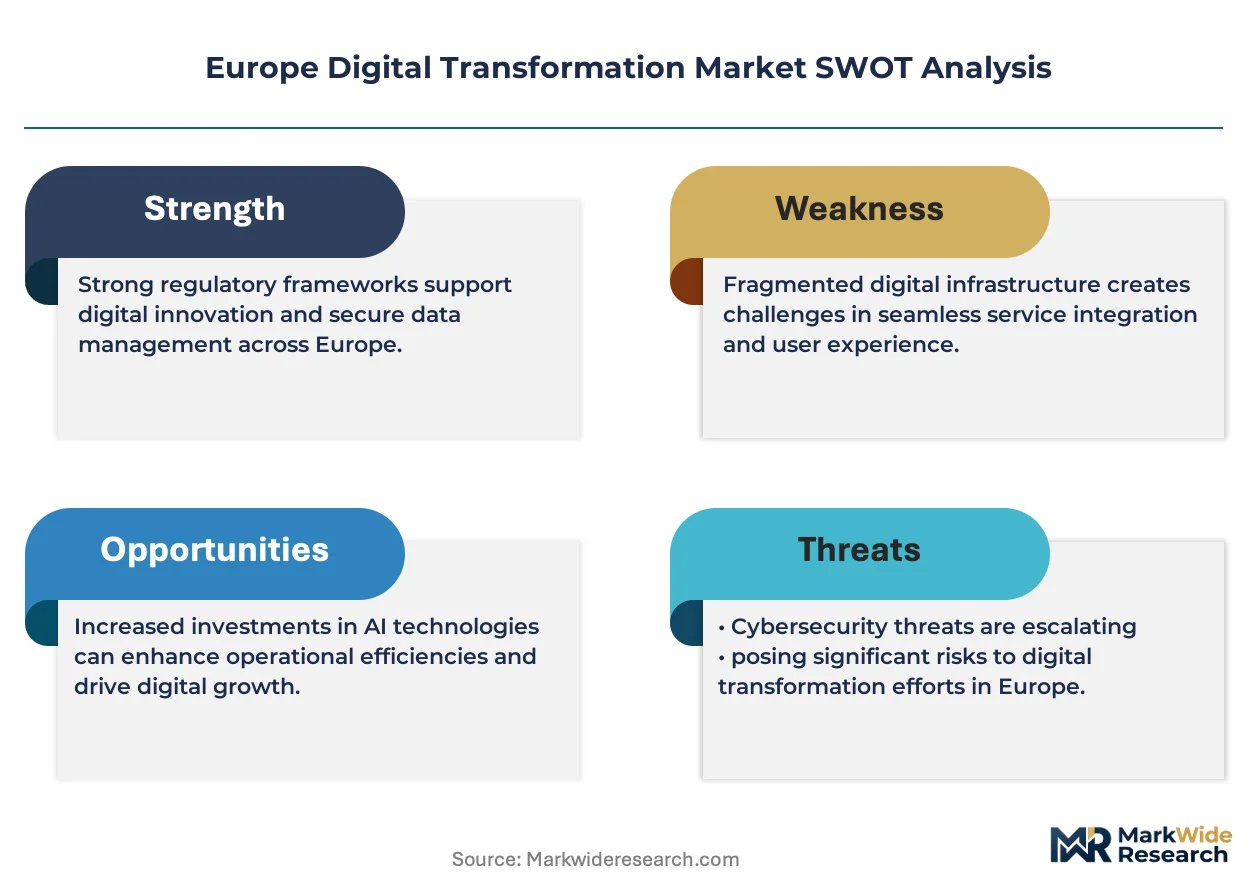
The EU AI Act and GDPR compliance deadlines are forcing European enterprises to re-architect data governance frameworks ahead of enforcement milestones, compressing procurement cycles for privacy-preserving infrastructure.
Growth Catalysts
- CE marking for digital health devices:EMA guidelines on digital health records mandate validated software systems, pulling investment into compliant operational technology platforms across pharmaceutical manufacturing.
- Industrial automation in German automotive:Smart factory investments by tier-one suppliers anchor regional cloud migration spending, with edge computing deployments accelerating quality-control digitization.
- EU Green Deal carbon-tracking mandates:ECHA chemical-tracking requirements extend digital thread investments into process industries, linking production data to sustainability reporting infrastructure.
Market Restraints
- Legacy system integration costs:Decades of on-premises ERP and MES investments in European manufacturing create technical debt that inflates total cost of ownership for cloud-native replacements.
- Cross-border data residency fragmentation:Divergent member-state implementations of GDPR adequacy decisions complicate multi-country platform deployments for multinationals.
- Specialized OT cybersecurity talent scarcity:Shortages of professionals certified in IEC 62443 standards limit execution velocity for critical infrastructure digitization programs.
Strategic Opportunities
- Polish and Romanian manufacturing clusters:Greenfield facility investments in Central European automotive and electronics assembly offer cloud-native deployment without legacy migration burdens.
- CSRD sustainability reporting convergence:The Corporate Sustainability Reporting Directive mandates granular emissions data collection, creating demand for integrated operational and financial data platforms.
- AI-IoT convergence at the edge:Federated learning architectures combined with industrial sensors enable predictive maintenance without raw data centralization, addressing GDPR localization requirements.
Industry Challenges
- Multi-framework compliance sequencing:Enterprises must synchronize EU AI Act algorithmic transparency documentation with existing ISO 27001 and IEC 62443 certification renewals.
- Operational technology cybersecurity retrofitting:Brownfield industrial sites lack network segmentation designed for zero-trust architectures, requiring physical infrastructure overhaul.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Digital Transformation Market |
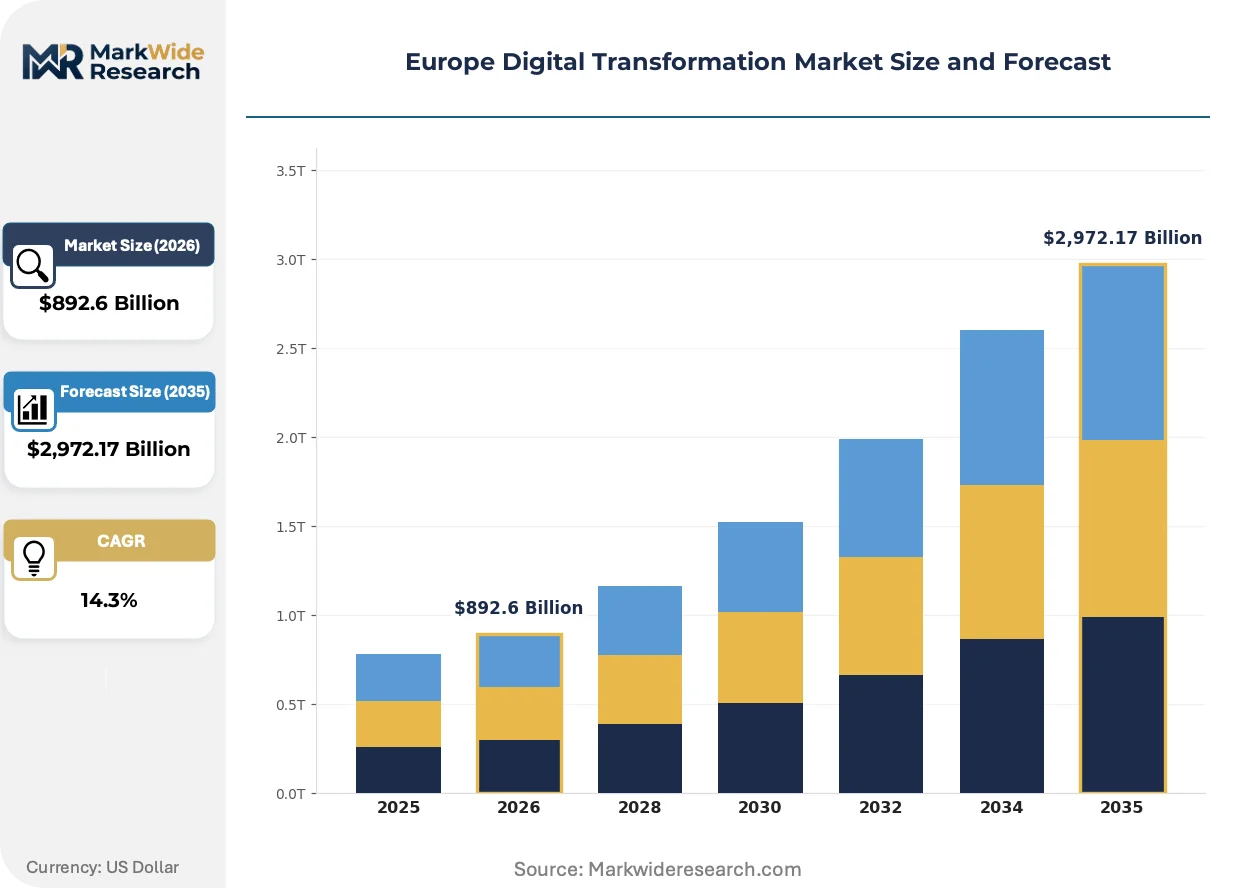
| Market Size in 2026 | $892.6 Billion |
| Market Size in 2035 | $2,972.17 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Industry Vertical: Retail, Healthcare, Manufacturing, BFSI Solution Type: AI, Big Data Analytics, IoT, RPA End User: SMEs, Large Enterprises, Public Sector, Non-Profits |
| Companies Covered | Atos SE, Microsoft Corporation, Accenture PLC, Siemens AG, Google LLC, SAP SE, IBM Corporation, Hewlett Packard Enterprise, Capgemini SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Digital Transformation Market Trends and Innovations
European industrial software is converging around edge-native architectures that process latency-sensitive workloads locally while maintaining centralized governance, reshaping how automation vendors package compute and analytics.
Edge AI inference engines are miniaturizing to run on resource-constrained programmable logic controllers. German automotive suppliers embed these modules directly into welding robots for real-time defect detection. The technology is miniaturizing hardware footprints while expanding inference capability, collapsing the distinction between control systems and analytics platforms.
GDPR Article 35 data protection impact assessments now precede any AI system procurement above defined risk thresholds. Industrial buyers demand pre-certified algorithmic transparency documentation from vendors. German machinery OEMs and French pharmaceutical manufacturers are most affected, inserting legal review stages that extend sales cycles by three to six months.
Subscription pricing for manufacturing software is displacing perpetual license models that dominated European industrial procurement for two decades. Buyers in the Benelux region and Nordic countries lead this transition, preferring operational expenditure treatment for digital transformation budgets. Automotive and process industry procurement teams now evaluate total cost of ownership over five-year horizons rather than upfront capital expenditure alone.
Europe Digital Transformation Market Segmentation
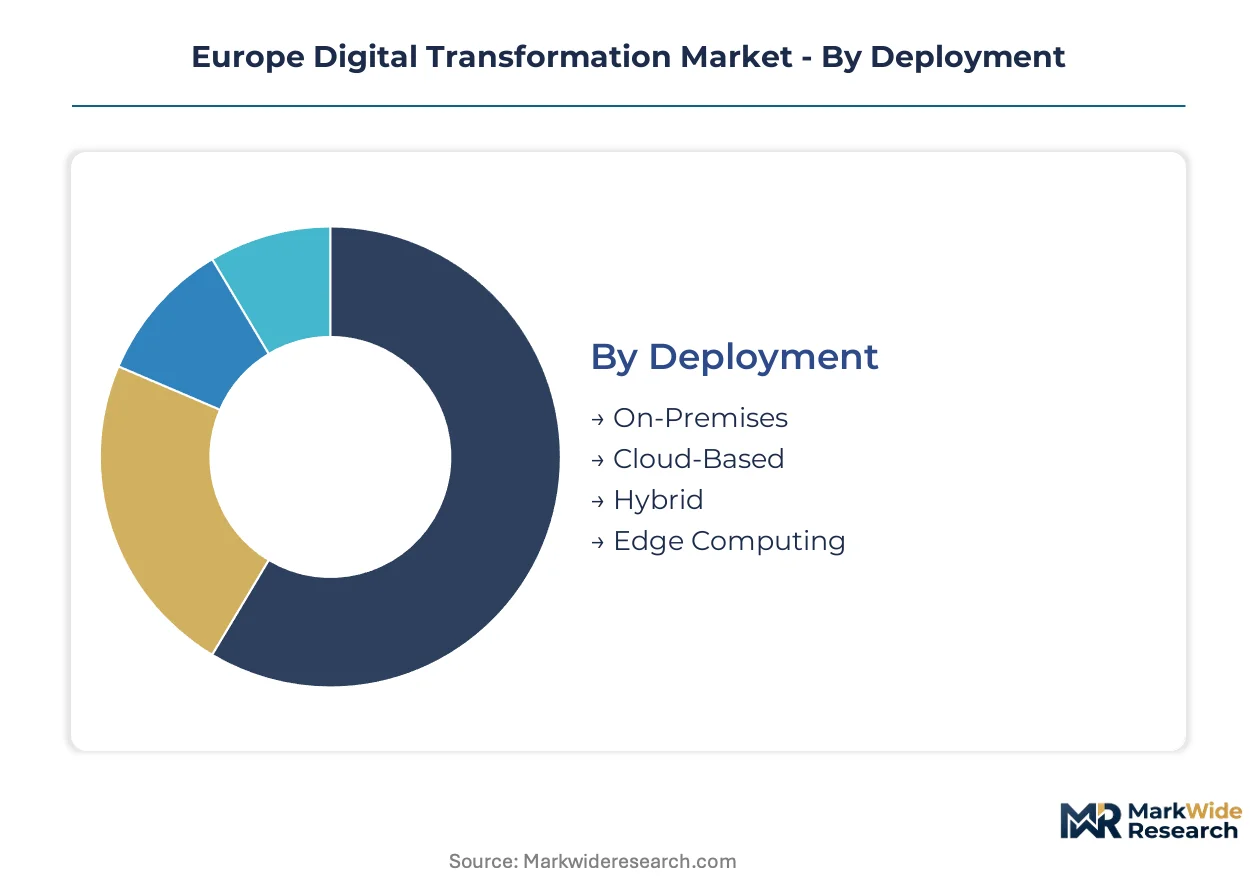
European enterprises structure digital transformation procurement around deployment risk tolerance, regulatory exposure, and legacy infrastructure position. Segment boundaries blur as hybrid architectures and edge-native solutions redraw traditional category lines.
Deployment:
German and French buyers dominate domestic cloud spending, while edge computing deployments cluster in export-intensive automotive corridors.
- On-Premises:Residual demand concentrates in defense-adjacent manufacturing and Swiss pharmaceutical facilities where data sovereignty requirements block external hosting. Basel and Stuttgart house the largest retained footprints.
- Cloud-Based:Public cloud consumption is displacing legacy stacks fastest in Nordic financial services and Dutch logistics, where GDPR adequacy rulings permit cross-border processing. AWS, Microsoft Azure, and Google Cloud partition the contract base.
- Hybrid:Split architectures accommodate workload-specific residency rules, with sensitive ERP cores on-premises and customer-facing applications in EU-sovereign cloud zones.
- Edge Computing:Real-time inference nodes localize AI processing for welding robotics and chemical process control, bypassing latency to centralized cloud.
Cloud-based deployment commands the established base. The steepest expansion runs through edge computing.
Industry Vertical:
Margin concentration follows regulatory intensity and transaction velocity, with manufacturing and BFSI capturing disproportionate platform investment.
- Manufacturing:German automotive suppliers and Italian machinery OEMs anchor smart factory spending, driven by CE marking requirements and EU Green Deal carbon-tracking mandates. Tier-one suppliers in Bavaria and Baden-Württemberg lead adoption.
- BFSI:GDPR Article 35 impact assessments and ECB operational resilience guidelines force continuous infrastructure refresh across Frankfurt, London, and Luxembourg banking clusters.
- Healthcare:EMA digital health record validation pulls investment into compliant software systems, with hospital networks in France and Germany consolidating procurement.
- Retail:Omnichannel fulfillment platforms concentrate in Benelux distribution hubs serving cross-border e-commerce.
Manufacturing holds the revenue concentration. Healthcare is climbing the fastest as EMA deadlines compress procurement cycles.
Solution Type:
AI and IoT solutions command premium pricing in industrial settings, while RPA spreads horizontally across cost-conscious administrative functions.
- AI:Machine learning platforms for predictive maintenance and quality control concentrate in German automotive and French aerospace supply chains. EU AI Act documentation requirements extend sales cycles.
- IoT:Sensor networks and digital thread infrastructure link production data to CSRD sustainability reporting, with ECHA chemical-tracking mandates driving process industry adoption.
- Big Data Analytics:Unified data lakes consolidate operational and financial reporting for Corporate Sustainability Reporting Directive compliance.
- RPA:Robotic process automation targets back-office consolidation in insurance and public administration, where labor cost arbitrage drives business case viability.
IoT anchors the installed base. AI is gaining share fastest as algorithmic transparency frameworks mature.
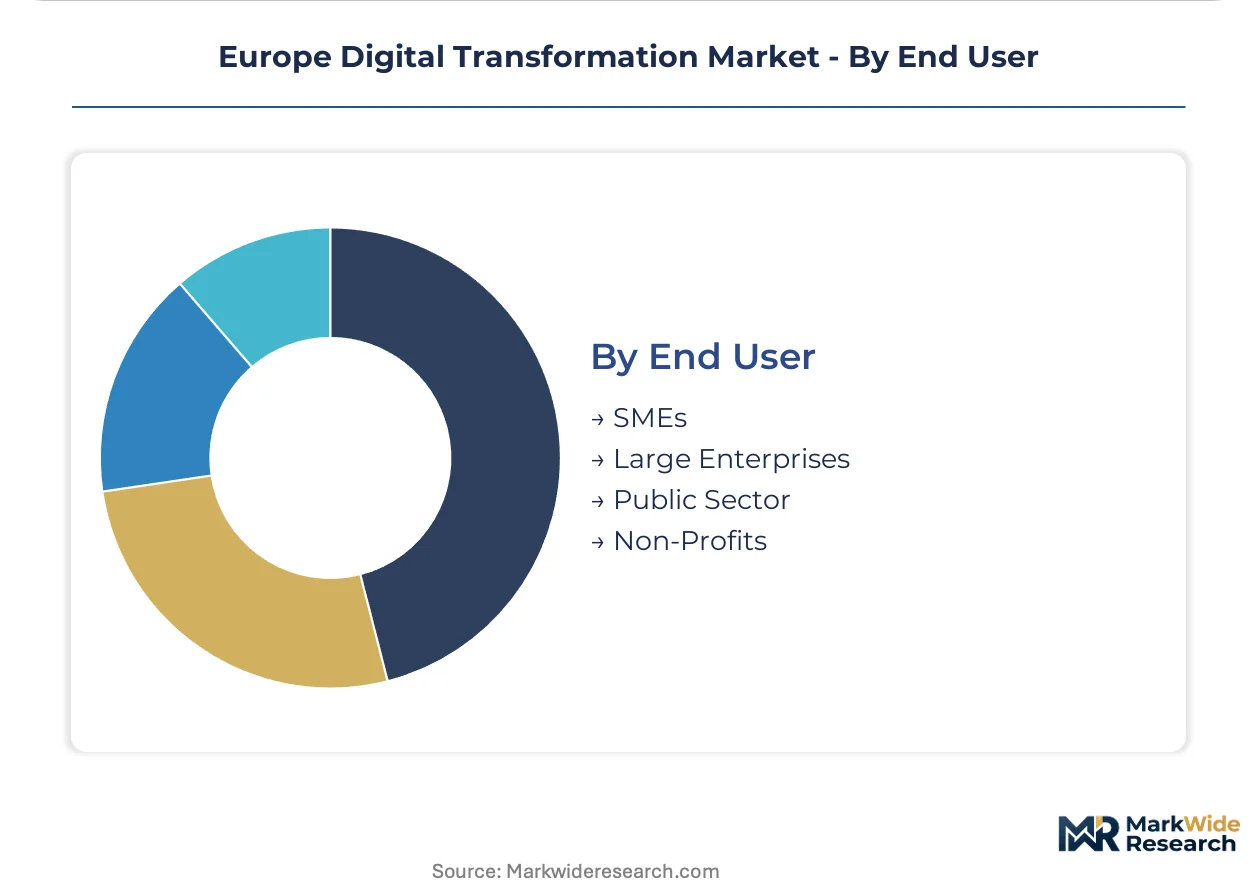
End User:
Large enterprises dominate absolute spending, but SME aggregators and public sector frameworks reshape procurement economics.
- Large Enterprises:Multinationals headquartered in Germany, France, and the Netherlands drive complex multi-country rollouts, absorbing compliance burdens that exclude smaller competitors.
- SMEs:Mid-sized manufacturers in Poland and Romania deploy cloud-native architectures without legacy migration costs, leveraging greenfield facility investments.
- Public Sector:National healthcare systems and municipal utilities in Scandinavia and Germany consolidate demand through framework agreements, privileging vendors with pre-certified data governance.
- Non-Profits:Research institutions and NGOs access subsidized cloud credits through EU digital sovereignty programs, though absolute contract values remain limited.
Large enterprises command the established base. SMEs represent the steepest expansion trajectory as subscription pricing democratizes access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive suppliers export digital manufacturing solutions to tier-one production networks across France, Italy, and Poland. This trade corridor channels cloud-native architectures and edge computing infrastructure into Central and Eastern European assembly plants.
Germany
Industrial automation and smart factory investments anchor regional adoption, with Bavarian automotive clusters driving edge computing deployments for real-time quality control. The EU AI Act and GDPR compliance requirements reshape procurement priorities for data governance platforms. Stuttgart and Munich house concentrated demand from tier-one suppliers modernizing legacy MES systems.
France
Pharmaceutical manufacturers and aerospace supply chains generate concentrated demand for compliant operational technology platforms. EMA guidelines on digital health records mandate validated software systems, pulling investment into regulated infrastructure. Île-de-France and Auvergne-Rhône-Alpes clusters lead CSRD sustainability reporting convergence for integrated data platforms.
United Kingdom
Financial services and insurance verticals force continuous infrastructure refresh under ECB operational resilience guidelines and GDPR Article 35 impact assessments. London banking clusters drive cloud migration spending for privacy-preserving architectures. The Southeast and Midlands concentrate procurement for hybrid deployment models.
Netherlands
Logistics and omnichannel fulfillment platforms concentrate in Benelux distribution hubs serving cross-border e-commerce. Dutch buyers lead subscription pricing transitions for manufacturing software, preferring operational expenditure treatment. Randstad logistics corridors anchor demand for real-time inventory orchestration systems.
Poland
Greenfield facility investments in Central European automotive and electronics assembly offer cloud-native deployment without legacy migration burdens. Polish manufacturing clusters absorb German-exported digital infrastructure for new capacity expansion. Warsaw and Kraków metropolitan areas concentrate SME aggregator demand through framework agreements.
Europe Digital Transformation Market Competitive Landscape
Player mix skews toward systems integrators and industrial software specialists competing on compliance depth and legacy modernization velocity. Market structure concentrates around three strategic tiers: cloud hyperscalers providing infrastructure foundations, European systems integrators delivering regulatory expertise, and industrial software vendors anchoring factory-floor digitization. Dominant competitive moves include strategic partnerships between cloud providers and compliance specialists, plus portfolio diversification into edge-native architectures.
Within the European systems integrator tier, Capgemini SE and Atos SE exemplify players competing on GDPR and EU AI Act documentation depth. Siemens AG anchors the industrial software vector for German automotive supplier modernization. Microsoft Corporation and Google LLC occupy positions as cloud infrastructure providers adapting sovereign cloud offerings for EU data residency requirements.
| Leading Market Players |
|---|
| Atos SE |
| Microsoft Corporation |
| Accenture PLC |
| Siemens AG |
| Google LLC |
| SAP SE |
| IBM Corporation |
| Hewlett Packard Enterprise |
| Capgemini SE |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud capacity utilization above eighty percent in Frankfurt and Amsterdam zones compresses marginal compute costs, concentrating pricing power among infrastructure providers while compressing price floors for mid-tier systems integrators competing on implementation services.
Pricing Analysis
Legacy perpetual-license pricing for on-premises ERP systems commands three-to-five-year depreciation cycles, while cloud-native subscription tiers for manufacturing software stratify across premium sovereign-cloud, standard multi-tenant, and economy shared-infrastructure levels. Price differentiation hinges on GDPR Article 35 pre-certification documentation depth and ISO 27001 renewal status. Cost compression in standard-tier SaaS is intensifying because Polish and Romanian greenfield buyers negotiate volume discounts without legacy migration overhead. SME procurement teams in Central Europe exhibit highest price sensitivity; German tier-one automotive suppliers demonstrate lowest sensitivity due to compliance-driven vendor stickiness.
Supply Chain Analysis
Just-in-time provisioning of edge computing hardware dominates German automotive corridors, while strategic stockpiling of EU-sovereign cloud capacity reserves concentrates in French pharmaceutical clusters anticipating EMA validation deadlines. Component supply draws from Taiwan for AI inference accelerators, Ireland for data center infrastructure, and Germany for industrial edge gateways. Supply chain risk centers on single-source vulnerability for specialized IEC 62443-certified cybersecurity talent. Distribution runs through systems integrator-led channel partnerships in the DACH region and direct hyperscaler relationships in Nordic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated automotive OEM procurement hubs and national healthcare framework agreements, fragmenting vendor access and compressing margins for undifferentiated implementation services.
For Market Incumbents: Compound compliance documentation depth into renewal pricing power by embedding EU AI Act algorithmic transparency modules into existing SAP and Siemens deployments. Defend against emerging Polish systems integrators by pre-certifying edge-native architectures for ECHA chemical-tracking mandates. Priority lever: vertical integration of IEC 62443 cybersecurity training academies to address talent scarcity. For New Entrants and Emerging Players: CE marking fast-track services for digital health devices open immediate white-space in French pharmaceutical manufacturing, where EMA validation timelines extend incumbent sales cycles. Target Polish SME manufacturing clusters through cloud-native MES deployments without legacy migration burdens. Go-to-market angle: subscription pricing with embedded GDPR Article 35 impact assessment tooling. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors edge-AI inference specialists with pre-certified EU sovereign-cloud deployments. Long-term viability rests on federated learning architectures that localize processing for GDPR compliance without raw data centralization. Acquisition target archetype: industrial software vendors with embedded sustainability reporting modules for CSRD convergence. Signal to watch: divergence between member-state GDPR adequacy rulings that fragments multi-country platform economics.| Strategic Initiative | Industry Significance |
|---|---|
| EU Sovereign Cloud Certification | GDPR Article 44 data residency requirements privilege Frankfurt and Amsterdam zone deployments for German automotive suppliers. |
| Edge-Native Architecture Launch | Real-time welding defect detection modules embedded in Bavarian robotic systems collapse latency to centralized cloud. |
| IEC 62443 Cybersecurity Partnership | Talent scarcity in operational technology security limits execution velocity for critical infrastructure digitization programs. |
| CSRD Sustainability Platform Integration | ECHA chemical-tracking mandates link production data to emissions reporting for EU Green Deal compliance. |
| AI Act Algorithmic Transparency Documentation | Pre-certified impact assessments extend sales cycles but lock out competitors without legal review capabilities. |
Research Methodology
A spread of perspectives from cloud infrastructure procurement officers, industrial automation engineers, GDPR compliance leads, and systems integration specialists converged on the working assumptions driving segment-level demand estimates. Primary fieldwork combined structured interviews with secondary validation against SEC filings from hyperscalers, EMA guideline releases, EU AI Act implementation timelines, and customs data on industrial software imports. Bottom-up deployment forecasts triangulated against top-down IT spending surveys from European manufacturing associations.
Segmentation dimensions modeled span deployment architecture, industry vertical regulatory intensity, solution type integration complexity, and end-user scale tier across the projection horizon. CAGRs were derived from weighted scenario analysis incorporating compliance deadline acceleration, cloud migration velocity by country, and edge computing adoption curves in automotive corridors. Industry-specific inputs included EMA digital health record validation timelines and German automotive supplier smart factory investment cycles.
The analysis sits within stated boundaries; outcomes outside synchronized EU AI Act and GDPR enforcement milestones would require recalibration. Forecasts reflect assumptions on regulatory harmonization, hyperscaler capacity expansion, and legacy system technical debt accumulation. Revision becomes warranted when cross-border data residency fragmentation crosses thresholds that block multi-country platform deployments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
Digital Platform Scale Market
Digital Transformation
North America Digital Transformation Market
Digital Transformation
Oman Digital Transformation Market
Digital Transformation
Canada Digital Transformation Market
Digital Transformation
France Digital Transformation Market
Digital Transformation
Workplace Transformation Market
Digital Transformation
Colombia Digital Transformation Market
Digital Transformation
Saudi Arabia Digital Transformation Market
Digital Transformation
Mexico Digital Transformation Market
Digital Transformation
Brazil Digital Transformation Market
Digital Transformation
China Digital Transformation Market
Digital Transformation
Germany Digital Transformation Market
Digital Transformation
Enterprise 2.0 Technologies Market
Digital Transformation
South East Asia Digital Transformation Market
Digital Transformation
Latin America Digital Transformation Market
Digital Transformation
Digital Transformation Consulting Market