
 Germany Digital Transformation Market | 2026-2036
Germany Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Digital Transformation Market Insights
Multi-source vendor strategies among German industrial conglomerates is recalibrating how enterprises procure digital infrastructure and analytics capabilities. SAP SE anchors enterprise resource planning modernization across DAX-listed manufacturers. Siemens AG leverages its digital industries software division to extend factory automation into predictive maintenance platforms. IBM Corporation competes through hybrid cloud consulting tailored to Germany's stringent data residency requirements.
Germany digital transformation encompasses the integration of cyber-physical systems, industrial software stacks, and data analytics platforms to automate decision-making across production, logistics, and customer operations. Cloud-native architectures with edge computing nodes process sensor data at sub-50 millisecond latency for real-time quality control in automotive assembly. AI and big data analytics command the fastest expansion as manufacturers deploy machine learning models for demand forecasting and defect detection. Managed services and integration segments capture disproportionate margin pools because German mid-sized enterprises lack internal DevOps capacity.
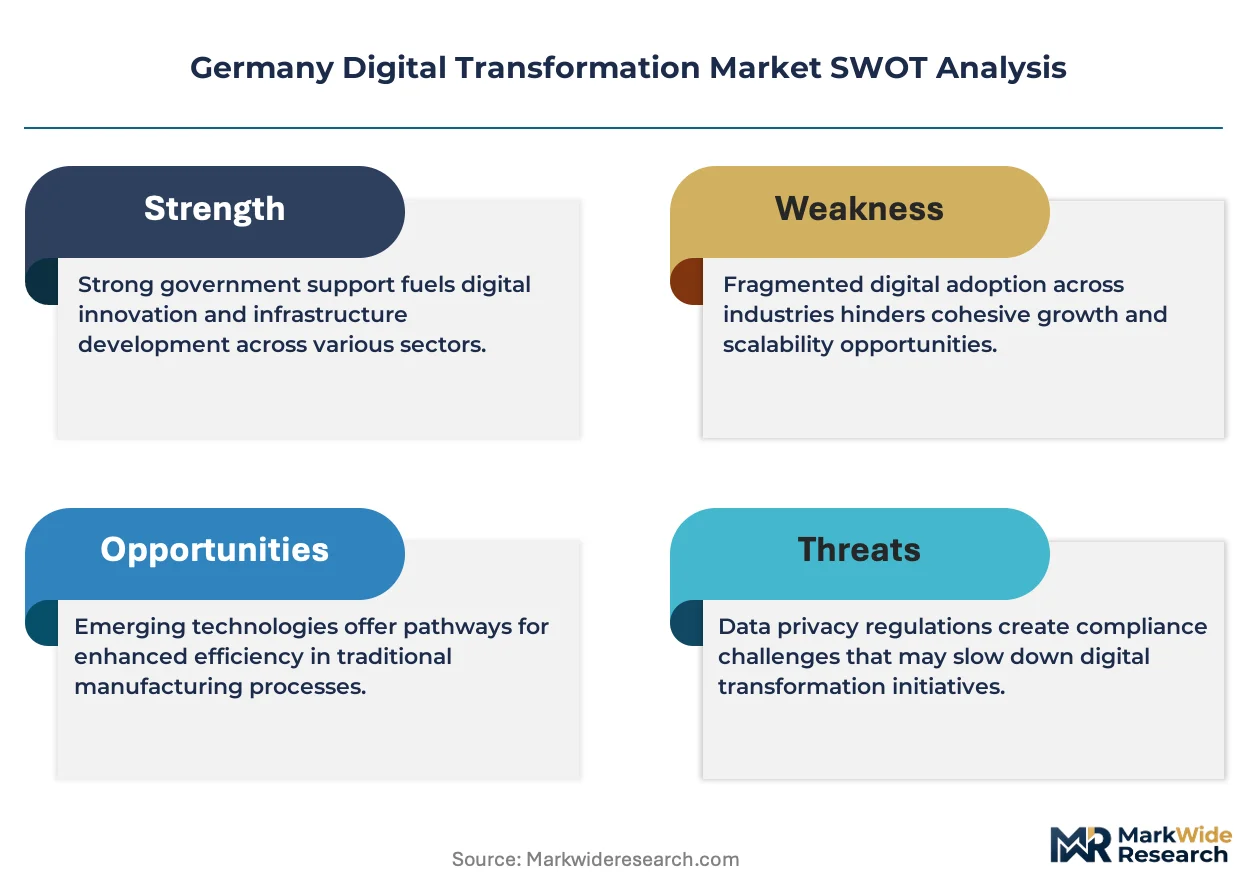
BfDI federal data protection oversight, EU AI Act risk classification requirements, and Germany's IT Security Act 2.0 collectively elevate compliance costs for foreign platform providers while creating domestic certification advantages. The EU Green Deal's digital product passport mandates force manufacturers to trace component-level carbon footprints through blockchain-enabled supply chain software. Stakeholders must monitor how BSI technical guidelines evolve to determine whether on-premises deployment retains regulatory preference over public cloud for critical infrastructure operators.
Market Dynamics
German machinery OEMs and automotive suppliers are consolidating vendor relationships around integrated platform providers capable of delivering edge-to-cloud infrastructure under unified service-level agreements.
Growth Catalysts
- EU AI Act risk-tiered compliance:Mandatory conformity assessments for high-risk industrial AI systems create certified demand for governance tooling and audit-ready MLOps pipelines among automotive quality control deployments.
- Baden-Württemberg industrial corridor concentration:Stuttgart-Mannheim machinery clusters generate dense demand for cyber-physical integration, with OEMs requiring sub-50 millisecond latency for real-time defect detection.
- IT Security Act 2.0 critical infrastructure designation:Energy and water utilities must deploy BSI-certified security architectures, expanding managed security service contracts for operational technology environments.
Market Restraints
- BSI technical guideline uncertainty:Evolving federal cybersecurity mandates create compliance timeline risk for public cloud deployments in critical infrastructure sectors.
- Mid-sized enterprise DevOps capacity scarcity:Mittelstand manufacturers lack internal platform engineering expertise, forcing reliance on high-margin managed service providers.
- Semiconductor component supply volatility:Edge computing hardware lead times extend deployment schedules for industrial IoT sensor networks.
Strategic Opportunities
- EU Green Deal digital product passport mandate:Blockchain-enabled supply chain traceability requirements open software revenue pools for component-level carbon footprint verification.
- Saxony semiconductor manufacturing expansion:Dresden's chip fabrication investments create localized demand for digital twin and predictive maintenance platforms.
- AI and big data analytics convergence:Unified machine learning pipelines for demand forecasting and energy optimization displace siloed point solutions.
Industry Challenges
- OT-IT security architecture integration:Converging operational and information technology networks expose legacy industrial control systems to ransomware vectors.
- Data residency and sovereignty verification:Federal data protection oversight requires demonstrable geographic control over sensitive manufacturing telemetry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Digital Transformation Market |
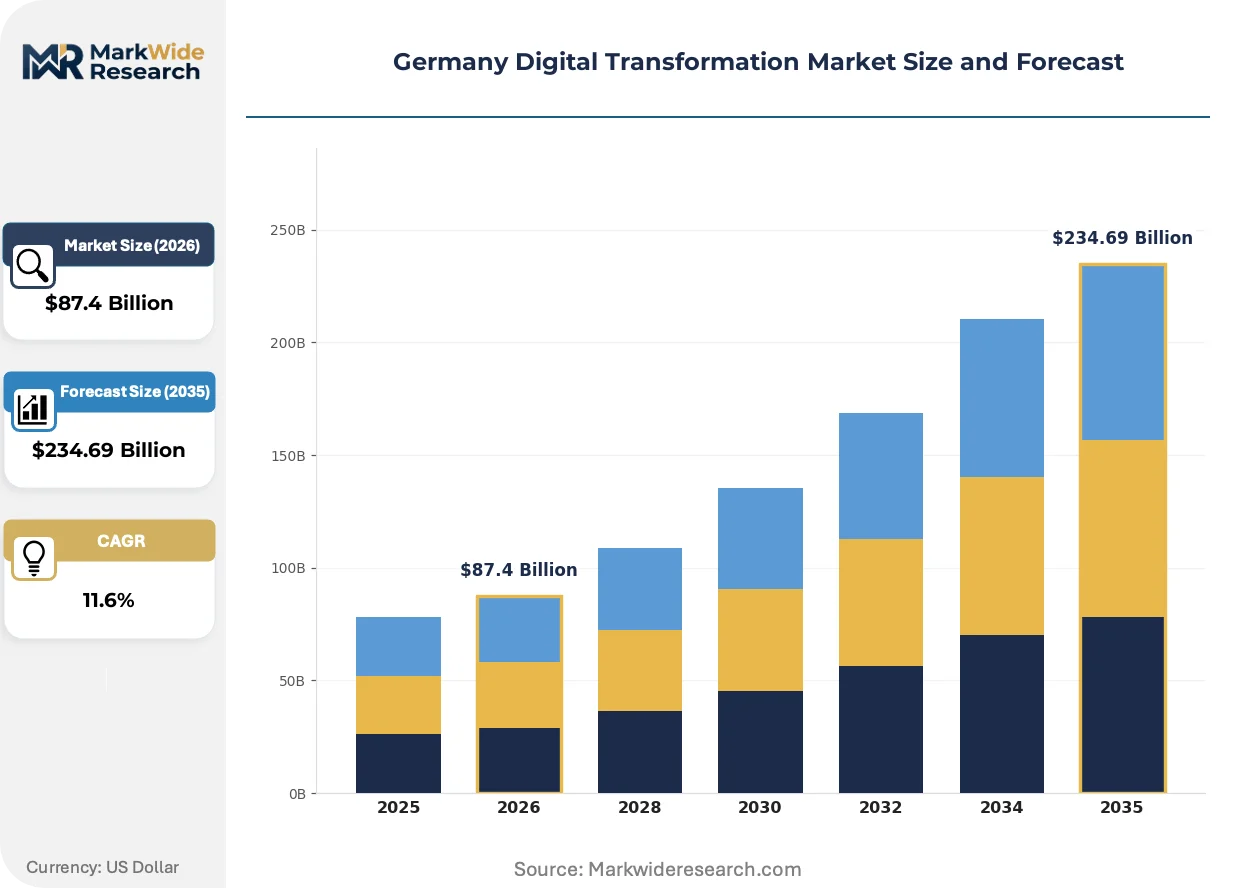
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $234.69 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, AI, Cloud Computing, Big Data End User: Manufacturing, Healthcare, Retail, Financial Services Deployment: On-premises, Hybrid, Public Cloud, Private Cloud Service Type: Consulting, Integration, Managed Services, Support |
| Companies Covered | Accenture PLC, SAP SE, IBM Corporation, Microsoft Corporation, Google LLC, Adobe Inc., Hewlett Packard Enterprise, Siemens AG, Oracle Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Digital Transformation Market Trends and Innovations
Platform consolidation and regulatory compliance automation are compressing procurement cycles while elevating vendor certification requirements.
Edge-native container orchestration is unifying factory-floor data processing with centralized analytics. Automotive assembly plants in Bavaria and Lower Saxony deploy these architectures at scale. The technology is compressing infrastructure vendor margins by reducing dual-stack maintenance overhead.
BfDI federal oversight and EU AI Act conformity procedures are mandating algorithmic transparency documentation. Industrial AI providers must now maintain technical files for high-risk system deployments. Automotive suppliers in Stuttgart's corridor are responding by embedding governance tooling directly into MLOps pipelines.
Mid-sized manufacturers are consolidating vendor relationships around outcome-guaranteed service contracts. Systems integrators displace discrete software licenses with consumption-based pricing. This pattern concentrates in North Rhine-Westphalia's machinery sector, where family-owned enterprises prioritize operational expenditure predictability.
Germany Digital Transformation Market Segmentation
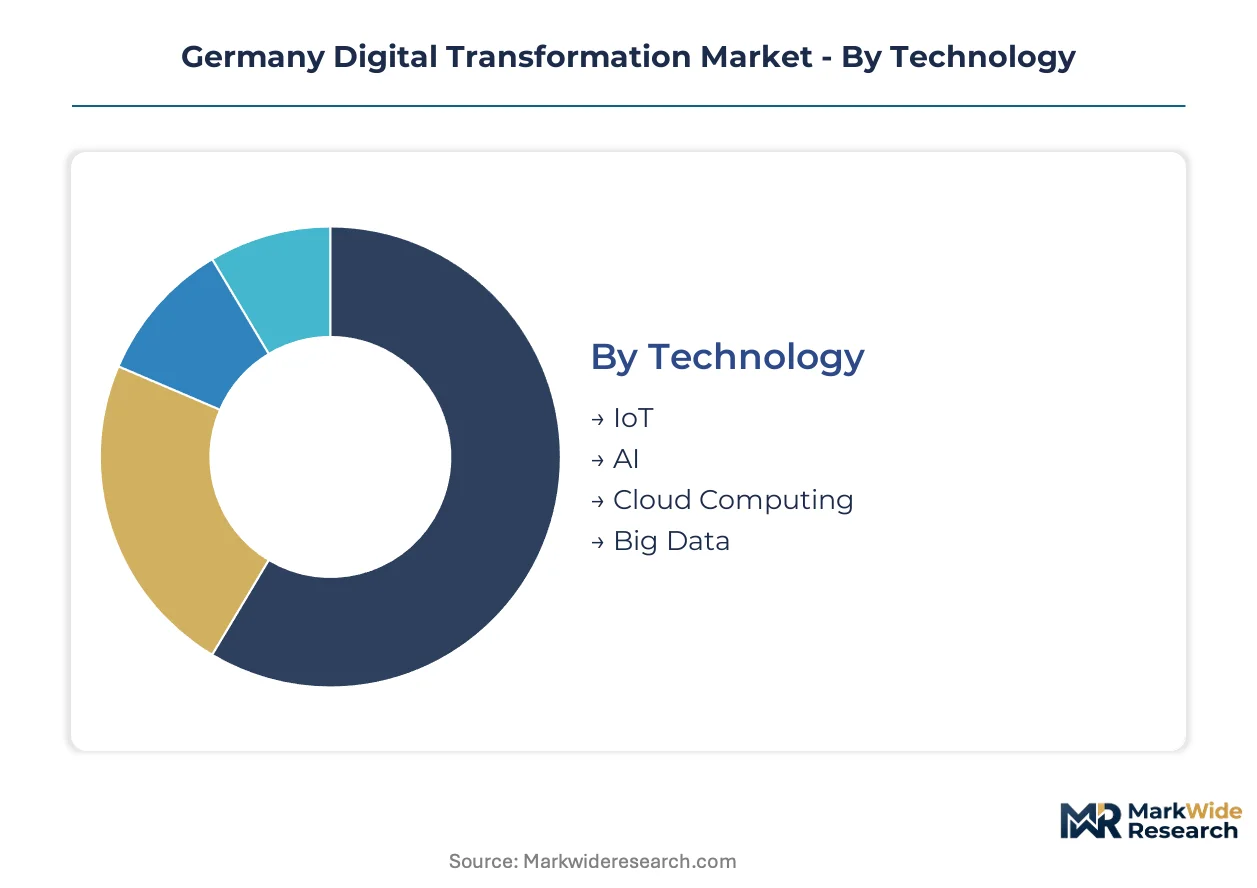
German enterprises structure digital procurement around technology capability, operational constraints, and compliance architecture. Segmentation reveals how Baden-Württemberg's automotive clusters, Bavarian healthcare networks, and North Rhine-Westphalian machinery firms allocate budgets across competing deployment models and service tiers.
Technology:
Industrial-grade specifications determine adoption sequencing across Germany's regulated sectors.
- AI:Machine learning pipelines for predictive quality control and demand forecasting dominate Stuttgart-Mannheim automotive corridors. EU AI Act high-risk system classifications mandate BSI-certified governance tooling for production-line deployments.
- Cloud Computing:Hybrid architectures with edge nodes achieve sub-50 millisecond latency for real-time defect detection. Energy and water utilities under IT Security Act 2.0 prefer private cloud for critical infrastructure telemetry.
- Big Data:Unified analytics platforms process sensor telemetry from cyber-physical systems across factory floors.
- IoT:Sensor networks for asset tracking and condition monitoring face semiconductor lead time volatility.
Mature deployment sits with Cloud Computing. Newer deployment is concentrated in AI.
End User:
Customer archetypes reflect sector-specific regulatory exposure and capital intensity.
- Manufacturing:Machinery OEMs and automotive suppliers in Baden-Württemberg consolidate vendor relationships around integrated platform providers. Family-owned Mittelstand enterprises prioritize outcome-guaranteed service contracts with consumption-based pricing.
- Healthcare:Hospital networks and medical device manufacturers navigate BfDI federal oversight for patient data residency requirements.
- Financial Services:Frankfurt banking clusters deploy BSI-certified security architectures for transactional systems.
- Retail:Omnichannel logistics networks demand real-time inventory optimization across distributed warehouse footprints.
Procurement maturity clusters in Manufacturing. Regulatory complexity peaks in Healthcare.
Deployment:
Infrastructure location decisions hinge on data sovereignty verification and latency requirements.
- Hybrid:Edge-to-cloud orchestration unifies factory-floor processing with centralized analytics, compressing infrastructure vendor margins by eliminating dual-stack maintenance.
- Private Cloud:Dedicated environments satisfy BSI technical guidelines for critical infrastructure operators in energy and water sectors.
- On-premises:Legacy control systems persist where OT-IT convergence exposes ransomware vulnerabilities.
- Public Cloud:Scalable compute for non-sensitive workloads faces timeline risk from evolving federal cybersecurity mandates.
Hybrid architectures dominate new investment. On-premises retention is strongest in critical infrastructure.
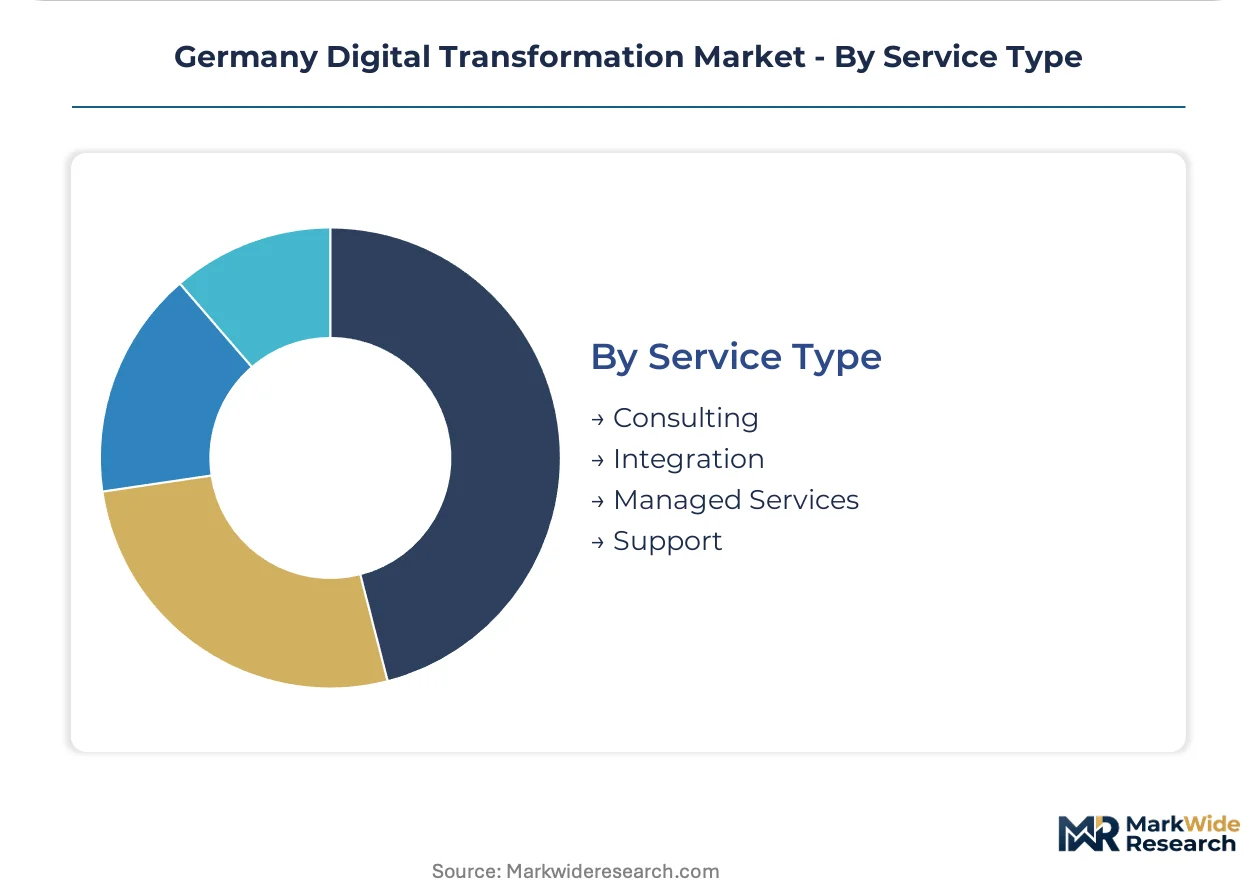
Service Type:
Value capture shifts from discrete licenses to ongoing operational expenditure models.
- Managed Services:DevOps capacity scarcity among mid-sized manufacturers drives disproportionate margin capture for platform engineering and security operations.
- Integration:Systems integrators consolidate fragmented point solutions into unified MLOps pipelines with embedded governance tooling.
- Consulting:Hybrid cloud advisory addresses Germany's stringent data residency requirements for multinational enterprises.
- Support:Maintenance contracts for legacy ERP modernization anchor recurring revenue streams.
Margin concentration sits with Managed Services. Growth velocity is highest in Integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Digital infrastructure investment concentrates in Germany's southern and western industrial corridors, where automotive and machinery clusters generate dense demand for cyber-physical integration and edge computing deployments.
Baden-Württemberg
Stuttgart-Mannheim machinery OEMs and automotive suppliers drive demand for sub-50 millisecond latency edge architectures. EU AI Act high-risk system classifications mandate BSI-certified governance tooling for production-line AI deployments. The Stuttgart industrial corridor anchors Germany's densest concentration of predictive maintenance and quality control automation projects.
Bavaria
Munich-based industrial software vendors and automotive assembly plants accelerate cloud-native manufacturing platform adoption. Germany's IT Security Act 2.0 elevates compliance costs for critical infrastructure operators in energy and water sectors. Bavarian automotive plants deploy edge-native container orchestration at scale for real-time defect detection systems.
North Rhine-Westphalia
Family-owned Mittelstand machinery manufacturers consolidate vendor relationships around outcome-guaranteed service contracts. BfDI federal data protection oversight requires demonstrable geographic control over sensitive manufacturing telemetry. The Ruhr industrial region's legacy steel and chemical facilities face OT-IT security architecture integration challenges from converging network exposures.
Lower Saxony
Volkswagen's Wolfsburg headquarters and supplier network generate concentrated demand for digital twin and supply chain traceability platforms. EU Green Deal digital product passport mandates force component-level carbon footprint verification through blockchain-enabled software. Hanover's industrial automation cluster specializes in logistics optimization and warehouse robotics integration.
Hesse
Frankfurt's banking and financial services sector deploys BSI-certified security architectures for transactional systems under stringent federal oversight. The state's data center concentration supports hybrid cloud infrastructure serving multi-national enterprises with Germany-specific data residency requirements. Darmstadt's cybersecurity research institutions influence BSI technical guideline evolution for critical infrastructure protection.
Germany Digital Transformation Market Competitive Landscape
Strategic partnerships dominate the current landscape as industrial conglomerates consolidate vendor relationships around integrated platform providers capable of delivering unified edge-to-cloud service-level agreements. The market structures around three tiers: global technology conglomerates with full-stack capabilities, specialized industrial software vendors with deep OT expertise, and regional systems integrators serving Mittelstand mid-market requirements. Platform consolidation and outcome-based contracting represent the dominant competitive vectors, compressing margins for discrete software licensing while expanding managed services revenue pools.
Within the industrial software tier, SAP SE and Siemens AG anchor enterprise resource planning and factory automation modernization across DAX-listed manufacturers. IBM Corporation occupies a position bridging hybrid cloud consulting and compliance architecture for Germany's stringent data residency framework. These three exemplify how global technology providers are recalibrating German market positioning around regulatory certification advantages and unified service-level guarantees rather than point solution differentiation.
| Leading Market Players |
|---|
| Accenture PLC |
| SAP SE |
| IBM Corporation |
| Microsoft Corporation |
| Google LLC |
| Adobe Inc. |
| Hewlett Packard Enterprise |
| Siemens AG |
| Oracle Corporation |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between BSI-certified managed service providers and uncertified commodity cloud resellers manifests in both pricing power and supply chain sourcing patterns across Germany's digital transformation procurement. Premium-tier vendors command service-level premiums through demonstrable compliance with IT Security Act 2.0 mandates, while mid-market buyers face compressed margins from semiconductor lead time volatility in edge computing hardware.
Pricing Analysis
Volume concentration in standardized SaaS subscriptions competes with margin-rich managed service contracts for DevOps-scarce Mittelstand manufacturers. Price differentiation rests on BSI certification tier and geographic data residency verification, with Frankfurt-based providers capturing premiums over pan-European operators. Pricing pressure stems from hyperscaler commodity compute pricing eroding mid-tier infrastructure margins. Family-owned machinery OEMs in North Rhine-Westphalia exhibit highest price sensitivity, while critical infrastructure operators in energy and water sectors prioritize compliance over cost.
Supply Chain Analysis
Freight cost escalation for edge computing hardware from Taiwan, South Korea, and China compresses deployment timelines for industrial IoT sensor networks across Baden-Württemberg automotive corridors. Component dependencies center on advanced semiconductors, industrial-grade sensors, and BSI-certified security modules. Single-source vulnerability in semiconductor fabrication creates supply chain risk for real-time quality control deployments. Distribution runs through systems integrators with embedded OT expertise serving machinery OEM clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's digital transformation market sits in a technology-transition phase where edge-native container orchestration displaces legacy dual-stack infrastructure maintenance. Cloud-native manufacturing platforms are consolidating procurement around unified service-level agreements.
For Market Incumbents: Acquire specialized OT security certification capabilities to defend against emerging industrial cybersecurity pure-plays threatening critical infrastructure contracts. Backward integration into edge hardware distribution mitigates semiconductor lead time exposure. Investment in BSI-compliant MLOps governance tooling addresses EU AI Act high-risk system mandates.
For New Entrants and Emerging Players: Begin with outcome-guaranteed service contracts targeting family-owned Mittelstand machinery manufacturers in North Rhine-Westphalia, where DevOps capacity scarcity creates white-space opportunity. Consumption-based pricing models penetrate faster than perpetual licenses. Channel partnerships with established systems integrators accelerate credibility in regulated manufacturing verticals.
For Investors and Strategic Acquirers: Re-rating potential sits with BSI-certified managed security service providers given IT Security Act 2.0 critical infrastructure designation expanding addressable market. Long-term viability hinges on recurring revenue concentration and OT-IT convergence expertise. Monitor BSI technical guideline evolution as inflection signal for public cloud versus private deployment preference shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| BSI Certification Investment | Unlocks IT Security Act 2.0 critical infrastructure contracts in energy and water sectors. |
| Edge-to-Cloud Platform Integration | Unifies factory-floor processing with centralized analytics for Stuttgart automotive suppliers. |
| Acquisition of OT Security Specialist | Addresses ransomware exposure from converging operational and information technology networks. |
| Strategic Partnership with Hyperscaler | Delivers hybrid cloud infrastructure meeting Germany's stringent data residency requirements. |
| Geographic Expansion into Saxony | Captures digital twin demand from Dresden semiconductor fabrication investments. |
Research Methodology
Independent corroboration across primary interviews with plant engineers, IT procurement officers, platform engineers, and aftermarket service heads, combined with secondary validation through SEC filings, hyperscaler capex disclosures, BSI technical guideline releases, and industrial automation trade data, underwrites the qualitative findings. Bottom-up demand modeling from individual enterprise deployments triangulates against top-down market sizing from vendor revenue disclosures.
Comparable-period anchoring to historical digital infrastructure investment cycles establishes baseline growth assumptions across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size by employee count, vertical industry, integration complexity tier, and regional adoption pattern within German federal states. CAGRs derive from trend extrapolation adjusted for regulatory inflection points, with forecast inputs incorporating EU AI Act implementation timelines and semiconductor supply normalization assumptions.
Underlying measurement precision varies by segment; cloud computing and managed services carry tighter precision than emerging AI governance tooling categories. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology substitution rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
India Digital Transformation Market
Digital Transformation
Netherlands Digital Transformation Market
Digital Transformation
Saudi Arabia Digital Transformation Market
Digital Transformation
Mexico Digital Transformation Market
Digital Transformation
MENA Digital Transformation Market
Digital Transformation
China Digital Transformation Market
Digital Transformation
UK Digital Transformation Market
Digital Transformation
Telco Transformation Market
Digital Transformation
Global Design Thinking Market
Digital Transformation
SQL Server Transformation Market
Digital Transformation
APAC Digital Transformation Market
Digital Transformation
Enterprise 2.0 Technologies Market
Digital Transformation
Canada Digital Transformation Market
Digital Transformation
Contact Center Transformation Market
Digital Transformation
South East Asia Digital Transformation Market
Digital Transformation
Global Network Transformation Market