
 Automotive Digital Transformation Market | 2026-2036
Automotive Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Digital Transformation Market Analysis
German automotive software engineering is consolidating around embedded systems and vehicle operating platforms. NVIDIA leverages its GPU architecture to dominate autonomous driving compute stacks, while Vector Informatik anchors its position in AUTOSAR-compliant middleware and diagnostic tools. Elektrobit competes through specialized automotive cybersecurity and over-the-air update solutions for major European OEM programs.
Automotive digital transformation encompasses the integration of software architectures, data analytics, and connectivity layers into vehicle design, manufacturing, and lifecycle management. The field relies on embedded Linux platforms, real-time operating systems, and edge computing nodes processing sensor fusion at sub-100-millisecond latency to enable safe autonomous operation. Cloud Computing infrastructure currently leads technology investment as OEMs migrate vehicle telemetry and fleet analytics to distributed server environments. Connected Vehicles represent the fastest-expanding product category as 5G-V2X deployment enables real-time traffic coordination and predictive maintenance services.
The EU AI Act and GDPR impose binding algorithmic transparency and data residency requirements on automotive AI systems deployed across European markets. The U.S. NHTSA and FCC jointly shape demand through autonomous vehicle safety standards and spectrum allocation for dedicated short-range communications. Stakeholders must monitor evolving type-approval frameworks for software updates as regulators treat over-the-air modifications with the same scrutiny as physical component changes.
Market Dynamics
Software-defined vehicle architectures are compressing hardware refresh cycles and forcing OEMs to decouple mechanical platforms from digital service layers. This structural shift rewrites supplier relationships and investment allocation across the value chain.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Binding requirements for explainable AI in autonomous systems accelerate demand for interpretable machine learning stacks and audit-ready development pipelines.
- 5G-V2X infrastructure deployment:Germany's KBA and federal transport ministry coordinate spectrum allocation for vehicle-to-everything communication, enabling real-time cooperative maneuvering and traffic flow optimization.
- Edge computing node proliferation:Sub-100-millisecond sensor fusion requirements drive embedded processor integration directly into powertrain and chassis control modules.
Market Restraints
- Semiconductor supply concentration:Advanced node GPU and AI accelerator fabrication concentrates among Taiwan-based foundries, exposing automotive programs to geopolitical disruption and allocation constraints.
- GDPR data residency compliance costs:European vehicle telemetry must remain within jurisdictional boundaries, fragmenting cloud architecture and multiplying infrastructure expenditure.
- Legacy embedded system technical debt:Millions of vehicles operate on non-upgradable AUTOSAR Classic platforms, blocking unified software stack deployment across model generations.
Strategic Opportunities
- India PLI scheme for automotive electronics:Production-linked incentives attract component manufacturing for software-defined vehicle platforms serving domestic and export markets.
- Predictive maintenance service unbundling:Fleet operators in Germany now procure vehicle health monitoring as standalone subscriptions separate from hardware lease arrangements.
- Digital twin convergence with manufacturing execution:Real-time virtual commissioning of assembly lines reduces physical prototyping cycles for new vehicle programs.
Industry Challenges
- Embedded cybersecurity specialist scarcity:Automotive-grade secure coding and penetration testing expertise remains concentrated among a limited pool of engineers with ISO/SAE 21434 credentials.
- OTA update type-approval timelines:KBA and similar national authorities apply physical component scrutiny to software modifications, extending validation cycles.
- Functional safety certification complexity:ISO 26262 ASIL-D compliance for autonomous driving compute demands exhaustive documentation and fault injection testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Digital Transformation Market |
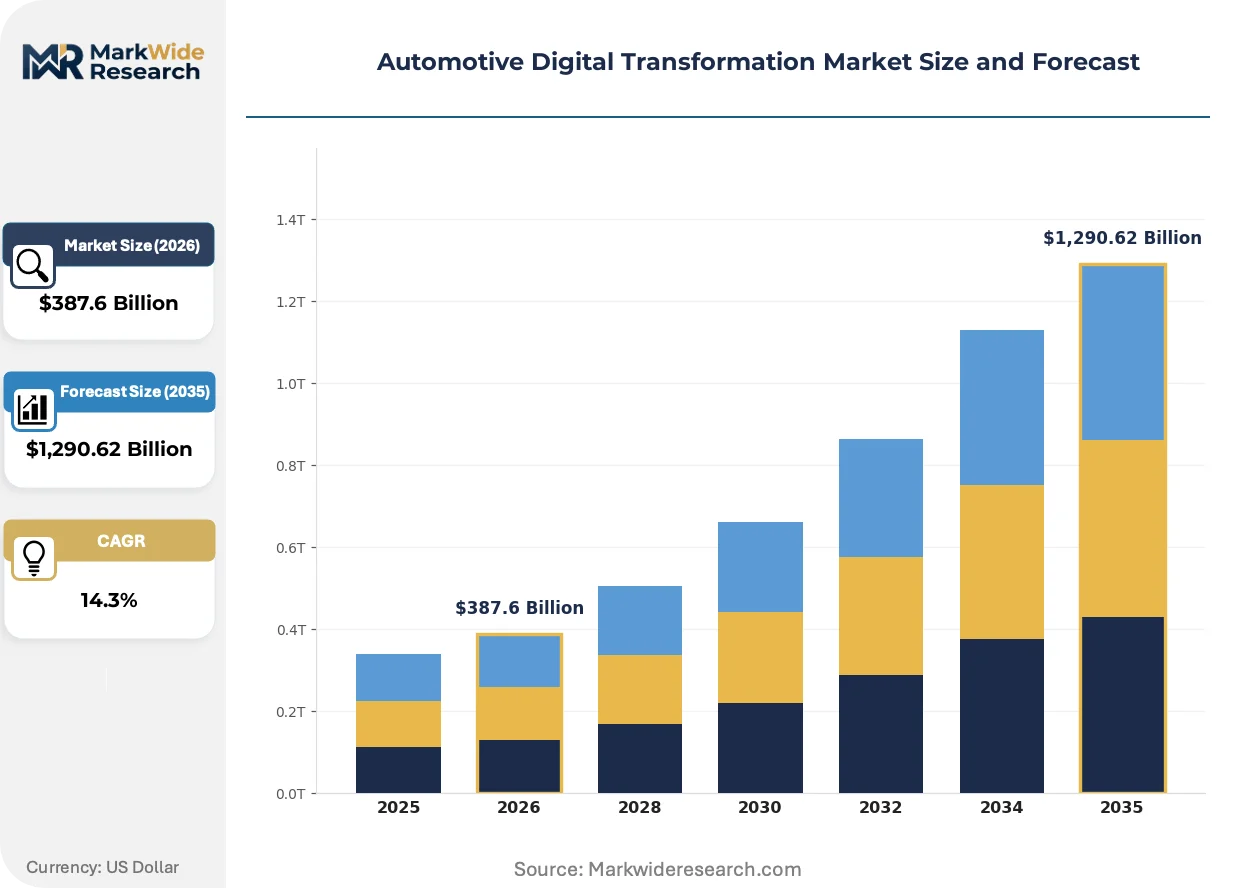
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,290.62 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telematics, Autonomous Driving, Connected Vehicles, Electric Vehicles Technology: Cloud Computing, IoT, AI, Blockchain End User: OEMs, Fleet Operators, Aftermarket Providers, Tier-1 Suppliers Application: Supply Chain Management, Maintenance, Customer Experience, Vehicle Monitoring |
| Companies Covered | Elektrobit, Vector Informatik, NVIDIA, PTC (Parametric Technology Corporation), Cerence, KPIT Technologies, HARMAN International, Master of Code Global, Luxoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Digital Transformation Market Emerging Trajectories
Automotive engineering is pivoting from mechanical-first to software-first development cycles. This transformation manifests across three vectors: compute architecture evolution, regulatory pressure on algorithmic systems, and procurement model restructuring.
Centralized zonal electronic architectures are rewriting vehicle electrical distribution. Domain controllers consolidate dozens of ECUs into high-performance compute clusters. BMW and Mercedes-Benz accelerate zonal designs for 2025-2026 platforms. This compression eliminates redundant wiring harness weight and enables software-defined feature activation post-sale.
The EU AI Act's risk-based classification system imposes conformity assessment obligations on autonomous driving functions. High-risk AI systems require human oversight mechanisms and bias testing documentation. German OEMs establish dedicated algorithmic governance offices to manage compliance portfolios and type-approval dossiers.
Fleet procurement now separates hardware ownership from software service tiers. Logistics operators in Stuttgart and Munich negotiate compute capacity subscriptions independent of vehicle chassis contracts. This unbundling shifts supplier relationships toward recurring revenue models and forces tier-one suppliers to develop service delivery capabilities.
Automotive Digital Transformation Market Segmentation
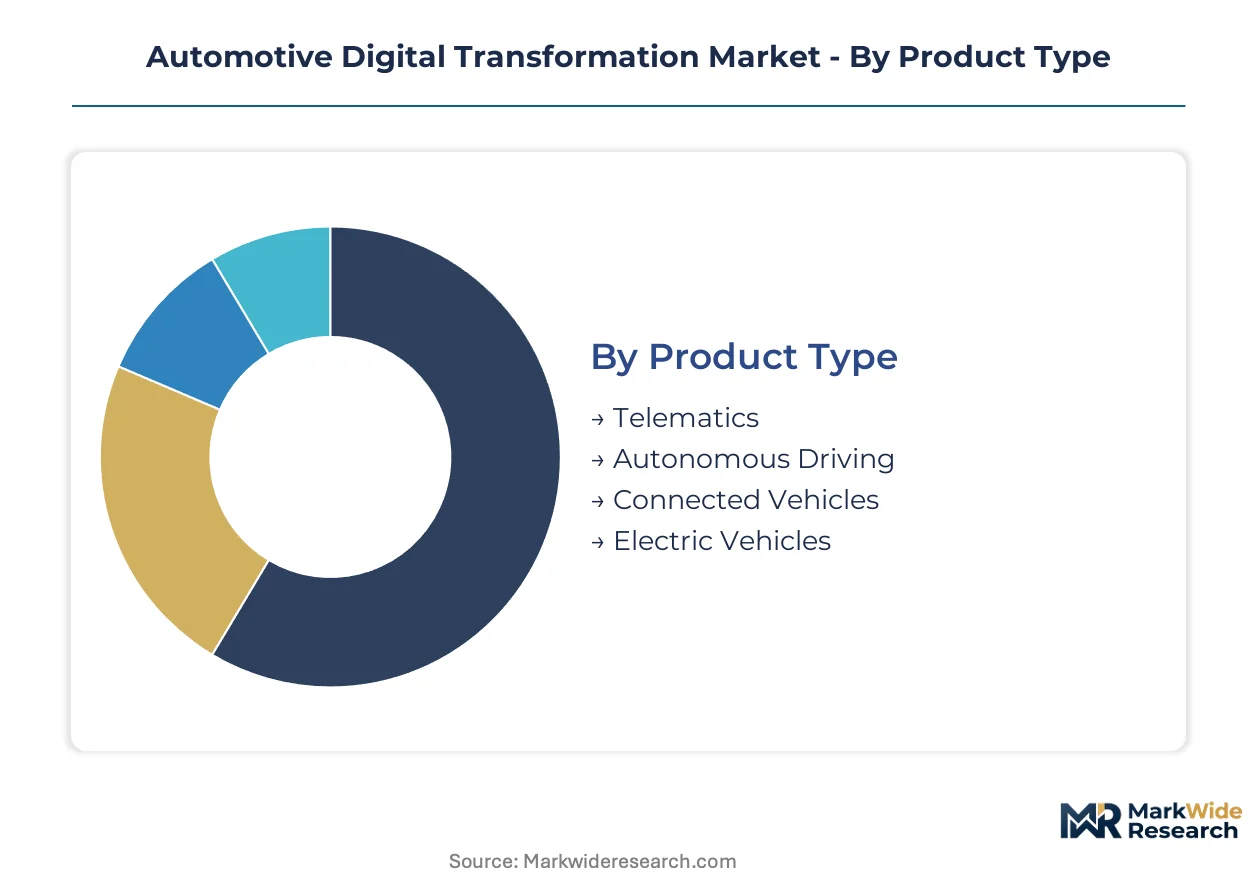
Automotive digital transformation segments reflect divergent investment priorities across the value chain. OEM procurement patterns vary sharply by whether they prioritize manufacturing efficiency, post-sale revenue streams, or regulatory compliance capabilities.
Product Type:
Fleet procurement teams and consumer buyers allocate capital differently based on connectivity maturity and autonomous feature availability.
- Connected Vehicles:Embedded 5G-V2X modems and edge computing nodes enable real-time traffic coordination and predictive maintenance services. German logistics operators in Stuttgart and Munich now subscribe to vehicle health monitoring as standalone services separate from hardware leases, accelerating demand for over-the-air update architectures.
- Autonomous Driving:Sensor fusion platforms processing lidar, radar, and camera inputs at sub-100-millisecond latency require ISO 26262 ASIL-D certified compute stacks. EU AI Act algorithmic transparency mandates force OEMs to maintain audit-ready development pipelines and human oversight mechanisms for high-risk AI systems.
- Telematics:GPS tracking and driver behavior analytics dominate fleet management procurement.
- Electric Vehicles:Battery management systems and charging infrastructure integration drive software investment.
Connected Vehicles leads volumes today; Autonomous Driving is gaining share fastest.
Technology:
Technology selection tracks directly to where latency constraints and data sovereignty requirements intersect.
- Cloud Computing:Distributed server environments host vehicle telemetry and fleet analytics, though GDPR data residency compliance fragments architecture across European jurisdictional boundaries. Multiplied infrastructure expenditure pressures margin structures for cross-border fleet operators.
- AI:Machine learning stacks power predictive maintenance and autonomous decision systems. KBA and national type-approval authorities apply physical component scrutiny to software modifications, extending validation cycles for algorithmic updates.
- IoT:Sensor networks and edge nodes bridge vehicle-to-infrastructure communication.
- Blockchain:Distributed ledger applications focus on supply chain provenance and secure over-the-air update verification.
Cloud Computing anchors current deployment; AI is expanding most quickly.
End User:
Stakeholder technical capabilities and regulatory exposure shape procurement sophistication.
- OEMs:Volkswagen, BMW, and Mercedes-Benz consolidate software-defined vehicle architectures around zonal electronic designs that compress hardware refresh cycles. These manufacturers decouple mechanical platforms from digital service layers, rewriting supplier relationships across tier-one and tier-two networks.
- Fleet Operators:Logistics companies negotiate compute capacity subscriptions independent of chassis contracts, forcing suppliers toward recurring revenue models. Predictive maintenance unbundling accelerates in German commercial vehicle markets.
- Tier-1 Suppliers:Bosch and Continental develop service delivery capabilities alongside hardware manufacturing.
- Aftermarket Providers:Diagnostic tool vendors and retrofit connectivity specialists serve legacy vehicle parc upgrade demand.
OEMs dominate current technology absorption; Fleet Operators are climbing the fastest.
Application:
Application prioritization separates manufacturing-phase investment from lifecycle service monetization.
- Supply Chain Management:Digital twin convergence with manufacturing execution systems enables real-time virtual commissioning of assembly lines. BMW accelerates zonal controller integration for 2025-2026 platforms, eliminating redundant wiring harness weight through centralized compute clusters.
- Maintenance:Predictive algorithms reduce unplanned downtime for commercial fleets. Stuttgart-based operators procure health monitoring as standalone subscriptions, separating software service tiers from hardware ownership structures.
- Vehicle Monitoring:Real-time telemetry tracks location, performance, and compliance metrics.
- Customer Experience:In-cabin personalization and infotainment integration drive consumer-facing software investment.
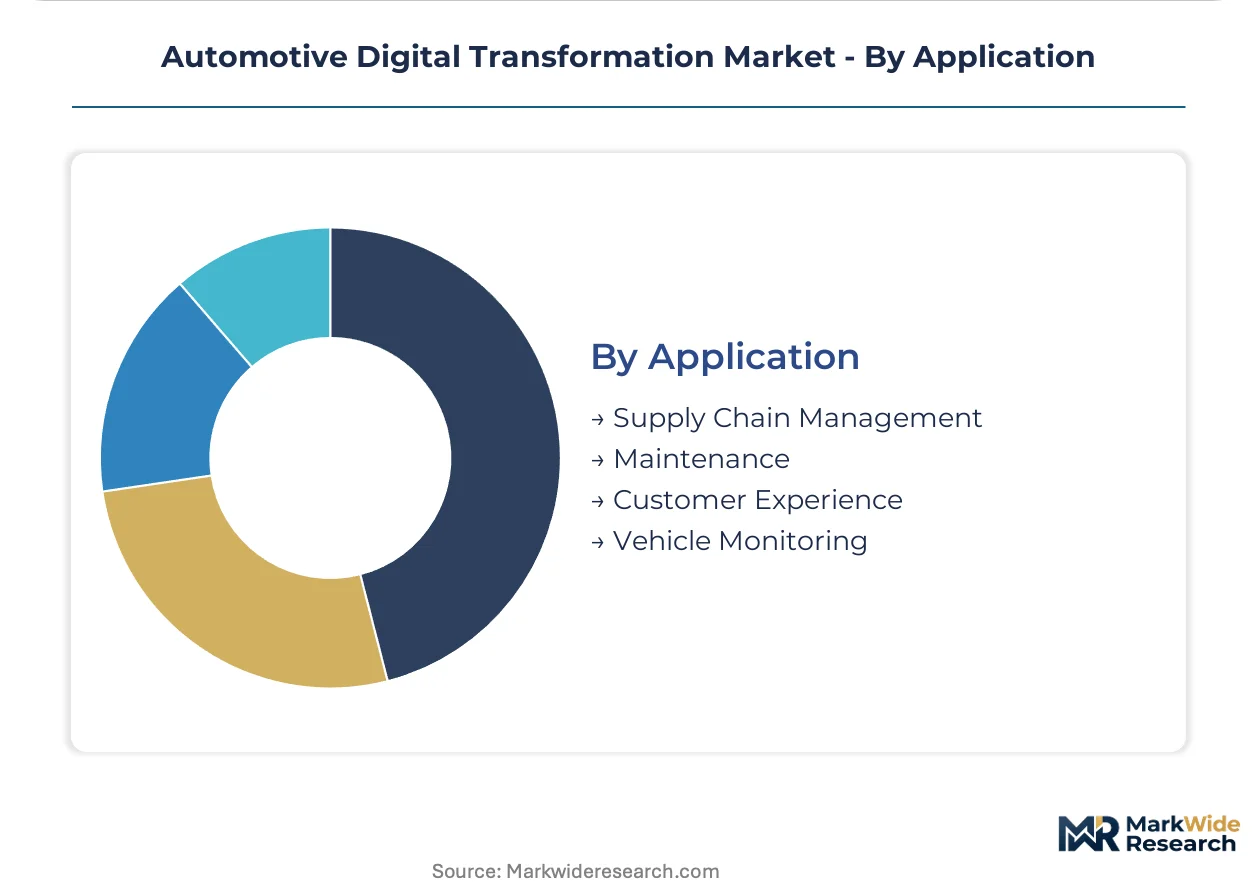
Supply Chain Management leads deployment today; Maintenance is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates software-defined vehicle engineering while the United States dominates cloud infrastructure and AI accelerator design, creating divergent investment patterns across Atlantic markets.
United States
Federal spectrum allocation through the FCC enables dedicated short-range communications for vehicle-to-everything networks. NHTSA autonomous vehicle safety standards shape algorithmic validation requirements for OEMs deploying on public roads. Detroit engineering centers and Silicon Valley compute clusters anchor parallel development tracks for manufacturing automation and autonomous driving stacks.
Germany
KBA type-approval frameworks treat over-the-air software modifications with equivalent scrutiny to physical component changes, extending validation timelines. The EU AI Act imposes binding algorithmic transparency mandates on high-risk autonomous systems deployed across European markets. Stuttgart and Munich automotive clusters concentrate AUTOSAR-compliant middleware development and zonal electronic architecture engineering for 2025-2026 vehicle platforms.
China
MIIT standards for intelligent connected vehicles accelerate domestic 5G-V2X deployment across urban corridors. Dual carbon goals and NEV mandates force software investment into battery management and charging optimization systems. Yangtze River Delta manufacturing hubs integrate digital twin platforms with real-time production execution for export-oriented vehicle programs.
Japan
METI industrial policy directs semiconductor and edge computing investment toward automotive sensor fusion applications. JIS functional safety standards align with ISO 26262 for autonomous driving compute certification. Nagoya engineering corridors and Tokyo software clusters split development between embedded real-time systems and cloud-connected fleet services.
India
PLI scheme production-linked incentives attract component manufacturing for software-defined vehicle platforms serving domestic and export demand. Automotive electronics localization requirements under DGFT rules reshape supplier geography for European and Asian OEM programs. Karnataka and Tamil Nadu tech corridors concentrate embedded systems engineering and diagnostic tool development for global tier-one supply chains.
Automotive Digital Transformation Market Vendor Landscape
German producers anchor the middleware and diagnostic tier; United States specialists hold autonomous driving compute and cloud infrastructure positions. The vendor base splits between consolidated semiconductor platforms and fragmented automotive software houses. Three archetypes dominate: GPU-accelerated autonomous driving stacks, AUTOSAR-compliant middleware providers, and connected vehicle service platforms. Competitive dynamics center on strategic partnerships binding chip vendors to OEM roadmaps and geographic expansion into Asian manufacturing zones.
Within the specialized automotive software tier, Elektrobit and Vector Informatik represent European engineering-centric positioning, while NVIDIA occupies the accelerated compute archetype. Elektrobit exemplifies cybersecurity and over-the-air update specialization for major OEM programs. Vector Informatik anchors AUTOSAR middleware and diagnostic tooling concentration. NVIDIA sits within the autonomous driving silicon layer, supplying GPU architectures that dominate sensor fusion compute stacks across German and US vehicle programs.
| Leading Market Players |
|---|
| Elektrobit |
| Vector Informatik |
| NVIDIA |
| PTC (Parametric Technology Corporation) |
| Cerence |
| KPIT Technologies |
| HARMAN International |
| Master of Code Global |
| Luxoft |
| Others |
Supply Flow & Price Mechanics
Fleet operator procurement of predictive maintenance as standalone subscriptions forces tier-one suppliers to restructure revenue models and absorb upfront platform development costs, compressing margins until service volumes achieve critical mass.
Pricing Analysis
Direct-to-OEM discount structures dominate automotive software procurement, with volume-scale agreements and ISO 26262 ASIL-D certification tiering as primary price differentiation drivers. SaaS-tiered pricing for connected vehicle services stratifies across premium, standard, and economy levels based on feature activation depth and data throughput. Cost compression in middleware licensing intensifies as Vector Informatik and Elektrobit compete for platform standardization wins. Tier-1 suppliers exhibit highest price sensitivity due to OEM consolidation pressure, while autonomous driving compute stacks command premium positioning.
Supply Chain Analysis
India's PLI scheme production-linked incentives and DGFT automotive electronics localization requirements reshape sourcing geography for European and Asian OEM programs. Advanced node GPU and AI accelerator fabrication draws from Taiwan-based foundries and South Korean memory suppliers, with embedded processor dependencies on German engineering clusters. Single-source vulnerability concentrates in Taiwan semiconductor fabrication exposing automotive programs to geopolitical disruption. Distribution runs through tier-one supplier integration into OEM platform engineering teams with direct contract relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act algorithmic transparency mandates compound demand for interpretable machine learning stacks and audit-ready development pipelines, creating structural procurement pressure across German and European OEM programs.
For Market Incumbents: Hedge against semiconductor supply concentration by diversifying foundry relationships beyond Taiwan toward South Korean and domestic European alternatives. Deepen backward integration into edge computing node design to capture value migrating from hardware to software-defined service layers. ISO 26262 ASIL-D certification investment protects against emerging cybersecurity specialist scarcity threatening development timelines.
For New Entrants and Emerging Players: The EU AI Act in Germany opens a window for algorithmic governance and bias testing documentation services targeting OEM compliance offices. White-space targets include predictive maintenance service unbundling for Stuttgart-based logistics operators and AUTOSAR Classic legacy platform migration tools. Go-to-market through tier-one supplier partnership programs accelerates OEM access without direct type-approval burden.
For Investors and Strategic Acquirers: Asymmetric upside sits with embedded cybersecurity specialists holding ISO/SAE 21434 credentials and zonal electronic architecture engineering capabilities. Long-term viability centers on software-defined vehicle platform consolidation over the next decade. Watch KBA type-approval timeline compression as inflection indicator for OTA update service scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | BMW and Mercedes-Benz zonal architecture programs eliminate redundant wiring harness weight through centralized compute clusters. |
| Geographic Manufacturing Footprint | Karnataka and Tamil Nadu tech corridors concentrate embedded systems engineering for global tier-one supply chains. |
| Platform Standardization | AUTOSAR-compliant middleware consolidation around Vector Informatik and Elektrobit reduces OEM integration complexity. |
| Battery Supply Agreement | Dual carbon goals and NEV mandates force software investment into battery management and charging optimization systems. |
| Charging Infrastructure Partnership | 5G-V2X deployment enables real-time traffic coordination and predictive maintenance services for commercial fleets. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, tier-one supplier procurement leads, aftermarket distributors, and dealership operations managers with secondary validation against vehicle production databases, IHS Markit registration data, KBA type-approval filings, and EU regulatory directives. Bottom-up segment modeling and top-down market triangulation anchored value estimates across technology and end-user dimensions.
Segment-weighting approaches distributed value across connected vehicles, autonomous driving, telematics, and electric vehicle product types, with technology layers spanning cloud computing, AI, IoT, and blockchain. Deployment maturity curves and OEM platform roadmaps informed CAGR derivation across the projection horizon. Content-per-vehicle trajectories for zonal electronic architectures and edge computing node penetration shaped automotive-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under KBA regulatory timeline extensions or Taiwan semiconductor supply disruption scenarios. Forecasts reflect documented assumptions regarding 5G-V2X infrastructure deployment pace and GDPR data residency compliance cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
Indonesia Digital Transformation Market
Digital Transformation
Europe Digital Transformation Market
Digital Transformation
Workspace Transformation Market
Digital Transformation
Colombia Digital Transformation Market
Digital Transformation
India Digital Transformation Market
Digital Transformation
Global Network Transformation Market
Digital Transformation
Digital Transformation in Healthcare Market
Digital Transformation
Middle East Digital Transformation Market
Digital Transformation
Australia and New Zealand Digital Transformation Market
Digital Transformation
Latin America Digital Transformation Market
Digital Transformation
Canada Digital Transformation Market
Digital Transformation
Oman Digital Transformation Market
Digital Transformation
Digital Transformation in Supply Chain Market
Digital Transformation
China Digital Transformation Market
Digital Transformation
Digital Transformation Consulting Market
Digital Transformation
Malaysia Digital Transformation Market