
 Malaysia Digital Transformation Market | 2026-2036
Malaysia Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Digital Transformation Market Insights
Malaysian systems integrators and cloud service providers is broadening their delivery footprint across Peninsular Malaysia and East Malaysia. TM One leverages its nationwide fiber infrastructure to anchor large-scale government and enterprise digitalization contracts. Microsoft Corporation sustains competitive positioning through Azure cloud availability zones and deep partnerships with local software vendors. IBM differentiates via hybrid cloud and AI consulting capabilities targeted at financial services and manufacturing clients in the Klang Valley.
Digital transformation encompasses the strategic integration of cloud computing, artificial intelligence, Internet of Things architectures, and big data analytics to re-engineer organizational processes, customer interfaces, and operational decision systems. The primary purpose is to replace legacy on-premise IT estates with scalable, API-connected platforms that enable real-time data orchestration and automated workflow execution. Cloud computing and artificial intelligence together command the dominant share of technology spending, while cybersecurity within the application layer is expanding fastest as regulatory pressure and threat surface expansion force enterprise budget reallocation. Integration services under the solution dimension capture concentrated margin pools due to the complexity of stitching heterogeneous legacy systems into modern cloud-native environments.
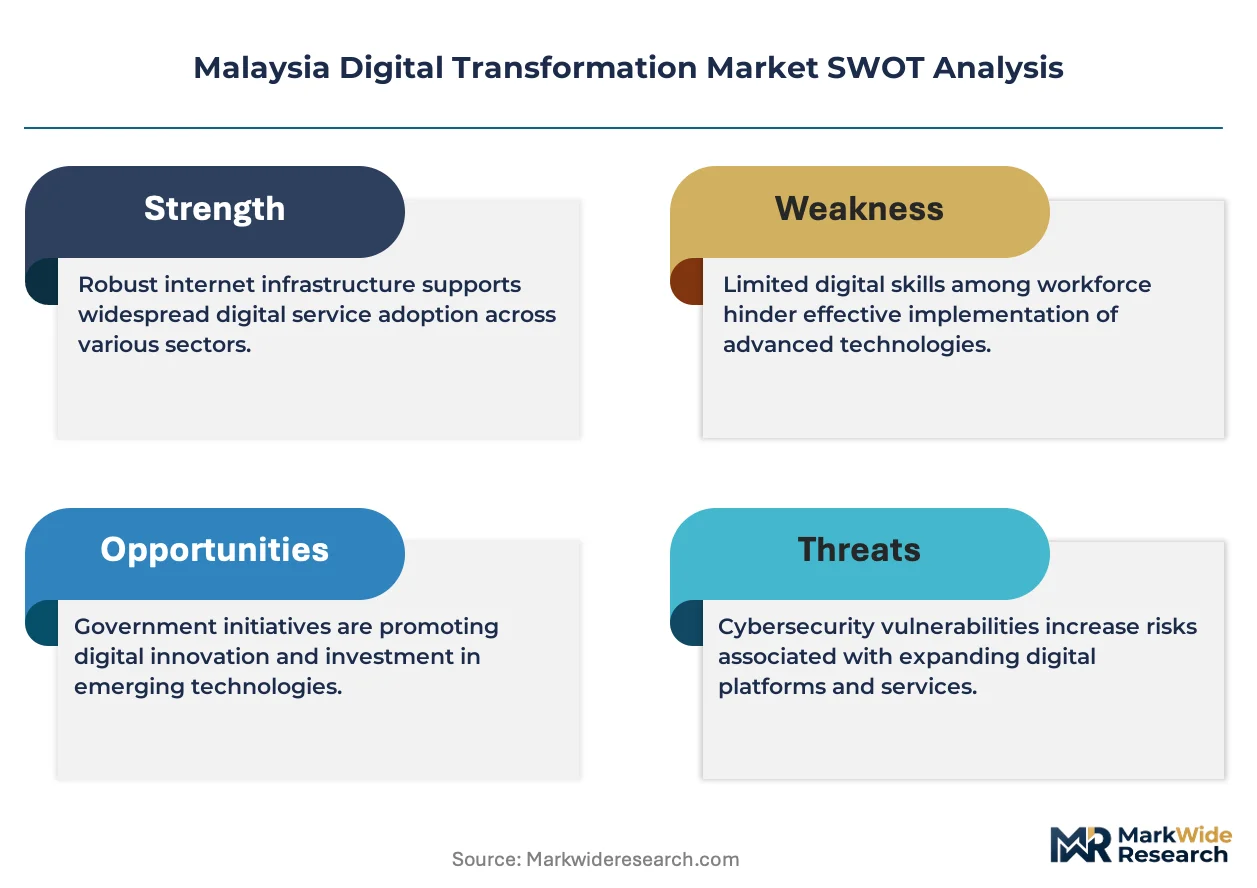
Malaysia's digital transformation trajectory operates under the oversight of the Malaysia Digital Economy Corporation, the Communications and Multimedia Commission, and BIS-equivalent standards bodies governing data sovereignty and cybersecurity certification. These frameworks mandate local data residency for sensitive sectors and prescribe security baselines that shape vendor qualification criteria and procurement specifications. Stakeholders must monitor how forthcoming amendments to the Personal Data Protection Act and sector-specific digital banking licenses reconfigure compliance obligations and competitive access rules.
Market Dynamics
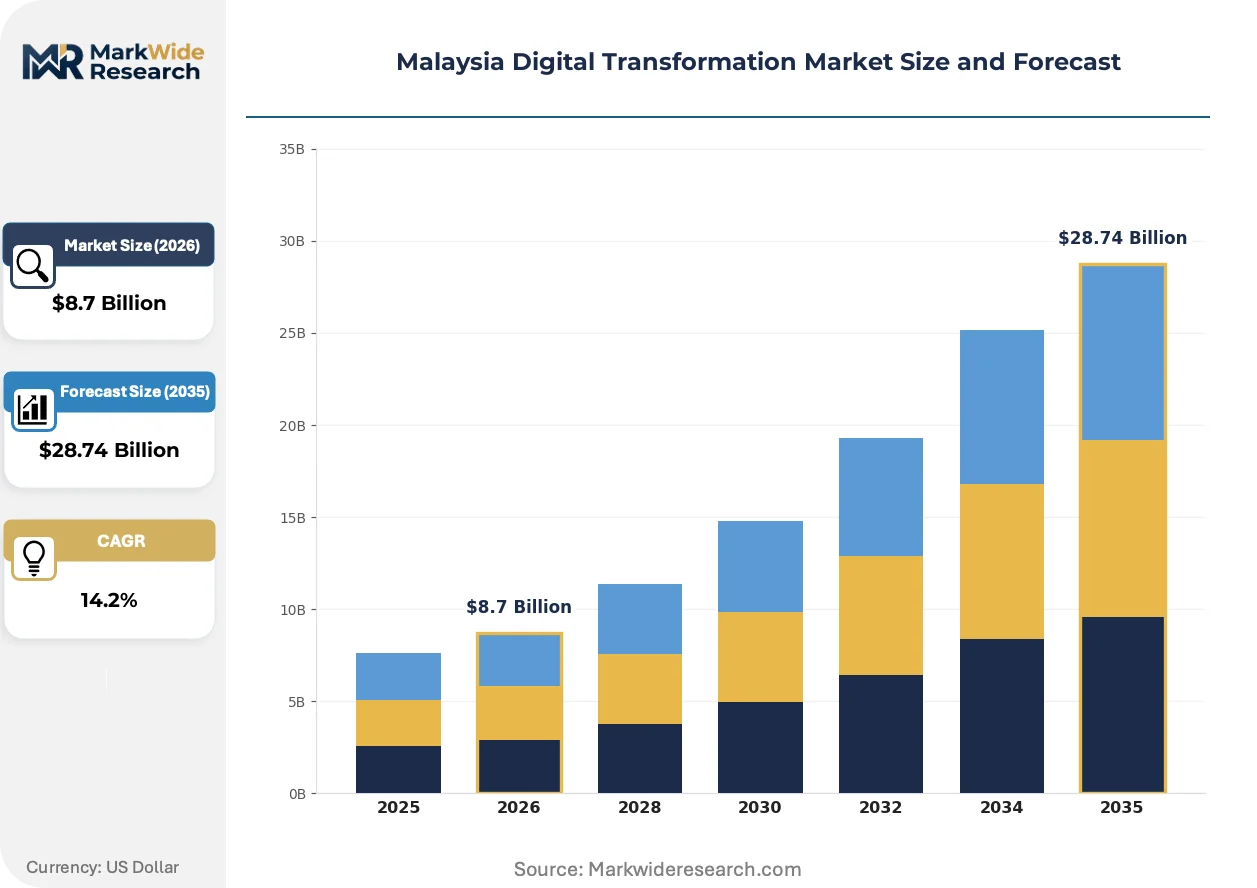
Malaysian banks and insurers are accelerating cloud-based core banking platform adoption, while the MyDIGITAL blueprint channels public investment into digital infrastructure. This dual pressure from financial sector modernization and government policy is compressing legacy system replacement timelines across enterprise IT estates.
Growth Catalysts
- MyDIGITAL Blueprint:The national digitalization framework mandates cloud-first procurement for government agencies, creating anchor demand that pulls private sector vendors into compliant service delivery models.
- Financial Services Modernization:Bank Negara Malaysia's digital banking licensing regime forces incumbent institutions to modernize core systems or cede retail deposits to neobank entrants.
- Klang Valley Enterprise Density:Kuala Lumpur and Selangor host Malaysia's densest concentration of headquarters functions, concentrating systems integration demand within a 50-kilometer corridor.
Market Restraints
- Data Residency Compliance Costs:Personal Data Protection Act amendments mandate local data storage for sensitive sectors, forcing foreign cloud providers to build Malaysian availability zones or exit regulated verticals.
- Legacy Technical Debt:Mainframe-based core banking systems at major financial institutions require multi-year migration timelines that delay API-native architecture deployment.
- Specialized Talent Scarcity:Domestic supply of cloud architects and cybersecurity engineers falls short of demand, inflating project costs and extending implementation schedules.
Strategic Opportunities
- East Malaysia Expansion:Sarawak and Sabah remain underpenetrated for enterprise cloud services, with state governments launching digital economy initiatives that replicate Peninsular Malaysia's earlier trajectory.
- AI-Cloud Convergence:Integration of generative AI capabilities with existing Azure and AWS deployments creates upsell opportunities in customer service automation and fraud detection.
- Manufacturing IoT:Electrical and electronics producers in Penang and Johor are piloting predictive maintenance platforms, opening industrial verticals beyond financial services dominance.
Industry Challenges
- Multi-Cloud Orchestration Complexity:Enterprises adopting hybrid environments struggle to unify security policies and cost governance across AWS, Azure, and domestic TM One infrastructure.
- Certification Backlogs:Cybersecurity assessment queues at the National Cyber Security Agency delay project go-live dates for critical infrastructure operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Digital Transformation Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud Computing, Artificial Intelligence, IoT, Big Data Application: Enterprise Resource Planning, Customer Relationship Management, E-Commerce, Cybersecurity End User: Financial Services, Healthcare, Retail, Manufacturing Solution: Software, Consulting, Integration Services, Training |
| Companies Covered | Accenture Malaysia, TM One, Microsoft Corporation, IBM, DXC Technology, Silverlake Group, SmartOSC, Hitachi Sunway, Maxis Berhad, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Digital Transformation Market Trends and Innovations
Malaysia's digital transformation market is experiencing accelerated automation of operational workflows as enterprises move beyond infrastructure migration toward intelligent process redesign. Three distinct forces are compressing traditional IT service delivery models.
Robotic process automation combined with machine learning is automating document-intensive workflows in insurance claims processing and trade finance operations. Malaysian banks are deploying these tools at scale, reducing manual processing headcount while accelerating customer response times. This capability shift is automating routine decision layers that previously required human intervention, reallocating staff toward exception handling and relationship management.
The National 4IR Policy mandates sector-specific digital adoption roadmaps for manufacturing, agriculture, and healthcare. This regulatory architecture forces technology vendors to align product roadmaps with ministry-level performance indicators rather than generic efficiency metrics. Financial services and palm oil processing show the steepest compliance-driven technology procurement curves, with state-linked enterprises leading implementation.
Enterprise buyers are consolidating vendor relationships around integrated platform providers capable of delivering infrastructure, applications, and managed services through single contracting vehicles. Systems integrators that previously specialized in implementation are acquiring managed service capabilities to capture recurring revenue streams. This preference consolidation is most visible among government-linked companies in Putrajaya and large family-owned conglomerates headquartered in Kuala Lumpur.
Malaysia Digital Transformation Market Segmentation
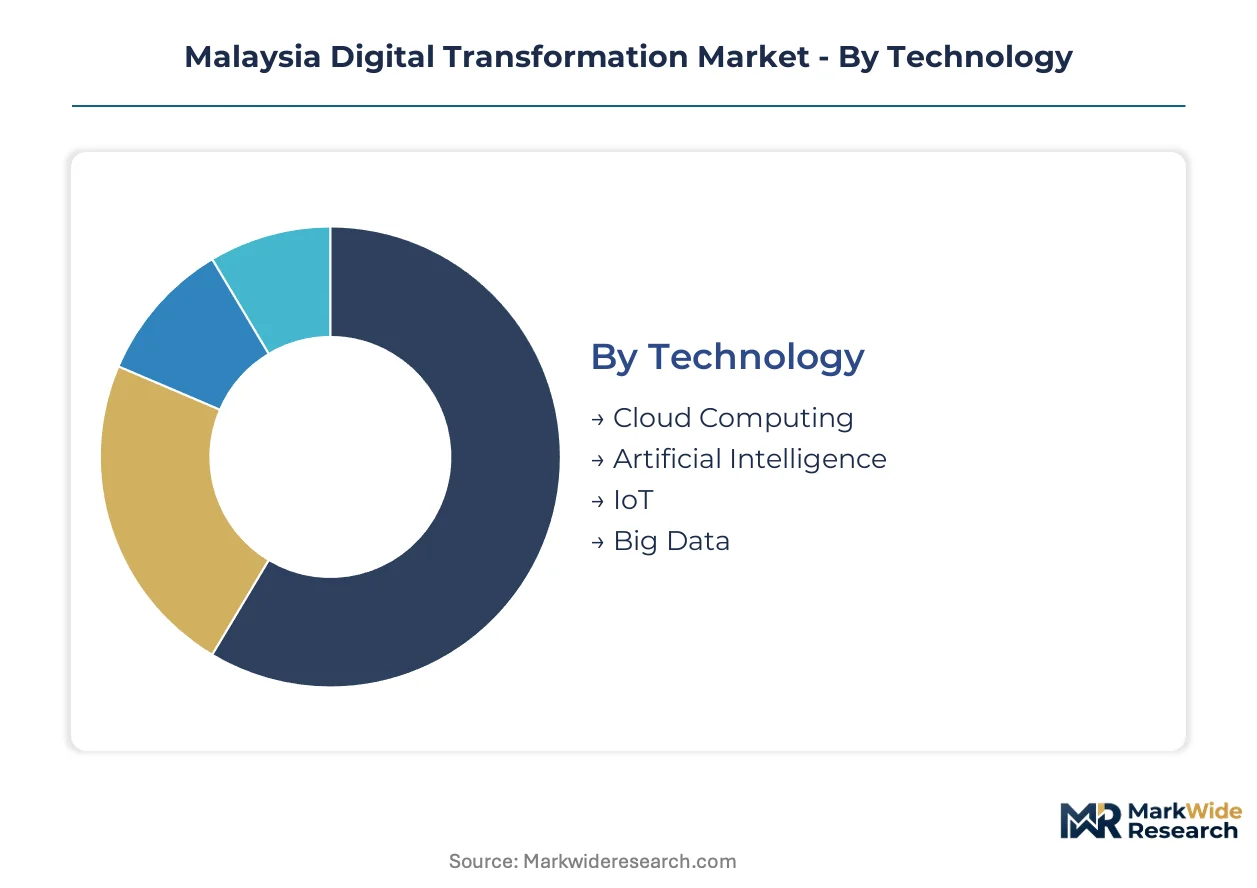
Technology procurement patterns in Malaysia diverge sharply between legacy modernization imperatives and greenfield digital infrastructure deployment. Vendor positioning and margin capture depend on matching solution architectures to sector-specific compliance requirements and existing technical debt profiles.
Technology:
Cloud-native platforms and intelligent automation engines define the specification hierarchy governing enterprise procurement evaluation criteria.
- Cloud Computing:Scalable infrastructure-as-a-service and platform-as-a-service offerings enable API-connected core banking replacements. Demand concentrates among Kuala Lumpur headquartered financial institutions facing Bank Negara Malaysia's digital banking license pressure.
- Artificial Intelligence:Machine learning models and generative AI capabilities automate document processing and fraud detection workflows. Newer deployment is concentrated in insurance claims automation and trade finance operations at Klang Valley banking clusters.
- IoT:Sensor networks and edge computing architectures connect industrial equipment for predictive maintenance. Penang electrical and electronics manufacturers pilot these platforms for factory floor optimization.
- Big Data:Distributed analytics platforms process high-velocity transaction streams and customer behavioral datasets. Mature deployment sits with telecommunications operators and government-linked enterprises in Putrajaya.
Mature deployment sits with Cloud Computing. Newer deployment is concentrated in Artificial Intelligence.
Application:
Functional software categories align with departmental budget ownership and measurable operational efficiency metrics.
- Enterprise Resource Planning:Integrated finance, supply chain, and human capital management modules replace fragmented legacy systems. Demand concentrates among Selangor-based manufacturing conglomerates consolidating multi-subsidiary operations onto single platforms.
- Cybersecurity:Application-layer security tools, identity management, and threat detection systems protect cloud-native architectures. Newer deployment is expanding most quickly as Personal Data Protection Act amendments force enterprise budget reallocation toward compliance-grade protection.
- Customer Relationship Management:Cloud-based sales automation and service platforms unify customer interaction channels. Retail banking divisions in Kuala Lumpur deploy these to counter neobank customer acquisition strategies.
- E-Commerce:Digital storefront platforms, payment gateways, and order management systems enable omnichannel retail operations. Johor-based consumer goods distributors adopt these for cross-border trade facilitation.
Procurement maturity clusters around Enterprise Resource Planning. Fastest adoption velocity appears in Cybersecurity.
End User:
Sector-specific regulatory frameworks and competitive pressure intensity shape technology investment prioritization.
- Financial Services:Banks, insurers, and emerging digital banking licensees modernize core systems and customer-facing platforms. This segment commands the dominant share of technology spending due to regulatory-mandated modernization timelines.
- Manufacturing:Electrical and electronics producers, palm oil processors, and industrial conglomerates deploy IoT and analytics for operational optimization. Penang and Johor host the densest concentration of Industry 4.0 pilot programs.
- Healthcare:Hospital networks and pharmaceutical distributors adopt electronic medical records and supply chain traceability systems. Ministry of Health procurement standards accelerate cloud adoption among public sector providers.
- Retail:Department store chains, grocery operators, and specialty retailers implement omnichannel commerce and inventory optimization platforms. Klang Valley consumer density supports advanced personalization technology deployment.
Investment scale and procurement sophistication peak in Financial Services. Manufacturing presents the steepest expansion trajectory for industrial IoT and predictive analytics.
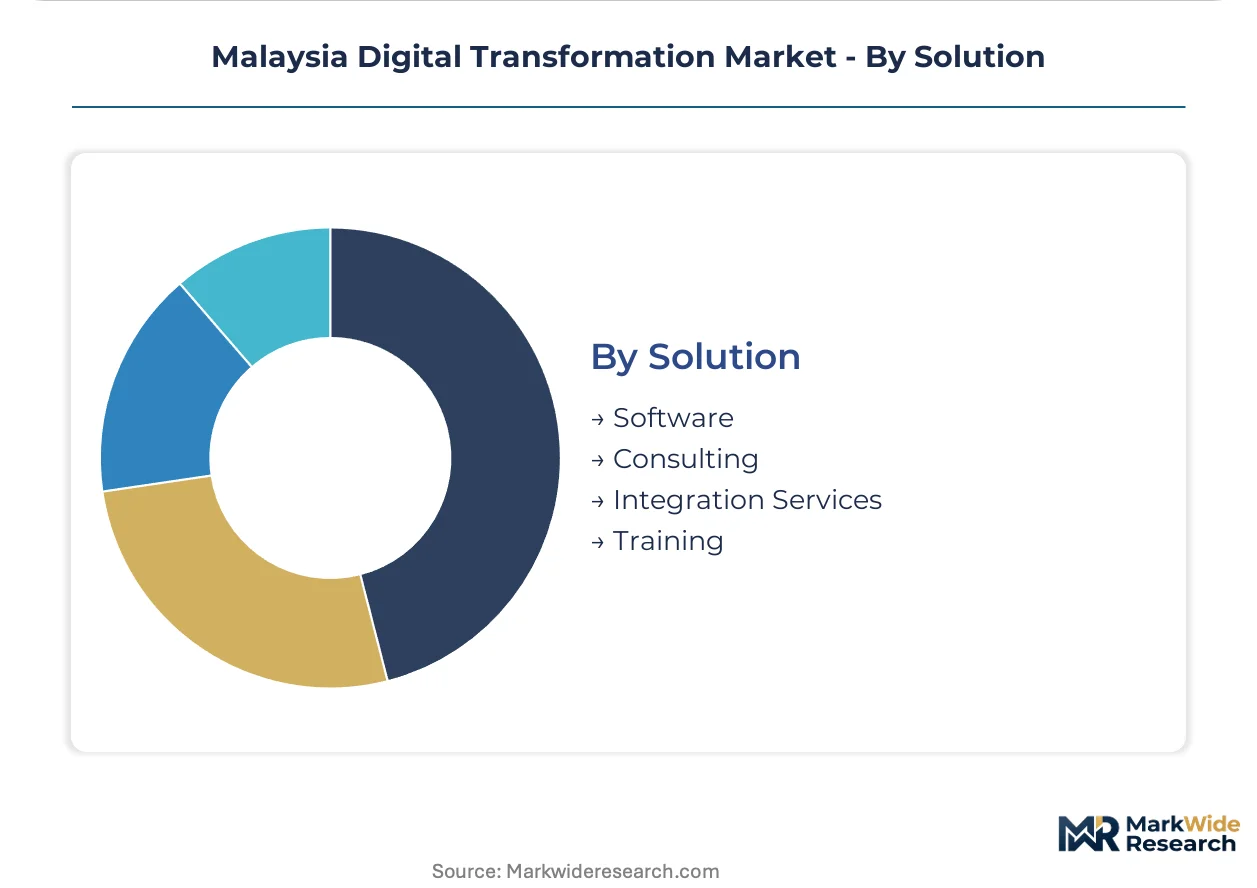
Solution:
Service delivery models range from licensed software products to multi-year transformation partnerships with recurring revenue structures.
- Integration Services:Systems integrators stitch heterogeneous legacy estates into modern cloud-native environments through API development and data migration. This segment captures concentrated margin pools due to project complexity and specialized talent requirements.
- Software:Licensed cloud applications and SaaS subscriptions deliver standardized functionality across common use cases. Mature procurement patterns govern enterprise resource planning and customer relationship management licensing.
- Consulting:Advisory engagements define transformation roadmaps, vendor selection criteria, and organizational change management programs. Demand spikes during initial cloud migration strategy formulation at government-linked companies.
- Training:Capability building programs address domestic cloud architect and cybersecurity engineer scarcity. State-led digital economy initiatives in Sarawak and Sabah fund workforce development to replicate Peninsular Malaysia's technical capacity.
Revenue concentration and margin sustainability favor Integration Services. Training investment is gaining share fastest as talent scarcity inflates project costs across all technology categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication and data center construction materials concentrate in the Klang Valley corridor, anchoring Peninsular Malaysia's digital infrastructure buildout.
Kuala Lumpur
Bank Negara Malaysia's digital banking licensing regime and the MyDIGITAL blueprint drive enterprise cloud procurement. The central bank's regulatory sandbox accelerates neobank market entry. Financial services headquarters in the city center deploy API-native core banking replacements.
Selangor
Manufacturing conglomerates consolidate multi-subsidiary ERP systems onto single platforms. The Malaysia Digital Economy Corporation administers cloud-first procurement standards. Cyberjaya technology park hosts densest systems integrator clusters for government contracts.
Penang
Electrical and electronics producers pilot predictive maintenance IoT platforms for factory optimization. The National 4IR Policy mandates sector-specific digital adoption roadmaps. Bayan Lepas industrial zone anchors Industry 4.0 implementation among semiconductor fabricators.
Johor
Cross-border trade facilitation drives e-commerce platform adoption among consumer goods distributors. Iskandar Malaysia economic corridor incentives attract data center investments. Pasir Gudang logistics hub digitizes supply chain traceability systems.
Sarawak
State government digital economy initiatives replicate Peninsular Malaysia's technical capacity trajectory. The Sarawak Digital Economy Strategy funds workforce development programs. Kuching hosts emerging cloud service delivery points for East Malaysia expansion.
Malaysia Digital Transformation Market Competitive Landscape
Established systems integrators occupy the standard tier; emerging cloud-native specialists pursue API-first architecture contracts. Market structure concentrates around three archetypes: telecommunications incumbents with fiber infrastructure, global hyperscalers with local availability zones, and domestic software vendors with regulatory compliance expertise. Competitive moves center on strategic partnerships with government-linked enterprises and vertical integration into managed services.
Within the telecommunications infrastructure tier, TM One leverages nationwide fiber assets to anchor government digitalization contracts. Microsoft Corporation sustains positioning through Azure cloud availability zones and partnerships with local software vendors. IBM occupies the hybrid cloud consulting segment targeting financial services and manufacturing clients in the Klang Valley corridor.
| Leading Market Players |
|---|
| Accenture Malaysia |
| TM One |
| Microsoft Corporation |
| IBM |
| DXC Technology |
| Silverlake Group |
| SmartOSC |
| Hitachi Sunway |
| Maxis Berhad |
| Others |
Pricing and Supply Chain Analysis
Government-linked companies in Putrajaya and Kuala Lumpur concentrate procurement authority for large-scale digital transformation contracts, anchoring project-based pricing with multi-year managed service attachments as the dominant commercial structure.
Pricing Analysis
Warranty and service bundling separates hyperscale cloud providers from domestic systems integrators, with Azure and AWS availability zones including 24/7 technical support while TM One and local vendors unbundle professional services for separate negotiation. Three-tier pricing structure across premium, standard, and economy levels governs SaaS subscriptions, with enterprise ERP and cybersecurity platforms commanding premium tiers due to Bank Negara Malaysia compliance requirements. Cost compression in mid-market integration services is intensifying because talent scarcity inflates project delivery costs. Small and medium enterprises show greatest price sensitivity, while financial institutions prioritize compliance-grade capabilities over unit cost.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand from Kuala Lumpur financial institutions, while systems integrators and TM One's fiber infrastructure anchor government contract distribution. Hardware supply draws from Taiwan, China, and South Korea for server components and networking equipment. Software licensing rests on US-based hyperscaler cloud platforms and domestic Malaysian vendors for regulatory-compliant modules. Single-source vulnerability concentrates in foreign cloud availability zones, where data residency mandates force local infrastructure buildout. Distribution runs through Cyberjaya technology park clusters and direct vendor relationships with enterprise headquarters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around integrated platform providers as multi-cloud orchestration complexity forces pure-play implementation vendors toward acquisition or exit.
For Market Incumbents: To counter neobank entrants and digital banking licensees, incumbent financial institutions must accelerate API-native core banking replacement timelines and deepen backward integration into proprietary data center infrastructure. Certification investment in Bank Negara Malaysia digital banking standards represents the critical defensive lever against deposit migration. For New Entrants and Emerging Players: Systems integrator partnerships with TM One provide the fastest channel to government-linked company contracts in Putrajaya. East Malaysia cloud service delivery points in Kuching and Kota Kinabalu present the most penetrable geography, with state-funded digital economy initiatives replicating Peninsular Malaysia's earlier infrastructure trajectory. For Investors and Strategic Acquirers: Distressed-cycle entries favor managed service providers with recurring revenue streams in Selangor and Penang manufacturing corridors. Long-term viability over the next decade hinges on AI-cloud convergence capabilities and hybrid cloud consulting depth. The signal to watch is Bank Negara Malaysia digital banking license award velocity as inflection indicator for core banking modernization demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies AWS, Azure, and TM One infrastructure under single security governance for Klang Valley banks. |
| Geographic Expansion | Establishes East Malaysia cloud availability zones to capture Sarawak Digital Economy Strategy procurement. |
| Acquisition of Specialist Firm | Adds cybersecurity engineering capabilities to address National Cyber Security Agency certification backlogs. |
| Strategic Partnership | Aligns product roadmaps with Ministry of Health procurement standards for electronic medical records deployment. |
| Product Launch | Introduces generative AI customer service automation targeting insurance claims processing in Kuala Lumpur. |
Research Methodology
Independent corroboration across Malaysia Digital Economy Corporation procurement records, Bank Negara Malaysia regulatory circulars, and hyperscaler capex disclosures underwrites the qualitative findings. Primary interviews with CTOs at Kuala Lumpur headquartered banks, IT procurement officers at government-linked companies, platform engineers at TM One, and integration specialists at Cyberjaya-based systems integrators combined with secondary validation from SEC filings, MCMC spectrum allocation data, and MyDIGITAL blueprint implementation reports. Bottom-up project pipeline analysis and top-down technology spending estimates triangulate market sizing.
Comparable-period anchoring to MyDIGITAL blueprint launch and National 4IR Policy implementation dates structured the forecast window across the analysis window. Segmentation dimensions modeled include technology category, application function, end-user vertical, and solution delivery model, with deployment complexity and regulatory compliance tier as industry-specific overlays. CAGRs derived from slope-intercept trend fitting to historical procurement velocity and projected license award timelines. Cloud infrastructure investment trajectories and digital banking application volumes served as primary forecast inputs.
Caveats apply where Bank Negara Malaysia regulatory amendments, Personal Data Protection Act revisions, or National Cyber Security Agency certification queue delays could materially shift the outlook. Forecasts reflect base-case assumptions regarding government procurement continuity and talent supply normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
North America Digital Transformation Market
Digital Transformation
Digital Transformation Consulting Market
Digital Transformation
UAE Digital Transformation Market
Digital Transformation
Europe Digital Transformation Market
Digital Transformation
Global Application Transformation Market
Digital Transformation
Australia and New Zealand Digital Transformation Market
Digital Transformation
Latin America Digital Transformation Market
Digital Transformation
France Digital Transformation Market
Digital Transformation
Colombia Digital Transformation Market
Digital Transformation
Global Design Thinking Market
Digital Transformation
Digital Transformation in Healthcare Market
Digital Transformation
Mexico Digital Transformation Market
Digital Transformation
United States Digital Transformation Market
Digital Transformation
South East Asia Digital Transformation Market
Digital Transformation
Workspace Transformation Market
Digital Transformation
Nigeria Digital Transformation Market