
 Global Mortuary Equipment Market | 2026-2036
Global Mortuary Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mortuary Equipment Market Foresight
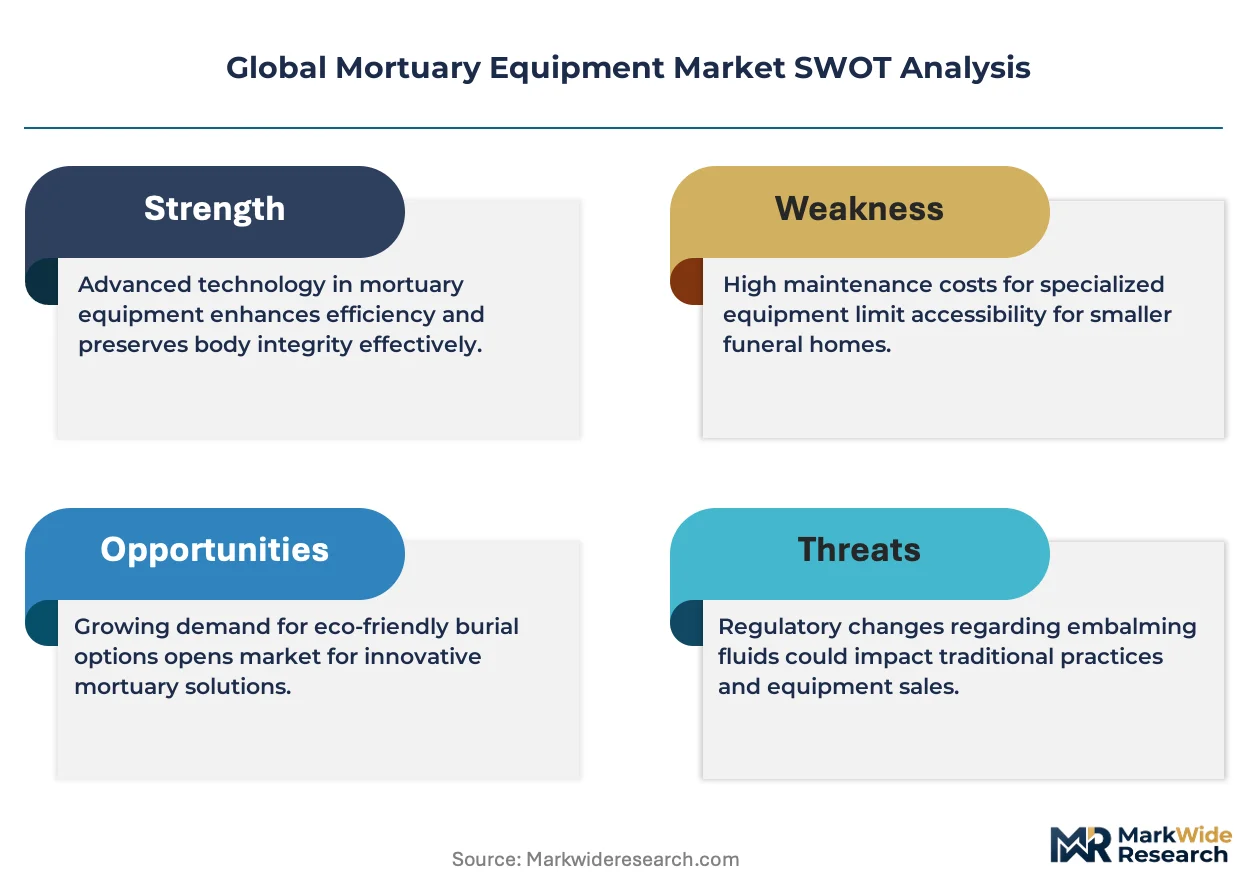
The EU F-Gas Regulation is decoupling mortuary refrigeration from high-global-warming-potential coolants, compelling European buyers to retool cold-chain assets. Thermo Fisher Scientific leverages its cryogenic portfolio to anchor premium positioning in forensic and research channels. Mopec competes through specialized autopsy table configurations for medical colleges and pathology labs. LEEC sustains manufacturing scale across UK and export markets with broad mortuary refrigerator lines.
Mortuary equipment encompasses refrigerated storage systems, embalming apparatus, autopsy platforms, and body transport mechanisms engineered to maintain temperatures between 2°C and 4°C for cadaver preservation and comply with biohazard containment standards. These assets serve hospitals, forensic centers, and funeral operations by preventing decomposition, supporting legal identification, and protecting personnel from pathogen exposure. Morgue trolleys and body lifting equipment occupy mature replacement cycles with stable margin pools, while digital body management systems represent the fastest-growing technology segment as facilities automate chain-of-custody tracking. Refrigeration cooling dominates installed base value, though cryogenic preservation commands premium pricing in research institute and disaster management applications.
FDA guidelines on medical device biocompatibility, EPA refrigerant phase-down mandates under the AIM Act, and EU MDR conformity requirements collectively elevate product certification costs and filter non-compliant suppliers from transatlantic procurement. Japan's METI energy-efficiency standards for commercial refrigeration further constrain equipment design flexibility in a key demand center. Stakeholders must monitor refrigerant chemistry transitions, digital traceability mandates, and shifting funeral-home consolidation patterns to align R&D and distribution investments with emerging compliance and customer structures.
Market Dynamics
The EU F-Gas Regulation is forcing refrigerant chemistry transitions across mortuary cold-chain assets, compelling buyers to replace hydrofluorocarbon-dependent units ahead of phase-down deadlines. This regulatory compression is accelerating replacement cycles in European healthcare procurement while reshaping supplier qualification requirements.
Growth Catalysts
- EPA AIM Act refrigerant mandates:US hospital systems face forced obsolescence of R-404A and R-507A equipment, driving systematic fleet replacement programs across forensic pathology departments.
- Japan's aging demographic profile:Expanding geriatric mortality volumes are pressuring prefectural governments to expand municipal morgue capacity and upgrade regional forensic infrastructure.
- Cryogenic preservation protocols:Disaster management agencies and biobanking consortia are adopting ultra-low temperature storage for mass-casualty scenarios and longitudinal tissue research.
Market Restraints
- Copper and stainless steel input volatility:Refrigeration cabinet fabrication depends on commodity metals with price swings that compress equipment margins during tender cycles.
- German compressor supply concentration:Premium refrigeration systems rely on a narrow supplier base for variable-speed hermetic compressors, creating lead-time vulnerability.
- EU MDR conformity costs:Medical device reclassification of temperature-monitoring systems elevates certification expenses and extends time-to-market for digital-integrated units.
Strategic Opportunities
- India's underserved tier-2 cities:Private hospital chains in Lucknow, Jaipur, and Kochi lack compliant mortuary infrastructure as accreditation standards tighten under NABH protocols.
- RFID chain-of-custody integration:Convergence of wireless tracking hardware and cloud-based audit software enables automated body management systems for high-throughput forensic centers.
- Funeral home consolidation wave:Aggregated buying power among US multi-location operators creates demand for standardized fleet configurations with centralized service contracts.
Industry Challenges
- Refrigeration technician scarcity:Specialized knowledge of low-GWP refrigerant handling and medical-grade calibration remains concentrated among aging workforce cohorts in mature markets.
- Legacy BMS integration friction:New digital body management platforms face protocol incompatibility with existing hospital building management systems, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mortuary Equipment Market |
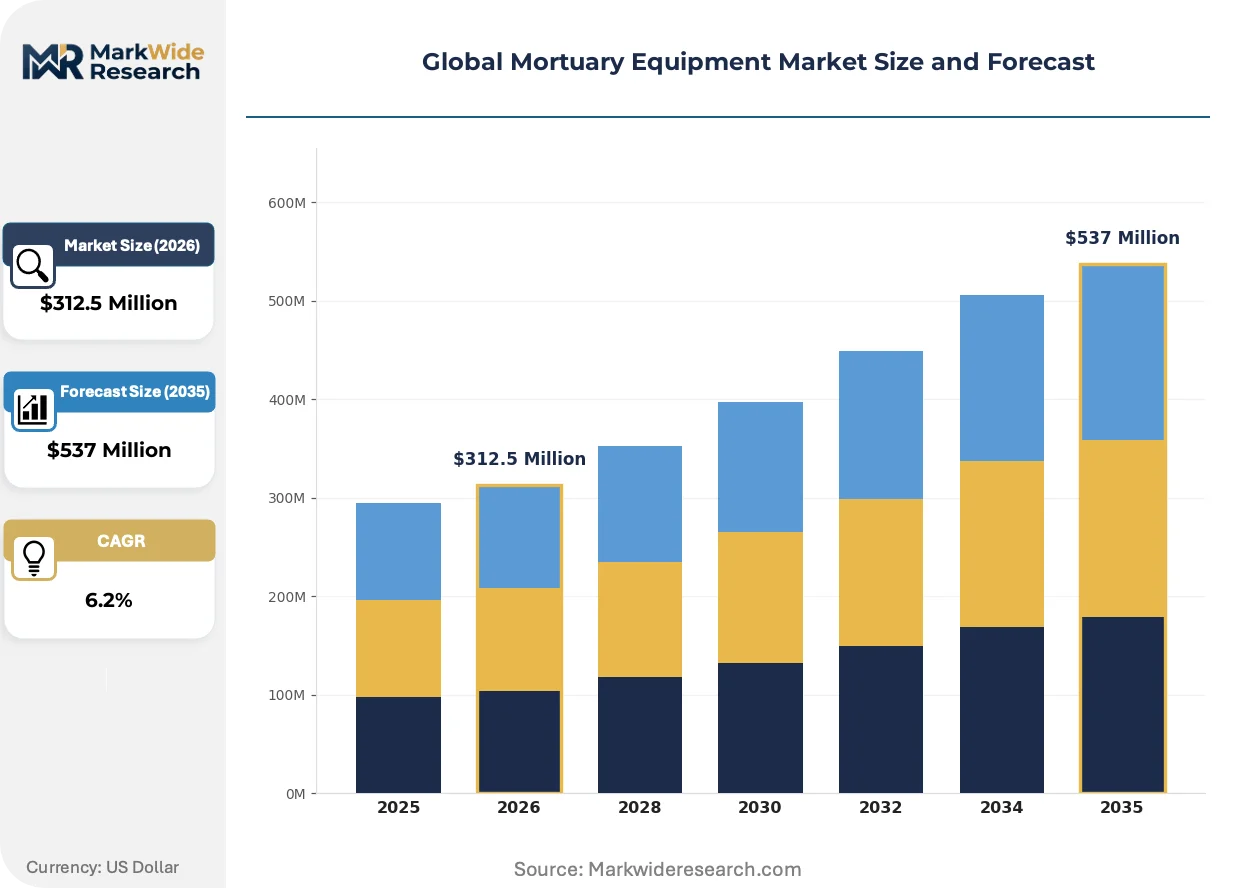
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $537 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mortuary Refrigerators, Embalming Machines, Autopsy Tables, Body Lifting Equipment, Morgue Trolleys Technology: Cryogenic Preservation, Vacuum Embalming, Refrigeration Cooling, Portable Autopsy Systems, Digital Body Management Application: Crematoriums, Funeral Homes, Medical Colleges, Pathology Labs, Forensic Centers End User: Hospitals, Government Facilities, Private Mortuaries, Research Institutes, Disaster Management Units |
| Companies Covered | Thermo Fisher Scientific, Mopec, LEEC, Ferno, KUGEL Medical, Mortech Manufacturing, HYGECO, Roftek, SM Scientific Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mortuary Equipment Market Shifts & Advancements
Digital traceability hardware and low-global-warming-potential refrigerant chemistry are converging to redefine equipment specifications. Suppliers are racing to embed compliance-ready architectures that anticipate multi-jurisdiction mandates.
Modular mortuary refrigeration rack systems are modularizing storage capacity for facilities with variable throughput. Regional hospital networks in France and Belgium are adopting scalable three-body to twelve-body configurations that expand without full replacement. This architecture is modularizing capital deployment patterns, allowing procurement teams to align capacity with census fluctuations rather than peak-load overbuilding.
The EU Green Deal's F-Gas Regulation is prohibiting new equipment using refrigerants with GWP above 150 in stationary commercial applications. Mortuary refrigerator OEMs are pivoting to R-290 (propane) and R-600a (isobutane) alternatives with redesigned safety systems. German and French buyers are prioritizing units with pre-certified compliance to avoid retrofit liability.
Consolidated procurement through group purchasing organizations is displacing direct manufacturer relationships for mid-scale hospital buyers. US health systems affiliated with Premier and Vizient are negotiating enterprise pricing for standardized mortuary equipment fleets. This concentration is most visible in the Southeast and Midwest, where Catholic health networks and for-profit chains dominate bed capacity.
Global Mortuary Equipment Market Segmentation
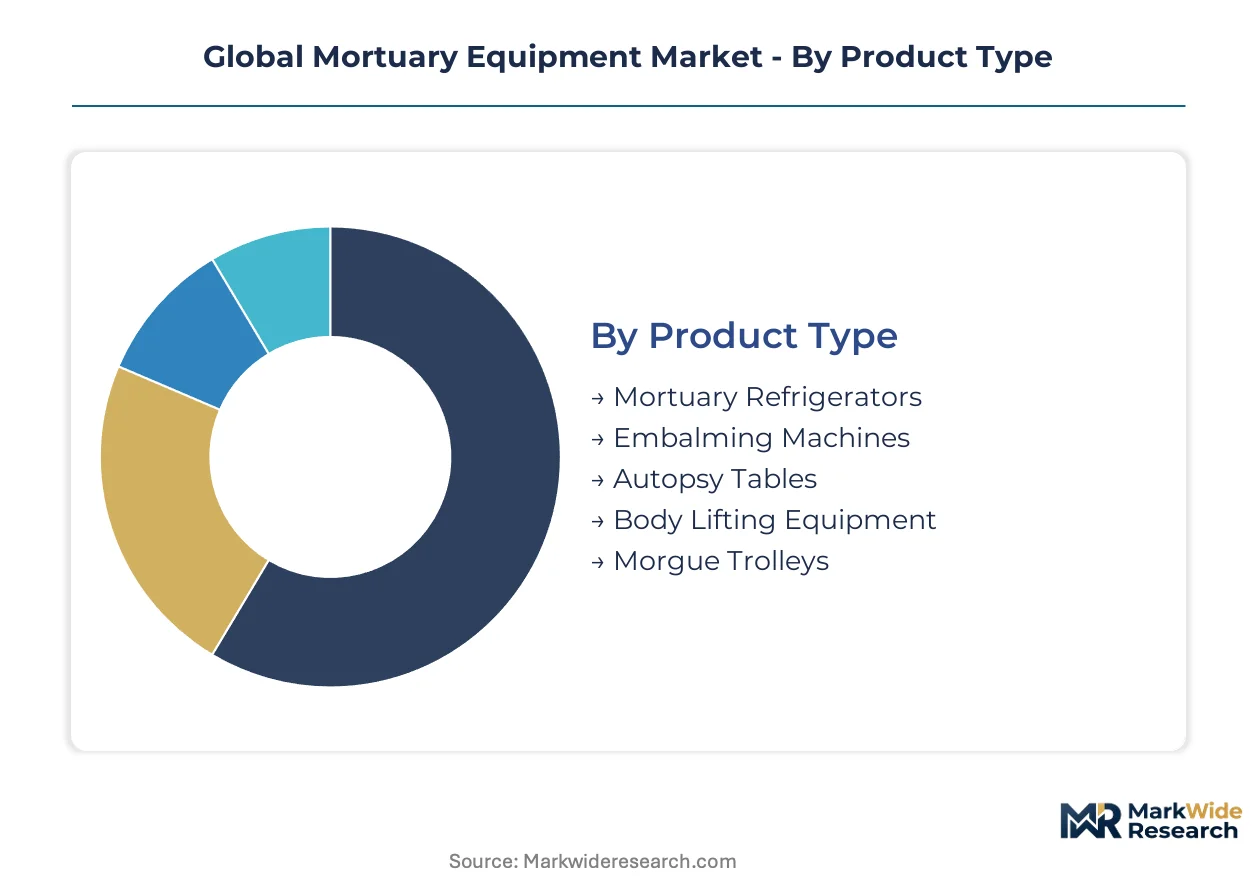
Mortuary equipment procurement follows distinct technical and regulatory pathways across product categories. Buyers prioritize infection control compliance, energy efficiency mandates, and throughput scalability when allocating capital across refrigeration, embalming, and autopsy infrastructure.
Product Type:
Capital allocation intensity varies sharply by equipment lifecycle and refrigerant compliance burden.
- Mortuary Refrigerators:These units maintain 2°C to 4°C storage for cadaver preservation using compressor-based cooling systems. Hospital procurement in Germany and France is accelerating replacement of R-404A-dependent fleets ahead of EU F-Gas phase-down deadlines.
- Embalming Machines:Pressure-controlled systems circulate preservative fluids through arterial networks. Demand concentrates in US funeral home chains consolidating under multi-location service contracts requiring standardized equipment configurations.
- Autopsy Tables:Stainless steel platforms with integrated drainage and ventilation for post-mortem examination.
- Body Lifting Equipment:Hydraulic and electric hoists for safe cadaver transport within facility corridors.
- Morgue Trolleys:Wheeled transport carts with locking mechanisms for chain-of-custody security.
Volume sits with mortuary refrigerators; growth tilts toward embalming machines.
Technology:
Regulatory chemistry transitions and digital traceability mandates are bifurcating R&D investment priorities.
- Refrigeration Cooling:Conventional compressor-based cold storage dominates installed base value. Japanese METI efficiency standards and EPA AIM Act refrigerant mandates are forcing simultaneous obsolescence across US and Japanese hospital fleets.
- Digital Body Management:RFID-enabled tracking platforms automate chain-of-custody documentation for high-throughput forensic centers. US pathology labs in consolidated health networks are piloting cloud-integrated audit systems.
- Cryogenic Preservation:Ultra-low temperature storage for biobanking and disaster management scenarios.
- Vacuum Embalming:Negative-pressure fluid injection systems reducing preservative consumption.
- Portable Autopsy Systems:Mobile examination units for field deployment in mass-casualty events.
Refrigeration cooling commands current value; digital body management is expanding most quickly.
Application:
Facility accreditation standards and throughput economics determine equipment specification tiers.
- Forensic Centers:High-volume facilities require redundant refrigeration capacity and digital tracking for legal chain-of-custody. Japanese prefectural governments are expanding municipal morgue infrastructure under geriatric mortality pressure.
- Pathology Labs:Research-oriented installations demand precision temperature monitoring and cryogenic backup systems. German university hospitals are retrofitting legacy buildings with modular rack configurations.
- Funeral Homes:Family-owned and consolidated operators balancing viewing room aesthetics with refrigeration compliance.
- Medical Colleges:Training facilities requiring durable autopsy platforms for repeated student use.
- Crematoriums:Pre-cremation holding areas with short-duration refrigeration needs.
Forensic centers absorb premium pricing; pathology labs are gaining share fastest.
End User:
Budget authority and compliance liability shape procurement channel selection and service contract structures.
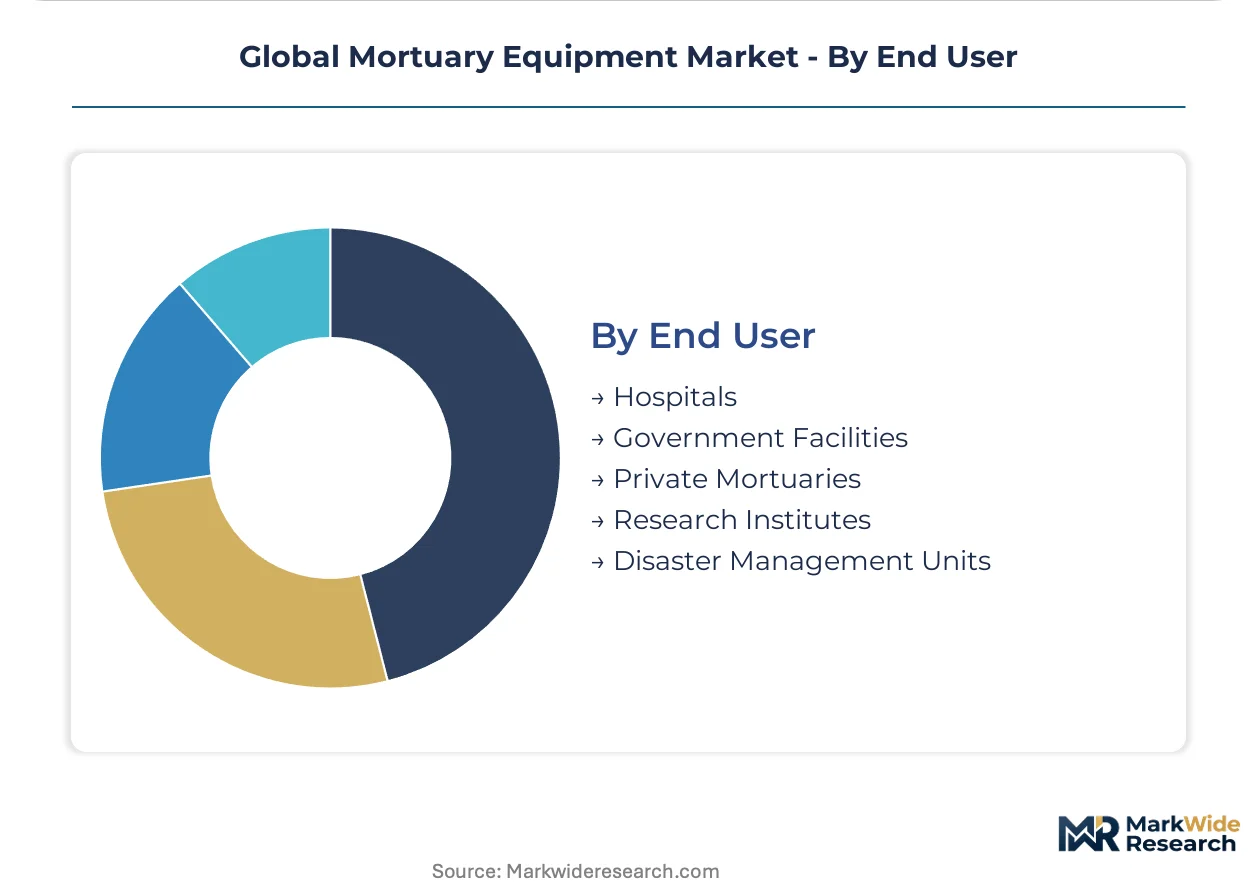
- Hospitals:Integrated health systems leverage group purchasing organization negotiating power for standardized fleet configurations. US Catholic health networks and for-profit chains affiliated with Premier and Vizient dominate enterprise procurement.
- Government Facilities:Municipal and county morgues operate under public procurement regulations with extended tender cycles. India's NABH accreditation tightening is pressuring tier-2 city infrastructure upgrades.
- Private Mortuaries:Independent operators prioritizing equipment financing flexibility over capital purchase.
- Research Institutes:Biobanking consortia requiring cryogenic preservation for longitudinal tissue studies.
- Disaster Management Units:Mobile and modular systems for mass-casualty surge capacity.
Hospitals anchor procurement volume; government facilities show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich's medical technology corridor anchors European procurement intensity for mortuary refrigeration systems, with forensic pathology departments across Bavaria driving specification upgrades ahead of regulatory deadlines.
United States
Hospital consolidation through Catholic health networks and for-profit chains affiliated with Premier and Vizient concentrates procurement volume in the Southeast and Midwest. EPA AIM Act refrigerant mandates under Section 103 are forcing systematic replacement of R-404A-dependent mortuary fleets across forensic pathology departments. Dallas-Fort Worth medical centers exemplify this transition, with health systems negotiating enterprise service contracts for standardized equipment configurations.
Germany
German university hospitals in Berlin and Heidelberg are retrofitting legacy buildings with modular rack refrigeration configurations that scale from three-body to twelve-body capacity. EU F-Gas Regulation prohibitions on refrigerants with GWP above 150 are compelling buyers toward R-290 and R-600a alternatives with redesigned safety systems. Baden-Württemberg's industrial base supplies variable-speed hermetic compressors, though concentration creates lead-time vulnerability for premium systems.
Japan
Prefectural governments in Osaka and Tokyo are expanding municipal morgue infrastructure under pressure from geriatric mortality volumes. METI energy-efficiency standards for commercial refrigeration constrain equipment design flexibility, forcing simultaneous obsolescence across hospital fleets. Kansai region pathology labs are piloting cryogenic backup systems for research-oriented installations requiring precision temperature monitoring.
India
Private hospital chains in Lucknow, Jaipur, and Kochi lack compliant mortuary infrastructure as NABH accreditation standards tighten for tier-2 cities. The country's national medical device regulator is elevating conformity assessment requirements for temperature-monitoring systems, extending time-to-market for digital-integrated units. Maharashtra's healthcare procurement hubs are emerging as distribution gateways for South Asian markets.
France
French forensic centers in Lyon and Marseille require redundant refrigeration capacity and digital tracking for legal chain-of-custody compliance. ANSM medical device oversight intersects with EU MDR requirements to elevate certification expenses for suppliers. Île-de-France hospital networks are adopting scalable mortuary configurations that align capital deployment with census fluctuations rather than peak-load overbuilding.
Global Mortuary Equipment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across refrigerant compliance and digital integration capabilities, with certification-ready architectures commanding pricing power in European and North American procurement. The vendor base organizes into three tiers: cryogenic specialists anchoring research institute relationships, modular refrigeration fabricators serving hospital replacement cycles, and regional assemblers competing on financing flexibility for funeral home operators. Consolidation through group purchasing organization contracting and refrigerant chemistry transitions are the dominant competitive vectors reshaping qualification requirements.
Among US-based life science conglomerates, Thermo Fisher Scientific occupies a position exemplifying the cryogenic-specialist archetype through its forensic and research channel presence. LEEC represents UK-based manufacturing scale across modular mortuary refrigerator lines serving export markets. Mopec sits within the specialized-configurations tier, with its positioning reflecting autopsy platform supply for medical colleges and pathology laboratories.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Mopec |
| LEEC |
| Ferno |
| KUGEL Medical |
| Mortech Manufacturing |
| HYGECO |
| Roftek |
| SM Scientific Instruments |
| Others |
Supply & Pricing Matrix
Stainless steel and copper commodity volatility cascades through mortuary equipment pricing tiers, compressing margins for European fabricators sourcing German compressors while amplifying cost premiums for low-GWP refrigerant-compliant systems sold to French and German hospital buyers.
Pricing Analysis
Uptime-guaranteed service contracts anchor value-based pricing for mortuary refrigeration systems sold to consolidated US health networks. Three-tier pricing structure across premium, standard, and economy levels separates cryogenic-capable units with digital traceability from basic R-290 retrofit models and non-compliant legacy inventory. Cost compression in the standard tier is intensifying because copper input volatility coincides with EU MDR certification expenses. Government facilities in India and Japan exhibit highest price sensitivity due to extended tender cycles, while biobanking consortia accept premium positioning for cryogenic backup systems.
Supply Chain Analysis
Single-source vulnerability sits with Baden-Württemberg's variable-speed hermetic compressor suppliers serving premium refrigeration OEMs. Manufacturing concentration in Germany, China, and the United States draws from stainless steel sheet, copper tubing, and refrigerant gas feedstocks. Tariff exposure on Chinese refrigeration components creates lead-time vulnerability for modular rack system assemblers. Distribution runs through group purchasing organizations for US hospital systems and direct manufacturer relationships for European pathology labs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mortuary equipment procurement is consolidating around refrigerant-compliant, digitally integrated suppliers as EU F-Gas and EPA AIM Act deadlines filter non-compliant fabricators from transatlantic markets.
For Market Incumbents: Extend certification-ready product architectures across R-290 and R-600a refrigerant platforms to capture replacement cycles forced by regulatory phase-downs. Deepen backward integration into compressor supply relationships to mitigate Baden-Württemberg supply concentration risk. Anchor hospital GPO contracts with embedded digital body management modules to lock out modular competitors.
For New Entrants and Emerging Players: Enter via India's tier-2 private hospital chains in Lucknow, Jaipur, and Kochi where NABH accreditation tightening outpaces compliant infrastructure supply. Target municipal morgue expansion in Japanese prefectures facing geriatric mortality pressure. Lead with financing-flexible lease structures rather than capital purchase to bypass incumbent service contract entrenchment.
For Investors and Strategic Acquirers: EPA refrigerant mandate enforcement acceleration is the leading indicator that replacement cycle velocity will compress vendor qualification windows and reward pre-certified scale players. Acquisition targets should display EU MDR technical documentation readiness and established GPO contracting relationships with Premier or Vizient. Watch for Japanese METI efficiency standard revisions as signal for simultaneous fleet obsolescence events.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Transition | Pre-certification to R-290 and R-600a chemistry secures EU F-Gas compliance ahead of 2025-2030 phase-down deadlines. |
| Digital Body Management Integration | RFID-enabled chain-of-custody modules differentiate premium positioning for high-throughput forensic centers in France and the United States. |
| Modular Rack System Expansion | Scalable three-body to twelve-body configurations align capital deployment with census fluctuations in German university hospitals. |
| GPO Contract Consolidation | Enterprise service agreements with Catholic health networks and for-profit chains concentrate procurement volume in the US Southeast and Midwest. |
| Tier-2 City Infrastructure Development | NABH-compliant mortuary equipment addresses accreditation gaps in India's underserved private hospital markets. |
Research Methodology
Trade association filings, EU regulatory databases, and hospital procurement records formed the secondary backbone, cross-referenced against primary interviews with biomedical engineering directors, GPO contracts managers, refrigeration OEM product planners, and pathology lab operations heads. Bottom-up equipment shipment tallies by product category and refrigerant chemistry were reconciled with top-down healthcare capital expenditure forecasts across the analysis window.
Historical trendline analysis of replacement cycle patterns and regulatory compliance cost trajectories informed the projection framework. Segmentation modeling incorporated product type, refrigerant technology tier, application setting, and end-user procurement channel across the projection horizon. CAGRs were derived from fitted growth curves applied to equipment unit economics and service contract value pools, with specific weighting for EPA AIM Act and EU F-Gas regulatory enforcement timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under refrigerant chemistry transition delays or copper price spike scenarios. Deviation in Japanese prefectural morgue expansion funding would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Tanning Units Market
Medical Equipment
Next Generation Centrifuge Market
Medical Equipment
Home Medical Equipment Market
Medical Equipment
Portable Steam Autoclave Market
Medical Equipment
Medical Gas Cylinders Market
Medical Equipment
Global Blood Purification Equipment Market
Medical Equipment
Proctologic Table Market
Medical Equipment
Global Medical Lighting Technologies Market
Medical Equipment
Medical Automation Market
Medical Equipment
Medical Ultrasonic Cleaners Market
Medical Equipment
Chile Radiotherapy Market
Medical Equipment
Refurbished MRI Systems Market
Medical Equipment
X-Ray Generator Market
Medical Equipment
Cell Culture Incubator Market
Medical Equipment
Life Support Systems Market
Medical Equipment
Contact Type Liquid Handling Workstation Market