
 Europe Mortgage / Loan Broker Market | 2026-2036
Europe Mortgage / Loan Broker Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Mortgage / Loan Broker Market Analysis
The EU Mortgage Credit Directive is hardening compliance thresholds for cross-border intermediation. Hypoport SE leverages its digital infrastructure to automate lender matching across German-speaking markets. Interhyp AG anchors its position through exclusive partnerships with regional savings banks. Moltiply Group competes on price transparency tools that reduce borrower search costs.
A mortgage or loan broker functions as a regulated intermediary that matches borrowers with suitable credit products from multiple lenders, earning commission or fees for placement services rather than balance-sheet lending. The broker assesses creditworthiness, compares terms across fixed rate, variable rate, and interest-only structures, and manages documentation through to completion. Independent brokers currently occupy the largest share of intermediary volume, while online brokers represent the fastest-expanding channel due to lower customer acquisition costs and 24-hour accessibility. First-time buyers dominate client-type demand, though refinancing activity creates episodic volume spikes when central bank rates shift.
The European Banking Authority coordinates national competent authorities in enforcing the Mortgage Credit Directive's responsible lending standards. EBA guidelines on remuneration disclosure and conflicts of interest directly shape how brokers structure fee models and lender panels. GDPR constraints on customer data handling add operational complexity to lead-generation and retention systems. Stakeholders must monitor how the EU Green Deal's energy-efficiency mortgage labeling requirements redirect broker expertise toward renovation financing products.
Market Dynamics
The European mortgage brokerage sector faces a structural inflection as the EU Mortgage Credit Directive's revised conduct standards force intermediaries to rebuild compliance architectures while digitizing client acquisition channels.
Growth Catalysts
- First-time buyer expansion:Younger cohorts across Germany, France, and the United Kingdom increasingly prefer broker-mediated comparisons over direct bank applications, expanding addressable volume.
- GDPR-compliant automation:Lead-generation platforms that embed consent-management protocols reduce customer acquisition costs while satisfying data protection mandates.
- Refinancing cyclicality:Central bank rate movements in the eurozone trigger episodic refinancing waves that brokers capture through rate-alert systems.
Market Restraints
- Commission compression:Lender panels in saturated markets squeeze per-loan remuneration, pressuring revenue per transaction for independent intermediaries.
- Regulatory fragmentation:National competent authorities interpret the Mortgage Credit Directive's responsible lending standards unevenly, raising cross-border operational complexity.
- Fintech direct lending:Balance-sheet lenders with proprietary digital interfaces bypass brokerage layers for prime-credit borrowers.
Strategic Opportunities
- Green renovation financing:The EU Green Deal's energy-efficiency mortgage labeling requirements position brokers to advise on renovation-linked products.
- Eastern European penetration:Broker density remains low in Poland and Romania relative to Western European benchmarks, offering whitespace for platform expansion.
- API-enabled lender connectivity:Real-time product aggregation through open banking interfaces differentiates intermediaries against static comparison sites.
Industry Challenges
- Compliance talent scarcity:Firms struggle to recruit professionals versed simultaneously in mortgage underwriting, GDPR protocols, and the Mortgage Credit Directive's disclosure requirements.
- Legacy system integration:Established brokers face technical debt when connecting proprietary CRM systems to lender decision engines and open banking APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Mortgage / Loan Broker Market |
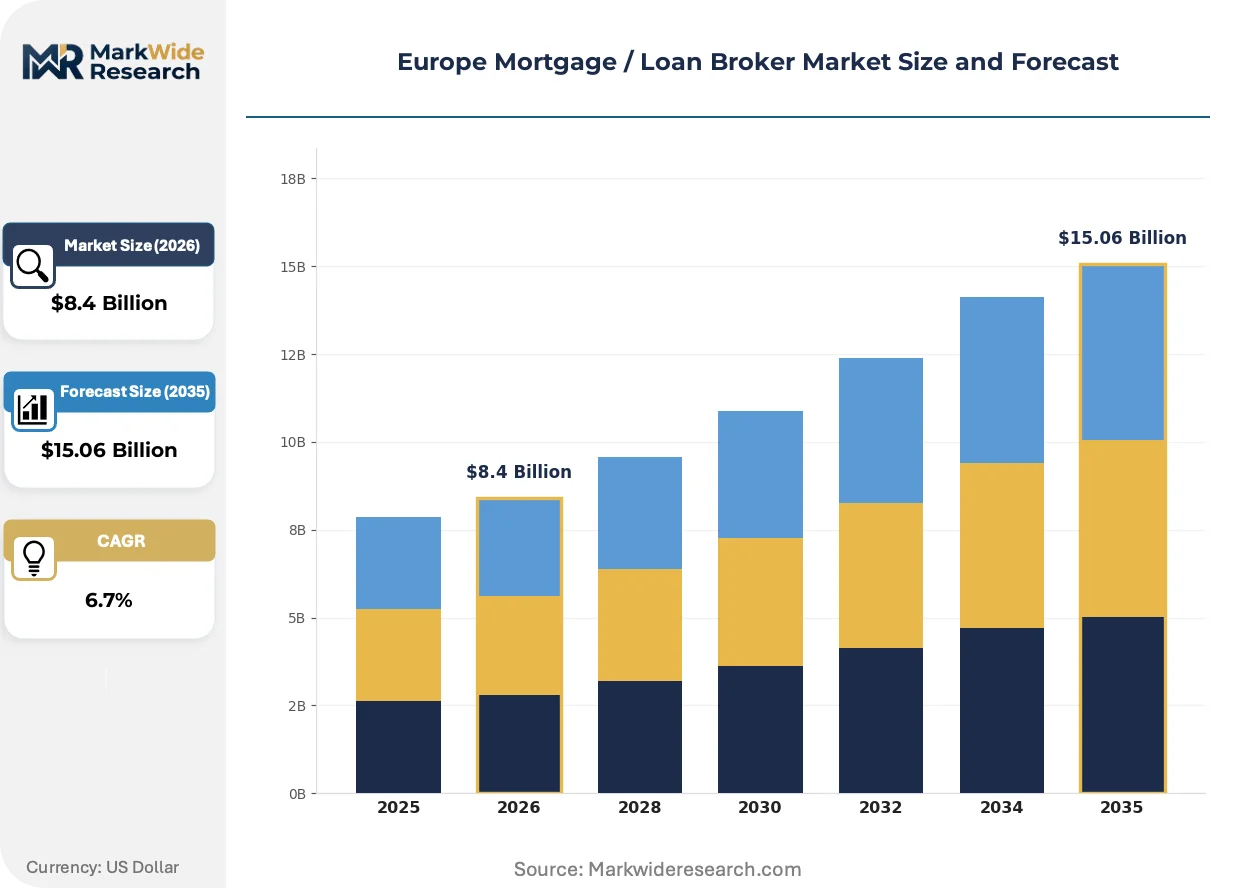
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Broker Type: Independent Brokers, Bank Brokers, Online Brokers, Hybrid Brokers Loan Type: Fixed Rate Loans, Variable Rate Loans, Interest-Only Loans, Reverse Mortgages Client Type: First-Time Buyers, Homeowners, Investors, Refinancers Service Offering: Consultation, Loan Comparison, Application Assistance, Financial Advisory |
| Companies Covered | Hypoport SE, Interhyp AG, Moltiply Group, London & Country Mortgages, Mortgage Advice Bureau, Dr. Klein, CAFPI, Meilleurtaux, Connells Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Mortgage / Loan Broker Market Emerging Trajectories
Digitization is redrawing competitive boundaries across European mortgage intermediation, compressing search costs while elevating transparency expectations among borrowers.
Open banking infrastructure is decentralizing how borrowers discover and compare credit products. First-time buyers in the United Kingdom and Germany access real-time rate feeds through API-connected platforms rather than sequential bank consultations. This disintermediation of traditional branch networks is compressing decision timelines from weeks to hours.
The EU Green Deal's energy-efficiency mortgage labeling requirements are redirecting product development priorities. Lenders must now classify renovation-linked loans against carbon-reduction benchmarks, forcing brokers to master technical eligibility criteria. German and French markets exhibit the earliest compliance velocity as national building codes tighten.
Channel preferences among younger cohorts are fragmenting traditional brokerage models. Digital-native borrowers in Scandinavia and the Netherlands complete entire application journeys through mobile-optimized platforms, displacing phone-based advice for standard cases. This behavioral shift pressures hybrid intermediaries to rebalance human advisor deployment toward complex cases.
Europe Mortgage / Loan Broker Market Segmentation
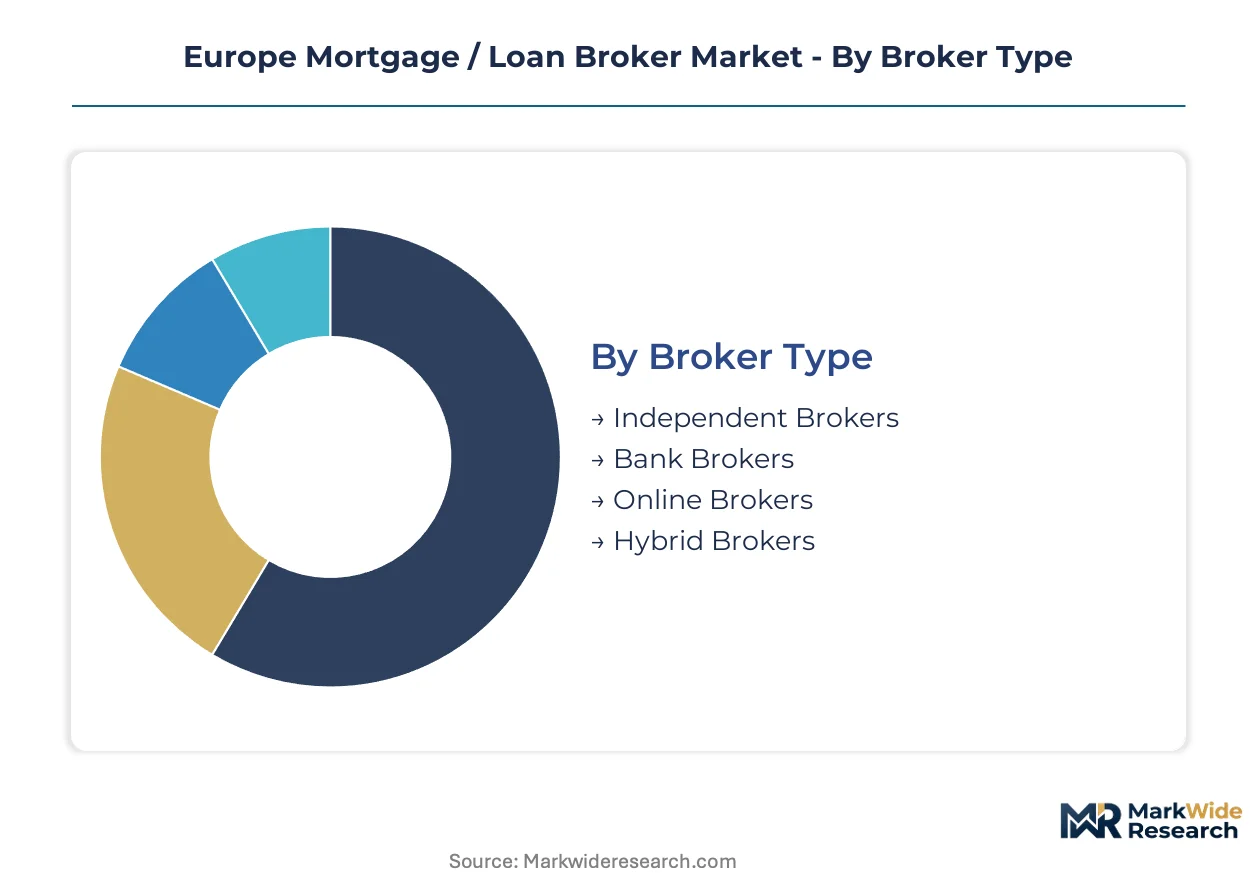
Segmentation reveals how broker business models diverge across client sophistication, regulatory exposure, and technology intensity. Each axis exposes distinct margin structures and compliance burdens that shape competitive positioning across European markets.
Broker Type:
Digital infrastructure and regulatory capital requirements differentiate how intermediaries capture borrower relationships across the continent.
- Independent Brokers:Unaffiliated intermediaries maintain broad lender panels and owe no fiduciary duty to single institutions. Their dominance in the United Kingdom and Germany reflects borrower preference for unbiased product comparison, though commission disclosure rules under the Mortgage Credit Directive compress fee flexibility.
- Online Brokers:API-connected platforms automate lender matching through real-time rate aggregation. Scandinavian markets exhibit the deepest penetration here, where mobile-native borrowers complete entire journeys without human intervention, reducing acquisition costs substantially.
- Bank Brokers:Captive intermediaries representing single institutions or consolidated banking groups. These dominate in France where regional mutual banks embed brokerage within branch networks, constraining borrower choice but simplifying documentation.
- Hybrid Brokers:Models blending digital self-service with human advisory for complex cases. Dutch and Belgian markets favor this structure, where regulatory advice requirements for high-loan-to-value products mandate qualified personnel involvement.
Mature deployment sits with Independent Brokers. Newer deployment is concentrated in Online Brokers.
Loan Type:
Interest rate risk allocation between borrower and lender determines where brokers add advisory value versus pure execution.
- Fixed Rate Loans:Rate certainty for multi-year terms dominates German-speaking markets where borrowers prioritize payment stability. Brokers here compete on access to extended-fixation products from Pfandbrief-backed lenders.
- Variable Rate Loans:Euribor-linked products transfer rate risk to borrowers and concentrate in Spain and Italy where central bank tightening has triggered migration toward shorter fixation periods.
- Interest-Only Loans:Structures deferring principal repayment appeal to buy-to-let investors in the United Kingdom, though the European Banking Authority's responsible lending guidelines restrict availability for owner-occupiers.
- Reverse Mortgages:Equity-release products for elderly homeowners remain niche outside the United Kingdom and Netherlands, constrained by cultural aversion to debt encumbrance in retirement and complex consumer protection requirements.
Volume leadership belongs to Fixed Rate Loans. Steepest expansion trajectory appears in Variable Rate Loans as monetary policy normalizes.
Client Type:
Life-cycle position and financial sophistication determine service intensity and cross-selling potential for brokerage operations.
- First-Time Buyers:Borrowers lacking established credit histories or deposit accumulation dominate volume across France, Germany, and the United Kingdom. These clients demand highest advisory intensity around affordability assessments and government subsidy schemes.
- Refinancers:Existing mortgage holders seeking rate reduction or term restructuring generate episodic volume spikes when central bank policy shifts. Their lower acquisition costs and established documentation make them margin-accretive despite smaller absolute numbers.
- Investors:Buy-to-let and commercial property purchasers operate across stricter underwriting criteria and higher interest rate tiers. Stress-testing requirements under the Mortgage Credit Directive's responsible lending standards elevate documentation complexity.
- Homeowners:Established owner-occupiers seeking additional borrowing for renovation or consolidation represent stable repeat business, particularly where energy-efficiency mortgage labeling under the EU Green Deal creates product specialization opportunities.
Revenue concentration rests with First-Time Buyers. Fastest share gains are emerging among Refinancers as rate volatility persists.
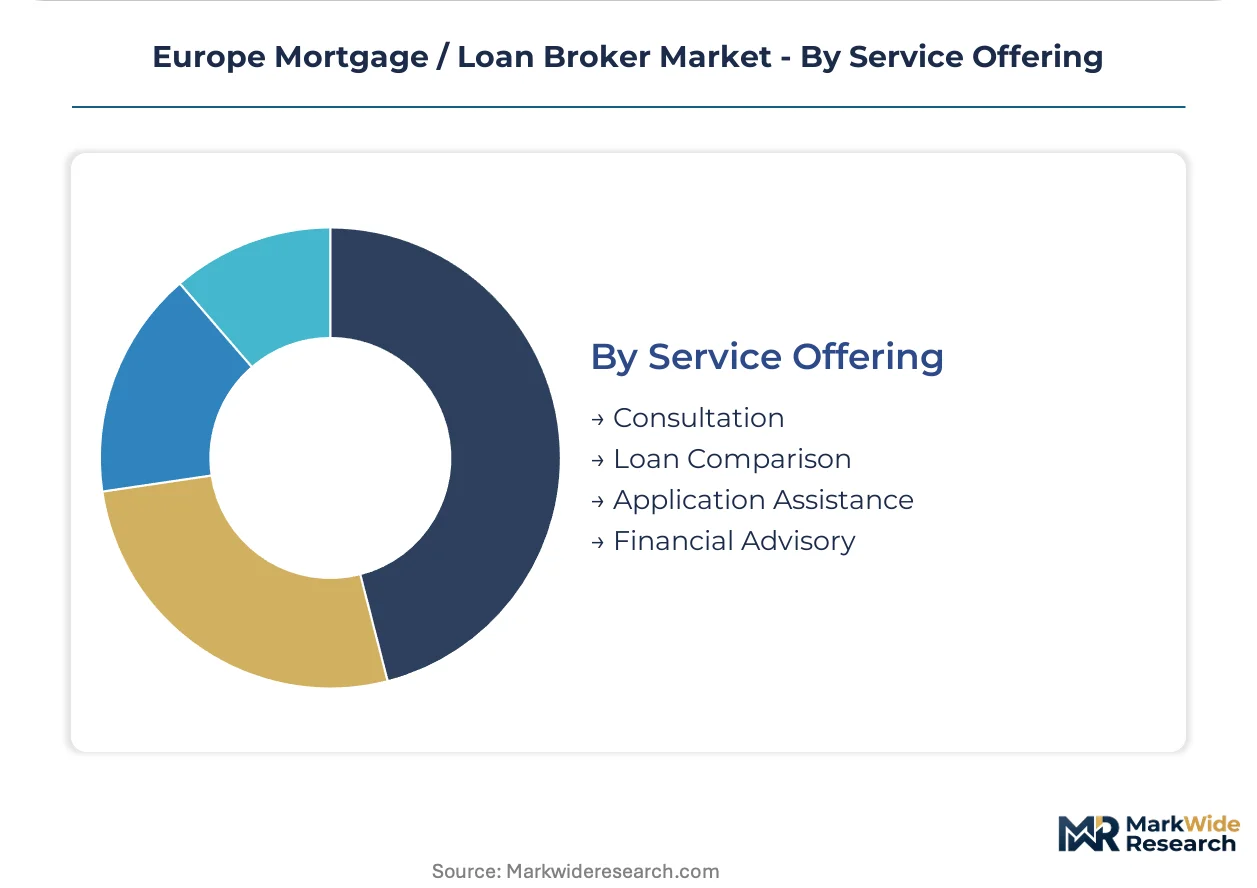
Service Offering:
Value-chain position determines fee model sustainability and vulnerability to platform disintermediation.
- Loan Comparison:Product aggregation and rate ranking constitute the core brokerage function, now largely automated through open banking interfaces. This service faces commoditization pressure as static comparison sites expand real-time connectivity.
- Application Assistance:Documentation compilation, lender submission, and completion management retain human involvement despite digitization. Polish and Romanian markets exhibit particular demand here given less standardized property registration systems.
- Financial Advisory:Holistic guidance spanning insurance, savings, and tax optimization commands premium fees but requires MiFID II licensing in most jurisdictions. This offering concentrates among established independent brokers in the United Kingdom and Ireland.
- Consultation:Preliminary eligibility assessment and product education represents the entry point for broker relationships, increasingly delivered through chatbot interfaces before human handoff for complex cases.
Fee sustainability is strongest in Financial Advisory. Automation penetration is deepest in Loan Comparison.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt Rhine-Main metropolitan region concentrates Germany's digital mortgage infrastructure, while London's regulatory sandbox environment shapes fintech brokerage models across northwestern Europe.
Germany
First-time buyer demand in Berlin and Munich drives platform expansion, with borrowers favoring extended fixed-rate products from Pfandbrief-backed lenders. BaFin enforces strict remuneration disclosure under the Mortgage Credit Directive's national implementation. The Frankfurt cluster hosts Hypoport SE's API infrastructure and Interhyp AG's savings bank partnerships.
United Kingdom
Refinancing waves following Bank of England rate decisions generate episodic volume concentration in London and the Southeast. The Financial Conduct Authority's Consumer Duty rules tighten advice standards for high-loan-to-value products. Manchester and Birmingham emerge as secondary hubs for hybrid advisory models blending digital self-service with qualified personnel.
France
Regional mutual banks embed captive brokerage within branch networks across Île-de-France and Auvergne-Rhône-Alpes, constraining independent intermediary penetration. The Autorité de Contrôle Prudentiel et de Résolution monitors compliance with EU responsible lending standards. Paris-based CAFPI and Meilleurtaux anchor the price-comparison segment.
Netherlands
Mobile-native borrowers in Amsterdam and Rotterdam complete entire application journeys through digital platforms, displacing phone-based advice for standard cases. The Dutch Authority for the Financial Markets mandates advice requirements for complex mortgage structures. The Randstad corridor exhibits the deepest online brokerage penetration in continental Europe.
Poland
Broker density remains low relative to Western European benchmarks, with Warsaw and Kraków showing early platform expansion. The Polish Financial Supervision Authority applies uneven interpretations of EU conduct standards. Application assistance services retain particular demand given less standardized property registration systems in emerging metropolitan markets.
Europe Mortgage / Loan Broker Market Vendor Landscape
German producers anchor the technology tier; UK specialists hold the advisory-intensive segment. The vendor base splits between consolidated digital platforms and fragmented independent networks. Three archetypes dominate: API-connected aggregators, hybrid advisory firms, and captive bank intermediaries. Competitive moves concentrate on open banking integration and geographic expansion into Eastern European whitespace.
Within the digital platform tier, Hypoport SE exemplifies infrastructure-led scaling across German-speaking markets. Interhyp AG occupies a position anchored through exclusive regional savings bank partnerships. London & Country Mortgages represents the advisory-intensive archetype in the UK hybrid segment. These three entities illustrate how technology intensity and distribution architecture determine competitive positioning under tightening EU conduct standards.
| Leading Market Players |
|---|
| Hypoport SE |
| Interhyp AG |
| Moltiply Group |
| London & Country Mortgages |
| Mortgage Advice Bureau |
| Dr. Klein |
| CAFPI |
| Meilleurtaux |
| Connells Group |
| Others |
Supply Flow & Price Mechanics
API-enabled lender connectivity is compressing search costs while redistributing pricing power toward platforms with real-time data feeds, concentrating intermediary margins in Germany and the United Kingdom where infrastructure investments are deepest.
Pricing Analysis
Short lead-time execution commands premium placement fees from lenders seeking rapid pipeline fill, while spot-rate comparison tools erode margins for static intermediaries. Commission-based remuneration dominates, with fee differentiation driven by loan complexity tier and GDPR-compliant automation depth. Pricing pressure intensifies as fintech direct lenders bypass brokerage layers for prime-credit borrowers. First-time buyers exhibit highest price sensitivity; high-net-worth refinancers tolerate premium advisory fees.
Supply Chain Analysis
Direct-to-lender API channels handle high-volume standard cases from Germany, France, and the United Kingdom, while hybrid advisory networks manage complex documentation for cross-border applications. Core inputs encompass credit bureau data, open banking feeds, and property valuation services. Single-source vulnerability concentrates in proprietary lender decision engines. Distribution runs through regional savings bank partnerships in German-speaking markets and captive mutual bank networks in France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
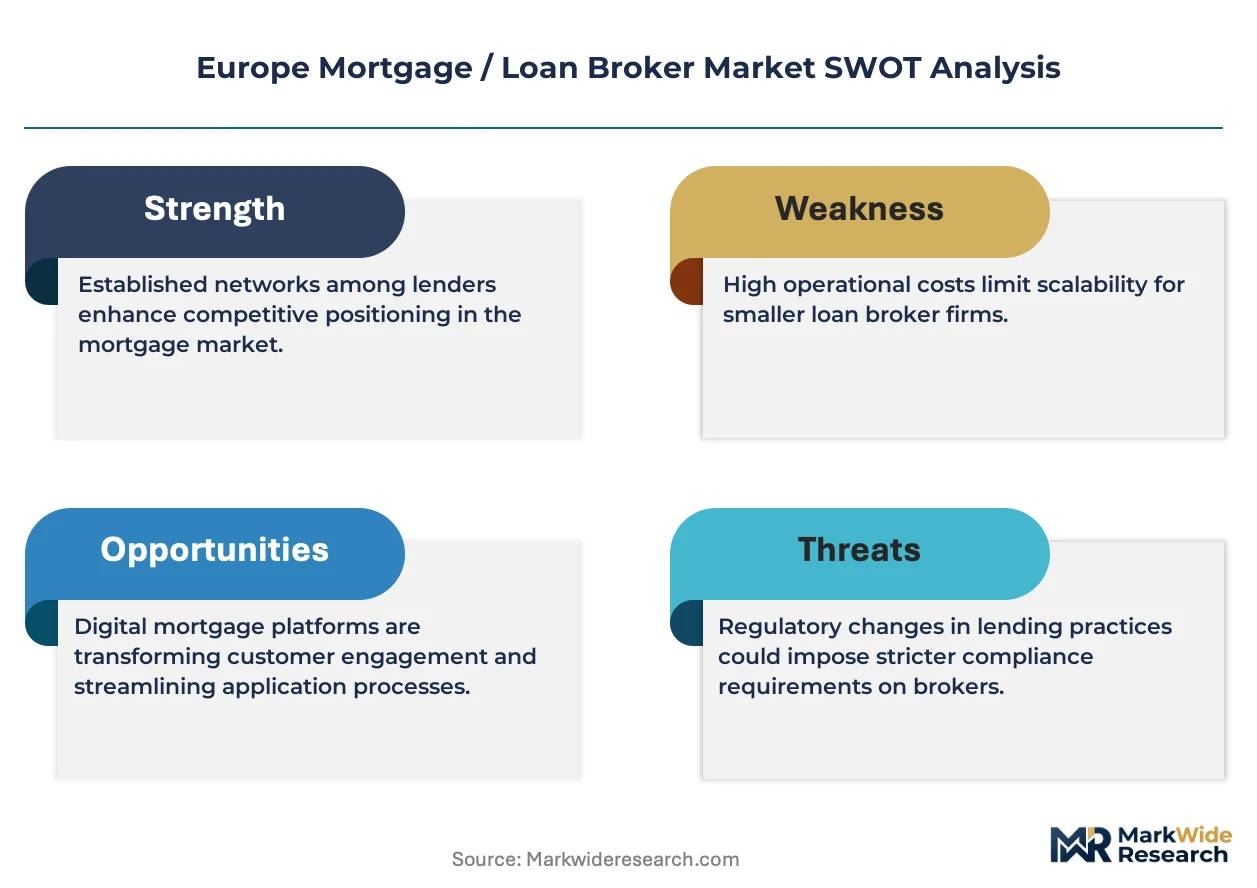
The EU Mortgage Credit Directive's revised conduct standards function as a cost-of-compliance moat, elevating capital requirements and disclosure burdens that filter out undercapitalized intermediaries while rewarding established platforms with compliant architectures.
For Market Incumbents: Hedge commission compression by deepening API integrations with Pfandbrief-backed lenders in German-speaking markets and acquiring compliance talent versed in GDPR protocols and EBA disclosure requirements. Consolidate regional savings bank partnerships before digital-native entrants capture Eastern European whitespace.
For New Entrants and Emerging Players: Mobile-optimized self-service platforms offer the lowest customer acquisition cost route into Poland and Romania, where broker density trails Western benchmarks. Target application assistance services in markets with less standardized property registration systems. Anchor go-to-market strategy around energy-efficiency mortgage labeling advisory under the EU Green Deal.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to consolidated banking groups seeking digital distribution capabilities. Five-to-ten-year viability favors platforms with open banking infrastructure and hybrid advisory licensing. Monitor central bank rate normalization velocity as the signal for refinancing wave timing and volume inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| API-Enabled Lender Connectivity | Real-time rate aggregation through open banking interfaces differentiates against static comparison sites in Germany and Scandinavia. |
| Green Renovation Financing Specialization | EU Green Deal energy-efficiency labeling requirements redirect broker expertise toward carbon-reduction-linked products. |
| Eastern European Geographic Expansion | Low broker density in Poland and Romania offers whitespace for platform expansion with localized application assistance. |
| Hybrid Advisory Model Development | Blending digital self-service with human advisory satisfies Dutch and Belgian regulatory requirements for complex cases. |
| GDPR-Compliant Automation Investment | Consent-management protocols embedded in lead-generation platforms reduce acquisition costs while satisfying data protection mandates. |
Methodological Framework
Independent corroboration across mortgage broker executives, regulatory compliance officers, and lender product managers underwrites the qualitative findings. Secondary validation draws from European Banking Authority guidelines, national competent authority enforcement actions, GDPR implementation case law, and property transaction databases. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators.
Comparable-period anchoring to pre-pandemic transaction volumes and post-Directive implementation phases structures the forecast window. Segmentation dimensions span broker type, loan structure, client life-cycle position, and service intensity tier. CAGRs derive from lender panel expansion rates and digital channel penetration curves. Forecast inputs incorporate central bank policy trajectory and first-time buyer cohort size projections.
The model holds under stable regulatory interpretation across EU member states; deviation in national competent authority enforcement stringency would shift competitive positioning. Forecasts reflect assumptions on open banking adoption velocity and GDPR compliance cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Europe Auto Loan Market
Loans and Leasing
Home Equity Lending Market
Loans and Leasing
Renting and Leasing Test and Measurement Equipment Market
Loans and Leasing
Russia Auto Loan Market
Loans and Leasing
Europe Car Loan Market
Loans and Leasing
Europe Syndicated Loans Market
Loans and Leasing
Asia-Pacific Motorcycle Loan Market
Loans and Leasing
Mexico Home Equity Lending Market
Loans and Leasing
Germany Auto Loan Market
Loans and Leasing
Solar Lease Service Market
Loans and Leasing
US Mortgage/Loan Brokers Market
Loans and Leasing
Working Capital Loan Market
Loans and Leasing
Europe Motorcycle Loan Market
Loans and Leasing
France Mortgage/Loan Brokers Market
Loans and Leasing
Global Revenue-Based Financing Market
Loans and Leasing
Canada Home Equity Lending Market