
 Digital Mobile X-Ray Products Market | 2026-2036
Digital Mobile X-Ray Products Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Mobile X-Ray Products Market Outlook
China is reshaping manufacturing economics for digital mobile X-ray components through expanded domestic flat-panel detector production. GE Healthcare leverages captive supply chains for amorphous silicon detectors to sustain cost advantages across portable system lines. Siemens Healthineers anchors European demand through specialized mobile C-arm configurations for hybrid operating rooms. Fujifilm Holdings Corporation differentiates via proprietary image processing algorithms that reduce retake rates in bedside trauma protocols.
Digital mobile X-ray products comprise self-contained radiographic systems mounted on motorized or manual transport chassis, integrating flat-panel detectors with wireless DICOM transmission at spatial resolutions exceeding 2.5 line pairs per millimeter. These systems enable image acquisition at patient location without fixed installation infrastructure, serving critical care units, emergency departments, and isolation wards where patient transport risks outweigh diagnostic urgency. Wireless X-ray devices command expanding share as battery energy density improvements extend cordless operation beyond eight hours, while direct radiography technology leads detector segment value due to superior dose efficiency and immediate image availability. Emergency services application remains the largest revenue pool, though bedside imaging grows fastest as hospital-at-home programs expand reimbursable remote diagnostics.
FDA 510(k) premarket notification requirements govern U.S. device commercialization, while the EU Medical Device Regulation mandates notified body conformity assessment for CE marking access across European member states. Japan's PMDA enforces JIS standards for electromagnetic compatibility and radiation leakage in mobile fluoroscopy deployments. Stakeholders must monitor evolving cybersecurity guidance from FDA and post-market surveillance obligations under MDR Article 83 as connected-device portfolios expand.
Market Dynamics
Wireless flat-panel detector technology is compressing replacement cycles for aging mobile fluoroscopy equipment across acute care networks, while hospital consolidation concentrates purchasing power among integrated delivery networks demanding standardized fleet configurations.
Growth Catalysts
- Point-of-Care Mandates:CMS reimbursement policies for hospital-at-home programs are expanding reimbursable remote diagnostics, pulling digital mobile X-ray units into ambulatory settings previously served by fixed-room systems.
- Battery Energy Density Gains:Lithium-silicon anode chemistry is extending cordless operation beyond eight hours, eliminating tethering constraints in isolation wards and emergency departments.
- FDA 510(k) Pathway Efficiency:Streamlined premarket notification for software-as-medical-device updates is accelerating iterative algorithm deployment for dose optimization.
Market Restraints
- Flat-Panel Detector Supply Concentration:Amorphous silicon substrate production clusters in East Asian foundries, exposing OEMs to single-source vulnerability for core imaging components.
- EU MDR Conformity Assessment Bottlenecks:Notified body capacity constraints are extending CE marking timelines for wireless DICOM transmission modules, delaying European commercialization.
- Fixed Digital Radiography Substitution:Retrofit detector panels for existing analog rooms offer capital expenditure avoidance, pressuring greenfield mobile unit demand in budget-constrained facilities.
Strategic Opportunities
- India Diagnostic Infrastructure Expansion:Ayushman Bharat Health and Wellness Centers are procuring portable radiography for tier-2 and tier-3 cities lacking fixed installation infrastructure.
- Hybrid Operating Room Integration:Surgical suites are converging mobile C-arm fluoroscopy with robotic navigation platforms, creating demand for specialized articulating detector configurations.
- Cybersecurity Certification Differentiation:FDA premarket guidance on connected device security is creating first-mover advantage for manufacturers embedding hardware-based encryption modules.
Industry Challenges
- Medical Physics Workforce Scarcity:Qualified clinical medical physicists for acceptance testing and annual compliance surveys are in short supply, extending deployment timelines for new unit installations.
- Legacy PACS Integration Complexity:Hospital information systems running outdated DICOM versions require middleware adaptation, inflating implementation costs and technical support burdens.
- Radiation Safety Training Gaps:Bedside imaging protocols in intensive care units demand specialized operator certification that nursing staff often lack, elevating liability exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Mobile X-Ray Products Market |
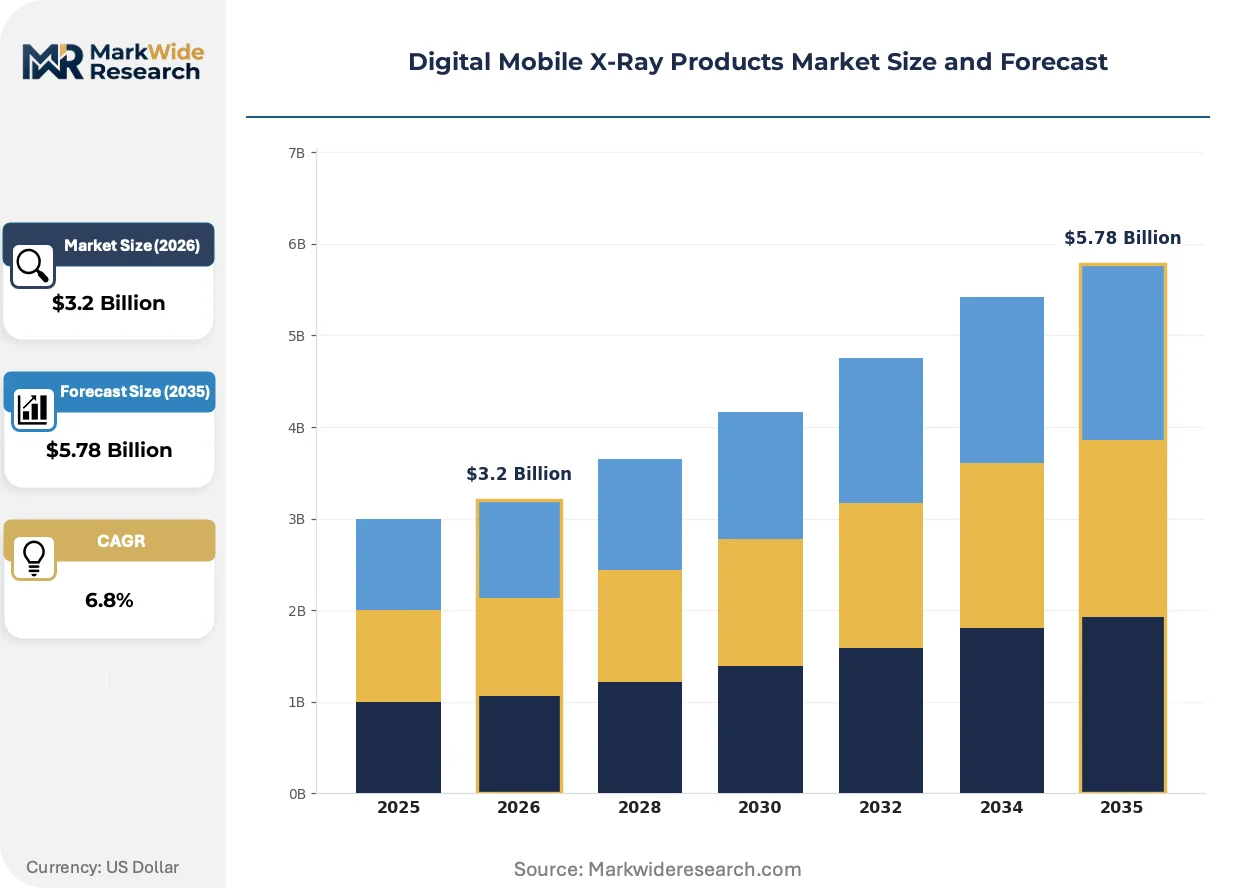
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable X-Ray Systems, Wireless X-Ray Devices, Digital Radiography Systems, Fluoroscopy Units End User: Hospitals, Clinics, Diagnostic Centers, Home Care Settings Technology: Computed Radiography, Direct Radiography, Hybrid Systems, Mobile Radiography Application: Emergency Services, Trauma Imaging, Patient Transport, Bedside Imaging |
| Companies Covered | GE Healthcare, Siemens Healthineers, Fujifilm Holdings Corporation, Canon Medical Systems, Koninklijke Philips N.V., Shimadzu Corporation, Carestream Health, MinXray, Inc., Hitachi, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Mobile X-Ray Products Market Strategic Shifts
Detector technology convergence with artificial intelligence inference engines is redefining image acquisition workflows, compressing the gap between exposure and diagnostic-ready output while redistributing computational load across edge and cloud architectures.
Dual-layer flat-panel detectors is hybridizing photon-counting sensitivity with conventional energy-integrating economics, enabling spectral imaging at bedside without dedicated CT capability. Emergency departments in Level I trauma centers are piloting these configurations for occult fracture detection. The technology is hybridizing hardware cost structures, forcing OEMs to recalibrate tiered pricing across premium and standard portable lines.
EU Medical Device Regulation Article 83 post-market surveillance obligations are mandating systematic collection of real-world performance data for wireless transmission modules. Manufacturers must now embed automated telemetry for cybersecurity incident reporting. European notified bodies are prioritizing technical documentation demonstrating continuous vulnerability monitoring, reshaping quality management system investments.
Integrated delivery networks are consolidating vendor contracts into multi-year fleet standardization agreements, displacing transactional equipment purchasing. Group purchasing organizations are aggregating demand across affiliated hospitals, extracting volume pricing concessions for detector calibration and preventive maintenance bundles. This concentration is most visible in United States metropolitan markets where hospital consolidation has reduced independent facility counts by half over the past decade.
Digital Mobile X-Ray Products Market Segmentation
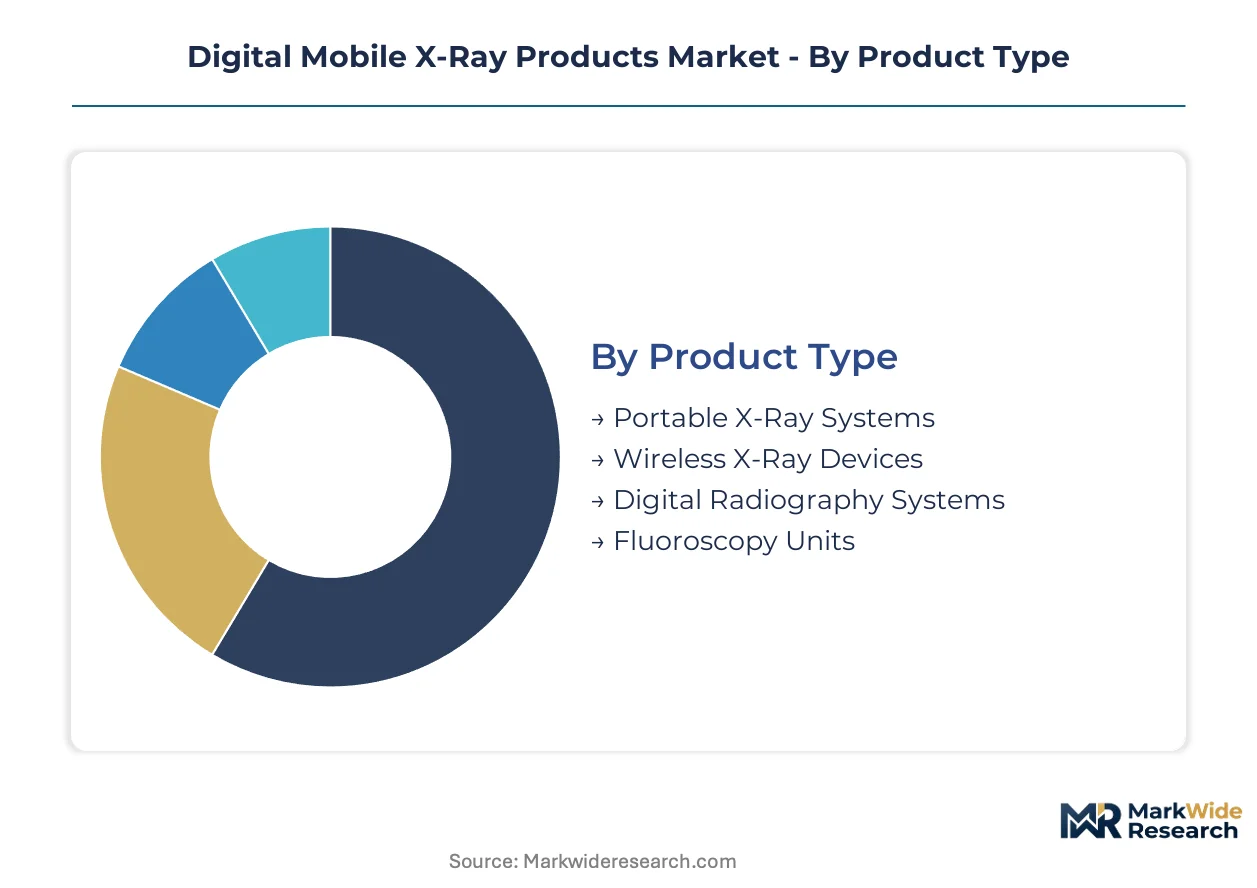
Segmentation in digital mobile X-ray products reveals how technology maturity and care setting economics allocate capital across healthcare infrastructure. Understanding these divides exposes where procurement power concentrates and which configurations face substitution pressure from adjacent modalities.
Product Type:
Mature motorized chassis designs now compete against emerging cordless architectures as battery chemistry advances reshape deployment economics.
- Portable X-Ray Systems:Self-contained units on motorized transport chassis integrate flat-panel detectors with onboard generators, serving intensive care units and emergency departments where patient stability precludes transport. Demand concentrates in United States acute care networks consolidating fleet standards under multi-year vendor agreements.
- Wireless X-Ray Devices:Battery-powered detectors eliminate tethering constraints, enabling isolation ward imaging and bedside trauma protocols without electrical infrastructure. Lithium-silicon anode improvements extending cordless operation beyond eight hours are pulling procurement toward these configurations in hospital-at-home programs.
- Digital Radiography Systems:Fixed-installation detectors with portable acquisition software bridge retrofit markets.
- Fluoroscopy Units:Mobile C-arm configurations serve hybrid operating rooms and interventional suites.
Portable X-Ray Systems handle the majority of throughput; Wireless X-Ray Devices are expanding most quickly on share.
End User:
Procurement authority fragments across facility scale, with integrated delivery networks extracting volume pricing distinct from independent clinic purchasing.
- Hospitals:Level I trauma centers and academic medical centers anchor demand for premium detector resolution and AI-integrated workflow engines, with emergency medicine departments driving replacement cycles for aging mobile fluoroscopy equipment.
- Diagnostic Centers:High-throughput outpatient imaging facilities prioritize throughput efficiency and DICOM interoperability with legacy PACS infrastructure.
- Clinics:Physician-owned practices and urgent care chains seek mid-tier configurations balancing capital constraints against referral network requirements.
- Home Care Settings:Hospital-at-home program expansion under CMS reimbursement policies is creating reimbursable demand for lightweight, battery-dominant units in residential environments.
Hospitals command the installed base; Home Care Settings are climbing the fastest on volume contribution.
Technology:
Detector physics and signal processing architecture separate premium configurations from cost-optimized alternatives.
- Direct Radiography:Amorphous silicon flat-panel detectors with immediate digital readout dominate acute care procurement due to superior dose efficiency and elimination of cassette-handling delays.
- Computed Radiography:Photostimulable phosphor plates with laser scanning readout persist in budget-constrained facilities and retrofit installations.
- Hybrid Systems:Dual-layer detectors combining photon-counting sensitivity with energy-integrating economics enable spectral imaging at bedside.
- Mobile Radiography:Self-propelled chassis with integrated generators serve corridor-based imaging without fixed room infrastructure.
Direct Radiography handles the majority of throughput; Hybrid Systems are gaining share fastest on clinical capability expansion.
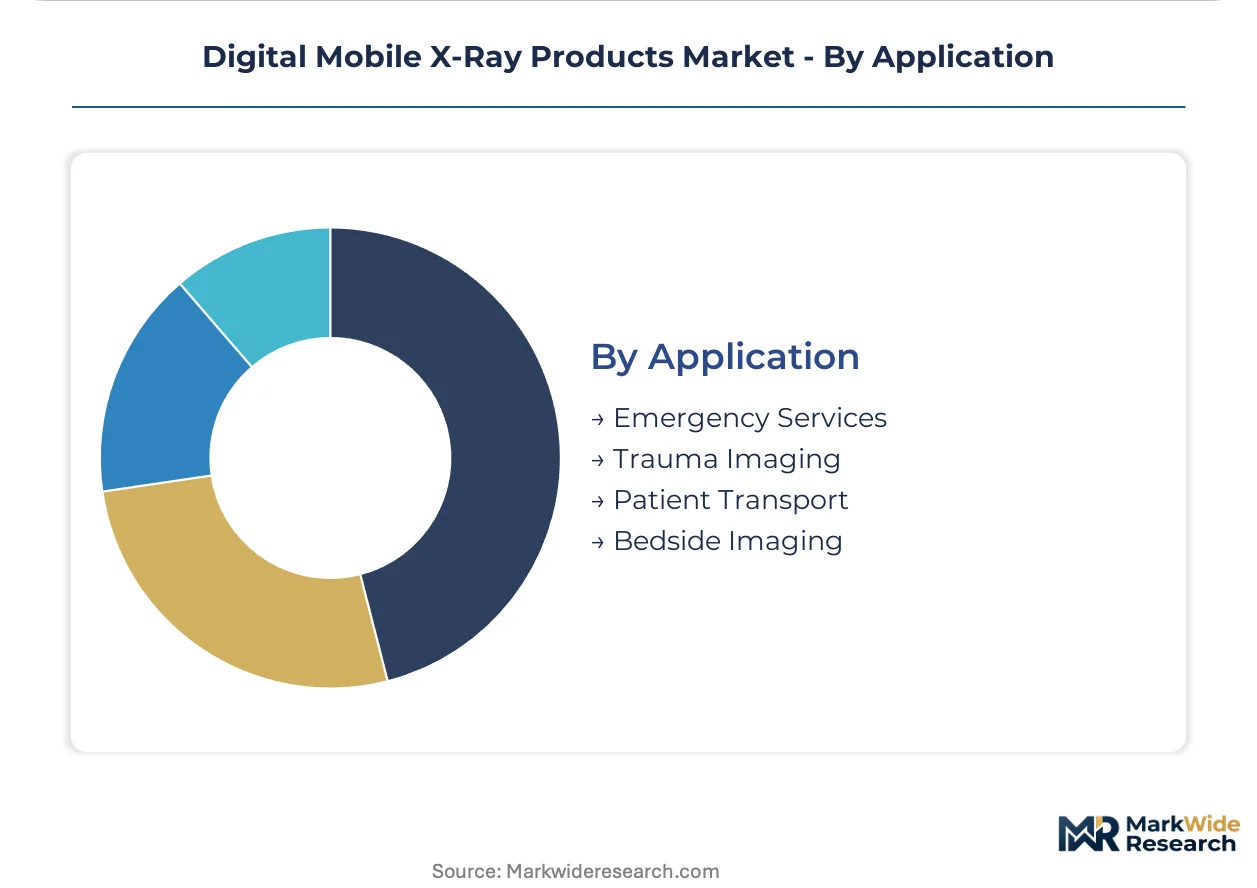
Application:
Clinical urgency and patient mobility constraints determine equipment specification and deployment location.
- Emergency Services:Pre-hospital and trauma bay imaging demands rapid deployment, ruggedized chassis, and wireless DICOM transmission for immediate surgical consultation.
- Bedside Imaging:Intensive care unit and isolation ward protocols prioritize cordless operation and infection-control surfaces, with nursing staff operating units under radiologist remote supervision.
- Trauma Imaging:Orthopedic and occult fracture detection in emergency departments drives demand for high-resolution detectors and specialized trauma positioning aids.
- Patient Transport:Inter-facility transfer imaging requires compact, battery-dominant units compatible with ambulance and aircraft power systems.
Emergency Services anchors revenue concentration; Bedside Imaging shows the steepest expansion trajectory as hospital-at-home programs scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Amorphous silicon substrate fabrication clusters in East Asian foundries, concentrating detector supply chains and exposing OEM procurement networks to geographic single-source vulnerability. Hospital consolidation and point-of-care imaging mandates are accelerating replacement cycles across acute care networks in multiple jurisdictions.
United States
Integrated delivery networks concentrate purchasing power through multi-year fleet standardization agreements, displacing transactional equipment procurement. FDA 510(k) premarket notification pathways govern commercialization timelines for wireless DICOM transmission modules. Metropolitan markets in the Northeast and Midwest exhibit the steepest reduction in independent facility counts, driving vendor contract consolidation.
Germany
Specialized mobile C-arm configurations for hybrid operating rooms anchor European demand through Siemens Healthineers' regional engineering base. EU Medical Device Regulation notified body conformity assessments create CE marking bottlenecks for wireless transmission modules. Bavaria's medical technology cluster concentrates R&D investment in surgical navigation integration.
China
Domestic flat-panel detector production expansion is compressing component manufacturing economics for regional OEMs. NMPA regulatory pathways align with national healthcare infrastructure modernization priorities under dual carbon goals. Yangtze River Delta manufacturing zones are scaling captive amorphous silicon foundry capacity for detector substrate supply.
Japan
PMDA enforcement of JIS standards for electromagnetic compatibility and radiation leakage shapes mobile fluoroscopy deployment protocols. METI industrial policy supports precision medical device exports through targeted R&D subsidies. Kanto region hospitals prioritize high-resolution detector specifications for trauma bay imaging workflows.
India
Ayushman Bharat Health and Wellness Centers are procuring portable radiography units for tier-2 and tier-3 cities lacking fixed installation infrastructure. CDSCO medical device regulations govern import and domestic manufacturing licensing for wireless detector systems. Maharashtra and Karnataka urban clusters are piloting hospital-at-home reimbursement models for bedside imaging.
Digital Mobile X-Ray Products Market Competitive Environment
Diversified healthcare conglomerates and specialized imaging equipment manufacturers split the market across premium detector resolution tiers and mid-tier cost-optimized configurations. Consolidation pressure concentrates among integrated delivery network procurement desks demanding standardized fleet configurations across affiliated facilities. Three archetypes dominate: captive vertical integration specialists controlling detector substrate supply, algorithm-differentiated workflow optimizers, and regional cost leaders leveraging localized manufacturing. Competitive moves center on M&A for detector technology access and strategic partnerships for AI-integrated image processing.
Among diversified healthcare technology conglomerates, GE Healthcare and Siemens Healthineers exemplify archetypes combining captive detector supply chains with broad modality portfolios. Fujifilm Holdings Corporation occupies a distinct position within the algorithm-differentiated tier, representing workflow optimization specialists competing on proprietary image processing rather than hardware specification alone.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Fujifilm Holdings Corporation |
| Canon Medical Systems |
| Koninklijke Philips N.V. |
| Shimadzu Corporation |
| Carestream Health |
| MinXray, Inc. |
| Hitachi, Ltd. |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency for amorphous silicon flat-panel detector substrates determines both pricing tier spreads and supply chain shape across the digital mobile X-ray market. East Asian foundry concentration exposes OEMs to tariff volatility and capacity allocation decisions that compress margins on mid-tier configurations while sustaining premium pricing for captive supply chains.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing tier structure across detector resolution grades and software integration levels. Three-tier pricing structure across premium, standard, and economy levels separates AI-integrated workflow engines from basic image acquisition units, with certification level and volume scale as primary differentiation drivers. Cost compression in standard-tier portable systems is intensifying because retrofit detector panels offer capital expenditure avoidance for budget-constrained facilities. Independent clinics and physician-owned practices exhibit the highest price sensitivity, while integrated delivery networks extract volume concessions that flatten tier premiums.
Supply Chain Analysis
East Asian contract foundries including Yangtze River Delta amorphous silicon substrate manufacturers hold dominant capacity for flat-panel detector production. Supply draws from China, South Korea, and Japan for detector substrates, lithium-silicon battery cells, and precision motor assemblies. Single-source vulnerability for amorphous silicon substrate production creates structural risk should export controls or foundry allocation shifts disrupt component flow. Distribution runs through integrated delivery network procurement desks and group purchasing organizations that aggregate hospital system demand into multi-year fleet agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital-at-home program expansion represents an early-cycle tailwind pulling digital mobile X-ray units into reimbursable residential diagnostics, creating penetration runway distinct from saturated acute care replacement cycles.
For Market Incumbents: Pre-empt emerging regional cost leaders by deepening captive supply of amorphous silicon detector substrates through foundry partnerships in the Yangtze River Delta. Consolidate position through multi-year fleet standardization agreements with integrated delivery networks before group purchasing organizations aggregate sufficient countervailing power. Invest in FDA premarket cybersecurity certification to create switching costs as connected-device mandates harden.
For New Entrants and Emerging Players: Tier-2 and tier-3 Indian cities under Ayushman Bharat Health and Wellness Center procurement represent the most penetrable geographic white space lacking fixed installation infrastructure. Target home care settings with lightweight, battery-dominant units as CMS reimbursement policies expand reimbursable remote diagnostics. Pursue CDSCO licensing partnerships with domestic distributors to navigate import regulatory complexity.
For Investors and Strategic Acquirers: The market sits at an early expansion phase that favors algorithm-differentiated workflow optimizers over undifferentiated hardware manufacturers. Long-term viability over the next decade rests on software-as-medical-device revenue streams and AI-integrated image processing capabilities rather than detector hardware margins alone. Watch for FDA premarket guidance finalization on connected device security as an inflection signal that will separate compliant from non-compliant portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Streamlined premarket notification accelerates commercialization timelines for wireless DICOM transmission modules. |
| CE Marking Pathway | EU MDR notified body conformity assessment opens European market access for hybrid detector configurations. |
| Hospital System Partnership | Multi-year fleet standardization agreements with integrated delivery networks displace transactional equipment purchasing. |
| Software Companion Development | AI-integrated image processing algorithms reduce retake rates and differentiate beyond hardware specifications. |
| Reimbursement Strategy | CMS hospital-at-home program alignment pulls procurement into reimbursable ambulatory settings. |
Study Parameters
A standing panel of hospital purchasing committee members, biomedical engineers, GPO contracts managers, and clinical medical physicists provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body documentation. Bottom-up unit demand modeling and top-down healthcare capital expenditure triangulation anchored volume and value estimates.
Scenario-bracketing framed analytical projections across the modeling period, with segmentation dimensions including detector technology tier, end-user facility scale, application urgency level, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to base-year market sizing, incorporating battery energy density improvement trajectories and hospital consolidation pace as medical-device-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Chinese OEMs or algorithm-specialist software entrants would shift outcomes beyond modeled ranges. Quarterly review of FDA premarket submission volumes, EU notified body capacity allocation, and integrated delivery network merger activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Germany Digital X-Ray Market
Medical Imaging
Global Confocal Microscope Market
Medical Imaging
Medical Image Analysis Software Market
Medical Imaging
Hand-Held X-Rays Market
Medical Imaging
Wireless Ultrasound Scanner Market
Medical Imaging
Global Computed Tomography (CT) Market
Medical Imaging
South Korea Mammography Market
Medical Imaging
SPECT Scanning Services Market
Medical Imaging
India Digital X-Ray Market
Medical Imaging
Australia Mammography Market
Medical Imaging
Image Guided Therapy Market
Medical Imaging
Asia Pacific Nuclear Imaging Market
Medical Imaging
Global Computer Vision in Healthcare Market
Medical Imaging
Spain Mammography Market
Medical Imaging
China Magnetic Resonance Imaging Market
Medical Imaging
Cardiology PACS Market