
 United States Indoor LBS Market | 2026-2036
United States Indoor LBS Market Size, Share, and Industry Trends Forecast 2026-2036
United States Indoor LBS Market Intelligence
Asset-light deployment models and subscription-based managed services are rewriting competitive entry barriers for indoor location platforms. Zebra Technologies leverages its hardware-software integration to dominate enterprise-grade tracking environments. Cisco Systems anchors network infrastructure sales with embedded positioning analytics for smart building clients. Inpixon specializes in high-security Ultra-Wideband installations for government and defense facilities.
Indoor location-based services encompass positioning, navigation, and analytics systems operating within enclosed structures where GPS signals degrade, typically achieving one-to-three-meter accuracy through beacon triangulation or time-of-flight measurement. These systems enable real-time spatial intelligence for workforce optimization, emergency routing, and consumer wayfinding in complex built environments. Ultra-Wideband and Bluetooth deployments are capturing the fastest expansion as healthcare and retail buyers prioritize sub-meter precision for asset tracking and footfall analytics. Cloud-based and hybrid delivery models are absorbing disproportionate investment as IT departments favor scalable subscription architectures over capital-intensive on-premise installations.
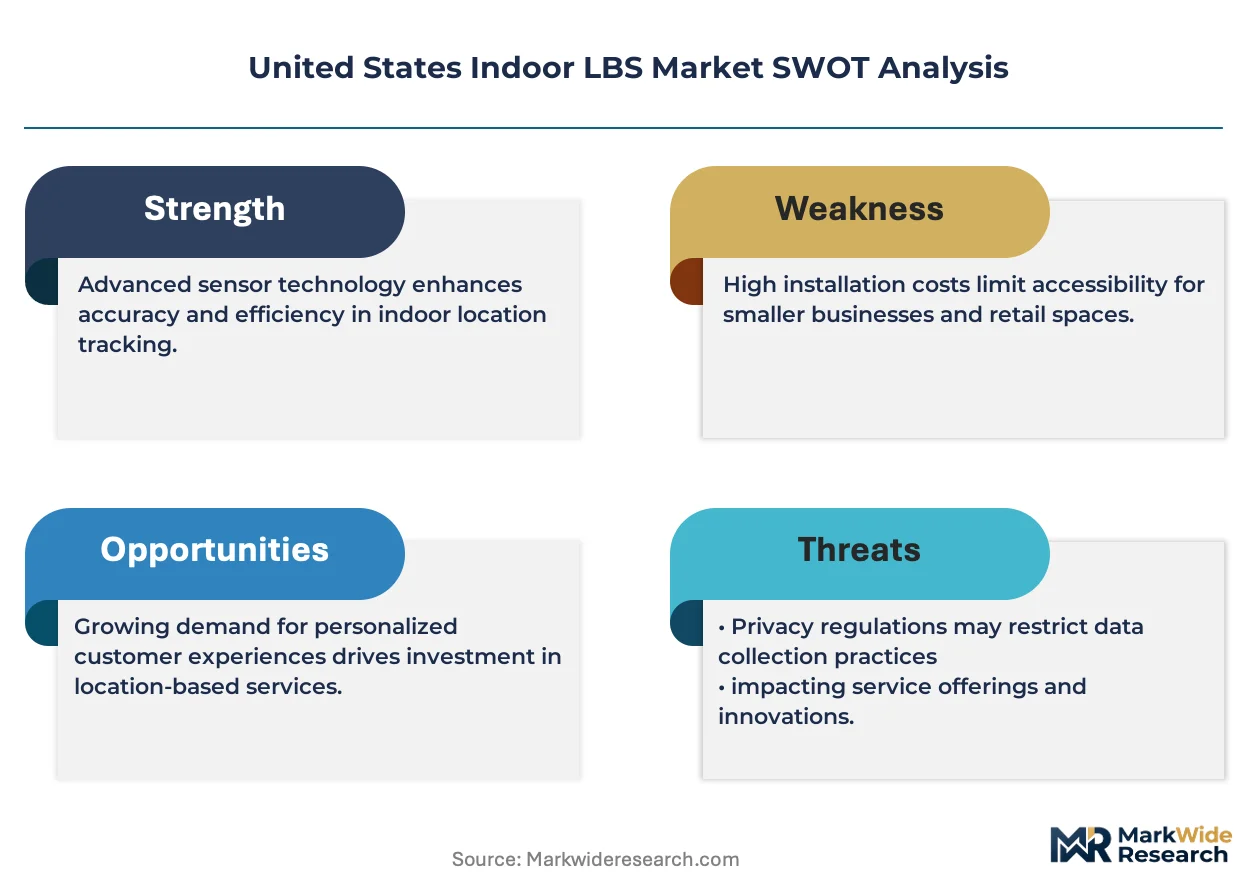
FCC Part 15 rules govern unlicensed spectrum use for Wi-Fi, Bluetooth, and Ultra-Wideband transmitters, directly shaping permissible power levels and indoor range performance. NIST cybersecurity frameworks and HIPAA privacy standards constrain how location data flows through hospital networks, creating compliance costs that favor established vendors with certified architectures. Stakeholders must weigh spectrum allocation debates and emerging federal privacy legislation when selecting technology partners and deployment timelines.
Market Dynamics
FCC Part 15 spectrum allocations for Ultra-Wideband transmitters are compressing deployment timelines for sub-meter precision systems across hospital networks and retail corridors.
Growth Catalysts
- HIPAA-compliant data architectures:Healthcare systems demand certified location platforms that satisfy federal privacy mandates for patient and asset tracking.
- Bluetooth Low Energy density:Retail operators in Texas and California corridors are tripling beacon deployments for footfall analytics and proximity marketing.
- Real-time asset visibility:Hospital supply chains are mandating continuous equipment location to reduce loss rates and optimize utilization rates.
Market Restraints
- Capital intensity of UWB infrastructure:Time-of-flight anchor installations require specialized contracting and extended commissioning periods.
- Spectrum interference risk:Unlicensed 2.4 GHz congestion from Wi-Fi and legacy Bluetooth compresses effective range in dense urban deployments.
- Cybersecurity certification delays:NIST framework compliance adds six-to-twelve-month validation cycles for federal facility installations.
Strategic Opportunities
- Cloud-native managed services:Subscription positioning platforms are displacing capital-heavy on-premise deployments among mid-market healthcare buyers.
- Emergency response routing:First responder agencies in California are piloting indoor navigation for complex structural environments.
- AI-augmented spatial analytics:Machine learning convergence with beacon data is enabling predictive occupancy and workflow optimization.
Industry Challenges
- RF engineering talent scarcity:Time-of-flight calibration and multipath mitigation require specialized expertise that outpaces domestic training pipelines.
- Legacy building integration friction:Pre-2000 structures lack power and network infrastructure for dense anchor deployment without invasive retrofitting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Indoor LBS Market |
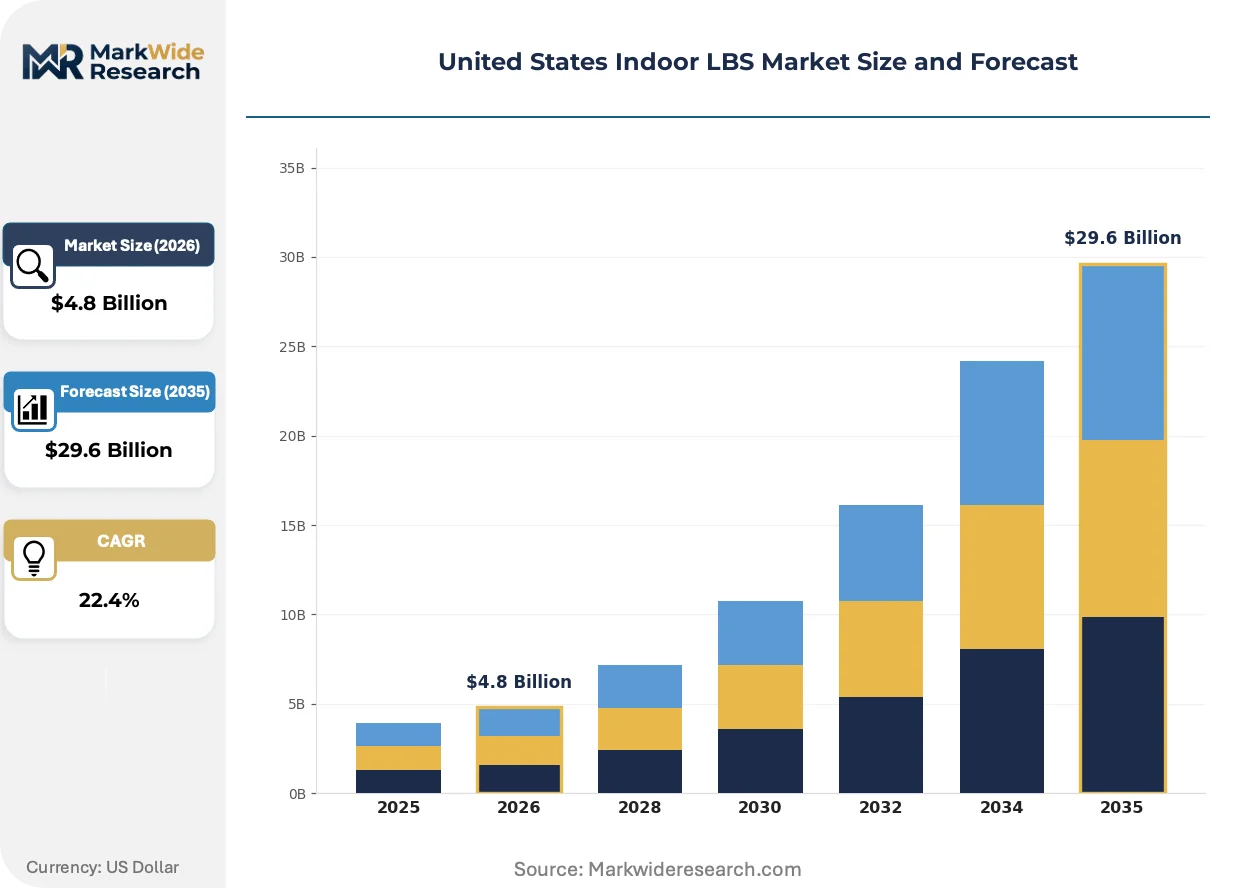
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $29.6 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wi-Fi, Bluetooth, RFID, Ultra-Wideband Application: Retail Analytics, Smart Buildings, Emergency Response, Indoor Navigation End User: Healthcare, Retail, Education, Hospitality Deployment Model: On-Premise, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Zebra Technologies, Cisco Systems, Google, Microsoft, Apple, Qualcomm Technologies, Inpixon, CenTrak, Hewlett Packard Enterprise, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Indoor LBS Market Strategic Shifts & Innovations
Positioning technology is migrating from hardware-centric beacon networks toward software-defined spatial intelligence layers that abstract physical infrastructure complexity.
Ultra-Wideband chipsets are migrating from specialized industrial modules toward mass-market consumer electronics form factors. Smartphone manufacturers are integrating UWB radios for spatial awareness applications. This migration from enterprise-only to consumer-grade availability is collapsing per-unit costs and expanding addressable installation bases.
FCC Part 15 rules governing unlicensed spectrum power levels are tightening enforcement around out-of-band emissions for UWB transmitters. Equipment manufacturers face additional certification testing for hospital and aviation-adjacent deployments. California medical device regulators are aligning state procurement standards with these federal emission limits.
Healthcare procurement committees are consolidating vendor relationships around integrated hardware-software-service bundles rather than point-solution acquisitions. Single-source contracts spanning beacon hardware, cloud analytics, and maintenance subscriptions are displacing multi-vendor integrations. Texas hospital networks are pioneering this consolidated sourcing model for new construction projects.
United States Indoor LBS Market Segmentation
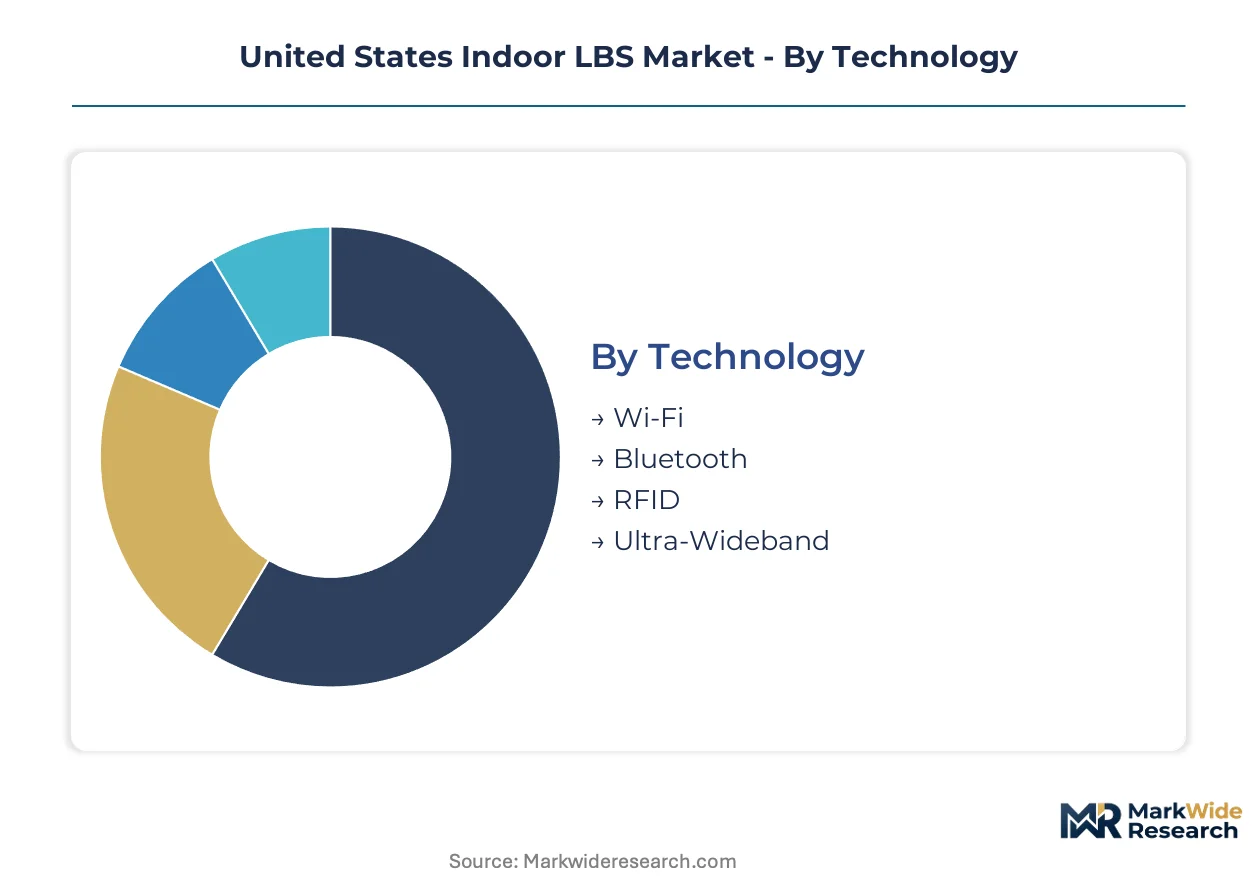
Indoor LBS buyers face distinct trade-offs between precision requirements, infrastructure constraints, and data sovereignty needs. Segmentation reveals how technology choices cascade through deployment architecture and end-use economics.
Technology:
Use-case spectrum spans proximity marketing at meter-level accuracy through surgical navigation demanding centimeter precision.
- Ultra-Wideband:Time-of-flight measurement achieves 10-30 centimeter positioning through FCC Part 15 spectrum allocations. California hospital networks are mandating UWB for high-value asset tracking and surgical tool location.
- Bluetooth:Low Energy beacon triangulation delivers 1-3 meter accuracy at lower infrastructure density. Texas retail corridors are tripling beacon deployments for footfall analytics and proximity marketing campaigns.
- Wi-Fi:Received signal strength fingerprinting leverages existing access point infrastructure for coarse positioning in cost-constrained environments.
- RFID:Passive and active tag systems provide presence detection at chokepoints rather than continuous positioning, serving legacy inventory workflows.
The dominant share belongs to Bluetooth, while Ultra-Wideband is closing the gap fastest.
Application:
Cost tier separates capital-intensive smart building integrations from lighter analytics deployments.
- Indoor Navigation:Real-time wayfinding for visitors and staff requires sub-meter accuracy and dense beacon grids. First responder agencies in California are piloting emergency routing for complex structural environments.
- Retail Analytics:Heat mapping and dwell-time measurement drive merchandise placement decisions. National retail chains are consolidating vendor relationships around integrated hardware-software-service bundles.
- Smart Buildings:HVAC integration, space utilization, and energy optimization demand enterprise-grade network infrastructure with embedded positioning.
- Emergency Response:First responder indoor location mandates are accelerating procurement timelines for public safety agencies.
Retail Analytics commands the largest installed base, though Indoor Navigation shows steepest expansion trajectory.
End User:
Customer type determines compliance burden and procurement cycle length.
- Healthcare:HIPAA-compliant architectures and NIST cybersecurity frameworks constrain vendor selection. Hospital supply chains are mandating continuous equipment location to reduce loss rates.
- Retail:Footfall analytics and proximity marketing dominate demand. Texas and California corridors concentrate beacon deployment activity.
- Education:Campus safety and classroom utilization drive moderate-precision requirements with tight capital budgets.
- Hospitality:Guest wayfinding and staff coordination prioritize user experience over measurement precision.
Healthcare generates the highest revenue per installation, while Retail provides the broadest addressable base.
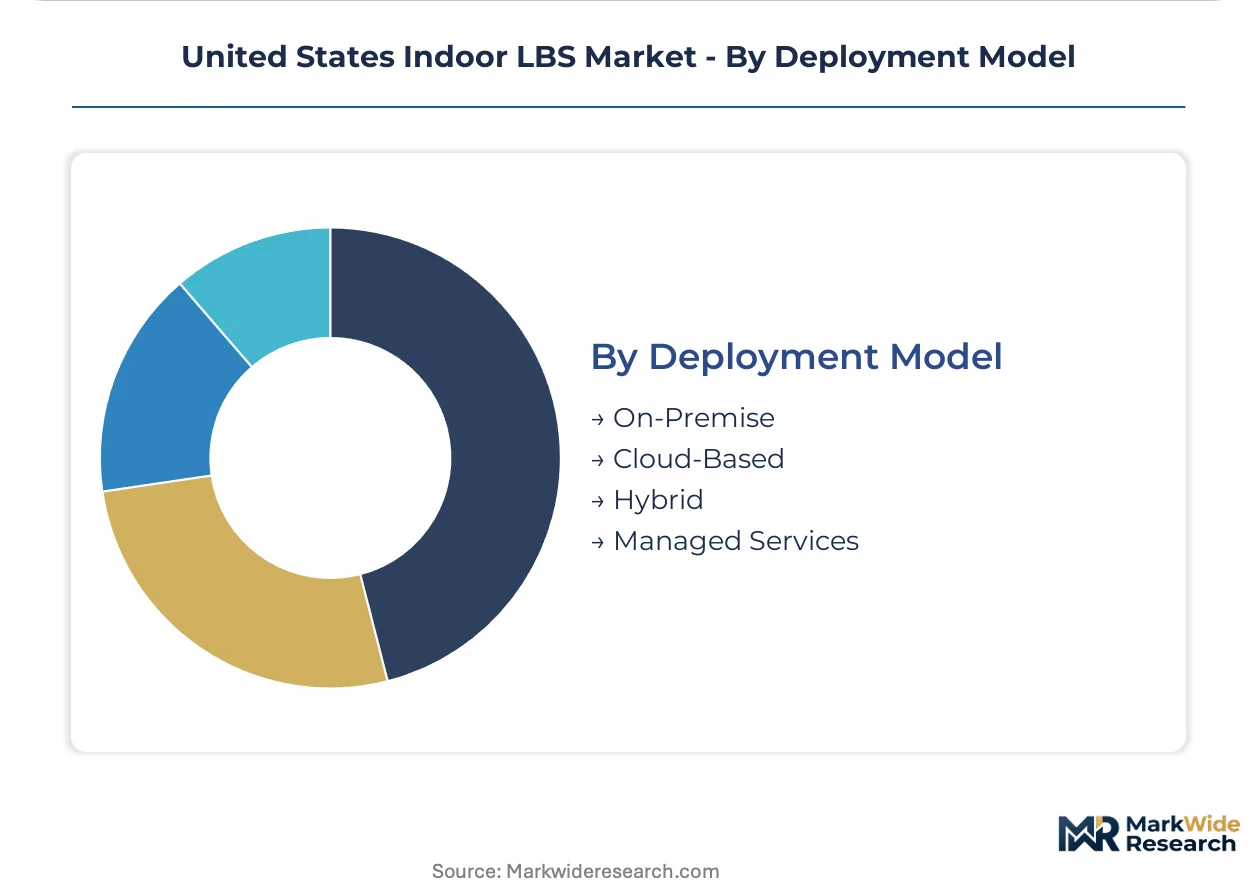
Deployment Model:
Maturity gradient runs from legacy on-premise installations toward cloud-native subscription architectures.
- Cloud-Based:Scalable subscription positioning platforms displace capital-heavy alternatives among mid-market healthcare buyers. IT departments favor operational expenditure models over infrastructure ownership.
- Managed Services:Vendor-operated beacon networks with guaranteed uptime and analytics delivery reduce internal technical staffing requirements.
- Hybrid:Edge processing for latency-sensitive positioning combined with cloud analytics for historical reporting serves security-conscious buyers.
- On-Premise:Air-gapped installations persist in federal facilities and defense-adjacent locations with stringent data residency requirements.
Cloud-Based deployments hold the dominant share, while Managed Services is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC Part 15 spectrum allocations for Ultra-Wideband transmitters are compressing deployment timelines for sub-meter precision systems across hospital networks and retail corridors.
California
Hospital networks in California are mandating UWB for high-value asset tracking and surgical tool location. State medical device regulators align procurement standards with federal emission limits under FCC Part 15 rules. The San Francisco Bay Area and Los Angeles medical corridors concentrate beacon deployment activity for healthcare systems expanding real-time asset tracking.
Texas
Retail operators in Texas corridors are tripling beacon deployments for footfall analytics and proximity marketing campaigns. State procurement committees favor integrated hardware-software-service bundles for new construction projects. Dallas-Fort Worth and Houston retail clusters anchor demand concentration for Bluetooth Low Energy density expansion.
New York Metro
First responder agencies in the New York metropolitan area are piloting indoor navigation for complex structural environments. NIST cybersecurity frameworks constrain vendor selection for federal facility installations. Manhattan smart building developments drive enterprise-grade network infrastructure with embedded positioning analytics.
Greater Boston
Education and research institutions in Greater Boston prioritize campus safety and classroom utilization with moderate-precision requirements. HIPAA-compliant architectures constrain location data flows through affiliated hospital networks. Cambridge and Boston medical-research clusters concentrate demand for continuous equipment location systems.
Pacific Northwest
Technology sector employers in the Pacific Northwest drive smart building integrations for HVAC optimization and space utilization. Cloud-native subscription platforms displace capital-heavy alternatives among mid-market healthcare buyers in Seattle and Portland. Regional IT departments favor operational expenditure models over infrastructure ownership.
United States Indoor LBS Market Key Industry Players
Channel-controlling players compete with product-specialist players across hardware-software integration and network infrastructure segments. The vendor base spans enterprise-grade tracking specialists, network equipment incumbents, and security-focused installation providers. Three archetypes dominate: hardware-software integrators, infrastructure-anchored analytics providers, and high-security UWB specialists. Consolidation pressures favor single-source contracts spanning beacon hardware, cloud analytics, and maintenance subscriptions.
Within the hardware-software integration tier, Zebra Technologies and Cisco Systems exemplify channel-controlling strategies that leverage existing enterprise relationships. Inpixon occupies a position among security-focused specialists serving government and defense-adjacent facilities with certified architectures. These three companies represent distinct competitive vectors—hardware dominance, network infrastructure anchoring, and high-security specialization—that structure rivalry across hospital networks and retail corridors.
| Leading Market Players |
|---|
| Zebra Technologies |
| Cisco Systems |
| Microsoft |
| Apple |
| Qualcomm Technologies |
| Inpixon |
| CenTrak |
| Hewlett Packard Enterprise |
| Others |
Cost & Logistics Intelligence
Dallas-Fort Worth anchors UWB anchor manufacturing capacity, where specialized RF engineering labor scarcity feeds directly into premium pricing for hospital-grade installations. Texas-based system integrators command 15-20% margin spreads over commodity beacon providers by bundling FCC Part 15 certification management with deployment services.
Pricing Analysis
Certification level creates the primary spread between economy Bluetooth beacon networks and premium Ultra-Wideband installations. Three-tier pricing structure across HIPAA-certified, enterprise-standard, and basic proximity tiers reflects NIST cybersecurity validation burdens. Pricing pressure stems from cloud-native SaaS competitors collapsing upfront hardware margins into recurring subscription models. Mid-market healthcare buyers exhibit highest price sensitivity, while federal defense facilities accept substantial premiums for air-gapped, certified architectures.
Supply Chain Analysis
Export control restrictions on precision timing chipsets limit flows from Taiwan and South Korea into domestic UWB module assembly. UWB anchor production draws from specialized RF substrates, precision oscillators, and FCC-certified transmitter components. Single-source vulnerability concentrates in Taiwan semiconductor foundries supplying time-of-flight measurement chipsets. Distribution runs through certified system integrators rather than direct OEM sales, with Zebra Technologies and Cisco Systems controlling hospital network procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as the primary defensive moat. FCC Part 15 certification timelines and NIST framework compliance create switching costs that cement incumbent positions across hospital networks and federal facilities.
For Market Incumbents: Entrench through backward integration into UWB chipset sourcing and captive RF engineering training pipelines. Cisco Systems and Zebra Technologies should expand Texas-based integration facilities to offset Taiwan foundry concentration risk. Threat from cloud-native SaaS entrants demands preemptive subscription platform launches before mid-market healthcare buyers complete vendor consolidation. For New Entrants and Emerging Players: Pursue white-space opportunities in education sector campus safety deployments, where moderate precision requirements and tight capital budgets exclude premium UWB incumbents. Pacific Northwest technology employers and Greater Boston research institutions represent most penetrable geographies. Go-to-market angle should emphasize hybrid cloud-edge architectures that bridge IT department preference for operational expenditure with security-conscious edge processing. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertical specialists with certified healthcare architectures over horizontal platform players. Long-term viability hinges on sustained HIPAA-NIST compliance moats rather than raw positioning precision advancement. Acquisition target archetype: sub-scale UWB specialists with existing federal facility installations. Signal to watch: California state procurement committee consolidation mandates accelerating single-source contract awards.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Cisco Systems embeds positioning analytics into existing network infrastructure contracts for smart building clients. |
| Acquisition of Specialist Firm | Consolidation around UWB module manufacturers with existing FCC Part 15 certification portfolios accelerates market entry. |
| Strategic Partnership | Texas hospital networks pioneer bundled hardware-software-service contracts spanning beacon deployment through cloud analytics. |
| Geographic Expansion | Pacific Northwest technology employers drive smart building integrations for HVAC optimization and space utilization. |
| Product Launch | Smartphone UWB radio integration collapses per-unit costs and expands consumer-grade availability for enterprise leverage. |
Research Approach
A spread of perspectives from hospital biomedical engineers, retail operations directors, FCC regulatory affairs specialists, and smart building facility managers converged on the working assumptions. Primary interviews with healthcare procurement committees and Texas retail corridor operators combined with secondary validation from FCC Part 15 rulemaking dockets, NIST cybersecurity framework documentation, and hospital GPO contract databases. Bottom-up installation volume estimates triangulated against top-down market sizing from infrastructure spending disclosures.
Demand-supply balance modeling across the projection horizon incorporated technology adoption curves, regulatory compliance timeline distributions, and RF engineering labor availability constraints. Segmentation dimensions spanned precision tier, deployment architecture, end-use vertical, and geographic corridor concentration. CAGRs derived from logistic diffusion curves fitted to historical beacon density expansion patterns. Industry-specific forecast inputs included FCC spectrum allocation proceedings and California state medical device procurement standard revisions.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles or federal defense budget allocations would shift the trajectory. Forecasts reflect documented assumptions regarding UWB chipset cost decline curves and cloud migration adoption rates. Material shifts in FCC Part 15 enforcement intensity or Taiwan semiconductor export restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Sports Events Market
Others
Europe Legal Services Market
Others
Nutricosmetics Market
Others
North America IT Device Market
Others
Digital Mortgage Software Market
Others
Africa Lime Market
Others
Gas Radiators Market
Others
Mexico 3D Printing Construction Market
Others
Smartphone Gimbal Market
Others
Global Alpha Cypermethrin Market
Others
Metal Air Battery Market
Others
Italy Automotive Adaptive Lighting System Market
Others
Residential Electrical Conduit Market
Others
Canada Laser Hair Removal Market
Others
Czech Republic Market
Others
Hearables Market