
 Advanced Combat Helmet Market | 2026-2036
Advanced Combat Helmet Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Combat Helmet Market Analysis
A capital-intensity divergence between ballistic composite weavers and final assembly houses is reorganizing supplier tiers in the helmet industry. Gentex Corporation leverages in-house aramid processing to sustain margin control across U.S. military contracts. Rheinmetall anchors European defense procurement through its integration with Bundeswehr modernization programs. MKU Limited competes on cost-engineered Kevlar helmets for paramilitary buyers across South Asia and the Middle East.
Advanced combat helmets integrate multi-hit ballistic shells, suspension systems, and rail interfaces for peripheral equipment, typically manufactured through compression molding of para-aramid or ultra-high-molecular-weight polyethylene prepregs to protect against fragmentation and handgun threats. Military application dominates procurement volumes, though law enforcement segments show faster upgrade cycles as agencies adopt night vision-compatible modular platforms. Kevlar retains the largest material share by tonnage, while carbon fiber variants command premium positioning in special operations configurations where weight reduction justifies higher unit economics.
U.S. Army Natick Soldier Systems Center, NATO Standardization Office, and India's BIS enforce divergent test protocols that fragment certification pathways and extend qualification timelines for cross-border vendors. The EU AI Act and emerging autonomous targeting regulations will increasingly shape sensor integration requirements for future helmet-mounted systems. Stakeholders must monitor how national offset rules and domestic content mandates reshape supplier eligibility before committing to regional capacity investments.
Market Dynamics
Material science divergence between aramid and polyethylene fiber systems is forcing suppliers to choose between margin protection and weight-performance leadership. The U.S. Army's Soldier Protection System mandates are compressing qualification timelines while fragmenting certification pathways across NATO and Indian standards.
Growth Catalysts
- Modular rail integration:Special operations forces across NATO member states now require universal accessory mounting for night vision and communication systems, expanding addressable kit value per helmet.
- REACH compliance migration:European manufacturers are accelerating Kevlar-to-UHMWPE transitions to meet chemical substance restrictions, creating material upgrade cycles in Bundeswehr procurement.
- Paramilitary modernization:India's Central Armed Police Forces and comparable units in South Asia are replacing legacy steel helmets with ballistic composite systems, opening volume tier below military specifications.
Market Restraints
- Para-aramid supply concentration:DuPont and Teijin control upstream Kevlar and Twaron fiber production, exposing assemblers to input cost volatility and allocation constraints during surge demand.
- Fragmented test protocols:Divergent NIJ, STANAG, and BIS certification requirements extend cross-border qualification timelines and lock vendors into single- geography revenue streams.
- Legacy inventory overhang:NATO member states maintain substantial PASGT and MICH helmet stocks, depressing replacement rates despite superior successor system availability.
Strategic Opportunities
- Sensor fusion integration:Helmet-mounted displays for augmented situational awareness are converging with ballistic protection, creating integrated headborne system categories beyond standalone armor.
- Domestic content mandates:India's phased manufacturing program and comparable localization rules in Saudi Arabia and UAE create captive demand for in-country assembly operations.
- Law enforcement upgrade cycles:Municipal agencies are compressing replacement intervals as modular platforms displace fixed-configuration helmets, opening faster-turn revenue streams than military procurement.
Industry Challenges
- Ballistic composite weaving expertise:The specialized skill base for prepreg handling and compression molding concentrates in defense-adjacent industrial clusters, constraining capacity scaling.
- Multi-hit test standard evolution:Emerging threats require helmets to defeat sequential impacts at oblique angles, forcing redesign of shell geometry and suspension attachment points.
- Legacy system integration:New helmet platforms must interface with existing night vision mounts, communication headsets, and gas mask seals, multiplying interface validation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Combat Helmet Market |
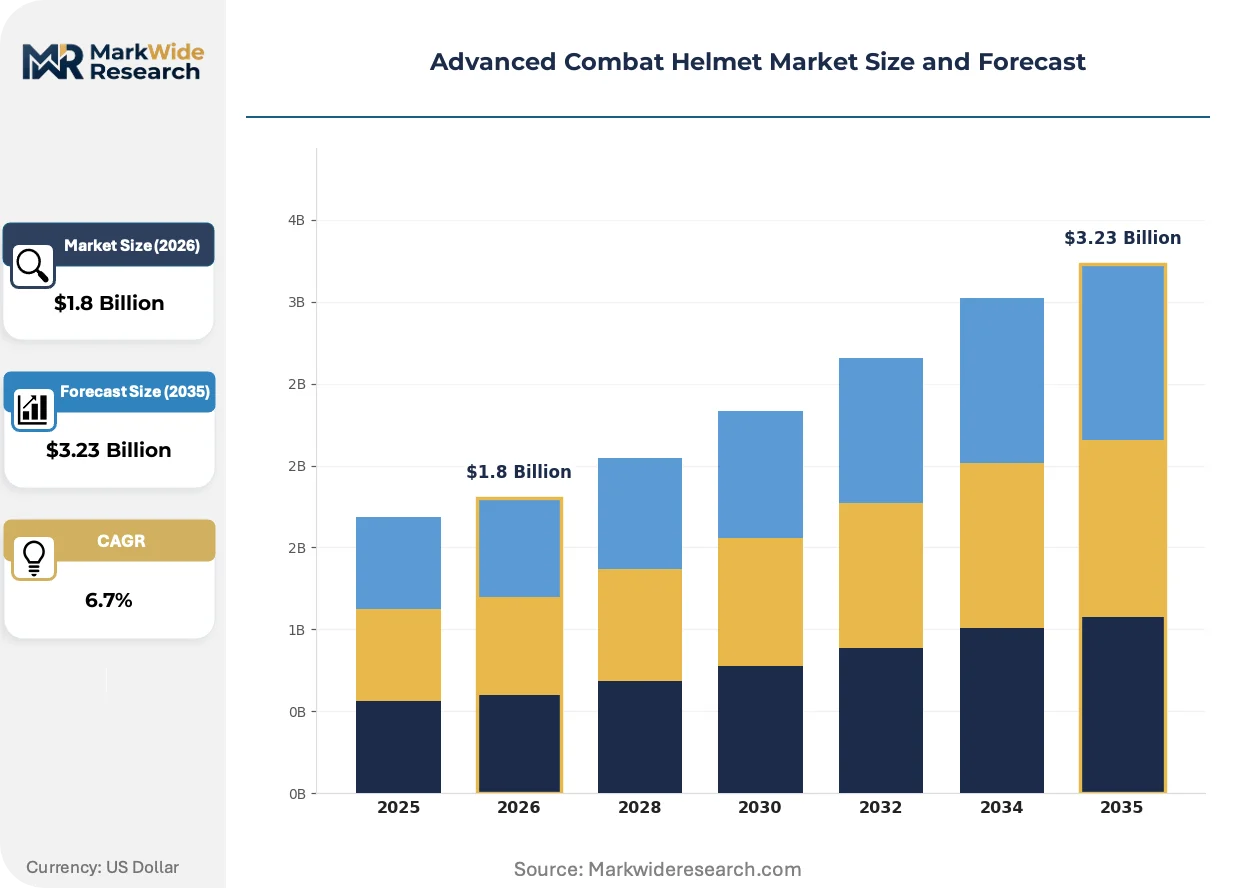
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ballistic Helmets, Bump Helmets, Modular Helmets, Night Vision Helmets Material: Kevlar, Carbon Fiber, Polycarbonate, Fiberglass Application: Military, Law Enforcement, Tactical Sports, Search and Rescue End User: Defense Forces, Security Agencies, Private Contractors, First Responders |
| Companies Covered | Avon Rubber p.l.c., MKU Limited, ArmorSource LLC, Ops-Core, Honeywell International Inc., Gentex Corporation, BAE Systems, Rheinmetall, Revision Military, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Combat Helmet Market Emerging Trajectories
Helmet architecture is splitting between mass-optimized ground force systems and weight-minimized special operations configurations. This divergence is compressing development cycles while expanding the performance gap between procurement tiers.
Ultra-high-molecular-weight polyethylene prepregs are bifurcating competitive positioning. Special operations commands in the United States and United Kingdom are adopting UHMWPE shells for maritime and airborne insertion roles where gram reduction justifies unit cost premiums. Ground force procurement remains anchored to aramid systems, preserving supplier margin structures optimized for Kevlar processing while segmenting the addressable market by mission profile rather than threat level alone.
The EU AI Act is reshaping sensor integration roadmaps. Helmet-mounted targeting and threat detection systems must now demonstrate human-in-the-loop decision protocols before Bundeswehr or comparable European force adoption, extending development timelines for autonomous cueing features. Manufacturers are responding with modular electronics bays that permit field removal of AI-enabled subsystems, preserving platform commonality across regulatory jurisdictions.
Buying patterns are compressing vendor qualification cycles. Defense ministries in Germany and India are moving from multi-year framework agreements to annual competitive tenders with accelerated technical evaluation phases. This shift favors suppliers with pre-positioned test data and established in-country representation, disadvantaging new entrants regardless of technical merit. The United States Army's expedited Soldier Protection System timeline exemplifies this acceleration, with contract awards following compressed source selection periods.
Advanced Combat Helmet Market Segmentation
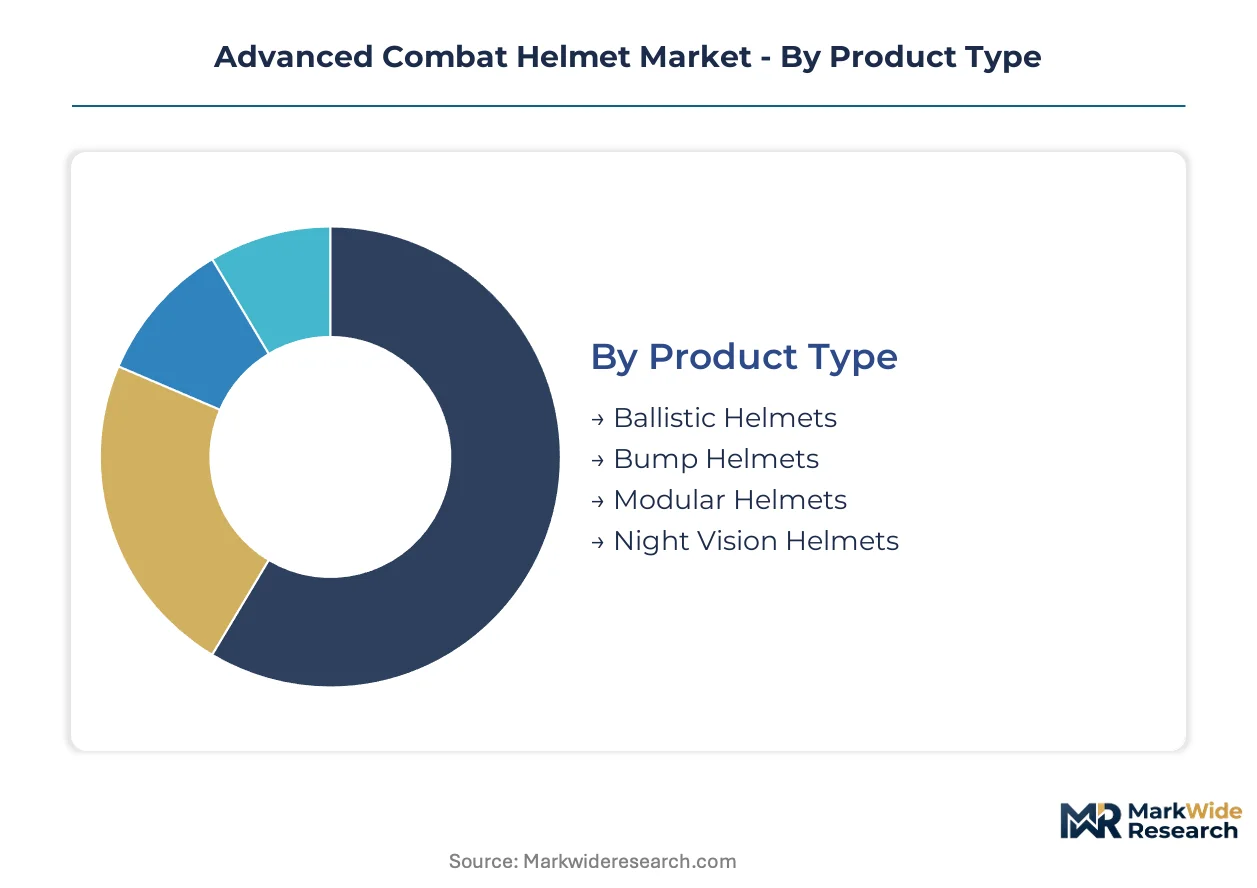
Helmet segmentation determines procurement eligibility across divergent threat environments and budget tiers. Material and configuration choices lock vendors into specific certification pathways that govern cross-border sales potential.
Product Type:
NIJ Level IIIA protocols govern ballistic performance, while STANAG fragmentation standards separate military-grade from commercial offerings.
- Ballistic Helmets:Compression-molded para-aramid or UHMWPE shells rated for handgun and fragmentation threats. Defense forces in the United States, Germany, and India drive procurement through Soldier Protection System and Bundeswehr modernization programs.
- Modular Helmets:Rail-integrated platforms supporting night vision, communication, and sensor peripherals. Law enforcement agencies in North America and Europe are compressing replacement cycles as agencies adopt night vision-compatible configurations.
- Bump Helmets:Lightweight polymer shells for impact protection without ballistic rating. Private contractors and tactical sports participants purchase these for training and low-threat environments where mobility outweighs armor requirements.
- Night Vision Helmets:Pre-configured shrouds and power integration for image intensification systems. Special operations commands specify these for maritime and airborne insertion roles where gram reduction justifies unit cost premiums.
Ballistic helmets handle the majority of throughput; modular helmets are expanding most quickly on share.
Material:
REACH chemical restrictions and weight-performance tradeoffs segment supplier capabilities across fiber systems.
- Kevlar:DuPont's para-aramid fiber dominates ground force procurement by tonnage, with established compression molding infrastructure preserving margin structures for U.S. and European assemblers.
- Carbon Fiber:Premium-positioned in special operations configurations where weight reduction justifies higher unit economics. United Kingdom and United States maritime commands specify these for extended wear missions.
- Ultra-High-Molecular-Weight Polyethylene:European manufacturers are accelerating adoption to meet chemical substance restrictions, creating material upgrade cycles in Bundeswehr procurement.
- Polycarbonate:Cost-engineered option for paramilitary and first responder budgets. India's Central Armed Police Forces specify these for volume tier procurement below military specifications.
- Fiberglass:Legacy material retained for training and simulation systems where ballistic performance is not required.
Kevlar retains volume leadership; UHMWPE is climbing the fastest on share.
Application:
Threat environment and operational tempo determine replacement intervals and performance tier selection.
- Military:Multi-hit ballistic requirements under NIJ and STANAG protocols drive the highest specification tier. Fragmented test standards across NATO and Indian BIS requirements extend qualification timelines for cross-border vendors.
- Law Enforcement:Modular platform adoption is compressing replacement intervals as municipal agencies upgrade from fixed-configuration helmets. Night vision compatibility is now standard for tactical units in major U.S. metropolitan departments.
- Tactical Sports:Bump helmet configurations for competitive shooting and training scenarios. Private purchase patterns favor rail integration and accessory compatibility over ballistic protection.
- Search and Rescue:Lightweight configurations prioritizing visibility and communication integration. First responder specifications vary by terrain and climate exposure.
Military application commands procurement volume; law enforcement is gaining share fastest.
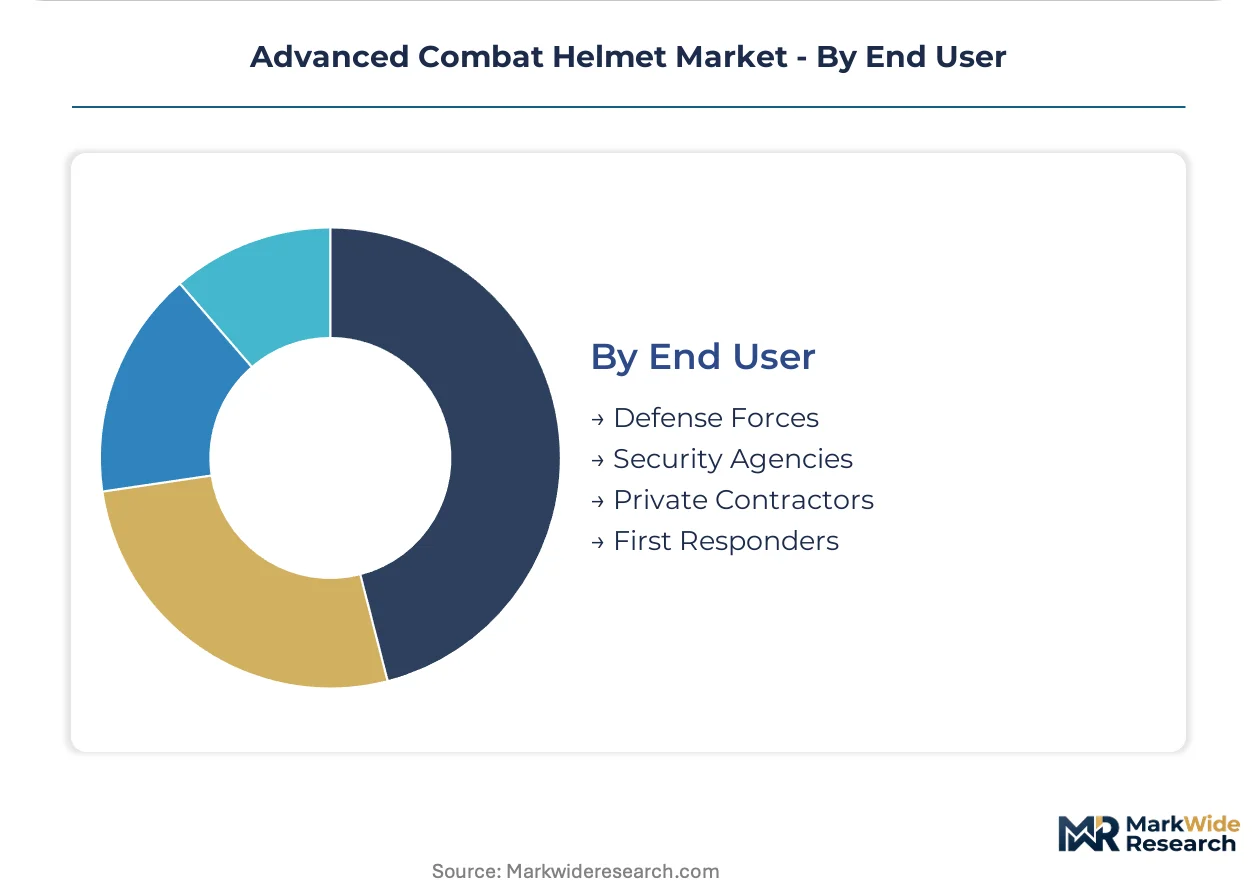
End User:
Budget authority and threat exposure stratify purchasing power across institutional buyer categories.
- Defense Forces:Multi-year framework agreements with accelerated technical evaluation phases. Germany and India are moving toward annual competitive tenders that favor suppliers with pre-positioned test data.
- Security Agencies:Paramilitary modernization programs in South Asia and the Middle East are replacing legacy steel helmets with ballistic composite systems.
- Private Contractors:Self-procurement patterns favor modular platforms with cross-compatibility across client requirements. Cost-engineered Kevlar helmets from Indian and Middle Eastern suppliers dominate this tier.
- First Responders:Municipal funding cycles and interoperability requirements with existing equipment constrain upgrade timing.
Defense forces handle the majority of throughput; security agencies show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in U.S. and German procurement channels while Indian suppliers compete on volume tiers. This asymmetry shapes where composite weaving expertise accumulates versus where final assembly achieves scale.
United States
The U.S. Army's Soldier Protection System compresses qualification timelines for next-generation helmet platforms. Natick Soldier Systems Center enforces NIJ protocols that diverge from European STANAG standards. Industrial capacity clusters around Pennsylvania and Michigan defense corridors where Gentex Corporation maintains in-house aramid processing operations.
Germany
Bundeswehr modernization programs drive REACH-compliant UHMWPE transitions in ground force equipment procurement. The EU AI Act shapes sensor integration requirements for helmet-mounted targeting systems. Manufacturing concentrates in North Rhine-Westphalia and Bavaria where Rheinmetall anchors European defense supply chains through integrated program delivery.
India
Central Armed Police Forces are replacing legacy steel helmets with ballistic composite systems at volume tier pricing. BIS certification requirements fragment cross-border qualification pathways for foreign vendors. Production gravitates toward Kanpur and Mumbai industrial belts where MKU Limited cost-engineers Kevlar platforms for paramilitary buyers.
United Kingdom
Maritime and airborne special operations commands specify weight-minimized UHMWPE configurations for extended wear missions. Ministry of Defence procurement aligns with NATO STANAG fragmentation standards while maintaining national test protocols. Defense industrial activity concentrates in South East England and Midlands regions with established composite processing heritage.
France
DGA procurement frameworks prioritize modular rail integration for night vision and communication peripherals. ANSM and CNIL oversight extends to data handling in helmet-mounted sensor systems. Industrial capacity clusters in Île-de-France and Provence-Alpes-Côte d'Azur regions with aerospace-defense supply chain adjacencies.
Advanced Combat Helmet Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics across procurement segments. The market structure consolidates around integrated defense primes with captive material processing capabilities while fragmenting among regional assemblers serving price-sensitive paramilitary buyers. Three archetypes dominate: vertically integrated primes controlling fiber-to-finished-product pipelines, specialized armor houses competing on qualification speed, and volume manufacturers optimizing for domestic content mandates. Competitive moves center on backward integration into prepreg weaving and accelerated certification positioning across divergent national test protocols.
Among U.S.-based defense primes, Gentex Corporation and Honeywell International Inc. occupy positions anchored to Soldier Protection System procurement channels, while Rheinmetall represents the European integrated prime archetype through Bundeswehr program anchoring. MKU Limited exemplifies the cost-engineered specialist model serving South Asian paramilitary modernization at volume scale below military specification tiers.
| Leading Market Players |
|---|
| Avon Rubber p.l.c. |
| MKU Limited |
| ArmorSource LLC |
| Ops-Core |
| Honeywell International Inc. |
| Gentex Corporation |
| BAE Systems |
| Rheinmetall |
| Revision Military |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at DuPont and Teijin para-aramid fiber plants shapes both input cost floors and tiered supplier margins across U.S., German, and Indian helmet assembly operations. This scale concentration preserves pricing power for upstream fiber producers while compressing margin capture at final assembly houses serving paramilitary volume tiers.
Pricing Analysis
The customization-premium spread separates configured-to-order special operations helmets from standard ground force procurement, with UHMWPE maritime configurations commanding substantial premiums over Kevlar baseline systems. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with NIJ Level IIIA-plus fragmentation ratings and STANAG compliance driving substantial differentials. Cost compression in the paramilitary tier is intensifying because India's Central Armed Police Forces and comparable South Asian buyers prioritize domestic content mandates over ballistic performance specifications. Defense forces exhibit the lowest price sensitivity, while private contractors and municipal law enforcement agencies demonstrate acute responsiveness to unit cost differentials.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports constrain European UHMWPE prepreg delivery schedules, with container availability fluctuations rippling through Bundeswehr modernization procurement timelines. Upstream para-aramid fiber production concentrates in the United States and Japan, while final helmet assembly clusters in the United States, Germany, and India. Raw material dependencies center on DuPont Kevlar, Teijin Twaron, and DSM Dyneema fiber systems. Single-source vulnerability at the prepreg weaving tier exposes assemblers to allocation constraints during surge demand periods. Distribution runs through defense prime direct contracts, government procurement frameworks, and authorized distributor networks serving law enforcement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as divergent national test protocols and domestic content mandates create protected niches for regional specialists. Modular sensor integration requirements under the EU AI Act and comparable regulations multiply certification pathways, opening entry points for qualified second-tier suppliers.
For Market Incumbents: Secure backward integration into prepreg weaving to defend margin structures against fiber cost volatility and allocation risk. Anchor capacity expansion in Pennsylvania and North Rhine-Westphalia defense corridors to maintain proximity to U.S. Army Natick and Bundeswehr qualification facilities. Accelerate STANAG and BIS certification positioning to lock in cross-border revenue streams before competitive tender compression intensifies. For New Entrants and Emerging Players: Lead with cost-engineered Kevlar platforms for India's Central Armed Police Forces and comparable paramilitary modernization programs where domestic content mandates create captive demand. Target the law enforcement modular upgrade cycle in North American municipal agencies, where compressed replacement intervals and night vision compatibility requirements outpace incumbent qualification speeds. Pursue channel partnerships with established defense distributors to bypass multi-year vendor approval timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors composite weaving specialists with captive aramid processing capabilities and pre-positioned multi-protocol certification data. Long-term viability rests on suppliers capable of bridging UHMWPE transition requirements under REACH compliance while maintaining Kevlar infrastructure for ground force volume tiers. Acquisition target archetype: regional assemblers with in-country representation in India, Saudi Arabia, or UAE localization programs. Monitor Bundeswehr and U.S. Army Soldier Protection System contract award velocity as inflection indicator for qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Prepreg Weaving | Captive fiber processing insulates margin structures from DuPont and Teijin allocation constraints during surge demand. |
| Multi-Protocol Certification Investment | Pre-positioned NIJ, STANAG, and BIS test data accelerates vendor qualification under compressed competitive tender timelines. |
| Domestic Content Mandate Compliance | In-country assembly operations in India, Saudi Arabia, and UAE unlock paramilitary procurement channels under phased manufacturing programs. |
| Modular Sensor Bay Development | Field-removable AI-enabled subsystems preserve platform commonality across EU AI Act and divergent autonomous targeting regulatory jurisdictions. |
| Law Enforcement Channel Expansion | Municipal agency upgrade cycles for night vision-compatible configurations generate faster-turn revenue streams than multi-year defense frameworks. |
Methodological Framework
A spread of perspectives from program managers at U.S. Army Natick Soldier Systems Center, Bundeswehr equipment procurement officers, BIS certification engineers, composite weaving plant managers, and defense prime contract specialists converged on the working assumptions. Primary interview data combined with secondary validation from NATO Standardization Office technical documentation, U.S. Army budget justification materials, EU AI Act regulatory filings, Indian PLI scheme notifications, and customs trade records for para-aramid fiber imports. Bottom-up unit economics and top-down defense budget allocation analysis triangulated market sizing.
Segmentation dimensions modeled include material fiber system, helmet configuration type, application threat environment, and end-user budget authority tier across the analysis window. CAGRs derived from defense procurement pipeline visibility, modernization program funding profiles, and replacement cycle compression indicators. Industry-specific forecast inputs encompass Soldier Protection System contract award velocity, REACH compliance migration timelines for UHMWPE transitions, and paramilitary steel-to-composite replacement rates in South Asia.
Forecasts assume regulatory continuity in U.S. NIJ protocols, European REACH and EU AI Act implementations, and Indian BIS certification requirements; material policy shifts would require re-modeling. Specific risk factors include para-aramid supply concentration disruption, accelerated multi-hit test standard evolution, and legacy inventory overhang depressing replacement rates in NATO member states. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Spinner Flask Market
Others
Digital Signage Media Player Market
Others
Global Mica Market
Others
Pet Care Packaging Market
Others
Synthetic Leather Market
Others
Vortexers Market
Others
Cloud Broadcasting Solutions Market
Others
Cloud Advertising Market
Others
Dried Egg Market
Others
North America Forklift Truck Market
Others
Storm Surge Barriers Market
Others
PC As a Service Market
Others
Fluid Dispensing Systems Market
Others
Gas Holders Market
Others
Japan Coal Market
Others
Augmented Reality (AR) in Warehousing and Logistics Market