
 Canada Feed Additives Market | 2026-2036
Canada Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Feed Additives Market Outlook
CFIA's Safe Feed/Safe Food certification is redrawing competitive boundaries across the Canadian supply base. Cargill Inc. leverages its integrated grain-handling and premix manufacturing footprint to dominate Prairie distribution corridors. Jefo Nutrition Group specializes in precision-coated additives that withstand pelleting temperatures, sustaining margins in premium ruminant formulations.
Feed additives comprise biologically active compounds including enzymes, amino acids, vitamins, and minerals incorporated into animal diets at inclusion rates typically below one percent by weight to enhance nutrient utilization, growth performance, or health status. Enzyme formulations containing phytase and xylanase target anti-nutritional factors in cereal-based poultry rations, while amino acid blends such as lysine and methionine correct protein deficiencies in corn-soybean diets. The poultry end-user segment leads volume consumption due to intensified barn operations in Ontario and British Columbia, though aquaculture applications represent the fastest-expanding margin pool as Atlantic salmon producers adopt functional gut-health additives. Direct sales channels capture the largest share of value through contracted supply relationships between manufacturers and integrated livestock operations, while e-commerce penetration remains constrained by bulk logistics and formulation customization requirements.
Health Canada's Veterinary Drugs Directorate and the Canadian Food Inspection Agency jointly govern ingredient approvals, residue limits, and manufacturing facility registrations under the Feeds Act and Feeds Regulations. The Canadian Grain Commission's mycotoxin monitoring programs indirectly shape demand for binder and detoxification additives in years with elevated fusarium pressure. Stakeholders must monitor pending amendments to the Feeds Regulations that could reclassify certain microbial products as veterinary drugs, altering registration pathways and competitive timelines for novel live-culture entrants.
Market Dynamics
Health Canada's pending amendments to the Feeds Regulations are compressing registration timelines for novel microbial additives, forcing reformulation strategies across Canadian livestock operations before the new classification framework takes effect.
Growth Catalysts
- Prairie cattle finishing intensity:Large-scale feedlots in Alberta and Saskatchewan are consolidating mineral and vitamin procurement into long-term supply contracts, locking in additive volume commitments.
- CFIA Safe Feed/Safe Food certification:Mandatory third-party verification is filtering out non-compliant premix suppliers, redirecting demand toward certified manufacturing networks.
- Precision-coated enzyme technology:Heat-stable phytase and xylanase formulations are surviving pelleting temperatures above 85°C, enabling inclusion in high-temperature poultry rations without activity loss.
Market Restraints
- Grain mycotoxin volatility:Fusarium pressure in Prairie wheat and corn harvests forces unpredictable surges in binder additive demand, disrupting annual procurement planning.
- Atlantic salmon supply concentration:Functional gut-health additive demand depends on fewer than 15 integrated aquaculture operations in New Brunswick and Newfoundland, creating customer concentration risk.
- Regulatory reclassification friction:Health Canada's Veterinary Drugs Directorate may recategorize certain live-culture products as veterinary drugs, extending approval pathways by 18-24 months.
Strategic Opportunities
- Quebec dairy precision nutrition:Underpenetrated robotic milking operations in the Montérégie region present white space for sensor-integrated additive dosing systems.
- E-commerce formulation platforms:Direct-to-farm digital channels for customized premix orders are bypassing traditional distributor markups in Ontario's independent hog sector.
- Clean Fuel Regulation crediting:Methane-reducing feed additives for cattle may qualify for federal compliance credits, creating a dual revenue stream for ruminant formulation suppliers.
Industry Challenges
- CFIA compliance talent scarcity:Qualified regulatory affairs specialists capable of navigating simultaneous Feeds Act and Feeds Regulations amendments command premium compensation in Toronto and Calgary.
- Legacy feed mill integration:Retrofitting Prairie grain-handling facilities for real-time additive dosing requires capital outlays that smaller cooperatives cannot absorb without consolidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Feed Additives Market |
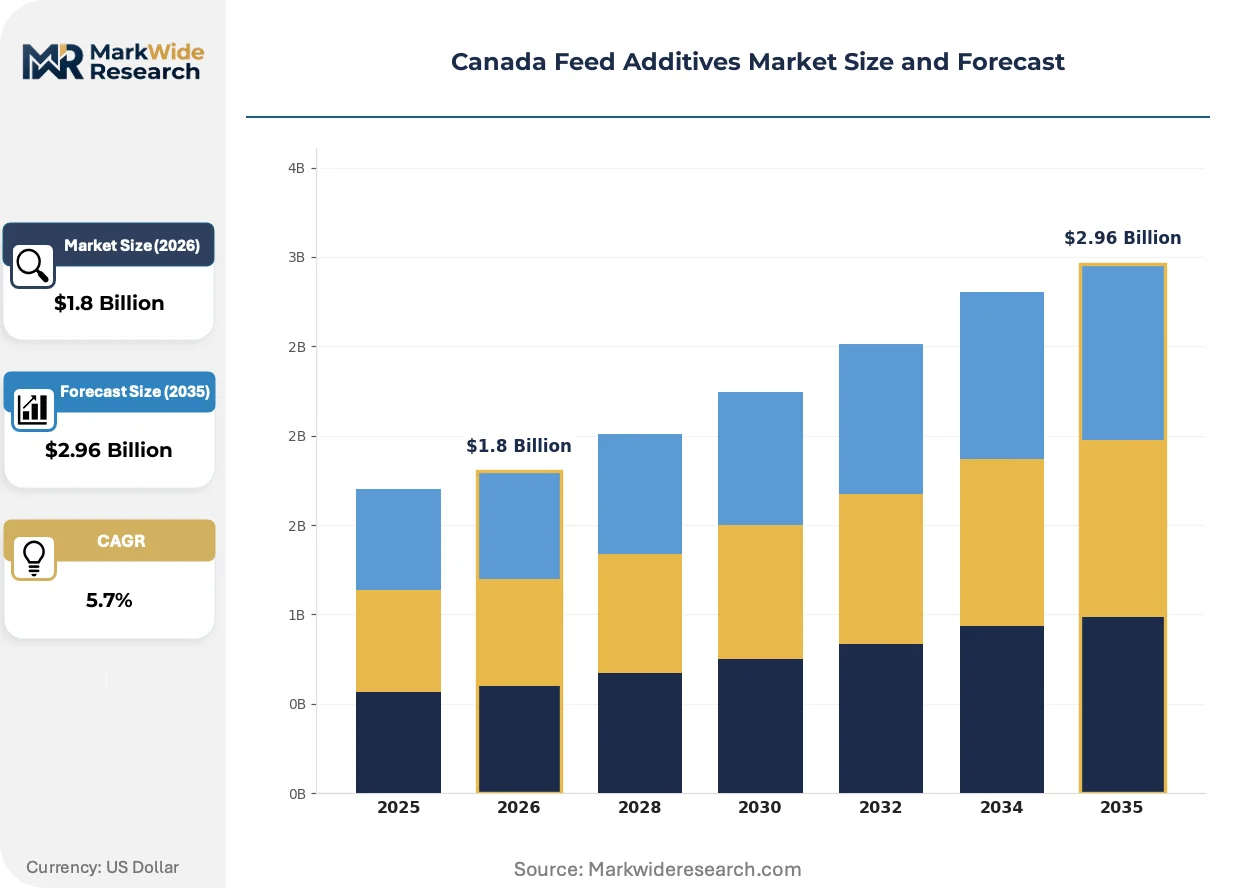
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Minerals, Vitamins, Amino Acids, Enzymes End User: Poultry, Ruminants, Swine, Aquaculture Application: Growth Promotion, Nutritional Enhancement, Digestibility Improvement, Health Management Distribution Channel: Retail, Direct Sales, E-Commerce, Wholesale |
| Companies Covered | Archer Daniels Midland Co., DSM-Firmenich, Elanco Animal Health Inc., Evonik Industries AG, IFF (Danisco Animal Nutrition), Cargill Inc., Jefo Nutrition Group, Canadian Bio-Systems Inc., Alltech, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Feed Additives Market Strategic Shifts
Canadian feed additive development is pivoting toward bioactive precision delivery and regulatory pre-emption, with manufacturers investing in heat-stability engineering and microbial characterization ahead of anticipated classification shifts.
Microencapsulation technology is fragmenting the traditional premix market by enabling farm-level inclusion of enzymes and organic acids that previously required centralized pelleting infrastructure. Ontario broiler integrators are adopting on-farm liquid application systems at a pace that compresses margins for conventional dry-blend suppliers. This decentralization is fragmenting volume concentration away from large-scale mill networks toward distributed dosing equipment vendors.
Health Canada's Veterinary Drugs Directorate is tightening residue surveillance protocols for antimicrobial alternatives, requiring enhanced pharmacokinetic documentation for novel peptides and bacteriophage cocktails. The industrial consequence is a bifurcation between established suppliers with regulatory dossier capabilities and entrants facing extended approval timelines. Atlantic salmon aquaculture operations in New Brunswick are responding by pre-qualifying additive suppliers based on existing veterinary drug master file portfolios.
Buyer concentration among integrated poultry operations is compressing switching costs and unbundling technical service from product supply. Ontario's largest broiler producers are negotiating direct formulation partnerships that displace distributor intermediaries. This disintermediation is most visible in the London-Woodstock corridor, where three integrators account for the majority of amino acid blend procurement.
Canada Feed Additives Market Segmentation
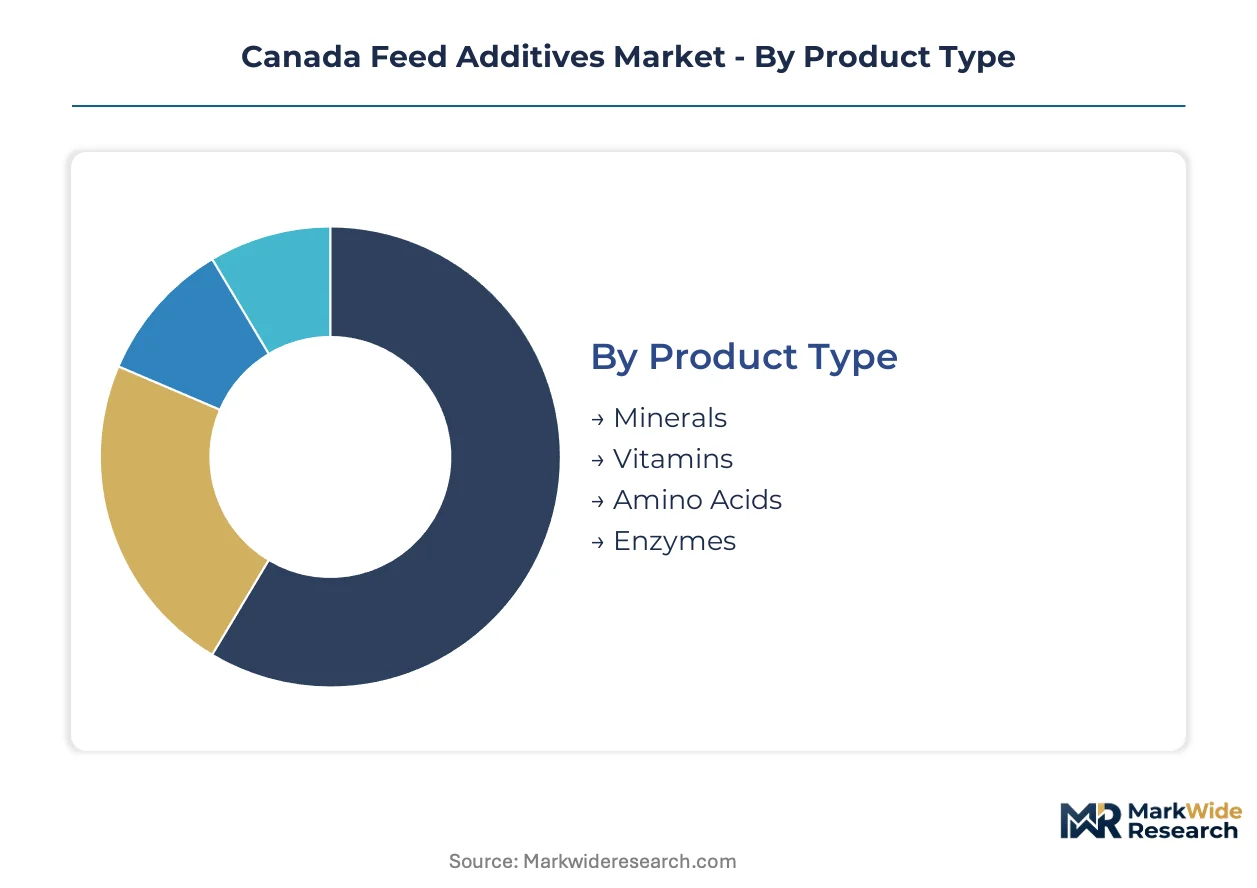
Canada's feed additive market segments reflect distinct procurement patterns across livestock operations, with each category exposing suppliers to different substitution pressures from alternative nutrition strategies and regulatory constraints.
Product Type:
Enzyme formulations face the most acute substitution pressure as heat-stable alternatives and on-farm liquid application systems displace traditional dry-blend premixes in Ontario poultry operations.
- Minerals:Macro and trace mineral premixes supply calcium, phosphorus, and selenium to correct dietary deficiencies. Alberta and Saskatchewan feedlots drive bulk procurement through long-term supply contracts that lock in volume commitments across finishing cycles.
- Vitamins:Fat-soluble and water-soluble vitamin blends prevent metabolic disorders and support immune function. Prairie cattle finishing intensity concentrates demand in fat-soluble formulations, particularly vitamins A, D, and E for feedlot rations.
- Amino Acids:Synthetic lysine, methionine, and threonine correct protein imbalances in corn-soybean diets.
- Enzymes:Phytase and xylanase formulations degrade anti-nutritional factors in cereal-based rations.
Minerals anchor the volume base while enzymes gain share at the steepest rate as heat-stable formulations survive pelleting temperatures above 85°C.
End User:
Cost tier differentiation separates commodity livestock operations from premium aquaculture and precision dairy systems that command formulation premiums.
- Poultry:Intensive barn operations in Ontario and British Columbia consume the largest additive volumes, with broiler integrators in the London-Woodstock corridor negotiating direct formulation partnerships that bypass distributor intermediaries.
- Ruminants:Cattle, sheep, and goat operations require mineral and vitamin supplementation for forage-based diets. Alberta feedlots consolidate procurement into contracted supply relationships, locking in additive commitments across multi-year finishing programs.
- Swine:Independent hog producers in Ontario utilize e-commerce channels for customized premix orders.
- Aquaculture:Atlantic salmon producers in New Brunswick and Newfoundland adopt functional gut-health additives, representing the most rapidly expanding margin pool as operations pre-qualify suppliers based on veterinary drug master file portfolios.
Poultry anchors the volume base while aquaculture climbs the fastest as fewer than fifteen integrated operations concentrate demand for premium functional additives.
Application:
Volume concentration favors nutritional enhancement applications where standardized inclusion rates simplify procurement, while health management applications fragment across species-specific therapeutic requirements.
- Growth Promotion:Additives that improve feed conversion ratios and daily weight gain through metabolic optimization. Ruminant feedlots prioritize growth promotion minerals in Alberta and Saskatchewan where finishing intensity drives bulk procurement.
- Nutritional Enhancement:Formulations that correct dietary deficiencies and optimize nutrient density. Poultry integrators in Ontario rely on precision amino acid blends to balance corn-soybean rations at least cost.
- Digestibility Improvement:Enzyme and acidifier applications that increase nutrient bioavailability.
- Health Management:Gut-health additives, mycotoxin binders, and immune-support compounds.
Nutritional enhancement anchors the volume base while health management expands most quickly as antimicrobial alternatives face tightened residue surveillance protocols.
Distribution Channel:
Customer type bifurcation separates integrated operations with direct manufacturer relationships from independent producers dependent on distributor networks and retail access.
- Direct Sales:Contracted supply relationships between manufacturers and integrated livestock operations capture the largest value share. Ontario broiler integrators negotiate direct formulation partnerships that displace traditional distributor intermediaries.
- Wholesale:Regional distributors serve mid-scale operations and cooperatives across Prairie provinces. Legacy feed mill integration challenges force smaller cooperatives toward consolidation to absorb retrofitting capital requirements.
- Retail:Farm supply stores and agricultural cooperatives serve independent producers with smaller volume requirements.
- E-Commerce:Digital platforms for customized premix orders bypass traditional distributor markups.
Direct sales anchors the volume base while e-commerce gains share at the steepest rate as on-farm liquid application systems fragment volume toward distributed dosing equipment vendors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal Clean Fuel Regulation crediting mechanisms for methane-reducing cattle additives are redirecting supplier investment toward Prairie feedlot corridors. Health Canada's pending Feeds Regulations amendments are compressing provincial registration timelines, forcing preemptive compliance investments across manufacturing networks.
Ontario
Intensive poultry barn operations in the London-Woodstock corridor drive bulk amino acid procurement through direct manufacturer contracts. Health Canada's Veterinary Drugs Directorate residue surveillance protocols tighten documentation requirements for antimicrobial alternatives entering the province. Broiler integrators in southwestern Ontario are consolidating additive sourcing into three dominant supply relationships, displacing traditional distributor intermediaries.
Quebec
Robotic milking operations in the Montérégie region generate underpenetrated demand for precision sensor-integrated additive dosing systems. The Canadian Food Inspection Agency's Safe Feed/Safe Food certification mandates are filtering non-compliant premix suppliers from provincial distribution networks. Dairy cooperatives in the Saint-Hyacinthe cluster are piloting automated mineral supplementation tied to real-time milk composition data.
Alberta
Large-scale cattle finishing feedlots consolidate mineral and vitamin procurement into multi-year supply contracts locking volume commitments. The Clean Fuel Regulation's compliance credit framework creates dual revenue streams for methane-reducing feed additive suppliers serving provincial ruminant operations. Calgary-area formulation facilities are retrofitting for real-time additive dosing to capture feedlot automation contracts.
British Columbia
Intensive poultry operations in the Fraser Valley anchor western Canadian additive consumption for enzyme and amino acid blends. The Canadian Grain Commission's mycotoxin monitoring programs elevate demand for binder additives during elevated fusarium pressure years. Vancouver port infrastructure supports import logistics for specialized aquaculture gut-health additives destined for Atlantic salmon producers.
Atlantic Canada
Integrated salmon aquaculture operations in New Brunswick and Newfoundland concentrate demand for premium functional gut-health additives among fewer than fifteen buyers. Health Canada's tightened pharmacokinetic documentation requirements for novel peptides are extending supplier pre-qualification timelines. Saint John-area distributors are building veterinary drug master file portfolios to meet pre-qualification criteria for premium additive supply.
Canada Feed Additives Market Competitive Environment
Player mix skews toward integrated grain-handling conglomerates with captive premix manufacturing and specialized precision-coating technology firms. Market structure concentrates value capture among vertically integrated suppliers controlling Prairie distribution corridors, while mid-scale regional formulators face certification barriers. Two strategic archetypes dominate: multinational nutrition conglomerates leveraging global R&D scale, and domestic coating specialists engineering heat-stable delivery systems. Competitive moves center on retrofitting legacy feed mill infrastructure for automated dosing and securing Safe Feed/Safe Food certification ahead of regulatory enforcement deadlines.
Among North American nutrition conglomerates, Cargill Inc. and Archer Daniels Midland Co. occupy positions anchored by grain-handling infrastructure integration. DSM-Firmenich and Evonik Industries AG represent the precision-chemistry archetype with specialized amino acid and enzyme portfolios. Jefo Nutrition Group exemplifies the domestic coating specialist model, engineering delivery systems for pelleting temperature survival. Elanco Animal Health Inc. and Alltech, Inc. sit within the health-management additive tier, while Canadian Bio-Systems Inc. anchors regional formulation capabilities. IFF (Danisco Animal Nutrition) occupies a position bridging enzyme technology with global manufacturing scale.
| Leading Market Players |
|---|
| Archer Daniels Midland Co. |
| DSM-Firmenich |
| Elanco Animal Health Inc. |
| Evonik Industries AG |
| IFF (Danisco Animal Nutrition) |
| Cargill Inc. |
| Jefo Nutrition Group |
| Canadian Bio-Systems Inc. |
| Alltech, Inc. |
| Others |
Value Chain & Pricing Dynamics
CFIA Safe Feed/Safe Food certification gates both supplier qualification and price differentiation simultaneously, filtering non-compliant premix manufacturers from provincial distribution networks while enabling certified operators to command formulation premiums. Prairie feedlot procurement consolidation and Ontario poultry integrator direct contracting compress distributor margins and reshape volume allocation across tiered service levels.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with CFIA-verified manufacturers capturing 15-20% formulation premiums over uncertified competitors. Volume scale and heat-stability performance differentiate mid-tier offerings, while independent hog producers in Ontario exhibit highest price sensitivity through e-commerce channel migration. Cost compression in conventional dry-blend enzymes is intensifying because on-farm liquid application systems displace centralized pelleting infrastructure.
Supply Chain Analysis
Inventory cycles for heat-stable enzyme precursors extend lead times during Prairie harvest peaks, forcing feedlots to pre-position mineral volumes ahead of finishing cycles. Manufacturing concentrates in Canada and the United States, with specialty coating inputs sourced from Germany and the Netherlands. The supply chain draws from single-source vulnerability in precision-coating chemistry, while distribution runs through direct manufacturer relationships with integrated livestock operations and wholesale networks serving regional cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Health Canada's pending Feeds Regulations amendments represent a regulatory inflection compressing registration timelines for novel microbial additives, creating high-growth disruption as manufacturers preempt compliance investments ahead of classification shifts.
For Market Incumbents: Fortify CFIA certification coverage across Prairie manufacturing networks to defend against emerging precision-coating specialists capturing feedlot automation contracts. Backward integration into captive grain-handling infrastructure locks in volume commitments against distributor disintermediation by Ontario poultry integrators. For New Entrants and Emerging Players: Anchor in Quebec's robotic milking operations in the Montérégie region, where sensor-integrated additive dosing systems remain underpenetrated relative to precision dairy demand. Target Atlantic salmon aquaculture operations through veterinary drug master file portfolio pre-qualification, leveraging Saint John distributor relationships for market access. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional formulators lacking Safe Feed/Safe Food certification infrastructure. Long-term viability over a 5-10 year window favors coating technology specialists with heat-stability IP and regulatory dossier capabilities. Watch Health Canada's microbial reclassification implementation as the signal for competitive timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| CFIA Safe Feed/Safe Food Certification Investment | Filters non-compliant suppliers from Prairie distribution corridors while enabling premium pricing capture. |
| Heat-Stability Engineering R&D | Extends enzyme activity survival above 85°C pelleting temperatures for Ontario poultry integrator contracts. |
| Real-Time Additive Dosing Retrofit | Captures Alberta feedlot automation contracts under Clean Fuel Regulation methane crediting frameworks. |
| Veterinary Drug Master File Portfolio Build | Pre-qualifies suppliers for Atlantic salmon aquaculture gut-health additive procurement concentration. |
| E-Commerce Formulation Platform Launch | Bypasses distributor markups in Ontario independent hog sector through direct-to-farm digital channels. |
Study Parameters
Cross-validation between regulatory filing analysis and trade data anchors the qualitative findings, combining primary interviews with feed mill operations managers, CFIA compliance officers, Prairie feedlot procurement directors, and aquaculture nutrition specialists with secondary validation through Health Canada Feeds Act amendments, Canadian Grain Commission mycotoxin reports, CFIA facility registration databases, and provincial agricultural statistics. Bottom-up volume triangulation across species-specific consumption rates converges with top-down value estimates from manufacturer revenue disclosures.
Sensitivity analysis across enzyme inclusion rate assumptions and cattle finishing cycle durations tests forecast robustness over the projection horizon. Segmentation dimensions modeled include product type, livestock species, application purpose, and distribution channel complexity, with CAGRs derived from historical volume trajectories and regulatory timeline impacts. Feed conversion ratio improvements and antimicrobial alternative substitution rates serve as industry-specific forecast inputs.
Material uncertainties — regulatory reclassification delays, fusarium pressure volatility, and feedlot consolidation pace — sit outside the modeled envelope. Forecasts reflect documented assumptions about certification adoption curves and precision technology penetration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
United States Bean Bags Market
Others
Exosome Technologies Market
Others
Social Media Engagement Applications Market
Others
Fresh Apples Market
Others
Stand-Up Pouch Valves Market
Others
Global Tobacco Market
Others
Lychee Market
Others
Latin America Video Conferencing Hardware Market
Others
Industrial Air Purifiers Market
Others
Global Social Networking Market
Others
Spinner Flask Market
Others
Solar Lighting Tower Market
Others
Vo5g Market
Others
North America Agricultural Enzymes Market
Others
Paper Shredder Market
Others
Aircraft Exterior Lighting Market