
 Anti-Microbial Anti-Fungal Test Market | 2026-2036
Anti-Microbial Anti-Fungal Test Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Microbial Anti-Fungal Test Market Analysis
Aftermarket service revenue for automated testing platforms is rewriting how vendors capture lifetime value from hospital customers. Thermo Fisher Scientific leverages its installed base of diagnostic instruments to sustain recurring consumable sales across high-throughput laboratories. bioMérieux anchors its competitive position through specialized culture-based and molecular diagnostic portfolios that dominate European reference labs.
Anti-microbial anti-fungal testing encompasses analytical methods that detect, identify, and quantify pathogenic microorganisms and fungal agents in clinical, environmental, and pharmaceutical samples, typically employing culture isolation, nucleic acid amplification, or immunochemical detection with sensitivity thresholds ranging from colony-forming units per milliliter to single-copy gene targets. These tests serve the primary commercial purpose of guiding therapeutic decisions, validating sterilization protocols, and ensuring compliance with microbial contamination limits in regulated products. Automated systems command premium pricing due to labor reduction and standardization benefits, while molecular diagnostics represents the fastest-expanding technology segment as multiplex PCR and next-generation sequencing displace slower culture-based workflows in time-critical infectious disease management. Home tests remain nascent with limited reimbursement, concentrating margin pools in hospital and diagnostic laboratory channels where volume contracts and integrated instrument-reagent bundles prevail.
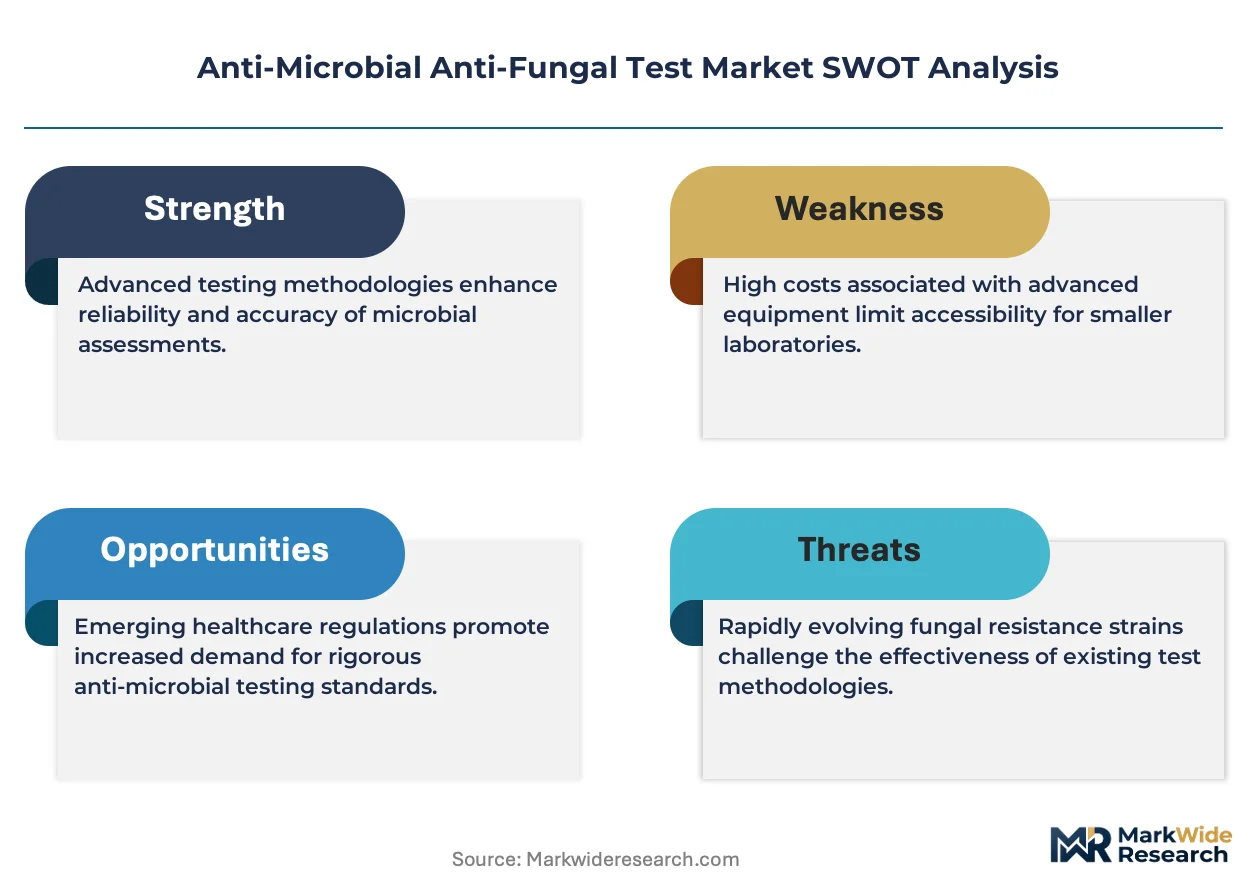
FDA oversight of in vitro diagnostic devices under the IVDR transition, EMA's infectious disease preparedness frameworks, and ISO 15189 accreditation requirements for clinical laboratories collectively elevate barriers to market entry while mandating continuous analytical performance verification. These regulatory frameworks compel manufacturers to invest in clinical validation studies and quality management systems that extend product development timelines but protect incumbent positions. Stakeholders must monitor evolving FDA guidance on antimicrobial susceptibility testing devices and EMA's pathogen-specific diagnostic qualification pathways to anticipate reimbursement and competitive access shifts.
Market Dynamics
Antimicrobial resistance surveillance mandates from FDA and EMA are forcing hospital laboratories to upgrade from culture-based workflows to molecular diagnostics platforms, compressing replacement cycles for diagnostic instruments and reshaping vendor-customer contracting structures toward integrated instrument-reagent bundles.
Growth Catalysts
- IVDR transition timelines:European laboratories face mandatory compliance deadlines under the In Vitro Diagnostic Regulation, accelerating capital deployment toward automated susceptibility testing systems that satisfy analytical performance verification requirements.
- Multiplex PCR adoption:Hospital microbiology departments in the United States are replacing sequential single-target assays with syndromic panels that detect bacterial and fungal pathogens simultaneously, driving reagent volume expansion.
- Environmental monitoring protocols:Pharmaceutical manufacturers in Germany must validate sterilization effectiveness under EMA guidance, sustaining demand for rapid microbial detection in cleanroom and finished-product testing.
Market Restraints
- Reagent supply concentration:Polymerase enzymes and fluorescent probes for molecular diagnostics originate from a limited supplier base in the United States, creating vulnerability to batch-to-batch variability and price volatility.
- ISO 15189 accreditation burden:Clinical laboratories in Japan must maintain continuous analytical performance verification under ISO standards, extending quality management system costs and staffing requirements.
- Culture-based method persistence:Reference laboratories in France retain gold-standard colony isolation for antifungal susceptibility testing, limiting molecular platform penetration in time-insensitive diagnostic pathways.
Strategic Opportunities
- Point-of-care decentralization:Emergency departments in the United Kingdom are deploying cartridge-based molecular systems that deliver pathogen identification within one hour, bypassing centralized laboratory bottlenecks.
- Next-generation sequencing convergence:Whole-genome sequencing platforms are integrating with antimicrobial resistance databases to predict susceptibility patterns directly from genetic markers, opening new service revenue streams.
- Home test channel development:Direct-to-consumer fungal infection screening faces limited reimbursement but presents margin capture potential through subscription-based result interpretation services in private healthcare markets.
Industry Challenges
- Bioinformatics skill scarcity:Clinical laboratories deploying sequencing-based diagnostics require computational biologists capable of interpreting complex resistance gene profiles, a workforce segment with severe supply constraints.
- Legacy LIS integration friction:Automated susceptibility testing instruments must interface with hospital laboratory information systems built on decades-old architectures, extending implementation timelines and customization costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Microbial Anti-Fungal Test Market |
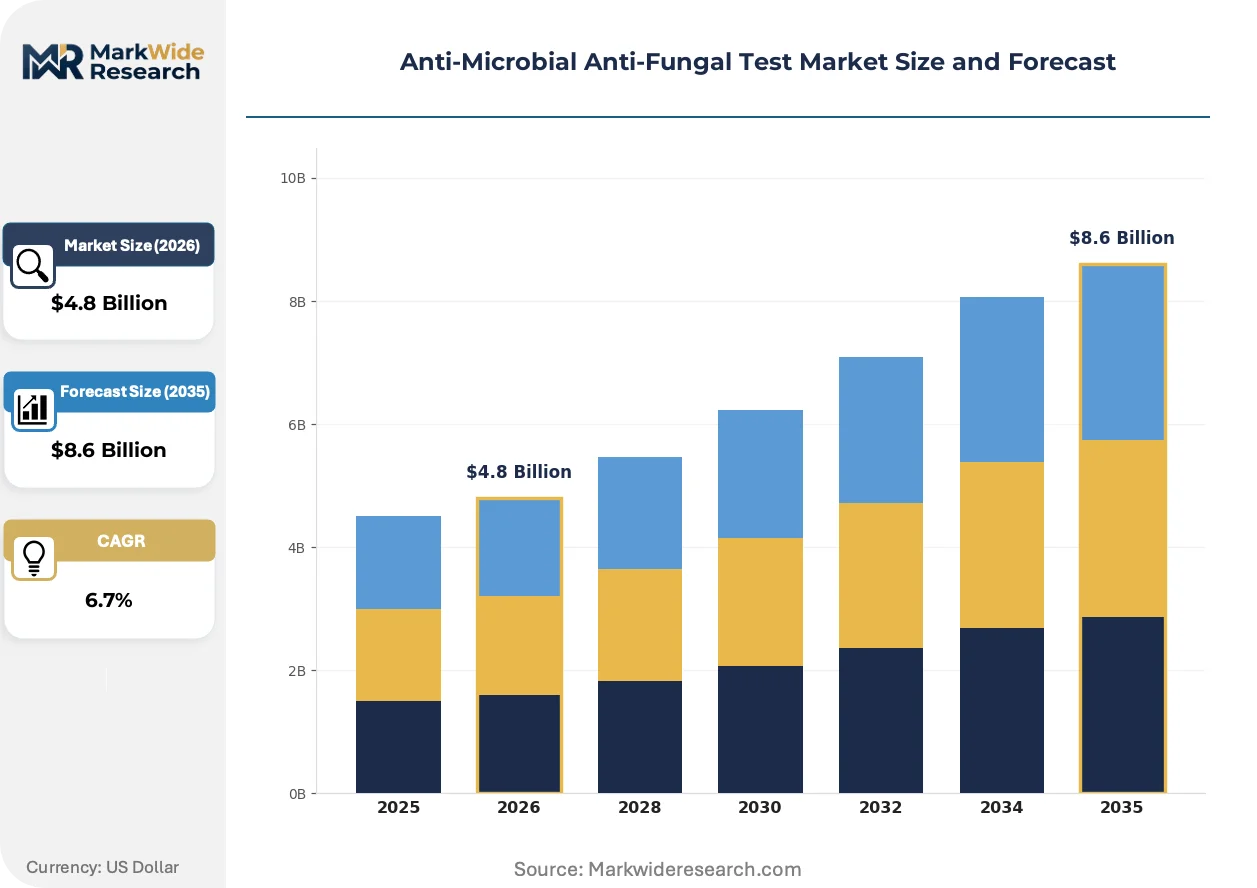
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid Tests, Laboratory Tests, Home Tests, Automated Systems End User: Hospitals, Diagnostic Labs, Research Institutions, Home Care Technology: Culture-Based, Molecular Diagnostics, Immunoassays, Microfluidics Application: Clinical Testing, Environmental Testing, Food Safety, Pharmaceutical |
| Companies Covered | Thermo Fisher Scientific, bioMérieux, Becton Dickinson and Company, Beckman Coulter, Bruker, Siemens Healthineers, QIAGEN, Bio-Rad Laboratories, Hologic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Microbial Anti-Fungal Test Market Emerging Trajectories
Digital pathology and cloud-based resistance surveillance are compressing the feedback loop between diagnostic result generation and therapeutic decision-making, shifting competitive advantage toward vendors with integrated data platforms rather than standalone instrument capabilities.
Artificial intelligence algorithms trained on mass spectrometry profiles are virtualizing microbial identification workflows that previously required skilled microbiologists to interpret biochemical test panels. Large hospital networks in Germany are deploying these systems to standardize species identification across geographically distributed laboratories. This virtualization is enabling 24-hour diagnostic coverage without proportional staffing increases, compressing the labor cost structure of high-throughput microbiology operations.
EMA's infectious disease preparedness frameworks now mandate diagnostic qualification pathways for pathogen-specific assays, requiring manufacturers to submit clinical validation data against reference methods before market authorization. This regulatory architecture elevates development costs but protects incumbent positions by extending competitive moats around validated assay portfolios. Reference laboratories in France and the Netherlands are prioritizing procurement from vendors with established EMA qualification track records, consolidating supplier relationships.
Consolidated purchasing agreements are reshaping how hospital procurement departments evaluate diagnostic platforms, with total cost of ownership models replacing upfront capital expenditure comparisons. Integrated delivery networks in the United States are negotiating multi-year reagent supply commitments tied to instrument placement, locking in volume discounts that independent laboratories cannot match. This concentration is most visible in the southeastern United States, where health system mergers have reduced the number of independent microbiology laboratories by half over the past decade.
Anti-Microbial Anti-Fungal Test Market Segmentation
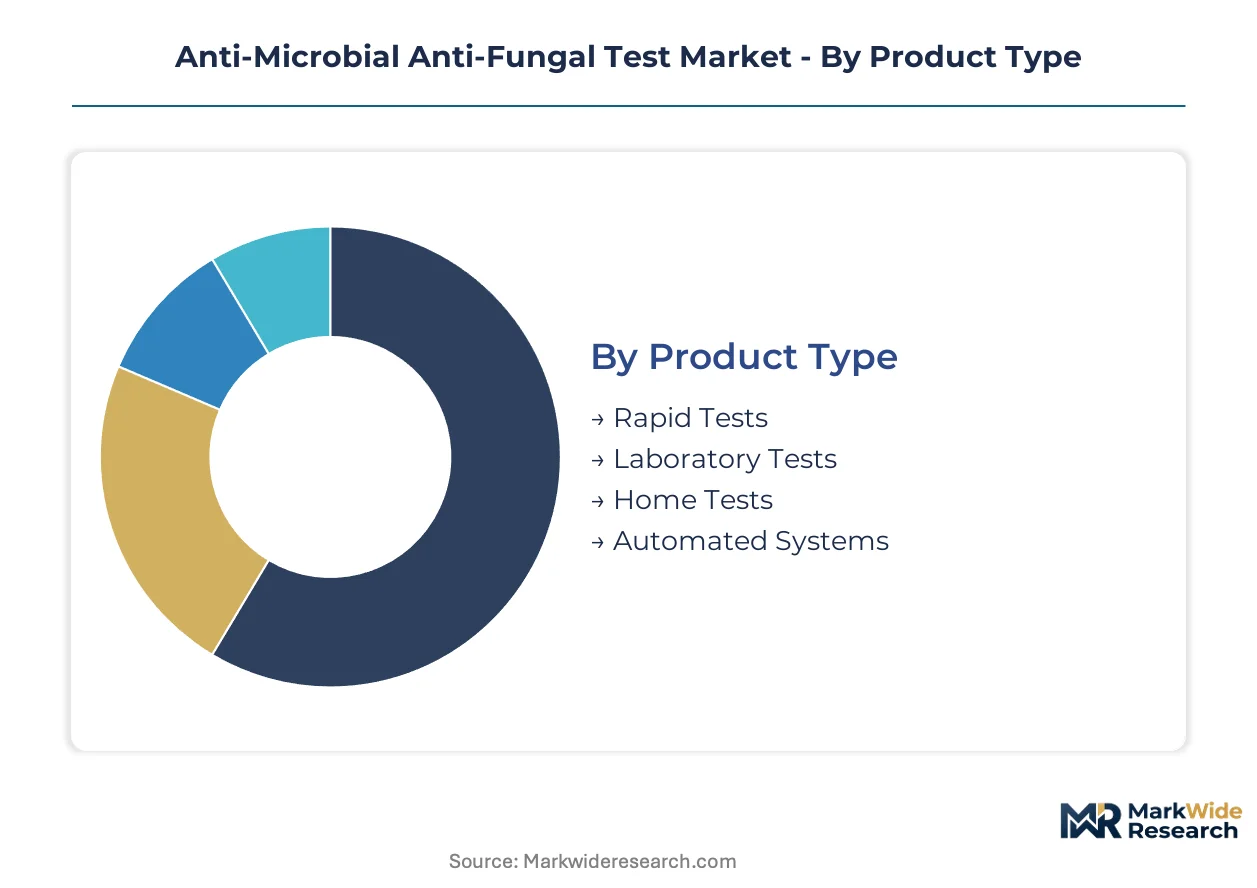
Segmentation in the Anti-Microbial Anti-Fungal Test Market reveals distinct replacement cycles and margin profiles across testing modalities. Hospital procurement departments evaluate segments through total cost of ownership lenses that favor automated platforms with extended service contracts over consumable-heavy alternatives.
Product Type:
Laboratory Tests and Automated Systems command the longest capital replacement cycles at seven to ten years, while Rapid Tests and Home Tests turn over within twelve to thirty-six months based on consumable consumption patterns.
- Laboratory Tests:Encompass culture-based susceptibility panels, biochemical identification systems, and manual microscopy workflows requiring specialized technician certification. Demand concentrates in tertiary care hospitals across Germany and Japan where antimicrobial stewardship programs mandate reference-grade analytical performance under EMA and PMDA frameworks.
- Automated Systems:Integrate specimen processing, incubation, and digital imaging modules that reduce hands-on time by sixty to eighty percent compared to manual methods. Academic medical centers in the United States prioritize these platforms to satisfy FDA antimicrobial resistance surveillance reporting requirements while managing staffing shortages in clinical microbiology departments.
- Rapid Tests:Lateral flow and cartridge-based assays delivering results within thirty minutes for emergency department triage decisions.
- Home Tests:Direct-to-consumer fungal infection screening kits with limited reimbursement coverage in private healthcare markets.
Laboratory Tests anchors the volume base while Rapid Tests gains share at the steepest rate.
End User:
Margin concentration varies sharply across customer types, with Hospitals capturing premium pricing through integrated instrument-reagent bundles while Home Care operates at lower price points with minimal service attachment.
- Hospitals:Drive seventy percent of molecular diagnostics revenue through centralized microbiology laboratories serving emergency, intensive care, and surgical units. Integrated delivery networks in the southeastern United States negotiate multi-year reagent commitments that independent laboratories cannot match, consolidating supplier relationships.
- Diagnostic Labs:Reference laboratories in France and the Netherlands maintain gold-standard culture isolation for antifungal susceptibility testing, limiting molecular platform penetration despite longer turnaround times.
- Research Institutions:Academic centers evaluating novel resistance mechanisms and therapeutic targets.
- Home Care:Nascent channel facing reimbursement barriers and regulatory complexity for unsupervised specimen collection.
Hospitals dominate current revenue contribution while Diagnostic Labs present the most concentrated procurement consolidation opportunity.
Technology:
Development timelines stretch from eighteen months for incremental immunoassay improvements to four years for next-generation sequencing validation under EMA qualification pathways.
- Molecular Diagnostics:Multiplex PCR and next-generation sequencing platforms detect bacterial and fungal pathogens simultaneously with sensitivity to single-copy gene targets. Hospital microbiology departments in the United States are displacing sequential single-target assays with syndromic panels that compress diagnostic turnaround from days to hours.
- Culture-Based:Colony isolation and biochemical identification remain the regulatory gold standard for antifungal susceptibility testing in European reference laboratories. EMA frameworks mandate these methods for clinical validation studies, extending competitive moats around established assay portfolios despite slower time-to-result.
- Immunoassays:Enzyme-linked and chemiluminescent detection systems for antigen and antibody quantification.
- Microfluidics:Lab-on-chip architectures integrating sample preparation, amplification, and detection in disposable cartridges.
Culture-Based technology retains the largest installed base while Molecular Diagnostics climbs the fastest as antimicrobial resistance surveillance intensifies.
Application:
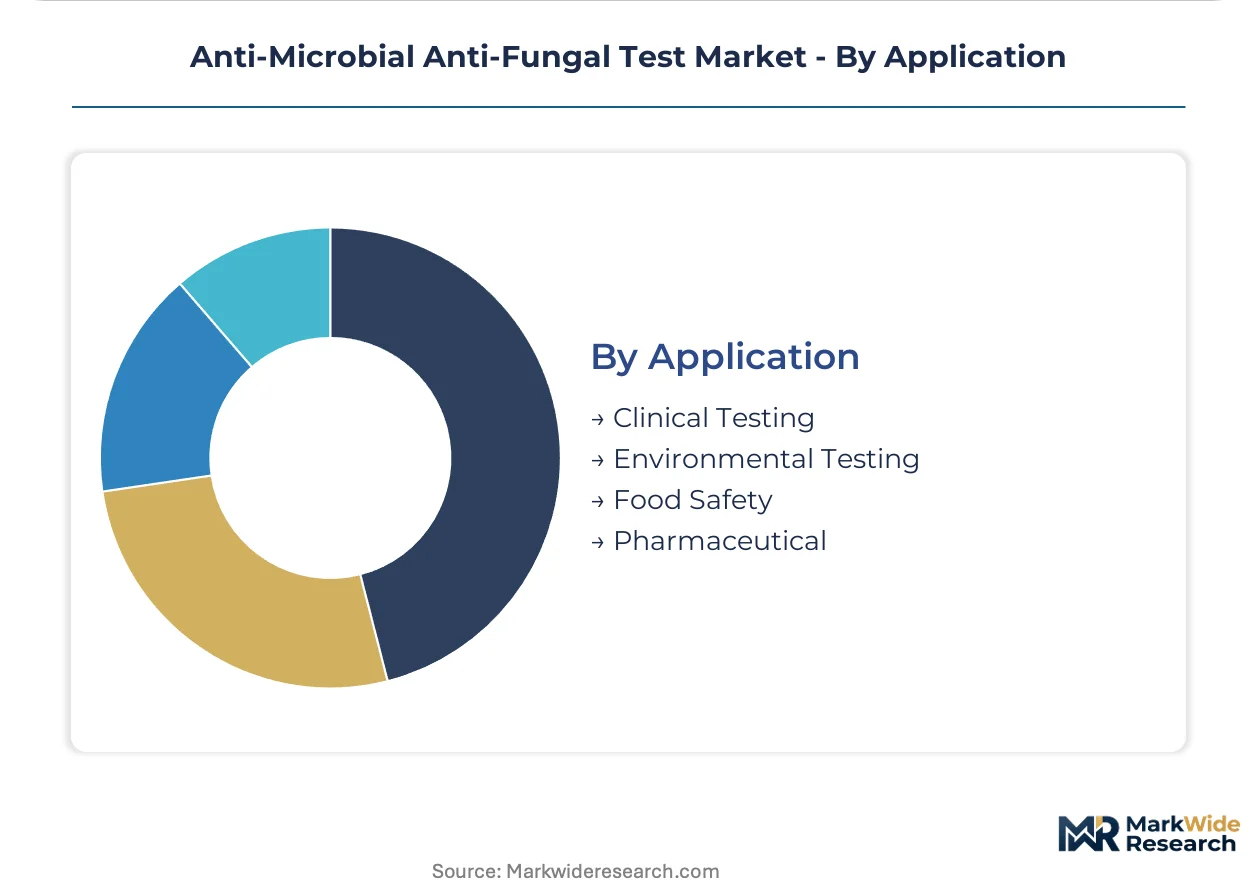
Regulatory stringency escalates from Environmental Testing through Food Safety to Clinical Testing and Pharmaceutical applications, with validation requirements directly determining pricing tiers.
- Clinical Testing:Patient specimen analysis for therapeutic decision support dominates revenue concentration. FDA oversight of in vitro diagnostic devices under evolving antimicrobial susceptibility testing guidance compels manufacturers to invest in clinical validation studies that extend product development timelines.
- Pharmaceutical:Sterility testing and microbial limits validation for finished product release under EMA guidance sustains demand for rapid microbial detection in cleanroom environments. German manufacturers prioritize procurement from vendors with established regulatory track records to minimize qualification risk.
- Environmental Testing:Cleanroom and water system monitoring for healthcare and manufacturing facilities.
- Food Safety:Pathogen detection in production environments and finished products under national food safety authority oversight.
Clinical Testing generates the deepest revenue pool while Pharmaceutical applications show the most pronounced pricing premium for validated assay portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital laboratories in the United States absorb premium pricing for automated susceptibility testing systems, while diagnostic facilities in India and Southeast Asia prioritize cost-efficient rapid tests that balance sensitivity with procurement budgets.
United States
Academic medical centers in Boston and the Research Triangle deploy multiplex PCR panels for antimicrobial resistance surveillance under FDA antimicrobial susceptibility testing guidance. The southeastern hospital networks negotiate multi-year reagent commitments that consolidate supplier relationships. Emergency departments in Atlanta and Houston pilot cartridge-based molecular systems delivering one-hour pathogen identification.
Germany
Pharmaceutical manufacturers in Bavaria and Baden-Württemberg validate sterilization protocols under EMA infectious disease preparedness frameworks. Reference laboratories in Heidelberg and Munich maintain gold-standard culture isolation for antifungal susceptibility testing despite slower turnaround times. Siemens Healthineers anchors diagnostic instrument production in Erlangen.
Japan
Clinical laboratories in Tokyo and Osaka maintain ISO 15189 accreditation for continuous analytical performance verification under PMDA oversight. Tertiary care hospitals in Kansai prioritize molecular diagnostics platforms for antimicrobial stewardship programs. METI funding accelerates next-generation sequencing integration with national resistance surveillance databases.
France
Reference laboratories in Paris and Lyon retain colony isolation methods for EMA-mandated clinical validation studies, extending competitive moats around established assay portfolios. The Île-de-France region concentrates diagnostic procurement from vendors with established regulatory track records. ANSM qualification pathways shape vendor selection criteria for hospital microbiology departments.
United Kingdom
Emergency departments in London and Manchester deploy point-of-care molecular systems bypassing centralized laboratory bottlenecks. NHS procurement frameworks favor total cost of ownership models over upfront capital expenditure comparisons. The Oxford-Cambridge corridor hosts sequencing-based diagnostics development targeting antimicrobial resistance prediction.
Anti-Microbial Anti-Fungal Test Market Vendor Landscape
Full-line diagnostic conglomerates and specialized microbiology houses split the market into distinct capability tiers. Thermo Fisher Scientific leverages installed base economics to sustain recurring consumable sales across high-throughput laboratories. bioMérieux anchors European reference lab relationships through specialized culture-based and molecular portfolios. The competitive arena rewards integrated instrument-reagent bundles and multi-year service contracts over standalone product sales.
Among diversified life science conglomerates, Thermo Fisher Scientific and Becton Dickinson occupy positions defined by scale-driven reagent supply and global distribution infrastructure. bioMérieux represents the specialized microbiology archetype with concentrated European reference laboratory presence. QIAGEN sits within the molecular diagnostics tier, anchoring nucleic acid extraction and amplification workflows. Siemens Healthineers exemplifies the integrated healthcare technology model spanning imaging and laboratory diagnostics.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| bioMérieux |
| Becton Dickinson and Company |
| Beckman Coulter |
| Bruker |
| Siemens Healthineers |
| QIAGEN |
| Bio-Rad Laboratories |
| Hologic |
| Others |
Supply Flow & Price Mechanics
Erlangen and the Bavarian diagnostics manufacturing corridor anchor polymerase enzyme and fluorescent probe production capacity, concentrating upstream supply power among a handful of specialized biochemical suppliers whose batch consistency directly shapes downstream reagent pricing for molecular diagnostics platforms.
Pricing Analysis
Aftermarket service revenue tiers including extended maintenance contracts and calibration subscriptions drive lifetime value capture for automated susceptibility testing platforms. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared multiplex PCR systems from CE-marked mid-tier instruments and basic rapid immunoassay readers. Price differentiation rests on ISO 15189 accreditation support and integrated LIS connectivity as value-added bundles. Cost compression in the rapid test segment is intensifying because diagnostic laboratories in Southeast Asia prioritize procurement budgets over analytical performance verification. Hospital procurement committees in integrated delivery networks exhibit the lowest price sensitivity due to multi-year reagent commitment structures, while independent reference laboratories in Eastern Europe face acute budget constraints.
Supply Chain Analysis
Upstream feedstock for molecular diagnostics reagents draws from specialized enzyme production facilities in the United States, Germany, and Japan, where fermentation-derived polymerases and synthetic fluorescent probes undergo multi-step purification. Raw material dependencies center on recombinant protein expression systems, oligonucleotide synthesis substrates, and stabilized master mix formulations. Single-source vulnerability concentrates in thermostable DNA polymerase supply, where proprietary strain development creates captive supplier relationships. Distribution runs through authorized distributor networks serving hospital laboratories and reference centers, with direct-to-manufacturer procurement emerging among large health systems negotiating instrument-reagent bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect around interoperability standards for laboratory information systems, where middleware compatibility between automated susceptibility testing instruments and hospital EMR architectures determines vendor lock-in durability and switching cost trajectories.
For Market Incumbents: Pre-empt emerging point-of-care molecular system entrants by embedding cartridge-based compatibility layers within existing automated platform software architectures. Consolidate position through backward integration into polymerase enzyme production, securing supply continuity against batch variability disruptions. Prioritize FDA antimicrobial susceptibility testing guidance alignment ahead of IVDR transition deadlines to extend competitive moats.
For New Entrants and Emerging Players: Southeast Asian diagnostic laboratories present the most penetrable white-space target, where cost-efficient rapid test procurement balances sensitivity requirements against constrained capital budgets. India's tertiary care hospital expansion under national health mission funding creates instrument placement opportunities without incumbent reagent lock-in. Pursue regulatory qualification partnerships with established reference laboratories to accelerate EMA pathway navigation.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates seeking portfolio rationalization away from microbiology-specialized divisions toward oncology or cell therapy platforms. Long-term viability frames around resistance surveillance mandate durability and molecular platform replacement cycle compression. Watch for next-generation sequencing convergence signals as antimicrobial resistance prediction algorithms achieve clinical validation against phenotypic reference methods.
| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Compliance Acceleration | EMA qualification pathway completion protects European reference laboratory access against regulatory deadline disruption. |
| Reagent Supply Integration | Backward control over polymerase production buffers margin compression from upstream biochemical price volatility. |
| Point-of-Care Cartridge Launch | Emergency department deployment in NHS trusts bypasses centralized laboratory bottlenecks and captures triage decision workflow. |
| LIS Middleware Development | Interoperability layer investment raises switching costs for hospital customers locked into legacy instrument architectures. |
| Sequencing Platform Partnership | Whole-genome resistance prediction integration with national surveillance databases opens service revenue streams in Germany and Japan. |
Methodological Framework
Initial hypotheses were tested against primary input from hospital microbiology directors, clinical laboratory managers, diagnostic instrument procurement officers, and regulatory affairs specialists at IVD manufacturers, then refined through secondary validation against FDA 510(k) filings, EMA IVDR technical documentation, ISO 15189 accreditation body reports, and hospital GPO contract databases. Bottom-up triangulation across installed base estimates and reagent consumption patterns was cross-checked against top-down market sizing derived from instrument shipment data and average selling price benchmarks.
Demand-supply-balance framing anchored the forecast framework, modeling test volume expansion against manufacturing capacity constraints across the analysis window. Segmentation dimensions included technology platform, end-user facility type, application area, and regional regulatory cluster. CAGRs were derived from replacement cycle compression rates and resistance surveillance mandate intensity trajectories. Industry-specific inputs incorporated antimicrobial stewardship program adoption curves and EMA infectious disease preparedness framework implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese diagnostic platform entrants or sequencing-native startups would shift outcomes beyond modeled ranges. Cross-checking against national health expenditure data and hospital capital equipment budget surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
B-Glucuronidase Enzymes Market
Industrial Microbiology
Bacillus Coagulans Market
Industrial Microbiology
Microbial Seed Treatment Market
Industrial Microbiology
Salinomycin Market
Industrial Microbiology
Global Microbial Identification Market
Industrial Microbiology
Eubiotics Market
Industrial Microbiology
Global Microbial Fermentation Technology Market
Industrial Microbiology
Global Escherichia Coli Testing Market
Industrial Microbiology
Bacterial Amylase Market
Industrial Microbiology
Europe Microbial Based Biological Seed Treatment Market
Industrial Microbiology
Global Microbial Protein Market
Industrial Microbiology
Molecular Microbiology Market
Industrial Microbiology
Microbiology Testing Market
Industrial Microbiology
Cultured Dextrose Market
Industrial Microbiology
Microbial Protein Used in Feed Market
Industrial Microbiology
Microbial Biosurfactants Market