
 Microbiome Sample Preparation Technology Market | 2026-2036
Microbiome Sample Preparation Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Microbiome Sample Preparation Technology Market Intelligence
CLIA-grade extraction fidelity is bifurcating the competitive landscape into clinical-validated and research-grade supply tiers. QIAGEN leverages its regulatory dossier depth to anchor premium positions in diagnostic laboratories. Thermo Fisher Scientific sustains broad catalog breadth across automated and manual technology segments. Zymo Research specializes in rapid-spin column chemistries that compete on turnaround time for environmental and agricultural research applications.
Microbiome sample preparation technology encompasses the integrated hardware, reagent systems, and protocols used to isolate, purify, and stabilize microbial nucleic acids, proteins, or whole cells from complex matrices including stool, soil, biofilm, and tissue specimens, typically operating at throughput scales from single-tube manual processing to 96/384-well automated formats with DNA integrity thresholds above 20 kb. The primary purpose spans enabling accurate taxonomic profiling, functional gene analysis, and strain-level resolution for downstream sequencing, qPCR, or mass spectrometry workflows. Extraction kits and purification kits together capture the dominant margin pool as recurring consumable demand outpaces capital equipment replacement cycles. Automated technology leads absolute revenue contribution while microfluidics represents the fastest-expanding technology segment as miniaturization reduces reagent cost per sample. Research institutions remain the largest end-user category by volume, though pharmaceutical companies now exhibit the steepest adoption trajectory for clinical-grade preparation systems.
FDA guidance on live biotherapeutic products, EPA methods for environmental DNA recovery, and ISO 17025 accreditation requirements for diagnostic laboratories collectively shape product validation standards and market access conditions for vendors serving regulated workflows. The EU In Vitro Diagnostic Regulation and MDR frameworks impose additional conformity burdens on kit manufacturers seeking European clinical market entry. Stakeholders must monitor evolving pharmacopeial standards for nucleic acid extraction purity ratios as these specifications increasingly determine contract eligibility in pharmaceutical quality control settings.
Market Dynamics
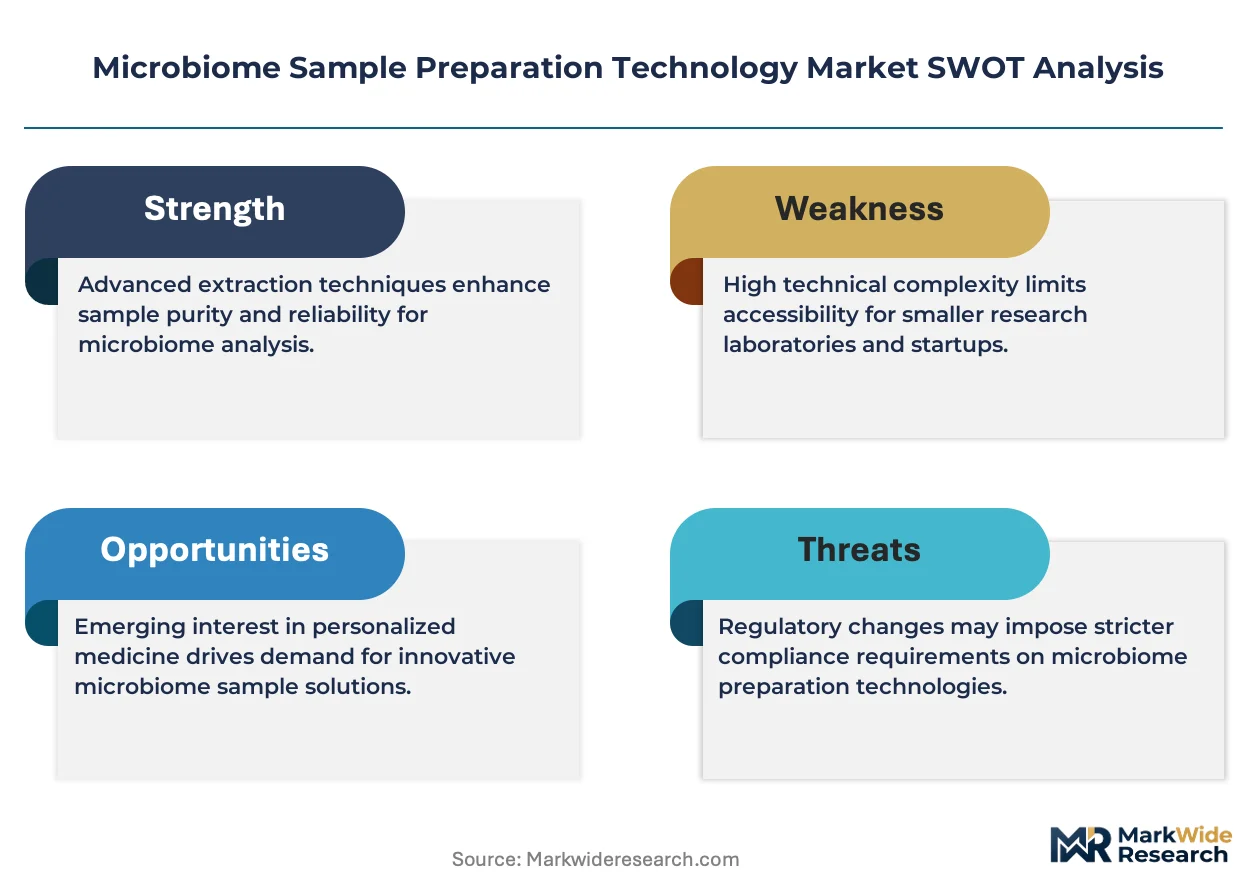
Automated extraction protocols are displacing manual workflows in high-throughput pharmaceutical laboratories, compressing turnaround times from hours to minutes while elevating nucleic acid yield consistency above 95% batch-to-batch fidelity thresholds.
Growth Catalysts
- FDA Live Biotherapeutic Products Guidance:Clarified regulatory pathways for microbiome-directed therapeutics have accelerated clinical investment and kit procurement volumes across US-based pharmaceutical pipelines.
- CLIA-grade extraction fidelity standards:Diagnostic laboratories now mandate clinical-validated preparation tiers, creating recurring consumable demand that outpaces capital equipment replacement cycles.
- Microfluidics miniaturization:Reduced reagent cost per sample is expanding addressable market penetration into environmental and agricultural research applications previously constrained by budget limitations.
Market Restraints
- Silica membrane supply concentration:Purification matrix production clusters in East Asian chemical manufacturing zones, exposing kit vendors to input cost volatility and logistics disruption risk.
- EU In Vitro Diagnostic Regulation conformity burdens:Extended certification timelines and notified body capacity constraints delay European clinical market entry for mid-tier manufacturers.
- Manual protocol substitution threat:Low-complexity research workflows in resource-constrained settings retain cost-driven preference for traditional phenol-chloroform extraction methods.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO alignment with ICH guidelines and PLI scheme incentives for biologics production create demand for GMP-compliant preparation systems.
- Single-cell microbiome analysis convergence:Integration of droplet microfluidics with long-read sequencing platforms opens strain-resolution applications in infectious disease diagnostics.
- Direct-to-consumer testing channel emergence:Wellness-focused gut health kits bypass traditional laboratory distribution, requiring simplified at-home collection and stabilization chemistries.
Industry Challenges
- Cross-functional talent scarcity:Hybrid expertise spanning microbial ecology, nucleic acid chemistry, and regulatory affairs commands premium compensation and constrains R&D team scaling.
- ISO 17025 accreditation timeline compression:Diagnostic laboratory contract eligibility demands accelerated validation documentation that strains quality assurance bandwidth.
- Legacy LIMS integration friction:Automated preparation platforms require middleware development to interface with established laboratory information management systems, extending deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbiome Sample Preparation Technology Market |
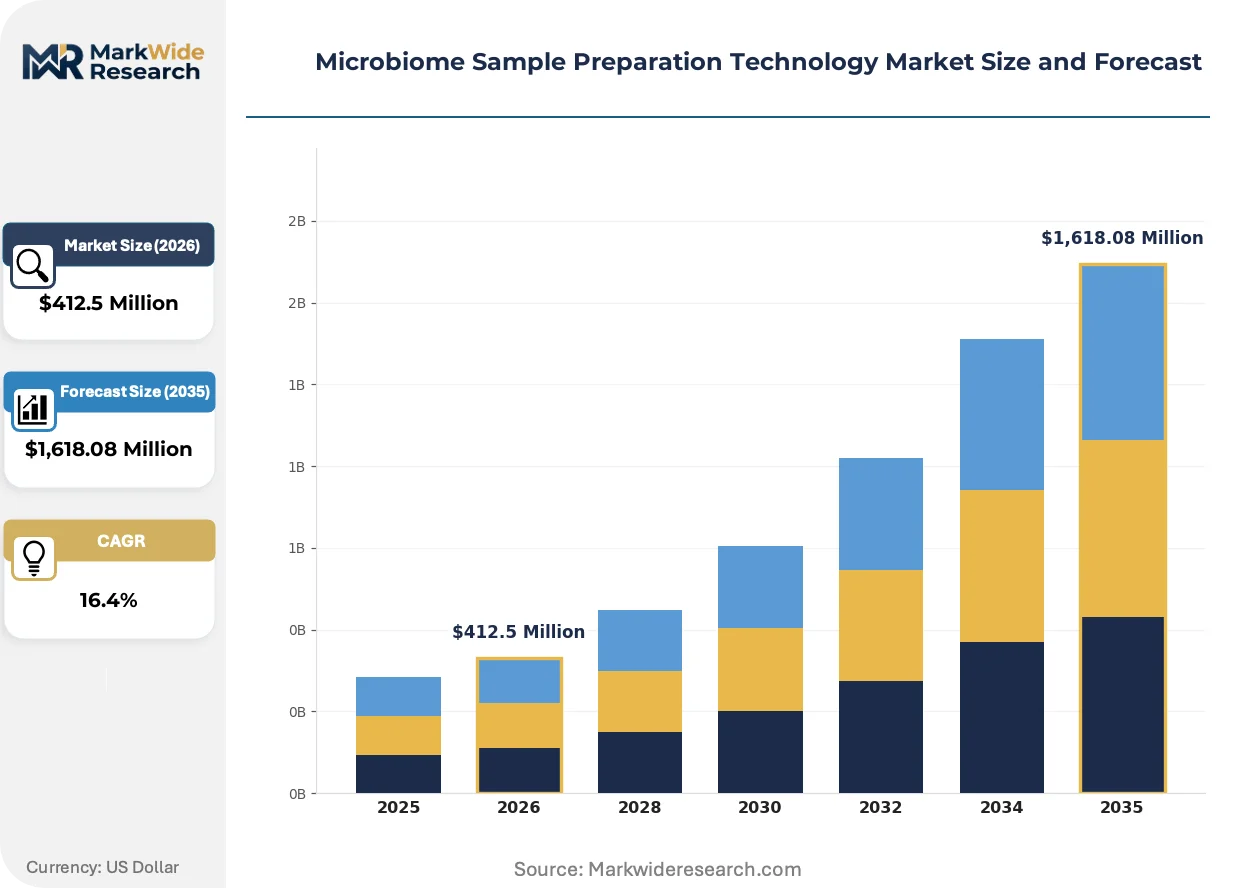
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,618.08 Million |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extraction Kits, Purification Kits, Reagents, Consumables Technology: Automated, Manual, Microfluidics, Matrix-Assisted End User: Research Institutions, Pharmaceutical Companies, Diagnostic Laboratories, Academic Labs Application: Clinical Research, Environmental Studies, Food Safety, Agricultural Research |
| Companies Covered | QIAGEN, Thermo Fisher Scientific, Illumina, Zymo Research, Danaher Corporation, BGI, Bio-Rad Laboratories, PerkinElmer, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbiome Sample Preparation Technology Market Strategic Shifts & Innovations
Workflow integration and miniaturization are compressing sample-to-data timelines while regulatory clarity is reshaping competitive tiering between research-grade and clinical-validated supply categories.
Magnetic bead-based extraction chemistries are displacing spin-column protocols in pharmaceutical quality control settings. High-throughput screening teams at contract research organizations have standardized on 96-well automated formats to process thousands of fecal specimens weekly. This displacement is compressing the addressable market for manual kit vendors and elevating instrument-agnostic reagent suppliers to preferred vendor status.
EMA qualification guidance for nucleic acid biomarkers in live biotherapeutic product development is harmonizing European validation standards with FDA precedents. Kit manufacturers must now maintain dual regulatory dossiers to serve transatlantic pharmaceutical clients. The diagnostic segment bears the heaviest documentation burden, with notified body audits extending certification cycles by 8-12 months relative to pre-MDR baselines.
Consolidated procurement through group purchasing organizations is concentrating buyer power among the largest academic medical centers and pharmaceutical central laboratories. Smaller research institutions find themselves priced out of volume-tier contracts and are migrating to regional distributor channels with bundled technical support. This channel rotation is most visible in the United States, where health system consolidation has reduced the number of independent purchasing decision-makers by over 40% in the past decade.
Microbiome Sample Preparation Technology Market Segmentation
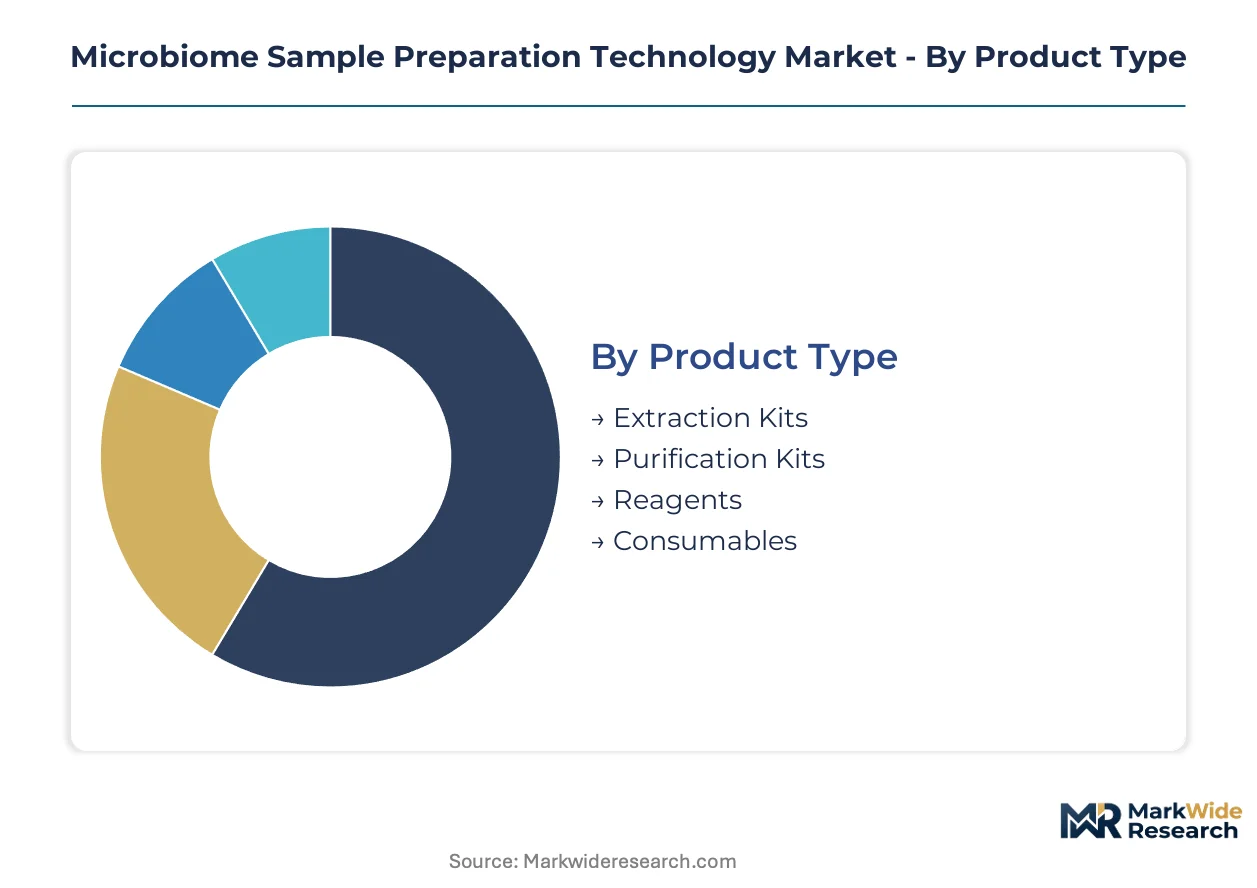
Technology choices in microbiome sample preparation cascade through validation requirements, throughput economics, and regulatory compliance tiers. Segmentation reveals where kit vendors concentrate R&D investment versus where price competition dominates procurement decisions.
Product Type:
Margin pools concentrate in recurring consumable formats rather than capital equipment, with extraction chemistry fidelity determining pricing power across clinical and research tiers.
- Extraction Kits:Integrated reagent systems isolate microbial nucleic acids from stool, soil, or tissue matrices with DNA integrity thresholds above 20 kb. Pharmaceutical quality control teams in the United States now mandate CLIA-grade extraction fidelity for live biotherapeutic product development, creating locked-in consumable demand.
- Purification Kits:Spin-column and magnetic bead formats remove PCR inhibitors and stabilize nucleic acids for downstream sequencing workflows. Environmental DNA researchers prioritize rapid-spin column chemistries that compete on turnaround time for high-sample-volume field studies.
- Reagents:Buffers, enzymes, and stabilization chemistries support custom protocol development in academic settings.
- Consumables:Plates, tubes, and tips complete automated workflow integration in high-throughput pharmaceutical laboratories.
Extraction kits hold installed capacity. Purification kits are rotating up the share rankings.
Technology:
Adoption velocity splits between throughput scale and miniaturization economics, with automated platforms capturing pharmaceutical volume and microfluidics penetrating budget-constrained research environments.
- Automated:96/384-well robotic platforms compress turnaround times from hours to minutes while maintaining above 95% batch-to-batch nucleic acid yield consistency. Contract research organizations processing thousands of fecal specimens weekly have standardized on these formats, displacing manual protocol market share in pharmaceutical settings.
- Manual:Single-tube spin-column workflows retain cost advantage in resource-constrained research institutions and low-complexity environmental sampling applications.
- Microfluidics:Droplet-based miniaturization reduces reagent cost per sample and opens strain-resolution applications through single-cell microbiome analysis convergence with long-read sequencing platforms.
- Matrix-Assisted:Specialized chemistries for biofilm and tissue specimen processing serve niche infectious disease diagnostic workflows.
Automated technology anchors current revenue contribution. Microfluidics is gaining share fastest as miniaturization expands addressable market penetration.
End User:
Procurement authority is consolidating through group purchasing organizations, concentrating vendor negotiation leverage among the largest academic medical centers and pharmaceutical central laboratories.
- Research Institutions:Academic laboratories and environmental research centers remain the largest category by sample volume, though pricing pressure from consolidated procurement channels is squeezing mid-tier kit vendors.
- Pharmaceutical Companies:Live biotherapeutic product pipelines are accelerating clinical-grade preparation system adoption with the steepest trajectory across all end-user categories.
- Diagnostic Laboratories:CLIA-certified facilities mandate ISO 17025-accredited preparation tiers with full regulatory dossier documentation.
- Academic Labs:Smaller research units are migrating to regional distributor channels with bundled technical support as independent purchasing decision-makers decline.
Research institutions hold legacy volume leadership. Pharmaceutical companies are climbing the fastest through clinical investment acceleration.
Application:
Validation burden intensity varies dramatically across use cases, with clinical and food safety applications demanding full regulatory compliance while environmental studies prioritize cost efficiency.
- Clinical Research:Microbiome-directed therapeutic development requires FDA-aligned extraction fidelity standards and dual regulatory dossiers for transatlantic pharmaceutical clients.
- Environmental Studies:EPA methods for environmental DNA recovery shape product validation standards, with budget constraints driving preference for rapid-turnaround manual protocols.
- Food Safety:Pathogen detection workflows require ISO-compliant preparation systems with documented batch traceability.
- Agricultural Research:Soil microbiome profiling for crop optimization combines high sample volumes with moderate fidelity requirements, favoring cost-optimized kit configurations.
Clinical research commands premium pricing tiers. Environmental studies are expanding most quickly as microfluidics miniaturization reduces per-sample costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based kit manufacturers export extraction chemistries to European pharmaceutical central laboratories and Asian contract research organizations, with transatlantic trade flows dominating high-fidelity consumable shipments.
United States
FDA guidance on live biotherapeutic products and CLIA-grade extraction fidelity standards drive pharmaceutical kit procurement volumes. The agency's clarified regulatory pathways for microbiome-directed therapeutics accelerate clinical investment in automated preparation systems. Greater Boston and San Diego biotech clusters host centralized laboratories processing thousands of fecal specimens weekly for therapeutic development pipelines.
Germany
EMA qualification guidance for nucleic acid biomarkers harmonizes European validation standards with FDA precedents, requiring dual regulatory dossiers from kit manufacturers. The country's notified body capacity constraints extend certification cycles for diagnostic-grade preparation tiers. Munich and Heidelberg academic medical centers consolidate procurement through group purchasing organizations, squeezing mid-tier vendor pricing power.
China
NMPA alignment with ICH guidelines and domestic biologics manufacturing expansion create demand for GMP-compliant preparation systems. The regulator's evolving pharmacopeial standards for nucleic acid extraction purity ratios determine contract eligibility in pharmaceutical quality control settings. Shanghai and Suzhou pharmaceutical manufacturing zones import automated extraction platforms to support live biotherapeutic product export capacity.
India
CDSCO alignment with ICH guidelines and PLI scheme incentives for biologics production drive adoption of clinical-grade preparation systems. The national pharmaceutical regulator's quality standards increasingly reference ISO 17025 accreditation requirements for diagnostic laboratory contracts. Hyderabad and Bangalore biotech corridors attract kit vendors establishing regional distribution hubs for South Asian pharmaceutical manufacturing.
United Kingdom
MHRA post-Brexit regulatory autonomy maintains alignment with EMA guidance while streamlining domestic certification timelines for kit manufacturers. The country's diagnostic laboratory network mandates ISO 17025-accredited preparation tiers for NHS contract eligibility. London and Cambridge research institutions rotate toward regional distributor channels as independent purchasing decision-makers decline under health system consolidation.
Microbiome Sample Preparation Technology Market Key Industry Players
Listed leaders compete with private specialists across regulatory dossier depth and automation platform breadth. The vendor base stratifies into clinical-validated tier holders, research-grade catalog breadth players, and rapid-turnaround chemistry specialists. Three archetypes dominate: diversified life science conglomerates with diagnostic regulatory infrastructure, pure-play nucleic acid extraction specialists competing on turnaround velocity, and sequencing platform integrators bundling preparation workflows. Competitive moves concentrate on M&A for regulatory dossier accumulation and strategic partnerships for automated platform integration.
Within the clinical-validated tier, QIAGEN and Thermo Fisher Scientific occupy positions anchored by regulatory infrastructure depth, while Zymo Research exemplifies the rapid-chemistry specialist archetype competing on environmental and agricultural research turnaround economics. These three entities represent the dominant competitive anchors across premium and mid-market positioning vectors, with QIAGEN and Thermo Fisher commanding pharmaceutical central laboratory relationships and Zymo Research penetrating budget-constrained field research settings.
| Leading Market Players |
|---|
| QIAGEN |
| Thermo Fisher Scientific |
| Illumina |
| Zymo Research |
| Danaher Corporation |
| BGI |
| Bio-Rad Laboratories |
| PerkinElmer |
| Agilent Technologies |
| Others |
Cost & Logistics Intelligence
Long-term consumable supply contracts lock in silica membrane access and stabilize reagent pricing for pharmaceutical central laboratories facing CLIA-grade extraction fidelity mandates. These arrangements tether kit vendors to East Asian chemical manufacturing zones while insulating high-volume buyers from spot-market volatility in purification matrix inputs.
Pricing Analysis
Current-generation automated magnetic bead platforms command three-tier pricing structure across premium, standard, and economy levels, while prior-generation spin-column formats face cost compression from microfluidics miniaturization. Price differentiation rests on ISO 17025 certification tier and batch-to-batch nucleic acid yield consistency above 95% thresholds. Pricing pressure stems from consolidated procurement through group purchasing organizations concentrating buyer leverage among academic medical centers. Research institutions exhibit highest price sensitivity due to budget constraints, while diagnostic laboratories prioritize regulatory dossier completeness over unit cost.
Supply Chain Analysis
China and Japan anchor silica membrane and magnetic bead production for extraction chemistry manufacturing, with Germany contributing specialized stabilization buffer formulations. Raw material dependencies center on high-purity silica substrates, rare-earth magnetic particles, and pharmaceutical-grade ethanol solvents. Supply chain risk concentrates in single-source vulnerability for CLIA-grade purification matrices certified under FDA live biotherapeutic products guidance. Distribution runs through direct vendor relationships with pharmaceutical central laboratories and regional distributor channels serving fragmented academic research markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored by regulatory entrenchment, where CLIA-grade extraction fidelity standards and dual FDA-EMA dossier requirements create switching costs that lock pharmaceutical clients into validated supply relationships.
For Market Incumbents: Compound regulatory dossier depth through accelerated ISO 17025 accreditation investments to defend against emerging microfluidics specialists threatening turnaround-time economics. Prioritize backward integration into silica membrane production to mitigate East Asian supply concentration risk and secure input cost visibility for long-term pharmaceutical contracts. For New Entrants and Emerging Players: Lead with simplified at-home collection chemistries targeting direct-to-consumer gut health testing channels that bypass consolidated laboratory procurement. Agricultural research applications in India offer the most penetrable geography, where CDSCO-aligned quality standards and PLI scheme incentives create demand for cost-optimized rapid-spin column formats without full clinical validation burdens. For Investors and Strategic Acquirers: The market sits at a clinical-validation consolidation phase that favors acquisition targets with existing FDA live biotherapeutic products regulatory dossiers and established pharmaceutical central laboratory relationships. Over the projection horizon, viability hinges on notified body capacity resolution in Europe and NMPA harmonization progress in China. Monitor EMA qualification guidance publication velocity as the critical inflection signal for transatlantic regulatory arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Accumulation | Dual FDA-EMA validation infrastructure secures pharmaceutical central laboratory contract eligibility. |
| Microfluidics Platform Integration | Droplet-based miniaturization reduces reagent cost per sample for environmental DNA research expansion. |
| Backward Integration into Silica Membranes | In-house purification matrix production mitigates East Asian supply concentration and input volatility. |
| Direct-to-Consumer Channel Development | At-home gut health kits bypass consolidated GPO procurement and capture wellness-focused end-user demand. |
| Single-Cell Microbiome Convergence | Long-read sequencing integration opens strain-resolution applications in infectious disease diagnostics. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with kit manufacturing executives, diagnostic laboratory directors, pharmaceutical regulatory affairs leads, and academic research principal investigators; and secondary validation through FDA live biotherapeutic products guidance documents, EMA qualification guidance publications, ISO 17025 accreditation registries, and pharmaceutical quality control procurement databases. Bottom-up triangulation across extraction kit shipment volumes and top-down reconciliation against automated platform installation bases anchored market sizing.
Across the analysis window, the forecasting framework modeled technology adoption curves, end-user procurement consolidation patterns, and regulatory timeline compression effects. Segmentation dimensions included product type fidelity tiers, automation throughput scale, and geographic regulatory cluster alignment. CAGRs derived from pharmaceutical pipeline expansion rates and diagnostic laboratory accreditation velocity, with cross-reference to CLIA-certified facility growth and biologics manufacturing capacity buildouts.
Forecasts assume regulatory continuity in FDA live biotherapeutic products guidance and EMA MDR implementation timelines; material policy shifts in CDSCO or NMPA alignment protocols would require re-modeling. Specific risks include notified body capacity constraints extending European certification cycles and silica membrane supply disruptions from East Asian logistics chokepoints. Recalibration cycles align with material shifts in pharmacopeial standards for nucleic acid extraction purity ratios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Cultured Dextrose Market
Industrial Microbiology
Galactosidase Market
Industrial Microbiology
Mycoplasma Plate Antigens Market
Industrial Microbiology
Molecular Microbiology Market
Industrial Microbiology
Salinomycin Market
Industrial Microbiology
Microbial Identification Panels Market
Industrial Microbiology
B-Glucuronidase Enzymes Market
Industrial Microbiology
Lactic Acid Bacteria Market
Industrial Microbiology
Real Time Continuous Microbiological Monitoring Systems Market
Industrial Microbiology
Lipase Market
Industrial Microbiology
Automated Microbial Detection Systems Market
Industrial Microbiology
Global Microbial Based Biological Seed Treatment Market
Industrial Microbiology
Microbial Biosurfactants Market
Industrial Microbiology
Automated Microbiology Market
Industrial Microbiology
Europe Microbial Based Biological Seed Treatment Market
Industrial Microbiology
Specialty Cultures Market