
 North America Microbial Protein Market | 2026-2036
North America Microbial Protein Market Size, Share, and Industry Trends Forecast 2026-2036
North America Microbial Protein Market Analytics
The North America microbial protein market is restructuring around a sharp divergence between premium single-cell protein isolates for human nutraceuticals and commodity-grade biomass for animal feed applications. Cargill leverages its grain handling infrastructure to anchor feed-grade fermentation supply chains across the Midwest. ENOUGH differentiates through mycoprotein specialization for alternative meat formulations. DSM-Firmenich sustains technology leadership in yeast-derived protein concentrates for high-value nutritional applications.
Microbial protein denotes biomass cultivated from bacteria, algae, yeast, or fungi through controlled fermentation or photosynthetic processes, typically containing 40-80% crude protein on a dry matter basis with essential amino acid profiles comparable to fishmeal or soybean meal. Its primary commercial purpose centers on displacing conventional protein sources in feed and food systems where land use, water consumption, or supply volatility constrain traditional agriculture. Yeast-derived proteins dominate current manufacturing scale owing to established fermentation infrastructure and GRAS status familiarity, while algae-based categories capture expanding margin pools in omega-3 fortified nutraceutical segments. Bacteria strains command premium positioning in aquaculture feed formulations where precise amino acid ratios accelerate fish growth rates.
The FDA's GRAS notification pathway and USDA FSIS labeling jurisdiction jointly determine market access timelines for novel microbial protein ingredients in food applications. EPA effluent guidelines under the Clean Water Act shape fermentation facility siting decisions, particularly for large-scale algae operations in water-stressed southwestern states. Stakeholders must monitor evolving state-level feed ingredient registration requirements and carbon intensity scoring methodologies that will determine eligibility for California Low Carbon Fuel Standard credits and emerging clean protein procurement programs.
Market Dynamics
Feed-grade microbial protein is consolidating around Cargill's grain-anchored fermentation infrastructure across the Midwest, while nutraceutical-grade isolates fragment among specialized mycoprotein developers serving alternative meat formulations.
Growth Catalysts
- FDA GRAS Pathway Streamlining:The Generally Recognized as Safe notification framework accelerates novel protein approvals for food applications, compressing time-to-market for yeast-derived concentrates targeting human nutrition.
- Livestock Production Corridor Demand:Concentrated animal feeding operations across the Texas Panhandle and Nebraska Sandhills are procuring bacterial protein biomass to reduce soybean meal dependency in cattle finishing rations.
- Great Lakes Aquaculture Expansion:Recirculating aquaculture systems in Michigan and Wisconsin are integrating algae-based protein into salmonid feed formulations to optimize omega-3 fatty acid profiles.
Market Restraints
- Natural Gas Price Volatility:Steam sterilization and aerobic fermentation processes consume substantial thermal energy, exposing Midwest production facilities to input cost swings from Henry Hub pricing fluctuations.
- Single-Source Strain Dependencies:Proprietary fungal cultures for mycoprotein production remain concentrated with limited qualified suppliers, creating supply continuity risks for alternative meat manufacturers.
- USDA FSIS Labeling Uncertainty:Evolving jurisdiction over cell-cultured and fermentation-derived proteins generates compliance friction, delaying retail packaging decisions for novel ingredient entrants.
Strategic Opportunities
- California Low Carbon Fuel Standard Credits:Fermentation facilities achieving verified carbon intensity scores below conventional agriculture thresholds qualify for LCFS credit monetization, creating margin expansion for western operators.
- Premium Pet Food Channel Penetration:Freeze-dried bacterial protein isolates are capturing shelf space in specialty retail channels targeting humanization-trend pet owners in urban Canadian markets.
- Continuous Bioprocessing Convergence:Integration of perfusion fermentation with inline analytical sensors enables real-time quality adjustment, reducing batch failure rates for high-value nutraceutical applications.
Industry Challenges
- Fermentation Scale-Up Talent Scarcity:Industrial bioprocess engineering expertise remains concentrated with legacy pharmaceutical and enzyme manufacturers, constraining facility expansion timelines for novel protein ventures.
- EPA Effluent Compliance Complexity:Clean Water Act permitting for high-biomass fermentation facilities requires sophisticated nutrient recovery systems, extending capital deployment cycles in water-stressed southwestern states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Microbial Protein Market |
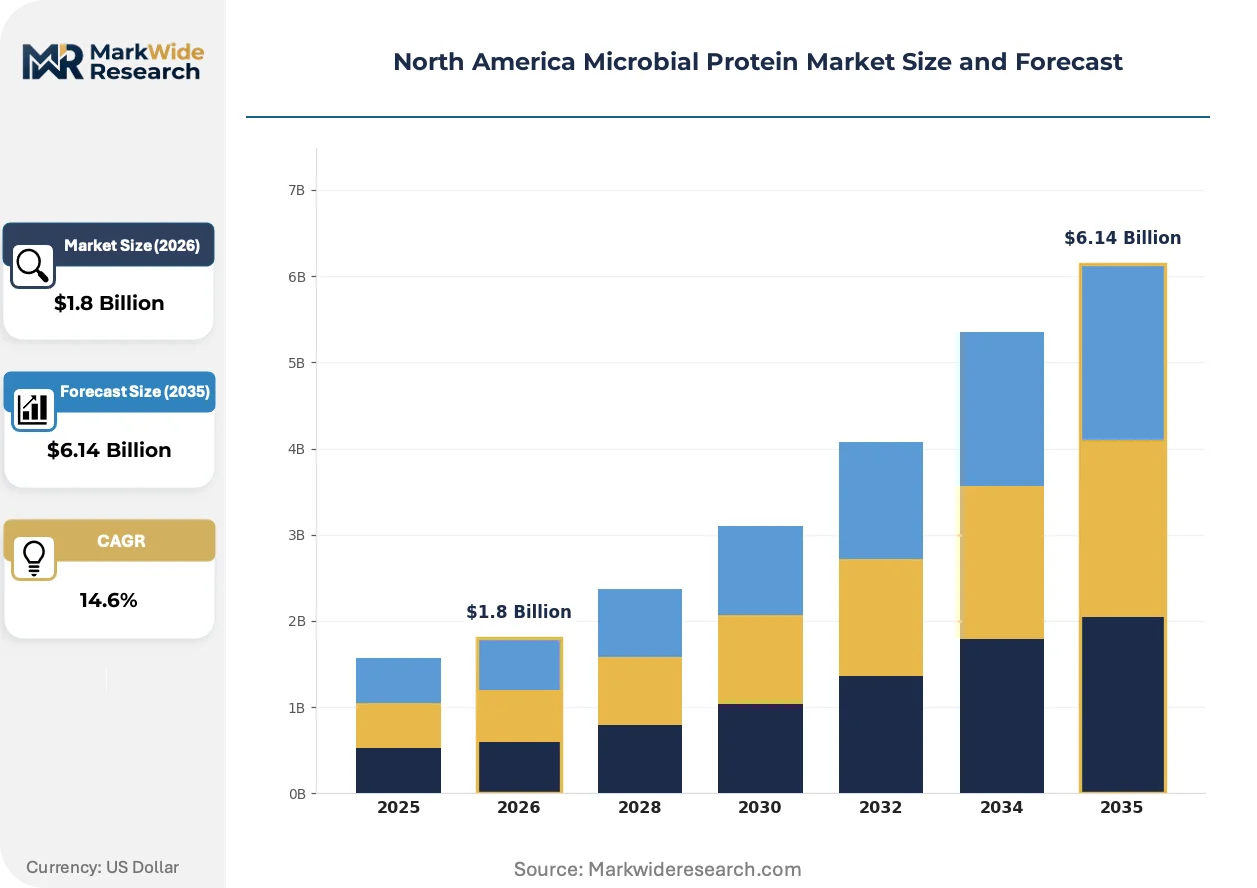
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacteria, Algae, Yeast, Fungi Application: Animal Feed, Food Supplements, Nutraceuticals, Biofuels End User: Aquaculture Industry, Livestock Production, Pet Food Manufacturers, Food Processing Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Arizona Algae Products LLC, Cargill, Corbion NV, Roquette Freres, DSM-Firmenich, The Scoular Company, Algenol Biotech LLC, ENOUGH, Cyanotech Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Microbial Protein Market Evolving Landscape
Precision fermentation is restructuring protein economics by decoupling production from agricultural land use, while regulatory clarity and buyer procurement sophistication accelerate category maturation across feed and food applications.
Continuous perfusion fermentation is overtaking traditional fed-batch methods for high-value protein isolate production. Nutraceutical manufacturers in the Northeast are adopting these systems to achieve higher cell densities and reduce downstream purification costs. The technology is compressing capital intensity requirements for entrants targeting pharmaceutical-grade protein concentrates.
USDA FSIS is clarifying labeling jurisdiction over fermentation-derived proteins through ongoing rulemaking consultations with industry stakeholders. This regulatory development is enabling retail packaging decisions that were previously stalled by classification uncertainty. Alternative meat brands operating in California and New York are accelerating product launches in response to anticipated guidance finalization.
Buyers in the aquaculture feed segment are consolidating procurement around vertically integrated suppliers offering bundled amino acid profiling services. Traditional commodity distributors serving Great Plains catfish operations are losing share to fermentation specialists providing customized biomass formulations with guaranteed lysine and methionine specifications. This concentration is most pronounced among large-scale recirculating system operators in Mississippi Delta processing clusters.
North America Microbial Protein Market Segmentation
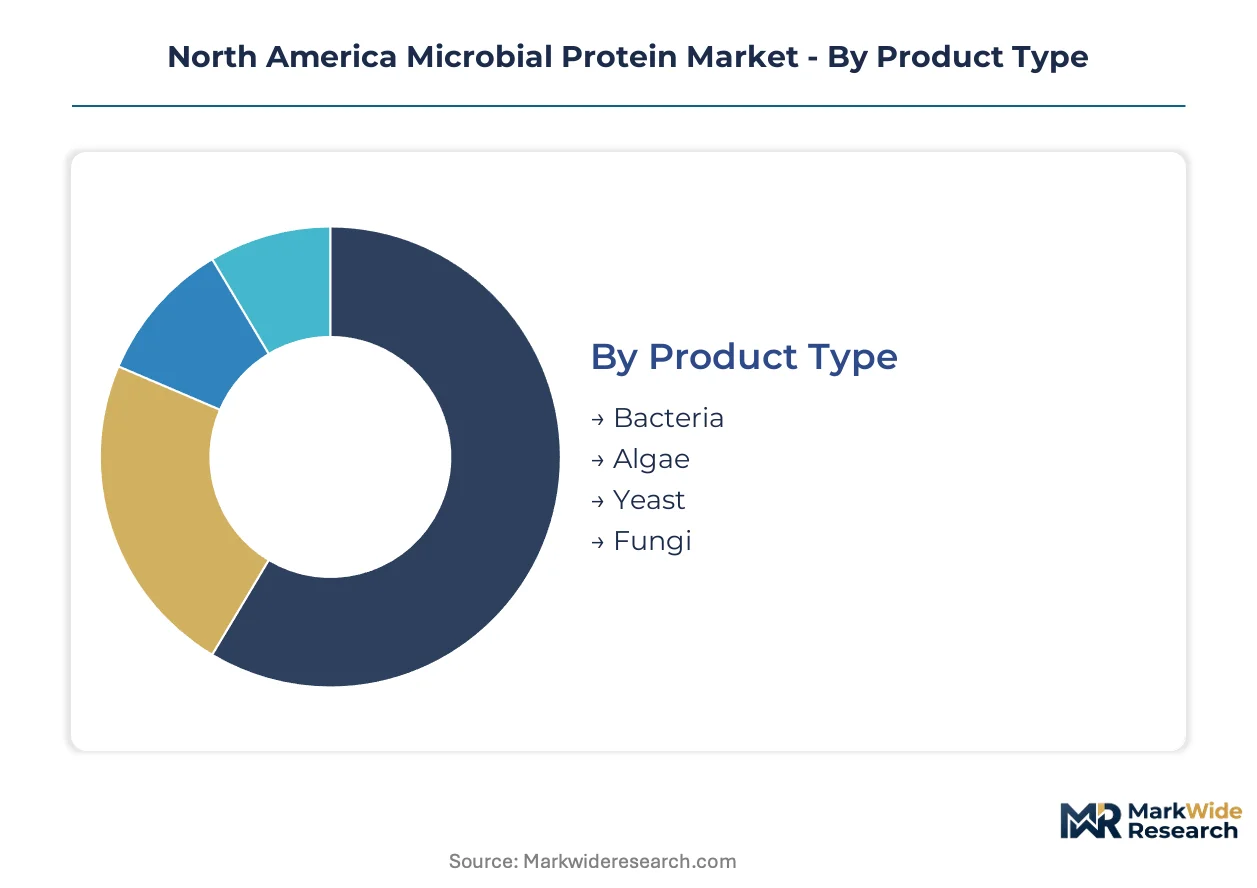
Microbial protein manufacturers deploy divergent capital strategies across product categories. Bacterial and algal fermentation systems demand specialized bioreactor infrastructure, while downstream application requirements dictate margin capture and facility scale decisions.
Product Type:
Capital intensity varies sharply across microbial platforms, with photobioreactor-dependent algae operations requiring the heaviest upfront investment compared to established yeast fermentation infrastructure.
- Bacteria:Single-cell protein biomass cultivated through aerobic fermentation achieves crude protein concentrations exceeding 70% on a dry matter basis. Demand concentrates in Nebraska Sandhills cattle finishing operations where precise amino acid ratios reduce soybean meal inclusion rates.
- Algae:Photosynthetic cultivation in closed photobioreactor systems yields protein with concurrent omega-3 fatty acid accumulation. Great Lakes aquaculture processors in Michigan and Wisconsin are procuring algae-based formulations to optimize salmonid feed fatty acid profiles.
- Yeast:Saccharomyces cerevisiae fermentation leverages existing brewing and enzyme manufacturing infrastructure across the Midwest.
- Fungi:Mycoprotein production through filamentous fungal fermentation targets alternative meat applications with textured protein structures.
Most installed capacity flows through Yeast. Expansion is steepest in Algae.
Application:
Application selection determines regulatory pathway complexity and customer concentration risk for microbial protein suppliers.
- Animal Feed:Commodity-grade biomass displaces fishmeal and soybean meal in ruminant and monogastric rations. Texas Panhandle feedlots are contracting bacterial protein supplies to hedge against soybean price volatility.
- Food Supplements:Isolated protein concentrates with enhanced digestibility scores command premium positioning in sports nutrition channels.
- Nutraceuticals:Yeast-derived beta-glucan and algae-derived astaxanthin formulations target immune support and antioxidant applications in human health.
- Biofuels:Residual biomass from protein extraction processes contributes to renewable diesel feedstock pools under California LCFS frameworks.
Animal Feed captures the majority of production volume. Nutraceuticals is gaining share fastest.
End User:
End-user procurement sophistication determines contract structure complexity and technical service requirements.
- Aquaculture Industry:Recirculating aquaculture system operators demand guaranteed amino acid specifications and batch-to-batch consistency for salmonid and catfish operations.
- Livestock Production:Concentrated animal feeding operations across the Texas Panhandle and Nebraska Sandhills are integrating bacterial protein into cattle finishing rations.
- Pet Food Manufacturers:Freeze-dried bacterial isolates are penetrating specialty retail channels targeting humanization-trend pet owners in urban Canadian markets.
- Food Processing:Alternative meat formulators require mycoprotein with specific textural properties for whole-cut analog applications.
Livestock Production channels the largest procurement volumes. Aquaculture Industry shows the steepest expansion trajectory.
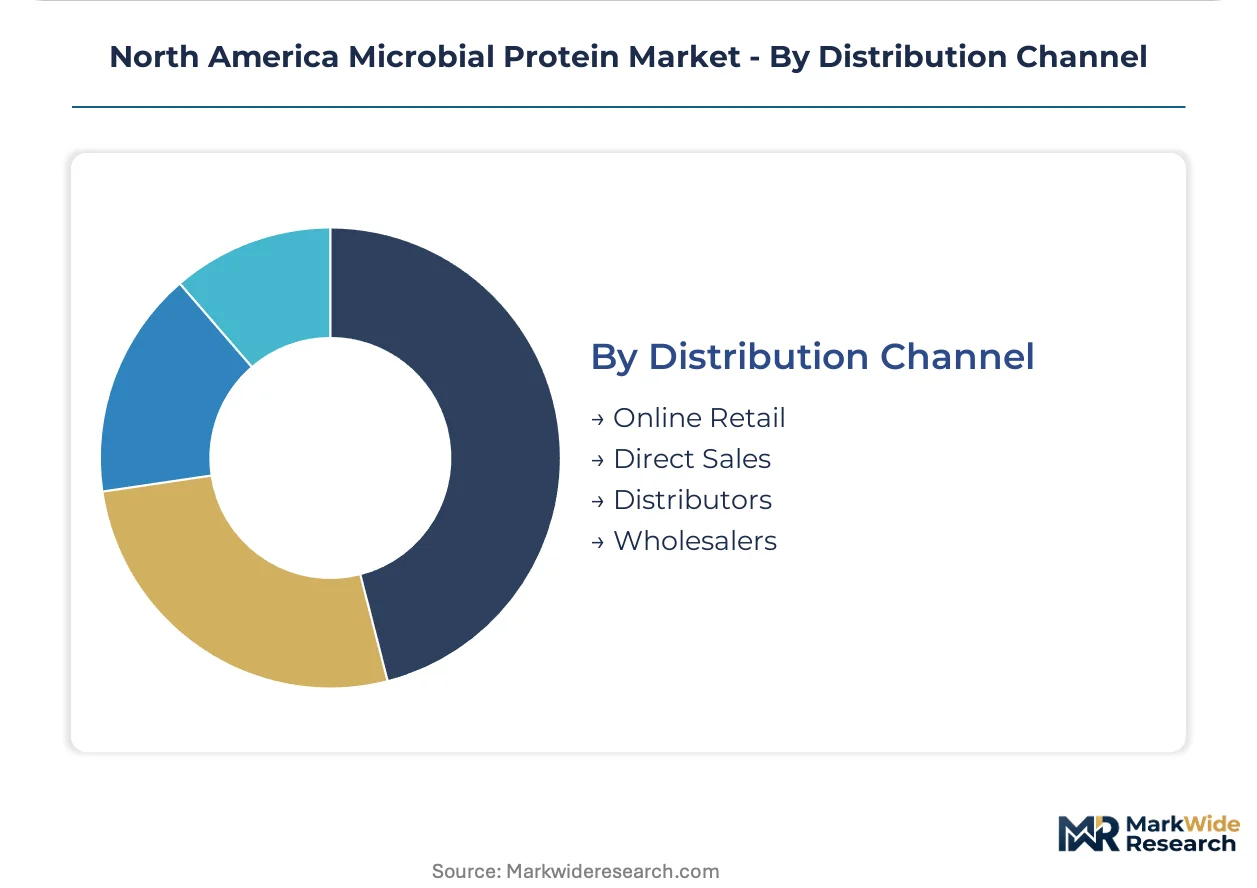
Distribution Channel:
Channel selection reflects customer scale and technical support requirements for microbial protein procurement.
- Direct Sales:Large-scale aquaculture and livestock operations negotiate multi-year supply agreements with fermentation specialists for customized biomass formulations.
- Distributors:Regional feed ingredient distributors serving Great Plains catfish operations are losing share to vertically integrated suppliers offering bundled amino acid profiling services.
- Online Retail:Freeze-dried bacterial protein isolates for premium pet food applications reach urban Canadian consumers through specialty e-commerce platforms.
- Wholesalers:Commodity-grade yeast protein concentrates flow through traditional agricultural supply cooperatives in Midwest grain production regions.
Direct Sales handles the majority of high-volume transactions. Online Retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's microbial protein sector concentrates on premium pet food applications, while the United States dominates feed-grade fermentation infrastructure across its agricultural heartland. Mexico's aquaculture expansion in Baja California creates emerging demand for algae-based protein formulations.
United States
Concentrated animal feeding operations across the Texas Panhandle and Nebraska Sandhills drive bacterial protein procurement for cattle finishing rations. The FDA's GRAS notification framework accelerates novel protein approvals for food applications, compressing time-to-market for yeast-derived concentrates. Midwest grain handling infrastructure anchors Cargill's feed-grade fermentation supply chains across Iowa, Illinois, and Minnesota processing clusters.
Canada
Urban pet owners in Toronto and Vancouver generate demand for freeze-dried bacterial protein isolates targeting humanization-trend companion animal nutrition. Health Canada's regulatory alignment with FDA frameworks streamlines cross-border ingredient approvals for fermentation-derived feed additives. Prairie Provinces livestock operations in Alberta and Saskatchewan integrate yeast protein into dairy cattle rations to reduce soybean meal dependency.
Mexico
Shrimp aquaculture expansion in Sonora and Sinaloa creates procurement pull for algae-based protein with optimized omega-3 fatty acid profiles. The country's national agricultural regulator coordinates feed ingredient registration requirements with state-level environmental permits for coastal photobioreactor facilities. Baja California processing clusters near Ensenada attract fermentation specialists serving Pacific coast mariculture operations.
North America Microbial Protein Market Competitive Landscape
Top-tier vendors anchor feed-grade biomass production, while specialized mycoprotein developers occupy premium alternative meat formulation segments. The vendor base stratifies across three strategic archetypes: grain-anchored agricultural conglomerates leveraging existing fermentation infrastructure, dedicated microbial protein specialists pursuing mycoprotein differentiation, and diversified nutrition ingredient suppliers with yeast technology platforms. Dominant competitive moves include backward integration into proprietary strain development and capacity expansion targeting California Low Carbon Fuel Standard credit eligibility.
Among Netherlands-based specialists, Corbion NV and DSM-Firmenich occupy positions within the yeast-derived protein concentrate tier. Cargill anchors the grain-anchored agricultural conglomerate archetype from its Midwest infrastructure base. ENOUGH represents the dedicated mycoprotein specialist segment targeting alternative meat applications.
| Leading Market Players |
|---|
| Arizona Algae Products LLC |
| Cargill |
| Corbion NV |
| Roquette Freres |
| DSM-Firmenich |
| The Scoular Company |
| Algenol Biotech LLC |
| ENOUGH |
| Cyanotech Corporation |
| Others |
Value Network & Pricing Analysis
Livestock procurement officers in the Texas Panhandle and Nebraska Sandhills demanding guaranteed amino acid specifications are forcing bacterial protein suppliers to invest in inline analytical infrastructure, compressing margins for commodity-grade biomass while creating pricing power for certified nutraceutical isolates.
Pricing Analysis
Capacity additions in Iowa and Minnesota are reshaping price floors for feed-grade yeast protein, intensifying competition among Midwest suppliers. Three-tier pricing structure across premium nutraceutical isolates, standard food-grade concentrates, and economy feed-grade biomass dominates contract negotiations. Price differentiation hinges on carbon intensity certification under California LCFS frameworks and guaranteed lysine-methionine ratios for aquaculture buyers. Cost compression in commodity feed-grade tiers is intensifying because natural gas price volatility exposes fermentation facilities to Henry Hub fluctuations. Livestock feed operations exhibit highest price sensitivity, while premium pet food channels absorb pricing premiums for freeze-dried bacterial isolates.
Supply Chain Analysis
Freight costs from Great Plains grain elevators to coastal aquaculture processors in Michigan and Wisconsin constrain algae protein competitiveness against locally produced bacterial biomass. Supply concentrates in the United States Midwest, with secondary nodes in Alberta and Saskatchewan for prairie livestock operations and emerging capacity in Baja California for Pacific mariculture. Raw material dependencies include corn-derived dextrose for yeast fermentation, natural gas for steam sterilization, and proprietary fungal cultures for mycoprotein production. Single-source strain vulnerabilities for filamentous fungal production create supply continuity exposure for alternative meat manufacturers. Distribution runs through direct sales contracts for large-scale livestock and aquaculture operations, with specialty pet food isolates reaching urban Canadian consumers through e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America microbial protein market represents a late-cycle quality story as aquaculture feed formulators shift procurement toward guaranteed omega-3 fatty acid profiles and verified amino acid specifications, rewarding suppliers with analytical capabilities and carbon certification.
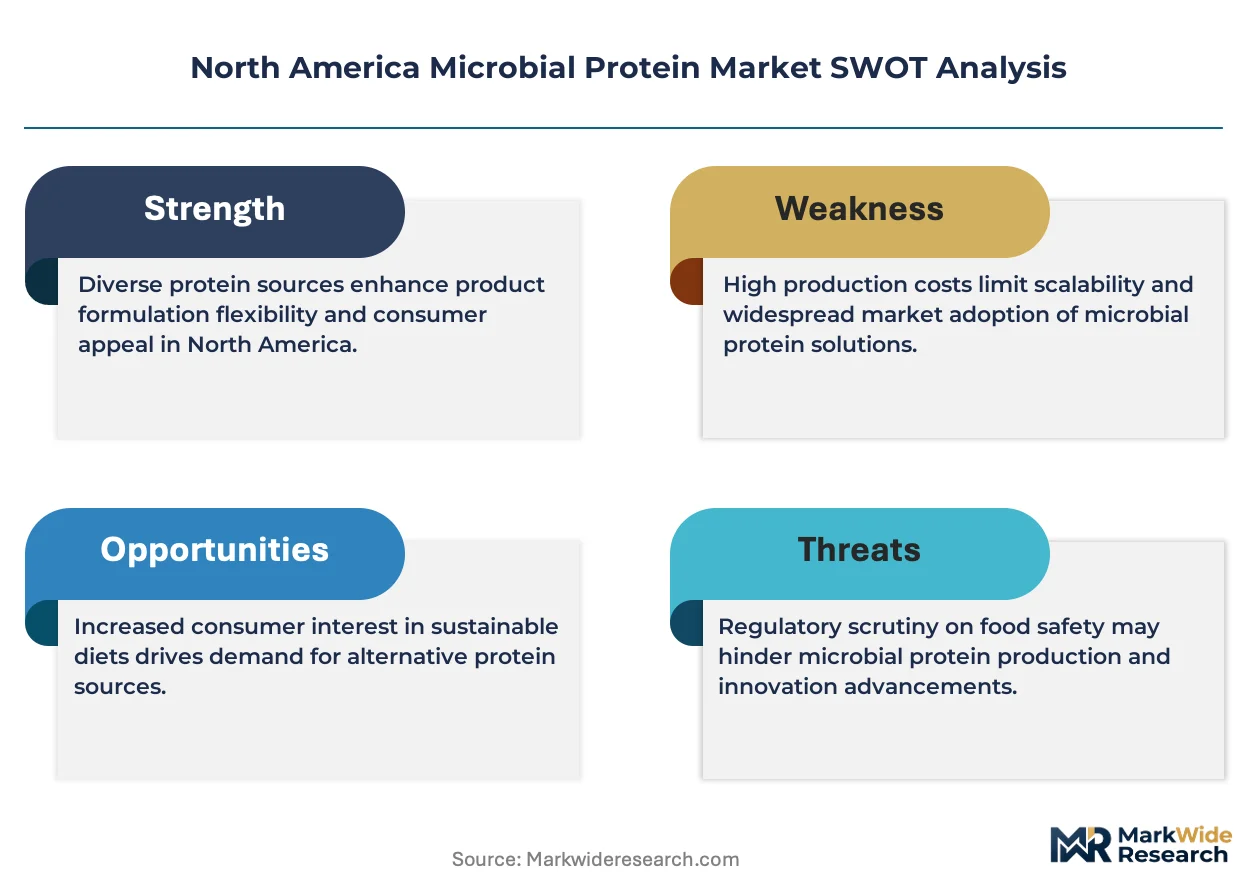
For Market Incumbents: Hedge against margin erosion in commodity feed-grade biomass by securing backward integration into proprietary bacterial strain libraries and expanding carbon-negative production capacity eligible for California LCFS credit monetization. Reinforce channel control through multi-year direct sales contracts with Great Lakes recirculating aquaculture system operators that bundle amino acid profiling services with biomass delivery. For New Entrants and Emerging Players: Capture white space in premium pet food applications targeting urban Canadian markets, where humanization-trend pet owners absorb pricing premiums for freeze-dried bacterial isolates with enhanced digestibility scores. Penetrate the nutraceutical-grade isolate segment through continuous perfusion fermentation systems that achieve pharmaceutical-grade protein concentrations with lower capital intensity than traditional fed-batch infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized mycoprotein developers possessing filamentous fungal cultivation expertise and established alternative meat formulator relationships. Long-term viability over the coming decade hinges on regulatory clarity from USDA FSIS labeling rulemaking and the pace of carbon intensity scoring methodology standardization. Watch for FDA GRAS notification acceleration for novel bacterial strains as the inflection signal for food-application market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Strain Development | Captive supply of qualified fungal cultures reduces supply continuity risks for mycoprotein manufacturers. |
| Carbon Intensity Certification | California LCFS credit eligibility creates margin expansion for western fermentation facility operators. |
| Continuous Perfusion Fermentation | Inline analytical sensors enable real-time quality adjustment for high-value nutraceutical applications. |
| Direct Sales Channel Expansion | Multi-year supply agreements with aquaculture operators displace traditional commodity distributors. |
| Regulatory Affairs Investment | FDA GRAS notification expertise compresses time-to-market for novel protein food applications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation facility operators, aquaculture procurement managers, pet food formulators, and regulatory affairs specialists with secondary validation from FDA GRAS notification databases, USDA FSIS rulemaking dockets, EPA effluent guideline filings, and California Air Resources Board LCFS certification records. Bottom-up facility capacity assessments and top-down protein displacement demand modeling were triangulated against trade flow data and feed ingredient registration databases.
Historical reference periods anchored the projection horizon, with growth trajectories derived from segment-specific adoption curves across bacterial, algal, yeast, and fungal protein platforms. The analytical framework modeled demand by application tier, end-user procurement sophistication, and distribution channel structure, incorporating natural gas price volatility scenarios and regulatory pathway timeline assumptions as sensitivity inputs.
Strain qualification delays, EPA effluent permitting backlogs, and USDA FSIS labeling jurisdiction uncertainty are the dominant revision risks that could compress or extend market penetration timelines. Stakeholders should weight assumptions against their own operating context and regulatory engagement capabilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Microbial Culture Market
Industrial Microbiology
Europe Microbial Based Biological Seed Treatment Market
Industrial Microbiology
Global Microbial Products Market
Industrial Microbiology
Microbial Protein Used in Feed Market
Industrial Microbiology
Bacillus Subtilis Market
Industrial Microbiology
Global Microbial Fermentation Technology Market
Industrial Microbiology
Eubiotics Market
Industrial Microbiology
Ripening Cultures Market
Industrial Microbiology
Microbial Cell Banking Market
Industrial Microbiology
Microbiomes Market
Industrial Microbiology
Global Microbial Identification Market
Industrial Microbiology
Specialty Cultures Market
Industrial Microbiology
Microbial Seed Treatment Market
Industrial Microbiology
Global Arabinogalactan Market
Industrial Microbiology
Global Escherichia Coli Testing Market
Industrial Microbiology
Probiotic Yeast Market