
 Microbial Biosurfactants Market | 2026-2036
Microbial Biosurfactants Market Size, Share, and Industry Trends Forecast 2026-2036
Microbial Biosurfactants Market Outlook
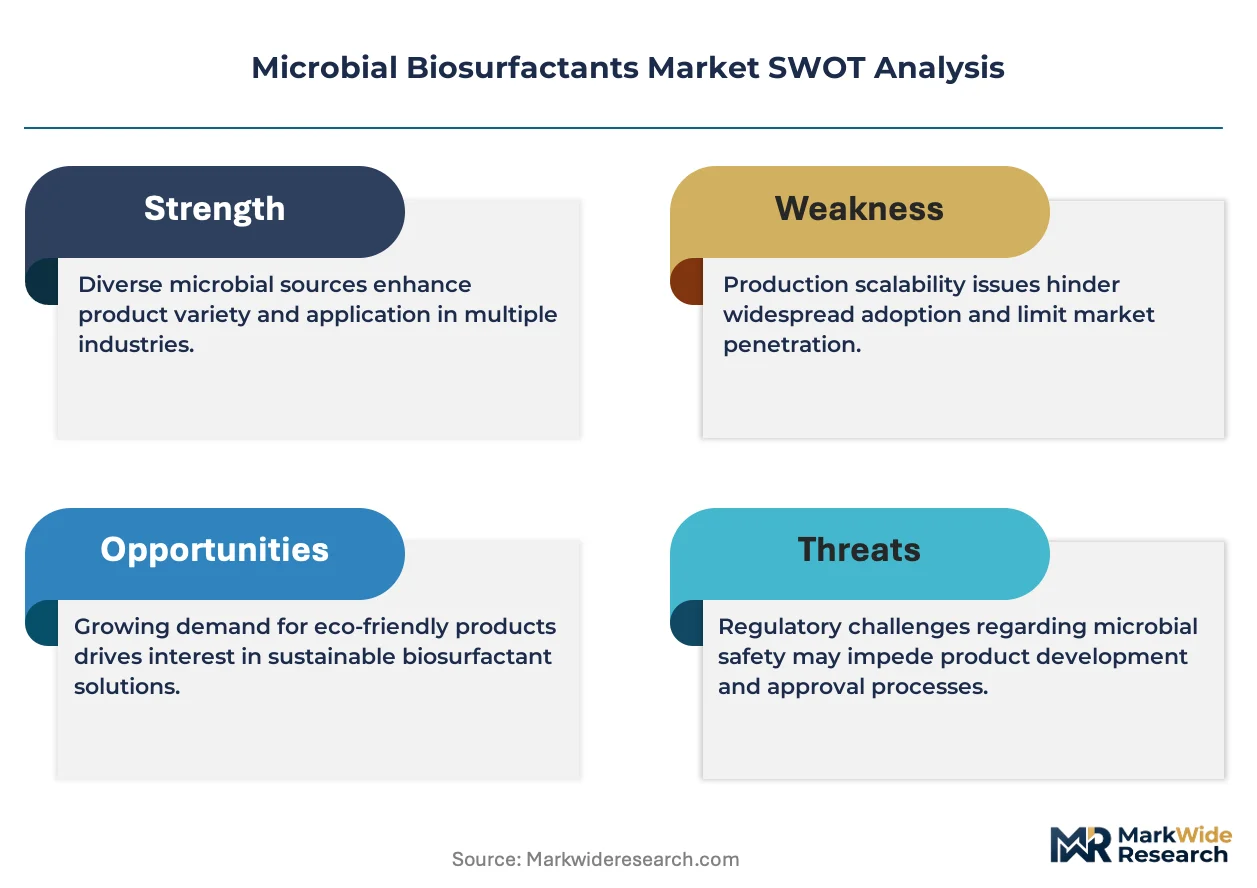
Modular formulation kits are decoupling biosurfactant supply from finished-product manufacturing, letting buyers customize active-ingredient ratios without captive fermentation capacity. Evonik Industries AG leverages its specialty chemicals infrastructure to supply high-purity sophorolipid intermediates to third-party formulators. BASF SE anchors European distribution through integrated biotech pilot facilities that shorten qualification cycles for industrial customers.
Microbial biosurfactants are surface-active compounds produced by fermentation of carbohydrates and oils using yeast or bacterial cultures, typically achieving critical micelle concentrations below synthetic alternatives. Their primary commercial purpose centers on replacing petroleum-derived surfactants in applications where biodegradability and low aquatic toxicity carry regulatory or brand value. Sophorolipids currently occupy the largest product-type position due to mature fermentation protocols and consistent batch yields. Rhamnolipids compete fastest in cleaning-product applications where foaming performance requirements have relaxed. The food-industry application segment sustains premium pricing through GRAS-affirmed grades that command stricter purity certifications than industrial variants.
REACH registration requirements and the EU Green Deal framework constrain synthetic surfactant formulations across European manufacturing, redirecting procurement toward fermentation-derived alternatives. ECHA substance evaluations and F-Gas Regulation phase-outs reinforce demand for low-toxicity emulsifiers in aerosol and precision-cleaning formats. FDA GRAS notifications and EPA Safer Choice program criteria shape parallel qualification pathways for North American market entry. Stakeholders must monitor regulatory divergence between jurisdictions where biosurfactant purity standards and feedstock sustainability certifications are tightening at different speeds.
Market Dynamics
REACH restrictions on synthetic surfactants are forcing European cleaning-product manufacturers to redirect procurement toward fermentation-derived alternatives, decoupling formulation from captive production capacity.
Growth Catalysts
- REACH Registration Mandates:ECHA substance evaluations tighten synthetic surfactant formulations across European manufacturing, redirecting procurement toward rhamnolipid and sophorolipid alternatives.
- Food-Industry GRAS Certification:FDA GRAS-affirmed grades sustain premium pricing through stricter purity certifications than industrial variants, opening high-margin commercial pathways.
- Germany-France Green Chemistry Mandates:Industrial substitution policies accelerate sophorolipid demand concentration in these core markets, creating anchor demand for fermentation capacity.
Market Restraints
- Feedstock Cost Volatility:Carbohydrate and vegetable oil input prices fluctuate with agricultural commodity cycles, compressing batch economics for sophorolipid fermentation.
- Fermentation Scale-Up Bottlenecks:Consistent batch yields above pilot scale remain technically constrained, limiting supply elasticity against demand surges.
- Synthetic Surfactant Price Competition:Petroleum-derived alternatives retain cost advantages in price-sensitive industrial cleaning applications outside regulated jurisdictions.
Strategic Opportunities
- Modular Formulation Kits:Third-party formulators now customize active-ingredient ratios without captive fermentation, opening service-layer revenue for intermediate suppliers.
- EU Green Deal Framework:Carbon-border adjustments and sustainability certifications create preferential market access for bio-based emulsifiers in precision-cleaning formats.
- CRISPR-Enhanced Strain Development:Gene-edited yeast and bacterial cultures promise yield improvements that could compress unit economics below current thresholds.
Industry Challenges
- Purification Skill Scarcity:High-purity sophorolipid production requires specialized downstream processing expertise concentrated among limited technical specialists.
- Qualification Cycle Compression:Industrial customers demand shortened validation timelines that strain biotech pilot facility throughput.
- Cross-Jurisdictional Certification Complexity:Divergent purity standards between EPA Safer Choice and ECHA substance evaluations force redundant compliance investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbial Biosurfactants Market |
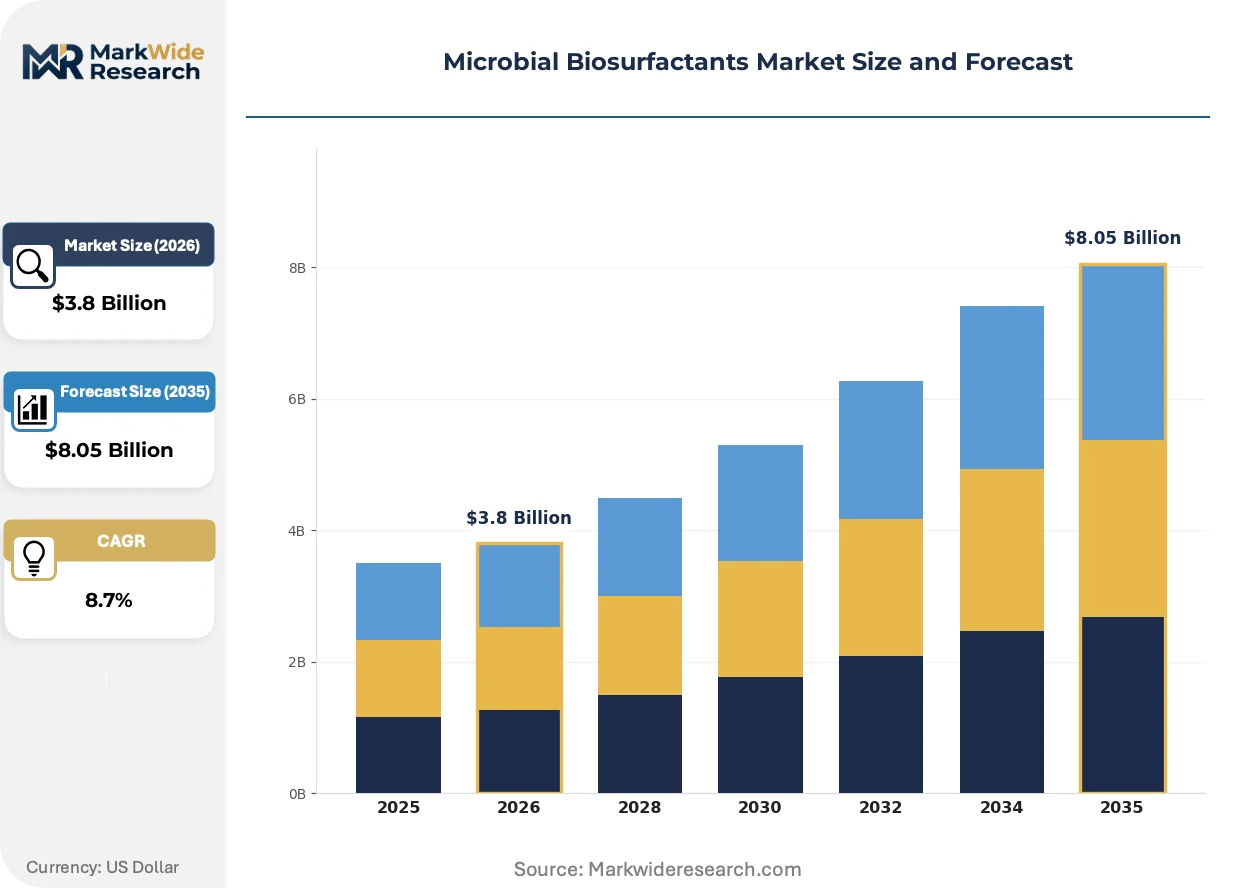
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sophorolipids, Rhamnolipids, Mannosylerythritol, Trehalolipids Application: Food Industry, Pharmaceuticals, Cosmetics, Cleaning Products End User: Manufacturers, Businesses, Research Institutions, Consumers Technology: Fermentation, Bioprocessing, Biomass Conversion, Genetic Engineering |
| Companies Covered | Evonik Industries AG, Jeneil Biotech, Inc., Stepan Company, Solvay S.A., Kaneka Corporation, BASF SE, Saraya Co., Ltd., Biotensidon GmbH, Allied Carbon Solutions Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbial Biosurfactants Market Strategic Shifts
Modular formulation architectures are fragmenting traditional value chains, enabling non-integrated players to capture margin previously locked within captive fermentation operations.
Continuous fermentation systems with real-time metabolite monitoring are overtaking batch protocols in commercial sophorolipid production. Specialty chemical distributors in Germany and France are adopting these systems to secure supply consistency for industrial formulators. The technology is compressing capital requirements for market entry, eroding the scale advantages historically held by integrated biotech majors.
REACH authorization timelines are tightening restrictions on nonylphenol ethoxylates and other legacy surfactant chemistries. European aerosol and precision-cleaning manufacturers face reformulation mandates that favor low-toxicity emulsifiers. Cleaning-product brands with pan-European distribution are accelerating rhamnolipid qualification to preempt supply discontinuity risks.
Ingredient-as-a-service contracts are replacing traditional bulk purchasing among mid-size cleaning-product manufacturers. Third-party formulators now lease fermentation capacity and technical support rather than owning fixed assets. This model concentrates most visibly in the Netherlands and Belgium, where contract manufacturing infrastructure supports rapid product iteration cycles.
Microbial Biosurfactants Market Segmentation
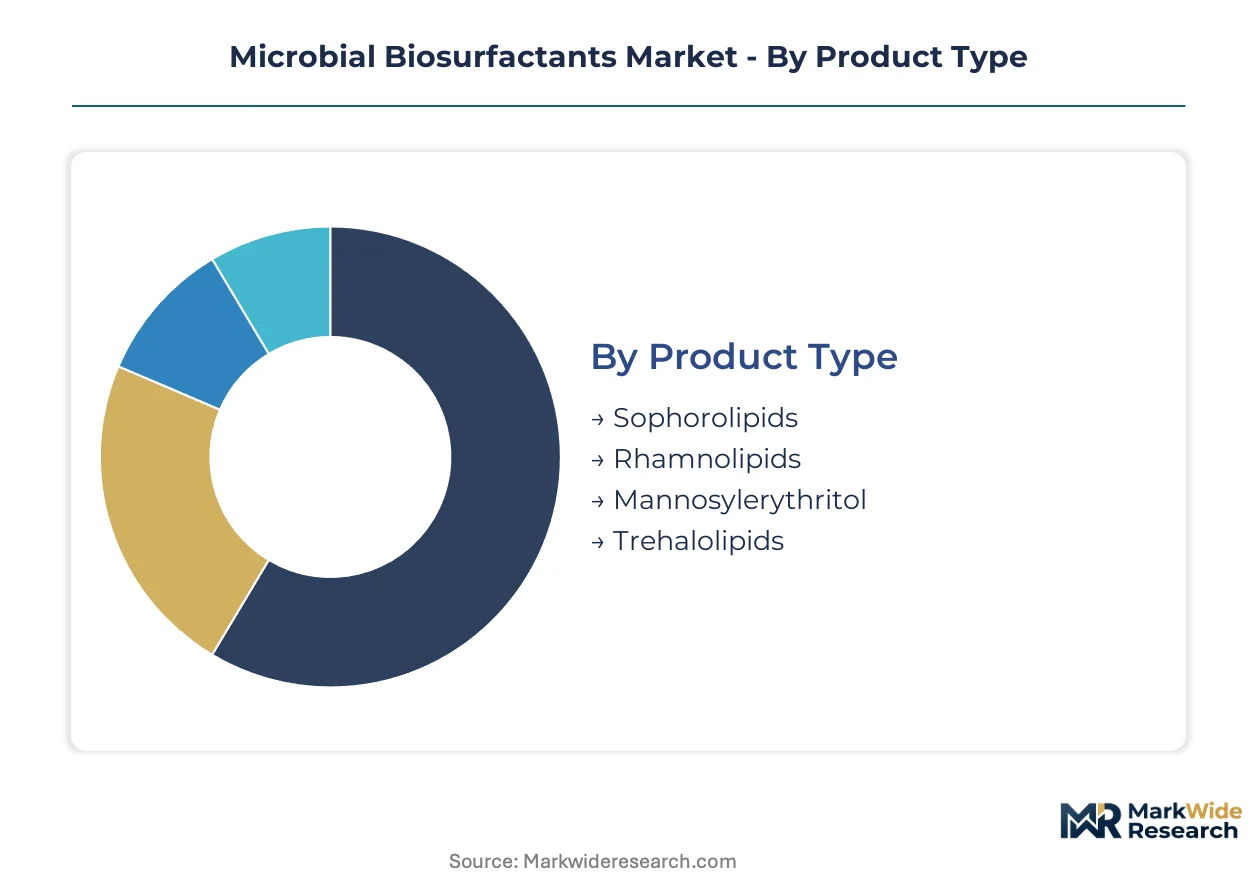
Segmentation in microbial biosurfactants reveals how technical specifications, regulatory pathways, and supply chain configurations fragment commercial opportunity. Buyers select segments based on purity thresholds, certification requirements, and integration depth with existing formulation infrastructure.
Product Type:
Buyers prioritize fermentation yield consistency and downstream purification costs when selecting biosurfactant chemistries.
- Sophorolipids:Glycolipid structures produced by yeast fermentation of glucose and vegetable oils, achieving critical micelle concentrations between 40-100 mg/L. Demand concentrates in Germany and France where REACH-authorized industrial formulators require batch-to-batch consistency for precision-cleaning applications. Sophorolipids currently occupy the largest revenue position due to mature Starmerella bombicola fermentation protocols.
- Rhamnolipids:Di-rhamnolipid and mono-rhamnolipid mixtures synthesized by Pseudomonas aeruginosa or engineered non-pathogenic strains, delivering superior foaming control and emulsification at oil-water interfaces. Procurement from European cleaning-product manufacturers is accelerating as ECHA substance evaluations restrict synthetic alternatives in aerosol formats.
- Mannosylerythritol:High-performance biosurfactant with exceptional surface tension reduction, commanding premium pricing in pharmaceutical emulsion applications.
- Trehalolipids:Mycobacterial-derived compounds with established dermatological compatibility profiles, finding niche adoption in cosmetic formulation.
Volume sits with sophorolipids; growth tilts toward rhamnolipids.
Application:
Regulatory certification requirements and pricing power vary dramatically across end-use segments.
- Cleaning Products:Industrial and household formulations where biodegradability mandates and brand sustainability commitments drive substitution from petroleum-derived surfactants. European aerosol manufacturers face reformulation deadlines under F-Gas Regulation phase-outs, redirecting procurement toward low-toxicity emulsifiers.
- Food Industry:GRAS-affirmed grades for emulsification, anti-adhesion, and solubilization functions in processed foods and beverages. FDA notification pathways and EFSA safety assessments sustain premium pricing tiers through stricter purity certifications than industrial variants.
- Pharmaceuticals:Drug delivery systems and vaccine adjuvants requiring endotoxin-controlled production environments.
- Cosmetics:Personal care formulations leveraging mildness profiles and natural positioning claims.
Revenue concentrates in cleaning products; margin expansion is steepest in food-industry applications.
End User:
Integration depth with fermentation infrastructure determines buyer category and contract structure.
- Manufacturers:Integrated chemical and consumer goods producers with captive fermentation capacity or long-term offtake agreements. These buyers optimize active-ingredient ratios through modular formulation kits, decoupling finished-product manufacturing from biosurfactant supply.
- Businesses:Mid-size cleaning-product and cosmetic brands leasing fermentation capacity through ingredient-as-a-service contracts rather than owning fixed assets.
- Research Institutions:Academic and government laboratories developing CRISPR-enhanced strain libraries and novel production pathways.
- Consumers:Direct purchasers of premium-positioned natural cleaning and personal care products with biosurfactant ingredient transparency claims.
Procurement volume flows through manufacturers; contract flexibility is expanding fastest among business segment buyers.
Technology:
Capital intensity and technical risk differentiate production methodologies.
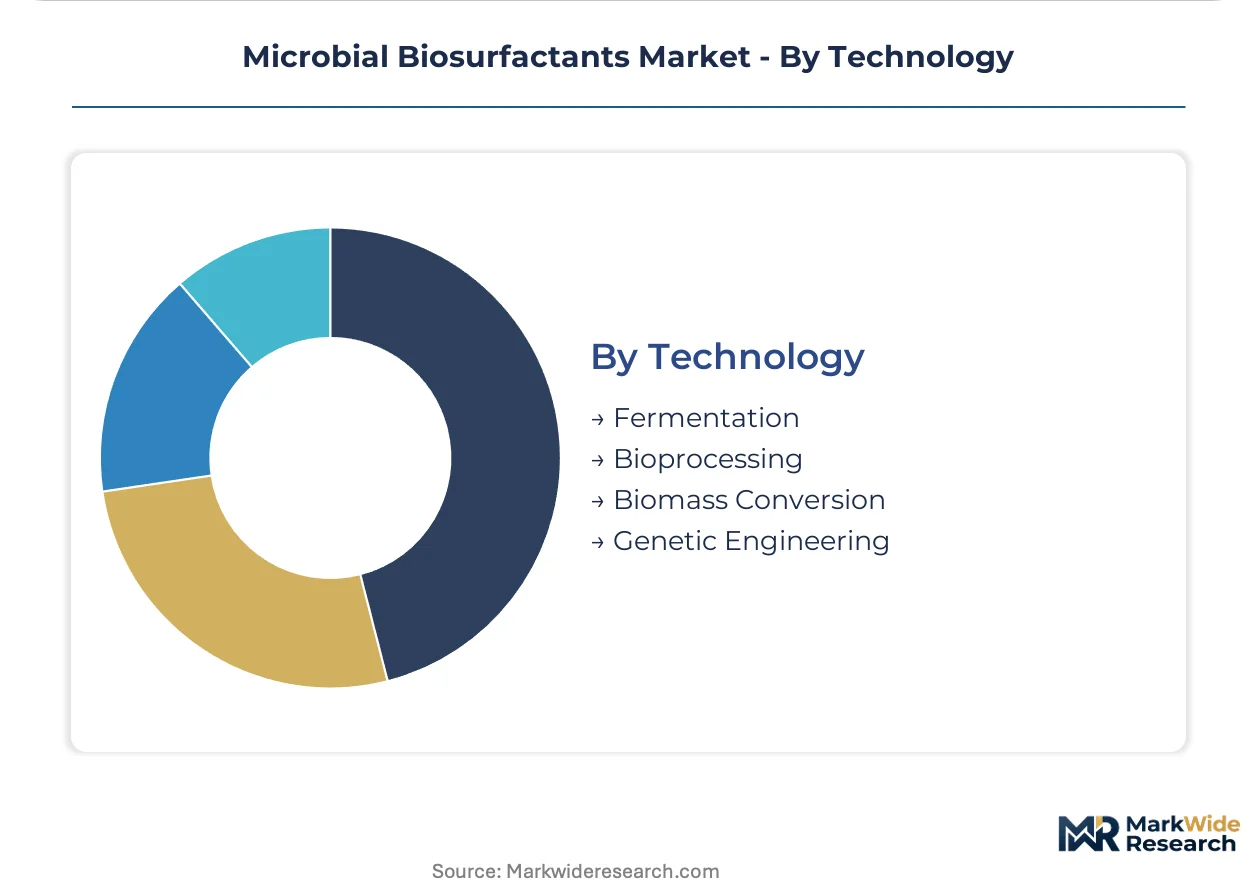
- Fermentation:Batch and continuous culture systems using yeast or bacterial inoculants on carbohydrate and oil feedstocks. Continuous fermentation with real-time metabolite monitoring is overtaking batch protocols in commercial sophorolipid production, compressing capital requirements for market entry.
- Genetic Engineering:CRISPR-Cas9 and metabolic engineering approaches to enhance yield, modify chain length distributions, and enable production in non-pathogenic host organisms. Gene-edited strain development promises unit economic improvements that could displace conventional fermentation economics.
- Bioprocessing:Integrated upstream and downstream operations including cell lysis, solvent extraction, and chromatographic purification.
- Biomass Conversion:Utilization of agricultural residues and waste streams as alternative feedstocks to reduce carbohydrate cost exposure.
Installed capacity centers on fermentation; investment momentum is shifting toward genetic engineering platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European fermentation capacity outpaces domestic consumption, forcing producers to qualify exports for North American and Asian food-grade markets. Asian manufacturing clusters absorb sophorolipid intermediates for downstream cleaning-product formulation. Regulatory divergence between ECHA substance evaluations and FDA GRAS pathways fragments certification timelines.
Germany
Industrial cleaning manufacturers in North Rhine-Westphalia anchor sophorolipid procurement volumes as REACH-authorized formulators face reformulation deadlines. The EU Green Deal framework accelerates carbon-border adjustment preparations for bio-based emulsifier exports. Cologne-Düsseldorf chemical distributors stock modular formulation kits to serve mid-size aerosol producers seeking rapid qualification cycles.
United States
EPA Safer Choice program criteria redirect procurement toward fermentation-derived surfactants in institutional cleaning contracts across the Midwest and Southeast. FDA GRAS notification pathways sustain premium pricing for food-grade rhamnolipid imports from European suppliers. New Jersey and Pennsylvania chemical distributors consolidate inventory positions to shorten lead times for industrial formulators.
France
Paris Basin cosmetic manufacturers drive trehalolipid demand for dermatological compatibility claims in premium personal care lines. ECHA substance evaluations restrict nonylphenol ethoxylate formulations in aerosol formats, forcing Lyonnaise cleaning-product brands toward rhamnolipid alternatives. Lyon-Grenoble biotech clusters pilot continuous fermentation systems with real-time metabolite monitoring.
Japan
Tokyo-Osaka pharmaceutical emulsion specialists command mannosylerythritol premiums for vaccine adjuvant applications requiring endotoxin-controlled production. METI biomanufacturing initiatives subsidize strain development partnerships between domestic fermentation houses and academic laboratories. Kansai region chemical traders inventory sophorolipid intermediates for precision-cleaning equipment manufacturers serving semiconductor fabrication.
Netherlands
Rotterdam-Antwerp contract manufacturing infrastructure supports ingredient-as-a-service contracts among mid-size European cleaning-product brands. REACH registration mandates concentrate third-party formulator activity in Dutch pilot facilities capable of rapid product iteration cycles. Biomass conversion research at Wageningen University clusters agricultural residue feedstock suppliers near fermentation capacity.
Microbial Biosurfactants Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across distinct capability tiers. Specialty chemical majors leverage integrated pilot facilities to compress qualification timelines for industrial customers. Biotechnology startups occupy modular formulation layers, decoupling active-ingredient supply from finished-product manufacturing. Dominant competitive moves include capacity expansion in continuous fermentation systems and strategic partnerships bridging strain development with downstream purification expertise.
Within the diversified conglomerate tier, Evonik Industries AG and BASF SE anchor European supply infrastructure through specialty chemicals distribution networks. Solvay S.A. occupies a position exemplifying Belgian chemical group diversification into bio-based emulsifiers. Among focused biotechnology specialists, Jeneil Biotech, Inc. represents the pure-play fermentation archetype with concentrated biosurfactant expertise. Kaneka Corporation and Saraya Co., Ltd. sit within the Asia-Pacific supplier cluster serving regional pharmaceutical and cosmetic formulators respectively.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Jeneil Biotech, Inc. |
| Stepan Company |
| Solvay S.A. |
| Kaneka Corporation |
| BASF SE |
| Saraya Co., Ltd. |
| Biotensidon GmbH |
| Allied Carbon Solutions Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Vegetable oil and glucose feedstock costs cascade through sophorolipid fermentation economics, compressing margins at industrial-grade tiers while GRAS-certified food-grade premiums absorb agricultural commodity volatility through long-term offtake structures.
Pricing Analysis
Margin tightening in industrial-grade rhamnolipid tiers reflects carbohydrate price volatility and synthetic surfactant price competition from petroleum-derived alternatives. Three-tier pricing structure across premium GRAS-affirmed food grades, standard industrial cleaning formulations, and economy bulk intermediates separates buyers by certification burden and volume scale. Cost-down pressure on industrial tiers accelerates as REACH-authorized formulators demand shortened qualification cycles without price premiums. Mid-size cleaning-product manufacturers leasing fermentation capacity through ingredient-as-a-service contracts exhibit highest price sensitivity, while pharmaceutical emulsion specialists command mannosylerythritol premiums regardless of feedstock fluctuations.
Supply Chain Analysis
ECHA substance evaluation timelines and FDA GRAS notification pathways gate supply qualification, stretching validation cycles for European producers seeking North American food-grade market entry. Fermentation capacity concentrates in Germany, France, and the Netherlands where integrated pilot facilities anchor sophorolipid and rhamnolipid output. Downstream supply draws from carbohydrate refiners in Belgium and vegetable oil processors across the Rhine corridor, creating feedstock cost exposure to agricultural commodity cycles. Single-source vulnerability concentrates in specialized downstream purification expertise for high-purity grades. Distribution runs through Rotterdam-Antwerp chemical distributors stocking modular formulation kits for rapid industrial customer response.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as fermentation scale-up bottlenecks and purification skill scarcity force sub-scale producers toward acquisition or contract manufacturing exit.
For Market Incumbents: Extend continuous fermentation system deployments to compress unit economics below batch protocol thresholds, defending position against specialty chemical distributors adopting real-time metabolite monitoring. Anchor backward integration into vegetable oil refining partnerships to neutralize feedstock volatility exposure. Prioritize GRAS certification maintenance for food-grade revenue streams as FDA notification pathways sustain premium pricing power. For New Entrants and Emerging Players: Contract manufacturing infrastructure in the Netherlands offers lowest-friction entry for mid-size cleaning-product brands seeking ingredient-as-a-service relationships without captive fermentation investment. Target pharmaceutical emulsion applications in Japan where mannosylerythritol premiums reward endotoxin-controlled production capabilities. Pursue white-space in CRISPR-enhanced strain development partnerships with Wageningen University biomass conversion clusters. For Investors and Strategic Acquirers: FDA GRAS notification acceleration for European rhamnolipid suppliers is the leading indicator that cross-jurisdictional certification complexity is resolving favorably for consolidated players. Long-term viability favors vertically integrated specialists with captive downstream purification expertise rather than pure-play fermentation capacity. Watch for ECHA substance evaluation timeline compression as signal that regulatory qualification moats are widening against new entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Fermentation Scale-Up | Real-time metabolite monitoring compresses capital requirements for sophorolipid market entry. |
| GRAS Certification Investment | FDA notification pathways sustain premium pricing tiers for food-grade rhamnolipid suppliers. |
| Backward Integration into Feedstocks | Vegetable oil refining partnerships neutralize agricultural commodity cost exposure. |
| Ingredient-as-a-Service Launch | Rotterdam-Antwerp contract infrastructure captures mid-size cleaning-brand procurement shifts. |
| CRISPR Strain Development Partnership | Gene-edited yeast cultures promise yield improvements displacing conventional fermentation economics. |
Study Parameters
Document review covered ECHA substance evaluation databases, FDA GRAS notification filings, and EU Green Deal policy frameworks, complemented by interviews with fermentation plant managers, specialty chemical procurement leads at downstream cleaning-product OEMs, distribution channel partners in the Cologne-Düsseldorf corridor, and technical R&D directors at integrated biotech pilot facilities. Secondary validation drew from customs and trade data, Cefic sector reports, and SEC 10-K disclosures from diversified chemical conglomerates. Bottom-up volume estimates triangulated against top-down market sizing across the analysis window.
Cross-referencing historical fermentation capacity buildouts against expert panel input shaped the analytical framework. Segmentation dimensions modeled include product type chemistry, application certification tier, end-user integration depth, and regional regulatory cluster. CAGRs were derived from growth rate convergence techniques applied to volume and value trajectories. Industry-specific forecast inputs incorporated REACH authorization timeline assumptions and F-Gas Regulation phase-out schedules for aerosol formulation demand.
Caveats apply where ECHA substance evaluation acceleration, CRISPR strain development breakthroughs, or agricultural commodity price spikes could materially shift the outlook. Forecasts reflect documented assumptions regarding fermentation yield consistency and downstream purification capacity expansion. A model refresh is warranted upon material change in EU Green Deal carbon-border adjustment implementation timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Anti-Microbial Anti-Fungal Test Market
Industrial Microbiology
Global Bacterial Cell Culture Market
Industrial Microbiology
Microbial Lipase Market
Industrial Microbiology
Antibiotic Resistance Market
Industrial Microbiology
Mesophilic Bacteria Market
Industrial Microbiology
Microbial-Derived Fiber Market
Industrial Microbiology
Mycoplasma Plate Antigens Market
Industrial Microbiology
North America Microbial Protein Market
Industrial Microbiology
Global Microbial Protein Market
Industrial Microbiology
Automated Microbiology Market
Industrial Microbiology
Bacillus Subtilis Market
Industrial Microbiology
Salinomycin Market
Industrial Microbiology
Industrial Microbiology Market
Industrial Microbiology
Specialty Cultures Market
Industrial Microbiology
Microbial Identification Panels Market
Industrial Microbiology
Microbial Coagulants Market