
 Mycoplasma Plate Antigens Market | 2026-2036
Mycoplasma Plate Antigens Market Size, Share, and Industry Trends Forecast 2026-2036
Mycoplasma Plate Antigens Market Foresight
Asset-light leasing models for specialized bioreactor equipment are reshaping how mid-sized diagnostic reagent manufacturers enter the mycoplasma plate antigens space. Thermo Fisher Scientific leverages its captive fermentation capacity to control raw antigen supply chains from cell culture through lyophilization. Charles River Laboratories International, Inc. anchors its position through contract manufacturing partnerships with veterinary health conglomerates. Bio-Rad Laboratories differentiates via proprietary plate coating chemistries that extend antigen stability during cold-chain distribution.
Mycoplasma plate antigens consist of purified membrane proteins or whole-cell lysates from Mycoplasma species, adsorbed onto polystyrene microtiter plates at defined concentrations for enzyme-linked immunosorbent assay detection. These reagents enable serological identification of mycoplasma infections in cell cultures, livestock herds, and human clinical specimens with specificity thresholds typically exceeding 95 percent. Diagnostic kits command the largest revenue share within product type segments, though reagents for in-house assay development are gaining traction among research laboratories seeking customization flexibility. Among end users, diagnostic centers represent the fastest-growing category as point-of-care veterinary testing decentralizes from centralized state laboratories.
The FDA Center for Veterinary Medicine enforces lot-release testing requirements that directly determine which antigen formulations qualify for interstate commerce in veterinary diagnostics. ISO 17025 accreditation standards for testing laboratories shape procurement specifications, filtering out plate antigen suppliers lacking documented measurement uncertainty protocols. Stakeholders must monitor evolving EPA guidelines on mycoplasma biocontainment levels in research facilities, as these will dictate capital allocation between BSL-2 and BSL-3 production infrastructure.
Market Dynamics
Asset-light leasing models for specialized bioreactor equipment are compressing capital barriers for mid-sized diagnostic reagent manufacturers entering mycoplasma plate antigen production. Thermo Fisher Scientific's captive fermentation capacity controls raw antigen supply chains from cell culture through lyophilization, forcing competitors toward contract manufacturing or niche coating chemistry differentiation.
Growth Catalysts
- ISO 17025 accreditation standards:Veterinary diagnostic laboratories in the United States now mandate documented measurement uncertainty protocols, filtering out non-compliant plate antigen suppliers and consolidating procurement toward accredited vendors.
- Point-of-care veterinary testing:Decentralized screening protocols across large-scale poultry and cattle operations are pulling demand from centralized state laboratories toward regional diagnostic centers.
- FDA Center for Veterinary Medicine lot-release testing:Interstate commerce requirements for veterinary biologics quality control are tightening manufacturing standards and qualifying only specific antigen formulations for commercial distribution.
Market Restraints
- Fermentation capacity concentration:Captive bioreactor infrastructure at dominant suppliers creates supply bottlenecks for membrane protein purification, constraining independent reagent developers.
- Polystyrene microtiter plate input volatility:Petrochemical feedstock price swings directly compress margin structures for plate coating operations at smaller manufacturers.
- Whole-cell lysate substitution threat:Recombinant protein expression systems are displacing traditional cultivation-dependent antigen sources in research laboratory segments.
Strategic Opportunities
- Research laboratory customization:Reagents for in-house assay development are gaining traction among academic and biopharma facilities seeking flexibility beyond standardized diagnostic kits.
- EPA biocontainment guideline evolution:Shifting BSL-2 versus BSL-3 production infrastructure requirements create first-mover advantages for facilities pre-positioned at higher containment tiers.
- Cold-chain distribution innovation:Proprietary plate coating chemistries extending antigen stability enable direct-to-farm veterinary diagnostic channels bypassing traditional distributor networks.
Industry Challenges
- Lyophilization process expertise scarcity:Specialized talent for stabilizing membrane proteins during freeze-drying operations concentrates at legacy diagnostic reagent manufacturers.
- Multi-jurisdiction certification timelines:Parallel FDA veterinary biologics and EPA biocontainment approvals extend product launch cycles for new antigen formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mycoplasma Plate Antigens Market |
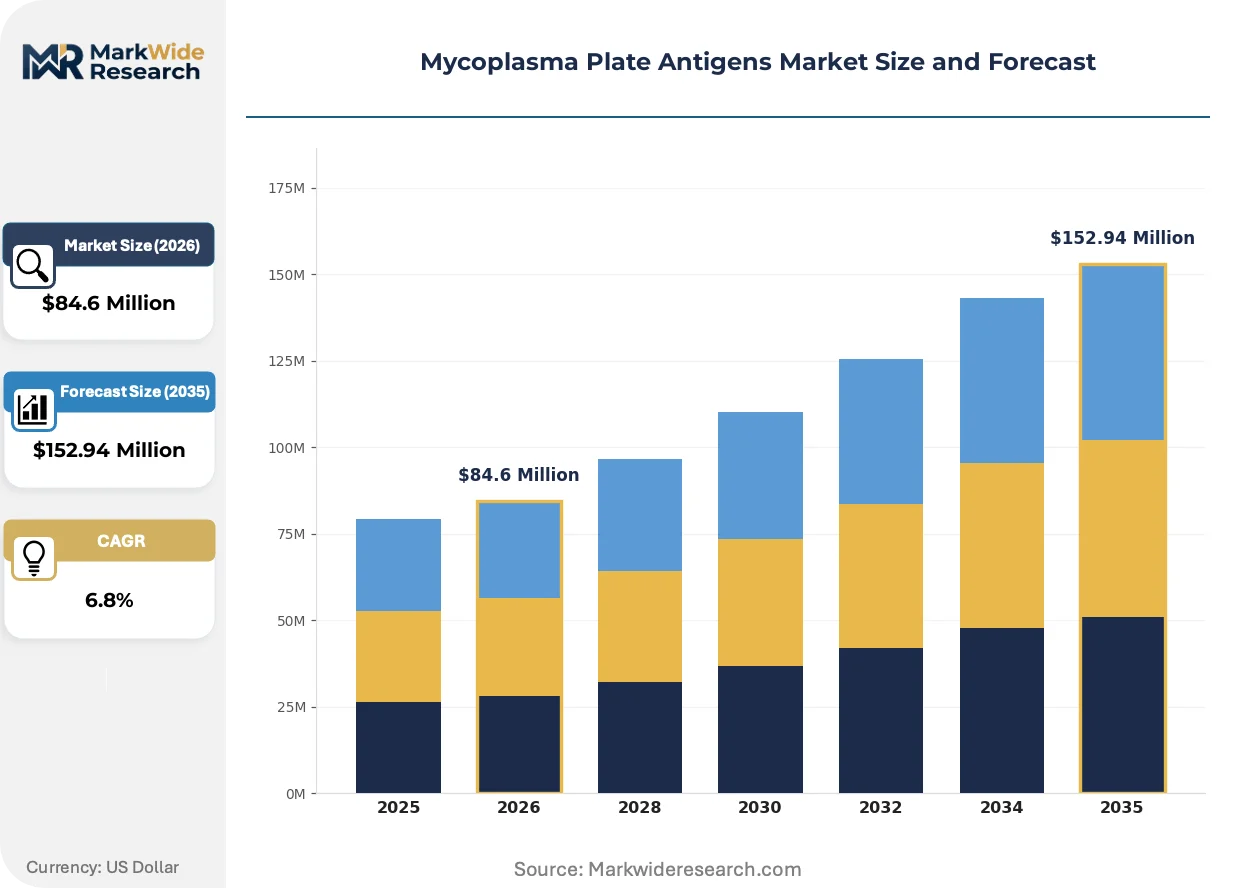
| Market Size in 2026 | $84.6 Million |
| Market Size in 2035 | $152.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Kits, Reagents, Antibodies, Control Samples End User: Research Laboratories, Hospitals, Diagnostic Centers, Academic Institutions Application: Infectious Disease Testing, Blood Testing, Vaccine Research, Quality Control Distribution Channel: Online Retail, Direct Sales, Distributors, Third-Party Resellers |
| Companies Covered | Thermo Fisher Scientific, QIAGEN N.V., Charles River Laboratories International, Inc., Bio-Rad Laboratories, Abnova Corporation, Prospec-Tany Technogene Ltd, MyBiosource, Inc., Eurofins Scientific S.E., Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mycoplasma Plate Antigens Market Shifts & Advancements
Diagnostic reagent manufacturing is migrating from standardized kit production toward modular, customizable platform architectures. This shift reflects pressure from research end-users seeking assay flexibility and from veterinary operations demanding rapid protocol adaptation.
Recombinant protein expression technology is displacing whole-cell lysate preparation as the dominant antigen source for mycoplasma detection assays. Academic research laboratories are adopting these systems fastest, driven by reproducibility requirements and reduced lot-to-lot variability. The technology is migrating from upstream R&D applications into commercial diagnostic manufacturing, compressing traditional cultivation-dependent supply chains.
REACH regulation amendments governing chemical substance registration are tightening documentation requirements for plate coating chemistries used in European diagnostic applications. Industrial consequence includes accelerated substitution of legacy adhesive formulations toward water-based alternatives. Veterinary diagnostic kit manufacturers serving EU member states are responding by reformulating coating protocols and revalidating stability data under revised compliance frameworks.
Consolidated procurement by large-scale integrated poultry operations is displacing fragmented purchasing across independent veterinary practices. Diagnostic reagent distributors serving the United States are restructuring toward direct enterprise contracts with multi-site livestock conglomerates. This concentration is most visible across the southeastern United States, where vertically integrated broiler operations now specify mycoplasma screening protocols at contract grower level.
Mycoplasma Plate Antigens Market Segmentation
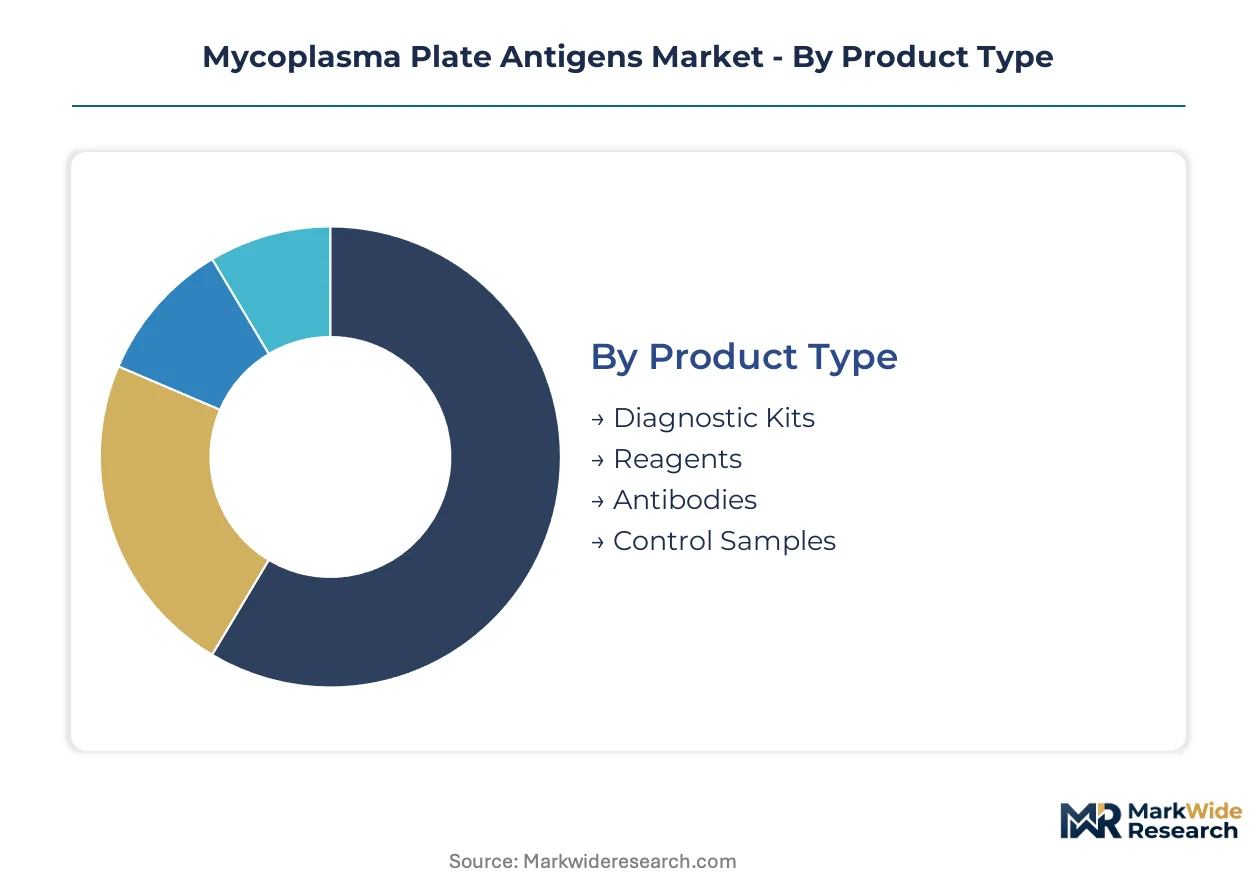
Antigen procurement patterns diverge sharply across customer archetypes in this market. Research laboratories prioritize reagent flexibility and lot-to-lot consistency, while diagnostic centers optimize for throughput and regulatory pre-qualification. Understanding these segment-specific buying criteria determines supplier positioning and pricing architecture.
Product Type:
Diagnostic kits turn inventory fastest through veterinary diagnostic centers, while control samples sit longest in quality assurance protocols. Reagents and antibodies occupy intermediate cycle positions depending on assay development timelines.
- Diagnostic Kits:Pre-configured ELISA plate assemblies with standardized antigen concentrations, buffers, and detection reagents. Demand concentrates in United States veterinary diagnostic centers serving large-scale poultry operations under FDA Center for Veterinary Medicine lot-release requirements.
- Reagents:Unconjugated antigens, conjugates, and substrate solutions for in-house assay development. Research laboratories in academic medical centers are pulling volumes fastest as customization flexibility displaces standardized kit procurement.
- Antibodies:Polyclonal and monoclonal detection reagents targeting Mycoplasma membrane proteins. Contract manufacturing organizations stock these for integration into proprietary diagnostic platforms.
- Control Samples:Certified reference materials with documented antigen titers for assay validation. Quality control laboratories in biopharma manufacturing maintain standing orders with extended shelf-life requirements.
Diagnostic kits dominate installed base. Reagents are where expansion concentrates.
End User:
Customer type determines margin structure more than volume scale in this market. Hospitals and diagnostic centers concentrate procurement through group purchasing organizations, while academic buyers fragment across individual principal investigator budgets.
- Research Laboratories:Academic and biopharma R&D facilities developing novel detection methodologies. These buyers prioritize recombinant antigen sources and modular reagent formats for protocol customization.
- Hospitals:Clinical microbiology laboratories performing cell culture contamination screening. United States hospital systems are consolidating mycoplasma testing into centralized reference laboratories to capture ISO 17025 accreditation efficiencies.
- Diagnostic Centers:Regional veterinary testing facilities serving livestock operations. Point-of-care decentralization across southeastern United States broiler production regions is pulling demand fastest.
- Academic Institutions:University core facilities supporting multi-investigator research programs. EPA biocontainment level requirements shape capital allocation between BSL-2 and BSL-3 infrastructure at these sites.
Diagnostic centers are climbing the fastest. Academic institutions retain the deepest customization requirements.
Application:
Application segmentation tracks directly to regulatory jurisdiction and reimbursement pathways. Quality control applications command premium pricing through validated manufacturing protocols, while research applications compete on technical specification.
- Infectious Disease Testing:Serological detection of Mycoplasma infections in livestock herds and cell cultures. United States veterinary operations specify these protocols at contract grower level under vertically integrated poultry company mandates.
- Blood Testing:Contamination screening in blood product manufacturing and transfusion medicine. FDA lot-release testing requirements govern antigen qualification for interstate commerce in this segment.
- Vaccine Research:Mycoplasma strain characterization and immunogenicity assessment during vaccine development. Biopharma companies source specialized antigen formulations for preclinical studies.
- Quality Control:Raw material and in-process testing for biologics manufacturing. ISO 17025 accreditation standards filter procurement toward suppliers with documented measurement uncertainty protocols.
Quality control commands premium positioning. Infectious disease testing shows the steepest expansion trajectory.
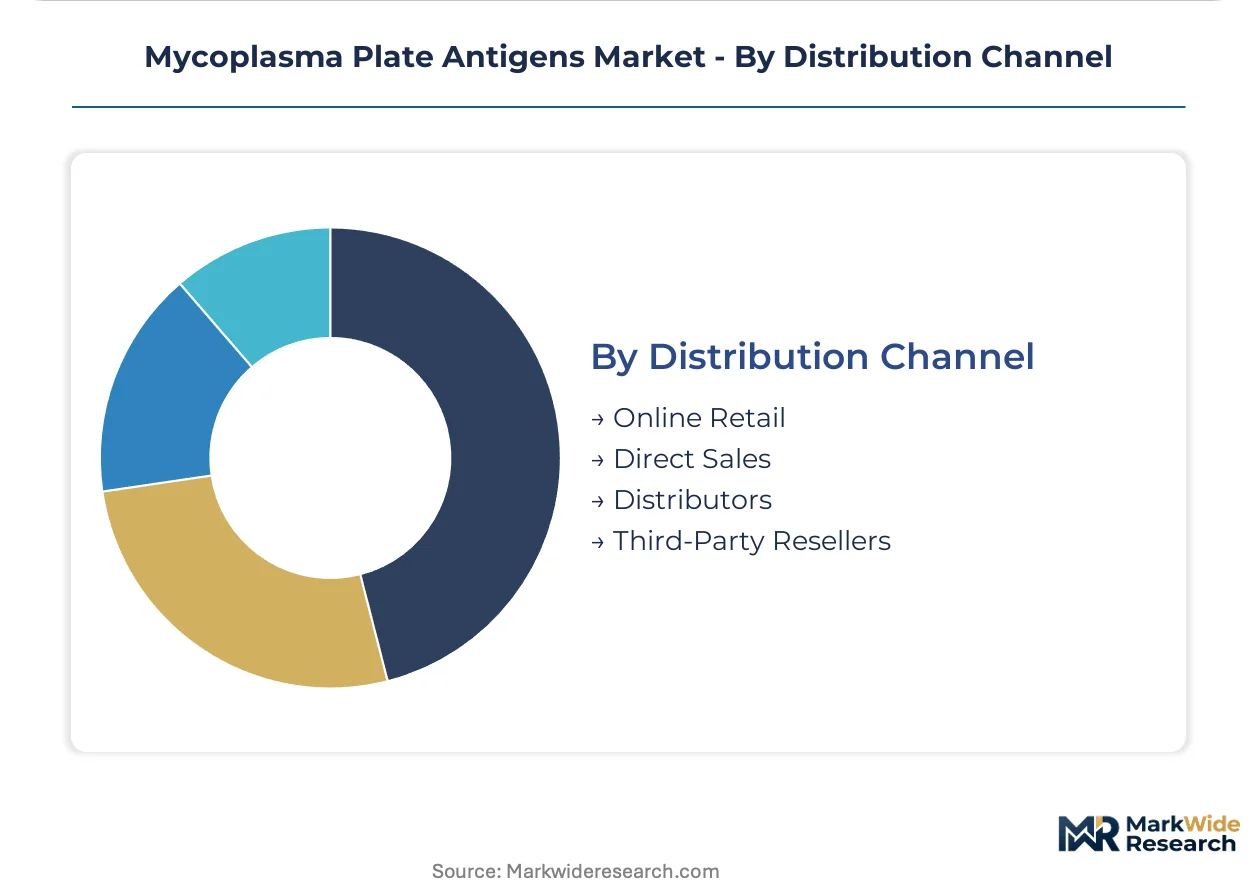
Distribution Channel:
Channel selection reflects customer scale and technical support requirements. Direct sales relationships dominate enterprise accounts, while online retail captures small-volume research buyers.
- Online Retail:E-commerce platforms serving research laboratories and small diagnostic facilities. Catalog distributors stock standard reagent grades with next-day fulfillment.
- Direct Sales:Manufacturer field organizations serving large veterinary health conglomerates and biopharma accounts. Thermo Fisher Scientific and Charles River Laboratories anchor positions through captive fermentation capacity and contract manufacturing partnerships.
- Distributors:Regional warehousing networks with cold-chain logistics capabilities. These intermediaries extend reach to decentralized diagnostic centers lacking direct supplier relationships.
- Third-Party Resellers:Specialized brokers sourcing hard-to-obtain antigen formulations or discontinued product lines. Niche coating chemistry suppliers leverage these channels for market entry.
Direct sales captures the largest transaction values. Online retail is gaining share fastest among research segment buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA lot-release testing requirements for veterinary biologics are tightening interstate commerce standards in the United States, while REACH amendments in Europe reshape coating chemistry documentation. These regulatory shifts are concentrating procurement toward accredited suppliers with documented measurement uncertainty protocols.
United States
Large-scale poultry and cattle operations in the Southeast require routine mycoplasma screening at contract grower level. The FDA Center for Veterinary Medicine enforces lot-release testing that determines which antigen formulations qualify for interstate veterinary commerce. Diagnostic reagent distributors are restructuring toward direct enterprise contracts with vertically integrated broiler operations across Georgia and Alabama.
Germany
REACH regulation amendments are tightening documentation requirements for polystyrene microtiter plate coating chemistries used in diagnostic applications. The ECHA is accelerating substitution toward water-based adhesive formulations. Industrial clusters in Baden-Württemberg host contract manufacturing organizations integrating these reformulated coating protocols into veterinary diagnostic platforms.
China
Biopharma manufacturing expansion is driving demand for mycoplasma quality control reagents in cell culture contamination screening. The NMPA governs diagnostic reagent registration with escalating documentation standards for imported antigen formulations. Yangtze River Delta biotech parks in Shanghai and Suzhou are attracting regional distribution hubs serving domestic vaccine producers.
United Kingdom
Academic research laboratories prioritize recombinant antigen sources for assay development flexibility. The country's national pharmaceutical regulator maintains alignment with EU veterinary biologics standards post-Brexit. Cambridge and Oxford research corridors concentrate procurement of modular reagent formats for multi-investigator core facilities.
Japan
Cell culture contamination screening in biologics manufacturing commands premium pricing for validated antigen formulations. The PMDA enforces strict lot-to-lot consistency requirements for diagnostic reagents used in pharmaceutical quality control. Kanto region biotech clusters around Tokyo anchor demand for ISO 17025-accredited reference materials.
Mycoplasma Plate Antigens Market Competitive Landscape
On the supply side, the industry is consolidating around captive fermentation capacity and proprietary coating chemistries. Diagnostic reagent manufacturing exhibits tiered structure with dominant integrated suppliers, specialized coating technology developers, and contract manufacturing intermediaries. Three strategic archetypes define positioning: captive bioreactor operators controlling upstream antigen supply, coating chemistry specialists differentiating through stability extension, and contract research organizations anchoring veterinary health partnerships. Competitive moves concentrate on backward integration into fermentation infrastructure and direct-to-farm distribution channel development.
Among integrated life sciences conglomerates, Thermo Fisher Scientific exemplifies the captive capacity archetype through control of cell culture through lyophilization supply chains. Charles River Laboratories International, Inc. occupies a position within the contract manufacturing tier, anchoring partnerships with veterinary health conglomerates. Bio-Rad Laboratories represents the coating chemistry specialist archetype, sitting within the stability innovation segment through proprietary plate formulations. These three entities collectively illustrate the strategic divergence between upstream supply control and downstream technical differentiation in mycoplasma plate antigen procurement.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| QIAGEN N.V. |
| Charles River Laboratories International, Inc. |
| Bio-Rad Laboratories |
| Abnova Corporation |
| Prospec-Tany Technogene Ltd |
| MyBiosource, Inc. |
| Eurofins Scientific S.E. |
| Merck KGaA |
| Others |
Supply & Pricing Matrix
Captive fermentation capacity in the United States and Western Europe concentrates upstream antigen production, directing margin capture toward lyophilization expertise and proprietary plate coating chemistries downstream. Polystyrene microtiter plate input volatility and recombinant protein substitution threats are compressing margin structures for smaller manufacturers lacking backward integration into cell culture operations.
Pricing Analysis
Certification level creates the primary spread between ISO 17025-accredited reference materials and non-validated research-grade reagents. Three-tier pricing structure across premium, standard, and economy levels reflects FDA lot-release qualification status, with veterinary diagnostic kits commanding premiums through interstate commerce compliance. Cost compression in the research-grade tier is intensifying because recombinant protein expression systems are displacing traditional whole-cell lysate sources. Academic laboratories exhibit highest price sensitivity, while biopharma quality control operations prioritize lot-to-lot consistency over unit cost.
Supply Chain Analysis
Export-control regimes governing dual-use bioreactor technology limit flow of specialized fermentation equipment to certain jurisdictions, constraining capacity expansion in emerging production regions. Raw antigen supply concentrates in the United States, Germany, and Japan, drawing from petrochemical feedstocks for polystyrene plates, specialized membrane protein purification resins, and lyophilization excipients. Single-source vulnerability in captive bioreactor infrastructure at dominant suppliers creates supply bottlenecks for independent reagent developers. Distribution runs through direct enterprise contracts with veterinary health conglomerates, supplemented by regional cold-chain distributors serving decentralized diagnostic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized talent for stabilizing membrane proteins during freeze-drying operations concentrates at legacy manufacturers, creating acquisition premiums for facilities with documented process expertise and established regulatory dossiers.
For Market Incumbents: Entrench position through captive fermentation capacity additions in BSL-3 infrastructure clusters ahead of anticipated EPA biocontainment guideline evolution. Lock in direct-to-farm distribution channels with vertically integrated poultry operations across the southeastern United States to preempt contract manufacturing competitors. Recombinant protein substitution in academic segments threatens traditional lysate-based revenue streams. For New Entrants and Emerging Players: Pursue white-space opportunities in modular reagent formats for research laboratories seeking customization flexibility beyond standardized diagnostic kits. The point-of-care veterinary testing segment offers lowest penetration barriers, with regional diagnostic centers in livestock-intensive states lacking established supplier relationships. A coating chemistry specialization strategy—proprietary formulations extending antigen stability during cold-chain distribution—enables bypass of traditional distributor networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturing organizations holding FDA Center for Veterinary Medicine lot-release approvals but lacking lyophilization depth. The five-to-ten year viability window favors targets combining captive fermentation with proprietary coating intellectual property. Watch for EPA biocontainment level revisions as the inflection signal determining capital allocation between BSL-2 and BSL-3 production infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Infrastructure | Captive bioreactor capacity insulates raw antigen supply from contract manufacturing bottlenecks at Thermo Fisher Scientific. |
| Proprietary Plate Coating Chemistry Development | Stability-extending formulations enable direct-to-farm veterinary channels bypassing traditional cold-chain distributors. |
| BSL-3 Production Facility Pre-positioning | EPA biocontainment guideline evolution will qualify higher-tier facilities for premium antigen manufacturing contracts. |
| ISO 17025 Accreditation Investment | Documented measurement uncertainty protocols filter procurement toward accredited vendors in veterinary diagnostic laboratories. |
| Recombinant Protein Expression Platform Migration | Academic research laboratories are accelerating adoption of reproducible antigen sources with reduced lot-to-lot variability. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with diagnostic reagent manufacturing executives, veterinary laboratory directors, and biopharma quality control managers; and secondary validation through FDA Center for Veterinary Medicine lot-release filings, EPA biocontainment facility registrations, ISO 17025 accreditation databases, and trade data on polystyrene microtiter plate imports. Bottom-up triangulation across antigen production volumes and top-down cross-check against veterinary diagnostic testing frequency estimates anchored market sizing.
Forecast inputs span product type segmentation across diagnostic kits, reagents, antibodies, and control samples; end-user categories from research laboratories through diagnostic centers; and application areas including infectious disease testing, blood testing, vaccine research, and quality control. CAGRs were derived from elasticity-adjusted demand projections incorporating regulatory approval timelines and livestock herd expansion patterns across the analysis window. Industry-specific inputs include FDA veterinary biologics approval trajectories and REACH amendment implementation schedules for coating chemistry reformulation.
Sensitivities concentrate around EPA biocontainment level revisions, REACH-driven coating chemistry substitution timelines, and recombinant protein expression technology adoption rates in academic research segments. Forecasts reflect documented assumptions on regulatory enforcement intensity and livestock operation consolidation patterns. Material shifts in FDA lot-release testing requirements or EPA facility classification standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Global Microbial Products Market
Industrial Microbiology
Probiotic Yeast Market
Industrial Microbiology
Microbial Identification Panels Market
Industrial Microbiology
Lactobacillus Strains Market
Industrial Microbiology
Microbiology Testing Market
Industrial Microbiology
Microbiomes Market
Industrial Microbiology
Microbial Rennet Market
Industrial Microbiology
Microbial Culture Market
Industrial Microbiology
Microbiome Sample Preparation Technology Market
Industrial Microbiology
Mineral Yeast Market
Industrial Microbiology
Salinomycin Market
Industrial Microbiology
Molecular Microbiology Market
Industrial Microbiology
Global Bacterial Cell Culture Market
Industrial Microbiology
Europe Microbial Based Biological Seed Treatment Market
Industrial Microbiology
Microbial Therapeutic Products Market
Industrial Microbiology
Microbial Bioreactors Market