
 Microbial Identification Panels Market | 2026-2036
Microbial Identification Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Microbial Identification Panels Market Foresight
A capital-intensity divergence between MALDI-TOF mass spectrometry specialists and multiplex PCR platform developers is rotating competitive investment priorities across the sector. Thermo Fisher Scientific leverages its integrated reagent-instrument ecosystem to sustain pricing power in high-throughput clinical labs. bioMérieux SA anchors its position through dedicated bloodstream infection workflows that dominate European reference laboratories. Bruker Corporation differentiates via proprietary protein fingerprint databases that compete aggressively on per-test economics.
Microbial identification panels are consumable assay cartridges or chip-based systems that detect, enumerate, or speciate microorganisms through biochemical, genetic, or proteomic signatures, typically processing 8–96 simultaneous targets with turnaround under 24 hours. Their primary purpose centers on guiding antimicrobial therapy selection and tracking resistance patterns in patient care and manufacturing environments. Mass spectrometry platforms command premium placement in tertiary hospital labs where speed justifies instrument cost, while next-generation sequencing segments gain fastest traction in outbreak surveillance and resistance gene mapping. Biosensors occupy emerging niches in point-of-care settings where miniaturization offsets lower multiplexing depth.
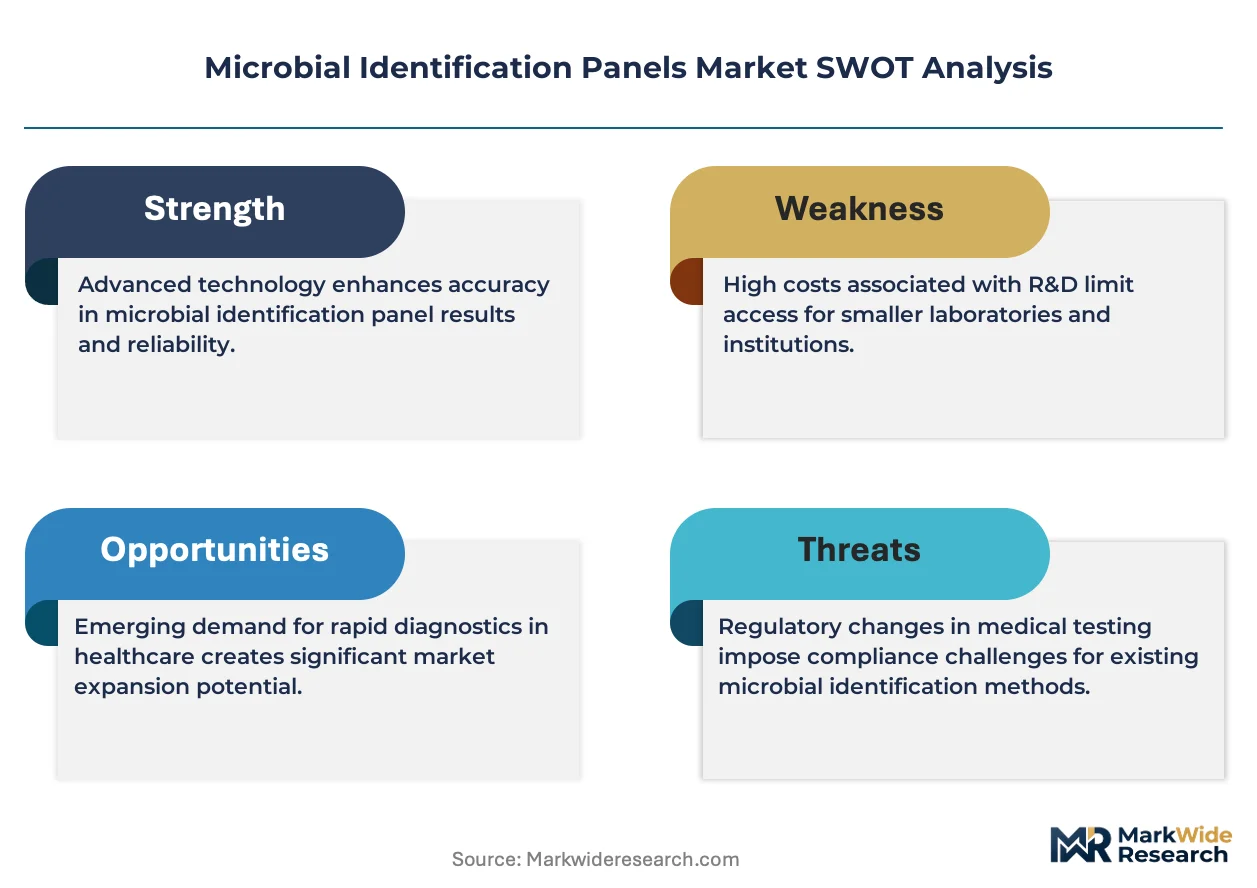
FDA clearance pathways under 21 CFR Part 866 and EMA IVD-DR requirements shape product development timelines and clinical claim substantiation for panel manufacturers. ISO 15189 accreditation standards and CLSI antimicrobial susceptibility testing guidelines further constrain which platforms hospitals and clinical labs may adopt. Stakeholders must monitor evolving WHO priority pathogen lists and corresponding national reimbursement decisions to align R&D portfolios with addressable demand.
Market Dynamics
Automated bloodstream infection workflows are compressing turnaround times from days to hours, forcing tertiary hospitals to consolidate testing platforms and abandon slower biochemical methods. This operational imperative is redistributing capital allocation across clinical laboratory networks.
Growth Catalysts
- FDA antimicrobial resistance surveillance mandates:The 21 CFR Part 866 pathway tightens pathogen reporting requirements, compelling clinical laboratories to upgrade from single-target assays to multiplex panels.
- Hospital-acquired infection monitoring budgets:Centers for Medicare & Medicaid Services penalty frameworks for preventable infections are expanding reimbursement coverage for rapid diagnostic testing in US acute care facilities.
- Mass spectrometry miniaturization:Benchtop MALDI-TOF systems are penetrating mid-sized hospital labs previously priced out of proteomic identification, extending addressable demand beyond reference laboratories.
Market Restraints
- Consumable cost concentration:Reagent-instrument lock-in models from dominant platform vendors inflate per-test economics 40-60% above open-system alternatives, squeezing mid-volume laboratory margins.
- Proprietary database fragmentation:Bruker's protein fingerprint libraries and Thermo Fisher's genetic reference panels operate as walled gardens, preventing cross-platform standardization and forcing redundant capital expenditure.
- ISO 15189 accreditation timelines:European clinical laboratories face 12-18 month validation periods for new panel introductions, delaying technology refresh cycles and freezing competitive switching.
Strategic Opportunities
- Point-of-care biosensor convergence:Miniaturized electrochemical sensors combining nucleic acid amplification with smartphone readouts are opening emergency department and ambulatory clinic channels previously inaccessible to centralized lab platforms.
- EMA IVD-DR harmonization:The 2022 In Vitro Diagnostic Medical Devices Regulation creates unified conformity assessment pathways across 27 member states, reducing fragmentation costs for panel manufacturers seeking European market entry.
- Next-generation sequencing outbreak surveillance:Resistance gene mapping applications in public health laboratories are outpacing traditional culture-based methods, creating white space for targeted amplicon panels in genomic epidemiology.
Industry Challenges
- CLSI antimicrobial susceptibility testing guideline compliance:Laboratories must maintain dual workflows for phenotypic confirmation alongside molecular panel results, duplicating staffing and quality control overhead.
- Legacy laboratory information system integration:Hospital IT infrastructure built around 1990s-era HL7 standards requires expensive middleware development to interface with cloud-connected panel instruments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbial Identification Panels Market |
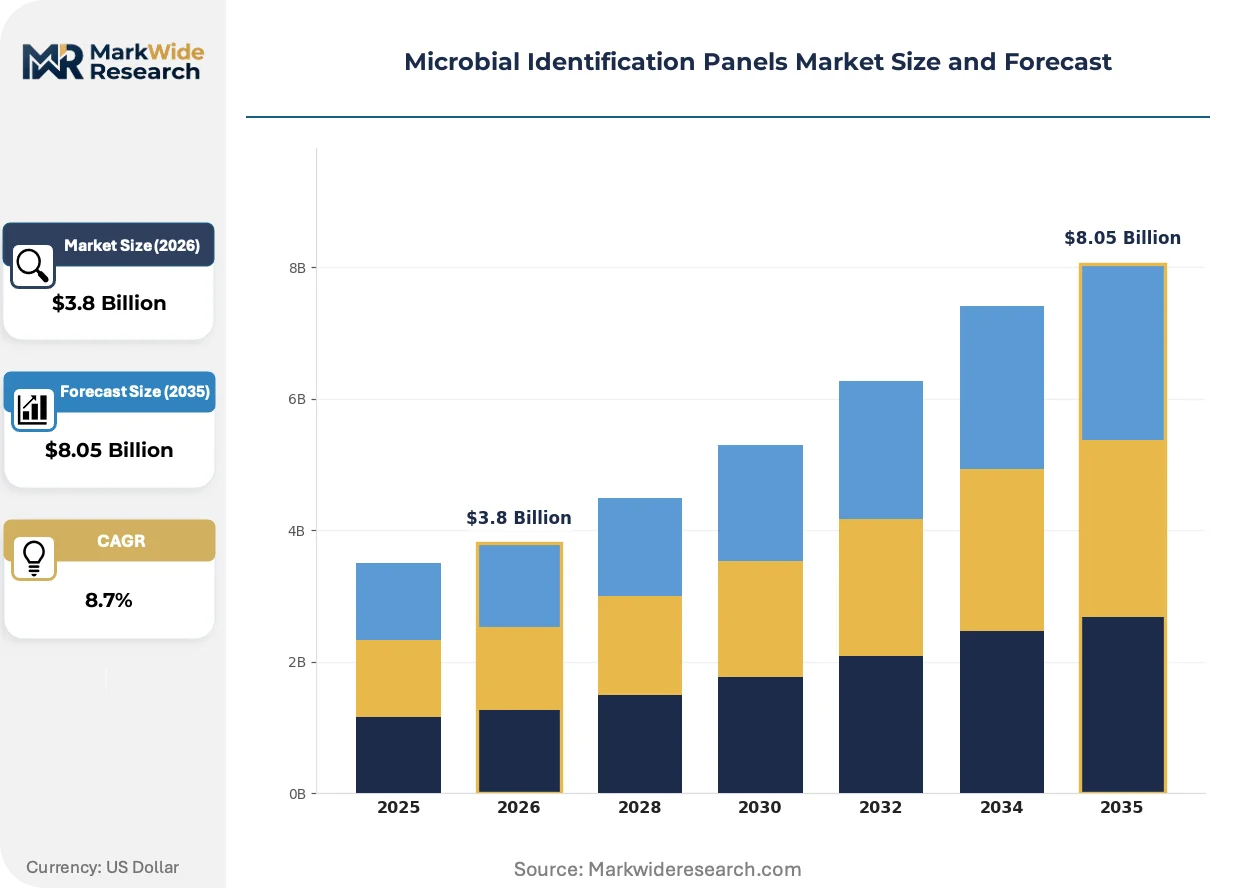
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymerase Chain Reaction, Mass Spectrometry, Next-Generation Sequencing, Biosensors Technology: Genetic Sequencing, Microarray, Biochemical Testing, Imaging Systems Application: Clinical Diagnostics, Environmental Testing, Food Safety, Pharmaceutical Research End User: Hospitals, Clinical Labs, Research Institutions, Diagnostic Centers |
| Companies Covered | bioMérieux SA, Becton, Dickinson and Company, Thermo Fisher Scientific Inc., Danaher Corporation, Merck KGaA, Bruker Corporation, Shimadzu Corporation, QIAGEN, Biolog Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbial Identification Panels Market Shifts & Advancements
Convergence between proteomic fingerprinting and genomic target detection is dissolving traditional boundaries between mass spectrometry and molecular diagnostic platforms. This technological overlap is compressing vendor differentiation strategies and accelerating platform consolidation decisions among hospital procurement committees.
Next-generation sequencing-based panels are fragmenting the reference laboratory segment previously dominated by MALDI-TOF mass spectrometry. Academic medical centers with in-house genomics cores are adopting targeted amplicon sequencing for resistance gene surveillance, bypassing commercial platform vendors entirely. This adoption pattern is compressing the addressable market for high-multiplex PCR cartridges in outbreak investigation settings.
EMA IVD-DR performance evaluation requirements are extending clinical validation timelines for novel panel submissions. Manufacturers must now generate prospective clinical evidence across multiple member states, inflating regulatory affairs staffing and delaying revenue recognition. Smaller platform developers are responding by prioritizing US FDA 510(k) clearance first, treating European market entry as a secondary phase.
Integrated service contracts are displacing instrument purchase models in German and French hospital networks. Procurement committees now bundle reagent supply, maintenance, and result interpretation support into single-source agreements, favoring vendors with field application scientist density. This bundling trend is visible most acutely in bloodstream infection workflow deployments where 24-hour technical support is mandatory.
Microbial Identification Panels Market Segmentation
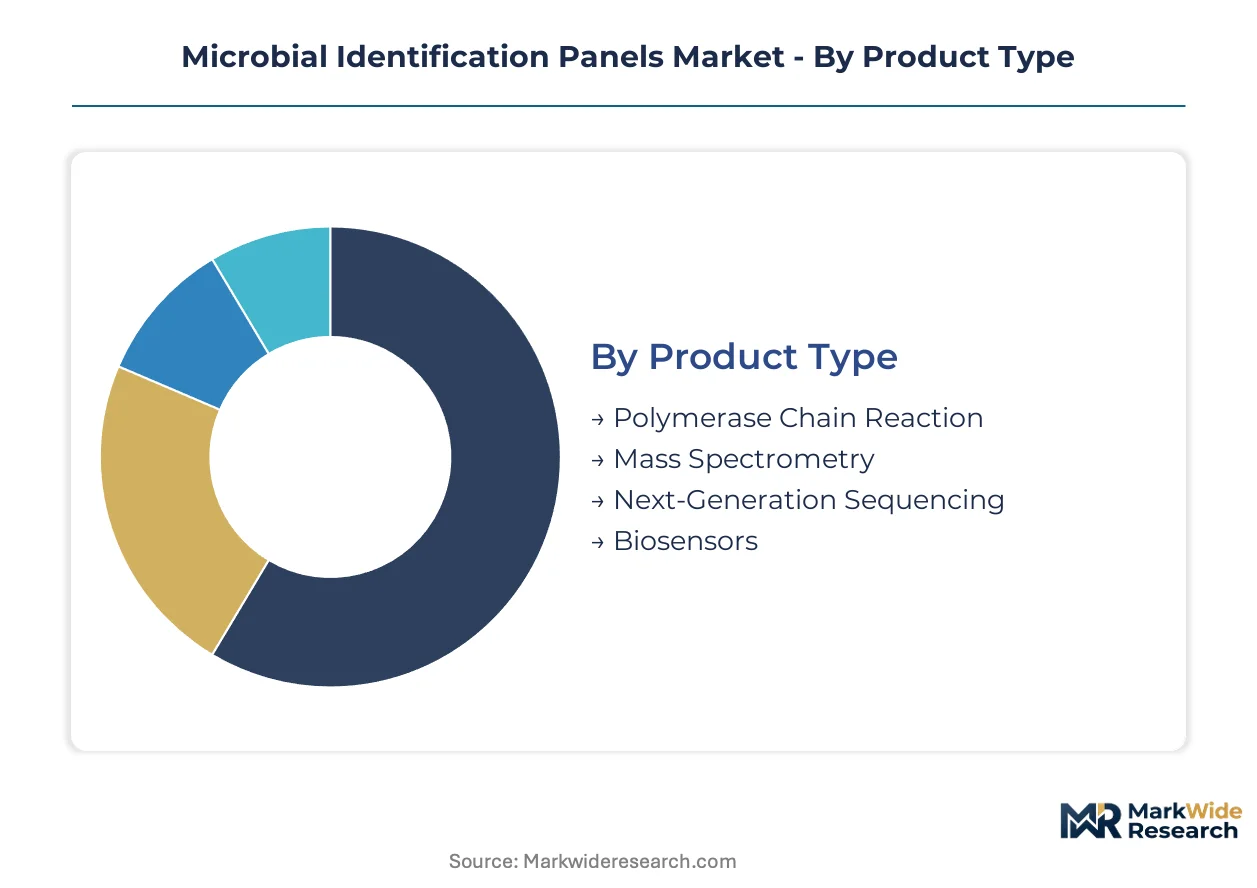
Platform selection in microbial identification hinges on throughput requirements, capital budgets, and regulatory compliance timelines. Segmentation reveals how technology choices fragment across laboratory tiers and geographic markets with divergent reimbursement frameworks.
Product Type:
Mass spectrometry platforms concentrate in German, French, and US tertiary hospitals with capital budgets exceeding reference laboratory thresholds. PCR-based systems dominate mid-volume clinical labs in China and India where per-test economics outweigh speed premiums.
- Polymerase Chain Reaction:Multiplex PCR cartridges process 8–96 targets simultaneously with turnaround under six hours. Demand clusters in US hospital-acquired infection surveillance programs where FDA 510(k) clearance accelerates procurement. CMS penalty frameworks for preventable infections drive replacement of single-target assays.
- Mass Spectrometry:MALDI-TOF systems generate protein fingerprints for species-level identification in minutes. European reference laboratories in Germany and France anchor adoption; benchtop miniaturization extends reach to mid-sized US hospitals previously priced out of proteomic platforms.
- Next-Generation Sequencing:Targeted amplicon panels map resistance genes for outbreak surveillance.
- Biosensors:Electrochemical sensors with smartphone readouts penetrate emergency departments.
Mass spectrometry holds the largest share; momentum sits with next-generation sequencing in public health applications.
Technology:
Genetic sequencing commands premium pricing in resistance gene mapping workflows. Biochemical testing retains footholds in resource-constrained settings where capital substitution outweighs speed requirements.
- Genetic Sequencing:Sanger and NGS methods detect nucleic acid signatures with single-base resolution. Academic medical centers in the United States bypass commercial vendors through in-house genomics cores, compressing addressable markets for high-multiplex cartridges.
- Biochemical Testing:Traditional phenotypic methods require 24–48 hour incubation but demand minimal capital. Rural diagnostic centers in India and China maintain these workflows where ISO 15189 accreditation timelines delay molecular platform validation.
- Microarray:Chip-based hybridization enables parallel detection of hundreds of targets.
- Imaging Systems:Automated microscopy with AI classification accelerates culture confirmation.
Genetic sequencing dominates revenue; biochemical testing retains volume in emerging markets.
Application:
Clinical diagnostics absorbs two-thirds of panel consumption through bloodstream infection and respiratory pathogen workflows. Environmental and food safety applications trail with longer replacement cycles and price-sensitive procurement.
- Clinical Diagnostics:Bloodstream infection panels guide antimicrobial therapy selection in intensive care units. US acute care facilities expand testing under CMS penalty frameworks; German hospital networks bundle reagent supply into integrated service contracts with mandatory 24-hour support.
- Food Safety:Pathogen detection in manufacturing environments requires environmental monitoring compliance. Chinese regulatory expansion under SAMR oversight drives adoption in dairy and meat processing facilities.
- Environmental Testing:Water and soil contamination screening for industrial discharge monitoring.
- Pharmaceutical Research:Sterility testing and raw material qualification in drug manufacturing.
Clinical diagnostics commands the largest share; food safety climbs fastest on regulatory expansion in Asia-Pacific manufacturing hubs.
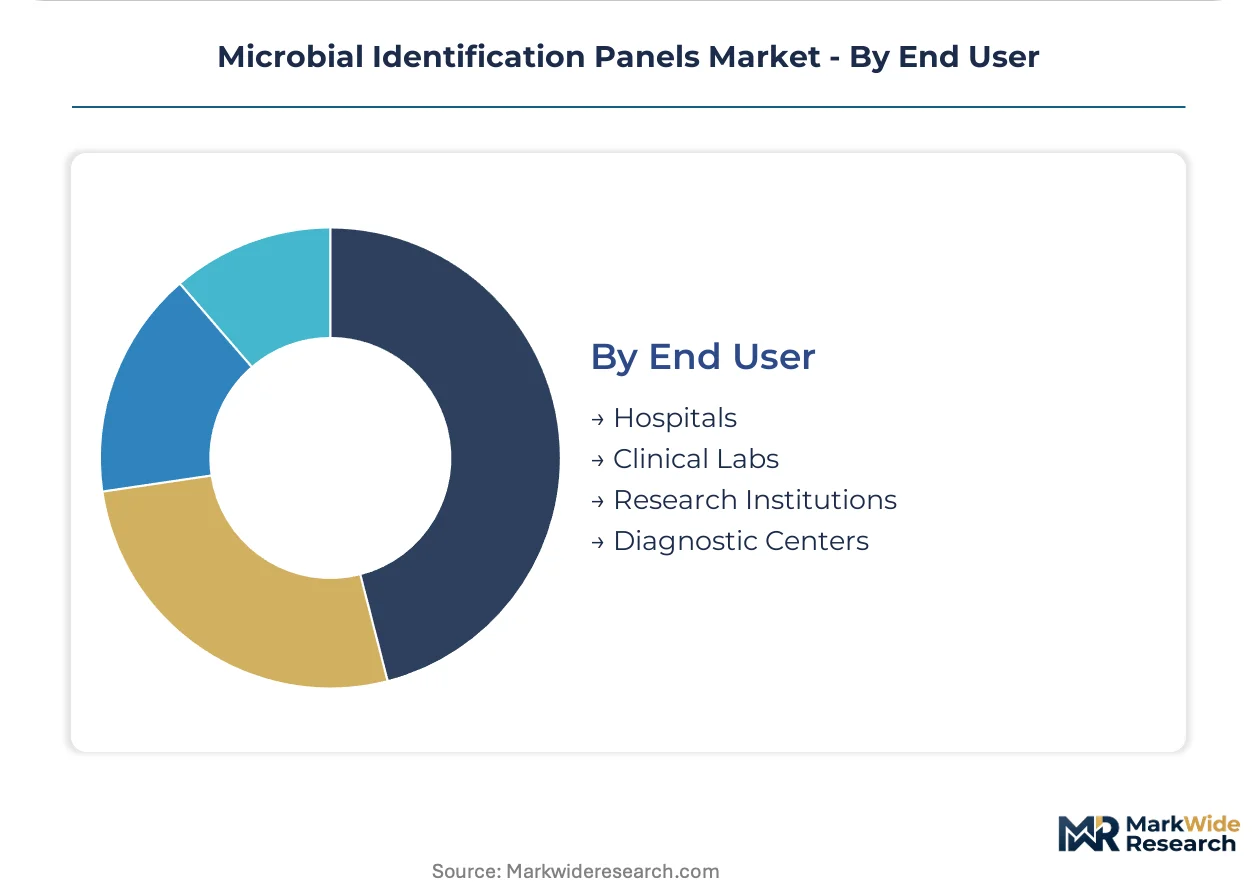
End User:
Hospital central laboratories consolidate testing platforms to compress turnaround times. Diagnostic centers fragment across independent chains and hospital-affiliated networks with divergent capital access.
- Hospitals:Tertiary academic centers in the United States, Germany, and China deploy automated workflows to reduce bloodstream infection mortality. Procurement committees prioritize platforms with HL7-compatible middleware to bridge legacy IT infrastructure.
- Clinical Labs:Reference laboratories process high-volume panels for hospital networks. European facilities face 12–18 month ISO 15189 validation timelines that freeze competitive switching and extend incumbent platform tenure.
- Research Institutions:Academic genomics cores develop in-house targeted amplicon protocols.
- Diagnostic Centers:Independent chains compete on turnaround time for outpatient infectious disease testing.
Hospitals hold the largest share; clinical labs gain momentum on network consolidation and integrated service contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds German benchmarks by approximately 25-30% for equivalent multiplex PCR platforms, while Chinese procurement operates on compressed per-test economics that prioritize volume scale over margin capture.
United States
CMS penalty frameworks for preventable hospital-acquired infections drive replacement of single-target assays with multiplex panels in acute care facilities. FDA 21 CFR Part 866 clearance pathways accelerate procurement decisions for bloodstream infection workflows. The Boston-Cambridge corridor anchors academic medical center adoption of next-generation sequencing for resistance gene surveillance.
Germany
Integrated service contracts bundle reagent supply, maintenance, and 24-hour technical support into single-source agreements across hospital networks. EMA IVD-DR harmonization reduces conformity assessment fragmentation across member states, though ISO 15189 accreditation timelines extend 12-18 months. The Rhine-Ruhr metropolitan region concentrates reference laboratory platform consolidation.
China
SAMR regulatory expansion drives adoption in dairy and meat processing facilities for environmental monitoring compliance. Mid-sized hospital labs prioritize PCR-based systems where per-test economics outweigh speed premiums. The Yangtze River Delta manufacturing corridor generates demand for sterility testing panels in pharmaceutical production.
France
ANSM oversight tightens clinical validation requirements for novel panel introductions, extending regulatory affairs staffing needs. Tertiary hospitals in the Paris-Saclay cluster deploy automated workflows to compress bloodstream infection turnaround times. Procurement committees favor vendors with dense field application scientist networks.
Japan
PMDA consultation pathways shape development timelines for manufacturers seeking pharmaceutical-quality diagnostic claims. METI industrial policy supports domestic platform development for infectious disease preparedness. The Kanto region's academic medical centers balance MALDI-TOF placement with in-house genomics core capabilities.
Microbial Identification Panels Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with mass spectrometry specialists commanding premium placement in tertiary hospitals while multiplex PCR developers compete on per-test economics in mid-volume laboratories. The vendor base stratifies into three tiers: integrated life science conglomerates with reagent-instrument ecosystems, dedicated diagnostic platform developers with proprietary databases, and emerging biosensor specialists targeting point-of-care miniaturization. Dominant competitive moves include strategic partnerships to bridge legacy IT infrastructure gaps and geographic expansion through integrated service contracting.
Among integrated conglomerates, Thermo Fisher Scientific Inc. and Danaher Corporation occupy positions that exemplify reagent-instrument lock-in models, while Bruker Corporation anchors the proteomic fingerprinting specialist tier with proprietary database differentiation. bioMérieux SA represents the dedicated diagnostic developer archetype focused on bloodstream infection workflow dominance in European reference laboratories.
| Leading Market Players |
|---|
| bioMérieux SA |
| Becton, Dickinson and Company |
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| Merck KGaA |
| Bruker Corporation |
| Shimadzu Corporation |
| QIAGEN |
| Biolog Inc. |
| Others |
Supply & Pricing Matrix
Integrated service contracts spanning reagent supply, instrument maintenance, and 24-hour technical support lock in both supply access and price visibility for hospital networks in Germany and France. These multi-year agreements compress procurement flexibility while stabilizing vendor margins against spot-market volatility in consumable pricing.
Pricing Analysis
The customization-premium spread between configured-to-order MALDI-TOF systems and standard multiplex PCR cartridges spans substantial territory in this market. Per-unit transactional pricing dominates consumable cartridges, while instrument placements run on bundled subscription models with minimum volume commitments. Price differentiation hinges on ISO 15189 accreditation tier and after-sales service density. Cost compression in mid-volume laboratory segments is intensifying because reagent-instrument lock-in models inflate per-test economics above open-system alternatives. Reference laboratories in European tertiary hospitals show least price sensitivity; independent diagnostic chains in India and China exhibit highest.
Supply Chain Analysis
Inbound logistics costs for precision optical components and rare-earth magnet assemblies have tightened following port congestion on Asia-Europe trade lanes serving German manufacturing hubs. Supply concentrates in the United States, Germany, and China for finished instrument assembly, with critical electronic subcomponents drawing from Taiwan and South Korea. Raw material dependencies span high-purity reagents, specialized polymer substrates, and noble-metal catalysts. Single-source vulnerability around proprietary reference database licensing poses structural risk. Distribution runs through direct field service organizations for hospital networks, with third-party distributors penetrating mid-sized clinical labs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital network consolidation and integrated service contracting, fragmenting procurement decisions into fewer hands with greater leverage over vendor terms.
For Market Incumbents: Secure proprietary database expansion through exclusive licensing of resistance gene libraries to forestall open-platform standardization. Anchor reagent production capacity in the United States to mitigate EMA IVD-DR regulatory disruption. The threat of academic medical centers bypassing commercial vendors through in-house genomics cores demands defensive R&D investment in cloud-connected bioinformatics layers. For New Entrants and Emerging Players: Anchor in point-of-care biosensor miniaturization where electrochemical sensors with smartphone readouts penetrate emergency departments previously inaccessible to centralized lab platforms. The most penetrable segment sits in ambulatory clinic channels across India's diagnostic center chains. A go-to-market angle pairing consumable affordability with minimal capital burden outflanks incumbent instrument-heavy models. For Investors and Strategic Acquirers: The market sits at a platform-consolidation phase that favors integrated reagent-instrument ecosystems with dense field service networks. Long-term viability hinges on regulatory navigation capabilities across FDA 21 CFR Part 866 and EMA IVD-DR pathways. Acquisition targets should display proprietary database assets and established ISO 15189 validation track records. The signal to watch is CMS reimbursement expansion for rapid diagnostic testing in acute care settings.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Database Expansion | Exclusive resistance gene libraries block open-platform standardization and extend vendor lock-in across hospital networks. |
| Benchtop Miniaturization Launch | Scaled-down MALDI-TOF systems penetrate mid-sized US hospitals previously priced out of proteomic identification platforms. |
| Integrated Service Contracting | Bundled reagent supply and 24-hour technical support displace instrument purchase models in German hospital procurement. |
| Point-of-Care Biosensor Development | Electrochemical sensors with smartphone readouts open emergency department channels beyond centralized laboratory reach. |
| Cloud-Connected Middleware Investment | HL7-compatible interfaces bridge legacy hospital IT infrastructure gaps that freeze competitive switching decisions. |
Research Methodology
Cross-validation between primary interviews with clinical laboratory directors and secondary validation through FDA 510(k) clearance databases anchors the qualitative findings in this analysis. Conversations with hospital procurement managers, biomedical engineers, GPO contracts managers, and reference laboratory quality officers generated demand-side intelligence. Secondary sources span CMS Medicare reimbursement data, EMA IVD-DR submission records, hospital procurement databases, and ISO 15189 accreditation registries. Bottom-up triangulation across instrument placement volumes and top-down reconciliation against consumable cartridge production estimates ensured consistency.
Sensitivity analysis across platform adoption scenarios and reimbursement policy shifts frames the quantitative outputs over the projection horizon. Segmentation dimensions modeled include technology platform, application workflow, end-user laboratory tier, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to historical adoption patterns. Forecast inputs incorporate antimicrobial resistance surveillance mandate expansion and hospital-acquired infection penalty framework evolution.
Material uncertainties — regulatory timeline delays, reimbursement coverage retractions, and supply chain disruptions — sit outside the modeled envelope. Forecasts reflect assumptions around continued FDA and EMA pathway stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Global Microbial Products Market
Industrial Microbiology
Mesophilic Bacteria Market
Industrial Microbiology
Molecular Microbiology Market
Industrial Microbiology
Global Microbial Fermentation Technology Market
Industrial Microbiology
Microbial Coagulants Market
Industrial Microbiology
Anti-Microbial Anti-Fungal Test Market
Industrial Microbiology
Automated Microbiology Market
Industrial Microbiology
Probiotic Yeast Market
Industrial Microbiology
Salinomycin Market
Industrial Microbiology
Microbiology Culture Market
Industrial Microbiology
Bacillus Subtilis Market
Industrial Microbiology
Automated Microbial Detection Systems Market
Industrial Microbiology
Specialty Cultures Market
Industrial Microbiology
Microbial Cell Banking Market
Industrial Microbiology
Galactosidase Market
Industrial Microbiology
Global Bacterial Cell Culture Market