
 Global Microbial Identification Market | 2026-2036
Global Microbial Identification Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microbial Identification Market Analysis
Direct distribution to hospital microbiology labs is narrowing as instrument vendors consolidate service contracts into multi-year enterprise agreements. Thermo Fisher Scientific leverages its reagent-instrument bundling to lock in high-throughput clinical customers. Becton Dickinson and Company anchors its position in automated blood culture systems that feed downstream identification workflows. bioMérieux SA differentiates through integrated software that connects benchtop instruments to laboratory information systems.
Microbial identification encompasses the taxonomic classification and characterization of bacteria, fungi, and other microorganisms through phenotypic or genotypic analysis, typically requiring 16S rRNA gene sequencing, MALDI-TOF mass spectrometry protein profiling, or biochemical panel testing with turnaround times ranging from minutes to 48 hours. Its primary commercial purpose centers on clinical infectious disease diagnosis, pharmaceutical sterility assurance, and food safety compliance verification. Reagents and kits capture recurring revenue streams with replacement-driven purchase cycles, while mass spectrometry instruments command higher upfront capital but yield superior per-sample economics at volume. PCR-based methods sustain growth in point-of-care settings where portability outweighs breadth of species coverage.
FDA clearance pathways for in vitro diagnostic devices shape product development timelines and clinical claim substantiation requirements for US market entry, while EMA's In Vitro Diagnostic Regulation in Europe imposes stricter performance documentation and post-market surveillance obligations. ISO 15189 accreditation standards for medical laboratories drive demand for validated, traceable identification systems that demonstrate measurement uncertainty control. Stakeholders must monitor how WHO antimicrobial resistance surveillance initiatives redirect national procurement budgets toward rapid molecular platforms versus conventional culture-based workflows.
Market Dynamics
Regulatory pressure from FDA and EMA is compressing validation timelines for molecular diagnostic platforms while hospital consolidation drives enterprise-scale procurement decisions that favor integrated identification-to-reporting workflows over standalone instruments.
Growth Catalysts
- Antimicrobial resistance surveillance mandates:WHO initiatives redirect national health budgets toward rapid molecular platforms capable of same-day resistance profiling in clinical laboratories across the United States, Germany, and Japan.
- Hospital-acquired infection control programs:Expanded surveillance protocols in tertiary care centers generate sustained demand for high-throughput MALDI-TOF systems that interface directly with laboratory information systems.
- Point-of-care decentralization:Portable PCR-based devices enable pathogen identification at pharmacy clinics and urgent care networks where turnaround time outweighs taxonomic breadth requirements.
Market Restraints
- Capital intensity of mass spectrometry platforms:MALDI-TOF instruments require substantial upfront investment that limits adoption in mid-volume laboratories and resource-constrained settings.
- Reagent supply concentration:Proprietary consumable ecosystems lock customers into single-vendor dependencies with limited price transparency or substitution options.
- Technical limitation in fungal identification:Protein spectral databases for yeasts and molds remain less comprehensive than bacterial libraries, creating diagnostic gaps in immunocompromised patient populations.
Strategic Opportunities
- Underpenetrated veterinary diagnostics:Livestock and companion animal health systems in Brazil and India represent expansion vectors for multiplex PCR panels targeting zoonotic pathogens.
- Food safety regulatory tailwinds:EU's expanded microbiological criteria regulation drives processor investment in rapid verification systems for ready-to-eat product lines.
- Technology convergence:Integration of artificial intelligence with MALDI-TOF spectral analysis accelerates species-level resolution for phenotypically ambiguous isolates.
Industry Challenges
- Specialized technician scarcity:Clinical laboratories face recruitment gaps for mass spectrometry operators and bioinformaticians capable of interpreting genomic identification outputs.
- Legacy system integration friction:Hospital information technology departments struggle to embed new identification instruments within entrenched laboratory information management architectures without custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microbial Identification Market |
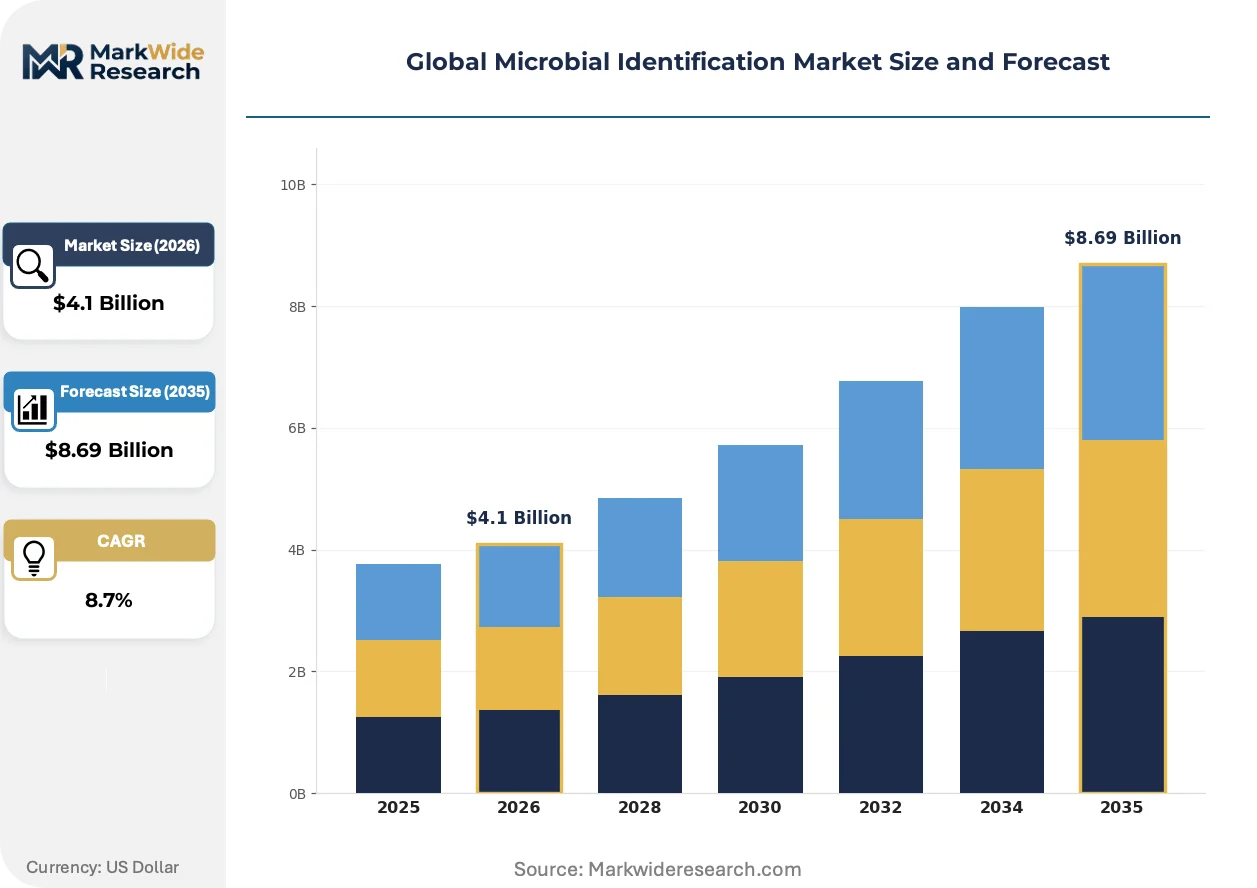
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $8.69 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Kits End User: Clinical Laboratories, Research Institutions, Food Industry, Pharmaceutical Firms Technology: Mass Spectrometry, PCR, NGS, ELISA Application: Infectious Disease Diagnosis, Food Safety Testing, Environmental Monitoring, Quality Control |
| Companies Covered | Thermo Fisher Scientific, Becton Dickinson and Company, bioMérieux SA, Shimadzu Corporation, Bruker Corporation, Danaher Corporation, Merck KGaA, Qiagen N.V., Charles River Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microbial Identification Market Emerging Trajectories
Cloud-based spectral libraries and artificial intelligence classification algorithms are compressing the expertise barrier for microbial identification while regulatory frameworks on both sides of the Atlantic tighten performance documentation requirements.
MALDI-TOF mass spectrometry is virtualizing the expertise embedded in traditional microbiology workflows. Community hospitals and smaller diagnostic networks now access reference-grade identification capabilities without maintaining on-site taxonomic specialists. This technology is virtualizing the knowledge concentration that previously limited accurate pathogen identification to academic medical centers and public health laboratories.
EMA's In Vitro Diagnostic Regulation imposes stricter post-market surveillance and clinical evidence standards than its predecessor directive. Manufacturers must now maintain updated performance documentation across expanded microorganism claims. European clinical laboratories are responding by consolidating procurement around vendors with established notified body relationships and comprehensive quality management systems.
Service unbundling is fragmenting traditional instrument-reagent bundling arrangements. Hospital procurement departments now negotiate reagent supply separately from capital equipment leases, pressuring vendors to demonstrate standalone consumable value. This behavioral shift is most visible in United States health systems where group purchasing organizations have centralized diagnostic supply contracts.
Global Microbial Identification Market Segmentation
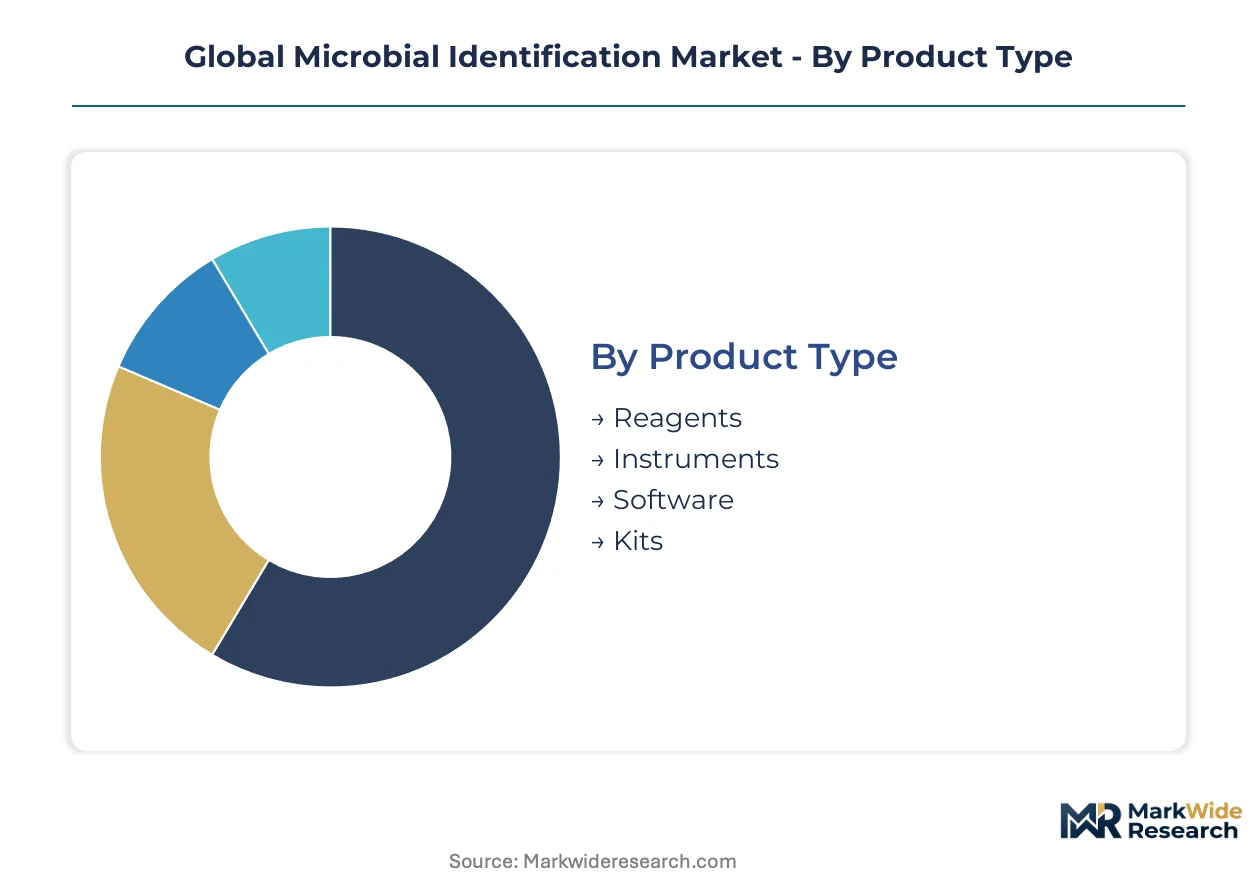
Segmentation in microbial identification reflects divergent purchase cycles and margin structures across consumables, capital equipment, and informatics. Reagent and kit replenishment generates recurring revenue streams with 30-90 day reorder cycles, while mass spectrometry instruments lock customers into multi-year depreciation schedules and service contracts.
Product Type:
Cycle times vary sharply: reagents and kits turn over in weeks, instruments amortize over 5-7 years, and software renews annually with version upgrades.
- Reagents:Stabilized biochemical substrates and selective media formulations constitute the highest-frequency purchase category. Clinical laboratories in the United States and Germany consume these in continuous workflows for blood culture confirmation and susceptibility testing, with procurement centralized through group purchasing organizations that negotiate multi-year supply agreements.
- Instruments:Capital equipment spans MALDI-TOF mass spectrometry platforms, automated blood culture systems, and PCR thermocyclers. Hospital consolidation in Japan and the United States drives enterprise-scale procurement decisions that favor vendors offering integrated identification-to-reporting workflows over standalone hardware.
- Software:Laboratory information system middleware and spectral analysis algorithms enable data interpretation and regulatory compliance documentation. Demand concentrates in European markets where EMA's In Vitro Diagnostic Regulation mandates enhanced traceability and post-market surveillance capabilities.
- Kits:Pre-configured consumable bundles combine reagents, controls, and disposables for specific pathogen panels. Food safety laboratories in the United States and Germany favor these for standardized compliance testing against ISO 17025 accreditation requirements.
Reagents anchor the volume base while software gains share at the steepest rate as laboratories prioritize interoperability and AI-enhanced classification capabilities.
End User:
Customer sophistication and budget authority create tiered demand patterns, from high-throughput hospital networks to decentralized point-of-care settings.
- Clinical Laboratories:Hospital-based microbiology departments and reference laboratories process thousands of isolates monthly. These facilities in the United States, Germany, and Japan drive adoption of MALDI-TOF platforms capable of same-day identification, with procurement influenced by antimicrobial resistance surveillance mandates from WHO and national health agencies.
- Research Institutions:Academic medical centers and public health laboratories develop novel taxonomic databases and validate emerging technologies. Funding from the NIH and European Research Council supports method development for phenotypically ambiguous organisms.
- Food Industry:Processors and contract testing laboratories verify microbiological criteria for ready-to-eat products. EU regulatory expansion drives investment in rapid verification systems among German and French food manufacturers.
- Pharmaceutical Firms:Sterility assurance and environmental monitoring teams in manufacturing facilities deploy validated identification systems. FDA compliance requirements for aseptic processing create demand for traceable, measurement-uncertainty-controlled workflows in United States-based production sites.
Clinical laboratories dominate absolute spend while food industry adoption climbs fastest as regulatory verification timelines compress.
Technology:
Performance characteristics and capital requirements stratify adoption across centralized reference facilities and distributed testing networks.
- Mass Spectrometry:MALDI-TOF protein profiling delivers species-level identification in minutes with minimal sample preparation. High-throughput clinical laboratories in the United States and Japan deploy these platforms for routine bacterial identification, though fungal spectral database limitations create diagnostic gaps for immunocompromised patient populations.
- PCR:Amplification-based methods target specific genetic signatures with high analytical sensitivity. Point-of-care networks in urgent care and pharmacy clinics favor portable PCR devices where turnaround time outweighs taxonomic breadth requirements.
- NGS:Next-generation sequencing enables strain-level resolution and resistance gene detection. Research institutions and public health laboratories leverage these capabilities for outbreak investigation and genomic epidemiology.
- ELISA:Enzyme-linked immunosorbent assays provide cost-effective screening for specific antigens. Food safety and environmental monitoring applications in Germany and the United States retain these methods for high-volume, targeted detection workflows.
Mass spectrometry commands the installed base while PCR expands most quickly into decentralized care delivery models.
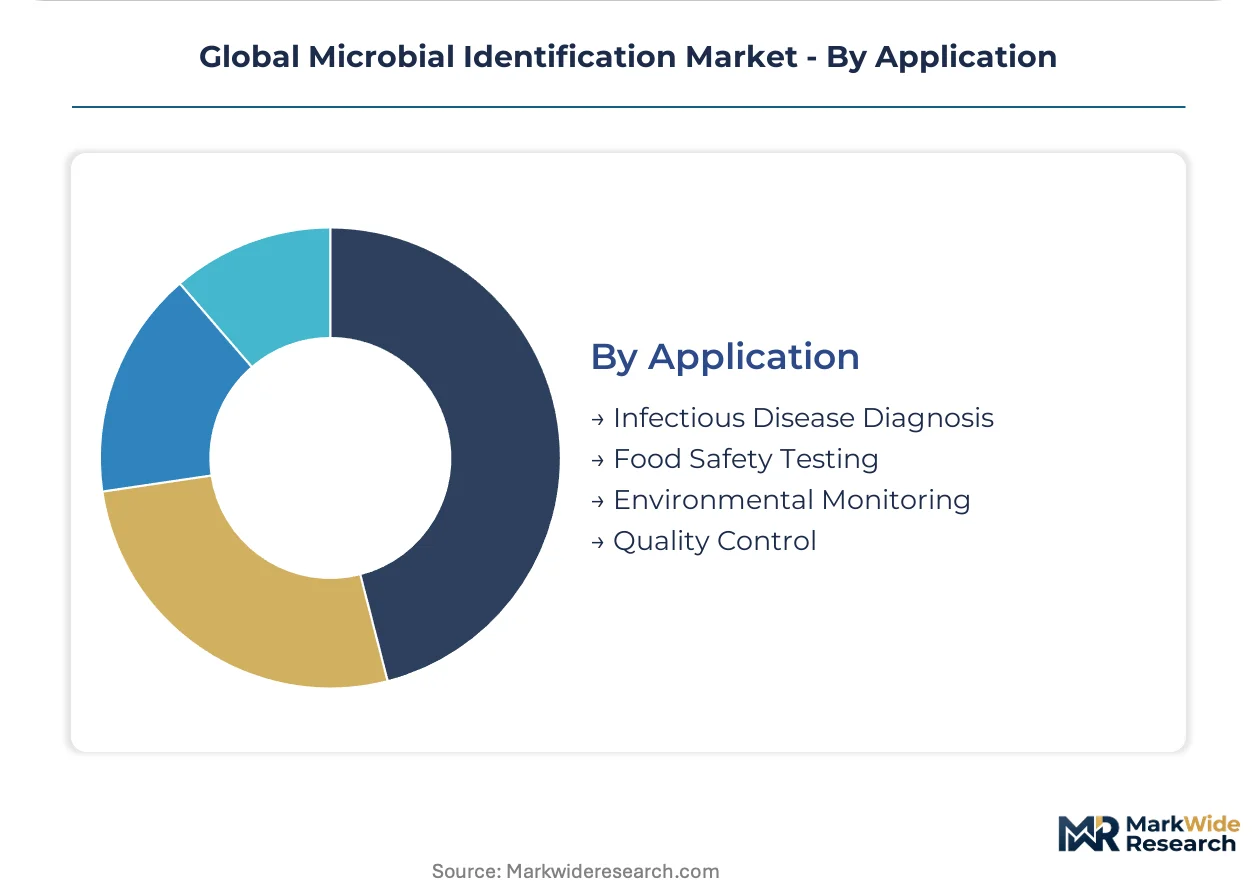
Application:
Regulatory urgency and reimbursement structures determine which use cases justify premium technology investments versus commoditized workflows.
- Infectious Disease Diagnosis:Bloodstream, respiratory, and urinary tract pathogen identification drives the majority of clinical demand. United States hospital-acquired infection surveillance programs and Japanese antimicrobial stewardship initiatives accelerate replacement of conventional culture methods with rapid molecular platforms.
- Food Safety Testing:Pathogen verification in ready-to-eat and raw agricultural products requires validated, accredited methods. EU microbiological criteria regulation expansion compels processor investment in rapid confirmation systems.
- Environmental Monitoring:Pharmaceutical cleanroom and water system surveillance maintains sterility assurance. FDA inspection emphasis on data integrity drives adoption of automated, LIS-integrated monitoring in United States manufacturing facilities.
- Quality Control:Raw material and in-process testing supports batch release decisions. Contract manufacturing organizations in Germany and Japan prioritize harmonized methods across multi-site production networks.
Infectious disease diagnosis generates the revenue foundation while environmental monitoring demonstrates the steepest expansion trajectory as pharmaceutical manufacturing quality standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance pathways anchor demand concentration in the United States, where hospital-acquired infection surveillance programs and antimicrobial stewardship mandates drive platform upgrades. Germany and Japan follow with EMA and PMDA frameworks tightening diagnostic accuracy requirements.
United States
Hospital consolidation and enterprise procurement favor integrated identification-to-reporting workflows over standalone instruments. FDA's in vitro diagnostic device regulations compress validation timelines for molecular platforms. The Boston-Cambridge biotech corridor and Research Triangle Park host reference laboratories deploying MALDI-TOF systems for rapid pathogen detection.
Germany
EMA's In Vitro Diagnostic Regulation imposes stricter post-market surveillance and clinical evidence standards than its predecessor directive. ISO 15189 accreditation requirements drive demand for validated, traceable identification systems. The Rhine-Main region around Frankfurt concentrates pharmaceutical manufacturing facilities investing in environmental monitoring capabilities.
Japan
METI and PMDA coordinate national antimicrobial resistance surveillance initiatives that redirect procurement budgets toward rapid molecular platforms. Hospital-acquired infection control programs in tertiary care centers sustain demand for high-throughput systems. The Kanto region surrounding Tokyo anchors clinical laboratory network expansion.
China
NMPA regulatory evolution and national health security priorities accelerate domestic platform development for infectious disease diagnostics. The country's national pharmaceutical regulator tightens sterility assurance requirements for biologics manufacturing. The Yangtze River Delta biotech cluster around Shanghai drives adoption of automated identification systems in contract research organizations.
India
CDSCO framework development and expanding hospital laboratory networks create procurement opportunities for mid-volume identification platforms. The country's national pharmaceutical regulator strengthens post-market surveillance for imported diagnostic devices. The Hyderabad-Genome Valley corridor and Bangalore biotech cluster concentrate contract manufacturing organizations requiring validated microbial testing workflows.
Global Microbial Identification Market Vendor Landscape
Integrated conglomerates and specialized diagnostic firms split the market through divergent bundling strategies. Thermo Fisher Scientific leverages reagent-instrument bundling to lock in high-throughput clinical customers. Becton Dickinson anchors automated blood culture systems that feed downstream identification workflows. bioMérieux differentiates through integrated software connecting benchtop instruments to laboratory information systems. Competitive moves concentrate on multi-year enterprise service contracts and AI-enhanced spectral classification capabilities.
Among diversified life sciences conglomerates, Thermo Fisher Scientific and Danaher Corporation occupy positions spanning reagents, instruments, and informatics. Bruker Corporation and Shimadzu Corporation represent mass spectrometry specialists with established MALDI-TOF platforms. bioMérieux SA exemplifies the integrated diagnostic pure-play archetype. Merck KGaA and Qiagen N.V. sit within the reagent and molecular biology tools segment. Becton Dickinson and Company anchors automated microbiology workflows. Charles River Laboratories represents the contract research and testing services vector.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Becton Dickinson and Company |
| bioMérieux SA |
| Shimadzu Corporation |
| Bruker Corporation |
| Danaher Corporation |
| Merck KGaA |
| Qiagen N.V. |
| Charles River Laboratories |
| Others |
Supply Flow & Price Mechanics
The Boston-Cambridge biotech corridor anchors global reagent manufacturing capacity, where Thermo Fisher Scientific and Danaher Corporation concentrate high-purity biochemical substrate production. This geographic concentration grants incumbent vendors pricing power over mid-volume clinical laboratories that lack alternative qualified suppliers for FDA-validated identification workflows.
Pricing Analysis
Price spreads between United States and European clinical laboratories reflect EMA's In Vitro Diagnostic Regulation compliance premiums. The market operates through three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by ISO 15189 certification tier and after-sales service bundling. Pricing pressure stems from group purchasing organization consolidation that extracts volume discounts from instrument-reagent bundles. Mid-volume hospital laboratories exhibit highest price sensitivity, while pharmaceutical sterility assurance teams prioritize traceability over unit cost.
Supply Chain Analysis
United States export controls on mass spectrometry components limit MALDI-TOF platform flows to Chinese and Indian diagnostic manufacturers. Supply concentrates in the United States, Germany, and Japan for precision optical components, ionization sources, and vacuum systems. The ecosystem draws from rare earth element processors in China, specialized germanium substrate foundries in Germany, and precision machining clusters in Japan. Single-source vulnerability for MALDI-TOF laser diodes creates procurement risk. Distribution runs through direct enterprise contracts with hospital systems and group purchasing organization intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as laboratory information system interoperability becomes the primary switching cost. Vendors that embed identification instruments within enterprise data architectures capture disproportionate lifetime value.
For Market Incumbents: Pre-empt modular reagent supply unbundling by negotiating standalone consumable value demonstrations before procurement departments force separation. Lock in multi-year enterprise service contracts that bundle spectral database updates with instrument maintenance. Defend against portable PCR disruptors by accelerating AI-enhanced MALDI-TOF classification speed to match point-of-care turnaround times. For New Entrants and Emerging Players: Mid-volume veterinary diagnostics in Brazil and India represent the most penetrable entry point, where regulatory barriers fall below human clinical thresholds and local manufacturing partnerships circumvent import duty structures. Food safety contract laboratories in Germany seeking ISO 17025 accreditation support offer second-tier opportunity. Pursue white-label instrument partnerships with established reagent vendors to bypass capital-intensive direct sales infrastructure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors AI-enabled spectral analysis software specialists over hardware manufacturers facing depreciation-driven replacement compression. Long-term viability rests on recurring revenue attachment rates rather than instrument shipment volumes. Monitor FDA breakthrough device designation velocity for rapid molecular platforms as inflection signal indicating regulatory preference shifts that would revalue incumbent MALDI-TOF installed bases.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enhanced Spectral Classification Development | Accelerates species resolution for phenotypically ambiguous isolates in clinical workflows. |
| Laboratory Information System Middleware Integration | Creates switching costs that embed identification platforms within hospital data architectures. |
| Veterinary Diagnostics Geographic Expansion | Captures zoonotic pathogen surveillance budgets in Brazil and India livestock sectors. |
| Reagent Supply Contract Unbundling | Addresses procurement department pressure for standalone consumable price transparency. |
| Cloud-Based Spectral Library Virtualization | Democratizes reference-grade identification capabilities for community hospital networks. |
Methodological Framework
Desk research of FDA 510(k) clearances, EMA notified body opinions, and hospital procurement databases preceded structured interviews with clinical laboratory directors, biomedical engineers, and group purchasing organization contracts managers. Primary fieldwork with microbiology department heads and diagnostic instrument service technicians validated instrument utilization patterns and replacement cycle timing. Secondary sources included ISO 15189 accreditation registries, WHO antimicrobial resistance surveillance reports, and SEC 10-K filings from publicly traded diagnostic conglomerates. Bottom-up installed base modeling triangulated against top-down health expenditure allocation estimates.
Assumptions held regulatory framework stability and antimicrobial resistance surveillance funding continuity fixed, while antimicrobial stewardship initiative intensity and hospital consolidation velocity varied across sensitivity scenarios. Segmentation modeling incorporated technology platform, end-user facility type, application purpose, and geographic regulatory cluster dimensions. CAGRs derived from logistic diffusion curves fitted to MALDI-TOF platform penetration rates and PCR point-of-care deployment trajectories. Forecast inputs included antimicrobial resistance gene prevalence surveillance data and pharmaceutical manufacturing facility expansion pipelines.
Practitioners should monitor FDA breakthrough device designation grants and EMA notified body capacity constraints for early signals of regulatory pathway disruption. Forecasts reflect assumptions of continued ISO 15189 accreditation expansion and sustained WHO antimicrobial resistance surveillance budget prioritization. Material shifts in United States hospital reimbursement structures or European diagnostic device procurement centralization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Bacterial Antigens Market
Industrial Microbiology
Microbiology Testing Market
Industrial Microbiology
Cultured Dextrose Market
Industrial Microbiology
Mineral Yeast Market
Industrial Microbiology
North America Microbial Protein Market
Industrial Microbiology
Global Escherichia Coli Testing Market
Industrial Microbiology
Microbial Protein Used in Feed Market
Industrial Microbiology
Global Starter Culture Market
Industrial Microbiology
Real Time Continuous Microbiological Monitoring Systems Market
Industrial Microbiology
Middle East Feed Probiotics Market
Industrial Microbiology
Lipase Market
Industrial Microbiology
Microbial Seed Treatment Market
Industrial Microbiology
Specialty Cultures Market
Industrial Microbiology
Microbial Biosurfactants Market
Industrial Microbiology
Microbial Lipase Market
Industrial Microbiology
Microbiome Sample Preparation Technology Market