
 Cultured Dextrose Market | 2026-2036
Cultured Dextrose Market Size, Share, and Industry Trends Forecast 2026-2036
Cultured Dextrose Market Analysis
Multi-source procurement of fermentation-derived ingredients is expanding as food manufacturers reduce reliance on single geographic supply zones. Corbion N.V. leverages its Dutch biotech fermentation infrastructure to serve European clean-label demand. DSM-Firmenich anchors global supply through its precision fermentation platforms. Cargill competes via backward integration into corn dextrose feedstock and captive bioprocessing capacity.
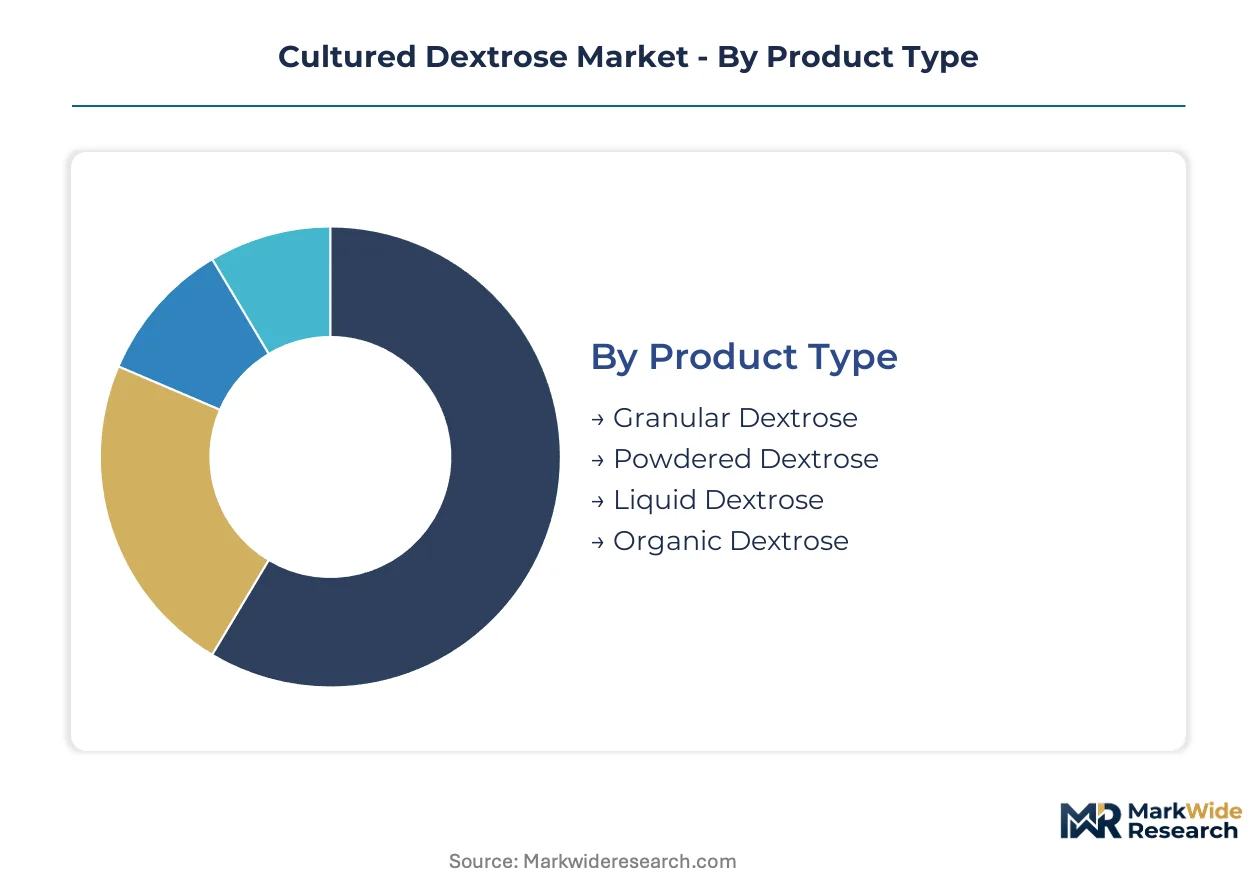
Cultured dextrose is a fermentation-derived carbohydrate produced by culturing dextrose with specific bacterial strains, yielding a functional ingredient with antimicrobial properties effective at pH ranges typical of refrigerated and ambient foods. Its primary commercial purpose is shelf-life extension in clean-label applications where synthetic preservatives face consumer rejection. Powdered dextrose dominates current volume due to handling efficiency and stability in bakery and dry-mix applications. Liquid dextrose is gaining fastest in beverage and sauce formulations where dissolution speed matters. Organic dextrose occupies a premium tier constrained by certified organic feedstock availability and smaller batch fermentation economics.
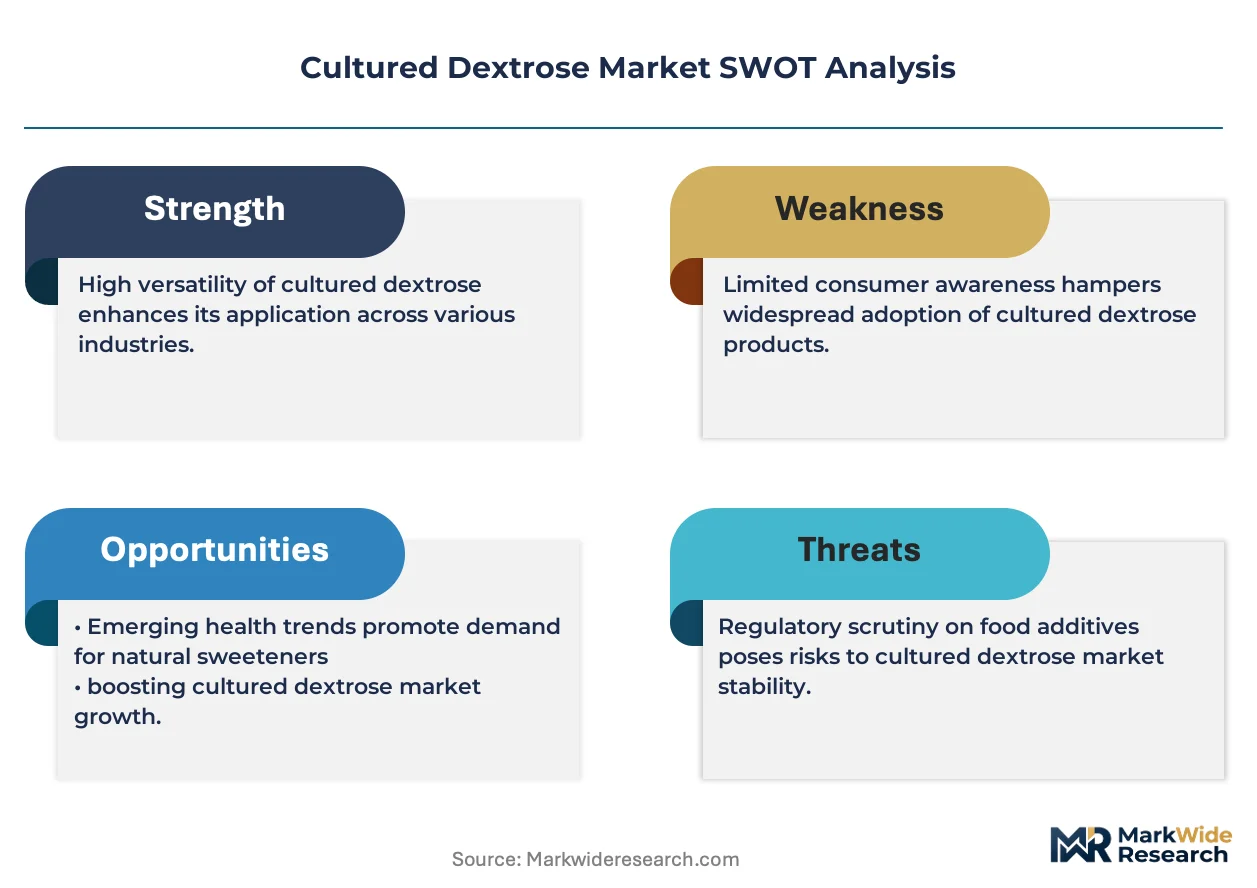
The FDA's GRAS self-affirmation pathway shapes U.S. market access timelines, while EFSA's novel food assessments govern European entry for newer fermentation strains. BIS standards in India and China's SAMR registration requirements add compliance layers for exporters targeting Asia-Pacific expansion. Stakeholders must monitor evolving strain-specific regulatory classifications that could redraw competitive boundaries between established and emerging suppliers.
Market Dynamics
Clean-label reformulation mandates from major retailers are compressing synthetic preservative demand while pulling fermentation-derived alternatives into mainstream food manufacturing. This structural shift reconfigures supplier relationships around strain-specific capabilities and regulatory documentation depth.
Growth Catalysts
- FDA GRAS Pathway:The self-affirmation mechanism accelerates cultured dextrose entry into U.S. refrigerated sauces and ready-to-eat meals without lengthy pre-market approvals.
- EU Clean-Label Regulations:EFSA guidance on novel food classifications is pushing manufacturers toward fermentation-derived shelf-life extenders in ambient bakery and dairy alternatives.
- Retail Private-Label Expansion:European and North American supermarket chains are mandating preservative-free formulations in their store-brand portfolios, concentrating procurement among qualified biotech suppliers.
Market Restraints
- Feedstock Volatility:Corn dextrose prices fluctuate with agricultural commodity cycles, compressing margins for fermentation operators without captive starch processing.
- Strain Patent Concentration:Intellectual property around high-yield bacterial cultures concentrates among three legacy biotechnology holdings, limiting new entrant access.
- Technical pH Limitations:Cultured dextrose antimicrobial efficacy drops substantially below pH 4.5, excluding its use from high-acid beverage categories where benzoates dominate.
Strategic Opportunities
- Indian FSSAI Alignment:India's food safety regulator is harmonizing with Codex standards on fermentation-derived additives, opening formulation partnerships for domestic dairy and snack manufacturers.
- Precision Fermentation Convergence:Integration of AI-driven strain optimization with continuous bioprocessing is collapsing batch-to-batch variability and unit economics.
- Direct-to-Manufacturer Platforms:Biotech suppliers are bypassing traditional ingredient distributors to offer technical formulation support through proprietary digital portals.
Industry Challenges
- Strain Qualification Timelines:EFSA novel food dossiers require 18-24 month toxicology and stability documentation, delaying European revenue recognition.
- Legacy System Integration:Food manufacturers' ERP platforms lack traceability modules for fermentation-derived inputs, forcing custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cultured Dextrose Market |
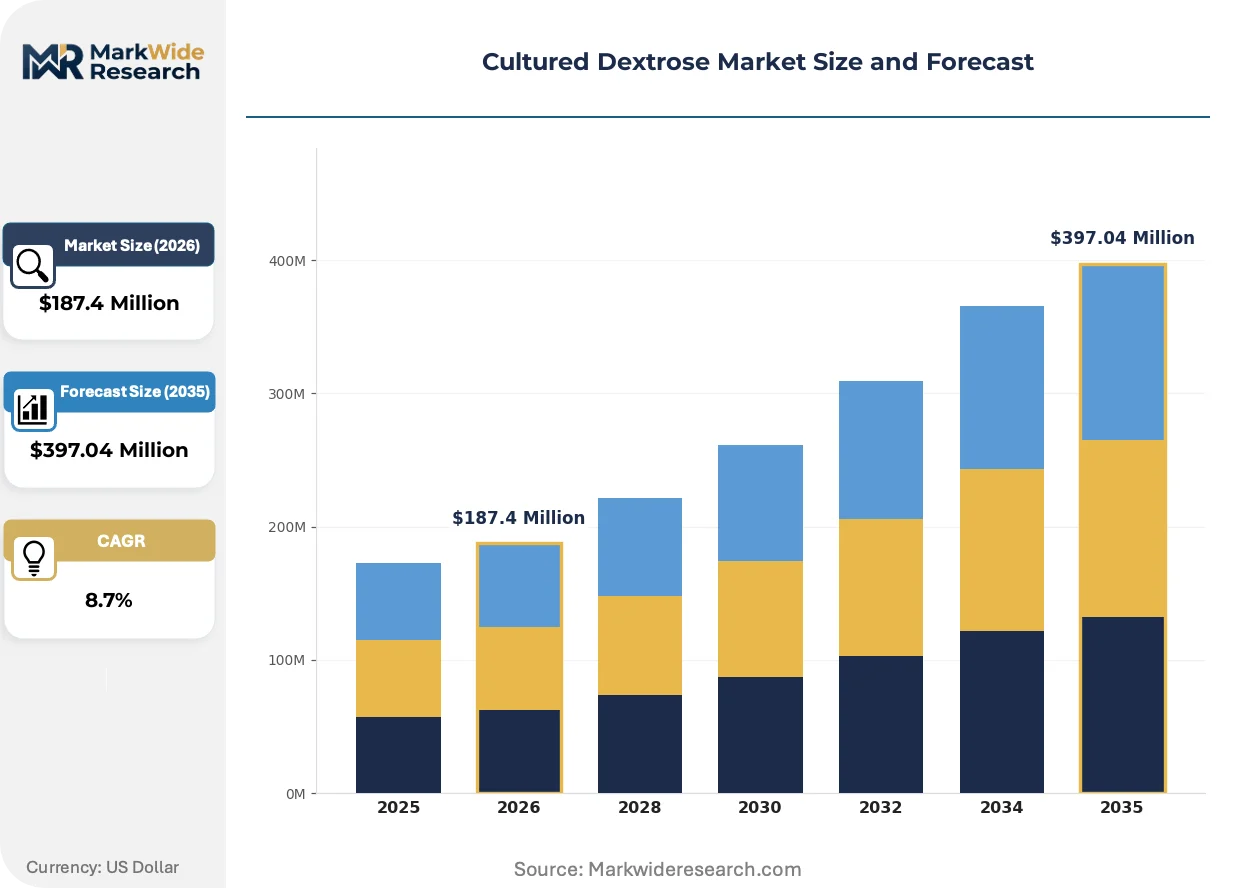
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular Dextrose, Powdered Dextrose, Liquid Dextrose, Organic Dextrose End Use Industry: Food & Beverage, Pharmaceuticals, Personal Care, Animal Feed Packaging Type: Bulk Bags, Sachets, Totes, Drums Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Tate & Lyle PLC, DuPont IFF, DSM-Firmenich, Cargill, Kemin Industries, Corbion N.V., Archer Daniels Midland Company, Tereos Group, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cultured Dextrose Market Emerging Trajectories
Bioprocess intensification and regulatory documentation automation are compressing development cycles for cultured dextrose applications. These forces are redrawing competitive boundaries between commodity carbohydrate suppliers and specialized fermentation houses.
Continuous fermentation technology is absorbing capital investment from batch reactor infrastructure. Mid-sized North American sauce manufacturers are adopting skid-mounted continuous systems to reduce cleaning validation downtime. This shift is absorbing technical talent from pharmaceutical bioprocessing and compressing the cost gap between synthetic and fermentation-derived preservatives.
REACH registration requirements for fermentation byproducts are tightening documentation obligations for European suppliers. The regulation now demands full metabolite profiling for strains not on the 2008 inventory. German and Dutch bakery ingredient formulators are responding by consolidating procurement around suppliers with pre-validated strain libraries.
Buyer concentration among multinational CPGs is consolidating technical service expectations. Large manufacturers now require on-site fermentation scientists from ingredient vendors, displacing traditional distributor technical support. This pattern is most visible in U.S. Midwest dairy processing corridors where plant-level reformulation teams negotiate directly with biotech R&D departments.
Cultured Dextrose Market Segmentation
Cultured dextrose suppliers must navigate divergent certification requirements across product formats and end-use verticals. FDA GRAS documentation dominates U.S. food applications, while pharmaceutical-grade production demands compliance with USP-NF monographs and EU GMP standards.
Product Type:
Certification burden varies sharply: organic dextrose requires dual USDA-NOP and EU organic certification, liquid forms face stringent microbial limits under FDA 21 CFR, while conventional powdered grades operate under self-affirmed GRAS.
- Powdered Dextrose:Spray-dried fermentation product with low water activity and extended ambient stability. Demand concentrates in U.S. Midwest bakery clusters where clean-label reformulation of refrigerated doughs accelerates procurement from qualified biotech suppliers.
- Liquid Dextrose:Unfiltered fermentation broth standardized to specific solids content and antimicrobial activity. Beverage manufacturers in Germany and the Netherlands adopt this format for dissolution speed in sauce and dressing applications, though cold-chain logistics constrain distribution radius.
- Granular Dextrose:Crystalline form produced through controlled evaporation and seeding protocols. Animal feed compounders in Iowa and Illinois specify this grade for pelleted ration applications.
- Organic Dextrose:Fermented from certified organic corn feedstock under batch-processed conditions with full chain-of-custody documentation. Premium pricing reflects limited organic starch supply and smaller fermentation scale economics.
Leading the category by volume: Powdered Dextrose. Growing fastest: Liquid Dextrose.
End Use Industry:
Customer concentration and margin structure diverge: food and beverage buyers negotiate multi-year supply agreements, while pharmaceutical procurement operates through qualified vendor lists with audit-intensive onboarding.
- Food & Beverage:Clean-label shelf-life extension in refrigerated sauces, ready-to-eat meals, and ambient bakery products. Major CPG reformulation programs in the United States and Germany absorb the majority of fermentation capacity expansion.
- Pharmaceuticals:Excipient applications in oral solid dosage forms and parenteral solutions where USP-NF compliance and endotoxin testing are mandatory. Regulatory filing support from suppliers determines vendor selection.
- Personal Care:Natural preservative systems in water-based cosmetics and personal hygiene formulations. Formulators prioritize low-irritation profiles over antimicrobial potency.
- Animal Feed:Mold inhibition in high-moisture feed ingredients and silage inoculants. Price sensitivity limits adoption to premium livestock segments.
Dominant by procurement volume: Food & Beverage. Expanding most quickly: Pharmaceuticals.
Packaging Type:
Handling infrastructure at customer facilities dictates format selection: automated bulk systems favor super sacks, while batch-scale manufacturers require drums with integrated dispensing ports.
- Bulk Bags:One-ton flexible intermediate bulk containers with liner systems for moisture protection. Large sauce manufacturers in Wisconsin and Minnesota deploy pneumatic conveying systems for automated ingredient addition.
- Drums:Fiber or steel drums with tamper-evident closures for pharmaceutical and personal care applications. Lot traceability and COA documentation accompany each unit.
- Totes:Intermediate liquid bulk containers ranging from 275 to 330 gallons. Regional beverage co-packers in California and Texas specify totes for just-in-time fermentation ingredient delivery.
- Sachets:Pre-measured single-use packets for artisan bakery and small-batch food service operations. Convenience positioning commands 40-60% price premium over bulk formats.
Highest shipment volume: Bulk Bags. Steepest expansion trajectory: Totes.
Distribution Channel:
Channel selection reflects customer scale and technical service requirements: multinational CPGs demand direct R&D partnership, while regional processors rely on distributor inventory buffers.
- Direct Sales:Long-term supply contracts with dedicated technical account managers and on-site fermentation scientists. Top ten North American food manufacturers account for concentrated procurement through this channel.
- Distributors:Regional ingredient distributors with local inventory and formulation support capabilities. Mid-sized sauce and dressing manufacturers in the U.S. Southeast and Pacific Northwest depend on this channel for just-in-time delivery.
- Wholesale:Aggregated purchasing cooperatives serving independent bakeries and small food service operators. Limited technical support and standardized specifications define this tier.
- Online Retail:E-commerce platforms targeting artisan food producers and research-scale pharmaceutical developers. Minimum order quantities and shipping constraints restrict commercial significance.
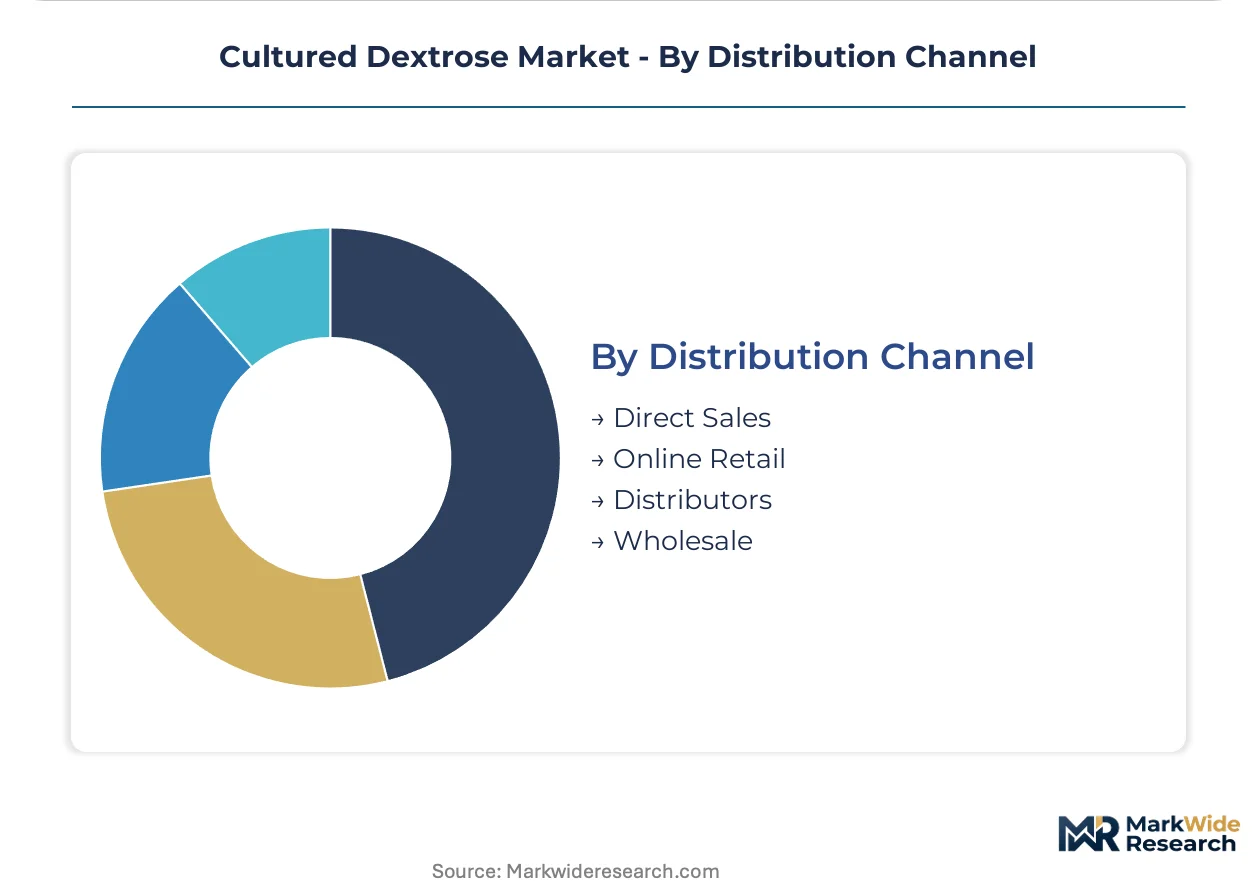
Capturing largest revenue share: Direct Sales. Gaining share fastest: Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corn belt concentration in Iowa and Illinois anchors North American feedstock supply for fermentation-derived ingredients. European biotech infrastructure in the Netherlands and Germany processes refined dextrose into clean-label preservatives. Asian regulatory harmonization is opening formulation partnerships in India and China.
United States
Major CPG reformulation programs in refrigerated sauces and ready-to-eat meals absorb the majority of fermentation capacity expansion. FDA's GRAS self-affirmation pathway accelerates cultured dextrose entry without lengthy pre-market approvals. Wisconsin and Minnesota sauce manufacturers deploy pneumatic conveying systems for automated ingredient addition.
Germany
Beverage manufacturers adopt liquid dextrose formats for dissolution speed in sauce and dressing applications. REACH registration requirements for fermentation byproducts demand full metabolite profiling for strains not on the 2008 inventory. Bakery ingredient formulators in the Rhine-Ruhr corridor consolidate procurement around suppliers with pre-validated strain libraries.
Netherlands
Precision fermentation platforms serve European clean-label demand through Dutch biotech infrastructure. EFSA novel food assessments govern entry for newer fermentation strains, requiring 18-24 month toxicology documentation. Rotterdam-area logistics hubs enable cold-chain distribution of liquid dextrose to regional beverage co-packers.
India
Domestic dairy and snack manufacturers seek formulation partnerships as FSSAI harmonizes with Codex standards on fermentation-derived additives. BIS standards add compliance layers for exporters targeting Asia-Pacific expansion. Maharashtra-based food processors pilot cultured dextrose in clean-label reformulation of traditional sweets.
China
SAMR registration requirements structure market entry for foreign fermentation-derived ingredient suppliers. Dual carbon goals incentivize bioprocessing investments over petrochemical preservative production. Yangtze River Delta food manufacturers evaluate cultured dextrose for shelf-stable sauce applications.
Cultured Dextrose Market Vendor Landscape
Capacity expansion dominates the current landscape as fermentation operators scale bioprocessing infrastructure to meet clean-label procurement surges. The vendor base concentrates around three legacy biotechnology holdings with high-yield bacterial culture patents, creating tiered supply relationships with multinational CPGs. Strategic archetypes include corn processors with backward integration into captive dextrose feedstock, specialized fermentation houses with strain-specific capabilities, and diversified ingredient conglomerates with precision fermentation platforms. M&A activity and technology licensing agreements represent the dominant competitive moves reshaping supplier relationships.
Among Dutch and Swiss biotechnology specialists, DSM-Firmenich and Corbion N.V. exemplify the precision fermentation archetype, occupying positions defined by regulatory documentation depth and strain optimization capabilities. Cargill represents the integrated agribusiness model with upstream control over corn dextrose feedstock and in-house bioprocessing capacity. These three anchors illustrate how competitive positioning depends on the intersection of feedstock security, fermentation expertise, and technical service infrastructure for on-site customer support.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| DuPont IFF |
| DSM-Firmenich |
| Cargill |
| Kemin Industries |
| Corbion N.V. |
| Archer Daniels Midland Company |
| Tereos Group |
| Kerry Group |
| Others |
Supply Flow & Price Mechanics
Multinational CPG procurement teams concentrate purchasing power through multi-year supply agreements, anchoring the market in contract-based long-term offtake pricing that bundles technical service and regulatory documentation. This buyer concentration enables fermentation houses to capture premium returns on certified organic and pharmaceutical-grade tiers while compressing margins on commodity powdered grades.
Pricing Analysis
Technical service bundling separates full-service suppliers from unbundled commodity vendors, with on-site fermentation scientists and strain qualification support commanding 15-25% price premiums over documentation-only supply. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with organic dextrose and USP-NF pharmaceutical grades occupying the premium tier. Cost compression in standard powdered grades is intensifying because corn feedstock volatility transfers directly to fermentation operators without captive starch processing. Mid-sized sauce manufacturers in the U.S. Southeast exhibit highest price sensitivity, while pharmaceutical formulators prioritize regulatory filing support over unit cost.
Supply Chain Analysis
Domestic-content mandates in India and China are reshaping sourcing patterns for fermentation-derived ingredients, pressuring foreign suppliers to establish local bioprocessing partnerships or license strains to domestic manufacturers. Feedstock supply concentrates in the United States, Brazil, and Ukraine for corn dextrose, while precision fermentation capacity clusters in the Netherlands, Germany, and Switzerland. Production draws from agricultural commodity cycles, refined dextrose processing, and bacterial strain propagation stages. Single-source vulnerability around high-yield bacterial culture patents held by legacy biotechnology holdings creates supply risk for new entrants. Distribution runs through direct sales channels for multinational CPGs and regional distributors for mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Strain patent concentration and EFSA novel food qualification timelines are forcing capital-constrained fermentation operators toward acquisition or exit, consolidating viable supply relationships around three legacy biotechnology holdings with regulatory documentation depth.
For Market Incumbents: Lock in exclusive strain licensing agreements with emerging precision fermentation platforms before patent cliffs erode differentiation. Expand captive corn processing capacity in Iowa and Illinois to insulate margins from agricultural commodity volatility. DSM-Firmenich and Corbion N.V. already demonstrate this defensive posture through Dutch biotech infrastructure control. For New Entrants and Emerging Players: The gap between premium organic dextrose and economy conventional grades offers entry space for mid-tier suppliers with FSSAI-aligned documentation for Indian dairy and snack manufacturers. Target Maharashtra-based food processors piloting clean-label reformulation of traditional sweets. Pursue joint development agreements with regional beverage co-packers in California and Texas seeking just-in-time fermentation ingredient delivery. For Investors and Strategic Acquirers: The window for entry favors fermentation houses with pre-validated strain libraries and REACH-compliant metabolite profiling. Acquire targets with EFSA novel food dossiers already in submission to compress European revenue recognition timelines. Watch for FSSAI-Codex harmonization completion as the inflection signal for Indian market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Processing | Cargill's captive starch supply secures feedstock cost advantage against fermentation-only competitors. |
| Precision Fermentation Platform Investment | DSM-Firmenich's AI-driven strain optimization collapses batch-to-batch variability for pharmaceutical-grade output. |
| EFSA Novel Food Dossier Submission | Corbion N.V.'s regulatory documentation depth accelerates European market access for new fermentation strains. |
| Direct-to-Manufacturer Digital Portal Launch | Biotech suppliers bypass traditional distributors to offer proprietary technical formulation support. |
| Indian FSSAI Partnership Development | Maharashtra-based processors gain clean-label reformulation capabilities for traditional dairy applications. |
Methodological Framework
Trade databases, FDA GRAS notification filings, and EFSA novel food registers formed the secondary backbone, supplemented by customs records from U.S. and EU agricultural commodity flows. Primary interviews with fermentation plant managers, CPG procurement leads, regulatory affairs directors at biotech suppliers, and category buyers at European supermarket chains validated strain-specific capabilities and documentation requirements. Bottom-up and top-down triangulation cross-referenced production capacity announcements with end-use demand absorption in refrigerated sauces and ready-to-eat meals.
Bottom-up modeling anchored volume projections in individual facility capacity expansions and customer reformulation program timelines, while top-down analysis tested aggregate demand against clean-label procurement mandates from major retailers. Segmentation dimensions included product format, certification tier, end-use vertical, and regional regulatory cluster. CAGRs were derived from weighted average of facility utilization trajectories and customer adoption curves. Industry-specific inputs incorporated corn price volatility indices and EFSA qualification timeline distributions.
Inputs from facility announcements and regulatory filings were available through the study window; gaps in private-label reformulation timelines introduce uncertainty bands around near-term demand acceleration. Forecasts reflect assumptions on strain qualification success rates and agricultural commodity cycle positioning. Corn belt weather patterns and REACH metabolite profiling requirement changes could revise supply-side capacity projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Microbial Biosurfactants Market
Industrial Microbiology
Mesophilic Bacteria Market
Industrial Microbiology
Microbiome Sample Preparation Technology Market
Industrial Microbiology
Eubiotics Market
Industrial Microbiology
Microbial-Derived Fiber Market
Industrial Microbiology
Lipase Market
Industrial Microbiology
Europe Microbial Based Biological Seed Treatment Market
Industrial Microbiology
Global Starter Culture Market
Industrial Microbiology
Automated Microbial Detection Systems Market
Industrial Microbiology
Global Microbial Identification Market
Industrial Microbiology
Bacillus Coagulans Market
Industrial Microbiology
Microbial Protein Used in Feed Market
Industrial Microbiology
Galactosidase Market
Industrial Microbiology
Microbiology Culture Market
Industrial Microbiology
Global Escherichia Coli Testing Market
Industrial Microbiology
Industrial Microbiology Market