
 Mineral Yeast Market | 2026-2036
Mineral Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Mineral Yeast Market Insights
Modular dosing formats for livestock and companion animal feeds is pivoting buyer procurement away from bulk commodity purchases. LALLEMAND leverages its strain development capabilities to dominate pharmaceutical-grade selenium yeast production. Angel Yeast anchors Asia-Pacific supply through integrated fermentation complexes. Kerry Group differentiates via customized premix solutions that blend mineral yeast with flavor masking systems.
Mineral yeast denotes Saccharomyces cerevisiae biomass cultivated in mineral-enriched media, typically achieving selenium concentrations of 2000–3000 ppm or chromium at 0.2–0.3% dry weight through intracellular bioaccumulation, then applied as bioavailable nutrient sources in human and animal nutrition. Yeast extract commands the largest value share due to its solubility advantages in liquid pharmaceutical formulations. Yeast flakes represent the fastest-expanding configuration as clean-label food manufacturers adopt visible fortification formats. Animal nutrition applications generate the deepest margin pools owing to volume scale in premix contracts and regulatory-driven substitution away from inorganic mineral salts.
FDA GRAS notifications and USDA organic certification govern human-food and feed-grade mineral yeast entry into the United States, while EU EFSA Novel Food evaluations and REACH substance registrations constrain strain introductions and labeling claims across European markets. Compliance with ISO 22000 and FSSC 22000 food safety management systems now functions as a baseline qualification for contract manufacturing relationships rather than a competitive differentiator. Stakeholders must monitor evolving EFSA guidance on maximum permitted levels of selenium in yeast supplements and assess whether in-house fermentation capacity or toll manufacturing delivers superior capital efficiency as volume requirements scale.
Market Dynamics
Feed-grade mineral yeast procurement pivots on modular dosing formats that displace bulk commodity purchasing, while pharmaceutical-grade strains face tightening purity mandates under EU REACH and F-Gas Regulation enforcement.
Growth Catalysts
- Antibiotic substitution mandates:Livestock producers across Germany and Denmark integrate selenium-enriched yeast into premix formulations as veterinary antibiotic restrictions tighten under EFSA guidelines.
- Clean-label food fortification:European food manufacturers adopt visible yeast flake formats for consumer-facing mineral enrichment, bypassing synthetic additive stigma.
- Continuous fermentation technology:Bioprocess engineering advances reduce batch-to-batch selenium variability, enabling pharmaceutical-grade consistency for nutraceutical applications.
Market Restraints
- Substrate cost volatility:Molasses and corn steep liquor prices fluctuate with agricultural commodity cycles, compressing fermentation margins for mineral yeast producers.
- Strain IP concentration:Proprietary Saccharomyces cerevisiae variants with superior selenium bioaccumulation remain controlled by a narrow base of European and North American germplasm holders.
- Inorganic mineral price competition:Sodium selenite and chromium chloride continue to undercut organic yeast-bound minerals on unit-cost basis in cost-sensitive feed applications.
Strategic Opportunities
- Companion animal premiumization:Pet food manufacturers in France and Italy seek yeast-bound mineral solutions for senior dog and cat formulations targeting joint and immune health.
- Regenerative agriculture incentives:USDA conservation programs and EU CAP eco-schemes reward livestock operations adopting bioavailable mineral sources that reduce environmental excretion.
- Precision fermentation convergence:Integration of CRISPR-edited yeast strains with real-time metabolite monitoring unlocks custom mineral profiles for targeted nutritional interventions.
Industry Challenges
- Fermentation scale-up expertise gap:Qualified bioprocess engineers capable of maintaining pharmaceutical-grade selenium consistency across 100,000+ liter tanks remain scarce in emerging production regions.
- Dual certification timelines:Simultaneous pursuit of FSSC 22000 and EU organic certification extends qualification cycles for new mineral yeast facilities by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mineral Yeast Market |
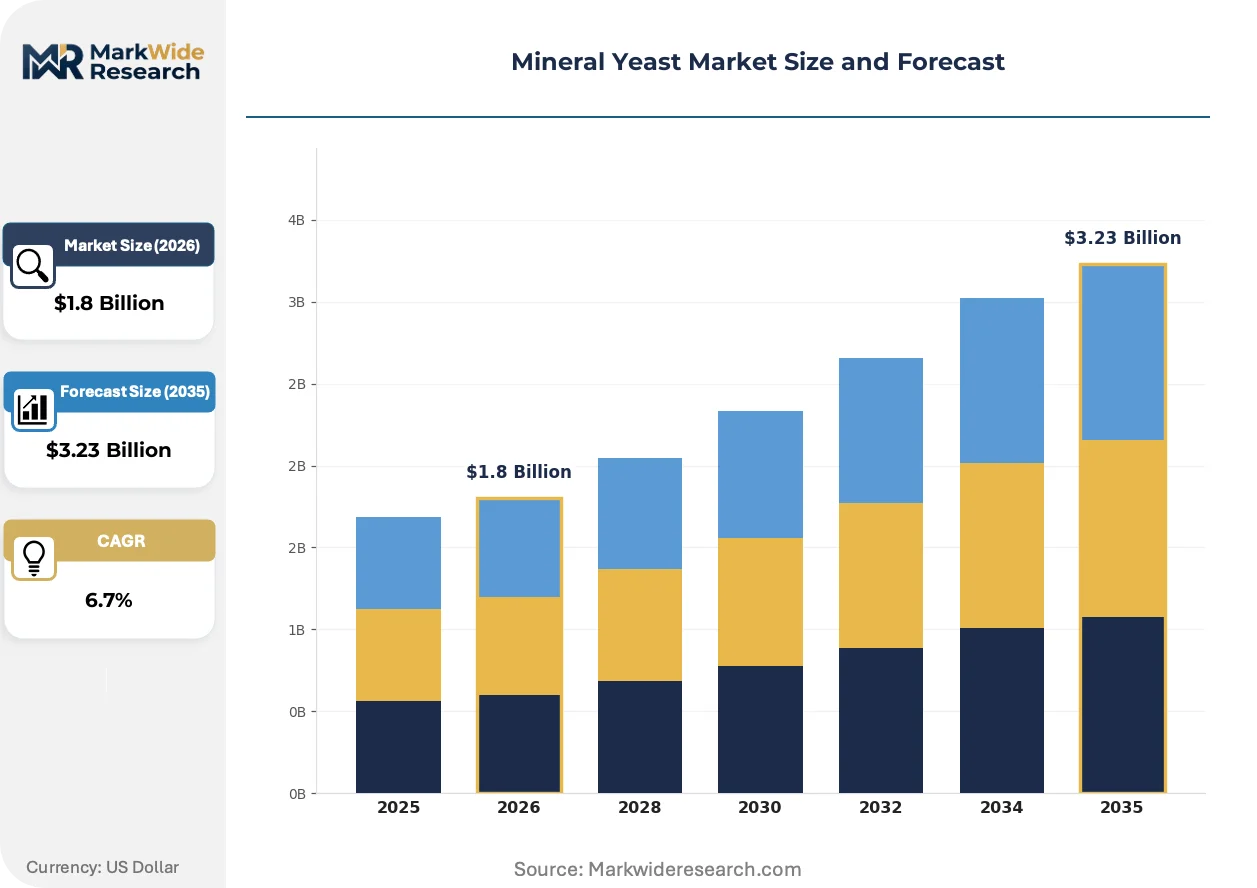
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yeast Extract, Yeast Powder, Yeast Flakes, Yeast Concentrate Application: Food Additives, Animal Nutrition, Biotechnology, Pharmaceutical Precursors End User: Feed Manufacturers, Bakery Units, Biotech Companies, Pharmaceutical Firms Packaging Type: Plastic Bags, Kraft Paper Bags, Bulk Containers, Vacuum Packaging |
| Companies Covered | LALLEMAND, SCETI K.K., AB Biotek Human Nutrition & Health, Angel Yeast, Chaitanya Agro Biotech, Leiber, Kerry Group, Pharma Nord, Alltech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mineral Yeast Market Trends and Innovations
Process intensification and regulatory digitization are compressing development cycles for mineral yeast applications, while downstream formulation demands reshape upstream strain selection priorities.
Sensor-integrated bioreactor arrays are automating real-time selenium uptake monitoring during Saccharomyces cerevisiae cultivation, replacing offline atomic absorption testing. Contract manufacturers in Germany and the Netherlands deploy these systems to guarantee 2000-3000 ppm selenium consistency for pharmaceutical clients. This automation is compressing batch release timelines from seven days to under 48 hours.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon refrigerants force fermentation facility retrofits, driving adoption of ammonia-based cooling systems in yeast production plants. The industrial consequence extends beyond capital expenditure to strain viability, as temperature excursion windows narrow during scale-up. Pharmaceutical-grade selenium yeast operations in Bavaria and Rhineland-Palatinate face the steepest compliance deadlines.
Ingredient sourcing decisions now prioritize third-party verified carbon intensity scores alongside unit pricing, reflecting scope 3 emissions accountability pressures from downstream food and feed customers. German retail chains and Dutch agricultural cooperatives increasingly specify yeast-bound minerals with documented lifecycle assessments. This behavioral shift concentrates contract awards among producers with integrated fermentation and downstream processing capabilities.
Mineral Yeast Market Segmentation
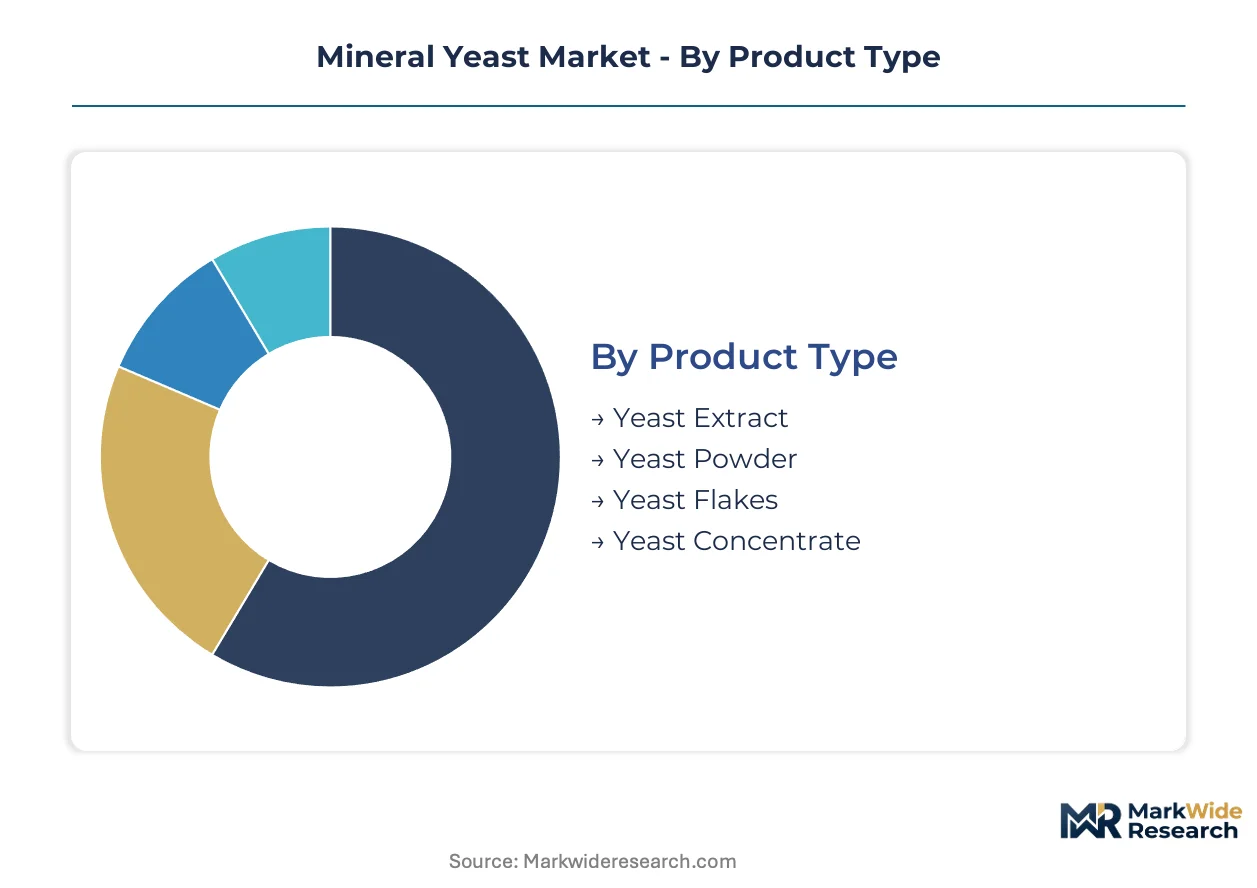
Mineral yeast segmentation reflects divergent certification burdens across food, feed, and pharmaceutical channels. Product format selection directly determines which regulatory gateways—FDA GRAS, EFSA Novel Food, or EU REACH—manufacturers must navigate to access specific revenue pools.
Product Type:
FDA GRAS notifications govern yeast extract and yeast powder destined for human consumption, while feed-grade yeast concentrate falls under USDA and state-level feed control regulations. Pharmaceutical-grade formats require the most stringent documentation, with EFSA Novel Food evaluations and REACH substance registrations creating multi-year approval timelines for novel selenium-enriched strains.
- Yeast Extract:Soluble biomass fraction standardized at 2000–3000 ppm selenium, favored by liquid pharmaceutical formulators for its complete dispersibility in aqueous systems. Demand concentrates in German nutraceutical contract manufacturing, where EFSA maximum permitted level compliance functions as a non-negotiable purchase qualifier.
- Yeast Powder:Spray-dried whole cell preparations retaining intracellular mineral content, dominating premix incorporation for livestock applications. Procurement by Danish and German feed manufacturers accelerates as veterinary antibiotic restrictions tighten under EFSA guidelines, displacing inorganic sodium selenite.
- Yeast Flakes:Visible fortification format gaining traction among clean-label food producers seeking consumer-facing mineral enrichment without synthetic additive stigma.
- Yeast Concentrate:High-density biomass slurry format optimized for industrial-scale animal nutrition blending, reducing transportation cost per mineral unit.
Yeast extract sits at the top of the volume ranking, with yeast flakes climbing the fastest.
Application:
Cost tier differentiation separates commodity feed applications from premium pharmaceutical precursor contracts. Animal nutrition commands the lowest unit prices but highest volume scale, while biotechnology applications extract maximum value per kilogram through custom strain development fees.
- Animal Nutrition:Feed-grade mineral yeast incorporated into premix formulations for swine, poultry, and ruminant diets. German and Danish livestock operations drive substitution away from inorganic mineral salts as regulatory pressure intensifies.
- Food Additives:Clean-label mineral fortification for baked goods, beverages, and dietary supplements. European manufacturers adopt yeast flake formats to bypass synthetic additive labeling requirements.
- Pharmaceutical Precursors:High-purity selenium-enriched yeast for nutraceutical capsules and tablets. Bavarian biotech clusters specialize in pharmaceutical-grade strain development, commanding substantial contract manufacturing premiums.
- Biotechnology:Research-grade mineral yeast for metabolic engineering and precision fermentation platform development.
Animal nutrition dominates absolute volume, with pharmaceutical precursors expanding most quickly.
End User:
Customer type determines procurement sophistication and contract structure. Feed manufacturers negotiate long-term premix supply agreements with price volatility clauses, while pharmaceutical firms demand batch-level certificates of analysis and full supply chain documentation.
- Feed Manufacturers:Industrial-scale buyers integrating mineral yeast into compound feed and premix formulations. Procurement decisions pivot on modular dosing format availability and third-party verified carbon intensity scores.
- Pharmaceutical Firms:Quality-critical purchasers requiring pharmaceutical-grade selenium consistency and full regulatory dossier support for EFSA Novel Food submissions.
- Bakery Units:Mid-scale food manufacturers adopting yeast-bound minerals for clean-label bread and pastry fortification.
- Biotech Companies:Research and development buyers seeking custom mineral profiles for strain engineering projects.
Feed manufacturers anchor the volume ranking, with pharmaceutical firms gaining share fastest.
Packaging Type:
Supply chain configuration shapes packaging selection, with bulk containers dominating integrated fermentation-to-premix operations and vacuum packaging protecting hygroscopic yeast extract during extended distribution.
- Bulk Containers:Intermediate bulk containers and tanker formats for high-volume feed-grade shipments direct from fermentation facilities to premix plants.
- Vacuum Packaging:Oxygen-barrier formats preserving selenium bioavailability in yeast extract and powder during pharmaceutical-grade distribution.
- Kraft Paper Bags:Sustainable packaging option for food-grade yeast flakes targeting European retail chain sustainability specifications.
- Plastic Bags:Cost-optimized format for standard-grade animal nutrition applications with shorter distribution cycles.
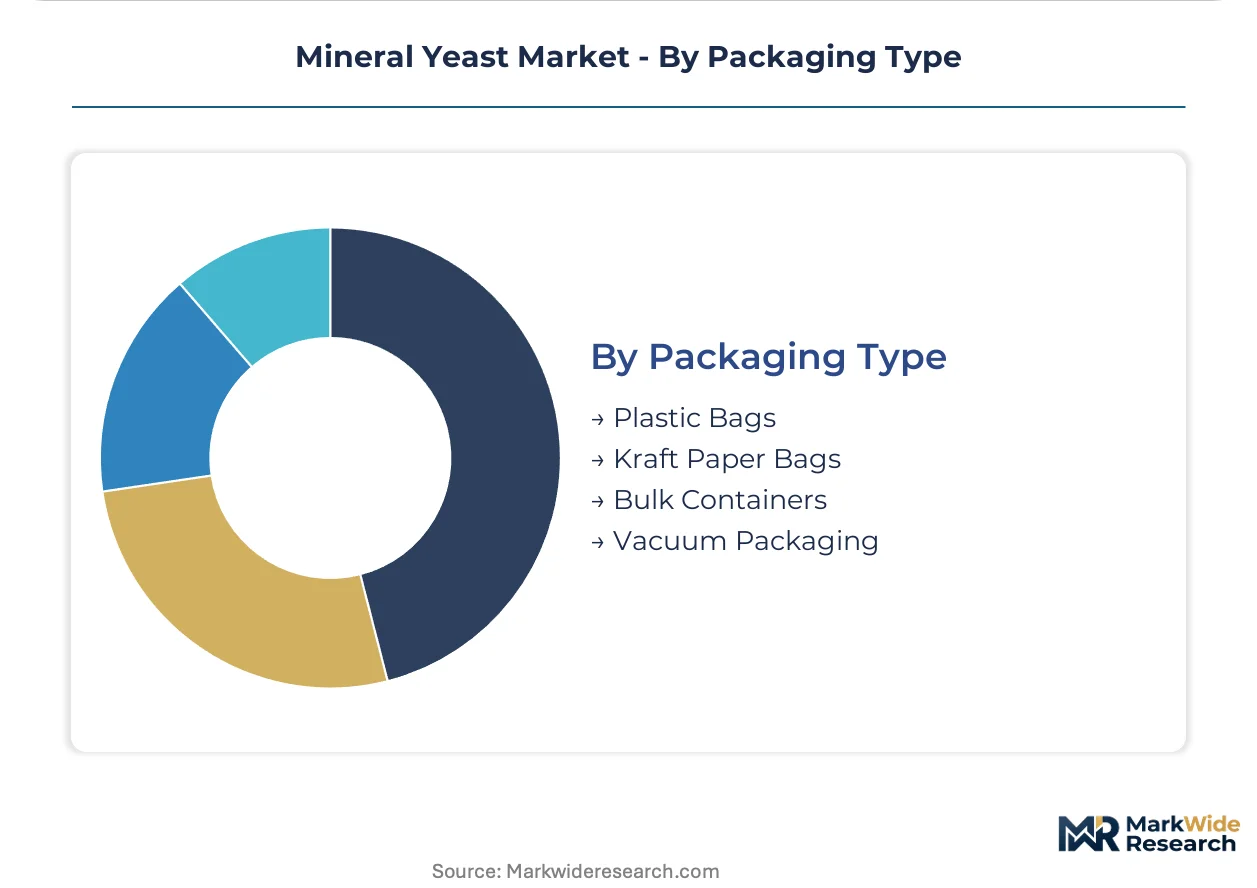
Bulk containers sit at the top of the volume ranking, with vacuum packaging climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial mineral yeast production traces its industrial lineage to post-war European fermentation science, where German and Danish dairy cooperatives first standardized selenium-enriched biomass for livestock supplementation. This technical foundation diffused through North Atlantic trade corridors before establishing secondary production nodes in East Asia during the 1990s biotechnology expansion.
Germany
Bavarian biotech clusters in Munich and Freising host specialized selenium yeast strain development for pharmaceutical-grade applications. EFSA Novel Food evaluations and REACH substance registrations constrain new market entrants, extending approval timelines for novel mineral-enriched variants. Rhineland-Palatinate fermentation facilities face steep F-Gas Regulation compliance deadlines, accelerating ammonia-based cooling retrofits.
United States
Midwest feed manufacturers integrate yeast-bound minerals into swine and poultry premix formulations as veterinary antibiotic restrictions tighten under FDA guidance. USDA organic certification and FDA GRAS notifications govern dual-track market access for human-food and feed-grade products. California clean-label food producers adopt visible yeast flake formats for consumer-facing fortification.
China
Yangtze River Delta fermentation complexes anchor Asia-Pacific supply capacity for both domestic consumption and export markets. SAMR food safety standards and GB certification requirements shape strain qualification protocols for human nutrition applications. Zhejiang and Jiangsu provinces concentrate toll manufacturing relationships with European pharmaceutical clients.
Denmark
Danish livestock operations drive substitution away from inorganic sodium selenite under EFSA veterinary antibiotic reduction mandates. National agricultural cooperatives specify third-party verified carbon intensity scores for mineral yeast procurement. Copenhagen-area premix manufacturers negotiate long-term supply agreements with modular dosing format requirements.
France
Paris Basin pet food manufacturers seek yeast-bound mineral solutions for senior companion animal formulations targeting joint and immune health. ANSM pharmaceutical regulations govern nutraceutical-grade selenium yeast import and distribution. Brittany agricultural regions participate in EU CAP eco-schemes rewarding bioavailable mineral adoption.
Mineral Yeast Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade stratification, with pharmaceutical-grade selenium yeast commanding substantial contract manufacturing premiums over feed-grade alternatives. The vendor base organizes into three functional tiers: integrated fermentation specialists with proprietary strain libraries, toll manufacturers serving pharmaceutical and food clients, and regional premix blenders sourcing bulk mineral yeast for livestock applications. Dominant competitive moves include backward integration into captive molasses supply and technology licensing agreements for continuous fermentation systems.
Within the integrated fermentation tier, LALLEMAND and Angel Yeast occupy positions reflecting decades of strain development investment, while Kerry Group exemplifies the formulation-specialist archetype blending mineral yeast with adjacent ingredient systems. These three anchors represent divergent strategic postures: germplasm control versus downstream formulation value capture versus Asia-Pacific scale manufacturing.
| Leading Market Players |
|---|
| LALLEMAND |
| SCETI K.K. |
| AB Biotek Human Nutrition & Health |
| Angel Yeast |
| Chaitanya Agro Biotech |
| Leiber |
| Kerry Group |
| Pharma Nord |
| Alltech |
| Others |
Pricing and Supply Chain Analysis
Qualified bioprocess engineers in Bavaria and Rhineland-Palatinate command wage premiums that widen spreads between pharmaceutical-grade and feed-grade mineral yeast pricing tiers. Labor-cost differentials between German fermentation specialists and toll manufacturers in Zhejiang province amplify certification-grade price stratification across the value chain.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade levels anchors the mineral yeast market. Price differentiation rests on EFSA Novel Food certification status and FSSC 22000 compliance depth, with pharmaceutical-grade strains extracting substantial premiums for batch-level consistency guarantees. Pricing pressure stems from inorganic sodium selenite undercutting yeast-bound alternatives in cost-sensitive livestock applications. Feed manufacturers exhibit highest price sensitivity, while pharmaceutical firms prioritize supply security over unit cost.
Supply Chain Analysis
Molasses supply rests on Brazilian sugarcane processors and Indian distilleries, with corn steep liquor sourcing concentrated in Midwest US grain processing. Fermentation inputs draw from agricultural commodity cycles that transmit volatility into yeast production economics. Single-source vulnerability concentrates in proprietary Saccharomyces cerevisiae strain libraries held by European germplasm holders. Distribution runs through integrated fermentation-to-premix pipelines for feed-grade volumes, while pharmaceutical-grade shipments deploy vacuum-sealed cold chain logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mineral yeast market compounds steadily as antibiotic substitution mandates in livestock nutrition create durable demand tailwinds. Regulatory pressure on veterinary antibiotic use across EFSA jurisdictions ensures sustained volume growth for bioavailable mineral alternatives.
For Market Incumbents: To counter proprietary strain IP concentration by European germplasm holders, invest in CRISPR-edited yeast development programs and secure captive molasses supply through backward integration into Brazilian sugarcane processing. Expand ammonia-based cooling capacity ahead of EU F-Gas Regulation deadlines to maintain pharmaceutical-grade production continuity. For New Entrants and Emerging Players: USDA conservation programs rewarding bioavailable mineral adoption in regenerative agriculture operations opens a window for regional premix blending partnerships. Target companion animal premiumization in French and Italian pet food markets with joint-health-focused selenium yeast formulations. Pursue toll manufacturing relationships with Zhejiang fermentation complexes to bypass capital-intensive strain development barriers. For Investors and Strategic Acquirers: Animal nutrition conglomerates are the most active acquirer in this space, seeking mineral yeast capabilities to complete antibiotic-free premix portfolios. Five-to-ten year viability rests on fermentation scale-up expertise scarcity that protects incumbent margins. Watch EFSA guidance on maximum permitted selenium levels as the key inflection trigger for product reformulation cycles and facility qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Fermentation Technology Deployment | Reduces batch-to-batch selenium variability for pharmaceutical-grade consistency guarantees. |
| Ammonia-Based Cooling Retrofit | Ensures EU F-Gas Regulation compliance for Rhineland-Palatinate fermentation facilities. |
| Carbon Intensity Certification Program | Meets Dutch agricultural cooperative and German retail chain sustainability procurement specifications. |
| Companion Animal Formulation Partnership | Captures premium margins in French senior pet food joint and immune health segments. |
| Toll Manufacturing Agreement | Leverages Yangtze River Delta capacity for European pharmaceutical client qualification. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from fermentation plant managers, feed manufacturer procurement leads, pharmaceutical regulatory affairs directors, and EFSA scientific committee members. Secondary validation drew from FDA GRAS notifications, EFSA Novel Food opinions, USDA organic certification databases, and customs trade records for molasses and yeast extract shipments. Bottom-up volume modeling and top-down market sizing triangulated segment-level outputs.
Segment-weighting approaches distributed value across yeast extract, powder, flakes, and concentrate formats by application channel. The analytical framework modeled animal nutrition, food additives, pharmaceutical precursors, and biotechnology end uses across the projection horizon. CAGRs derived from historical volume trajectories and regulatory-driven substitution elasticity parameters. Forecast inputs incorporated EFSA veterinary antibiotic restriction timelines and EU CAP eco-scheme adoption curves.
Revisions become necessary when EFSA maximum permitted level guidance shifts, F-Gas Regulation enforcement accelerates, or precision fermentation platforms displace conventional Saccharomyces cerevisiae cultivation. Forecasts reflect assumptions about strain qualification timelines and certification maintenance costs. A small set of named triggers—regulatory threshold changes, cooling system retrofit delays, and carbon intensity scoring adoption—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Bacterial Antigens Market
Industrial Microbiology
Ripening Cultures Market
Industrial Microbiology
Lactobacillus Strains Market
Industrial Microbiology
Mesophilic Bacteria Market
Industrial Microbiology
Global Starter Culture Market
Industrial Microbiology
Middle East Feed Probiotics Market
Industrial Microbiology
Microbial Biosurfactants Market
Industrial Microbiology
Global Arabinogalactan Market
Industrial Microbiology
Cultured Dextrose Market
Industrial Microbiology
Microbial Bioreactors Market
Industrial Microbiology
Lipase Market
Industrial Microbiology
Microbial Rennet Market
Industrial Microbiology
Microbiome Sample Preparation Technology Market
Industrial Microbiology
Microbial Culture Market
Industrial Microbiology
Microbiomes Market
Industrial Microbiology
Probiotic Yeast Market