
 Middle East Feed Probiotics Market | 2026-2036
Middle East Feed Probiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Feed Probiotics Market Foresight
The UAE's Ministry of Climate Change and Environment antibiotic-reduction mandate is pivoting commercial poultry operations toward documented probiotic regimens. Biomin sustains a strong formulation presence across Gulf Cooperation Council feed mills with yeast-derived product lines tailored to heat-stressed broilers. Chr. Hansen Holding AS leverages its strain-banking capabilities to supply lactic acid bacteria cultures for ruminant feedlots in Saudi Arabia. Alltech anchors technical service teams in Dubai to support direct-sales relationships with integrated poultry producers.
Feed probiotics comprise live microbial cultures, typically administered at colony-forming unit counts ranging from 10^6 to 10^9 CFU per gram of feed, designed to colonize the gastrointestinal tract and modulate host-microbiome interactions for improved nutrient assimilation and pathogen exclusion. Bacteria-based formulations dominate volume given their established efficacy in poultry gut-acidification protocols, while enzymatic blends represent the fastest-expanding category as Saudi and Emirati feed mills seek simultaneous fiber-breakdown and probiotic benefits in least-cost rations. Dry formulation types command the largest share of distribution through wholesalers serving small-to-midscale ruminant operations, though liquid probiotics are gaining traction in automated aquaculture systems along the Red Sea coast.
Saudi Arabia's Food and Drug Authority and the UAE's Ministry of Climate Change and Environment enforce registration requirements that strain-level documentation and stability claims for imported feed additives, effectively filtering out uncertified suppliers. The Saudi Standards, Metrology and Quality Organization (SASO) has aligned national feed-quality protocols with Gulf Standardization Organization benchmarks, creating a harmonized compliance corridor across the six GCC states. Stakeholders must monitor how national food-security strategies reshape procurement patterns for locally manufactured versus imported probiotic stocks.
Market Dynamics
Antibiotic-residue enforcement by Saudi Arabia's Food and Drug Authority and the UAE's Ministry of Climate Change and Environment is restructuring feed formulation priorities across Gulf poultry operations, forcing integrators to validate probiotic strain documentation or face import blockages.
Growth Catalysts
- Regulatory Mandates:The UAE's Ministry of Climate Change and Environment has imposed strict import protocols requiring strain-level verification for veterinary feed additives, accelerating documented probiotic adoption in commercial broiler operations.
- Poultry Belt Concentration:Vertically integrated producers in Saudi Arabia's Riyadh-Qassim corridor operate the region's largest hatchery-to-processing complexes, creating concentrated demand pull for gut-health solutions.
- Heat-Stress Formulation:Yeast-derived product lines engineered for thermotolerant microbial cultures are gaining traction as summer temperature extremes compromise conventional bacterial strain viability.
Market Restraints
- Strain Stability Costs:Maintaining colony-forming unit viability above 10^6 CFU per gram through Gulf climate storage and transport requires specialized cold-chain infrastructure that elevates landed costs.
- Supplier Concentration:Lactic acid bacteria culture supply for Saudi ruminant feedlots remains dependent on a narrow base of strain-banking specialists with Gulf-compliant documentation systems.
- Technical Limitations:Liquid probiotic formulations face shelf-life constraints that restrict distribution radius from Red Sea aquaculture automation hubs to coastal zones.
Strategic Opportunities
- Aquaculture Automation:Liquid delivery systems for automated feeding infrastructure along Saudi Arabia's Red Sea coast represent underpenetrated deployment channels for specialized marine-adapted strains.
- Least-Cost Ration Convergence:Enzymatic-probiotic blends that simultaneously enable fiber breakdown and microbiome modulation are capturing formulation share in price-sensitive Emirati feed mills.
- GCC Harmonization:Saudi Standards, Metrology and Quality Organization alignment with Gulf Standardization Organization benchmarks creates a unified compliance corridor for cross-border probiotic distribution.
Industry Challenges
- Documentation Burden:Registration requirements demanding stability claims and strain-level verification extend product approval timelines, compressing commercialization windows for new entrants.
- Technical Service Scarcity:Direct-sales relationships with integrated poultry producers require on-site microbiology support that outstrips available specialist staffing in the Gulf.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Feed Probiotics Market |
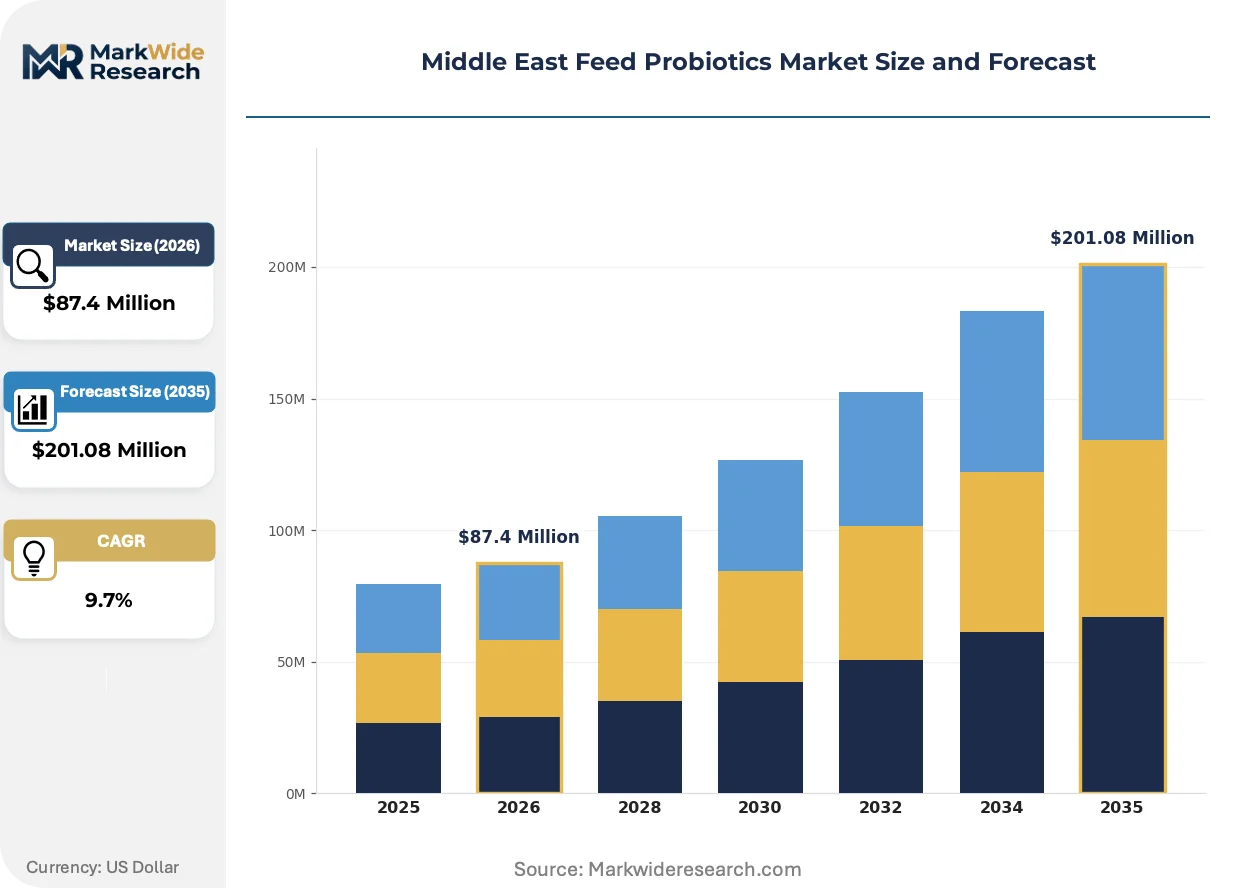
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $201.08 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacteria, Yeast, Fungal, Enzymatic Application: Poultry, Swine, Ruminants, Aquaculture Formulation Type: Dry, Liquid, Granulated, Powdered Distribution Channel: Direct Sales, Retail, E-Commerce, Wholesalers |
| Companies Covered | Adisseo, DuPont, Biomin, Chr. Hansen Holding AS, Lallemand Inc., Alltech, Archer Daniels Midland, Cargill, DSM Nutritional Products, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Feed Probiotics Market Shifts & Advancements
Formulation science and compliance architecture are converging to reshape competitive positioning in Gulf feed probiotics, with strain-specific documentation and climate-adaptive delivery systems emerging as primary differentiation vectors.
Multi-strain consortia combining lactic acid bacteria with bacillus spores is overtaking single-species formulations in Saudi broiler operations. Poultry integrators in the Riyadh-Qassim belt are accelerating adoption rates as summer mortality events expose the limitations of acidification-only protocols. This technology is compressing supplier margins on legacy direct-fed microbial products while rewarding integrated strain-banking capabilities.
Saudi Arabia's Food and Drug Authority has tightened antibiotic-residue surveillance in processed poultry, triggering mandatory feed-additive traceability requirements. Commercial operations must now maintain batch-level documentation linking probiotic inclusion rates to slaughterhouse residue testing. Heat-stressed broiler categories face the steepest compliance burden, driving demand for yeast-derived alternatives with established thermotolerance profiles.
Direct technical engagement models are displacing traditional wholesale distribution for large-scale integrated producers. Biomin and Alltech have established captive service teams in Dubai and Riyadh to bypass feed-mill intermediaries. Saudi Arabia's central poultry belt exhibits the most pronounced channel compression, with hatchery-to-processing complexes demanding strain-specific performance guarantees rather than commodity probiotic supply.
Middle East Feed Probiotics Market Segmentation
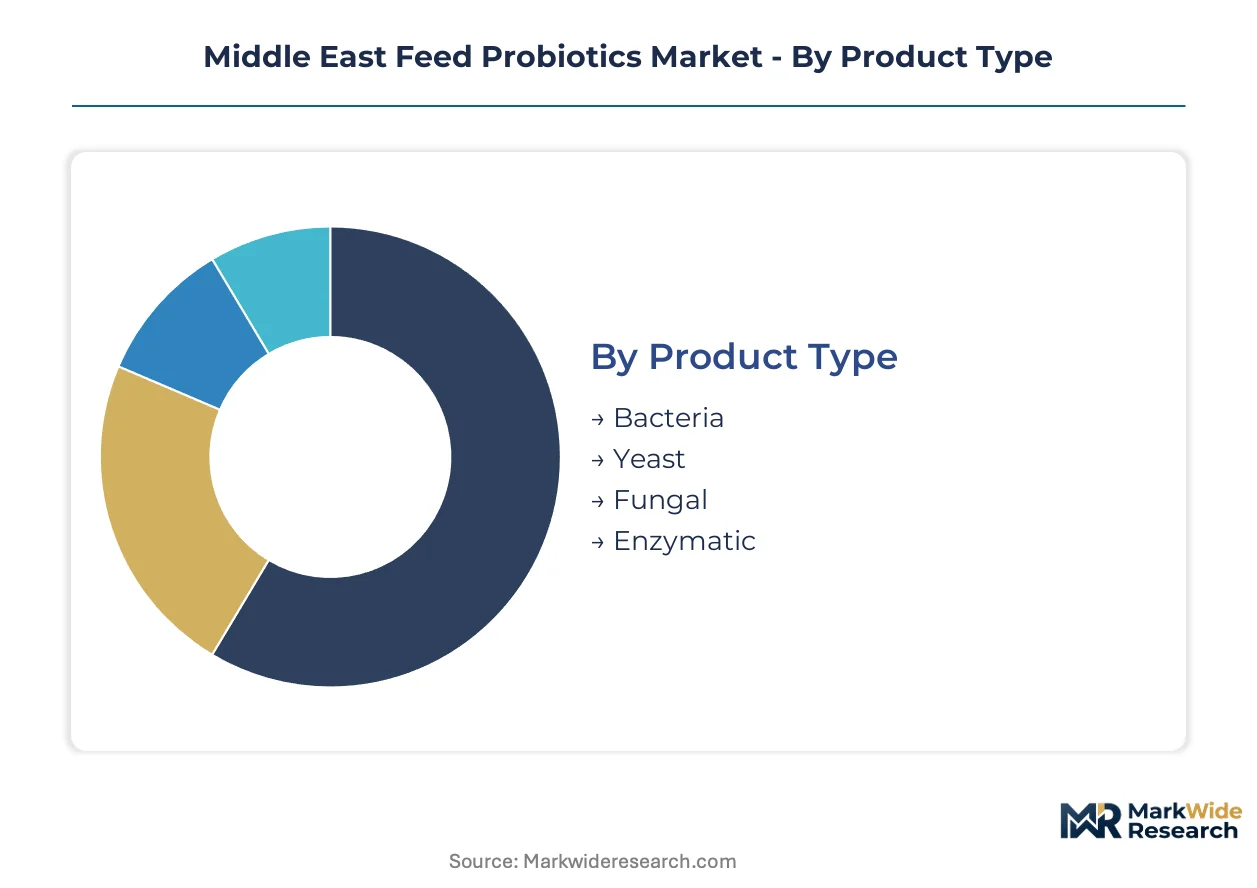
Feed probiotic segmentation in the Middle East reflects the tension between climate-adaptive delivery systems and regulatory documentation requirements. Gulf integrators select formulations based on strain stability under thermal stress and compliance with national food safety mandates.
Product Type:
Microbial taxonomy determines functional efficacy across Gulf livestock categories, with thermotolerance and colonization rates serving as primary selection criteria.
- Bacteria:Lactic acid bacteria and bacillus spores dominate commercial volumes, delivering gut acidification and competitive pathogen exclusion. Saudi Arabia's Riyadh-Qassim poultry belt concentrates demand as integrators replace antibiotic growth promoters with documented bacterial regimens under SFDA residue surveillance.
- Yeast:Saccharomyces cerevisiae and related thermotolerant strains command premium positioning for summer broiler operations. UAE commercial farms facing Ministry of Climate Change and Environment import protocols favor yeast derivatives with established stability above 40°C ambient temperatures.
- Fungal:Aspergillus-based preparations target fiber degradation in ruminant feedlots.
- Enzymatic:Probiotic-enzyme hybrids are gaining formulation share in cost-optimized Emirati mills seeking dual-function inclusion.
Mature deployment sits with Bacteria. Newer deployment is concentrated in Enzymatic.
Application:
End-use segmentation tracks vertical integration depth and regulatory exposure across Gulf livestock sectors.
- Poultry:Broiler integrators in Saudi Arabia's central belt drive volume, with hatchery-to-processing complexes mandating strain-specific performance guarantees. SFDA antibiotic-residue enforcement has made probiotic documentation mandatory for slaughterhouse clearance.
- Ruminants:Saudi feedlot operations source lactic acid bacteria cultures for rumen microbiome modulation. Strain-banking capabilities from specialized suppliers remain concentrated given documentation requirements for imported cultures.
- Swine:Limited regional demand given Islamic dietary restrictions and minimal commercial pig farming.
- Aquaculture:Automated Red Sea coastal systems are deploying liquid probiotics for marine species, though shelf-life constraints restrict inland distribution.
Volume concentration favors Poultry. Fastest expansion is occurring in Aquaculture.
Formulation Type:
Physical state governs distribution economics and viability maintenance through Gulf supply chains.
- Dry:Pellet-compatible powders and granules dominate wholesale distribution to small-to-midscale ruminant operations across GCC states. SASO-aligned quality protocols favor dry formats with extended ambient stability.
- Liquid:Specialized delivery for automated aquaculture feeding infrastructure along Saudi Arabia's Red Sea coast. Temperature-controlled logistics requirements elevate landed costs and compress distribution radius.
- Granulated:Heat-resistant coatings protect CFU counts through pelleting thermal exposure.
- Powdered:Base format for on-farm mixing in non-integrated operations.
Wholesale penetration is deepest with Dry. Technical sophistication is advancing fastest in Liquid.
Distribution Channel:
Channel structure reflects customer scale and technical service intensity requirements.
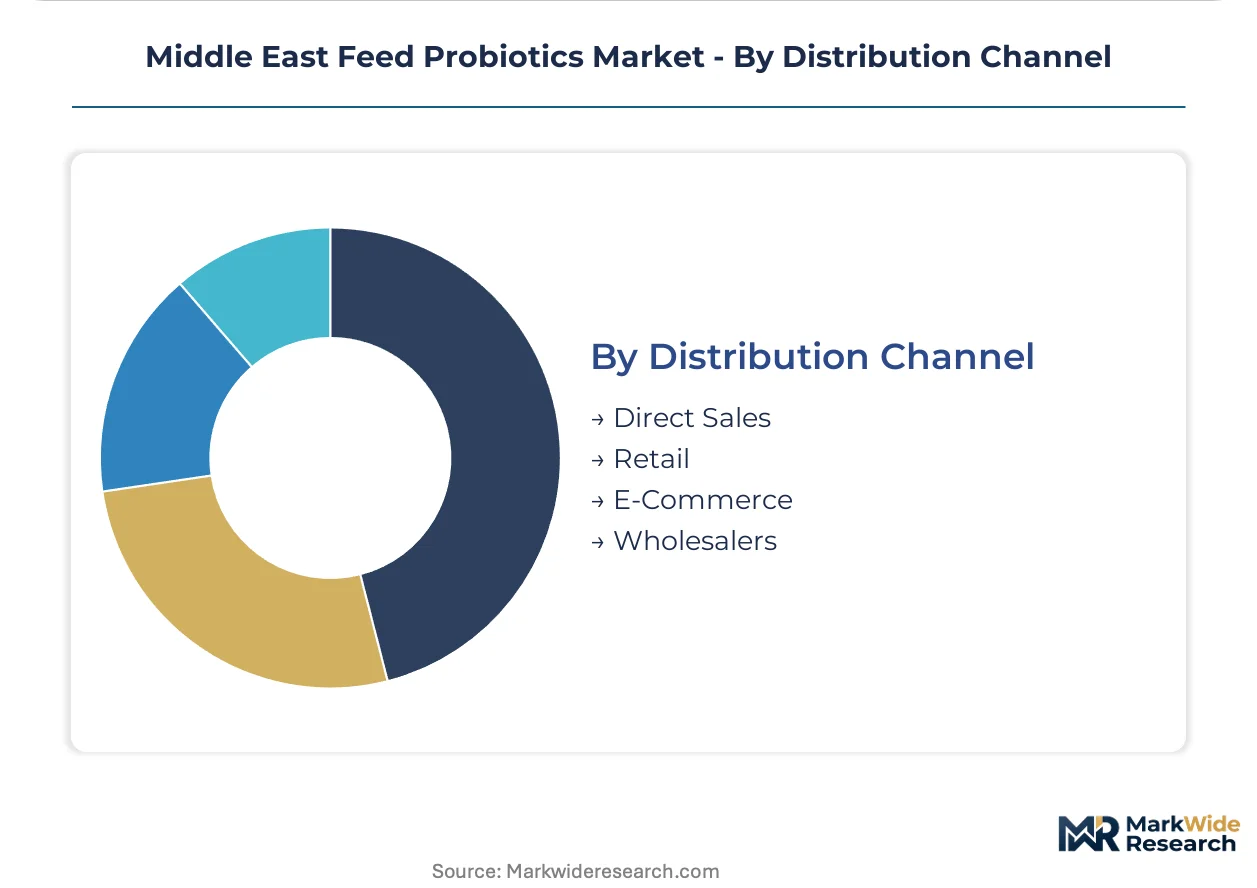
- Direct Sales:Integrated poultry producers in Saudi Arabia and the UAE bypass intermediaries, demanding captive technical teams for strain-specific troubleshooting. Biomin and Alltech maintain Dubai and Riyadh service hubs to support these relationships.
- Wholesalers:Traditional route for fragmented ruminant and small-scale poultry operations across GCC secondary markets.
- Retail:Limited presence serving hobby farms and specialty livestock holdings.
- E-Commerce:Emerging channel for documentation-verified specialty strains, though cold-chain fulfillment remains underdeveloped.
Relationship intensity peaks in Direct Sales. Reach expansion is concentrated in E-Commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh anchors Middle East feed probiotics demand through its vertically integrated poultry corridor linking hatcheries to processing facilities under tightening SFDA antibiotic-residue surveillance.
Saudi Arabia
The Riyadh-Qassim belt concentrates regional broiler production, with hatchery-to-processing complexes demanding strain-documented probiotic regimens. SFDA enforcement of antibiotic-residue limits in processed poultry mandates batch-level feed-additive traceability. Thermotolerant yeast formulations command premium positioning as summer mortality events expose bacterial strain limitations.
United Arab Emirates
Commercial broiler operations in Dubai and Abu Dhabi pivot toward documented probiotic inclusion amid Ministry of Climate Change and Environment import protocol tightening. Strain-level verification requirements filter uncertified suppliers from veterinary feed additive channels. Biomin and Alltech maintain captive technical service teams in Dubai to support direct-sales relationships with integrated producers.
Qatar
Food security strategies drive localized feed manufacturing investments around Doha's industrial zone, creating procurement pull for GCC-compliant probiotic stocks. National self-sufficiency targets reshape import dependency patterns for livestock nutrition inputs. Small-scale ruminant operations rely on wholesale distribution of dry-formulation probiotics through SASO-aligned quality channels.
Kuwait
Poultry integrators in Al-Jahra and Al-Farwaniya governorates adopt heat-stress formulations as summer temperature extremes compromise conventional bacterial viability. Feed mill consolidation favors suppliers with documented stability claims above 40°C ambient thresholds. Distribution runs through established Gulf Cooperation Council trade corridors benefiting from harmonized standards alignment.
Oman
Coastal aquaculture automation along the Sultanate's shores deploys liquid probiotic delivery systems for marine species cultivation. Shelf-life constraints restrict inland distribution radius, concentrating technical deployment in Muscat-adjacent zones. Temperature-controlled logistics requirements elevate landed costs for specialized marine-adapted strains.
Middle East Feed Probiotics Market Competitive Landscape
The competitive structure tilts toward multinational specialists with strain-banking capabilities and regional technical service infrastructure. Tiered positioning separates integrated biotechnology firms from commodity feed additive traders. Three archetypes dominate: thermotolerant formulation specialists, direct-engagement service providers, and diversified nutrition conglomerates. Capacity expansion and regulatory documentation systems constitute the primary competitive vectors as SFDA and UAE Ministry requirements harden compliance barriers.
Within the specialist tier, Chr. Hansen Holding AS and Biomin occupy positions anchored by microbial culture banking and climate-adaptive formulation science. Lallemand Inc. exemplifies the diversified fermentation technology archetype with cross-species probiotic portfolios. Among integrated nutrition conglomerates, Adisseo and DSM Nutritional Products represent scale-driven positions leveraging global R&D infrastructure for regional compliance adaptation. Archer Daniels Midland and Cargill sit within agricultural commodity trading networks extending into feed additive distribution.
| Leading Market Players |
|---|
| Adisseo |
| DuPont |
| Biomin |
| Chr. Hansen Holding AS |
| Lallemand Inc. |
| Alltech |
| Archer Daniels Midland |
| Cargill |
| DSM Nutritional Products |
| Others |
Supply & Pricing Matrix
Family-owned fermentation specialists across Denmark and France anchor strain-banking capacity, translating proprietary culture collections into pricing power over commodity traders lacking thermotolerant documentation. Their ownership structure enables patient capital allocation toward cold-chain infrastructure that bacterial-only competitors cannot replicate, compressing margins on generic direct-fed microbials while rewarding integrated formulation science.
Pricing Analysis
Value-based pricing anchored to feed-conversion-ratio outcomes dominates large-scale poultry contracts in Saudi Arabia's Riyadh-Qassim belt. Pricing stratifies across premium, standard, and economy tiers based on strain-banking depth and SFDA documentation completeness. Cost compression in economy-tier bacterial powders is intensifying because Indian and Chinese traders lack Gulf-compliant stability verification. Small-to-midscale ruminant operations exhibit highest price sensitivity, while integrated hatchery-to-processing complexes prioritize performance guarantees over unit cost.
Supply Chain Analysis
Live culture supply rests on Danish and French specialty fermentation houses for lactic acid bacteria banking, with German and Dutch distributors handling GCC customs clearance and temperature-controlled logistics. Critical inputs include cryoprotectant formulations, nitrogen-flush packaging, and validated cold-chain monitoring hardware. Single-source vulnerability concentrates in thermotolerant yeast strains where two European suppliers hold documented stability data above 40°C. Distribution runs through Dubai-Jebel Ali free zone hubs serving Saudi and Emirati feed mills directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
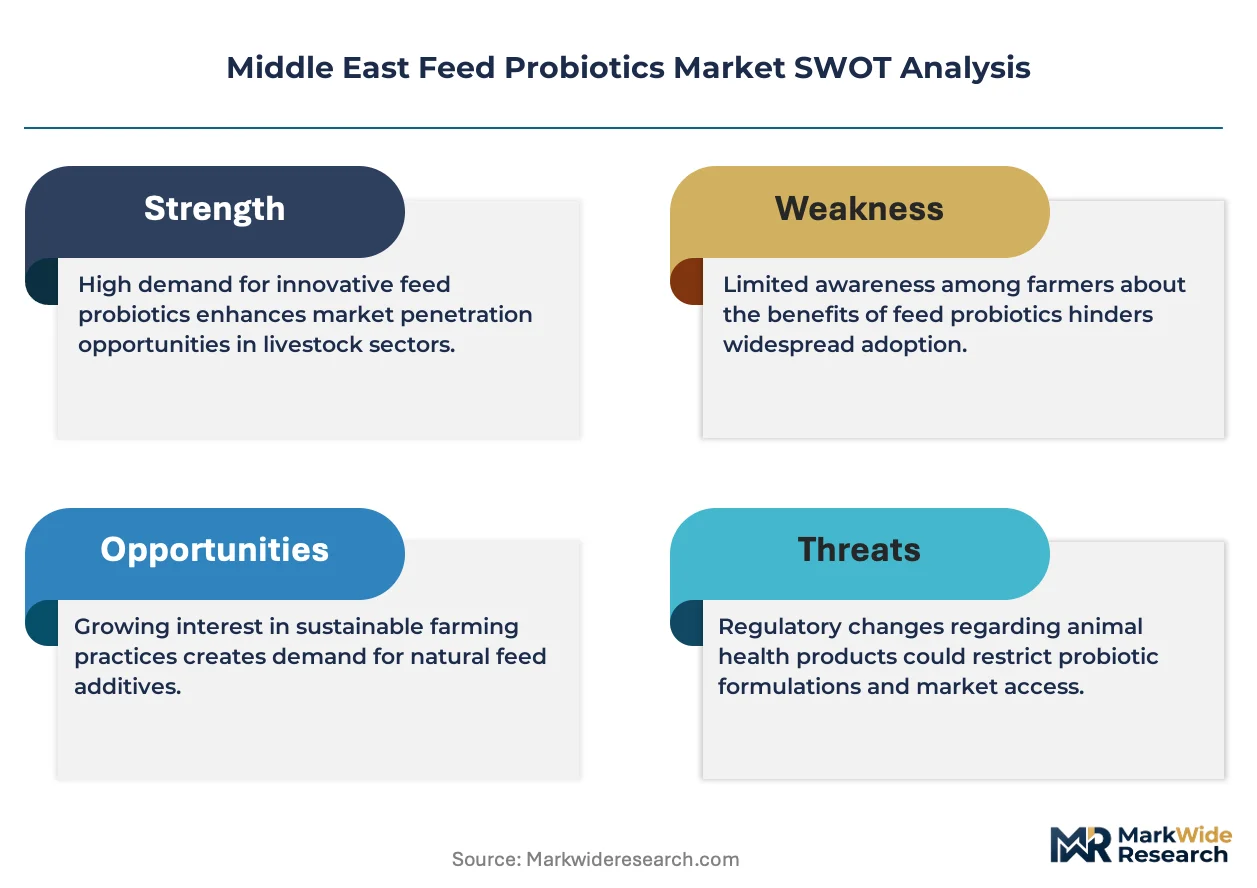
SFDA and UAE Ministry documentation mandates are consolidating supplier tiers, forcing uncertified traders toward exit while rewarding strain-banking incumbents with compliance infrastructure already deployed.
For Market Incumbents: Deepen captive technical service presence in Riyadh and Dubai to defend direct-sales relationships against emerging enzymatic-probiotic hybrid suppliers. Expand backward integration into thermotolerant strain development before summer mortality events accelerate yeast formulation switching. Prioritize SASO-aligned quality certification investments to capture Qatar and Kuwait procurement flows through harmonized GCC trade corridors. For New Entrants and Emerging Players: Marine-adapted liquid probiotic technology offers the most penetrable wedge for Red Sea aquaculture automation, where shelf-life constraints have kept established players coastal. Target Oman's Muscat-adjacent zones with temperature-controlled logistics partnerships before inland distribution infrastructure matures. Lead with strain-specific performance guarantees rather than commodity CFU counts to bypass wholesaler intermediaries. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap fermentation specialists with incomplete GCC registration portfolios in Germany and the Netherlands. Long-term viability hinges on 5-10 year regulatory harmonization bets across the six GCC states. Watch SFDA batch-level traceability enforcement intensity as the inflection signal for documentation-premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Strain-Banking Capacity Expansion | Chr. Hansen and Biomin strengthen thermotolerant culture collections for Gulf summer conditions. |
| Cold-Chain Infrastructure Partnership | Temperature-controlled logistics alliances reduce CFU degradation through Jebel Ali distribution hubs. |
| Regulatory Documentation Investment | SFDA and UAE Ministry compliance systems filter uncertified competitors from import channels. |
| Direct Technical Service Deployment | On-site microbiology teams in Riyadh and Dubai displace feed-mill intermediaries for integrated poultry. |
| Enzymatic-Probiotic Hybrid Development | Dual-function formulations capture least-cost ration share in price-sensitive Emirati feed mills. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving feed mill procurement directors, poultry integration veterinarians, strain-banking R&D leads, and cold-chain logistics operators. SFDA registration databases, UAE Ministry import protocols, GCC customs manifests, and SASO quality standards provided documentary validation. Bottom-up volume estimates from hatchery capacity and feed production statistics were reconciled against top-down probiotic inclusion rate assumptions.
Data-stream reconciliation across microbial taxonomy, formulation type, application segment, and distribution channel generated segmented projections over the analysis window. CAGRs derived from trend extrapolation of antibiotic-reduction policy trajectories and vertical integration depth in Saudi poultry. Modeled inputs included summer temperature mortality correlations, strain stability half-life curves, and documentation approval timeline distributions.
Several conditions sit outside the modeled scope, including abrupt GCC trade policy fragmentation, novel antibiotic-residue detection methodology shifts, and aquaculture disease outbreaks altering marine species cultivation economics. Forecasts reflect assumptions about regulatory harmonization continuity and cold-chain infrastructure investment pacing. A small set of named triggers warrants ongoing watch: SFDA enforcement intensity, UAE Ministry protocol expansion, and Red Sea logistics corridor development.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Antibiotic Resistance Market
Industrial Microbiology
Eubiotics Market
Industrial Microbiology
Molecular Microbiology Market
Industrial Microbiology
Anti-Microbial Anti-Fungal Test Market
Industrial Microbiology
Galactosidase Market
Industrial Microbiology
Microbial Biosurfactants Market
Industrial Microbiology
Bacterial Amylase Market
Industrial Microbiology
Global Arabinogalactan Market
Industrial Microbiology
Specialty Cultures Market
Industrial Microbiology
Benzoate-Free Enzymes Market
Industrial Microbiology
Lipase Market
Industrial Microbiology
Microbial-Derived Fiber Market
Industrial Microbiology
Global Microbial Protein Market
Industrial Microbiology
Microbial Therapeutic Products Market
Industrial Microbiology
Microbiome Sample Preparation Technology Market
Industrial Microbiology
Microbial Cell Banking Market