
 Europe Solar Backsheet Market | 2026-2036
Europe Solar Backsheet Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Solar Backsheet Market Insights
Photovoltaic engineering talent shortages across Central Europe are reorganizing how backsheet manufacturers allocate technical resources. DuPont de Nemours Inc. leverages its polymer science heritage to sustain fluoropolymer leadership in high-humidity environments. Coveme SpA anchors Italian production networks with specialized PET-based laminates. Krempel GmbH competes through precision coating capabilities serving German utility-scale developers.
A solar backsheet is the outermost protective layer of a photovoltaic module, typically a multi-layer polymer film measuring 300-500 microns that shields cells from moisture, UV degradation, and electrical insulation failure. Fluoropolymer types command premium positioning due to superior weathering resistance and extended field life, while composite formulations capture mid-tier residential demand through cost-optimized laminated constructions. Application segmentation tilts toward utility-scale procurement as developers standardize on thickness-customized products that reduce levelized cost of energy.
REACH restrictions on perfluorinated substances are forcing reformulation timelines across European supply chains, with ECHA substance evaluations directly impacting fluoropolymer backsheet chemistries. CE marking under the EU Construction Products Regulation governs module-level fire safety and electrical integrity, creating compliance thresholds for backsheet material selection. Stakeholders must track polymer substitution pathways and recyclability mandates as the EU Green Deal tightens circular economy requirements for photovoltaic components.
Market Dynamics
REACH compliance pressures on perfluorinated substances are forcing European backsheet manufacturers into accelerated reformulation cycles, compressing product development timelines while utility-scale developers demand extended field-life guarantees.
Growth Catalysts
- EU Green Deal decarbonization mandates:Binding renewable targets across member states are accelerating utility-scale solar procurement in Spain, Germany, and Italy.
- Fluoropolymer durability premiums:High-humidity field performance in Mediterranean climates favors weathering-resistant laminated constructions over standard PET alternatives.
- German industrial solar corridor expansion:Manufacturing clusters and feed-in tariff structures concentrate demand for thickness-customized backsheet solutions.
Market Restraints
- PVDF resin supply concentration:European fluoropolymer precursor availability depends on limited polymerization capacity in Germany and Belgium.
- ECHA substance evaluation timelines:REACH restrictions on perfluorinated chemistries create regulatory friction without clear substitution pathways.
- Composite formulation performance gaps:Cost-optimized PET-based laminates exhibit accelerated UV degradation in southern European installations.
Strategic Opportunities
- Italian agrivoltaic integration:Dual-use solar installations on agricultural land create demand for translucent backsheet variants with modified spectral transmission.
- CSRD-aligned circular economy mandates:Extended producer responsibility frameworks incentivize recyclable thermoplastic backsheet development over thermoset fluoropolymers.
- Building-integrated photovoltaics convergence:Architectural solar facades in German and Dutch urban cores require aesthetic-grade backsheet finishes with fire-rated certifications.
Industry Challenges
- Photovoltaic polymer engineering talent scarcity:Central European universities produce insufficient specialists in multi-layer film extrusion and adhesion chemistry.
- CE marking certification bottlenecks:Module-level fire safety testing under the EU Construction Products Regulation extends backsheet qualification timelines.
- Legacy inventory stranding risk:Reformulated non-fluorinated chemistries require parallel production lines while REACH transition periods remain unresolved.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Solar Backsheet Market |
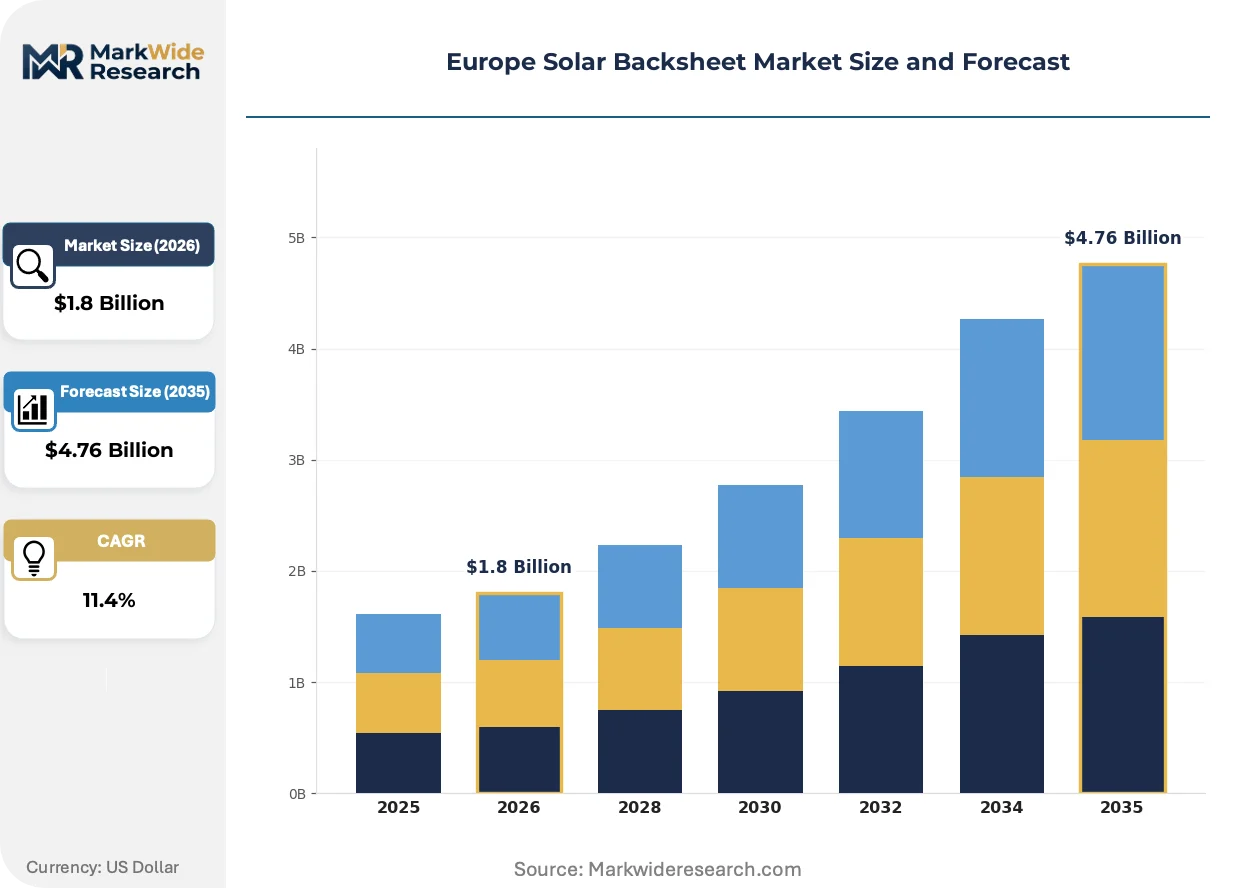
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Polymer, Fluoropolymer, Composite, Ethylene Vinyl Acetate Application: Residential, Commercial, Utility-Scale, Off-Grid Material: Non-Woven, Film, Laminated, Coated Thickness: Standard, Thin, Ultra-Thin, Customized |
| Companies Covered | DuPont de Nemours Inc., Coveme SpA, 3M Co., Krempel GmbH, Isovoltaic AG, Arkema SA, DUNMORE, Targray Technology International Inc., Madico Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Solar Backsheet Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are simultaneously pulling European backsheet innovation toward sustainable polymer architectures without sacrificing field durability in harsh UV environments.
Co-extruded thermoplastic olefin backsheet constructions are decomposing the traditional fluoropolymer-PET-fluoropolymer laminate hierarchy. German utility-scale developers are piloting these structures in multi-hundred-megawatt installations. The technology is decomposing premium-tier pricing power by delivering comparable hydrolysis resistance at reduced material cost.
REACH Annex XVII restrictions on perfluorooctanoic acid derivatives are compelling reformulation investments across European supply chains. ECHA substance evaluations now directly impact PVDF and ETFE backsheet chemistries previously grandfathered under transitional arrangements. Fluoropolymer manufacturers are accelerating hydrofluoric acid-free polymerization processes to maintain CE marking eligibility.
Buyers are consolidating procurement specifications around thickness-customized products that reduce balance-of-system costs. Tier-one module assemblers in the Netherlands and Denmark are unbundling backsheet supply from cell-and-module contracts to secure direct material traceability. This pattern concentrates volume with coating specialists capable of sub-10-micron tolerance control across 2-meter web widths.
Europe Solar Backsheet Market Segmentation
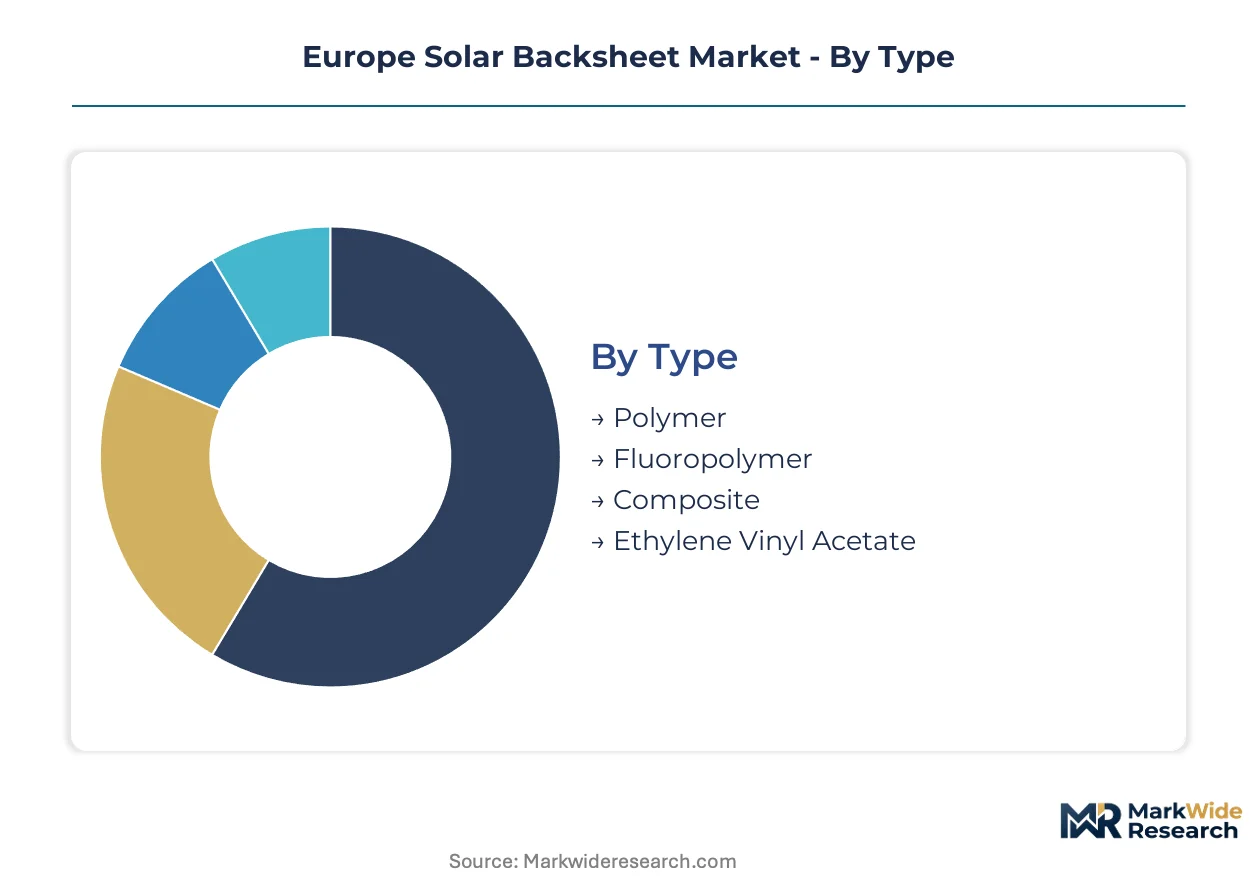
Solar backsheet procurement in Europe fragments across material chemistry, installation scale, and dimensional specifications. Each segmentation axis carries distinct margin profiles and regulatory exposure that reshape supplier positioning under REACH and EU Green Deal timelines.
Type:
Fluoropolymer formulations capture premium margin pools through extended field-life guarantees demanded by Mediterranean utility-scale developers.
- Fluoropolymer:Multi-layer PVDF or ETFE constructions deliver superior hydrolysis resistance and UV stability in high-humidity Iberian and Italian installations. German utility-scale procurement clusters favor these chemistries despite ECHA evaluation pressures on perfluorinated precursors.
- Composite:PET-based laminates with fluorinated surface layers balance cost and performance for mid-tier residential segments across Central Europe. Accelerated degradation in southern European UV exposure limits warranty extensions below fluoropolymer tiers.
- Polymer:Standard thermoplastic constructions serve price-sensitive distributed generation in Eastern European markets.
- Ethylene Vinyl Acetate:Encapsulant-integrated backsheet variants emerging in building-integrated photovoltaic applications requiring flexible substrate compatibility.
Fluoropolymer holds installed capacity. Composite is rotating up the share rankings as reformulation investments accelerate.
Application:
Utility-scale procurement concentrates volume while residential channels distribute margin across smaller batch sizes.
- Utility-Scale:Megawatt-scale solar farms across Spain, Germany, and Italy standardize on thickness-customized backsheets reducing balance-of-system costs. Feed-in tariff structures and power purchase agreement tenors drive 25-year durability specifications.
- Commercial:Rooftop and carport installations in Dutch and Danish industrial zones demand fire-rated certifications under EU Construction Products Regulation with shorter payback horizons.
- Residential:Distributed rooftop systems in German and Austrian markets prioritize cost-optimized PET laminates with standard warranty terms.
- Off-Grid:Remote and island installations in Greek and Portuguese archipelagos require enhanced moisture barrier performance without grid connection redundancy.
Utility-Scale anchors procurement volume. Commercial is climbing the fastest as building-integrated mandates expand.
Material:
Film-based constructions dominate technical specifications while laminated architectures capture integration value.
- Laminated:Multi-ply fluoropolymer-PET-fluoropolymer structures remain the durability benchmark for Mediterranean utility-scale assets. Krempel GmbH and Coveme SpA production networks specialize in sub-10-micron tolerance control across 2-meter web widths.
- Film:Co-extruded thermoplastic olefin constructions from German developers are decomposing traditional laminate hierarchies through comparable hydrolysis resistance at reduced material cost.
- Coated:Precision-applied barrier layers enable thickness customization for specific climatic zones without full laminate redundancy.
- Non-Woven:Emerging textile-reinforced substrates for agrivoltaic applications requiring mechanical resilience against agricultural equipment contact.
Laminated commands specification authority. Film is gaining share fastest as co-extrusion technology matures.
Thickness:
Standard thickness maintains procurement share while customized dimensions unlock system-level cost reductions.
- Customized:Thickness-tailored products reduce module weight and mounting hardware requirements for German utility-scale developers optimizing levelized cost of energy. Tier-one assemblers in the Netherlands and Denmark unbundle backsheet supply to secure direct material traceability.
- Standard:300-500 micron constructions serve conventional framed modules across European residential and commercial segments with established supply chain availability.
- Thin:Reduced-gauge films for lightweight rooftop applications in urban Dutch and Belgian markets with structural load constraints.
- Ultra-Thin:Experimental sub-200 micron constructions for flexible and building-integrated photovoltaic form factors.
Standard retains volume leadership. Customized is expanding most quickly as procurement specifications consolidate around system optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes fluoropolymer backsheet formulations at intensity levels unmatched elsewhere in Europe, while Mediterranean markets favor weathering-resistant laminates for high-UV exposure. This consumption-mix differential reflects divergent installation scales and regulatory incentive structures across national solar programs.
Germany
Utility-scale solar farms in the industrial corridor between Bavaria and North Rhine-Westphalia drive specification-grade fluoropolymer procurement. The EEG feed-in tariff revision prioritizes 25-year durability guarantees for ground-mounted assets. Krempel GmbH anchors precision coating capacity in Baden-Württemberg to serve these developers directly.
Spain
Andalusian and Extremadura solar parks under the National Integrated Energy and Climate Plan standardize on high-humidity-resistant backsheet constructions. ECHA REACH compliance timelines force accelerated reformulation investments among suppliers serving Iberian projects. Madrid-based engineering clusters coordinate module assembly specifications for Mediterranean climate exposure.
Italy
Agrivoltaic installations across Lombardy and Emilia-Romagna create demand for translucent backsheet variants with modified spectral transmission. The EU Green Deal national recovery plan channels funding toward dual-use solar infrastructure. Coveme SpA production networks in Veneto specialize in PET-based laminates for these agricultural integration projects.
Netherlands
Rooftop solar mandates in the Randstad conurbation prioritize fire-rated backsheet certifications under EU Construction Products Regulation. CSRD-aligned circular economy reporting drives procurement toward recyclable thermoplastic constructions. Eindhoven-region coating specialists capture volume from unbundled backsheet supply contracts.
France
Building-integrated photovoltaic deployments in Île-de-France and Auvergne-Rhône-Alpes require aesthetic-grade backsheet finishes with architectural certification. The F-Gas Regulation restricts fluorinated precursor availability for domestic fluoropolymer production. Lyon-based polymer engineering clusters develop hydrofluoric acid-free polymerization alternatives.
Europe Solar Backsheet Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in European backsheet supply. The upper tier commands specification authority through polymer science heritage and precision coating capabilities. Three archetypes dominate: fluoropolymer heritage players with REACH transition expertise, precision laminators serving utility-scale procurement clusters, and coating specialists capturing unbundled supply contracts. Competitive moves concentrate on reformulation investments for ECHA compliance and capacity alignment with German utility-scale development timelines.
Among heritage-anchored polymer science groups, DuPont de Nemours Inc. exemplifies the integrated leader archetype through sustained fluoropolymer positioning. Coveme SpA and Krempel GmbH occupy complementary specialist positions within the European tier, representing the precision laminator and coating specialist archetypes respectively. These three entities collectively illustrate how supplier positioning fragments across material chemistry expertise, geographic production clustering, and procurement specification capture.
| Leading Market Players |
|---|
| DuPont de Nemours Inc. |
| Coveme SpA |
| 3M Co. |
| Krempel GmbH |
| Isovoltaic AG |
| Arkema SA |
| DUNMORE |
| Targray Technology International Inc. |
| Madico Inc. |
| Others |
Pricing and Supply Chain Analysis
Sixty-day resin inventory buffers among German fluoropolymer coaters concentrate pricing power with PVDF suppliers in Belgium and Germany, compressing margin capture for downstream laminators serving utility-scale developers.
Pricing Analysis
Long-term offtake contracts dominate procurement between tier-one module assemblers and precision coating specialists, insulating volume buyers from PVDF resin spot volatility while spot-market exposure concentrates among smaller residential distributors. Pricing stratifies across REACH-compliant fluoropolymer tiers, standard PET-based laminates, and emerging thermoplastic olefin alternatives, with certification grade under EU Construction Products Regulation commanding measurable premiums. Cost compression in composite formulations is intensifying because ECHA substance evaluation timelines force parallel production line investments. Residential channel buyers in Eastern Europe exhibit highest price sensitivity, while German utility-scale developers prioritize thickness-customized durability guarantees over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies prevail among Dutch and Danish module assemblers unbundling backsheet supply, while German utility-scale developers maintain strategic stockpiles against PVDF resin allocation constraints. Manufacturing concentration centers on Germany, Italy, and Belgium, with precision coating capacity clustering in Baden-Württemberg and Veneto. Raw material flows draw from fluoropolymer polymerization facilities in Germany, PET film extrusion in Italy, and adhesive chemistry specialists in the Netherlands. Single-source vulnerability runs through limited European PVDF precursor capacity. Distribution feeds from direct mill relationships with tier-one assemblers and specialized industrial distributors serving mid-tier residential channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory chemistry fragmentation under REACH timelines is spawning addressable niches for specialists capable of bridging fluoropolymer performance with circular economy compliance.
For Market Incumbents: Fortify specification authority by accelerating hydrofluoric acid-free polymerization investments ahead of F-Gas Regulation tightening, and deepen backward integration into PET film extrusion to offset resin allocation risk from Belgian suppliers. CE marking certification bottlenecks threaten to strand legacy inventory; parallel production lines for reformulated non-fluorinated chemistries preserve optionality during unresolved transition periods. For New Entrants and Emerging Players: Lead with translucent backsheet variants for Italian agrivoltaic installations, where modified spectral transmission requirements have not yet locked in incumbent supply relationships. The Lombardy and Emilia-Romagna dual-use solar corridor offers lowest penetration resistance among application segments. Direct mill relationships with agricultural cooperative developers bypass established module assembler procurement hierarchies. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with dormant European backsheet assets capable of rapid REACH-compliant reformulation. Long-term viability hinges on positioning for circular economy mandates tightening across the projection horizon. Precision coating specialists with sub-10-micron tolerance control represent the acquisition archetype of interest. The signal to watch is CSRD-aligned extended producer responsibility framework implementation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Reformulation Investment | ECHA substance evaluation timelines directly threaten CE marking eligibility for legacy fluoropolymer chemistries. |
| Backward Integration into PET Film Extrusion | Coveme SpA and Krempel GmbH production networks demonstrate margin capture from captive substrate supply. |
| Agrivoltaic Translucent Backsheet Development | Italian National Recovery Plan funding channels create first-mover advantage in dual-use solar infrastructure. |
| Co-extruded Thermoplastic Olefin Scale-Up | German utility-scale pilot installations validate comparable hydrolysis resistance at reduced material input cost. |
| Unbundled Supply Contract Capture | Tier-one assemblers in the Netherlands and Denmark consolidate procurement specifications around direct material traceability. |
Research Methodology
A standing panel of module assembly procurement directors, fluoropolymer plant managers, EPC contractors, and EU regulatory affairs specialists provided ongoing calibration against secondary validation from customs trade data, ECHA substance evaluation registers, SEC filings of listed chemical conglomerates, and national solar program disbursement records. Primary interviews with coating specialists and utility-scale developers combined with bottom-up installation forecasts and top-down polymer consumption estimates.
Consistency checks against IEA renewable deployment trajectories and Cefic chemical production indices validated volume and value outputs across the projection horizon. Segmentation modeling incorporated material chemistry tiers, installation scale categories, thickness specifications, and regional regulatory cluster variations. CAGRs were derived from fitted growth curves calibrated to historical capacity expansion patterns and feed-in tariff revision schedules.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal funding commitment or accelerated REACH restriction timelines would require recalibration. Forecasts reflect documented assumptions regarding polymer substitution pathway viability and module assembly localization trends. Revision becomes warranted when ECHA perfluorinated substance evaluation outcomes cross regulatory certainty thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Global Dye-Sensitized Solar Cells (Dssc) Market
Solar Power Systems
Thin-Film Photovoltaic Market
Solar Power Systems
Solar Polysilicon Ingot Wafer Cell Module Market
Solar Power Systems
Europe Concentrated Solar Power Market
Solar Power Systems
Smart Solar Tracker Market
Solar Power Systems
United Kingdom Solar Power Market
Solar Power Systems
Plastic Solar Cell Market
Solar Power Systems
United States Distributed Solar Power Generation Market
Solar Power Systems
Solar Encapsulation Market
Solar Power Systems
Residential Solar Energy Market
Solar Power Systems
Brazil Solar Energy Market
Solar Power Systems
Marine Solar Panel Market
Solar Power Systems
Distributed Solar Power Generation System Market
Solar Power Systems
Photovoltaic (PV) Materials Market
Solar Power Systems
Solar Shed Light Market
Solar Power Systems
Solar Module Market