
 US Behavioral Health Care Software and Services Market | 2026-2036
US Behavioral Health Care Software and Services Market Size, Share, and Industry Trends Forecast 2026-2036
US Behavioral Health Care Software and Services Market Intelligence
Multi-source procurement of behavioral health IT is realigning how provider networks assemble their technology stacks. Epic Systems Corporation anchors inpatient psychiatric workflows through deep EHR integration with medical records. Netsmart Technologies, Inc. specializes in community mental health and substance-use platforms for state-funded agencies. Qualifacts competes on cloud-native architecture designed specifically for behavioral health clinical workflows.
US behavioral health care software and services encompass digital platforms that manage clinical documentation, scheduling, billing, telehealth delivery, and regulatory compliance for mental health and substance-use treatment providers; these systems typically incorporate HIPAA-compliant encryption, HL7 FHIR interoperability protocols, and outcome measurement tools to support value-based reimbursement models. The deployment dimension shows cloud-based infrastructure capturing the fastest expansion as rural clinics abandon client-server legacy systems; among applications, patient engagement tools command premium pricing due to their direct linkage to CMS quality metrics and readmission reduction incentives. Telehealth modules within product type segmentation retain elevated margins following permanent regulatory flexibilities enacted after the public health emergency.
FDA oversight of digital therapeutics, HIPAA privacy enforcement by OCR, and state-level Medicaid managed care contracting rules collectively determine product design priorities and go-to-market pathways for vendors. The 21st Century Cures Act information-blocking provisions force incumbents to open APIs, lowering switching costs for provider organizations. Stakeholders must track how CMS innovation center payment models for integrated behavioral health reshape software procurement criteria before the next federal rulemaking cycle concludes.
Market Dynamics
The 21st Century Cures Act's information-blocking provisions are forcing incumbent vendors to open APIs, fundamentally restructuring how US provider organizations evaluate and switch behavioral health IT platforms.
Growth Catalysts
- Medicaid Expansion:California and Texas are driving platform upgrades as state-funded agencies modernize infrastructure to serve newly eligible populations with integrated care mandates.
- Telehealth Regulatory Flexibility:Permanent CMS reimbursement rules for virtual behavioral health visits sustain elevated deployment of remote patient engagement modules across community mental health centers.
- FHIR Interoperability:HL7 protocols are mandating data exchange standards that compel EHR vendors to build behavioral health-specific connectors, accelerating procurement cycles for replacement systems.
Market Restraints
- Legacy Technical Debt:Rural clinics running client-server architectures face prohibitive migration costs to cloud-native platforms, delaying replacement timelines by 24-36 months.
- Specialized Labor Scarcity:Behavioral health informaticists with dual clinical-technical training command premium salaries, constraining implementation bandwidth at mid-sized provider networks.
- HIPAA Enforcement Intensity:OCR audit protocols and state attorney general actions elevate compliance insurance premiums, compressing IT budget allocations for software acquisition.
Strategic Opportunities
- Integrated Primary-Behavioral Care:Federally qualified health centers in Medicaid expansion states are unbundling siloed systems to procure unified platforms spanning medical and psychiatric workflows.
- Digital Therapeutics Convergence:FDA-cleared prescription software for substance-use disorder is creating reimbursement pathways that EHR vendors can capture through embedded module partnerships.
- Value-Based Contracting Infrastructure:CMS innovation center models for behavioral health integration are reshaping procurement criteria toward outcome measurement tools before the next federal rulemaking cycle.
Industry Challenges
- Interoperability Implementation Complexity:Provider IT departments struggle to map non-standardized behavioral health terminologies to FHIR resources, delaying go-live dates and inflating professional services costs.
- Outcome Measurement Standardization:Competing proprietary assessment instruments from different vendors fragment quality reporting for managed care contracts, forcing redundant data entry by clinicians.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Behavioral Health Care Software and Services Market |
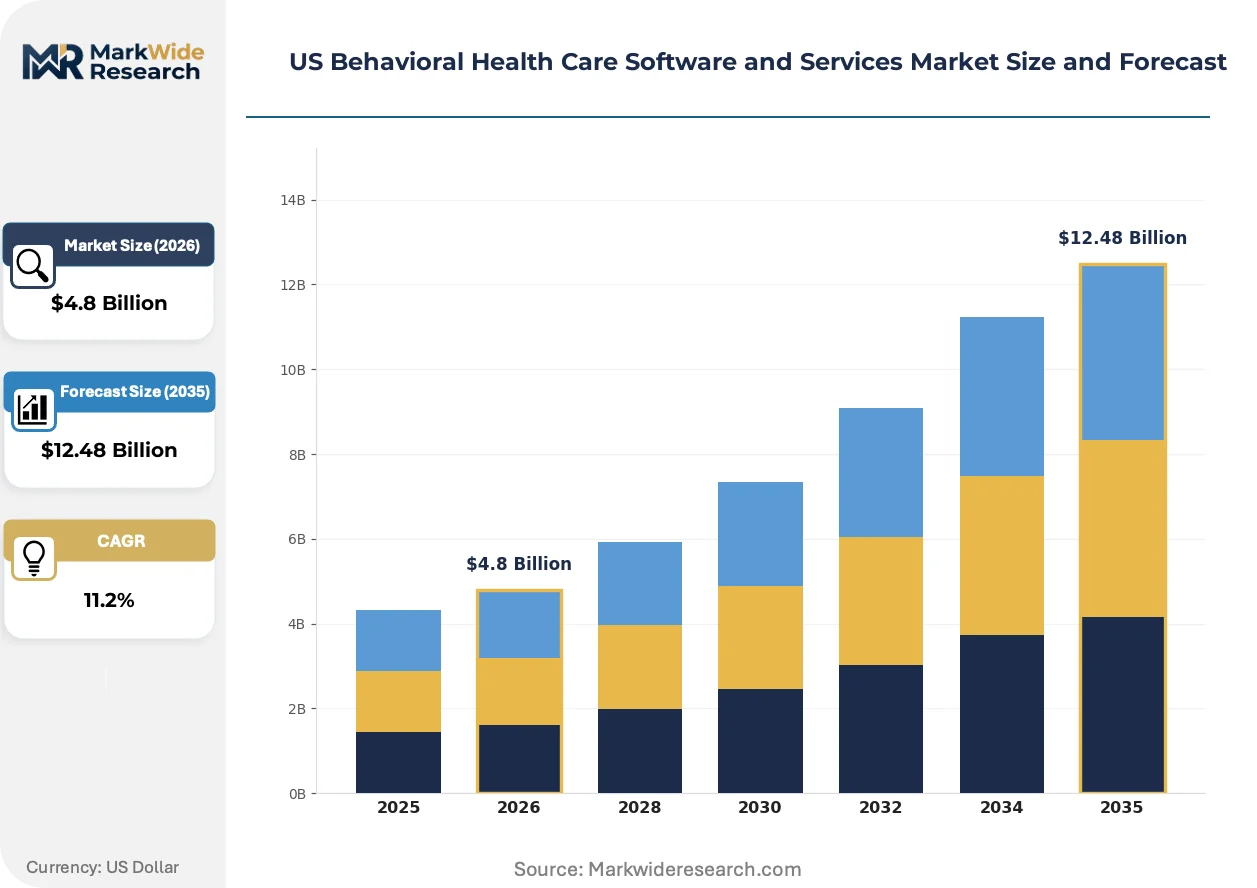
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.48 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EMR, Practice Management, Telehealth, Billing Solutions End User: Clinics, Hospitals, Private Practices, Mental Health Organizations Deployment: On-Premise, Cloud-Based, Hybrid, Client-Server Application: Patient Engagement, Data Analytics, Resource Management, Compliance Monitoring |
| Companies Covered | Oracle (Cerner Corporation), Core Solutions, Inc., Epic Systems Corporation, Netsmart Technologies, Inc., Qualifacts, SimplePractice, LLC, TherapyNotes, LLC, Holmusk, Welligent, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Behavioral Health Care Software and Services Market Strategic Shifts & Innovations
Behavioral health IT architecture is fragmenting from monolithic suites into composable components, with procurement patterns favoring best-of-breed specialization over single-vendor consolidation.
Cloud-native clinical documentation platforms is modularizing how provider networks assemble technology stacks, allowing federally qualified health centers to swap individual components without full EHR replacement. State-funded agencies in Texas and California are adopting this approach fastest, decoupling scheduling, billing, and telehealth modules from legacy inpatient psychiatric systems. The structural consequence is compressing switching costs and accelerating competitive displacement of integrated suite vendors.
CMS information-blocking enforcement under the 21st Century Cures Act is mandating API accessibility that incumbent vendors previously resisted, compelling open data exchange across previously walled gardens. This regulatory pressure is reshaping vendor product roadmaps toward modular interoperability. Community mental health centers and substance-use treatment providers are the segments most affected, responding by inserting FHIR capability requirements into every RFP.
Consolidated purchasing by multi-state behavioral health networks is displacing decentralized IT decision-making that historically favored local customization. Large provider systems are centralizing vendor negotiations and mandating standardized platforms across acquired clinics, stripping autonomy from individual facility administrators. This concentration is most visible in California's county mental health plan regions and Texas's Medicaid managed care service areas.
US Behavioral Health Care Software and Services Market Segmentation
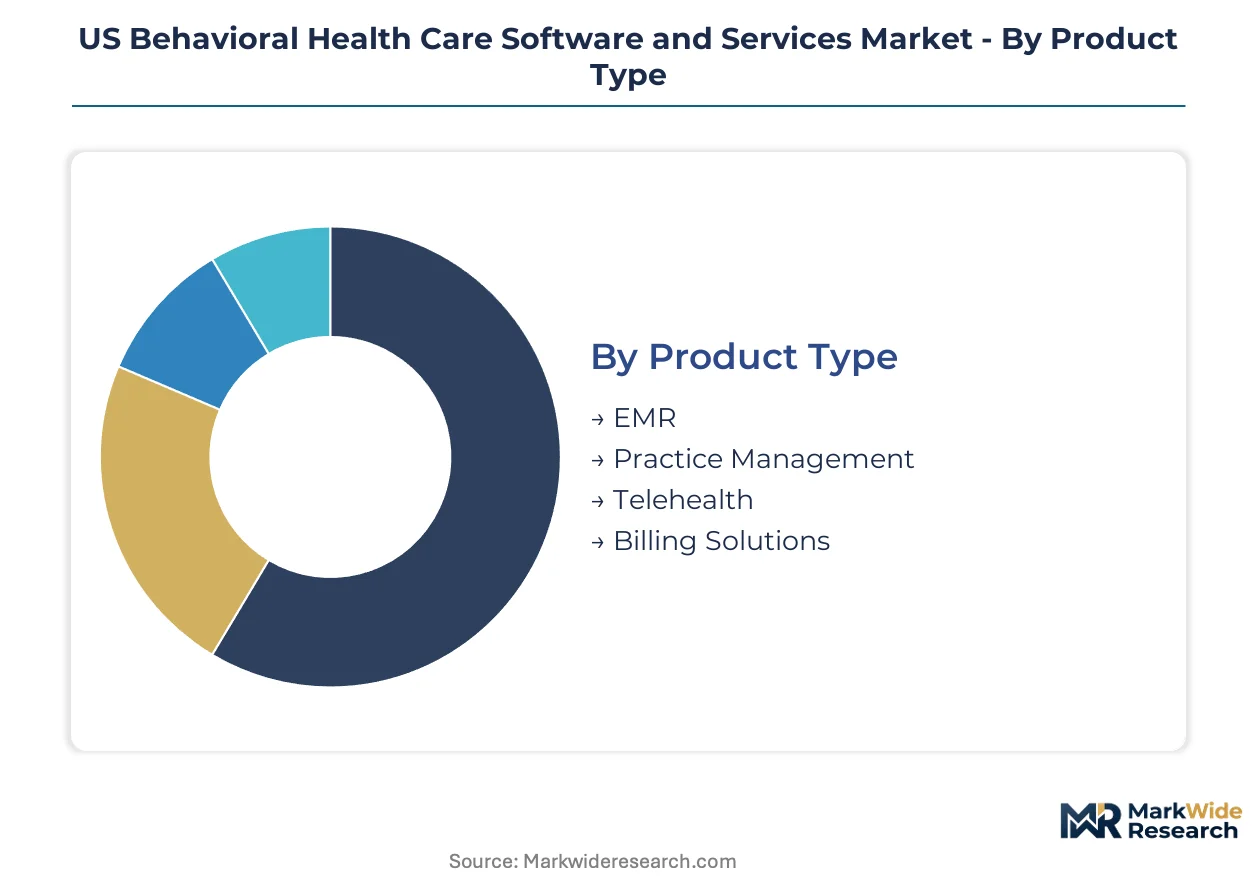
Segmentation in US behavioral health IT reveals how procurement patterns split between institutional buyers seeking integrated suites and specialized providers demanding modular components. Understanding these divisions exposes where vendor consolidation pressure concentrates versus where best-of-breed solutions retain pricing power.
Product Type:
Technology architecture and clinical workflow integration define how provider organizations evaluate software procurement decisions across functional modules.
- EMR:Psychiatric-specific electronic medical records incorporate structured assessment instruments, medication management tools, and care coordination features absent from general medical EHRs. Demand concentrates in California county mental health plans and Texas Medicaid managed care regions where state mandates require outcome tracking for value-based reimbursement.
- Telehealth:Virtual care platforms embed HIPAA-compliant video, asynchronous messaging, and remote monitoring calibrated for therapeutic relationships. Federally qualified health centers in Medicaid expansion states deploy these most aggressively to extend specialist access into rural service areas where psychiatrist scarcity limits in-person capacity.
- Practice Management:Scheduling, credentialing, and referral tracking systems streamline administrative workflows for high-volume outpatient practices.
- Billing Solutions:Claims scrubbing and prior authorization automation address behavioral health-specific coding complexity including bundled payment rules.
EMR leads on scale; telehealth leads on momentum.
End User:
Organizational scale and funding source create divergent requirements for system customization, implementation support, and ongoing vendor relationship intensity.
- Clinics:Community mental health centers and substance-use treatment facilities operate on thin margins requiring subscription pricing and rapid deployment timelines. These buyers in Texas and California prioritize cloud-native platforms that minimize IT staffing overhead while satisfying state reporting mandates for block grant funding.
- Hospitals:Inpatient psychiatric units and emergency departments demand deep integration with medical EHRs for medication reconciliation and suicide risk protocols. Academic medical centers anchor this segment, driving procurement toward vendors offering robust interoperability with Epic or Cerner installations.
- Private Practices:Solo and group psychiatry practices favor lightweight solutions emphasizing patient portal engagement and automated intake workflows.
- Mental Health Organizations:Nonprofit networks and state-funded agencies require multi-site administration tools and grant compliance reporting.
Hospitals anchor procurement volume; clinics represent the steepest expansion trajectory.
Deployment:
Infrastructure architecture decisions reflect tradeoffs between data control, capital expenditure constraints, and workforce technical capacity across provider settings.
- Cloud-Based:Browser-accessible platforms with automatic updates and elastic scaling eliminate server maintenance burdens for resource-constrained organizations. Rural clinics in Texas Hill Country and California's Central Valley are migrating fastest as legacy client-server systems reach end-of-life without internal IT staff to manage replacements.
- Hybrid:Split configurations keep sensitive records on local servers while exposing scheduling and telehealth modules through cloud interfaces. Large multi-site networks in California's county mental health systems adopt this model to satisfy county-level data sovereignty requirements while enabling centralized telehealth operations.
- On-Premise:Self-hosted installations persist where state contracts mandate physical data location control.
- Client-Server:Legacy two-tier architectures continue in underfunded facilities delaying modernization due to migration cost barriers.
Cloud-based infrastructure commands dominant share; hybrid deployments are gaining share fastest.
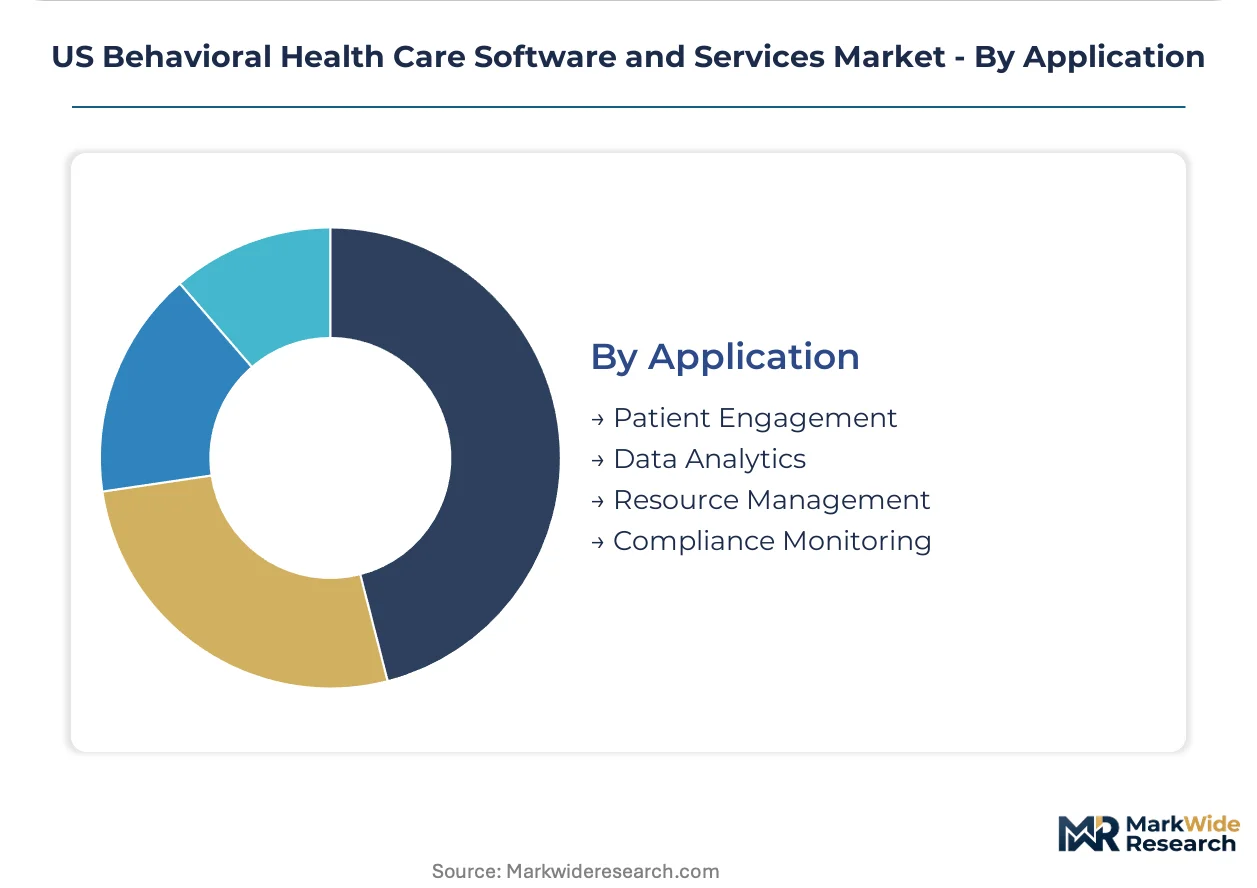
Application:
Functional use cases determine which modules command premium pricing based on direct linkage to reimbursement incentives and regulatory compliance obligations.
- Patient Engagement:Portal-based appointment scheduling, secure messaging, and automated reminders reduce no-show rates while generating data for CMS quality metrics. Federally qualified health centers invest here most heavily because patient activation scores directly influence Health Resources and Services Administration funding allocations.
- Data Analytics:Population health dashboards and predictive risk stratification tools support value-based contract negotiations with Medicaid managed care plans. Texas regional health information exchanges and California's Mental Health Services Act reporting requirements drive demand for cross-provider outcome aggregation.
- Resource Management:Bed availability tracking and workforce scheduling optimize capacity utilization in crisis and residential settings.
- Compliance Monitoring:Automated audit trails and HIPAA security rule documentation reduce OCR exposure for breach incidents.
Patient engagement leads on scale; data analytics leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage across state Medicaid programs is redistributing behavioral health IT procurement toward jurisdictions with the most favorable reimbursement rules and interoperability mandates. California and Texas dominate absolute spending, yet state-level policy variation creates localized competitive advantages for vendors aligned with specific compliance frameworks.
California
County mental health plans and federally qualified health centers drive procurement volume through Mental Health Services Act funding and Medi-Cal expansion. HIPAA enforcement by OCR and state attorney general actions elevate compliance requirements for cloud deployments. Los Angeles County and the Bay Area anchor the state's vendor ecosystem, where Epic Systems installations at academic medical centers influence regional interoperability standards.
Texas
Medicaid managed care organizations and state-funded agencies modernize infrastructure to serve rural populations under STAR+PLUS and STAR Health programs. The 21st Century Cures Act information-blocking provisions accelerate replacement of legacy client-server systems. Dallas-Fort Worth and Houston metropolitan clusters concentrate vendor implementation teams serving the state's fragmented provider network landscape.
New York
Office of Mental Health regulations and Medicaid Redesign Team initiatives compel integrated care documentation across hospital and community settings. Value-based payment models for behavioral health integration reshape software procurement criteria toward outcome measurement tools. New York City anchors demand, with Albany's state agency procurement influencing vendor certification requirements statewide.
Florida
Managed medical assistance programs and substance-use disorder block grants fund platform upgrades at community mental health centers. State Medicaid agency rules on telehealth reimbursement sustain deployment of remote patient engagement modules. Miami-Dade and Tampa Bay metropolitan areas concentrate provider networks pursuing cloud-native architectures to minimize IT staffing overhead.
Illinois
Medicaid expansion and the Illinois Department of Human Services' integrated care mandates drive procurement at federally qualified health centers. CMS innovation center payment models for behavioral health integration reshape software requirements toward population health dashboards. Chicago anchors the state's vendor relationships, with Cook County's health system influencing regional EHR integration standards.
US Behavioral Health Care Software and Services Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue modular specialization and API-native architectures. The vendor base stratifies across three maturity tiers: legacy suite providers with deep EHR integration, cloud-native specialists targeting community mental health workflows, and point-solution vendors capturing discrete functions like telehealth or billing automation. Dominant competitive moves include strategic partnerships with federally qualified health center networks and portfolio diversification into digital therapeutics modules.
Within the integrated suite tier, Epic Systems Corporation and Oracle (Cerner Corporation) anchor hospital and academic medical center procurement through deep interoperability with medical records infrastructure. Netsmart Technologies, Inc. occupies a distinct position serving state-funded agencies and community mental health centers with specialized substance-use and mental health platforms. Qualifacts represents the cloud-native archetype, with architecture designed specifically for behavioral health clinical workflows rather than adapted from general medical templates.
| Leading Market Players |
|---|
| Oracle (Cerner Corporation) |
| Core Solutions, Inc. |
| Epic Systems Corporation |
| Netsmart Technologies, Inc. |
| Qualifacts |
| SimplePractice, LLC |
| TherapyNotes, LLC |
| Holmusk |
| Welligent |
| Others |
Cost & Logistics Intelligence
Behavioral health informaticists concentrated in California's Bay Area and Texas's Dallas-Fort Worth corridor command premium compensation that compresses vendor margins and widens pricing spreads between enterprise-tier and mid-market SaaS subscriptions.
Pricing Analysis
Direct-to-provider SaaS subscriptions bypass traditional distributor markups, with vendors capturing 85-90% of recurring revenue. Three-tier pricing structure across premium, standard, and economy levels segments by integration complexity and outcome-measurement depth. Price differentiation hinges on FHIR certification tier and customization level for state Medicaid reporting. Pricing pressure stems from federally qualified health centers consolidating purchasing through multi-site networks. Community mental health centers exhibit highest price sensitivity; academic medical centers anchored to Epic installations show lowest.
Supply Chain Analysis
Dual-sourcing requirements embedded in HIPAA business associate agreements compel providers to qualify redundant cloud infrastructure vendors. Software development concentrates in the United States, India, and Ireland. Raw material dependencies include AWS and Azure compute capacity, HL7 FHIR middleware libraries, and OCR-compliant encryption modules. Supply chain risk centers on single-source vulnerability for specialized behavioral health assessment content. Distribution runs through direct vendor sales teams and value-added resellers serving state-funded agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement committees prioritize outcome-measurement depth over base functionality, elevating vendors with embedded CMS quality reporting.
For Market Incumbents: Anticipate displacement pressure from cloud-native specialists by hardening API accessibility and pre-integrating digital therapeutics modules. Defensive moves require deepening FHIR connector development and securing exclusive partnerships with Texas Medicaid managed care organizations. Vertical integration into outcome analytics engines represents the critical lever for margin defense. For New Entrants and Emerging Players: Enter via white-space opportunities in rural Texas Hill Country clinics and California Central Valley federally qualified health centers still operating client-server legacy systems. The most penetrable segment comprises substance-use treatment facilities seeking modular telehealth components unbundled from monolithic EHR suites. Go-to-market positioning should emphasize rapid cloud deployment without IT staff requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among cloud-native specialists with proven FHIR interoperability and established state agency relationships. Long-term viability over a multi-year horizon hinges on capturing CMS innovation center payment model contracts before federal rulemaking cycles conclude. Acquisition target archetype: mid-scale platforms with Mental Health Services Act compliance certification in California. The signal to watch is Medicaid managed care RFP language shifting toward mandatory outcome measurement tool integration.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR API Certification | 21st Century Cures Act enforcement compels open data exchange architecture for continued hospital procurement eligibility. |
| Digital Therapeutics Partnership | FDA-cleared prescription software integration creates new reimbursement pathways for substance-use disorder modules. |
| State Medicaid Contract Capture | Texas STAR+PLUS and California Medi-Cal procurement decisions lock in multi-year recurring revenue streams. |
| Outcome Analytics Acquisition | CMS quality metric alignment commands premium pricing from federally qualified health centers seeking HRSA funding protection. |
| Rural Clinic Rapid Deployment | Zero-IT-staff onboarding protocols accelerate displacement of legacy client-server systems in underserved geographies. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with behavioral health IT procurement officers, state Medicaid agency technology directors, federally qualified health center CEOs, and EHR integration specialists with secondary validation against CMS Medicare data, hospital GPO contracts, state Mental Health Services Act expenditure reports, and 21st Century Cures Act federal register filings. Bottom-up vendor revenue triangulation against top-down Medicaid spending estimates anchored market sizing.
Comparable-period anchoring tied projection assumptions to historical procurement cycles preceding and following the public health emergency regulatory flexibilities. Segmentation modeling spanned deployment architecture, organization scale, application function, and state-level Medicaid expansion status across the projection horizon. CAGRs derived from fitted growth curves calibrated to documented platform replacement timelines and telehealth module attach rates. Forecast inputs incorporated OCR audit frequency trends and CMS innovation center payment model adoption curves.
Inputs from state Medicaid procurement databases and vendor revenue disclosures were available through the study window; gaps in private practice segment spending introduce uncertainty bands around the lower tier of the market. Forecasts reflect assumptions regarding permanent telehealth reimbursement parity and continued HIPAA enforcement intensity. Deviation in 21st Century Cures Act information-blocking penalty implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
Behavioral Health Software Market
Mental Health Services
Relationship Counselling Market
Mental Health Services
South Korea Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Mental Health Software Market
Mental Health Services
US Workplace Stress Management Market
Mental Health Services
Schizoaffective Disorders Treatment Market
Mental Health Services
Global Behavioral Health Market
Mental Health Services
Maternal Mental Health Market
Mental Health Services
Postpartum Depression (PPD) Treatment Market
Mental Health Services
Germany Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Spain Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
North America Maternal Mental Health Market
Mental Health Services
Behavioral Health Care Software and Services Market
Mental Health Services
UK Mental Health Apps Market
Mental Health Services
Mental Health Market
Mental Health Services
Global Anxiety Disorder Treatment Market