
 Maternal Mental Health Market | 2026-2036
Maternal Mental Health Market Size, Share, and Industry Trends Forecast 2026-2036
Maternal Mental Health Market Analytics
The capital-intensity divergence between platform-native and clinic-dependent providers is rotating competitive advantage toward scalable technology infrastructure. Sage Therapeutics leverages its pharmaceutical development expertise to anchor prescription-grade neuroactive therapies for postpartum depression. Maven Clinic sustains virtual care networks that integrate OB-GYN coordination with behavioral health coaching across employer contracts.
Maternal mental health encompasses clinical and subclinical psychological conditions occurring during pregnancy and the first postpartum year, including perinatal depression, anxiety disorders, and birth-related trauma, typically assessed through standardized screening instruments such as the Edinburgh Postnatal Depression Scale and managed via psychotherapy, psychopharmacology, or structured peer support. Telehealth delivery mode leads service volume expansion by removing geographic and scheduling barriers that historically limited rural and working-parent access. Medication product type occupies concentrated margin pools where FDA-approved neuroactive therapies command premium pricing against generic counseling alternatives.
The FDA regulates pharmacological interventions through pregnancy exposure registries and risk categorization frameworks, while HIPAA governs data portability across telehealth platforms serving obstetric populations. The EU MDR and GDPR impose parallel conformity and privacy obligations on European digital health entrants seeking cross-border maternity coverage. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring as payors recalibrate covered benefits for perinatal behavioral episodes.
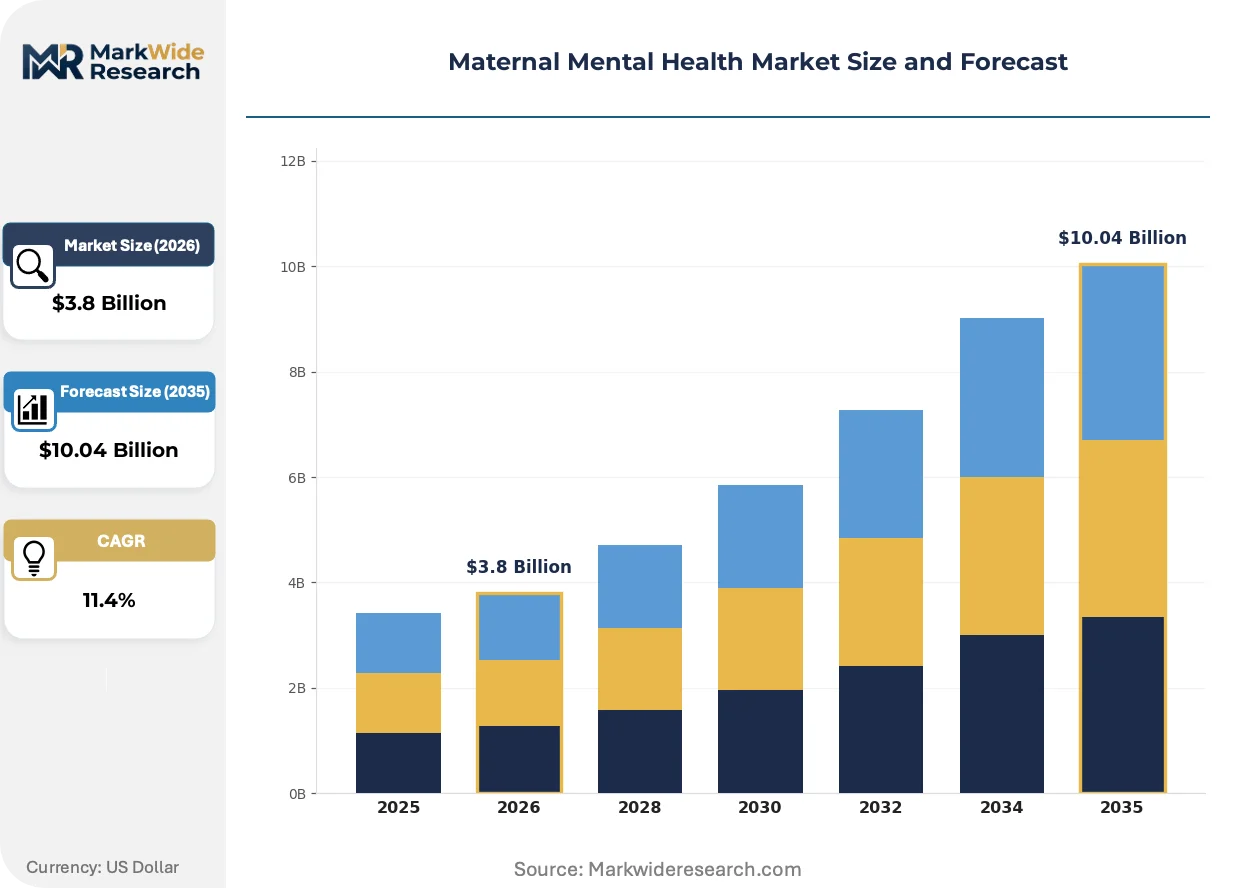
Market Dynamics
Telehealth infrastructure investments are redistributing competitive advantage away from brick-and-mortar clinics toward platform-native providers capable of delivering synchronous behavioral health at scale across dispersed obstetric populations.
Growth Catalysts
- Medicaid Expansion:State-level coverage extensions for perinatal behavioral health services in the United States are removing prior authorization barriers that previously delayed postpartum depression treatment initiation.
- FDA Digital Therapeutics Guidance:The agency's expanded qualification pathways for software-based interventions are enabling prescription-grade mental health apps to secure reimbursement codes alongside traditional psychotherapy.
- Employer Benefits Mandates:Large self-insured employers are adding dedicated maternal mental health carve-outs to reduce maternity-related disability leave costs and improve workforce retention metrics.
Market Restraints
- Reimbursement Fragmentation:Inconsistent CPT code coverage for remote patient monitoring across state Medicaid programs creates administrative complexity that limits telehealth platform expansion.
- Clinical Workforce Concentration:Licensed perinatal psychiatrists and specialized behavioral health coaches cluster in urban metropolitan areas, constraining rural service availability regardless of technology deployment.
- Pharmacological Risk Categorization:FDA pregnancy exposure registries impose lengthy data collection requirements that delay neuroactive therapy approvals for breastfeeding populations.
Strategic Opportunities
- Peer Support Integration:Structured group interventions delivered through asynchronous messaging platforms are capturing subclinical anxiety cases that traditional therapy excludes due to severity thresholds.
- EU MDR Harmonization:The Medical Device Regulation's consolidated conformity assessment process enables cross-border digital health deployment across Germany, France, and the Netherlands under single certification.
- AI-Assisted Triage:Natural language processing tools analyzing patient-reported outcome measures are stratifying risk scores to prioritize high-acuity cases for human clinician intervention.
Industry Challenges
- Credentialing Bottlenecks:Multi-state licensure requirements for telehealth practitioners create operational friction that delays network expansion into new geographic markets.
- EHR Interoperability:Fragmented data exchange standards between behavioral health platforms and obstetric electronic health record systems impede care coordination and episode attribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maternal Mental Health Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Therapy, Counseling, Medication, Support Groups Delivery Mode: In-person, Telehealth, Mobile App, Workshops End User: Pregnant Women, New Mothers, Healthcare Providers, Mental Health Professionals Application: Anxiety Management, Depression Support, Stress Reduction, Psychoeducation |
| Companies Covered | Sage Therapeutics, Maven Clinic, SonderMind, Happify Health, Wildflower Health, Canopie, Therapy Mama, Hims & Hers Health, Postpartum Support International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maternal Mental Health Market Evolving Landscape
Artificial intelligence and asynchronous care modalities are compressing the traditional synchronous therapy model while regulatory frameworks race to accommodate software-based interventions as reimbisable care standards.
Machine learning algorithms analyzing vocal biomarkers and natural language patterns in patient communications are displacing scheduled screening appointments as the primary detection mechanism for perinatal mood disorders. OB-GYN practices in the United States are piloting these tools during routine prenatal visits to flag high-risk patients for immediate behavioral health referral. The technology is displacing reliance on self-reported Edinburgh Postnatal Depression Scale scores that suffer from underreporting due to stigma and time constraints.
The FDA's evolving framework for prescription digital therapeutics is creating distinct qualification pathways that separate clinically validated software from wellness applications. Developers must now demonstrate randomized controlled trial evidence comparable to pharmacological interventions to secure designated status. Postpartum depression digital therapeutics face the steepest evidentiary requirements given the vulnerable population and concurrent breastfeeding considerations.
Large employers and Medicaid managed care organizations are unbundling maternal mental health from general behavioral health contracts to secure specialized networks with demonstrated obstetric integration capabilities. These purchasers are replacing traditional employee assistance program models with dedicated perinatal care navigation services that coordinate across OB-GYN, lactation consulting, and psychiatric functions. The shift is most pronounced in California and New York where regulatory pressure and litigation exposure around maternal mortality have elevated C-suite prioritization of comprehensive benefits design.
Maternal Mental Health Market Segmentation
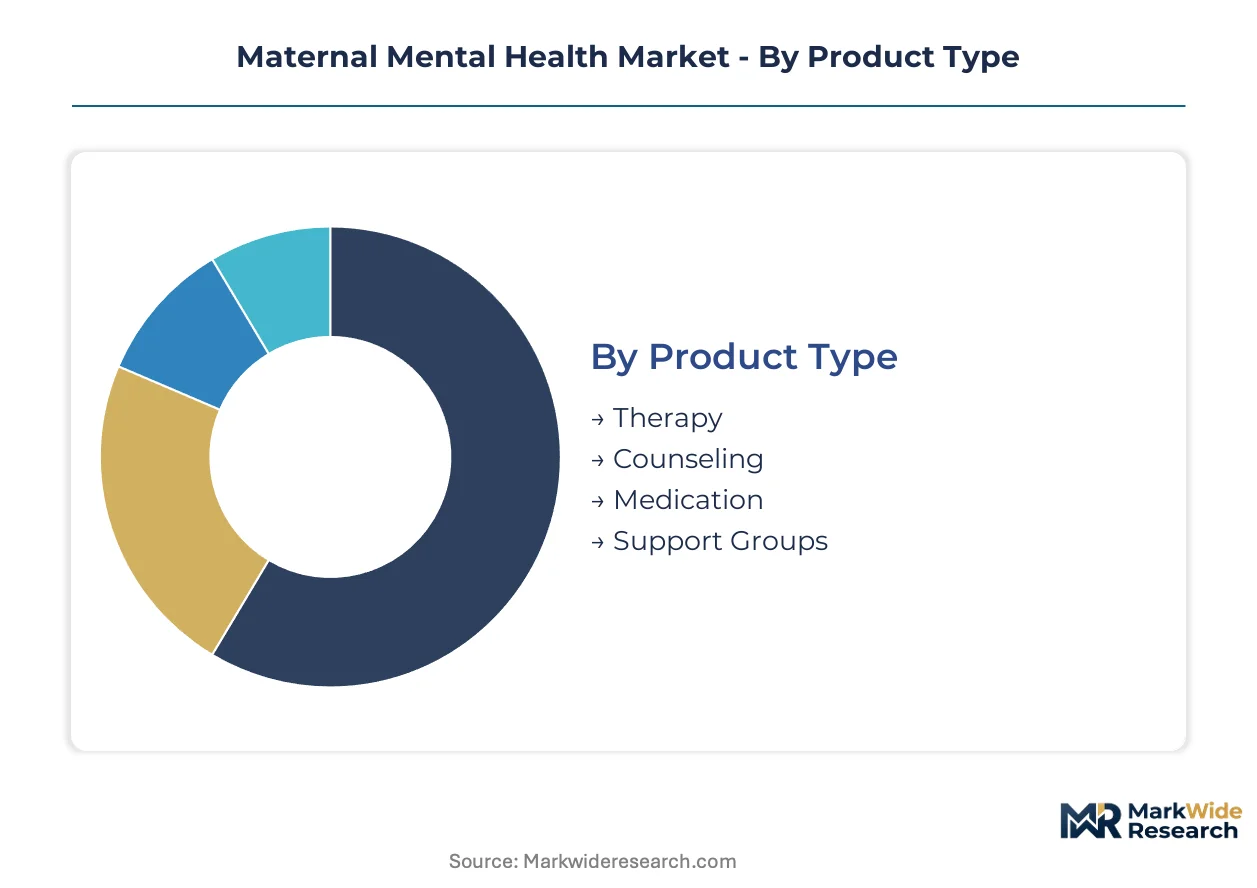
Segmentation in maternal mental health reveals divergent margin structures and reimbursement pathways. Therapy and telehealth combinations command premium positioning through employer contracts, while medication segments face FDA pregnancy registry constraints that delay market entry.
Product Type:
Product flows split between reimbursed clinical services and out-of-pocket wellness purchases, with prescription-grade interventions requiring separate FDA qualification pathways from supportive counseling models.
- Medication:Neuroactive therapies for postpartum depression require FDA pregnancy exposure registry data and lactation safety profiles before formulary inclusion. Sage Therapeutics' brexanolone established the reimbursement precedent for intravenous infusion protocols in hospital outpatient settings.
- Therapy:Structured psychotherapy delivered through licensed clinicians generates recurring revenue via per-session billing codes. Demand concentrates in employer-sponsored benefit plans where maternity-related disability reduction justifies carve-out spending.
- Counseling:Non-clinical behavioral coaching addresses subclinical anxiety through lower-cost practitioner tiers.
- Support Groups:Peer-facilitated interventions capture mild symptom presentations excluded from formal diagnosis thresholds.
Therapy dominates installed base through established CPT code recognition. Medication is where expansion concentrates as novel neuroactive formulations advance through FDA review.
Delivery Mode:
Channel economics favor asynchronous and remote modalities that eliminate geographic constraints on specialized perinatal workforce availability.
- Telehealth:Synchronous video platforms integrate OB-GYN warm handoffs with behavioral health intake, removing transportation and childcare barriers that previously limited rural and working-parent access. Medicaid expansion in states like California and New York has removed prior authorization requirements for perinatal telehealth visits.
- Mobile App:Prescription digital therapeutics pursuing FDA qualification require randomized controlled trial evidence comparable to pharmacological interventions. The FDA's expanded guidance creates distinct reimbursement pathways separating clinically validated software from wellness applications.
- In-person:Brick-and-mortar delivery concentrates in urban metropolitan clusters where perinatal psychiatrists maintain practices.
- Workshops:Group-based psychoeducation serves employer wellness programs seeking scalable preventive interventions.
Telehealth dominates installed base through pandemic-accelerated infrastructure investment. Mobile App is climbing the fastest as FDA digital therapeutic frameworks mature and employers seek lower-cost alternatives to synchronous clinical delivery.
End User:
Customer segmentation reflects divergent purchasing authority, with individual patients accessing services through insurance intermediaries while healthcare providers control referral pathways.
- Pregnant Women:Antenatal anxiety screening through Edinburgh Postnatal Depression Scale administration in OB-GYN practices creates the primary demand entry point. Machine learning tools analyzing vocal biomarkers during routine prenatal visits are displacing scheduled screening appointments as the detection mechanism.
- New Mothers:Postpartum depression episodes drive the highest acuity service consumption, with Medicaid expansion extending coverage through 12 months postpartum in multiple states.
- Healthcare Providers:OB-GYN practices purchase care coordination platforms that integrate behavioral health warm handoffs into obstetric workflows.
- Mental Health Professionals:Licensed perinatal psychiatrists and specialized behavioral health coaches cluster in urban metropolitan areas, constraining supply regardless of technology deployment.
New Mothers dominate installed base through postpartum episode severity and Medicaid eligibility extensions. Pregnant Women is where expansion concentrates as early detection technologies embed in routine prenatal workflows.
Application:
Application segmentation tracks symptom severity thresholds and corresponding reimbursement eligibility, with clinical diagnoses qualifying for insurance coverage while subclinical presentations rely on employer wellness or out-of-pocket payment.
- Depression Support:Postpartum depression commands the most concentrated clinical resources and pharmaceutical development investment. FDA-approved neuroactive therapies command premium pricing against generic counseling alternatives in this segment.
- Anxiety Management:Perinatal anxiety disorders often co-occur with depression but receive less dedicated pharmacological development, creating opportunity for digital therapeutic and peer support models that address subclinical presentations excluded from traditional therapy severity thresholds.
- Stress Reduction:General prenatal stress falls below clinical diagnosis thresholds, positioning this application for employer wellness and direct-to-consumer channels.
- Psychoeducation:Information delivery and coping skill instruction serves preventive benefit designs seeking to reduce downstream clinical episode incidence.
Depression Support dominates installed base through established diagnostic criteria and pharmacological intervention pathways. Anxiety Management is gaining share fastest as structured group interventions through asynchronous platforms capture cases below clinical severity thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Employer-sponsored benefits in the United States absorb premium pricing with minimal elasticity, while Medicaid-dependent populations in emerging markets face acute price sensitivity that constrains service design.
United States
California and New York drive demand through employer mandates and Medicaid expansion extending postpartum coverage to twelve months. FDA digital therapeutics guidance accelerates qualification pathways for prescription-grade mental health applications. Boston's biotech corridor hosts Sage Therapeutics' neuroactive therapy development for postpartum depression.
Germany
EU MDR harmonization enables cross-border digital health deployment under single certification across German-speaking markets. The country's national pharmaceutical regulator, BfArM, evaluates digital health applications for statutory insurance reimbursement eligibility. Berlin's health tech cluster concentrates telehealth platform development serving perinatal populations across the DACH region.
United Kingdom
NHS Long Term Plan commitments to perinatal mental health services expand screening coverage in maternity pathways. MHRA aligns with FDA digital therapeutics frameworks to streamline software-based intervention approvals. London's digital health ecosystem produces asynchronous care platforms targeting subclinical anxiety presentations.
Canada
Provincial health authority procurement of maternal mental health services varies across Ontario, British Columbia, and Quebec reimbursement schedules. Health Canada maintains pregnancy exposure registries for neuroactive therapy safety profiling in breastfeeding populations. Toronto's health innovation district pilots AI-assisted triage tools for obstetric behavioral health referrals.
Australia
Medicare Benefits Schedule updates incorporate telehealth psychology items for perinatal populations following pandemic-era temporary provisions. TGA evaluates digital therapeutic submissions against pharmaceutical-equivalent evidentiary standards. Melbourne's medical research institutes conduct longitudinal cohort studies on postpartum depression detection technologies.
Maternal Mental Health Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with platform-native providers commanding valuation premiums over clinic-dependent operators. The upper tier consolidates around pharmaceutical developers with FDA-approved neuroactive therapies and virtual care networks with employer contract scale. Strategic archetypes include prescription-grade therapy developers, asynchronous coaching platforms, and OB-GYN-integrated care navigators. Competitive moves concentrate on strategic partnerships with obstetric practices and portfolio diversification into adjacent reproductive health services.
Within the pharmaceutical development archetype, Sage Therapeutics exemplifies prescription-grade neuroactive therapy positioning through its intravenous infusion protocols. Maven Clinic and Happify Health occupy complementary positions across the synchronous-to-asynchronous care spectrum, with the former anchoring employer-sponsored virtual networks and the latter pursuing FDA digital therapeutic designation for software-based interventions. These three entities represent the dominant competitive vectors reshaping reimbursement access and care delivery standards.
| Leading Market Players |
|---|
| Sage Therapeutics |
| Maven Clinic |
| SonderMind |
| Happify Health |
| Wildflower Health |
| Canopie |
| Therapy Mama |
| Hims & Hers Health |
| Postpartum Support International |
| Others |
Value Network & Pricing Analysis
Platform scale economies in telehealth infrastructure are compressing per-session delivery costs while concentrating pricing power among network-native providers capable of cross-state clinician deployment. This scale dynamic establishes price floors that clinic-dependent operators struggle to match, particularly as Medicaid expansion in states like California and New York removes prior authorization barriers that previously sustained premium pricing for in-person care.
Pricing Analysis
After-sales revenue through employer-sponsored benefit carve-outs and extended Medicaid reimbursement contracts drives lifetime value capture for maternal mental health platforms. Subscription-tiered pricing stratifies across premium synchronous therapy, standard asynchronous coaching, and economy peer-support tiers, with FDA digital therapeutic certification commanding material premiums against wellness-application alternatives. Pricing pressure stems from reimbursement code fragmentation across state Medicaid programs, compressing margins for remote patient monitoring services. Employer purchasers exhibit the lowest price sensitivity given maternity-related disability cost reduction justifications, while individual cash-pay patients in non-expansion states face acute affordability constraints.
Supply Chain Analysis
The United States anchors specialized perinatal psychiatrist and behavioral health coach supply, with concentration in urban metropolitan clusters across California, New York, and Massachusetts. Canada and the United Kingdom feed supplementary clinical workforce through credentialing reciprocity agreements and telehealth licensure compacts. Platform infrastructure draws from cloud computing providers and HIPAA-compliant data architecture vendors, with machine learning triage tools resting on natural language processing componentry. Single-source vulnerability concentrates in multi-state clinician licensure bottlenecks that delay network expansion. Distribution runs through employer benefits administrators, Medicaid managed care organizations, and OB-GYN practice care coordination platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Maternal mental health represents a platform-economics inflection where EHR interoperability standards and FDA digital therapeutic frameworks are rewiring competitive moats around data integration capabilities rather than clinical credential accumulation alone.
For Market Incumbents: Fortify network effects by deepening OB-GYN EHR integration through dedicated API development, while securing multi-state clinician licensure compacts to preempt emerging telehealth platforms from achieving comparable geographic coverage. The threat of AI-assisted triage tools displacing synchronous therapy volumes necessitates investment in proprietary machine learning risk stratification to maintain episode attribution control. For New Entrants and Emerging Players: Differentiate on asynchronous peer support models targeting subclinical anxiety presentations excluded from traditional therapy severity thresholds, where reimbursement code gaps create white-space pricing flexibility. Rural Medicaid expansion states offer the most penetrable geography given incumbent workforce concentration in urban corridors. A direct-to-employer go-to-market angle bypasses credentialing bottlenecks through carved-out benefit contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-native providers with demonstrated FDA digital therapeutic qualification pathways and employer contract scale over clinic-dependent operators with limited technology infrastructure. Long-term viability hinges on reimbursement code consolidation for remote patient monitoring across state Medicaid programs. The signal to watch is CMS guidance on perinatal behavioral health episode attribution methodology.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Digital Therapeutic Submission | Secures prescription-grade reimbursement codes alongside Sage Therapeutics' neuroactive therapy precedents. |
| OB-GYN EHR Integration Partnership | Embeds behavioral health warm handoffs into routine prenatal workflows across Maven Clinic's employer networks. |
| Multi-State Licensure Compact Expansion | Removes credentialing friction delaying telehealth platform geographic network scaling. |
| AI-Assisted Triage Development | Prioritizes high-acuity cases for human clinician intervention through natural language processing analysis. |
| Medicaid Managed Care Contracting | Captures postpartum coverage extensions through twelve-month eligibility windows in expansion states. |
Research Methodology
Cross-validation between primary interviews with perinatal psychiatrists, OB-GYN practice administrators, employer benefits directors, and Medicaid managed care executives anchors the qualitative findings against secondary validation. FDA digital therapeutics guidance documents, CMS reimbursement code updates, state Medicaid expansion filings, and employer benefits carve-out contract disclosures provide regulatory and procurement context. Bottom-up service volume estimates triangulate against top-down addressable population calculations across the analysis window.
Sensitivity analysis around Medicaid expansion pace and FDA digital therapeutic approval timelines shapes the forecast framework. Segmentation dimensions include product type, delivery mode, end user, and application severity threshold, with regional regulatory cluster variations modeled separately. CAGRs derive from installed base growth rates adjusted for reimbursement access elasticity and technology substitution effects. Workforce supply constraints and EHR interoperability adoption curves constitute key industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained Medicaid expansion, FDA qualification pathway stability, or employer benefits mandate continuity would require recalibration. Forecasts reflect documented assumptions regarding telehealth infrastructure investment pace and perinatal workforce licensure reform. Recalibration cycles align with material shifts in CMS reimbursement guidance and state-level behavioral health parity enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
Mental Health Market
Mental Health Services
Panic Attack Treatment Market
Mental Health Services
Agoraphobia Treatment Market
Mental Health Services
North America Maternal Mental Health Market
Mental Health Services
Global Mental Health Care Software and Services Market
Mental Health Services
UK Mental Health Apps Market
Mental Health Services
US Workplace Stress Management Market
Mental Health Services
Schizoaffective Disorders Treatment Market
Mental Health Services
Post-Traumatic Stress Disorder (PTSD) Market
Mental Health Services
Obsessive-Compulsive Disorder Market
Mental Health Services
Behavioral Health Software Market
Mental Health Services
South Korea Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Behavioral Health Care Software and Services Market
Mental Health Services
China Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Global Behavioral Health Market
Mental Health Services
Spain Post-Traumatic Stress Disorder Treatment Market