
 Robotic Process Automation (RPA) Market | 2026-2036
Robotic Process Automation (RPA) Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Process Automation (RPA) Market Analysis
Subscription-based orchestration layers is decoupling perpetual license economics from customer value capture in the RPA sector. UiPath leverages cloud-native delivery to extend its footprint across mid-market accounts. Automation Anywhere sustains competitive pressure through native AI integration within its platform architecture. Microsoft anchors enterprise adoption by embedding RPA capabilities directly into Office 365 and Dynamics workflows.
Robotic Process Automation denotes software technology that deploys configurable software robots to emulate human interactions with digital systems, executing rule-based tasks through user interface manipulation and API-level integration at throughput rates exceeding manual processing by orders of magnitude. Cloud-based deployment now leads segment growth as organizations prioritize elastic scaling over fixed infrastructure commitments, while managed services commands premium pricing by absorbing operational complexity from buyer IT organizations. Banking and BFSI verticals concentrate near-term demand as regulatory reporting and anti-money laundering workflows drive bot density.
The EU AI Act imposes conformity assessment obligations on RPA vendors deploying automated decision systems in European jurisdictions, while the SEC in the United States scrutinizes bot-generated financial disclosures for material accuracy. ISO 27001 certification shapes procurement eligibility for RPA platforms handling sensitive customer data across regulated industries. Stakeholders must monitor how evolving algorithmic accountability standards will redraw competitive barriers between compliant and non-compliant platform architectures.
Market Dynamics
Cloud-native orchestration architectures are compressing deployment cycles from quarters to weeks, forcing incumbent vendors to abandon perpetual license models or cede mid-market accounts to agile competitors. This structural shift rewrites how value capture distributes across the RPA value chain.
Growth Catalysts
- EU AI Act compliance mandates:European banking and insurance regulators now require documented audit trails for automated decision systems, compelling institutions to upgrade from basic screen-scraping tools to enterprise-grade platforms with embedded governance.
- Anti-money laundering workflow density:BFSI institutions in the United States face escalating transaction monitoring volumes that exceed human processing capacity, driving bot deployment for suspicious activity report generation and regulatory filing automation.
- API-first integration architectures:Modern enterprise software stacks expose native interfaces that reduce bot fragility, lowering maintenance overhead and expanding viable use cases beyond legacy green-screen environments.
Market Restraints
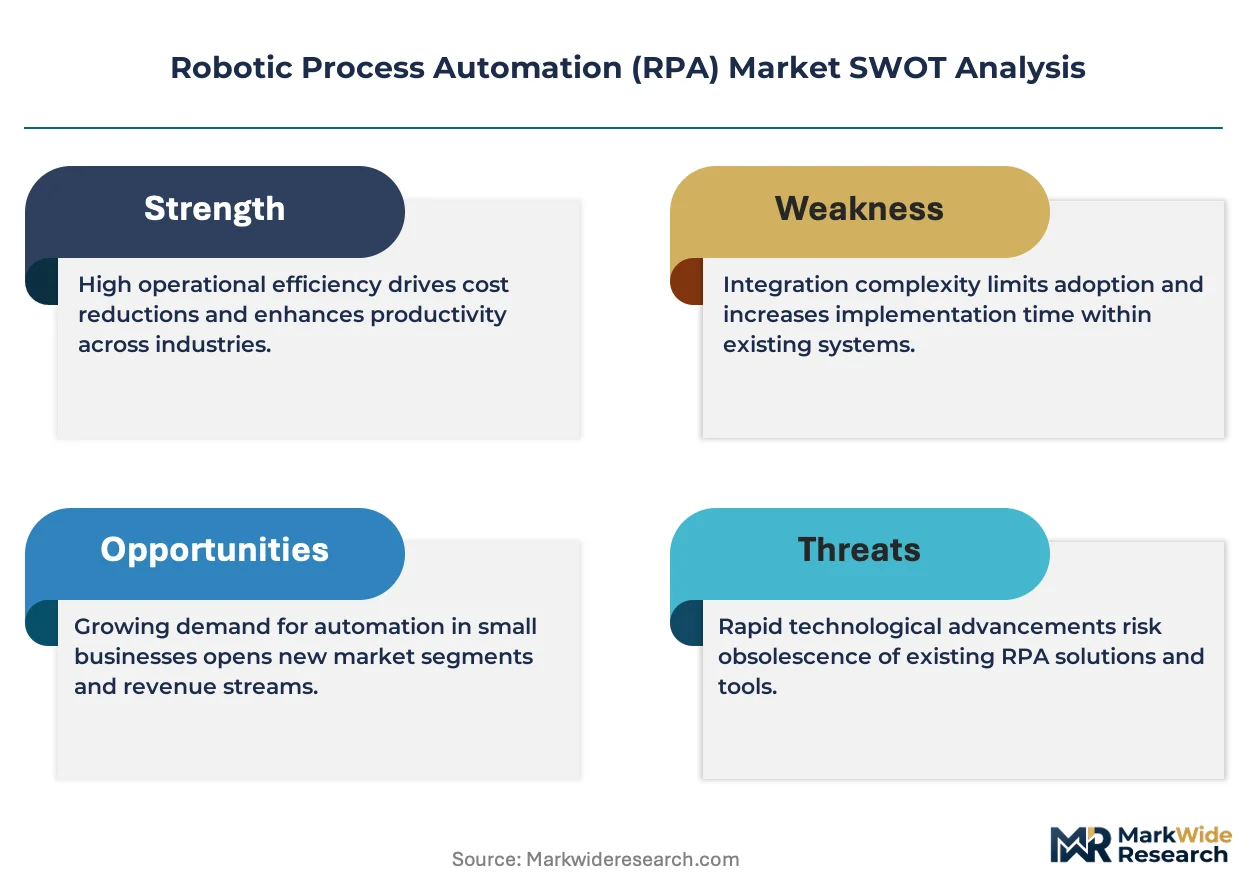
- Specialized talent scarcity:RPA implementation requires hybrid skill sets combining process engineering, API integration, and compliance documentation, with qualified practitioners commanding premium compensation that inflates total cost of ownership.
- Cloud infrastructure concentration:Major orchestration platforms depend on hyperscale compute providers concentrated in limited geographic zones, creating latency and data residency constraints for regulated workloads.
- Process standardization deficits:Many target workflows lack documented procedures or vary across business units, forcing expensive customization that erodes the unit economics driving automation business cases.
Strategic Opportunities
- Process mining convergence:Integration of RPA with process discovery tools that map actual versus documented workflows creates bundled value propositions that justify platform premiums over point solutions.
- Small and medium enterprise penetration:Pre-configured industry templates and consumption-based pricing models open addressable markets previously excluded by implementation complexity and upfront licensing costs.
- SEC disclosure automation:Regulatory pressure on financial statement accuracy and timeliness creates demand for bots that extract, validate, and format quantitative data for EDGAR filings and investor communications.
Industry Challenges
- Bot maintenance backlog accumulation:Interface changes in target applications trigger cascading failures requiring continuous monitoring and remediation, consuming resources planned for new automation deployment.
- ISO 27001 certification timelines:Procurement eligibility for sensitive data handling requires extensive documentation and third-party audit cycles that delay revenue recognition and extend sales cycles.
- Shadow IT proliferation:Business units deploying unsanctioned automation tools create governance gaps and integration debt that central IT must later reconcile at elevated cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Process Automation (RPA) Market |
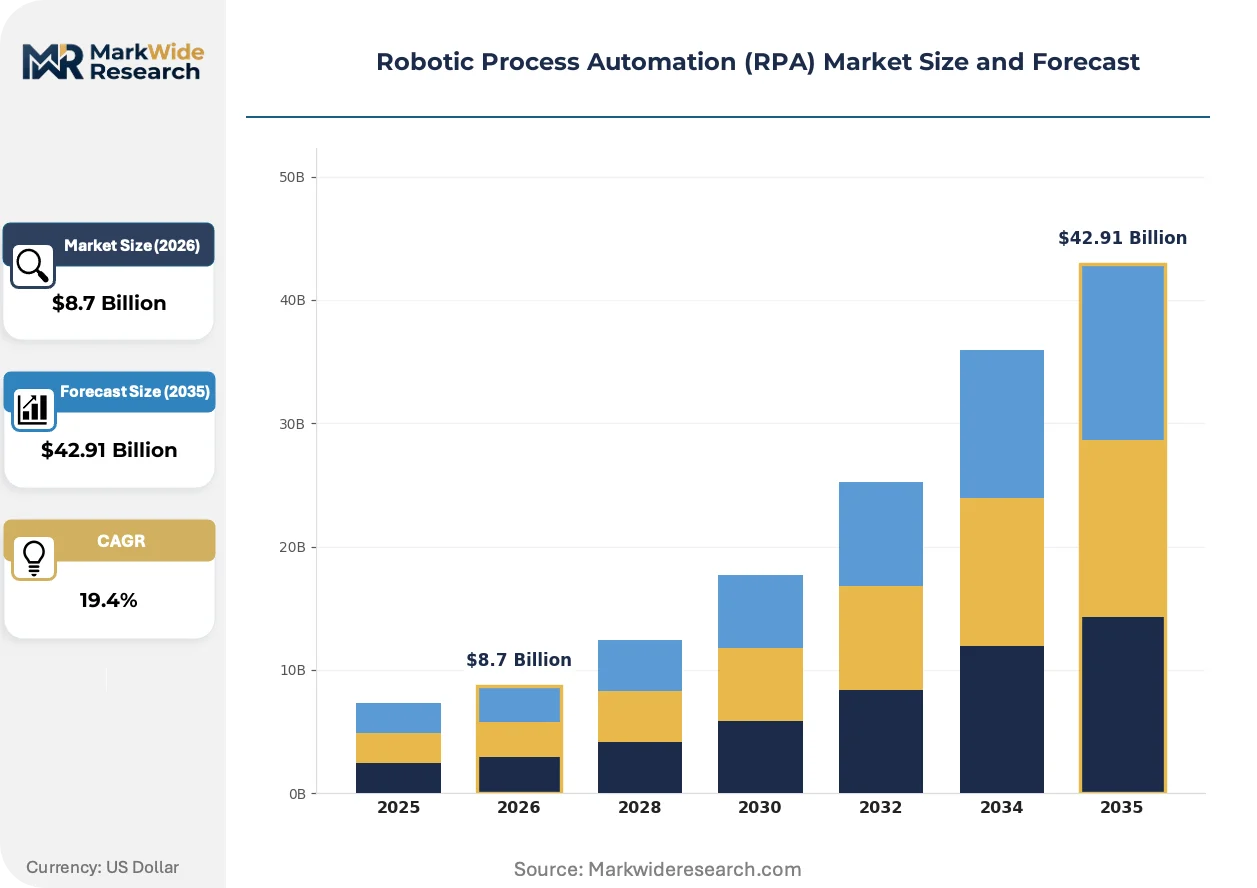
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-premises, Cloud-based, Hybrid, Managed Services Solution: Task Automation, Data Integration, Workflow Automation, Analytics End User: Banking, Healthcare, Retail, Telecom Industry Vertical: Manufacturing, BFSI, Government, Travel |
| Companies Covered | UiPath, Automation Anywhere, SS&C Blue Prism, Microsoft, Pegasystems, NICE, IBM, SAP, Kofax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Process Automation (RPA) Market Emerging Trajectories
Agentic AI architectures are dissolving the boundary between deterministic rule execution and adaptive decision-making, transforming RPA from scripted task replication toward autonomous workflow optimization. This evolution demands reconceptualized governance frameworks and reskilling investments.
Intelligent document processing is decentralizing data extraction from centralized capture centers to edge workflows within business operations. Insurance claims processors and healthcare revenue cycle teams deploy computer vision models that classify, extract, and validate unstructured documents without human handoff. This compression eliminates queue-based processing delays and reduces per-transaction costs by removing offshore labor arbitrage dependencies.
The EU AI Act's conformity assessment obligations are forcing vendors to engineer explainability features and human oversight mechanisms directly into platform architectures. Automated decision systems deployed in European jurisdictions must now document logic pathways and enable intervention points that interrupt bot execution. Banking and credit scoring applications face the steepest compliance burden, with institutions conducting gap analyses against existing bot portfolios to identify retrofit requirements.
Consumption-based commercial models are displacing traditional seat licensing as buyers demand alignment between expenditure and realized automation hours. Mid-market procurement teams negotiate contracts tied to actual bot execution minutes rather than provisioned software entitlements. This shift concentrates in United States technology and professional services sectors where finance organizations scrutinize SaaS spend efficiency and prefer operational expenditure classification over capital deployment.
Robotic Process Automation (RPA) Market Segmentation
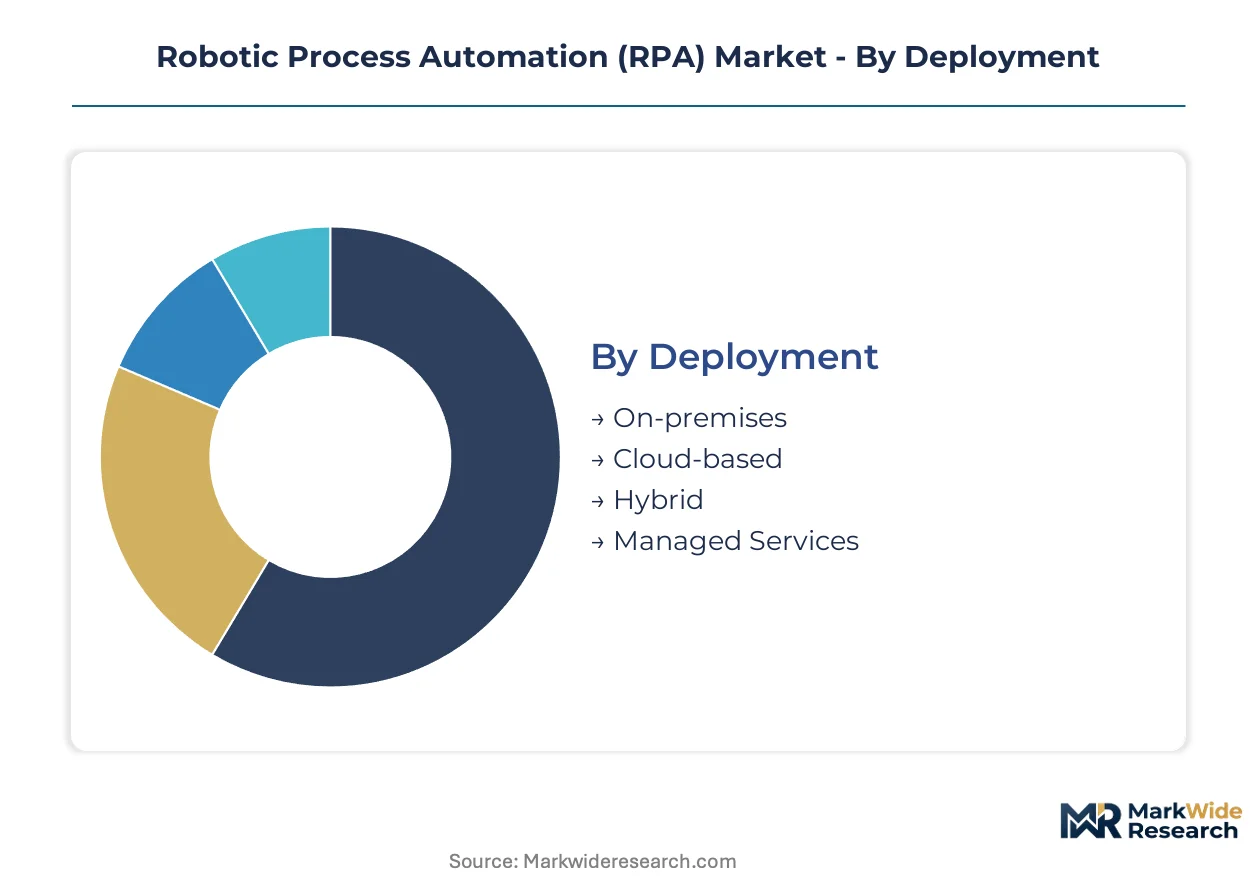
Segmentation in the RPA market exposes how deployment architectures, solution capabilities, and vertical applications create divergent value capture profiles. Buyers select configurations based on data residency constraints, process complexity, and compliance exposure rather than generic automation potential.
Deployment:
Organizations replace legacy on-premises installations with elastic orchestration layers that eliminate fixed infrastructure commitments and compress upgrade cycles from years to quarters.
- On-premises:Installed within buyer-controlled data centers with direct hardware governance. Financial institutions in Germany and Switzerland maintain these deployments for core banking workflows subject to strict data localization mandates from national regulators.
- Cloud-based:Delivered through multi-tenant SaaS architectures with automatic feature updates. United States technology firms and professional services organizations drive demand here, prioritizing consumption-based pricing alignment with operational expenditure budgets.
- Hybrid:Combines on-premises control for sensitive processes with cloud elasticity for variable workloads. European manufacturers adopt this architecture to isolate proprietary production data while leveraging cloud analytics for supply chain optimization.
- Managed Services:Third-party providers assume full operational responsibility including monitoring, patching, and scaling. Healthcare systems in the United States contract these arrangements to offset internal talent scarcity in bot maintenance and compliance documentation.
Volume placements concentrate in Cloud-based configurations; the faster expansion belongs to Managed Services as buyers outsource operational complexity.
Solution:
Cost tier differentiation separates point solutions addressing narrow pain points from integrated platforms commanding premium pricing through bundled capability stacks.
- Task Automation:Executes discrete, rule-based activities such as data entry, form population, and file transfers. Retail back-office teams in the United States deploy these for invoice processing and inventory reconciliation where process standardization permits simple scripting.
- Workflow Automation:Orchestrates multi-step business processes across systems and departments. Banking institutions prioritize this tier for loan origination pipelines requiring sequential validation, approval routing, and regulatory documentation generation.
- Data Integration:Synchronizes information across disparate applications through API connectors and middleware. Telecom operators leverage these capabilities to unify customer records across billing, service provisioning, and support platforms.
- Analytics:Captures bot execution metrics and process performance indicators for optimization. BFSI compliance teams in the United States utilize embedded analytics to generate audit trails demanded by SEC disclosure requirements.
Revenue concentration sits with Workflow Automation; Analytics solutions are climbing the fastest as governance mandates intensify documentation burdens.
End User:
Application maturity varies sharply across sectors, with early adopters now facing maintenance backlogs while laggards pursue first-wave deployments with pre-configured templates.
- Banking:Deploys bots for anti-money laundering surveillance, regulatory reporting, and customer onboarding. United States institutions concentrate investment here as transaction monitoring volumes exceed human processing capacity and FinCEN enforcement intensifies.
- Healthcare:Automates revenue cycle management, claims processing, and patient data reconciliation. Revenue cycle teams deploy computer vision models that extract and validate unstructured documents without human handoff, eliminating offshore labor dependencies.
- Retail:Addresses inventory management, supplier reconciliation, and customer service routing. Mid-market retailers adopt consumption-based pricing models that align expenditure with seasonal demand fluctuations.
- Telecom:Focuses on network provisioning, billing dispute resolution, and churn prediction workflows. European operators face EU AI Act compliance obligations for automated decision systems affecting customer credit terms.
Deployment density peaks in Banking; Healthcare presents the steepest expansion trajectory as reimbursement complexity drives automation investment.
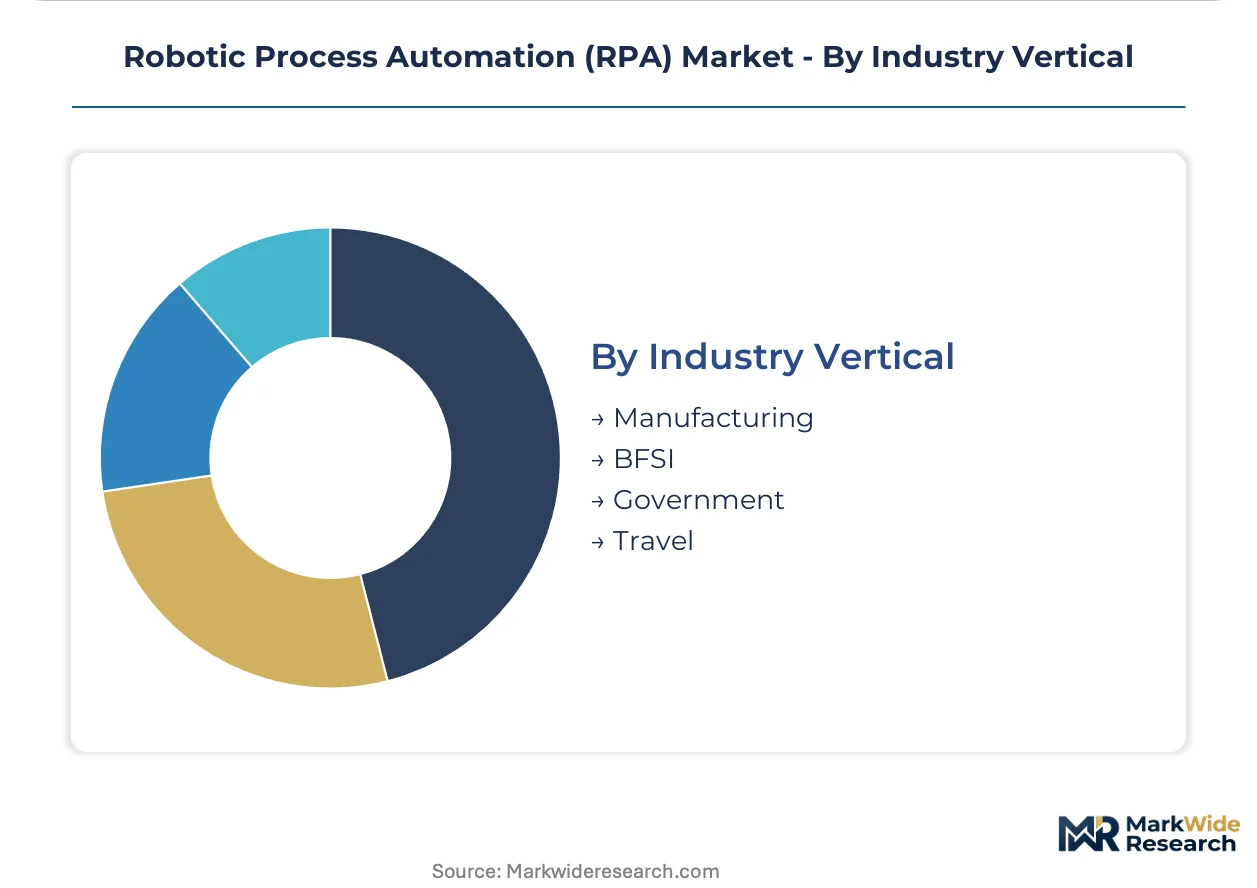
Industry Vertical:
Customer type segmentation reveals how procurement authority and implementation resources distribute across centralized IT functions versus line-of-business budgets.
- BFSI:Concentrates the most sophisticated governance requirements and largest bot fleets. EU AI Act conformity assessments force European institutions to retrofit explainability features and human oversight mechanisms into existing automated decision systems.
- Manufacturing:Applies RPA to purchase order processing, supplier quality documentation, and production scheduling. German automotive suppliers integrate process mining tools with automation platforms to map actual versus documented workflows before bot deployment.
- Government:Procures through lengthy certification cycles with extensive documentation requirements. ISO 27001 certification shapes eligibility for platforms handling citizen data, extending sales cycles and delaying revenue recognition.
- Travel:Automates booking modifications, loyalty program administration, and disruption management. United States airlines and hospitality chains prioritize cloud-native solutions that scale with demand volatility.
Investment scale dominates in BFSI; Manufacturing is gaining share fastest as Industry 4.0 integration creates bundled automation opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of RPA platforms concentrates among US-headquartered vendors, while consumption spreads across banking and insurance institutions in multiple jurisdictions seeking compliance-grade automation infrastructure.
United States
Enterprise IT budgets for cognitive automation continue expanding across financial services and healthcare sectors. SEC scrutiny of bot-generated financial disclosures intensifies documentation requirements for automated reporting systems. New York and Chicago banking clusters deploy dense bot fleets for anti-money laundering surveillance and loan processing workflows.
Germany
Automotive suppliers and industrial manufacturers drive demand for process mining-integrated automation platforms. National data localization mandates from financial regulators preserve on-premises deployment preferences for core banking workflows. Munich and Frankfurt insurance hubs retrofit existing bot portfolios to meet emerging algorithmic accountability standards.
United Kingdom
Professional services firms and fintech operators prioritize cloud-native orchestration with consumption-based pricing alignment. Post-Brexit regulatory divergence creates dual compliance obligations for automated decision systems serving EU and UK markets. London's financial district concentrates vendor competition for workflow automation contracts.
Japan
Manufacturing conglomerates deploy RPA for supply chain documentation and quality certification processes. METI guidelines on AI governance shape procurement criteria for automated systems handling sensitive operational data. Tokyo and Osaka enterprise clusters favor hybrid deployment architectures balancing data control with cloud analytics capabilities.
India
IT services providers and banking institutions scale bot deployments for back-office transformation and regulatory reporting automation. RBI guidelines on digital lending and data governance influence platform selection for financial sector implementations. Bangalore and Mumbai technology corridors host delivery centers executing RPA implementation for multinational clients.
Robotic Process Automation (RPA) Market Vendor Landscape
Top-tier vendors anchor enterprise-grade orchestration platforms, while mid-market specialists compete on implementation velocity and industry-specific templates. The vendor landscape organizes into three strategic tiers: cloud-native platform providers, legacy enterprise software integrators, and vertical-focused automation boutiques. Competitive intensity manifests through native AI capability integration and consumption-based commercial model adoption rather than pure price competition.
Among platform-native providers, UiPath and Automation Anywhere exemplify the cloud-first archetype with elastic deployment architectures, while Microsoft occupies a position leveraging existing enterprise software relationships. These three anchors demonstrate how distribution through familiar procurement channels shapes competitive positioning more than feature differentiation alone.
| Leading Market Players |
|---|
| UiPath |
| Automation Anywhere |
| SS&C Blue Prism |
| Microsoft |
| Pegasystems |
| NICE |
| IBM |
| SAP |
| Kofax |
| Others |
Supply Flow & Price Mechanics
Consumption-based procurement preferences among United States mid-market enterprises are compressing vendor margins and forcing platform providers to restructure delivery economics around operational expenditure classification rather than perpetual license recognition.
Pricing Analysis
Margin tightening in cloud-native tiers reflects hyperscaler infrastructure passthrough costs and consumption-based contract renegotiations. Three-tier pricing structure across enterprise, professional, and developer levels separates ISO 27001-certified governance bundles from basic orchestration entitlements. Pricing pressure stems from Microsoft embedding RPA capabilities into existing Office 365 subscriptions at marginal incremental cost. Mid-market healthcare and retail buyers exhibit highest price sensitivity, while BFSI institutions prioritize audit-grade documentation over per-seat economics.
Supply Chain Analysis
Hyperscale compute capacity rests on concentrated infrastructure footprints in the United States, Ireland, and Singapore. Platform engineering talent, GPU clusters for AI model training, and compliance documentation services constitute critical input dependencies. Single-source vulnerability in cloud infrastructure concentration creates latency and data residency constraints for regulated European workloads. Distribution runs through direct enterprise sales organizations, systems integrator partnerships, and cloud marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized RPA engineering talent scarcity props platform pricing and extends implementation timelines, creating supply-constrained conditions that favor vendors with established delivery capacity.
For Market Incumbents: To counter Microsoft's embedded distribution advantage through Office 365, deepen native AI integration investments and secure exclusive systems integrator partnerships with tier-one consultancies. Prioritize ISO 27701 privacy certification alongside existing ISO 27001 security credentials to maintain procurement eligibility for European BFSI accounts facing EU AI Act conformity deadlines. For New Entrants and Emerging Players: Agentic AI architectures that enable autonomous workflow optimization without deterministic scripting represent the most penetrable wedge against incumbent platform inertia. Target mid-market healthcare revenue cycle automation in the United States, where pre-configured computer vision templates for claims processing address acute labor scarcity. Pursue consumption-based pricing alignment with hospital system operational expenditure budgets as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors vertical-focused automation boutiques with embedded process mining capabilities and established BFSI reference accounts. Long-term viability hinges on differentiation from hyperscaler-embedded alternatives through specialized compliance documentation and industry-specific template libraries. Watch SEC enforcement actions against bot-generated financial disclosure inaccuracies as an inflection indicator for governance-premium platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding RPA into existing enterprise software stacks reduces procurement friction and accelerates time-to-value for Microsoft and SAP. |
| Acquisition of Specialist Firm | Process mining vendors with actual-versus-documented workflow mapping capabilities command premium valuations from orchestration platform acquirers. |
| Strategic Partnership | Exclusive alliances with tier-one systems integrators create defensive moats against hyperscaler-embedded alternatives in competitive BFSI tenders. |
| Product Launch | Agentic AI architectures that dissolve deterministic scripting boundaries differentiate next-generation platforms from legacy screen-scraping tools. |
| Geographic Expansion | Cloud-native delivery enables rapid addressable market extension into India and Southeast Asia without fixed infrastructure commitments. |
Methodological Framework
SEC filings, EU regulatory compliance databases, and hyperscaler capex disclosures formed the secondary backbone, supplemented by primary interviews with RPA platform engineering directors, BFSI compliance officers, healthcare revenue cycle managers, and systems integrator practice leads. Bottom-up triangulation across deployment volume estimates and top-down validation against enterprise IT budget surveys ensured cross-verification of market sizing assumptions.
Historical trendline analysis of cloud infrastructure spending and automation software procurement patterns informed the projection framework across the analysis window. Segmentation modeling incorporated deployment architecture, solution capability tier, end-user vertical, and geographic regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted adoption curves and compliance mandate timing, with AI governance regulation enforcement intensity and API-first enterprise software penetration serving as key forecast inputs.
Several conditions sit outside the modeled scope, including unannounced hyperscaler product launches, abrupt EU AI Act enforcement calibration changes, and unforeseen algorithmic accountability standard expansions beyond automated decision systems. Forecasts reflect documented assumptions about talent scarcity persistence and cloud infrastructure concentration stability. A small set of named triggers—including SEC bot disclosure enforcement actions and ISO 27701 certification adoption rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Cybersecurity in Robotics Market
Robotics and Automation
Surgical Robots Market
Robotics and Automation
Global Soft Robotics Market
Robotics and Automation
Global Programmable Robots Market
Robotics and Automation
Healthcare Companion Robots Market
Robotics and Automation
Robotic Air Purifier Market
Robotics and Automation
Global Adaptive Robotics Market
Robotics and Automation
Household Robots Market
Robotics and Automation
Medical Automation Technologies Market
Robotics and Automation
Robot Coffee Kiosk Market
Robotics and Automation
Disinfectant Robot Market
Robotics and Automation
Deep Sea Robot Market
Robotics and Automation
Global Enterprise Robotic Process Automation Market
Robotics and Automation
Italy Cloud Robotics Market
Robotics and Automation
Mobile Cobots Market
Robotics and Automation
Social Robots Market