
 Piece Picking Robots Market | 2026-2036
Piece Picking Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Piece Picking Robots Market Outlook
Robot-as-a-service subscription models with integrated software updates is hardening as the dominant commercial architecture. Amazon Robotics leverages its captive logistics network to refine deployment protocols at scale. RightHand Robotics specializes in gripper-agnostic architectures that accommodate heterogeneous SKU profiles. Geek+ anchors its expansion through dense channel partnerships across Asian distribution hubs.
Piece picking robots are autonomous or semi-autonomous systems equipped with multi-axis manipulators, machine vision arrays, and force-torque sensors that identify, grasp, and transfer individual items from unstructured bins into order containers. These systems operate at throughput rates between 600 and 1,200 picks per hour depending on gripper configuration and item geometry, serving primarily to reduce manual labor dependency in high-variability fulfillment environments. Mobile robots now represent the largest installed base segment, though collaborative robots are capturing the fastest expansion trajectory as safety-certified human-robot workcells proliferate. Artificial intelligence and computer vision technologies command the deepest margin pools, since proprietary perception algorithms create meaningful differentiation against commodity hardware platforms.
FAA guidelines on autonomous mobile robot operation in shared airspace adjacent to logistics facilities, OSHA collaborative robot safety standards, and ISO 10218 robotic equipment certification collectively determine product liability exposure and facility deployment timelines. The EU Machinery Directive and CE marking requirements impose additional conformity costs for vendors seeking European warehouse penetration. Stakeholders must weigh software-defined feature roadmaps against hardware refresh cycles as the primary capital allocation tension.
Market Dynamics
Robot-as-a-service subscription models with integrated software updates are hardening as the dominant commercial architecture, compressing upfront capital barriers and locking vendors into recurring revenue relationships with fulfillment operators.
Growth Catalysts
- OSHA collaborative robot safety standards:Certification clarity accelerates deployment velocity in shared human-robot workcells across US distribution facilities.
- Same-day delivery velocity requirements:E-commerce fulfillment centers demand throughput rates above 1,000 picks per hour to meet consumer expectations.
- Machine vision arrays:Proprietary perception algorithms differentiate vendor offerings against commodity hardware platforms and deepen margin pools.
Market Restraints
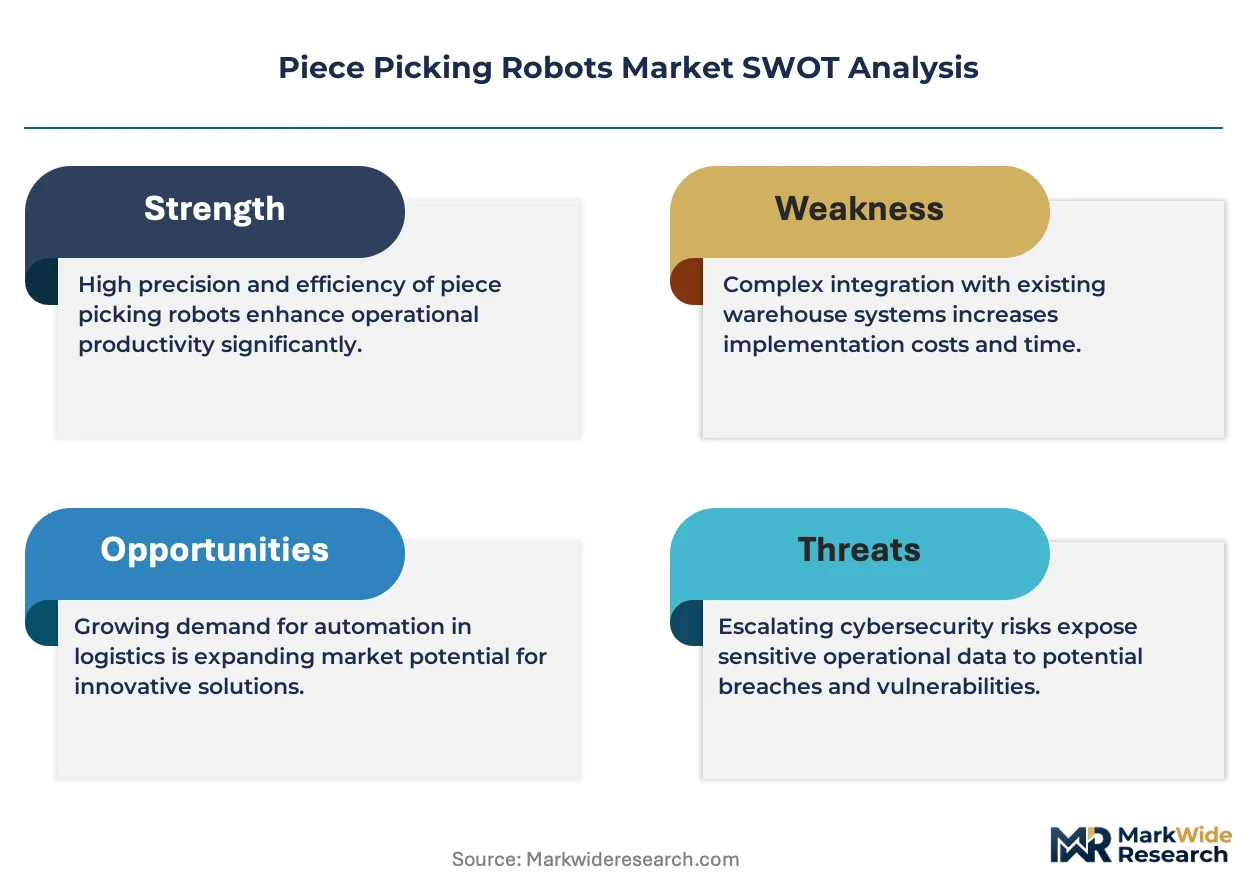
- Force-torque sensor input costs:Precision sensing components concentrate supply among Japanese and German component specialists, creating margin pressure during demand surges.
- ISO 10218 certification timelines:Multi-month validation cycles delay facility deployment and extend vendor liability exposure windows.
- Manual piece picking substitution economics:Low-wage labor markets in Southeast Asian distribution hubs blunt automation ROI calculations.
Strategic Opportunities
- EU Machinery Directive compliance services:CE marking advisory bundles create ancillary revenue streams for vendors penetrating European warehouse networks.
- Pharmaceutical cold-chain fulfillment:Temperature-controlled piece picking for biologics and vaccines represents an underpenetrated application with stringent handling protocols.
- 5G-enabled edge computing convergence:Millisecond-latency vision processing enables real-time grip adjustments in high-SKU-variability environments.
Industry Challenges
- Multi-axis manipulator integration complexity:Legacy warehouse management systems require expensive middleware development to interface with autonomous picking cells.
- Computer vision engineering talent scarcity:Shortage of specialists capable of training SKU-agnostic recognition models constrains vendor R&D velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Piece Picking Robots Market |
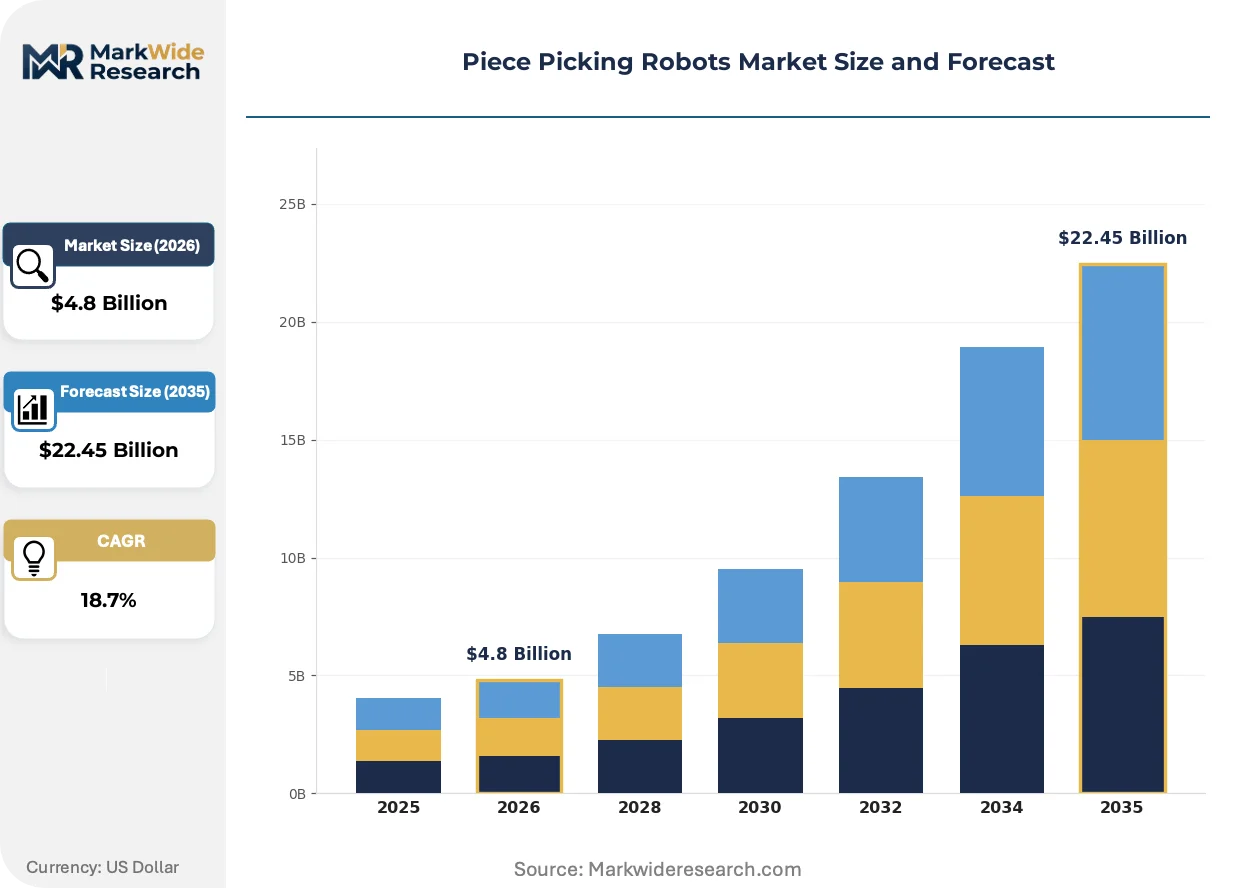
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Robots, Stationary Robots, Collaborative Robots, Autonomous Robots Technology: Machine Learning, Computer Vision, Sensor Technology, Artificial Intelligence End User: E-commerce, Retail, Logistics, Manufacturing Application: Warehouse Automation, Order Fulfillment, Inventory Management, Material Handling |
| Companies Covered | Plus One Robotics, Amazon Robotics, RightHand Robotics, Locus Robotics, Geek+, Berkshire Grey, Ocado Group (Robotics Solutions), GreyOrange, Covariant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Piece Picking Robots Market Strategic Shifts
Artificial intelligence and computer vision technologies command the deepest margin pools in piece picking robotics, with proprietary perception algorithms creating meaningful differentiation against commodity hardware platforms.
Soft robotic grippers employing pneumatically actuated fingers and adaptive grasping algorithms are converging with heterogeneous SKU environments. Apparel and grocery fulfillment centers deploy these systems to handle deformable packages without pre-programmed grip patterns. The technology is converging with traditional vacuum and jaw gripper architectures, compressing the addressable market for single-purpose end-effector suppliers.
EU AI Act risk classification frameworks impose documentation burdens on robotic systems employing machine learning for real-time decision-making. Vendors must maintain algorithmic audit trails and human oversight protocols to achieve CE marking under the Machinery Directive. Collaborative robot deployments in German and Dutch distribution hubs face the steepest compliance adaptation costs.
After-sales service unbundling accelerates as fulfillment operators negotiate separate contracts for hardware maintenance, software licensing, and perception algorithm retraining. Third-party logistics providers in the United States lead this procurement fragmentation, treating robot fleets as depreciating assets while outsourcing capability upgrades to specialized vision engineering shops.
Piece Picking Robots Market Segmentation
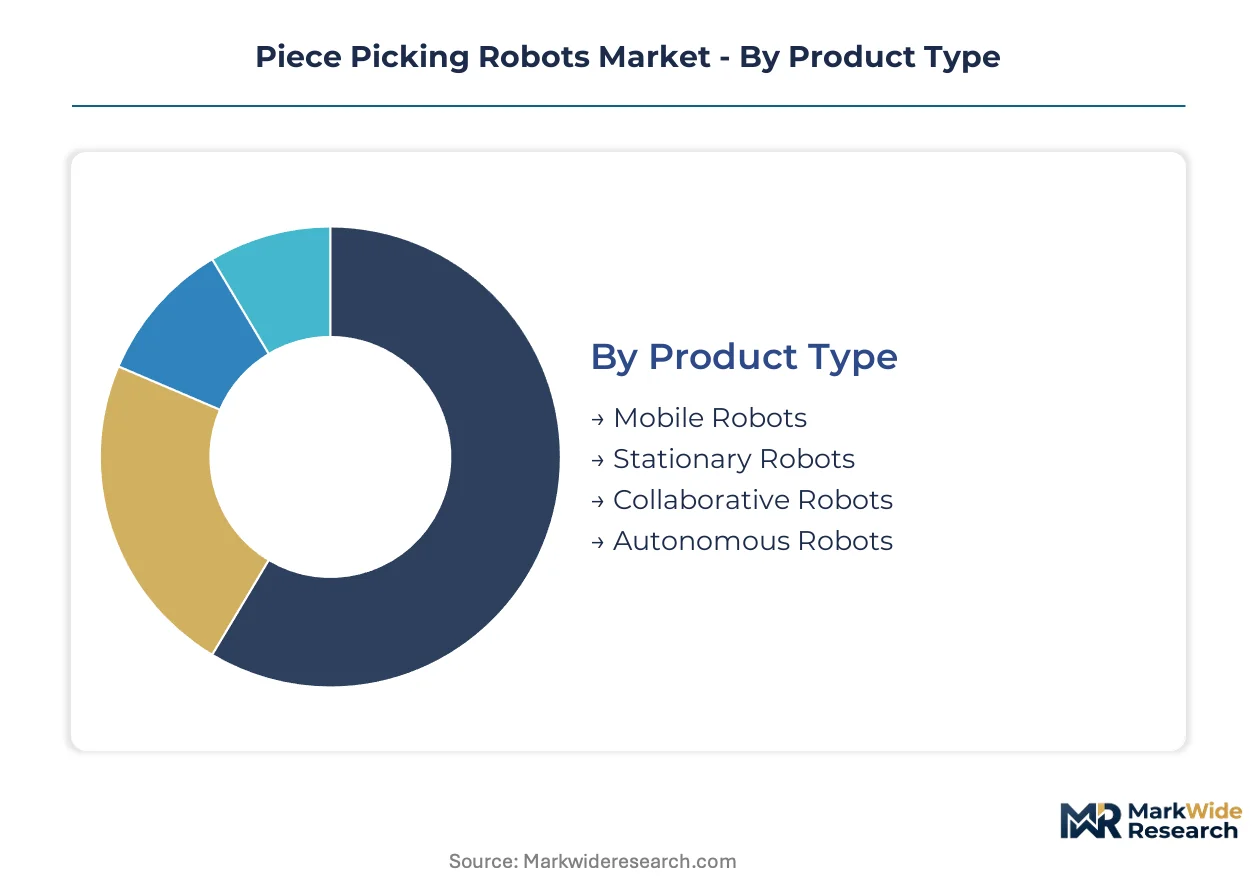
Piece picking robots segment across hardware mobility, perception intelligence, and operational context. Each axis determines integration complexity, capital intensity, and facility retrofit requirements for fulfillment operators.
Product Type:
Hardware mobility configurations determine facility footprint requirements and throughput scalability.
- Mobile Robots:Autonomous platforms navigate warehouse aisles while carrying manipulator arms to picking locations. Demand concentrates in United States e-commerce hubs where facility square footage exceeds 500,000 square feet and SKU density demands distributed picking stations.
- Collaborative Robots:Force-limited manipulators operate in certified human-robot workcells without safety cages. Newer deployment is concentrated in European pharmaceutical fulfillment where ISO 10218 certification and CE marking requirements favor safety-certified architectures over traditional industrial robots.
- Stationary Robots:Fixed-base systems anchor high-throughput picking stations with multi-axis reach envelopes.
- Autonomous Robots:Fully self-directed systems integrate navigation, perception, and manipulation without human intervention boundaries.
Mature deployment sits with mobile robots. Newer deployment is concentrated in collaborative robots.
Technology:
Perception and decision-stack technologies command the steepest R&D investment and create the widest vendor differentiation.
- Artificial Intelligence:Deep learning models trained on SKU-specific grasp strategies enable generalization across novel items. Demand concentrates in grocery fulfillment where produce deformation and packaging variability exceed rule-based programming limits.
- Computer Vision:Multi-camera arrays with structured light projection generate 3D point clouds for pose estimation. Deployment concentrates in apparel fulfillment where fabric deformation and hanger interference demand sub-millimeter grasp point identification.
- Machine Learning:Reinforcement learning from demonstration improves pick success rates through iterative grasp refinement.
- Sensor Technology:Force-torque and tactile sensing arrays provide closed-loop grasp feedback.
Established capability sits with computer vision. Fastest capability expansion is occurring in artificial intelligence.
End User:
Customer verticals impose distinct handling protocols, throughput requirements, and regulatory constraints on robot specifications.
- E-commerce:High-variability SKU profiles with same-day delivery windows demand 1,000+ picks per hour throughput. Deployment concentrates in United States fulfillment centers where labor cost pressures and delivery velocity expectations are most acute.
- Logistics:Third-party operators serving multiple clients require rapid SKU profile switching without engineering reconfiguration. Demand is expanding most quickly in German and Dutch distribution hubs where EU Machinery Directive compliance creates vendor selection criteria.
- Retail:Store replenishment and micro-fulfillment applications prioritize compact footprints.
- Manufacturing:Component kitting and assembly line supply impose precision tolerances.
Volume concentration sits with e-commerce. Regulatory-driven specification tightening is most pronounced in logistics.
Application:
Operational use cases determine workstation design, software integration depth, and ROI measurement frameworks.
- Warehouse Automation:End-to-end facility robotics integration including receiving, put-away, and shipping. Demand concentrates in new-build United States fulfillment centers where capital budgets accommodate full-stack automation without legacy system constraints.
- Order Fulfillment:Direct-to-consumer picking from unstructured bins into order containers. Deployment is climbing the fastest in apparel and grocery verticals where item deformability and fragility exceed traditional automation limits.
- Inventory Management:Cycle counting and stock location verification through mobile manipulation.
- Material Handling:Intra-facility transport and sortation of individual items.
Capital deployment maturity sits with warehouse automation. Fastest specification evolution is occurring in order fulfillment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardware fabrication concentrates in German and Japanese industrial corridors, while fulfillment deployment tilts toward the United States and Chinese e-commerce hubs. Consumption patterns diverge sharply: North American operators prioritize throughput velocity, European buyers emphasize safety certification, and Asian markets balance cost efficiency with SKU density.
United States
Same-day delivery mandates from Amazon and Walmart drive 1,000+ picks-per-hour specifications across fulfillment centers. OSHA collaborative robot safety standards accelerate cage-free workcell deployment in California and Texas distribution hubs. The Inland Empire logistics corridor east of Los Angeles hosts the densest concentration of mobile robot installations, with operators retrofitting legacy facilities for autonomous piece picking.
Germany
EU Machinery Directive compliance costs and ISO 10218 certification requirements filter vendor selection toward safety-certified collaborative architectures. The country's national industrial regulator enforces stringent documentation for machine-learning-enabled decision systems under the EU AI Act. The Rhine-Ruhr logistics cluster anchors deployment, with Düsseldorf and Cologne distribution centers serving as testbeds for pharmaceutical cold-chain piece picking.
China
Domestic e-commerce platforms JD.com and Pinduoduo compress delivery windows to same-day or next-day across tier-one cities. MIIT robotics industry guidelines and GB standard certification shape local vendor product roadmaps. The Yangtze River Delta—Shanghai, Suzhou, Hangzhou—concentrates both manufacturing capacity and fulfillment deployment, with operators integrating piece picking into existing automated storage systems.
Japan
Aging workforce demographics and labor shortage projections compel automation investment in logistics and manufacturing kitting applications. METI industrial robot safety guidelines and JIS certification requirements impose multi-month validation cycles on foreign vendors. The Chubu region around Nagoya hosts automotive parts distribution centers deploying force-torque sensing arrays for precision component handling.
Netherlands
Rotterdam-Europoort distribution hubs serve as European gateway facilities requiring rapid SKU switching for cross-border e-commerce. CE marking under the EU Machinery Directive and REACH chemical handling protocols influence gripper material selection. The Randstad corridor—Amsterdam, Rotterdam, Utrecht—attracts third-party logistics operators piloting collaborative robot workcells for apparel and consumer electronics fulfillment.
Piece Picking Robots Market Competitive Environment
Top-tier vendors anchor integrated platform ecosystems, while mid-tier specialists concentrate on modular perception or gripper subsystems. The vendor base stratifies across three tiers: captive technology divisions of major e-commerce operators, independent robotics platforms with RaaS subscription models, and component specialists supplying force-torque sensors or machine vision modules. Dominant competitive moves include strategic partnerships with warehouse management system providers and backward integration into proprietary perception algorithm development.
Within the captive technology tier, Amazon Robotics occupies a position exemplifying vertical integration into fulfillment operations. Among independent platform vendors, RightHand Robotics and Geek+ represent contrasting geographic anchoring—US-based and China-based respectively—while both pursuing gripper-agnostic architectures. Covariant sits within the AI-native specialist tier, its positioning tied to reinforcement learning approaches for SKU-agnostic grasping.
| Leading Market Players |
|---|
| Plus One Robotics |
| Amazon Robotics |
| RightHand Robotics |
| Locus Robotics |
| Geek+ |
| Berkshire Grey |
| Ocado Group (Robotics Solutions) |
| GreyOrange |
| Covariant |
| Others |
Value Chain & Pricing Dynamics
Large United States e-commerce fulfillment operators concentrate procurement power and lock vendors into Robot-as-a-service subscription models with integrated software updates. This buyer concentration compresses upfront capital barriers while embedding vendors in recurring revenue relationships that span multi-year facility deployment cycles.
Pricing Analysis
Cost-down pressure on collaborative robot tiers accelerates because ISO 10218 certification timelines extend vendor liability exposure and inflate compliance overhead. Pricing stratifies across premium safety-certified architectures, standard mobile platforms, and economy stationary configurations. Price differentiation hinges on CE marking tier and after-sales service bundling. Third-party logistics providers in the United States exhibit the sharpest price sensitivity, treating robot fleets as depreciating assets while unbundling maintenance and software licensing contracts.
Supply Chain Analysis
Reverse logistics flows for force-torque sensors and machine vision arrays remain underdeveloped, with refurbishment concentrated among Japanese component specialists serving Nagoya automotive distribution centers. Hardware fabrication draws from German industrial corridors and Japanese precision manufacturing clusters, with final assembly tethered to Chinese Yangtze River Delta facilities. Single-source vulnerability concentrates in pneumatic soft gripper membranes and structured light projection modules. Distribution runs through channel partnerships anchored by Geek+ across Asian hubs and direct sales teams serving California Inland Empire operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated platform vendors as proprietary perception algorithms create insurmountable capability gaps for hardware-only specialists. The commoditization of mobile robot chassis is forcing weaker players toward acquisition or exit.
For Market Incumbents: Anchor platform differentiation through backward integration into machine vision algorithm development rather than sourcing from third-party engineering shops. Defend position by securing exclusive channel partnerships with warehouse management system providers serving the German Rhine-Ruhr logistics cluster. ISO 10218 certification investment represents the priority defensive lever against emerging collaborative robot entrants. For New Entrants and Emerging Players: Launch via gripper-agnostic architectures targeting pharmaceutical cold-chain fulfillment in Dutch Rotterdam-Europoort facilities. White-space concentration sits with temperature-controlled biologics handling where stringent protocols deter established vendors. Penetrate through 5G-enabled edge computing pilots offering millisecond-latency vision processing that legacy platforms cannot match. For Investors and Strategic Acquirers: The window for entry favors AI-native specialists with reinforcement learning capabilities for SKU-agnostic grasping. Long-term viability hinges on software-defined feature roadmaps that outpace hardware refresh cycles. Acquisition targets should demonstrate algorithmic audit trail compliance with EU AI Act documentation burdens. Monitor OSHA collaborative robot safety standard revisions as inflection signals for cage-free workcell deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Perception Algorithm Acquisition | Proprietary computer vision models differentiate vendors against commodity hardware platforms in United States fulfillment centers. |
| EU Machinery Directive Compliance Service Launch | CE marking advisory bundles create ancillary revenue streams penetrating German and Dutch warehouse networks. |
| 5G-Enabled Edge Computing Partnership | Millisecond-latency vision processing enables real-time grip adjustments in high-SKU-variability grocery environments. |
| Pharmaceutical Cold-Chain Pilot Expansion | Temperature-controlled piece picking for biologics represents underpenetrated applications with stringent handling protocols. |
| Channel Partnership Density Buildout | Geek+ demonstrates Asian distribution hub penetration through dense local integrator relationships. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with fulfillment center operations directors, warehouse management system integrators, collaborative robot safety certification specialists, and third-party logistics procurement managers combined with secondary validation from OSHA guidance documents, EU Machinery Directive implementation reports, and FAA autonomous mobile robot operation guidelines. Bottom-up installation data triangulated against top-down vendor revenue estimates across hardware mobility, perception intelligence, and operational context segmentation dimensions.
Granularity-level modeling distinguished mobile robot, collaborative robot, stationary robot, and autonomous robot configurations at the product type level. Artificial intelligence, computer vision, machine learning, and sensor technology capabilities were projected across the analysis window with CAGRs derived from SKU density trajectories in e-commerce fulfillment and labor cost pressure indices. End-user segmentation incorporated e-commerce, logistics, retail, and manufacturing verticals with application-level modeling spanning warehouse automation, order fulfillment, inventory management, and material handling.
The model assumes a particular technology adoption path; alternative pathways for soft robotic gripper convergence with traditional vacuum architectures would alter the outlook. Forecasts reflect assumptions about OSHA collaborative robot safety standard finalization timing and EU AI Act enforcement intensity. Practitioners should monitor force-torque sensor supply allocation announcements from Japanese component specialists and 5G private network deployment schedules in United States Inland Empire facilities for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Disinfectant Robot Market
Robotics and Automation
Robot As a Service Market
Robotics and Automation
Europe Automated Guided Vehicle (AGV) Market
Robotics and Automation
Household Cleaning Robotics Market
Robotics and Automation
Smart Personal Assistance Devices Market
Robotics and Automation
Agriculture Robotics Market
Robotics and Automation
Mobile Robotics Software Market
Robotics and Automation
Professional Service Robots Market
Robotics and Automation
AI Powered Robot Market
Robotics and Automation
North America Collaborative Robots Market
Robotics and Automation
Robotic Process Automation in BFSI Market
Robotics and Automation
Healthcare Assistive Robot Market
Robotics and Automation
Global Robotics Parking System Market
Robotics and Automation
Global Adaptive Robotics Market
Robotics and Automation
Industrial Robot Controllers Market
Robotics and Automation
Global Robot Teach Pendant Market