
 Middle East and Africa Underwater Robotics Market | 2026-2036
Middle East and Africa Underwater Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Underwater Robotics Market Foresight
A shortage of certified subsea robotics technicians is collapsing project timelines across the Middle East and Africa. Eddyfi leverages its advanced electromagnetic inspection platforms to dominate non-destructive testing contracts in West African offshore fields. Saab AB anchors defense-oriented autonomous underwater vehicle programs through long-term supply agreements with regional navies. ATLAS ELEKTRONIK GmbH competes on mine countermeasures and seabed warfare systems, sustaining its position through German government-backed export financing.
Underwater robotics encompasses tethered, autonomous, and hybrid platforms engineered to operate at depths exceeding 3,000 meters, utilizing pressure-resistant hulls, acoustic positioning, and fiber-optic or wireless data links for subsea intervention. These systems execute inspection, maintenance, repair, survey, and security missions in environments lethal to human divers. Remotely operated vehicles still generate the largest revenue share due to their reliability in high-risk oil and gas infrastructure work, though autonomous underwater vehicles are capturing the fastest growth trajectory as battery energy density and machine-learning-based navigation improve. Environmental monitoring applications remain nascent but carry expanding margin pools as marine protected area enforcement tightens across East African coastal states.
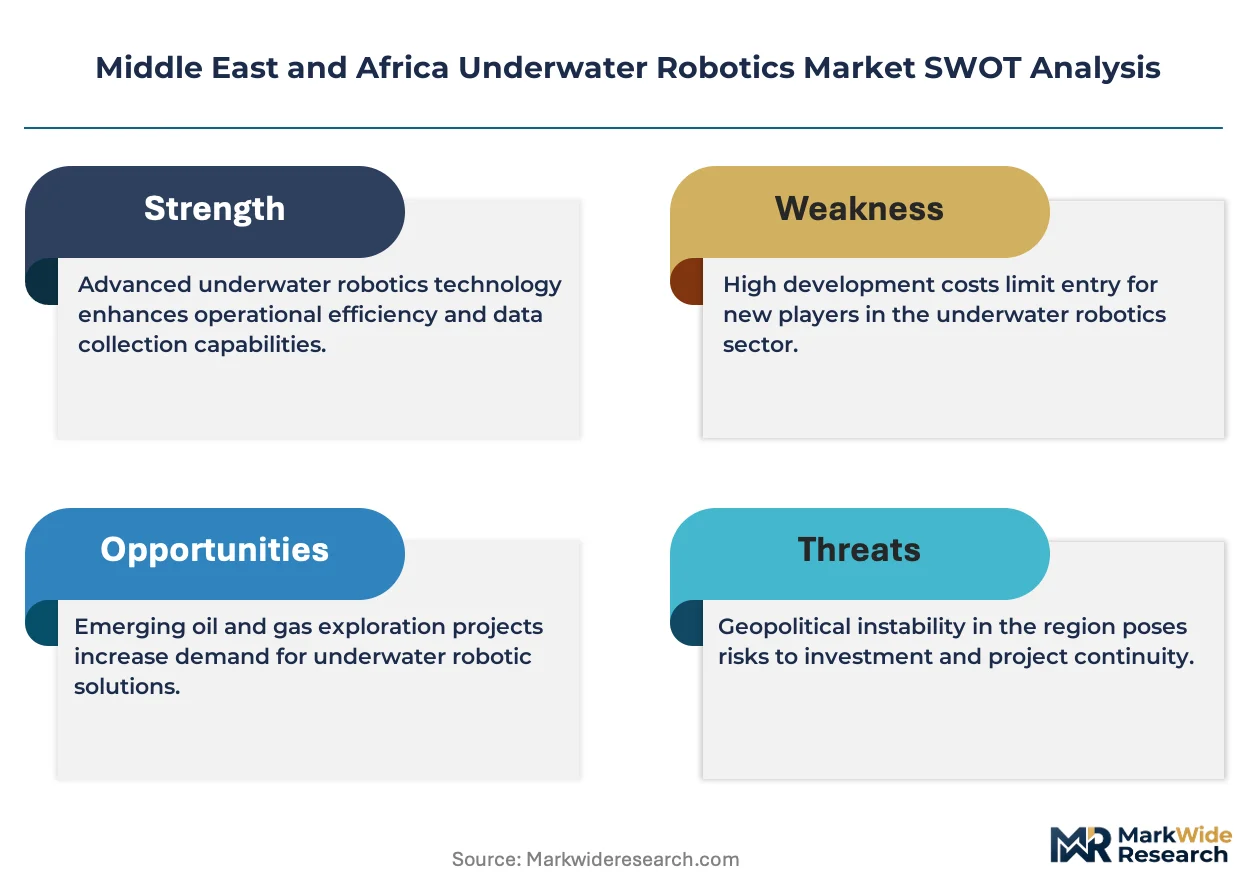
SFDA and MOHAP frameworks in Saudi Arabia and the UAE govern occupational safety standards for subsea operations, while national oil companies impose equipment certification requirements that filter market access for non-compliant vendors. The EU AI Act and ISO 13628-8 standards indirectly shape procurement specifications for European-headquartered operators active in African waters. Stakeholders must track how regional content mandates evolve in Nigeria and Angola, as local partnership requirements will determine which technology suppliers can bid on upcoming deepwater field development robotics packages.
Market Dynamics
The convergence of deepwater field development in the Gulf of Mexico and West African basins with national energy diversification mandates is redirecting capital toward robotic subsea infrastructure. This structural pull is compressing procurement cycles and elevating autonomous platforms above traditional tethered systems in operator preference hierarchies.
Growth Catalysts
- SFDA and MOHAP frameworks:Saudi Arabia and the UAE have tightened occupational safety standards for subsea operations, forcing national oil companies to accelerate robotic substitution for human divers in hazardous inspection zones.
- Deepwater field development:Nigeria and Angola are expanding subsea robotics packages as local content mandates require technology transfer alongside hardware procurement.
- Battery energy density improvements:Lithium-sulfur and solid-state chemistries are extending autonomous underwater vehicle endurance beyond 72 hours, enabling pipeline integrity monitoring across longer tieback distances.
Market Restraints
- Certified technician scarcity:The shortage of subsea robotics technicians qualified to ISO 13628-8 standards is collapsing project timelines across Nigerian and Angolan offshore fields.
- High-grade titanium alloy concentration:Pressure hull manufacturing depends on a concentrated supplier base in East Asian forging facilities, exposing procurement to input cost volatility.
- Acoustic positioning limitations:Signal degradation in complex seabed topography restricts autonomous navigation accuracy below 500 meters in certain West African canyon systems.
Strategic Opportunities
- Marine protected area enforcement:East African coastal states are expanding environmental monitoring applications as regulatory frameworks tighten around coral reef preservation.
- Mine countermeasures modernization:Regional navies are replacing legacy seabed warfare inventories, creating demand for hybrid autonomous-tethered platforms with improved machine-learning classification.
- Local partnership mandates:Evolving Nigerian and Angolan content requirements will filter market access, rewarding vendors who establish joint ventures with domestic engineering firms.
Industry Challenges
- Multi-standard certification complexity:Equipment must simultaneously satisfy EU AI Act provisions, ISO 13628-8 specifications, and national oil company technical requirements, elongating qualification timelines.
- Legacy ROV fleet integration:Autonomous platforms must interface with existing tethered vehicle infrastructure and topside control systems, complicating deployment architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Underwater Robotics Market |
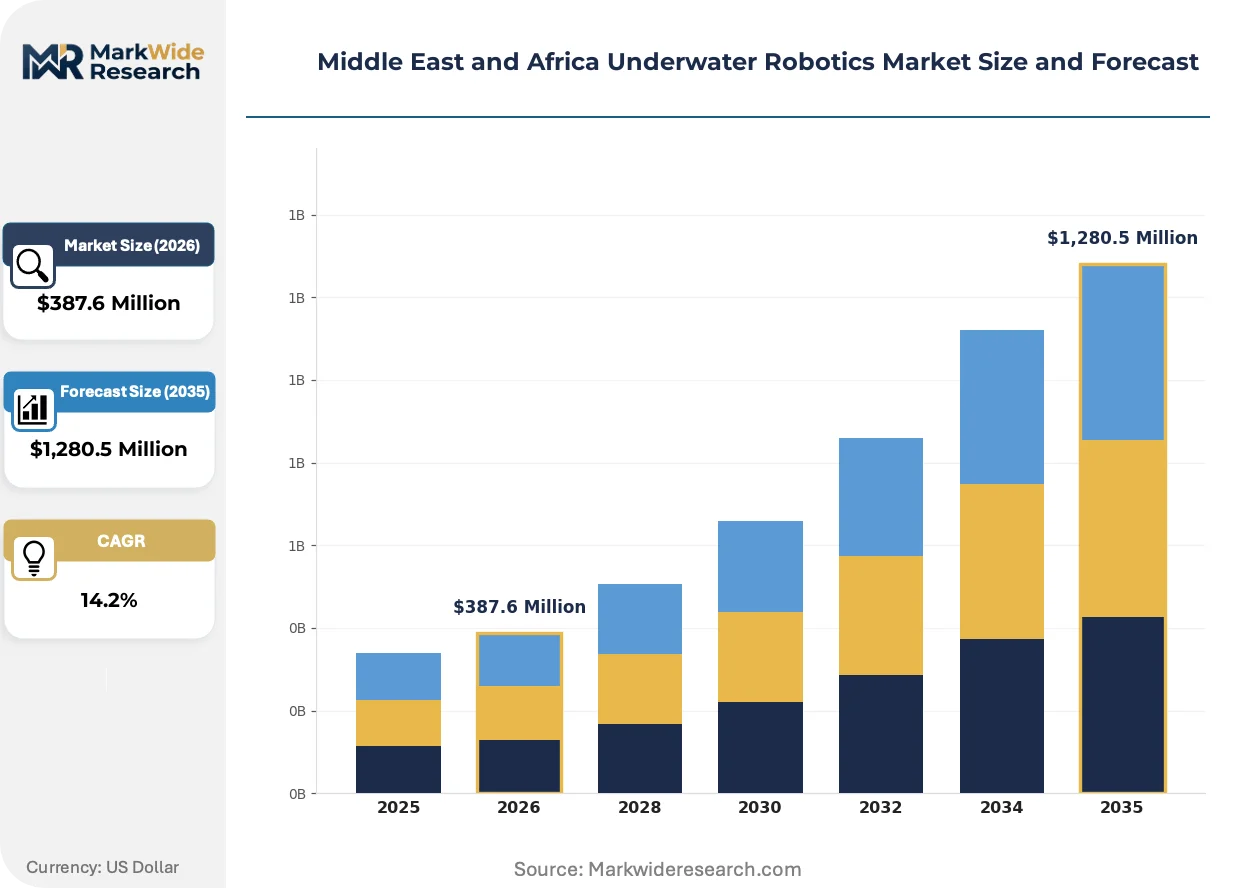
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Remotely Operated Vehicles, Autonomous Underwater Vehicles, Hybrid Vehicles, Underwater Drones End User: Defense, Oil & Gas, Research Institutions, Environmental Monitoring Application: Surveillance, Exploration, Inspection, Data Collection Technology: Navigation Systems, Communication Systems, Power Supply, Control Systems |
| Companies Covered | Eddyfi, Saab AB, ATLAS ELEKTRONIK GmbH, TechnipFMC plc, Forum Energy Technologies, Inc., General Dynamics Mission Systems, Inc., Oceaneering International, Inc., SUBSEA 7, ECA Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Underwater Robotics Market Shifts & Advancements
Machine-learning-based navigation architectures are decomposing traditional acoustic positioning dependencies across subsea robotics platforms. This shift is compressing the performance gap between autonomous and tethered systems while opening new operational envelopes in GPS-denied environments.
Reinforced composite pressure hulls utilizing carbon-fiber filament winding are decomposing the historical dominance of titanium alloy construction in deep-rated autonomous vehicles. Nigerian and Angolan operators are specifying these materials for pipeline inspection contracts below 2,000 meters. The weight reduction is enabling smaller launch-and-recovery systems, compressing vessel day-rate requirements for survey campaigns.
EU AI Act algorithmic transparency requirements are reshaping procurement specifications for European-headquartered operators active in African waters. Automated decision-making systems aboard autonomous underwater vehicles must now document classification logic for seabed object identification. This regulatory friction is most acute in mine countermeasures programs, where German and French defense contractors are reengineering software architectures to satisfy audit trails.
Service unbundling is fragmenting traditional integrated robotics contracts across Middle Eastern national oil companies. Operators now separate platform procurement from piloting services, maintenance, and data interpretation, enabling direct software licensing agreements with navigation and imaging specialists. This pattern is most visible in Saudi Aramco's accelerated deployment programs, where third-party analytics providers are capturing margin pools previously retained by original equipment manufacturers.
Middle East and Africa Underwater Robotics Market Segmentation
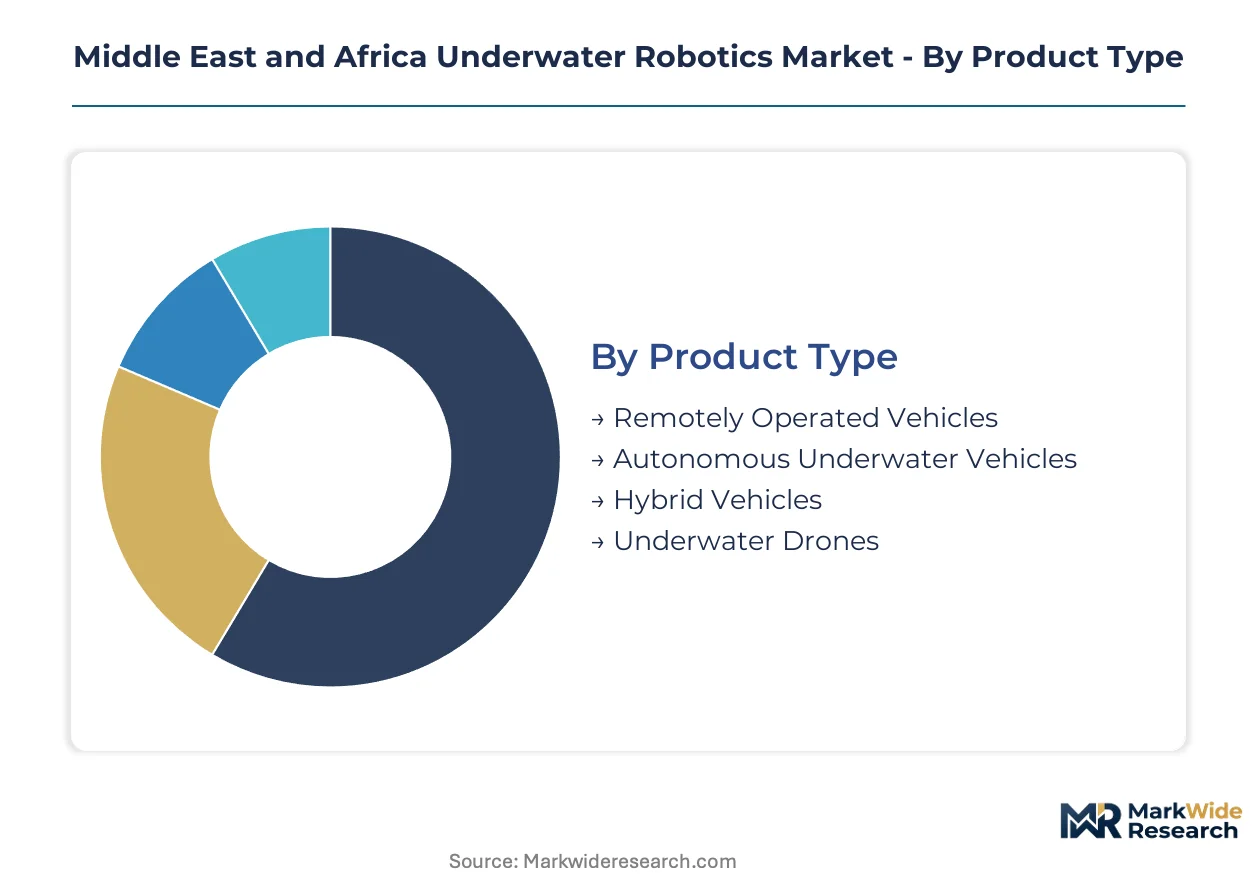
Segmentation in the Middle East and Africa underwater robotics market reveals how procurement channels, technical specifications, and operator requirements fragment demand across distinct product configurations and mission profiles. Understanding these divisions exposes where margin pools concentrate and which technology trajectories align with regional investment priorities.
Product Type:
Channel flow varies sharply by product category, with tethered systems dominating capital-intensive oil and gas procurement while autonomous platforms penetrate through defense and research channels.
- Remotely Operated Vehicles:Tethered architectures with fiber-optic data links and hydraulic manipulator arms deliver proven reliability for pipeline intervention at depths exceeding 3,000 meters. Nigerian and Angolan national oil companies specify these systems for subsea infrastructure integrity programs where human diver substitution is mandatory under tightening occupational safety frameworks.
- Autonomous Underwater Vehicles:Battery-powered untethered platforms utilizing lithium-sulfur chemistries and machine-learning navigation architectures are compressing the performance gap with traditional ROVs. Saudi Aramco's accelerated deployment for pipeline monitoring illustrates how energy diversification strategies redirect procurement budgets toward robotic systems with extended endurance profiles.
- Hybrid Vehicles:Dual-mode platforms combining tethered precision with autonomous endurance are gaining traction in mine countermeasures modernization programs.
- Underwater Drones:Compact shallow-rated systems serve environmental monitoring contracts in East African coastal states.
By volume, Remotely Operated Vehicles leads. By growth pace, Autonomous Underwater Vehicles is expanding most quickly.
End User:
Cost tier stratification separates defense procurement with long-term supply agreements from commercial oil and gas spot contracting and institutional research grants.
- Defense:Regional navies in Saudi Arabia and the UAE are replacing legacy seabed warfare inventories through German government-backed export financing arrangements. Mine countermeasures and anti-submarine warfare applications specify hybrid platforms with improved machine-learning classification for seabed object identification.
- Oil & Gas:National oil companies impose equipment certification requirements filtering market access for non-compliant vendors. Deepwater field development in Nigeria and Angola drives demand for inspection-class systems with pressure-resistant titanium alloy hulls rated below 2,000 meters.
- Research Institutions:University and oceanographic laboratory procurement concentrates on modular platforms with reconfigurable sensor payloads.
- Environmental Monitoring:East African coastal states are expanding marine protected area enforcement applications as regulatory frameworks tighten around coral reef preservation.
Defense commands premium pricing tiers. Environmental Monitoring is climbing the fastest as regulatory enforcement tightens.
Application:
Volume concentration in inspection missions contrasts with margin expansion in data interpretation services unbundled from hardware procurement.
- Inspection:Pipeline integrity monitoring, subsea infrastructure assessment, and platform structural evaluation constitute the core revenue base. SFDA and MOHAP occupational safety standards in Saudi Arabia and the UAE are accelerating robotic substitution for human divers in hazardous zones.
- Surveillance:Maritime security applications span port protection, coastal perimeter monitoring, and seabed warfare intelligence gathering. Regional navies specify systems with acoustic positioning and encrypted communication links for GPS-denied environments.
- Exploration:Geophysical survey and hydrographic mapping missions demand high-resolution sonar payloads and precise navigation architectures.
- Data Collection:Oceanographic sampling and environmental baseline studies are fragmenting traditional integrated contracts into direct software licensing agreements with analytics specialists.
Inspection dominates current deployment volumes. Data Collection is gaining share fastest as service unbundling accelerates.
Technology:
Supply concentration in East Asian forging facilities for pressure hull components exposes procurement to input cost volatility across all technology subsystems.
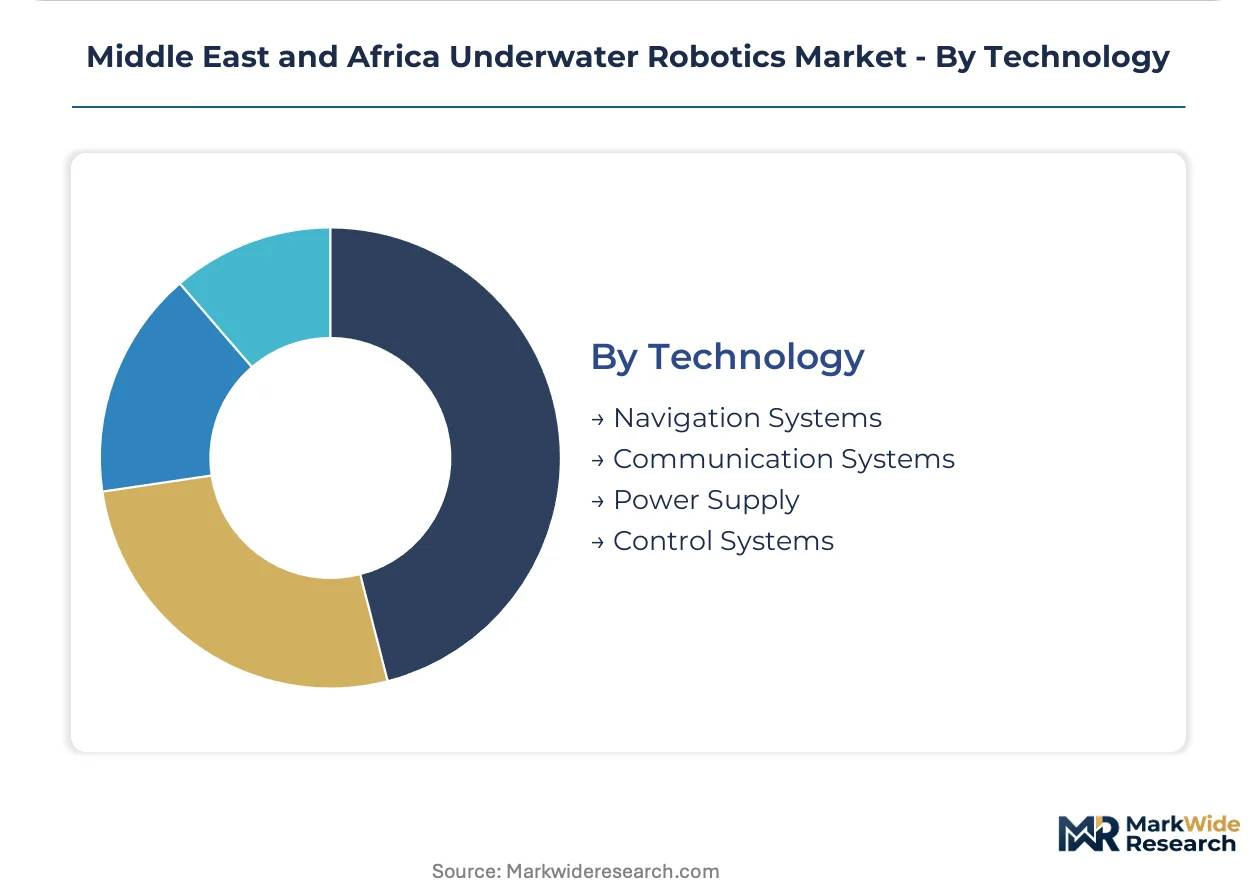
- Navigation Systems:Acoustic positioning with ultra-short baseline arrays and inertial measurement units enables sub-meter accuracy in complex seabed topography. Signal degradation below 500 meters in certain West African canyon systems restricts autonomous navigation accuracy and drives demand for hybrid architectures.
- Communication Systems:Fiber-optic tethers, acoustic modems, and emerging optical wireless links transmit command telemetry and sensor data. EU AI Act algorithmic transparency requirements are reshaping procurement specifications for European-headquartered operators active in African waters.
- Power Supply:Lithium-sulfur and solid-state battery chemistries are extending autonomous endurance beyond 72 hours.
- Control Systems:Topside command consoles and autonomous decision-making architectures must interface with legacy ROV fleet infrastructure.
Navigation Systems represents the largest technology spend. Communication Systems faces the steepest expansion trajectory as regulatory audit requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA frameworks in Saudi Arabia anchor procurement specifications across the Middle East and Africa underwater robotics market, redirecting national oil company budgets toward certified robotic systems as occupational safety mandates tighten.
Saudi Arabia
Deepwater field development in the Gulf and Red Sea basins drives demand for autonomous pipeline inspection platforms. SFDA occupational safety standards accelerate robotic substitution for human divers in hazardous subsea zones. Dhahran-based engineering clusters concentrate deployment programs for national energy diversification strategies.
United Arab Emirates
MOHAP regulations governing subsea operations filter equipment certification requirements for vendors accessing Abu Dhabi and Dubai offshore contracts. Maritime security investments converge with oil and gas infrastructure work across the emirates. Jebel Ali industrial zones host integration facilities for hybrid autonomous-tethered platforms.
Nigeria
Local content mandates require technology transfer alongside hardware procurement for deepwater field robotics packages. The country's national petroleum regulator imposes equipment standards that elongate qualification timelines for non-compliant suppliers. Lagos and Port Harcourt anchor fabrication and service clusters for West African offshore operations.
Angola
Deepwater pre-salt development programs specify inspection-class systems with pressure-resistant hulls rated below 2,000 meters. Evolving local partnership requirements filter market access for upcoming subsea robotics tenders. Luanda-based engineering firms increasingly serve as mandatory joint venture partners for technology suppliers.
South Africa
Marine protected area enforcement applications expand as regulatory frameworks tighten around coastal ecosystem preservation. The country's national environmental regulator drives specification of shallow-rated monitoring platforms for coral reef surveillance. Cape Town oceanographic clusters concentrate research procurement for modular reconfigurable sensor payloads.
Middle East and Africa Underwater Robotics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Middle East and Africa underwater robotics market. The upper tier commands premium pricing through long-term supply agreements with national oil companies and regional navies. Specialist players compete on non-destructive testing platforms, mine countermeasures systems, and environmental monitoring applications. Dominant competitive moves include strategic partnerships with domestic engineering firms to satisfy local content mandates, and technology licensing arrangements to compress qualification timelines under multi-standard certification regimes.
Within the defense-oriented tier, Saab AB and ATLAS ELEKTRONIK GmbH exemplify positioning anchored by government-backed export financing and seabed warfare program participation. Eddyfi occupies a position among inspection specialists leveraging electromagnetic platforms for West African offshore field contracts. These three entities represent distinct archetypes: Swedish and German defense contractors navigating mine countermeasures modernization, and Canadian-headquartered testing specialists capturing non-destructive evaluation margin pools.
| Leading Market Players |
|---|
| Eddyfi |
| Saab AB |
| ATLAS ELEKTRONIK GmbH |
| TechnipFMC plc |
| Forum Energy Technologies, Inc. |
| General Dynamics Mission Systems, Inc. |
| Oceaneering International, Inc. |
| SUBSEA 7 |
| ECA Group |
| Others |
Supply & Pricing Matrix
Twelve-month order backlogs for titanium alloy pressure hulls from East Asian forging facilities concentrate pricing power among incumbent vendors serving Nigerian and Angolan deepwater contracts. This lead-time compression shapes how national oil companies structure procurement cycles and how equipment suppliers tier their service offerings across the Middle East and Africa.
Pricing Analysis
Saudi Aramco contracts command premiums above West African spot pricing by roughly one tier, reflecting SFDA certification requirements and bundled piloting services. Three-tier pricing structure across premium, standard, and economy levels separates defense procurement with German government-backed financing from commercial oil and gas spot contracting and research institutional grants. Cost compression in the standard tier is intensifying because reinforced composite hull alternatives are displacing titanium below 2,000-meter ratings. Environmental monitoring agencies in East African coastal states exhibit highest price sensitivity; defense ministries in Saudi Arabia and the UAE show lowest.
Supply Chain Analysis
Pressure hull manufacturing draws from concentrated forging capacity in China, Japan, and South Korea, with acoustic positioning arrays sourced from specialized European sensor houses. Raw material dependencies center on high-grade titanium sponge, carbon-fiber filament, and lithium-sulfur battery cells. Single-source vulnerability in East Asian forging exposes procurement to input cost volatility when regional capacity constraints emerge. Distribution runs through Jebel Ali integration facilities and Lagos service clusters before final deployment on offshore vessels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service unbundling across Middle Eastern national oil companies fragments traditional integrated contracts, creating specialized niches for navigation software vendors and analytics providers previously absorbed within OEM margin pools.
For Market Incumbents: Compound defensive positioning by securing long-term supply agreements with regional navies before mine countermeasures modernization cycles peak, and accelerate backward integration into carbon-fiber filament winding to offset titanium cost volatility. Hybrid autonomous-tethered platforms threaten pure-play ROV fleets; certification investment in EU AI Act algorithmic transparency requirements anchors premium pricing tiers. For New Entrants and Emerging Players: ISO 13628-8 fast-track partnerships with Nigerian engineering firms unlock access to deepwater field robotics tenders where local content mandates filter non-compliant vendors. White-space targets concentrate in East African marine protected area enforcement and Saudi pipeline integrity monitoring data interpretation services. A direct software licensing model with national oil companies bypasses hardware procurement barriers. For Investors and Strategic Acquirers: Long-term, this sits as a defense-energy hybrid play because seabed warfare modernization and oil field robotics procurement cycles exhibit low correlation with commodity price swings. Acquisition targets should display established joint venture structures with domestic engineering firms in Nigeria or Angola. The signal to watch is evolving local partnership mandate enforcement intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture with Domestic Engineering Firms | Satisfies Nigerian and Angolan local content requirements for deepwater robotics tenders. |
| EU AI Act Algorithmic Transparency Investment | Enables audit-trail compliance for European-headquartered operators active in African waters. |
| Carbon-Fiber Pressure Hull Development | Reduces vessel day-rate requirements for inspection campaigns below 2,000 meters. |
| Long-Term Supply Agreement with Regional Navies | Secures mine countermeasures modernization revenue through German export financing. |
| Software Licensing for Data Interpretation | Captures margin pools unbundled from hardware procurement by Saudi Aramco. |
Research Methodology
A standing panel of subsea robotics program managers, national oil company procurement directors, regional navy acquisition officers, and marine protected area enforcement coordinators provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against SEC filings from listed equipment vendors, customs records for titanium alloy imports, and project development databases for West African deepwater fields. Bottom-up deployment volume estimates triangulated against top-down national oil company capital expenditure disclosures.
Consistency checks validated volume and value outputs against external benchmarks including national energy diversification strategy documents and defense ministry seabed warfare procurement announcements. Segmentation modeling spanned product type, end user, application, and technology subsystem across the projection horizon. CAGRs were derived from fitted growth curves anchored to documented procurement cycle accelerations and battery chemistry improvement trajectories. Forecast inputs incorporated SFDA and MOHAP regulatory implementation timelines and lithium-sulfur energy density advancement curves.
Decision-makers should treat outputs as directional under stable regulatory enforcement intensity and continued national oil company robotics substitution mandates; material deviation in local partnership requirements or battery chemistry breakthroughs would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Europe Service Robotics Market
Robotics and Automation
Robotic Process Automation in Legal Services Market
Robotics and Automation
AGV Software Market
Robotics and Automation
Global Wafer Handling Robots Market
Robotics and Automation
Asia-Pacific Robotic Process Automation Market
Robotics and Automation
Asia Pacific Industrial Robots Market
Robotics and Automation
Medical Automation Technologies Market
Robotics and Automation
Asia Pacific Automated Guided Vehicle (AGV) Market
Robotics and Automation
Underwater Rescue Robot Market
Robotics and Automation
Disinfectant Robot Market
Robotics and Automation
Automotive Robotic Painting Market
Robotics and Automation
India Cloud Robotics Market
Robotics and Automation
Global Robot Teach Pendant Market
Robotics and Automation
Global AI Based Surgical Robots Market
Robotics and Automation
North America Service Robotics Market
Robotics and Automation
Delta Robotics Market