
 APAC 3D Telepresence Market | 2026-2036
APAC 3D Telepresence Market Size, Share, and Industry Trends Forecast 2026-2036
APAC 3D Telepresence Market Outlook
The direct sales channel for enterprise-grade holographic systems is narrowing as regional systems integrators in Tokyo, Seoul, and Sydney consolidate procurement relationships with end users. Cisco Systems Inc. leverages its established video conferencing installed base to cross-sell immersive room solutions across ASEAN financial services clients. Microsoft Corporation anchors cloud-rendered 3D telepresence through Azure spatial computing infrastructure, sustaining recurring revenue models that displace capital-heavy hardware purchases. ZTE Corporation competes on telecommunications carrier partnerships, embedding telepresence modules within 5G network service bundles for Chinese and Indonesian corporate subscribers.
APAC 3D telepresence encompasses real-time volumetric capture, compression, and photorealistic reconstruction of human subjects transmitted across low-latency networks to enable spatially accurate remote interaction, typically requiring 50-100 Mbps sustained bandwidth and sub-50 millisecond latency for acceptable user experience. Holographic Displays and Immersive Environments currently occupy the highest margin pools due to specialized optics and proprietary light-field rendering engines, while Visual Collaboration Platforms extend fastest across mid-market corporate offices seeking software-centric deployment without dedicated room infrastructure. Telepresence Robotic Systems remain nascent in healthcare and education settings, constrained by mechanical reliability standards and facility retrofit costs that limit addressable volume.
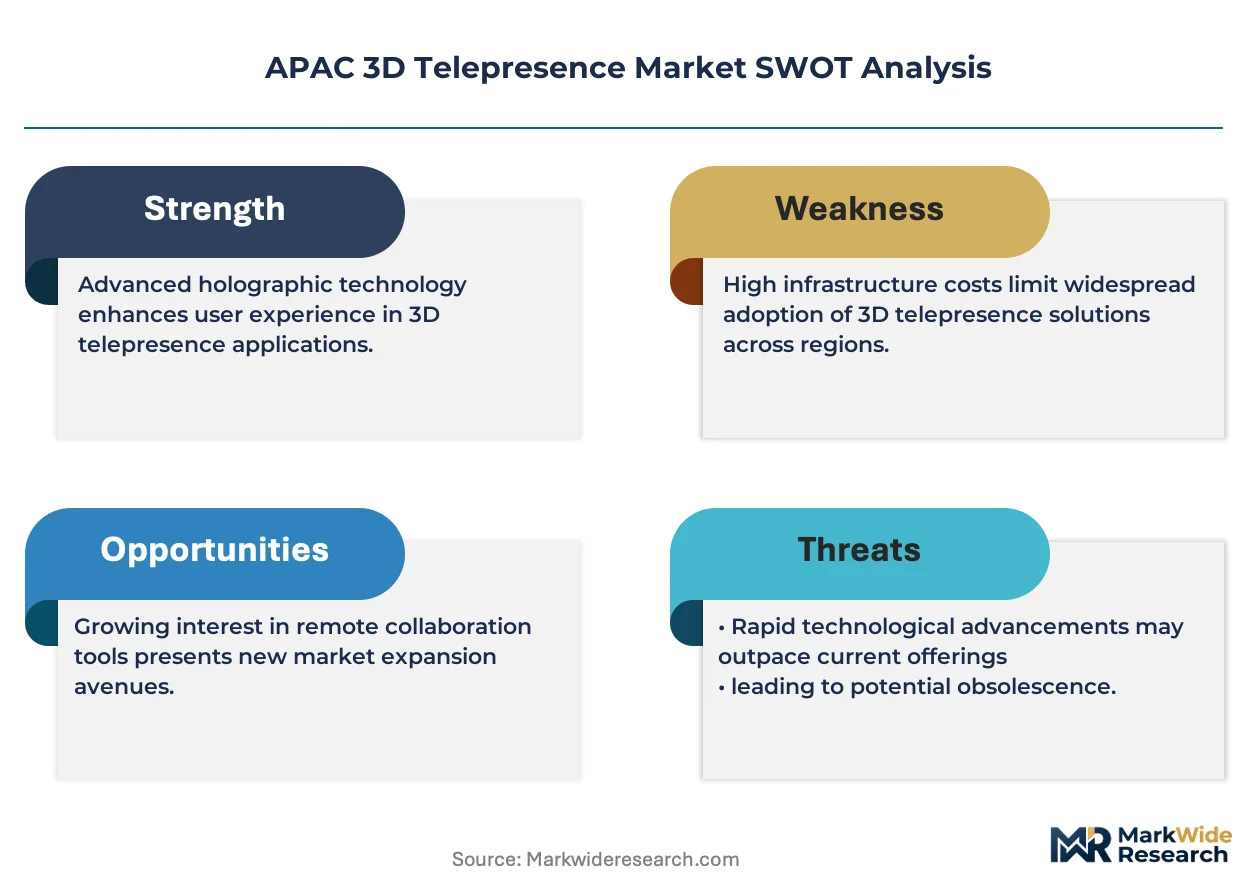
Japan's METI enforces JIS standards on electromagnetic compatibility and eye safety for near-field holographic projection equipment, while China's NMPA and MIIT jointly regulate medical-grade volumetric imaging devices used in telemedicine applications across the region. Australia's TGA assesses diagnostic accuracy claims for remote consultation platforms, creating compliance thresholds that favor vendors with established clinical validation pathways. Stakeholders must weigh hardware specialization against platform interoperability as regulatory fragmentation across these jurisdictions hardens into distinct certification requirements.
Market Dynamics
Hybrid work permanence across APAC corporate offices is compressing sales cycles for holographic meeting infrastructure as facilities managers prioritize spatial communication over incremental video conferencing upgrades.
Growth Catalysts
- Japan's METI JIS standards:Electromagnetic compatibility and eye safety certifications for near-field holographic projection equipment are accelerating vendor qualification timelines for enterprise deployment.
- Telemedicine diagnostics:Australian healthcare providers now routinely incorporate volumetric video for specialist remote consultations, creating pull-through demand for capture hardware.
- Light-field rendering engines:Proprietary optics advancements in holographic displays are expanding addressable use cases from boardroom presentations to surgical training simulations.
Market Restraints
- Bandwidth infrastructure gaps:Sustained 50-100 Mbps requirements with sub-50 millisecond latency exclude tier-two Chinese and Indonesian cities from viable deployment.
- Specialized optics supply concentration:Precision lens and spatial light modulator fabrication remains concentrated in Japanese and South Korean component suppliers.
- Facility retrofit costs:Dedicated room infrastructure requirements for immersive environments limit mid-market corporate adoption across ASEAN economies.
Strategic Opportunities
- India's PLI scheme:Electronics manufacturing incentives are compressing hardware costs and accelerating vendor entry for domestic production of volumetric capture systems.
- Cloud-rendered spatial computing:Azure and carrier-agnostic platforms are displacing capital-heavy hardware purchases with recurring software subscriptions.
- 5G network service bundles:Telecommunications carriers in China and Indonesia are embedding telepresence modules within enterprise connectivity packages.
Industry Challenges
- Volumetric compression expertise:Real-time photorealistic reconstruction requires scarce software engineering talent familiar with neural radiance fields and point cloud optimization.
- Cross-jurisdictional certification timelines:Separate METI, NMPA, MIIT, and TGA validation pathways delay product launches by 8-14 months across the region.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC 3D Telepresence Market |
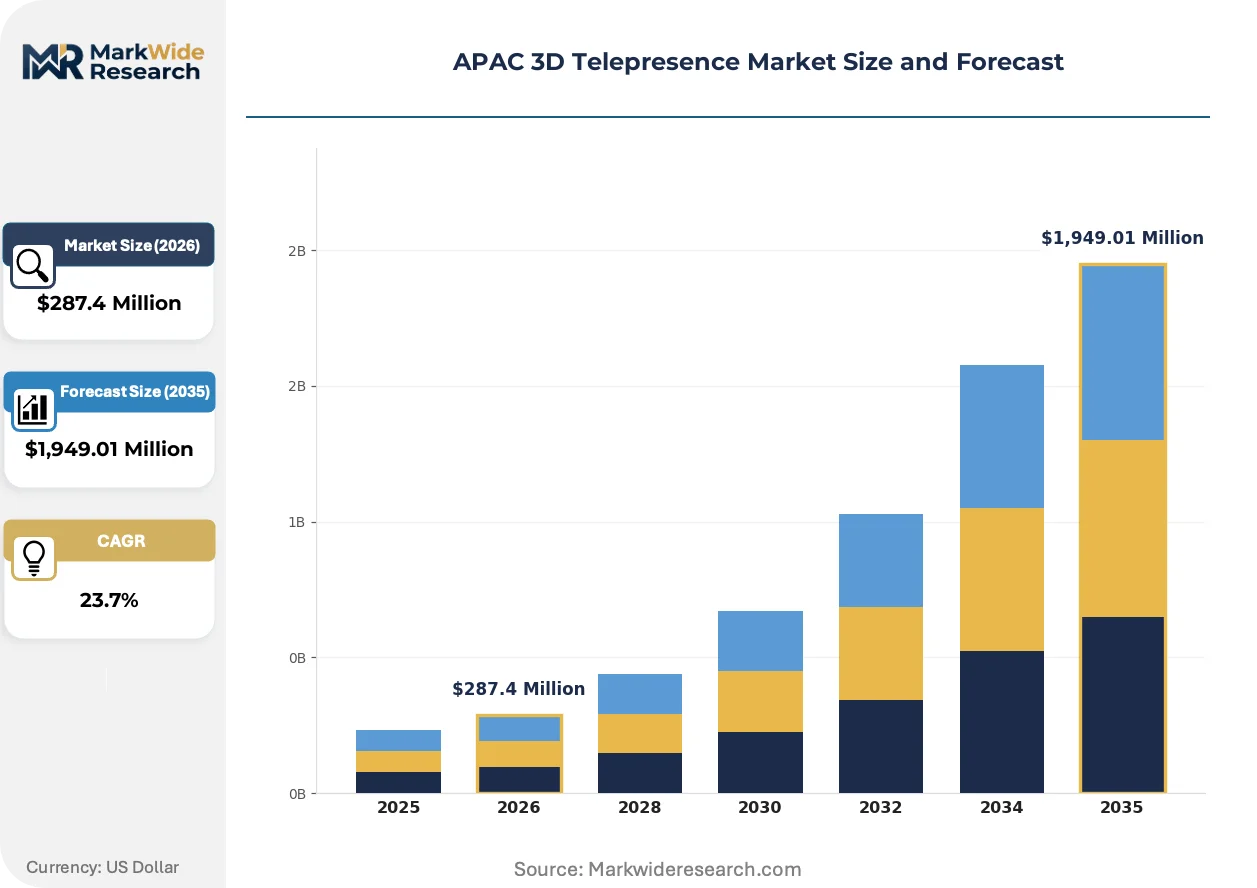
| Market Size in 2026 | $287.4 Million |
| Market Size in 2035 | $1,949.01 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telepresence Robotic Systems, Holographic Displays, Immersive Environments, Visual Collaboration Platforms End User: Education Institutions, Healthcare Providers, Corporate Offices, Entertainment Venues Technology: Virtual Reality, Augmented Reality, Live Streaming, Interactive Software Application: Remote Meetings, Training Sessions, Telemedicine Consultations, Event Broadcasting |
| Companies Covered | Cisco Systems Inc., Microsoft Corporation, ZTE Corporation, TelePresence Tech, Holoxica Limited, Polycom Inc., Digital Video Enterprises Inc., MDH Hologram Ltd., Primasonic Spectrum Private Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC 3D Telepresence Market Strategic Shifts
Real-time volumetric capture is migrating from proprietary hardware stacks toward software-defined pipelines, while regulatory fragmentation hardens certification requirements and procurement consolidates through regional systems integrators.
Neural radiance field (NeRF) rendering is migrating from research environments into production telepresence workflows, compressing bandwidth requirements by reconstructing human subjects from sparse camera arrays rather than dense point clouds. South Korean broadcast studios and Japanese corporate training departments are piloting these systems for live holographic transmission. This migration from dense capture to AI-driven reconstruction is enabling acceptable user experience at 35-50 Mbps, expanding addressable geographies beyond fiber-rich metropolitan cores.
China's MIIT guidelines on immersive communication infrastructure, jointly administered with NMPA for medical applications, are mandating interoperability testing for volumetric imaging devices used in cross-border telemedicine. Industrial consequence includes accelerated standardization of compression codecs and security protocols. Australian healthcare providers and Chinese hospital networks are responding by pre-qualifying vendors against both jurisdictions' requirements before procurement.
Enterprise buyers across ASEAN financial services are consolidating holographic system procurement through Tokyo, Seoul, and Sydney-based systems integrators rather than direct vendor relationships. These integrators bundle installation, network optimization, and support contracts, displacing capital-only transactions. This pattern is most visible in Singapore and Hong Kong banking headquarters, where facilities managers lack internal expertise for spatial computing deployment.
APAC 3D Telepresence Market Segmentation
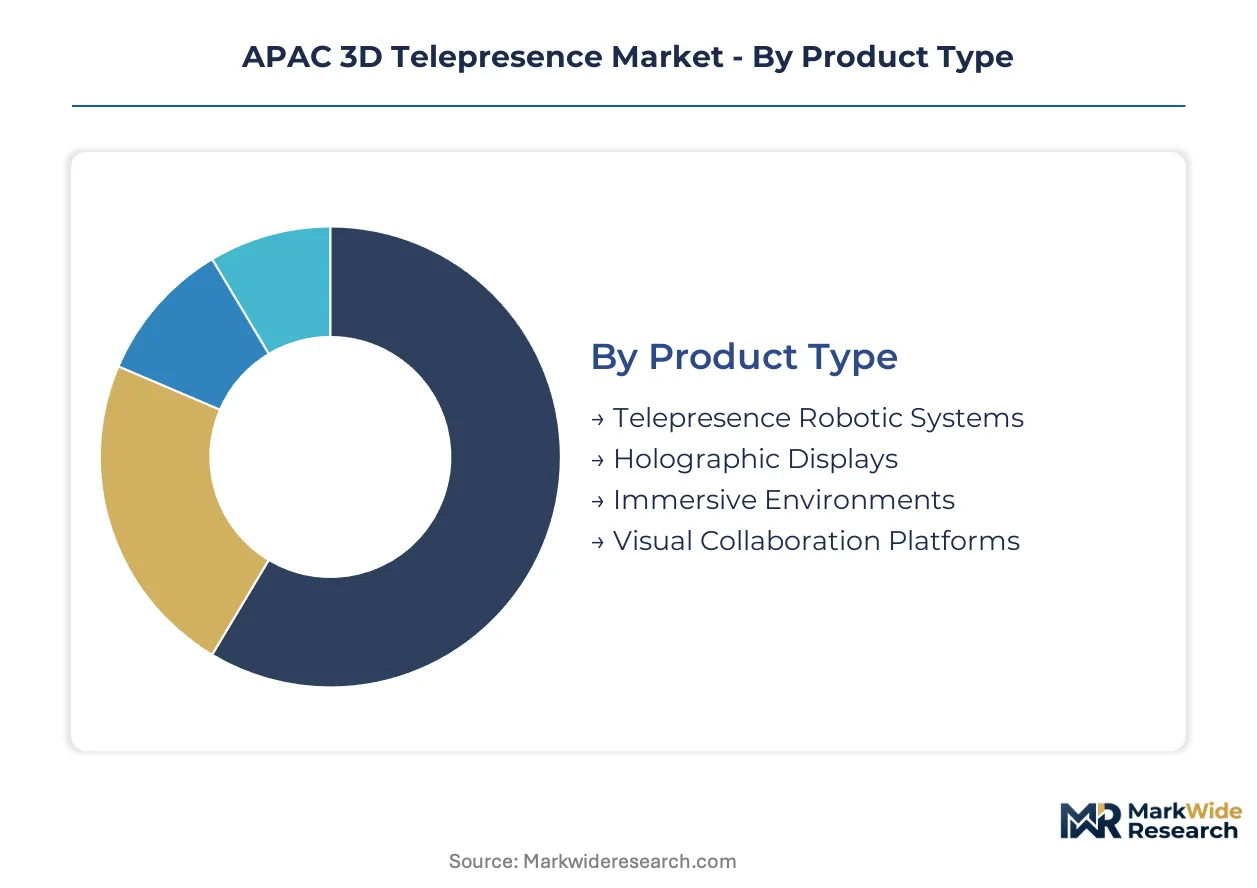
APAC 3D telepresence segmentation reveals divergent refresh cycles across hardware and software layers, with infrastructure-heavy categories demanding multi-year capital planning while cloud-native segments enable quarterly capability upgrades. Procurement patterns in Japanese and Australian enterprise accounts favor longer depreciation schedules for holographic room systems against subscription-renewal rhythms for visual collaboration tools.
Product Type:
Replacement cycles stretch from 18-month software refresh intervals to 7-year hardware infrastructure amortization, compressing vendor revenue recognition timelines for immersive environments while elongating recurring streams for platform providers.
- Holographic Displays:Light-field rendering engines and proprietary optics deliver photorealistic human reconstruction without head-mounted apparatus. Australian healthcare providers and Japanese corporate training centers anchor demand, driven by METI JIS certification requirements for near-field projection safety. Procurement concentrates through Tokyo and Sydney systems integrators bundling installation with network optimization.
- Visual Collaboration Platforms:Software-defined volumetric pipelines transmit spatially accurate remote interaction through standard computing endpoints. ASEAN financial services and mid-market corporate offices across South Korea adopt fastest, displacing capital-heavy hardware purchases with Azure-hosted subscriptions. Cloud-rendered spatial computing sustains recurring revenue models that challenge traditional equipment vendors.
- Immersive Environments:Dedicated room infrastructure integrating capture arrays, spatial audio, and holographic projection surfaces.
- Telepresence Robotic Systems:Mobile volumetric capture and display units for healthcare and education settings, constrained by mechanical reliability standards.
Holographic Displays anchors the volume base while Visual Collaboration Platforms gains share at the steepest rate.
End User:
Customer archetypes diverge sharply on procurement authority, with centralized facilities management in corporate offices enabling six-figure room deployments against distributed clinical budgets in healthcare fragmenting purchasing decisions.
- Healthcare Providers:Australian specialists now routinely incorporate volumetric video for remote diagnostic consultations, creating pull-through demand for medical-grade capture hardware. TGA assessment of diagnostic accuracy claims favors vendors with established clinical validation pathways. China's NMPA and MIIT joint regulation of cross-border telemedicine devices accelerates pre-qualification against dual-jurisdiction requirements.
- Corporate Offices:Hybrid work permanence across Japan and South Korea compresses sales cycles for holographic meeting infrastructure as facilities managers prioritize spatial communication over incremental video conferencing upgrades. Procurement consolidates through regional systems integrators in Tokyo, Seoul, and Sydney.
- Education Institutions:Surgical training simulations and remote laboratory instruction drive pilot deployments, constrained by facility retrofit costs.
- Entertainment Venues:Live event broadcasting and audience-facing holographic performances, currently limited to premium venues in Shanghai and Singapore.
Corporate Offices generates the installed base revenue concentration while Healthcare Providers expands most quickly across the forecast window.
Technology:
Technical foundations separate capital-intensive optical hardware from software-centric rendering approaches, with bandwidth and latency requirements determining addressable geography for each pathway.
- Live Streaming:Real-time volumetric transmission demanding sustained 50-100 Mbps bandwidth with sub-50 millisecond latency for acceptable user experience. Neural radiance field rendering migration from dense point clouds to AI-driven reconstruction compresses requirements to 35-50 Mbps, expanding beyond fiber-rich metropolitan cores into tier-two Chinese and Indonesian cities previously excluded from viable deployment.
- Interactive Software:Compression codecs, spatial computing orchestration, and user interface layers enabling photorealistic reconstruction from sparse camera arrays. Scarce engineering talent familiar with point cloud optimization and neural radiance fields constrains vendor development velocity across the region.
- Virtual Reality:Head-mounted immersive display for individual participants, limited by ergonomic fatigue in extended enterprise sessions.
- Augmented Reality:Overlay volumetric content onto physical environments, finding niche adoption in field service and maintenance applications.
Live Streaming commands the current infrastructure investment while Interactive Software captures the steepest capability advancement trajectory.
Application:
Use case maturity correlates with regulatory clarity, with telemedicine and remote meetings advancing through defined certification pathways while event broadcasting remains experimental.
- Telemedicine Consultations:Volumetric video enables specialist diagnostic depth impossible with conventional video conferencing. Australian TGA assessment protocols and China's NMPA-MIIT joint guidelines create compliance thresholds that favor vendors with cross-jurisdictional validation. Pre-qualification against both requirements accelerates procurement in hospital networks spanning Sydney and Shanghai.
- Remote Meetings:Holographic presence for distributed corporate teams, now standard in Japanese and South Korean headquarters with permanent hybrid protocols. Facilities managers prioritize spatial communication infrastructure over incremental upgrades to flat-panel video conferencing systems.
- Training Sessions:Surgical simulation and technical skill transfer through volumetric demonstration, piloting in South Korean broadcast studios and Japanese corporate academies.
- Event Broadcasting:Live holographic performance and audience engagement, currently limited by production complexity and venue infrastructure requirements.
Remote Meetings provides the revenue foundation while Telemedicine Consultations climbs the fastest as regulatory pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI JIS standards for electromagnetic compatibility and eye safety anchor Japan's regulatory framework, establishing certification baselines that neighboring economies reference for holographic projection equipment deployment.
Japan
Corporate training centers and broadcast studios in Tokyo and Osaka drive holographic system procurement. METI enforces JIS standards on near-field projection safety, compressing vendor qualification timelines. The Kanto region concentrates systems integrator activity bundling installation with network optimization.
China
Cross-border telemedicine networks and 5G enterprise subscribers create dual demand channels. NMPA and MIIT jointly regulate medical-grade volumetric imaging devices, mandating interoperability testing. Shanghai hospital networks pre-qualify vendors against both domestic and Australian TGA requirements.
South Korea
Broadcast studios and corporate headquarters in Seoul pilot neural radiance field rendering for live holographic transmission. The national electronics regulator enforces electromagnetic compatibility standards for volumetric capture hardware. Pangyo Techno Valley clusters software engineering talent for point cloud optimization.
Australia
Specialist diagnostic consultations in Sydney and Melbourne routinely incorporate volumetric video for remote telemedicine. TGA assessment protocols for diagnostic accuracy claims favor vendors with established clinical validation pathways. Healthcare procurement concentrates through Sydney-based systems integrators.
India
Domestic manufacturing of volumetric capture systems accelerates under electronics production incentives. The central government's PLI scheme compresses hardware costs for regional vendor entry. Bengaluru and Hyderabad electronics clusters attract component assembly for holographic display modules.
APAC 3D Telepresence Market Competitive Environment
Established video conferencing vendors and telecommunications equipment manufacturers split the market structure, with cloud infrastructure providers displacing capital-heavy hardware specialists. The vendor base tiers across three strategic archetypes: legacy collaboration platform extenders, carrier-embedded solution bundlers, and specialized holographic optics fabricators. Dominant competitive moves include strategic partnerships with regional systems integrators and technology licensing for volumetric compression algorithms.
Within the legacy extender tier, Cisco Systems Inc. and Microsoft Corporation occupy positions that leverage installed video conferencing relationships for cross-selling immersive room solutions and Azure-hosted spatial computing subscriptions. ZTE Corporation exemplifies the carrier-embedded archetype, anchoring telecommunications partnership strategies across Chinese and Indonesian enterprise connectivity markets. These three entities collectively represent the strategic spectrum from software-centric recurring revenue models to hardware-integrated network service bundles.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Microsoft Corporation |
| ZTE Corporation |
| TelePresence Tech |
| Holoxica Limited |
| Polycom Inc. |
| Digital Video Enterprises Inc. |
| MDH Hologram Ltd. |
| Primasonic Spectrum Private Ltd. |
| Others |
Value Chain & Pricing Dynamics
Pangyo Techno Valley's concentration of neural radiance field engineering talent feeds directly into pricing power for South Korean holographic display vendors serving Australian healthcare and Japanese corporate buyers. Light-field rendering engine specialists command premium positioning against commoditized visual collaboration software.
Pricing Analysis
Price spreads between Tokyo-integrated holographic room systems and cloud-rendered ASEAN subscriptions reflect a three-tier pricing structure across premium, standard, and economy levels. Premium tiers anchor on METI JIS certification and proprietary optics, while mid-market buyers in South Korea and Singapore gravitate toward Azure-hosted subscriptions. Pricing pressure stems from India's PLI scheme compressing domestic hardware costs for volumetric capture modules. Healthcare providers in Sydney and Melbourne exhibit lowest price sensitivity due to TGA-mandated diagnostic accuracy requirements.
Supply Chain Analysis
Extended payment terms from Japanese systems integrators in Tokyo and Osaka are reshaping working capital dynamics for precision lens fabricators. Component supply draws from Japan, South Korea, and Taiwan for spatial light modulators and specialized optics. Raw material dependencies center on rare-earth phosphors, high-purity optical glass, and semiconductor-grade silicon substrates. Single-source vulnerability concentrates in Japanese electromagnetic compatibility testing facilities. Distribution runs through regional systems integrators bundling installation with network optimization contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across METI, NMPA-MIIT, and TGA jurisdictions is fragmenting vendor qualification pathways, creating specialist niches for compliance-native entrants.
For Market Incumbents: Build certification moats by pre-qualifying holographic systems against dual-jurisdiction requirements before procurement cycles open. Deepen backward integration into proprietary light-field rendering engines to defend margin position against cloud-rendered displacement. Anchor capacity in Sydney and Tokyo systems integrator relationships to lock out direct vendor competitors. For New Entrants and Emerging Players: Pursue India's PLI scheme incentives for domestic volumetric capture assembly, exploiting cost compression against incumbent hardware pricing. Target mid-market ASEAN corporate offices seeking software-centric deployment without dedicated room infrastructure. Lead with carrier-agnostic platform positioning to bypass ZTE's embedded telecommunications partnerships. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-software convergence play because recurring revenue models are displacing capital-heavy hardware purchases across the analysis window. Prioritize acquisition targets with established clinical validation pathways for TGA and NMPA-MIIT dual certification. Watch for bandwidth infrastructure buildout in tier-two Chinese and Indonesian cities as inflection signal for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Qualification | Dual-jurisdiction validation against METI JIS and TGA protocols compresses vendor selection timelines for hospital networks. |
| Carrier-Agnostic Platform Development | Azure-hosted spatial computing subscriptions displace capital-heavy hardware purchases in ASEAN financial services. |
| Neural Radiance Field Talent Acquisition | Pangyo Techno Valley engineering clusters enable bandwidth-efficient reconstruction expanding beyond fiber-rich metropolitan cores. |
| Systems Integrator Partnership | Tokyo and Sydney-based integrators bundle installation with network optimization, locking procurement relationships. |
| PLI Scheme Manufacturing Localization | India's electronics incentives compress hardware costs for regional vendor entry in volumetric capture systems. |
Study Parameters
The analysis maps holographic display hardware, visual collaboration platforms, immersive environments, and telepresence robotic systems, each validated through facilities managers, biomedical engineers, telecommunications procurement officers, and cloud platform architects. Primary interviews with hospital purchasing committees in Sydney and Melbourne, corporate IT directors in Tokyo and Seoul, and carrier enterprise sales teams in Jakarta and Shanghai combined with secondary validation against MIIT guidelines, TGA assessment protocols, METI JIS standards, and NMPA medical device filings. Bottom-up vendor revenue triangulation against top-down bandwidth infrastructure deployment data anchored market sizing.
Assumptions held hybrid work permanence and 5G network expansion as fixed conditions, while varying regulatory certification timelines and neural radiance field rendering adoption curves across the projection horizon. Segmentation dimensions modeled include product type, end user archetype, technology foundation, and application use case, with geographic regulatory cluster as an additional industry-specific dimension. CAGRs derived from installed base replacement cycles and subscription renewal velocity. Forecast inputs incorporated bandwidth infrastructure buildout trajectories and PLI scheme manufacturing capacity additions.
Sensitivities concentrate around MIIT guideline revisions, TGA diagnostic accuracy protocol updates, and neural radiance field bandwidth compression breakthroughs. Forecasts reflect documented assumptions on sustained 50-100 Mbps infrastructure deployment and sub-50 millisecond latency availability. Macroeconomic deviation in ASEAN enterprise IT spending, regulatory harmonization between NMPA and TGA, or volumetric compression algorithm breakthroughs would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
3D Machine Vision Market
3D Technology
Europe 3D Telepresence Market
3D Technology
3D Technology Market
3D Technology
Visualization and 3D Rendering Software Market
3D Technology
Global 3D Mapping and 3D Modeling Market
3D Technology
Smartphone 3D Camera Market
3D Technology
3D Photogrammetry Software Market
3D Technology
Spatial Computing Market
3D Technology
Digital Holography Market
3D Technology
3D Mobile Mapping Market
3D Technology
North America 3D 4D Technology Market
3D Technology
3D Scanning Market
3D Technology
Global 3D 4D Technology Market
3D Technology
3D Reconstruction Technology Market
3D Technology
3D Scanner Market
3D Technology
Mobile 3D Market