
 Automated Guided Vehicle (AGV) Market | 2026-2036
Automated Guided Vehicle (AGV) Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Guided Vehicle (AGV) Market Analysis
Leasing and robotics-as-a-service financing is fragmenting capital barriers for mid-size warehouse operators who previously could not afford fleet automation. Toyota Industries Corporation leverages its captive finance arm to bundle vehicles with maintenance contracts, while Daifuku Co., Ltd. anchors premium positioning through in-house production of control systems and navigation software. Seegrid Corporation differentiates via vision-guided technology that eliminates infrastructure modifications, competing directly against magnetic-tape incumbents.
An automated guided vehicle is a mobile robot that follows markers or wires in the floor, uses vision systems, or relies on lidar-based simultaneous localization and mapping to transport materials without human drivers, typically operating at speeds up to 2 meters per second with payload capacities ranging from 500 kilograms to over 50 tons depending on chassis configuration. Its primary commercial purpose is to execute repetitive horizontal transport tasks in controlled environments where labor costs, safety incidents, or throughput precision create economic justification for capital substitution. Unit load carriers dominate installed base in semiconductor fabs and automotive assembly plants where tote-to-line delivery demands high repeatability, while vision guidance technology captures fastest expansion in brownfield warehouses where retrofitting magnetic strips or reflectors proves cost-prohibitive. Tow tractors sustain entrenched positions in airport baggage handling and automotive sequencing yards where tugger trains follow predictable loops with minimal traffic intersection complexity.
The EU Machinery Directive and CE marking requirements enforce functional safety standards on AGV deployments across European manufacturing and logistics facilities, while OSHA workplace safety regulations in the United States mandate risk assessments for human-robot collaborative zones that directly influence sensor redundancy and emergency stop system design. China's GB standards for industrial mobile robots, administered by SAMR, establish electromagnetic compatibility and battery safety thresholds that manufacturers must satisfy for domestic market access. Buyers should monitor how evolving interoperability protocols between competing fleet management platforms reshape vendor lock-in risks and total cost of ownership calculations across multi-site automation programs.
Market Dynamics
Leasing and robotics-as-a-service financing is fragmenting capital barriers for mid-size warehouse operators who previously could not afford fleet automation, compressing payback periods from five years to eighteen months and accelerating replacement cycles for magnetic-tape infrastructure.
Growth Catalysts
- EU Machinery Directive safety mandates:Updated CE marking requirements for collaborative zones are forcing facility upgrades across German automotive plants and French distribution centers, pulling demand for sensor-redundant platforms.
- E-commerce fulfillment density:Parcel sortation hubs in Guangdong province are deploying unit load carriers at scale to manage peak-season throughput spikes without proportional labor expansion.
- Vision-guided navigation maturation:Lidar-based SLAM systems eliminate floor modifications in brownfield warehouses, opening retrofit opportunities in aging industrial corridors across the US Midwest.
Market Restraints
- Lithium battery supply concentration:Cathode material processing dominates in specific East Asian supply chains, exposing fleet operators to cell price volatility and extended lead times for high-capacity packs.
- Technical limitation in dynamic environments:Simultaneous localization and mapping struggles with unpredictable pedestrian traffic in shared human-robot zones, constraining deployment in pharmaceutical cleanrooms with strict contamination protocols.
- OSHA compliance friction:Risk assessment requirements for collaborative operations add six-to-nine month certification timelines that delay revenue recognition for system integrators.
Strategic Opportunities
- Underpenetrated cold chain logistics:Temperature-controlled food distribution in India lacks automated horizontal transport, presenting first-mover advantage for frost-resistant chassis designs.
- Regulatory tailwind from IRA manufacturing incentives:Domestic production credits for battery and semiconductor facilities in the United States are triggering greenfield construction with native AGV corridor integration.
- Technology convergence of 5G and edge computing:Millisecond latency for fleet coordination enables traffic management algorithms that were previously computationally infeasible, unlocking dense multi-vehicle operations in narrow-aisle warehouses.
Industry Challenges
- Controls engineering talent scarcity:Programming expertise for mixed-vendor fleet management platforms commands premium compensation that mid-size integrators struggle to match.
- Legacy warehouse management system integration:Proprietary protocols from incumbent software vendors create middleware development burdens that extend project timelines and erode margin.
- CE marking certification backlog:Notified body capacity constraints for functional safety validation are stretching European deployment schedules beyond contractual delivery windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Guided Vehicle (AGV) Market |
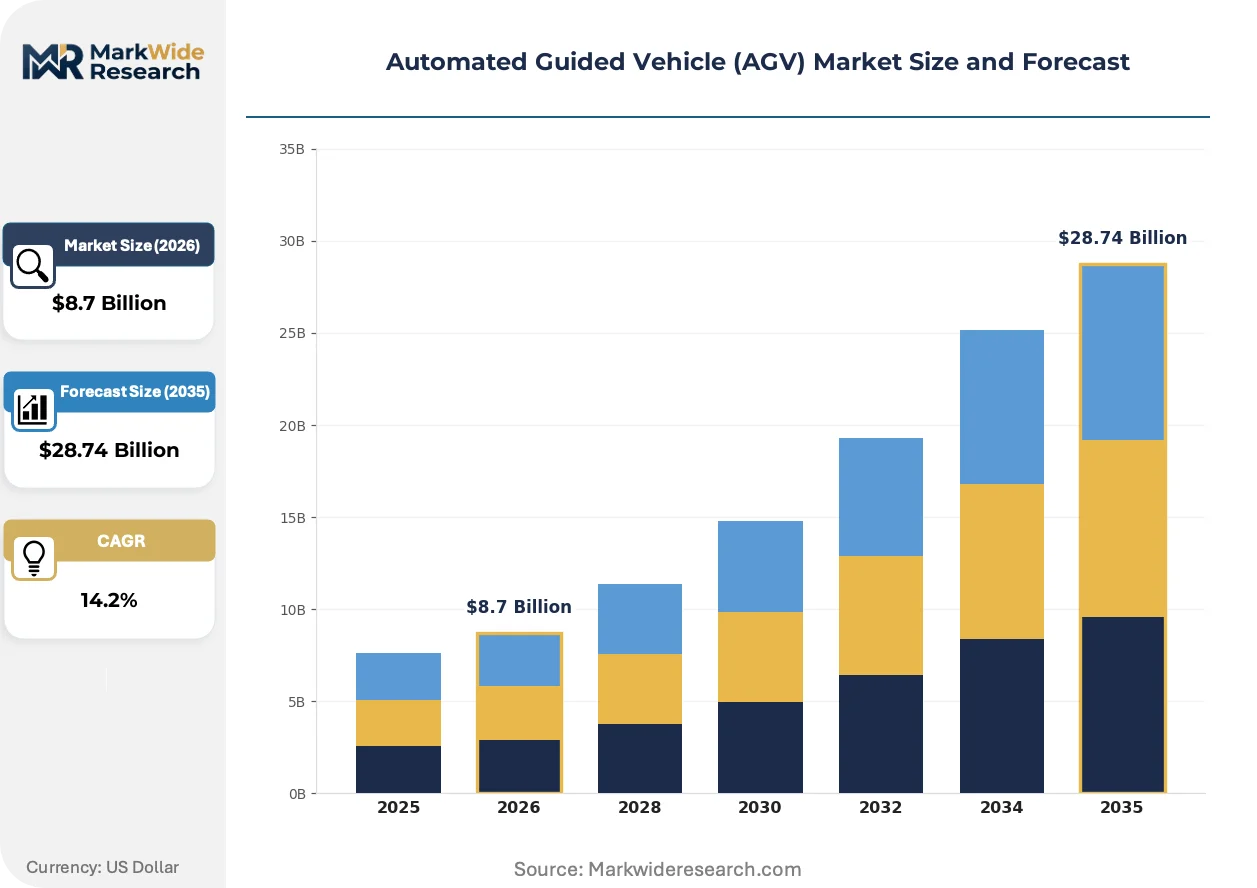
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unit Load Carrier, Pallet Truck, Tow Tractor, Robotic Cart Technology: Lidar, Magnetic Navigation, Vision Guidance, Inductive Guiding End User: Manufacturing, Warehouse, Retail, Healthcare Application: Material Handling, Inventory Management, Assembly Line, Delivery Services |
| Companies Covered | Toyota Industries Corporation, Daifuku Co., Ltd., JBT Corporation, KION Group AG, KUKA AG, Dematic Corp., Seegrid Corporation, Swisslog Holding AG, SSI SCHÄFER Systems International DWC LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Guided Vehicle (AGV) Market Emerging Trajectories
Navigation technology is bifurcating between infrastructure-dependent and infrastructure-agnostic approaches, with each path carrying distinct capital intensity and scalability trade-offs that reshape competitive positioning across end-use verticals.
Lidar-based simultaneous localization and mapping is rendering obsolete magnetic tape and QR-code floor markers in brownfield warehouse retrofits. Third-party logistics operators with multi-site footprints are standardizing on vision-guided platforms to avoid facility-specific engineering. This compression of deployment preparation is shortening vendor selection cycles and favoring technology-agnostic system integrators over hardware-captive suppliers.
The EU Machinery Directive's updated collaborative robot safety annexes are mandating force-limiting controls and redundant emergency stop architectures. Semiconductor fabs in Dresden and automotive sequencing yards in Stuttgart are reconfiguring aisle widths and traffic patterns to accommodate these human-proximity protocols. Vision-guided unit load carriers with certified safety-rated monitored stop functions are capturing specification preference in these regulated environments.
Mid-size warehouse operators are unbundling capital expenditure from operational expenditure through robotics-as-a-service contracts that wrap maintenance, software updates, and performance guarantees into per-pallet-move pricing. This procurement model shift is displacing traditional equipment financing for fleets under fifty vehicles. Food and beverage distribution centers in the Netherlands and pharmaceutical wholesalers in Switzerland are piloting these outcome-based arrangements to preserve balance sheet flexibility.
Automated Guided Vehicle (AGV) Market Segmentation
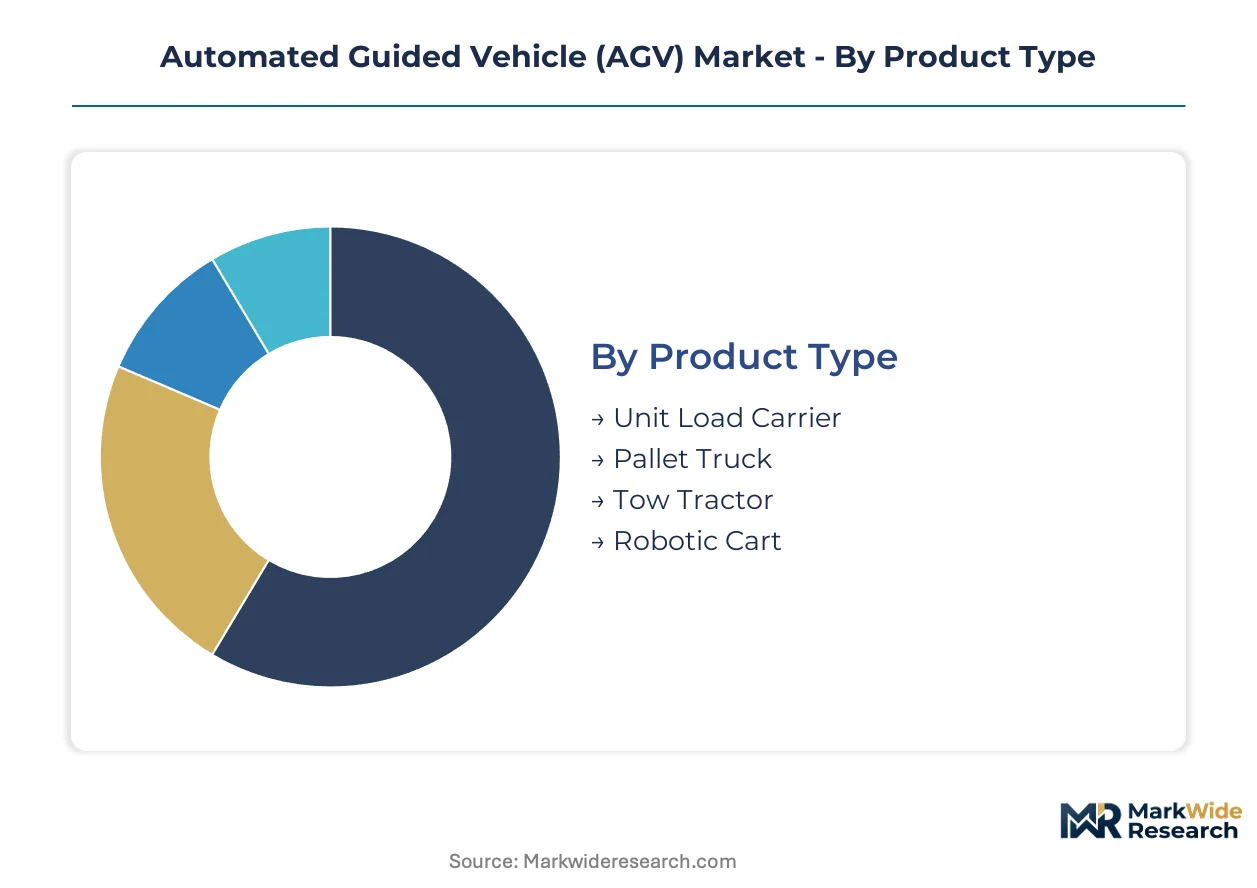
AGV purchasing cycles vary dramatically by product type and technology maturity, with infrastructure-dependent systems requiring 18-24 month replacement windows while vision-guided platforms compress refresh rates to under 12 months. Segment-specific procurement patterns determine vendor pricing power and service attach rates across fleet management contracts.
Product Type:
Unit load carriers and pallet trucks command the shortest replacement cycles due to intensive duty cycles in e-commerce fulfillment, while tow tractors and robotic carts operate on extended depreciation schedules in less demanding loop-based applications.
- Unit Load Carrier:These platforms transport discrete loads on integrated decks with capacities reaching 1,500 kilograms. Semiconductor fabs in Dresden and automotive assembly plants in Stuttgart specify these for tote-to-line delivery where positioning repeatability within 5 millimeters prevents production stoppages. Battery swap architectures dominate here to eliminate charge downtime.
- Pallet Truck:Fork-equipped variants handle European pallet standards (1200x800mm) with lift heights up to 200 millimeters. Cold storage distribution centers in the Netherlands deploy frost-resistant chassis configurations to maintain throughput in -25°C environments where manual labor availability contracts seasonally.
- Tow Tractor:Tugger trains pull multiple trailers along predictable loops at airport baggage facilities and automotive sequencing yards. Magnetic tape guidance sustains entrenched positions here due to minimal traffic intersection complexity and established maintenance protocols.
- Robotic Cart:Compact platforms under 100 kilograms navigate narrow hospital corridors and retail backrooms. Vision guidance eliminates floor modifications in aging healthcare infrastructure where construction disruption risks patient safety compliance.
Unit load carriers anchor the volume base while robotic carts gain share at the steepest rate.
Technology:
Cost tiers separate infrastructure-heavy installations from software-defined alternatives, with capital intensity ranging from 15,000 dollars per vehicle for magnetic systems to 45,000 dollars for lidar-equipped platforms requiring no facility modifications.
- Lidar:Simultaneous localization and mapping enables infrastructure-agnostic navigation through 360-degree environmental scanning. Brownfield warehouses in the US Midwest adopt these systems where floor drilling for reflectors or tape would trigger structural engineering reviews and permitting delays.
- Magnetic Navigation:Buried wire or surface tape systems deliver centimeter-level precision at lowest hardware cost. Airport baggage handling in Frankfurt and Munich maintains specification preference here due to predictable loop topology and minimal pedestrian interference.
- Vision Guidance:Camera-based recognition of ceiling features or floor markers eliminates electromagnetic infrastructure. Third-party logistics operators with multi-site footprints standardize on these platforms to avoid facility-specific engineering at each location.
- Inductive Guiding:Electromagnetic field detection from embedded cables provides navigation in high-interference environments. Heavy manufacturing in Guangdong province deploys these where metal particulate contamination would obstruct optical sensors.
Magnetic navigation retains the largest installed base though lidar is climbing the fastest among new deployments.
End User:
Customer type determines fleet scale and integration complexity, with manufacturing buyers prioritizing line-side precision while warehouse operators emphasize traffic density and retail buyers demand rapid deployment without IT infrastructure overhauls.
- Manufacturing:Automotive sequencing yards and electronics assembly plants require sub-10-millimeter positioning accuracy for just-in-time component delivery. Foxconn and BYD facilities in Guangdong province operate integrated AGV corridors with centralized fleet management platforms coordinating 200+ vehicles per site.
- Warehouse:Parcel sortation hubs and distribution centers optimize for throughput density during peak seasons. German e-commerce fulfillment centers under EU Machinery Directive mandates are retrofitting collaborative zones with force-limiting controls and redundant emergency stop architectures.
- Retail:Backroom inventory replenishment and click-and-colicle order consolidation drive demand for compact footprints. Swiss pharmaceutical wholesalers pilot robotics-as-a-service contracts to preserve balance sheet flexibility while scaling automation.
- Healthcare:Sterile supply transport and pharmacy logistics require contamination-resistant chassis with sealed bearing assemblies. Cleanroom protocols in pharmaceutical manufacturing constrain deployment where simultaneous localization and mapping struggles with unpredictable pedestrian traffic.
Warehouse deployments generate the highest unit volumes while healthcare represents the most rapid expansion trajectory.
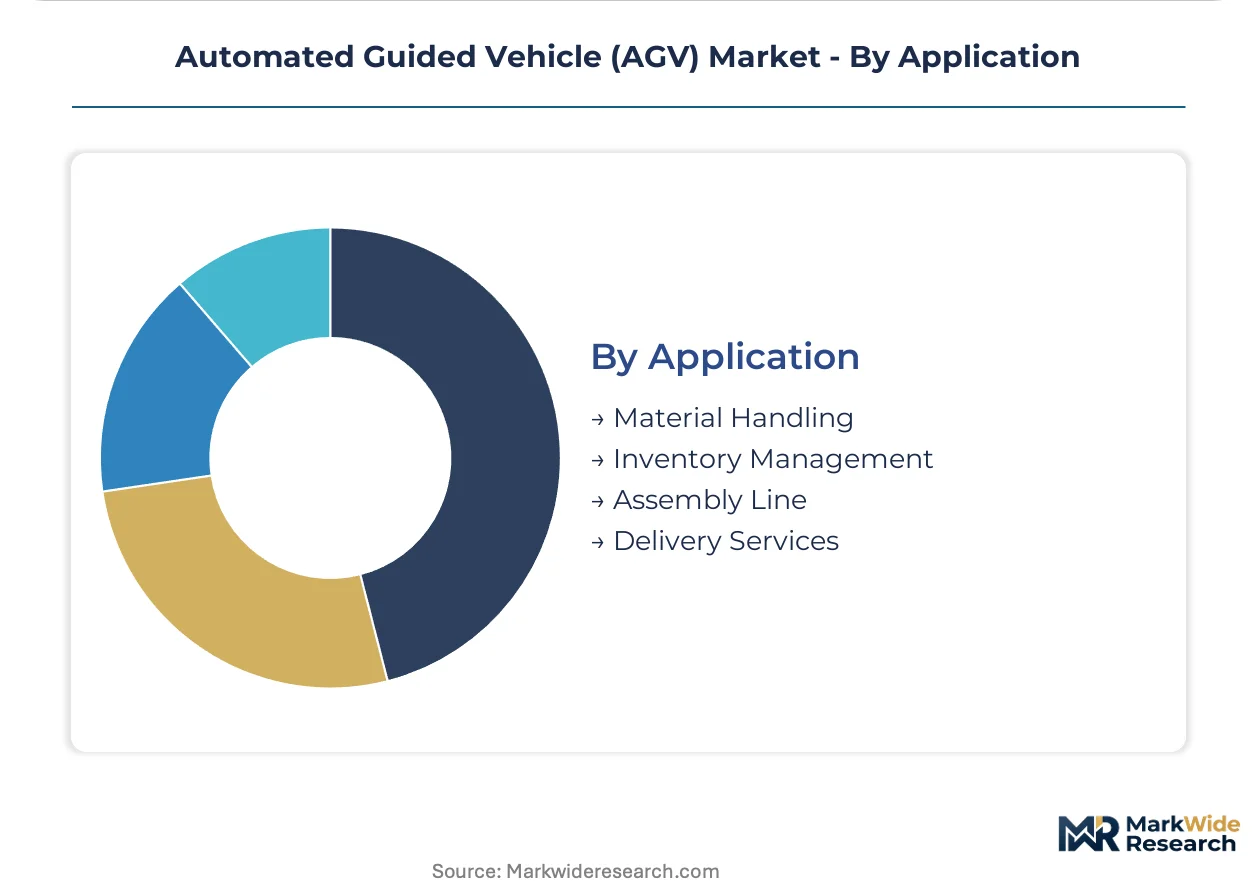
Application:
Maturity stages separate established horizontal transport from emerging use cases, with material handling offering proven return-on-investment models while delivery services remain experimental in last-mile contexts.
- Material Handling:Repetitive pallet movement between dock doors and storage racks constitutes the dominant commercial use case. Unit load carriers with 500-kilogram to 2-ton capacities execute these tasks at speeds up to 2 meters per second in controlled environments.
- Inventory Management:Cycle counting and put-away operations leverage robotic carts with integrated weighing scales and barcode scanners. Vision-guided platforms enable these functions in brownfield facilities without rack-mounted reflector installation.
- Assembly Line:Sequenced component delivery to production stations demands high availability guarantees. Tow tractors with tugger train configurations sustain 99.5% uptime commitments through redundant battery systems and predictive maintenance protocols.
- Delivery Services:Campus and intra-facility mail distribution represents nascent deployment. Healthcare systems in Switzerland evaluate these applications for nighttime pharmacy replenishment when corridor traffic diminishes.
Material handling commands the revenue concentration while inventory management is expanding most quickly among retrofit opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for AGV navigation components and battery systems shapes regional deployment patterns, with manufacturing clusters in East Asia supplying European and North American integrators. Export flows concentrate through specialized logistics corridors serving automotive and semiconductor fabs.
United States
Domestic battery and semiconductor facility construction under IRA manufacturing incentives is triggering greenfield AGV corridor integration. OSHA workplace safety regulations mandate risk assessments for human-robot collaborative zones that directly influence sensor redundancy specifications. Midwest brownfield warehouses in Illinois and Ohio are retrofitting with lidar-based systems to avoid structural permitting delays for floor modifications.
Germany
Automotive sequencing yards in Stuttgart and semiconductor fabs in Dresden are reconfiguring aisle widths under updated EU Machinery Directive collaborative robot safety annexes. CE marking requirements for force-limiting controls and redundant emergency stop architectures are pulling demand for certified platforms. E-commerce fulfillment centers in the Ruhr region are expanding fleet deployments under these mandates.
China
GB standards for industrial mobile robots administered by SAMR establish electromagnetic compatibility and battery safety thresholds for domestic market access. Foxconn and BYD operate mega-factories with integrated AGV corridors in Guangdong province where mega-factory concentration drives unit load carrier demand. Pearl River Delta parcel sortation hubs deploy at scale for peak-season throughput management.
Japan
METI industrial automation initiatives support precision manufacturing upgrades requiring sub-10-millimeter positioning accuracy. JIS standards govern electromagnetic compatibility in high-interference metalworking environments. Kansai region automotive suppliers and Chubu precision equipment manufacturers specify redundant battery architectures to sustain 99.5% uptime commitments.
Netherlands
Cold storage distribution centers deploy frost-resistant chassis configurations to maintain throughput in -25°C environments where manual labor contracts seasonally. Third-party logistics operators with multi-site footprints standardize on vision-guided platforms to avoid facility-specific engineering. Rotterdam port logistics corridors are piloting robotics-as-a-service contracts for balance sheet flexibility.
Automated Guided Vehicle (AGV) Market Vendor Landscape
On the supply side, the industry is consolidating around captive finance arms and in-house control system production, with tiered positioning between infrastructure-dependent and infrastructure-agnostic technology paths. Three strategic archetypes dominate: diversified industrial conglomerates bundling vehicles with maintenance contracts, premium system integrators anchoring positioning through proprietary navigation software, and vision-guided specialists eliminating facility modification requirements. Competitive moves center on M&A for fleet management platform capabilities and strategic partnerships for 5G-enabled edge computing coordination.
Among Japanese industrial conglomerates, Toyota Industries Corporation and Daifuku Co., Ltd. exemplify contrasting positioning archetypes, with the former leveraging captive finance bundling and the latter anchoring premium standing through in-house control system production. Seegrid Corporation occupies the vision-guided specialization tier, representing the infrastructure-agnostic alternative to magnetic-tape incumbents. These three entities collectively illustrate the technology bifurcation reshaping vendor selection cycles and service attach rates across fleet management contracts.
| Leading Market Players |
|---|
| Toyota Industries Corporation |
| Daifuku Co., Ltd. |
| JBT Corporation |
| KION Group AG |
| KUKA AG |
| Dematic Corp. |
| Seegrid Corporation |
| Swisslog Holding AG |
| SSI SCHÄFER Systems International DWC LLC |
| Others |
Supply Flow & Price Mechanics
Guangdong province's cathode material processing clusters anchor global lithium-ion cell supply for AGV power systems, with capacity utilization swings in Shenzhen and Dongguan directly transmitting downstream to fleet procurement pricing power. OEM buyers in German automotive sequencing yards and US Midwest distribution centers face volatile pass-through costs when East Asian cell manufacturers adjust output.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on CE marking certification tier and after-sales service bundling, with sensor-redundant platforms commanding substantial premiums over magnetic-tape equivalents. Cost compression in economy-tier magnetic systems is intensifying because Chinese producers are scaling standardized chassis for domestic e-commerce fulfillment. Mid-size warehouse operators exhibit highest price sensitivity, while semiconductor fabs in Dresden demonstrate lowest elasticity due to uptime guarantee requirements.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for navigation component sourcing. Lidar sensor assembly concentrates in China, South Korea, and Japan, with raw material dependencies spanning rare earth magnets, high-purity silicon, and cobalt-bearing cathodes. Single-source vulnerability in solid-state laser diode supply creates chokepoint exposure for infrastructure-agnostic platform manufacturers. Distribution runs through specialized system integrators who bundle hardware with fleet management software deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward mid-size warehouse operators as robotics-as-a-service financing fragments capital barriers and consolidates procurement leverage among third-party logistics networks.
For Market Incumbents: Build captive finance moats through bundled maintenance contracts and sensor-redundant platform certification. Toyota Industries Corporation's finance arm model demonstrates defensive positioning against pure-play vision-guided entrants. Pursue backward integration into lithium battery pack assembly to secure cell allocation during supply crunches. CE marking certification backlog creates temporary margin protection for pre-qualified suppliers. For New Entrants and Emerging Players: Pursue underpenetrated cold chain logistics in India where frost-resistant chassis designs face minimal incumbent competition. Vision-guided navigation maturation opens brownfield warehouse retrofits in the US Midwest where structural permitting delays deter magnetic-tape installations. Robotics-as-a-service contracts offer the most penetrable go-to-market angle for balance-sheet-constrained operators seeking per-pallet-move pricing. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors infrastructure-agnostic platform developers over magnetic-tape incumbents facing replacement cycle compression. Long-term viability across the projection horizon rests on 5G-enabled edge computing integration for dense fleet coordination. Acquisition targets should demonstrate fleet management software capabilities with multi-site standardization. The signal to watch is OSHA collaborative zone certification timelines, which compress revenue recognition windows and favor pre-certified vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Finance Bundling | Toyota Industries Corporation's maintenance-inclusive contracts reduce customer capital barriers and extend replacement cycle capture. |
| Vision-Guided Platform Development | Seegrid Corporation's infrastructure-agnostic navigation eliminates floor modification costs in brownfield retrofits. |
| CE Marking Pre-Certification | Daifuku Co., Ltd.'s in-house safety system production accelerates EU Machinery Directive compliance for German automotive buyers. |
| Robotics-as-a-Service Launch | Swiss pharmaceutical wholesalers pilot per-pallet-move contracts preserving balance sheet flexibility during automation scaling. |
| 5G Edge Computing Partnership | Millisecond latency fleet coordination unlocks dense multi-vehicle operations in narrow-aisle Netherlands cold storage facilities. |
Methodological Framework
A standing panel of fleet operations directors, system integration engineers, OEM procurement managers, and aftermarket service heads provided ongoing calibration against secondary validation from customs trade data, SEC manufacturing capex disclosures, automotive production databases, and EU Machinery Directive notification records. Bottom-up unit deployment tracking across semiconductor fabs, e-commerce fulfillment centers, and automotive sequencing yards triangulated against top-down industrial automation spend analysis.
Scenario-bracketing around lithium battery price volatility and OSHA certification timeline variations bounded the projection horizon. Segmentation modeling spanned navigation technology, chassis configuration, end-use vertical, and regional regulatory cluster. CAGRs derived from unit shipment trajectories weighted by average selling price evolution across infrastructure-dependent and infrastructure-agnostic platform tiers. Fleet management software attach rates and robotics-as-a-service contract penetration served as industry-specific demand elasticity inputs.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles and East Asian cell supply constraints would shift the trajectory. Forecasts embed assumptions regarding EU Machinery Directive enforcement consistency and 5G infrastructure rollout pace in target warehouse corridors. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Asia Pacific Industrial Robots Market
Robotics and Automation
Japan Cloud Robotics Market
Robotics and Automation
Grafting Robot Market
Robotics and Automation
Solar Panel Cleaning Robot Market
Robotics and Automation
AI Powered Robot Market
Robotics and Automation
Global Wafer Handling Robots Market
Robotics and Automation
Commercial Service Robotics Market
Robotics and Automation
Self-Driving Delivery Robot Market
Robotics and Automation
Underwater Drone Market
Robotics and Automation
Social Robots Market
Robotics and Automation
Wearable Robotic Exoskeleton Market
Robotics and Automation
Short-Range Drone Package Delivery Market
Robotics and Automation
Robotic Tool Changer Market
Robotics and Automation
Robot Label Applicators Market
Robotics and Automation
SLAM Robots Market
Robotics and Automation
Assistive Robotics Market