
 Spain Data Center Physical Security Market | 2026-2036
Spain Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Data Center Physical Security Market Insights
Channel partnerships between systems integrators and security technology vendors is fragmenting as hyperscale operators build direct procurement relationships with equipment manufacturers. Johnson Controls leverages its building automation heritage to bundle physical security with critical infrastructure cooling and power management. Siemens AG anchors its position through integrated command-and-control platforms that unify access control with fire safety and energy systems. Axis Communications AB specializes in network video architectures purpose-built for edge-to-core data center topologies.
Spain data center physical security encompasses layered protection systems designed to safeguard facilities, equipment, and data against unauthorized physical access, environmental threats, and deliberate sabotage, typically integrating biometric authentication, video surveillance with analytics, perimeter intrusion detection, and environmental sensors operating at 99.999% availability thresholds. Access control systems dominate capital allocation as facilities prioritize zero-trust physical entry protocols for server halls and meet-me rooms. Video analytics and artificial intelligence represent the fastest-expanding technology category as operators deploy behavioral analysis and anomaly detection to reduce guard staffing costs. Managed services command premium pricing as financial services and telecommunications end users outsource 24/7 security operations center functions to specialized providers.
Spain's national cybersecurity strategy aligns with EU NIS2 Directive requirements enforced by the National Cryptologic Center and the National Security Scheme, mandating physical security audits for operators of essential services. The Spanish Data Protection Agency imposes additional facility access logging standards that intersect with GDPR Article 32 safeguards for processing locations. Stakeholders must monitor evolving EU critical infrastructure designations that will expand physical security compliance obligations beyond current telecommunications and financial services coverage.
Market Dynamics
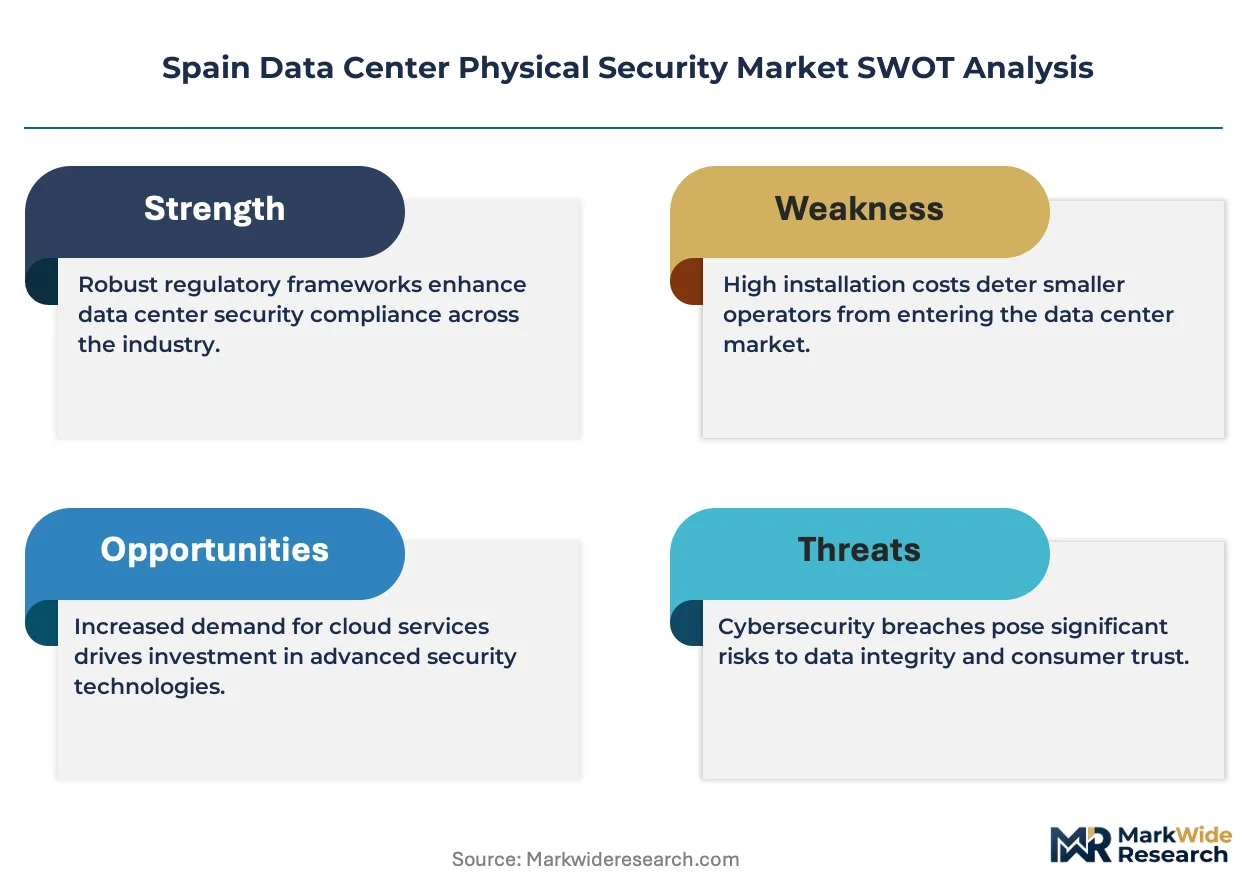
The EU NIS2 Directive is forcing Spanish data center operators to harden physical security postures beyond legacy perimeter defenses, compressing procurement cycles for integrated access control and surveillance architectures.
Growth Catalysts
- EU NIS2 Directive enforcement:Spain's National Cryptologic Center mandates physical security audits for operators of essential services, accelerating capital deployment into biometric authentication and intrusion detection systems.
- Hyperscale colocation expansion:Cloud service providers in Madrid and Barcelona are scaling multi-tenant facilities, generating concentrated demand for zero-trust physical entry protocols and 24/7 security operations center infrastructure.
- Edge-to-core video analytics:Artificial intelligence-powered behavioral analysis reduces guard staffing costs while meeting GDPR Article 32 facility access logging standards imposed by the Spanish Data Protection Agency.
Market Restraints
- Specialized engineering talent scarcity:Integration of physical security with building automation and critical power cooling demands cross-functional expertise that Madrid's technical labor pool cannot supply at scale.
- Copper and semiconductor input volatility:Perimeter intrusion detection cabling and network video encoder chipsets face price instability from concentrated Asian foundry supply.
- GDPR compliance friction:Biometric data storage requirements under Spanish data protection law extend deployment timelines and inflate legal review costs for facial recognition deployments.
Strategic Opportunities
- Andalusia and Valencia corridor underpenetration:Secondary Spanish markets outside Madrid lack tier-three certified facilities, creating first-mover advantage for security-integrated colocation builds.
- Convergence of physical security with fire safety and energy management:Integrated command-and-control platforms unify previously siloed building systems, reducing total cost of ownership for facility operators.
- Managed security services outsourcing:Financial services and telecommunications end users in Barcelona seek specialized providers for 24/7 security operations center functions, shifting revenue from equipment sales to recurring service contracts.
Industry Challenges
- Multi-vendor integration complexity:Legacy access control systems from disparate manufacturers resist seamless integration with modern video analytics platforms, extending deployment timelines.
- Certification timeline compression:Tier IV uptime certification from the Uptime Institute demands synchronized commissioning of physical security, power, and cooling systems, creating project coordination bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Data Center Physical Security Market |
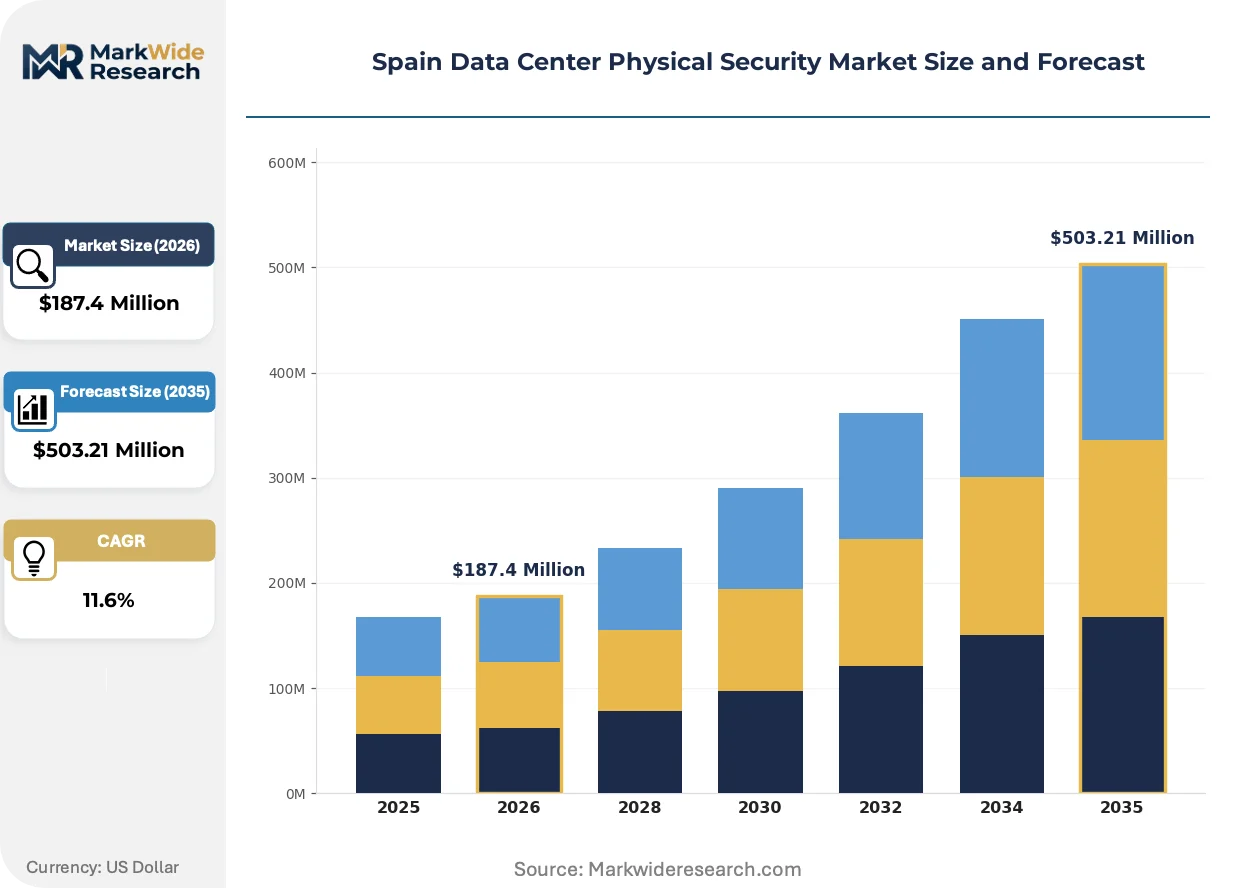
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Security Type: Access Control, Intrusion Detection, Surveillance Systems, Environmental Monitoring End User: Telecommunications, Financial Services, Government, Healthcare Service Model: Managed Services, Consulting, Implementation, Maintenance Technology: Biometrics, RFID, Video Analytics, Artificial Intelligence |
| Companies Covered | Johnson Controls, Siemens AG, Axis Communications AB, Hikvision, Schneider Electric, Bosch Sicherheitssysteme GmbH, Securitas Technology, Genetec, Honeywell International Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Data Center Physical Security Market Trends and Innovations
Artificial intelligence is compressing the value chain between raw sensor data and actionable security intelligence, eliminating intermediate processing layers that previously required dedicated hardware and human interpretation.
Computer vision algorithms with on-camera edge processing are rendering obsolete centralized network video recorder architectures that aggregated footage before analysis. Hyperscale operators in Madrid are deploying these systems at meet-me room entry points to achieve sub-second anomaly detection. The shift collapses infrastructure requirements and eliminates single points of failure in video data pipelines.
Spain's alignment with the EU NIS2 Directive tightens physical security audit mandates for critical infrastructure operators. The National Security Scheme now requires documented penetration testing of perimeter controls and biometric failover protocols. Telecommunications and financial services facilities face the steepest compliance curves, with Madrid-based operators accelerating procurement of integrated access control platforms that automate audit trail generation.
Buyer concentration among hyperscale cloud providers is compressing vendor negotiation leverage and standardizing procurement specifications. Direct relationships between Madrid facility operators and equipment manufacturers are displacing systems integrator intermediaries that historically specified and installed security infrastructure. The channel disintermediation is most visible in the Barcelona metropolitan corridor, where colocation providers now issue unified tenders spanning video surveillance, access control, and environmental monitoring.
Spain Data Center Physical Security Market Segmentation
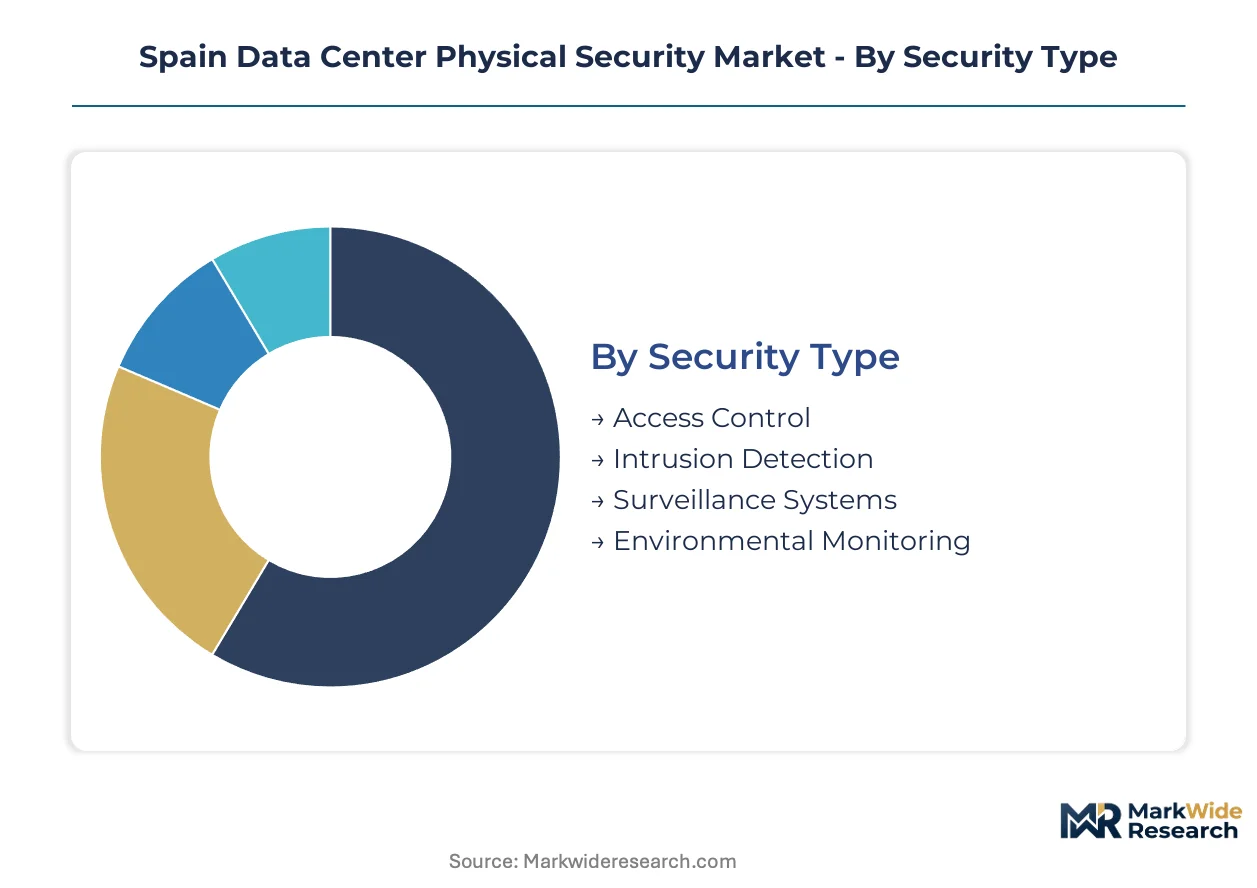
Physical security procurement in Spanish data centers fragments across technology layers, operational models, and compliance-driven end-user requirements. Segmentation reveals where capital concentrates and which integration pathways command premium pricing.
Security Type:
Cost tier determines procurement sequencing, with perimeter hardening preceding interior server hall protection in facility buildouts.
- Access Control:Biometric readers, card credential systems, and mantrap configurations enforce zero-trust entry protocols at meet-me rooms and server halls. Madrid hyperscale facilities allocate disproportionate capital here to satisfy Uptime Institute Tier IV certification requirements for documented entry logging.
- Surveillance Systems:Network video architectures with edge-to-core processing deliver 99.999% availability for continuous monitoring. Barcelona colocation providers deploy these at loading docks and perimeter gates to reduce guard staffing while meeting Spanish Data Protection Agency GDPR Article 32 facility access standards.
- Intrusion Detection:Perimeter sensors and fence-mounted detection cables protect against unauthorized facility breach.
- Environmental Monitoring:Temperature, humidity, and water leak sensors safeguard critical infrastructure from thermal runaway and flooding.
Access Control holds installed capacity. Surveillance Systems is rotating up the share rankings.
End User:
Application-specific compliance mandates reshape procurement specifications across verticals.
- Telecommunications:Operators of essential services under Spain's National Cryptologic Center NIS2 implementation face mandatory physical security audits. Madrid-based carriers accelerate integrated platform deployment to automate audit trail generation and biometric failover documentation.
- Financial Services:Banks and payment processors combine GDPR facility access logging with internal fraud prevention protocols. Barcelona financial institutions outsource 24/7 security operations center functions to specialized managed services providers.
- Government:National Security Scheme compliance drives hardened perimeter standards for state-owned facilities.
- Healthcare:Patient data processing locations require intersection of physical access controls with HIPAA-equivalent Spanish health data protections.
Telecommunications dominates current procurement volume. Financial Services is climbing the fastest.
Service Model:
Customer type and internal capability gaps determine whether operators buy outcomes or build in-house.
- Managed Services:24/7 security operations center outsourcing shifts revenue from equipment sales to recurring contracts. Financial services and telecommunications end users in Barcelona and Madrid seek specialized providers to fill technical labor scarcity in cross-functional security-building automation integration.
- Implementation:Systems integrators historically specified and installed security infrastructure, though hyperscale direct procurement relationships now displace this channel.
- Consulting:Physical security audits and NIS2 compliance gap assessments guide capital allocation sequencing.
- Maintenance:Post-deployment service contracts ensure 99.999% availability thresholds for biometric and video systems.
Implementation holds legacy share. Managed Services is gaining share fastest.
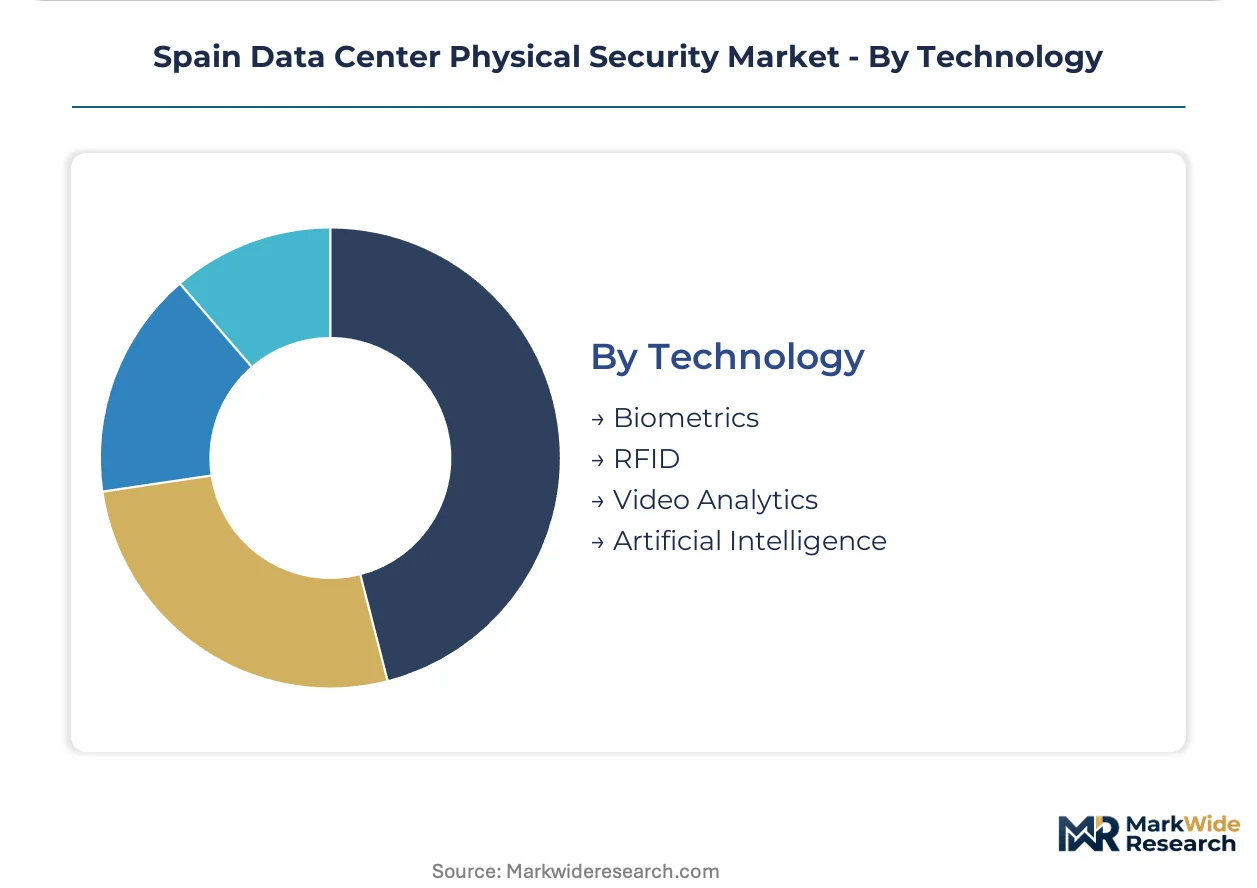
Technology:
Maturity curves and integration complexity separate deployed base from emerging adoption.
- Artificial Intelligence:Computer vision algorithms with on-camera edge processing collapse infrastructure requirements and eliminate single points of failure in video data pipelines. Hyperscale operators deploy these at Madrid meet-me room entry points for sub-second anomaly detection.
- Video Analytics:Behavioral analysis reduces guard staffing costs while meeting GDPR compliance. The technology represents the steepest expansion trajectory as operators replace centralized network video recorder architectures.
- Biometrics:Facial recognition and fingerprint authentication face extended deployment timelines from Spanish data protection law storage requirements and inflated legal review costs.
- RFID:Card credential systems provide foundational access control with lower compliance friction than biometric alternatives.
Biometrics holds installed base. Artificial Intelligence is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Madrid commands pricing premiums unmatched by Andalusian markets, where facility operators absorb higher security integration costs without equivalent procurement scale. Barcelona's colocation corridor narrows this gap through hyperscale tenant concentration. Secondary Spanish regions face structural disadvantages in security technology deployment economics.
Madrid
Hyperscale cloud providers cluster along the metropolitan corridor, driving concentrated demand for zero-trust physical entry protocols and Tier IV certification-aligned security infrastructure. The National Cryptologic Center enforces NIS2 Directive physical security audits for essential service operators headquartered in the capital. Alcobendas and San Sebastián de los Reyes host the densest concentration of multi-tenant facilities with integrated biometric authentication and 24/7 security operations center infrastructure.
Catalonia
Barcelona's financial services sector outsources security operations center functions to managed services providers, shifting procurement from equipment sales toward recurring service contracts. The Spanish Data Protection Agency imposes GDPR Article 32 facility access logging standards that intersect with Catalan regional data sovereignty requirements. The Sant Cugat del Vallès technology corridor attracts colocation builds serving Mediterranean submarine cable landing points.
Basque Country
Industrial data processing facilities serving automotive and machine tool sectors require hardened perimeter protection against targeted sabotage. Basque regional cybersecurity frameworks supplement national NIS2 implementation with additional critical infrastructure designations for manufacturing data centers. Bilbao's port-adjacent facilities integrate maritime supply chain security protocols with physical access control systems.
Andalusia
Secondary market underpenetration creates first-mover advantage for security-integrated colocation builds in Málaga and Seville metro areas. The Junta de Andalucía offers investment incentives for tier-three certified facility construction that meet EU critical infrastructure protection mandates. Current facility stock lacks the biometric failover protocols and automated audit trail generation systems standard in Madrid operations.
Valencia
Emerging demand from logistics and maritime trade data processing drives perimeter intrusion detection procurement at port-adjacent facilities. Valencia's regional government aligns local data center regulations with EU NIS2 physical security requirements ahead of national enforcement timelines. The Parc Tecnològic de Paterna hosts the region's only facilities approaching Madrid-grade security integration standards.
Spain Data Center Physical Security Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying video encoders, biometric readers, and perimeter sensors. The vendor base organizes around three strategic archetypes: building automation conglomerates bundling physical security with critical infrastructure cooling and power management; network video specialists delivering edge-to-core architectures; and managed services providers capturing recurring revenue from 24/7 security operations center outsourcing. Competitive dynamics center on direct procurement relationships displacing systems integrator channels, and convergence plays unifying access control with fire safety and energy management platforms.
Within the building automation tier, Johnson Controls and Siemens AG occupy positions exemplifying integrated command-and-control platform strategies. Axis Communications AB represents the network video specialist archetype with purpose-built architectures for data center topologies. These three companies anchor the competitive structure without exhausting the vendor ecosystem, as specialized biometric providers and regional security services firms populate adjacent market segments.
| Leading Market Players |
|---|
| Johnson Controls |
| Siemens AG |
| Axis Communications AB |
| Hikvision |
| Schneider Electric |
| Bosch Sicherheitssysteme GmbH |
| Securitas Technology |
| Genetec |
| Honeywell International Inc |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Madrid's specialized engineering labor pool compresses deployment timelines and inflates configured-to-order premiums for integrated security-building automation systems. Spanish facility operators absorb these cost premiums to meet National Cryptologic Center NIS2 audit mandates, while hyperscale direct procurement relationships displace systems integrator markups.
Pricing Analysis
The customization-premium spread separates standard RFID card credential systems from biometric mantrap configurations with automated audit trail generation. Project-based pricing dominates procurement, with Tier IV certification-aligned access control commanding substantial premiums over baseline perimeter solutions. Price differentiation hinges on Uptime Institute certification grade and after-sales service bundling. Cost compression in standard surveillance tiers is intensifying because hyperscale buyers issue unified tenders spanning multiple technology layers. Financial services end users in Barcelona exhibit lowest price sensitivity due to GDPR compliance friction and outsourced security operations center requirements.
Supply Chain Analysis
Upstream feedstock constraints in semiconductor fabrication and copper refining tether Spanish data center security deployments to Asian foundry output. Taiwan, South Korea, and China concentrate network video encoder chipset manufacturing, while Chile and Peru anchor copper supply for perimeter intrusion detection cabling. Supply chain risk centers on single-source vulnerability for advanced biometric sensor modules. Distribution runs through direct procurement relationships between Madrid hyperscale operators and equipment manufacturers, bypassing traditional systems integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-functional expertise gaps in security-building automation integration constrain deployment velocity across Spanish facilities, creating persistent bottlenecks for NIS2-compliant infrastructure builds. Madrid's technical labor shortage amplifies these constraints.
For Market Incumbents: Entrench position through backward integration into critical power cooling systems, bundling physical security with building automation to capture recurring service contracts. Deepen channel control by establishing direct procurement protocols with Alcobendas hyperscale operators before emerging platform vendors displace legacy relationships. Certification investment in National Security Scheme compliance documentation represents the priority defensive lever against specialized AI-video analytics entrants. For New Entrants and Emerging Players: Build out managed security services capabilities targeting Barcelona financial institutions seeking 24/7 security operations center outsourcing. The Andalusia corridor offers the most penetrable geography, with Málaga and Seville metro areas lacking tier-three certified facilities with biometric failover protocols. A consulting-led go-to-market angle—delivering NIS2 compliance gap assessments—opens doors for subsequent equipment and service contracts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-powered video analytics sub-segments as edge-to-core architectures demand specialized semiconductor talent and on-camera processing hardware. Long-term viability favors platform integrators with converged command-and-control capabilities spanning access control, fire safety, and energy management. Acquisition targets should demonstrate National Cryptologic Center audit relationships and recurring managed services revenue. The signal to watch is hyperscale procurement standardization—unified tender specifications indicate vendor consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Convergence Investment | Unifies access control with fire safety and energy management, reducing total cost of ownership for Madrid facility operators. |
| Managed Services Buildout | Captures recurring revenue from Barcelona financial services outsourcing 24/7 security operations center functions. |
| Andalusia Geographic Expansion | Establishes first-mover advantage in security-integrated colocation builds across Málaga and Seville metro areas. |
| AI Video Analytics Development | Deploys computer vision with on-camera edge processing to eliminate single points of failure in Madrid meet-me room pipelines. |
| NIS2 Compliance Certification | Automates audit trail generation for National Cryptologic Center physical security mandates affecting telecommunications operators. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs data, and hyperscaler capex disclosures. Primary interviews engaged data center facility managers, physical security systems integrators, biometric technology procurement leads, and National Cryptologic Center compliance officers. Secondary validation drew from EU NIS2 Directive implementation guidance, Spanish Data Protection Agency facility access standards, Uptime Institute certification databases, and SEC filings from publicly traded building automation conglomerates. Bottom-up segmentation modeling triangulated against top-down market sizing from infrastructure investment tracking.
Forecast inputs considered security technology procurement cycles, compliance mandate enforcement timelines, and hyperscale colocation expansion patterns across the analysis window. Segmentation dimensions modeled include security type, end-user vertical, service model, and technology maturity tier. CAGRs derived from regression analysis against historical infrastructure investment correlations with cloud provider facility announcements. Industry-specific forecast inputs encompassed biometric authentication adoption curves and edge-to-core video analytics deployment velocity.
Sensitivities concentrate around EU critical infrastructure designation expansion, semiconductor supply disruption duration, and specialized engineering labor availability in Madrid. Forecasts reflect assumptions regarding NIS2 enforcement consistency and hyperscale procurement standardization trajectories. Cross-checking against Uptime Institute certification database growth rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Transfer Switches and Switchgears Market
Data Center Infrastructure
Data Center Support Infrastructure Market
Data Center Infrastructure
Chile Data Center Processor Market
Data Center Infrastructure
Singapore Data Center Rack Market
Data Center Infrastructure
Data Center Asset Management Market
Data Center Infrastructure
China Data Center Storage Market
Data Center Infrastructure
Global Data Center RFID Market
Data Center Infrastructure
Data Center Renovation Market
Data Center Infrastructure
Advanced Data Center Infrastructure Market
Data Center Infrastructure
Israel Data Center Server Market
Data Center Infrastructure
Low-Cost Energy Data Center Market
Data Center Infrastructure
Long Term Data Retention Solutions Market
Data Center Infrastructure
Jakarta Data Center Market
Data Center Infrastructure
Singapore Data Center Power Market
Data Center Infrastructure
South Africa Data Center Physical Security Market
Data Center Infrastructure
Denmark Data Center Market