
 Canada Anesthesia Devices Market | 2026-2036
Canada Anesthesia Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Anesthesia Devices Market Outlook
Health Canada's Medical Device Licensing framework is recalibrating the cost-of-entry calculus for anesthesia device manufacturers seeking market authorization. B. Braun Melsungen AG leverages its established distribution infrastructure to sustain competitive positioning across provincial procurement networks. Medtronic PLC anchors its presence through R&D intensity in integrated monitoring ecosystems. Draegerwerk AG differentiates via specialized vaporizer engineering that meets Canadian electrical and gas-connector standards.
Anesthesia devices encompass electromechanical and digital systems engineered to deliver precise inhalational and intravenous anesthetic agents while monitoring patient vital parameters such as end-tidal carbon dioxide, oxygen saturation, and airway pressure. These systems serve the primary commercial purpose of enabling controlled, reversible loss of consciousness for surgical and diagnostic procedures in institutional settings. Anesthesia machines and monitoring systems represent the dominant product categories, with digital technology platforms capturing expanding margin pools as hospitals prioritize interoperability with electronic health records. Portable technology variants are gaining traction in ambulatory surgery centers where space constraints and case-volume flexibility drive equipment selection.
Health Canada, the Canadian Standards Association, and provincial health authorities collectively govern device approval, electrical safety certification, and procurement eligibility across Canadian jurisdictions. Health Canada's transition toward enhanced post-market surveillance is elevating documentation burdens for manufacturers while creating compliance-based segmentation between established licensees and new entrants. Stakeholders must monitor evolving provincial bundled-procurement strategies and the pace of digital-health integration mandates to anticipate shifts in purchasing authority and technical specifications.
Market Dynamics
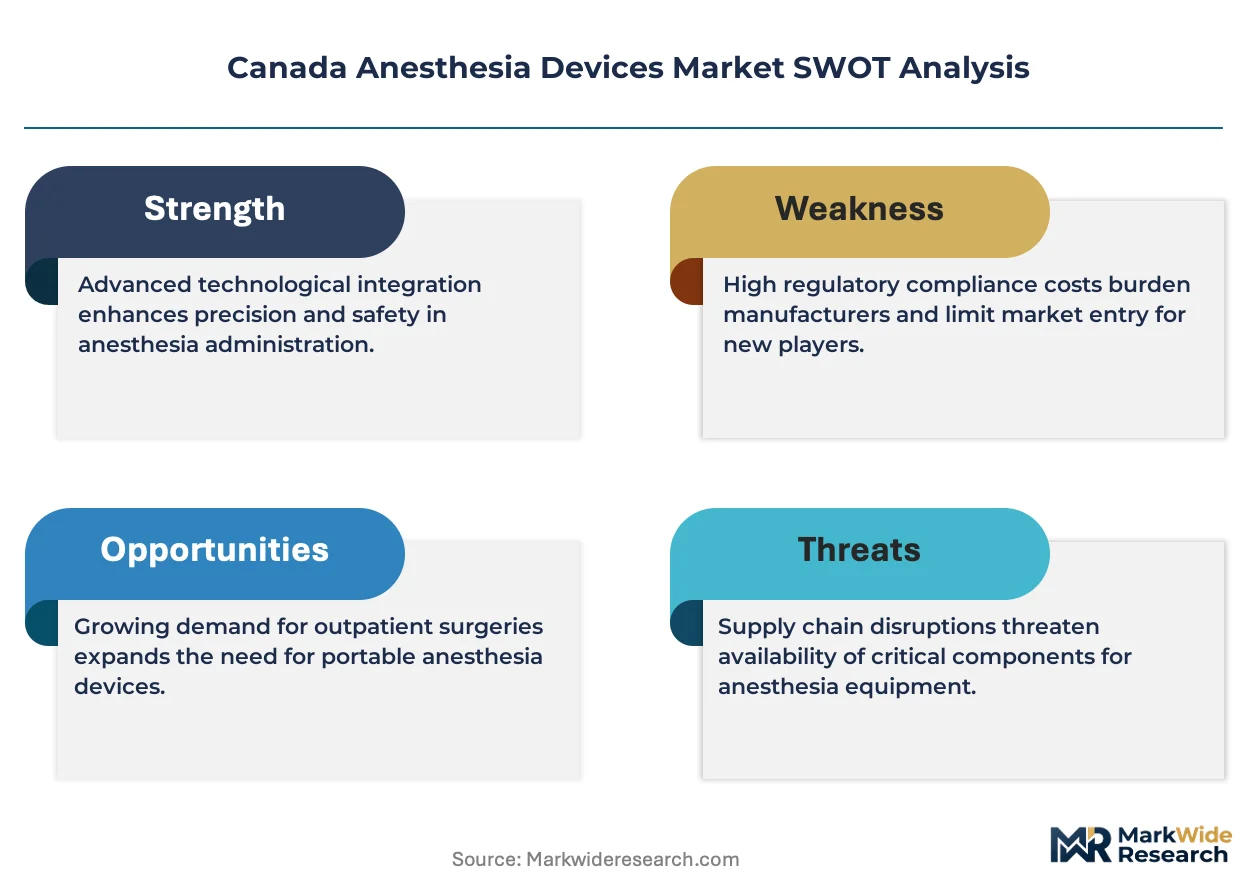
Health Canada's Medical Device Licensing framework is compressing market entry timelines while elevating post-market surveillance obligations, forcing manufacturers to front-load compliance investment before revenue realization.
Growth Catalysts
- Provincial bundled-procurement strategies:Ontario and Quebec health authorities are consolidating anesthesia device purchasing across hospital networks, creating volume incentives for vendors meeting interoperability standards with electronic health record platforms.
- CSA electrical safety certification:Accelerated certification pathways for devices meeting Canadian Standards Association gas-connector and electrical standards are reducing time-to-market for compliant manufacturers.
- Ambulatory surgery center expansion:British Columbia and Alberta are licensing new outpatient surgical facilities, generating demand for portable anesthesia systems with compact footprints and rapid setup protocols.
Market Restraints
- Specialized component supply concentration:Precision vaporizer assemblies and digital flow sensors rely on concentrated North American and European component suppliers, exposing procurement to transatlantic logistics volatility.
- Health Canada documentation burdens:Enhanced post-market surveillance requirements mandate extensive adverse-event reporting infrastructure, disproportionately taxing smaller manufacturers without established regulatory affairs departments.
- Extended capital equipment replacement cycles:Hospital networks are stretching anesthesia machine utilization beyond traditional depreciation schedules, compressing new equipment demand.
Strategic Opportunities
- Atlantic Canada hospital modernization:Newfoundland and Nova Scotia health authorities are replacing legacy anesthesia infrastructure, creating first-mover advantages for vendors with integrated monitoring ecosystems.
- Digital-health integration mandates:Provincial interoperability requirements are opening margin pools for anesthesia platforms with native HL7 FHIR connectivity and automated anesthesia record documentation.
- Remote monitoring convergence:Tele-anesthesia support for rural surgical sites is driving demand for devices with cloud-connected vital parameter streaming and centralized oversight capabilities.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in anesthesia device calibration and preventive maintenance is concentrating in major urban hospital networks, leaving rural facilities dependent on deferred service schedules.
- Legacy system integration complexity:Hospital networks with heterogeneous equipment vintages face interoperability failures when connecting new digital anesthesia platforms to existing patient monitoring networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Anesthesia Devices Market |
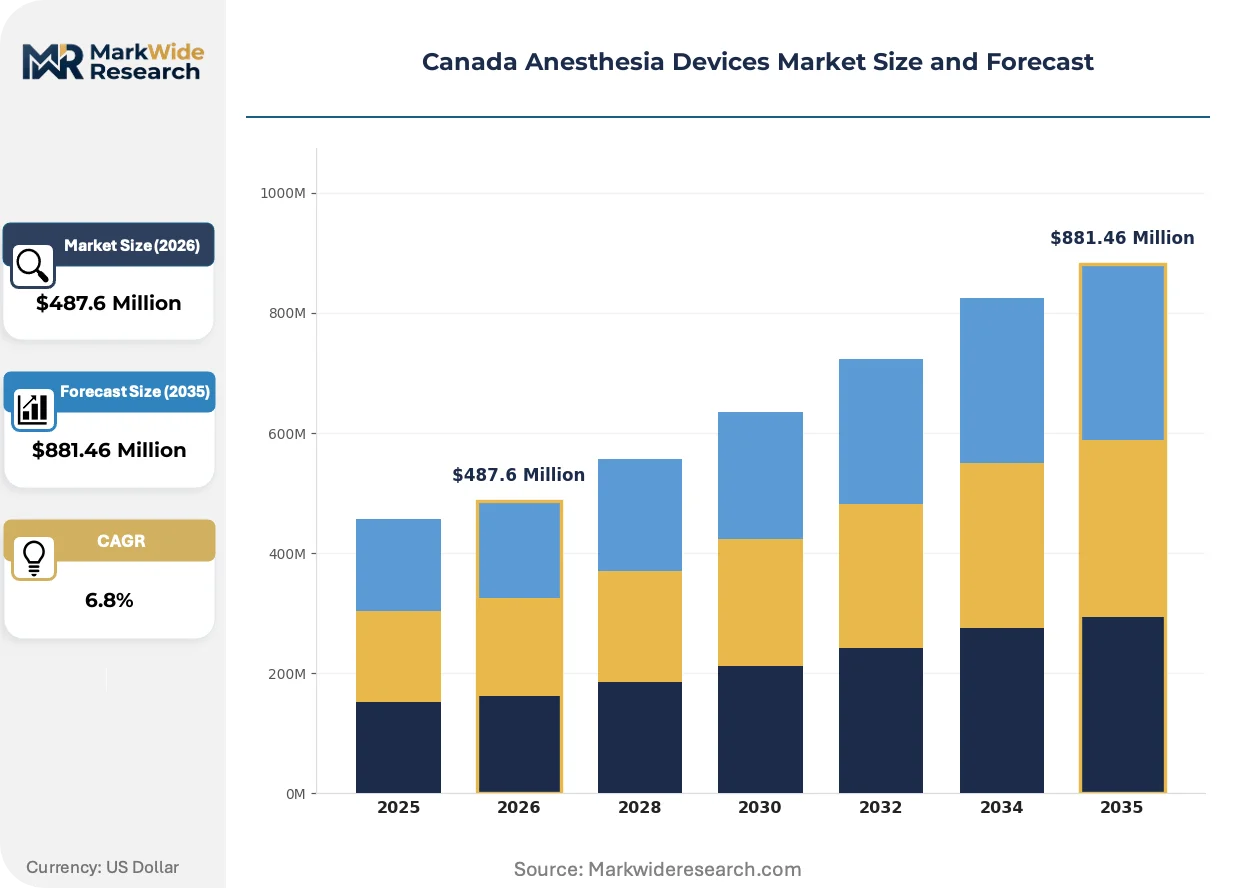
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anesthesia Machines, Monitoring Systems, Vaporizer Devices, Accessories End User: Hospitals, Surgical Centers, Clinics, Ambulatory Surgery Centers Technology: Electromechanical, Digital, Portable, Hybrid Application: General Surgery, Dentistry, Pain Management, Cardiac Procedures |
| Companies Covered | B. Braun Melsungen AG, Medtronic PLC, Draegerwerk AG, Koninklijke Philips, Fisher & Paykel Healthcare, GE Healthcare, Mindray Medical International Limited, Ambu A/S, Smiths Medical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Anesthesia Devices Market Strategic Shifts
Digital anesthesia platforms are compressing the competitive landscape by embedding monitoring, documentation, and decision-support into unified hardware-software architectures that reward R&D-intensive vendors.
Closed-loop anesthesia delivery systems incorporating real-time bispectral index monitoring and automated propofol titration are overtaking manual infusion protocols in tertiary care centers. Ontario teaching hospitals are piloting these systems for complex cardiac and neurosurgical cases. The technology is compressing variability in anesthetic depth management and reducing cognitive load on specialized anesthesia teams.
Health Canada's transition toward enhanced post-market surveillance is elevating documentation burdens for manufacturers while creating compliance-based segmentation between established licensees and new entrants. Device approval timelines are extending for novel vaporizer designs lacking predicate equivalence. Manufacturers are responding by front-loading clinical evidence generation and establishing dedicated Canadian regulatory affairs functions.
Provincial health authorities are consolidating purchasing authority through bundled-procurement frameworks that prioritize total-cost-of-ownership over acquisition price. Ontario and Quebec hospital networks are shifting from capital purchase models toward multi-year equipment-service agreements. This reconfiguration is visible in recent tenders mandating preventive maintenance, software updates, and training inclusion within contract terms.
Canada Anesthesia Devices Market Segmentation
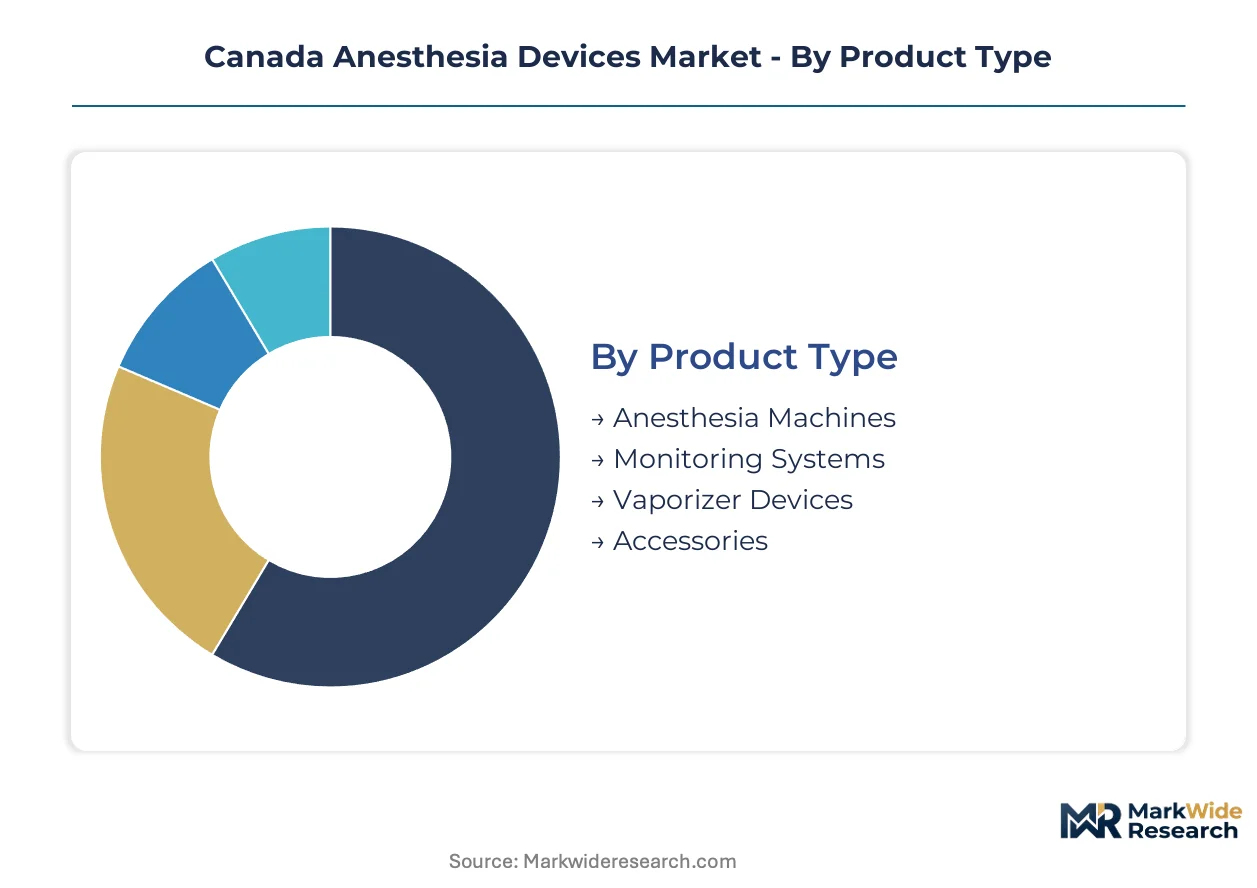
Anesthesia device procurement across Canada fragments across institutional hierarchies, technology vintages, and procedural specializations. Understanding these fault lines clarifies where interoperability mandates and capital replacement cycles concentrate commercial opportunity.
Product Type:
Hospital procurement committees differentiate equipment tiers based on integration depth with existing patient monitoring networks and electronic health record platforms.
- Anesthesia Machines:Electromechanical platforms integrating gas delivery, ventilation, and scavenging systems serve as the procedural backbone in Ontario and Quebec tertiary centers. Health Canada's Medical Device Licensing requirements for predicate equivalence slow novel vaporizer introductions, entrenching established suppliers in hospital networks with extended depreciation schedules.
- Monitoring Systems:Digital platforms capturing end-tidal carbon dioxide, oxygen saturation, and bispectral index data are capturing expanding procurement budgets as provincial interoperability mandates harden. British Columbia health authorities prioritize HL7 FHIR connectivity in recent bundled tenders, favoring vendors with native software architectures over retrofitted legacy equipment.
- Vaporizer Devices:Precision assemblies for desflurane, sevoflurane, and isoflurane delivery maintain concentrated supply relationships with German and Swiss component manufacturers.
- Accessories:Breathing circuits, masks, and filters constitute recurring revenue streams with shorter procurement cycles than capital equipment.
Anesthesia machines lead volumes today; monitoring systems are gaining share fastest.
End User:
Facility licensing status and case-volume profiles determine equipment specifications, with provincial health authorities applying divergent capital allocation frameworks across institutional categories.
- Hospitals:Tertiary and community hospitals in Ontario, Quebec, and Alberta concentrate demand for integrated anesthesia ecosystems with multi-parameter monitoring and automated documentation. Extended replacement cycles—stretching utilization beyond 12-15 years—compress near-term new equipment demand despite aging installed bases.
- Ambulatory Surgery Centers:Outpatient facilities licensed across British Columbia and Alberta prioritize portable anesthesia systems with compact footprints, rapid setup protocols, and lower capital intensity. Space constraints and case-volume flexibility drive procurement toward modular platforms with streamlined maintenance requirements.
- Surgical Centers:Privately operated facilities in urban markets favor leasing arrangements over capital purchase, shifting vendor relationships toward service-inclusive contracts.
- Clinics:Dental and minor procedure clinics concentrate demand for nitrous oxide delivery systems and conscious sedation platforms with simplified operator interfaces.
Hospitals anchor procurement volumes today; ambulatory surgery centers are expanding most quickly.
Technology:
R&D intensity and regulatory compliance investment separate competitive tiers, with digital capabilities increasingly prerequisite for provincial procurement eligibility.
- Digital:Platforms embedding software-defined gas delivery, automated record documentation, and cloud-connected parameter streaming command premium positioning in Ontario teaching hospitals. Closed-loop anesthesia delivery incorporating real-time bispectral index monitoring is overtaking manual protocols in cardiac and neurosurgical cases.
- Portable:Compact electromechanical systems with battery backup and rapid deployment protocols serve British Columbia and Alberta ambulatory surgery centers where facility flexibility overrides integration depth. Reduced calibration requirements and simplified preventive maintenance address biomedical engineering scarcity in rural markets.
- Electromechanical:Established pneumatic and mechanical systems dominate legacy installed bases awaiting replacement in Atlantic Canada hospital modernization programs.
- Hybrid:Architectures combining digital monitoring interfaces with electromechanical delivery mechanisms bridge interoperability requirements with capital cost constraints.
Digital platforms command the steepest expansion trajectory; electromechanical systems retain largest installed base.
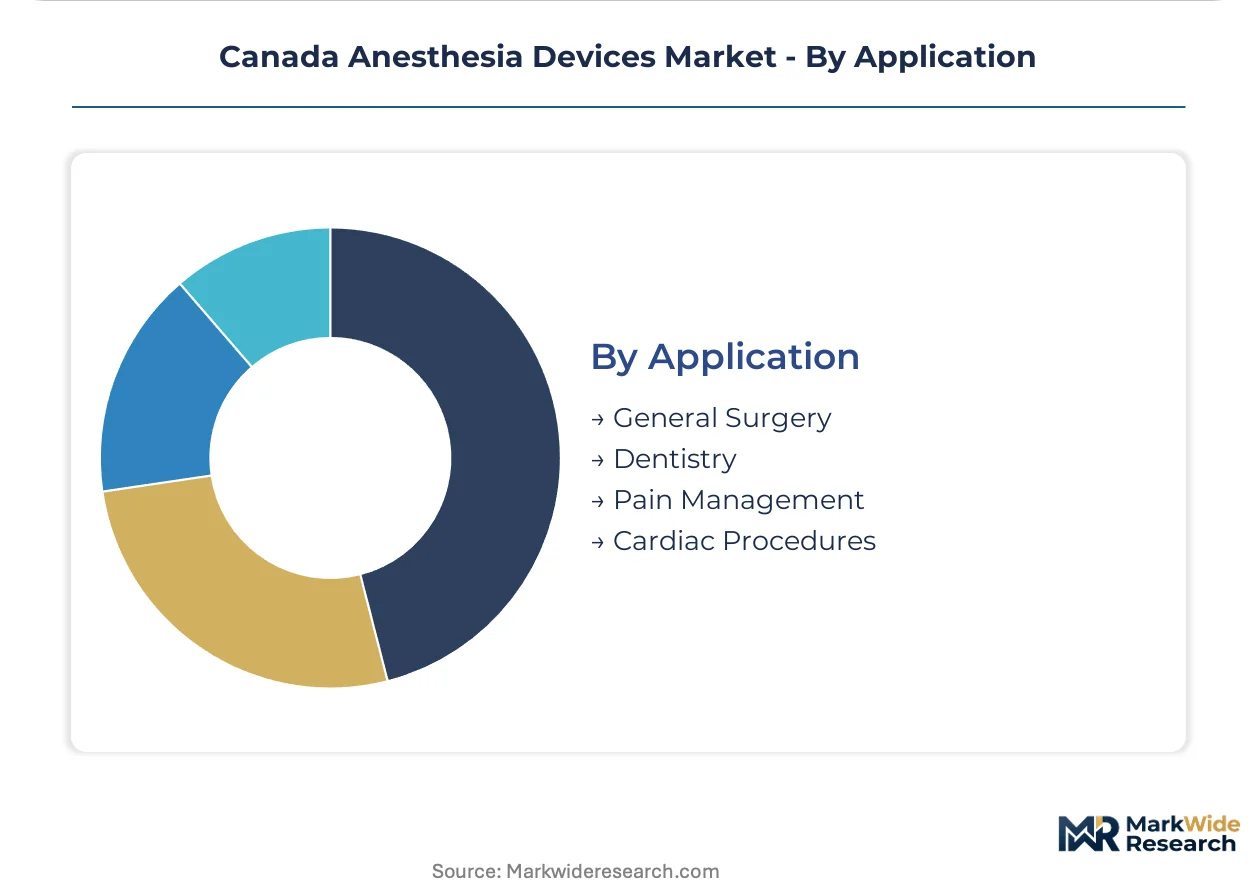
Application:
Procedural complexity and reimbursement frameworks shape equipment specification intensity across surgical specialties.
- General Surgery:Abdominal, orthopedic, and trauma procedures generate baseline demand for versatile anesthesia platforms with broad agent compatibility and standard monitoring configurations. Ontario hospital networks prioritize total-cost-of-ownership frameworks incorporating preventive maintenance and training in procurement evaluations.
- Cardiac Procedures:Complex cases requiring precise hemodynamic control and rapid anesthetic depth modulation drive demand for closed-loop delivery systems and advanced monitoring ecosystems. Tertiary centers in Quebec and Alberta pilot automated propofol titration protocols with real-time feedback loops.
- Pain Management:Chronic pain clinics and interventional suites concentrate demand for regional anesthesia delivery and neuromodulation compatibility.
- Dentistry:Conscious sedation and nitrous oxide administration in oral surgery and pediatric dentistry favor simplified operator interfaces and compact equipment footprints.
General surgery leads procedure volumes today; cardiac applications show strongest technology upgrade intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized anesthesia technologists and biomedical engineers concentrate in Ontario and Quebec hospital networks, creating talent gravity that shapes equipment procurement patterns across provincial health systems.
Ontario
Toronto and Ottawa teaching hospitals drive demand for closed-loop anesthesia delivery systems with integrated monitoring ecosystems. Health Canada's Medical Device Licensing requirements for predicate equivalence slow novel vaporizer introductions, entrenching established suppliers. The Greater Toronto Area anchors procurement volume for digital platforms with HL7 FHIR connectivity.
Quebec
Montreal cardiac centers pilot automated propofol titration protocols with real-time bispectral index feedback loops. The province's bundled-procurement frameworks prioritize total-cost-of-ownership over acquisition price. McGill University Health Centre and affiliated networks concentrate demand for advanced monitoring ecosystems in complex surgical cases.
British Columbia
Vancouver and Lower Mainland ambulatory surgery centers prioritize portable anesthesia systems with compact footprints and rapid setup protocols. Provincial interoperability mandates favor vendors with native software architectures. The region's outpatient facility licensing expansion generates demand for modular platforms with streamlined maintenance.
Alberta
Calgary and Edmonton hospital networks stretch anesthesia machine utilization beyond traditional depreciation schedules, compressing near-term replacement demand. The province's health authorities are licensing new outpatient surgical facilities. Rural surgical sites in Southern Alberta drive emerging interest in tele-anesthesia support with cloud-connected parameter streaming.
Atlantic Canada
Newfoundland and Nova Scotia health authorities are replacing legacy anesthesia infrastructure in St. John's and Halifax. First-mover advantages accrue to vendors with integrated monitoring ecosystems addressing modernization backlogs. Biomedical engineering scarcity in the region favors equipment with reduced calibration requirements.
Canada Anesthesia Devices Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered procurement channels in Canadian anesthesia devices. The vendor base clusters around three strategic archetypes: diversified medical technology conglomerates with full-spectrum portfolios, anesthesia-focused specialists with concentrated R&D investment, and regional distributors leveraging established service networks. Consolidation pressure intensifies as provincial bundled-procurement frameworks reward scale and interoperability depth. Dominant competitive moves include multi-year equipment-service agreements replacing capital purchase models and backward integration into precision vaporizer component supply.
Among Germany-based diversified manufacturers, B. Braun Melsungen AG and Draegerwerk AG occupy positions reflecting deep anesthesia specialization within broader medical technology portfolios. Medtronic PLC represents the North American conglomerate archetype with integrated monitoring ecosystem capabilities. These three exemplify how geographic origin and corporate structure shape competitive positioning within Health Canada's regulatory framework.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Medtronic PLC |
| Draegerwerk AG |
| Koninklijke Philips |
| Fisher & Paykel Healthcare |
| GE Healthcare |
| Mindray Medical International Limited |
| Ambu A/S |
| Smiths Medical |
| Others |
Value Chain & Pricing Dynamics
Family-owned German and Swiss precision component specialists anchor vaporizer manufacturing, translating concentrated upstream ownership into disciplined pricing power across Canadian procurement networks. Their captive control over desflurane and sevoflurane delivery assemblies constrains margin compression even as Health Canada documentation burdens elevate compliance costs.
Pricing Analysis
The bundled-versus-unbundled service split separates capital purchase agreements from multi-year equipment-service contracts across Ontario and Quebec hospital networks. Three-tier pricing structure across premium, standard, and economy levels reflects interoperability certification grade and preventive maintenance inclusion. Pricing pressure stems from provincial bundled-procurement frameworks prioritizing total-cost-of-ownership over acquisition price. Ambulatory surgery centers in British Columbia exhibit highest price sensitivity due to constrained capital budgets, while tertiary cardiac centers in Montreal and Toronto demonstrate lowest sensitivity given procedural complexity requirements.
Supply Chain Analysis
Precision vaporizer assemblies rest on concentrated German and Swiss specialty component producers, with digital flow sensors drawing from North American semiconductor fabricators. Critical inputs encompass precision-machined aluminum vaporizer chambers, piezoelectric flow sensors, and medical-grade polymer breathing circuits. Single-source vulnerability concentrates in desflurane-specific vaporizer engineering where predicate equivalence requirements slow alternative supplier qualification. Distribution runs through provincial health authority procurement frameworks and established hospital network service contracts, with B. Braun and Draegerwerk leveraging direct field service organizations for aftermarket capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Health Canada's Medical Device Licensing framework operates as a regulatory compounder, with enhanced post-market surveillance mandates accelerating demand for compliant integrated monitoring ecosystems.
For Market Incumbents: Hedge against margin compression by deepening backward integration into precision vaporizer component supply and establishing dedicated Canadian regulatory affairs functions. Threat substitution from closed-loop anesthesia delivery systems demands accelerated R&D investment in automated propofol titration protocols. Certification investment in HL7 FHIR connectivity represents the critical lever for sustaining provincial procurement eligibility. For New Entrants and Emerging Players: Enter via Atlantic Canada hospital modernization programs in Newfoundland and Nova Scotia, where legacy infrastructure replacement creates first-mover opportunities absent entrenched supplier relationships. The most penetrable segment encompasses rural surgical sites dependent on tele-anesthesia support with cloud-connected parameter streaming. A service-inclusive contract model addressing biomedical engineering scarcity offers the strongest go-to-market angle against capital-purchase incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap anesthesia monitoring specialists with native software architectures and incomplete Canadian regulatory filings. Long-term viability across the projection horizon favors vendors with integrated hardware-software platforms capable of capturing multi-year equipment-service agreement renewals. The signal to watch is Health Canada predicate equivalence determination timelines for novel vaporizer designs.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Medical Device Licensing Pathway | Accelerated approval timelines for CSA-certified devices compress competitive entry windows for established licensees. |
| Hospital System Partnership | Ontario bundled-procurement frameworks reward vendors with embedded training and preventive maintenance infrastructure. |
| Software Companion Development | Native HL7 FHIR connectivity captures provincial interoperability mandates in British Columbia and Quebec tenders. |
| Backward Integration into Vaporizer Supply | Captive precision component production insulates margin structures from transatlantic logistics volatility. |
| Reimbursement Strategy | Alignment with provincial digital-health integration mandates opens margin pools for automated documentation platforms. |
Study Parameters
Direct dialogue with hospital purchasing committee members, biomedical engineering directors, anesthesia department heads, and provincial health authority procurement officers grounded the qualitative foundation. Secondary validation drew from Health Canada Medical Device Licensing databases, CSA electrical safety certification records, hospital procurement tender documents, and GPO contract repositories. Bottom-up and top-down triangulation reconciled equipment shipment data with provincial capital budget allocations.
Bottom-up modeling segmented the market across product type, end user, technology, and application dimensions, with value outputs derived from average selling price analysis across capital purchase and service-inclusive contract structures. CAGRs were computed from installed base replacement cycles, ambulatory surgery center licensing expansion rates, and digital-health integration mandate implementation timelines. Forecast inputs incorporated Health Canada predicate equivalence approval velocity and provincial bundled-procurement framework adoption curves.
Inputs from Health Canada licensing databases and provincial tender repositories were available through the study window; gaps in real-time adverse-event reporting infrastructure utilization introduce uncertainty bands around post-market surveillance cost assumptions. Forecasts reflect documented assumptions regarding regulatory timeline stability and provincial budget continuity. Regulatory framework acceleration, supply chain disruption, or biomedical engineering labor scarcity revisions warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Fluidics for Preclinical Market
Medical Devices
Pressotherapy Systems Market
Medical Devices
Medical Bionic Implant Market
Medical Devices
Actigraphy Sensors & PSG Devices Market
Medical Devices
Global Wearable Injectors Market
Medical Devices
Laryngoscopes Market
Medical Devices
Europe Urinary Catheters Market
Medical Devices
3D Printed Prosthetics Market
Medical Devices
Incubator Devices Market
Medical Devices
Global Endovascular Aneurysm Repair Devices Market
Medical Devices
Incontinence Devices and Ostomy Market
Medical Devices
Auto Keratometer Market
Medical Devices
At-Home Blood Collection Kits and Devices Market
Medical Devices
Global Joint Pain Injections Market
Medical Devices
Brazil Contraceptive Devices Market
Medical Devices
Medical Electrodes Market