
 Medical and Industrial Gloves Market | 2026-2036
Medical and Industrial Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Medical and Industrial Gloves Market Foresight
Aftermarket service revenue for glove inventory management and compliance auditing is tilting toward integrated suppliers with direct hospital contracts. Top Glove Corporation Bhd leverages its Klang Valley production base to anchor bulk procurement relationships with American distributors. Hartalega Holdings Berhad differentiates through automated nitrile lines that sustain premium positioning in examination-grade segments. Ansell Ltd. competes via specialized chemical-resistant portfolios targeting pharmaceutical manufacturing environments.
Medical and industrial gloves are barrier-protective wearables manufactured from elastomeric compounds—nitrile butadiene rubber, natural latex, or synthetic polyisoprene—typically ranging from 3 to 8 mils in thickness, designed to prevent pathogen transmission and chemical permeation in occupational settings. The nitrile material segment leads volume output due to latex allergy mitigation and superior puncture resistance, while vinyl retains share in food processing applications where cost sensitivity dominates. Chemical-resistant gloves within the industrial product category represent the fastest-growing margin pool as semiconductor and battery manufacturing expand solvent-handling requirements.
The US FDA enforces Quality System Regulation and 510(k) clearance pathways for surgical gloves, while OSHA's Personal Protective Equipment standards mandate hazard-specific glove selection in industrial workplaces. Malaysia's Department of Standards Malaysia (DSM) and rubber board certifications shape export eligibility for Klang Valley producers serving European and North American buyers. Stakeholders must monitor evolving EU MDR requirements for medical device classification and anticipate how dual-carbon regulatory pressures in major manufacturing jurisdictions will reshape nitrile versus natural rubber sourcing calculus.
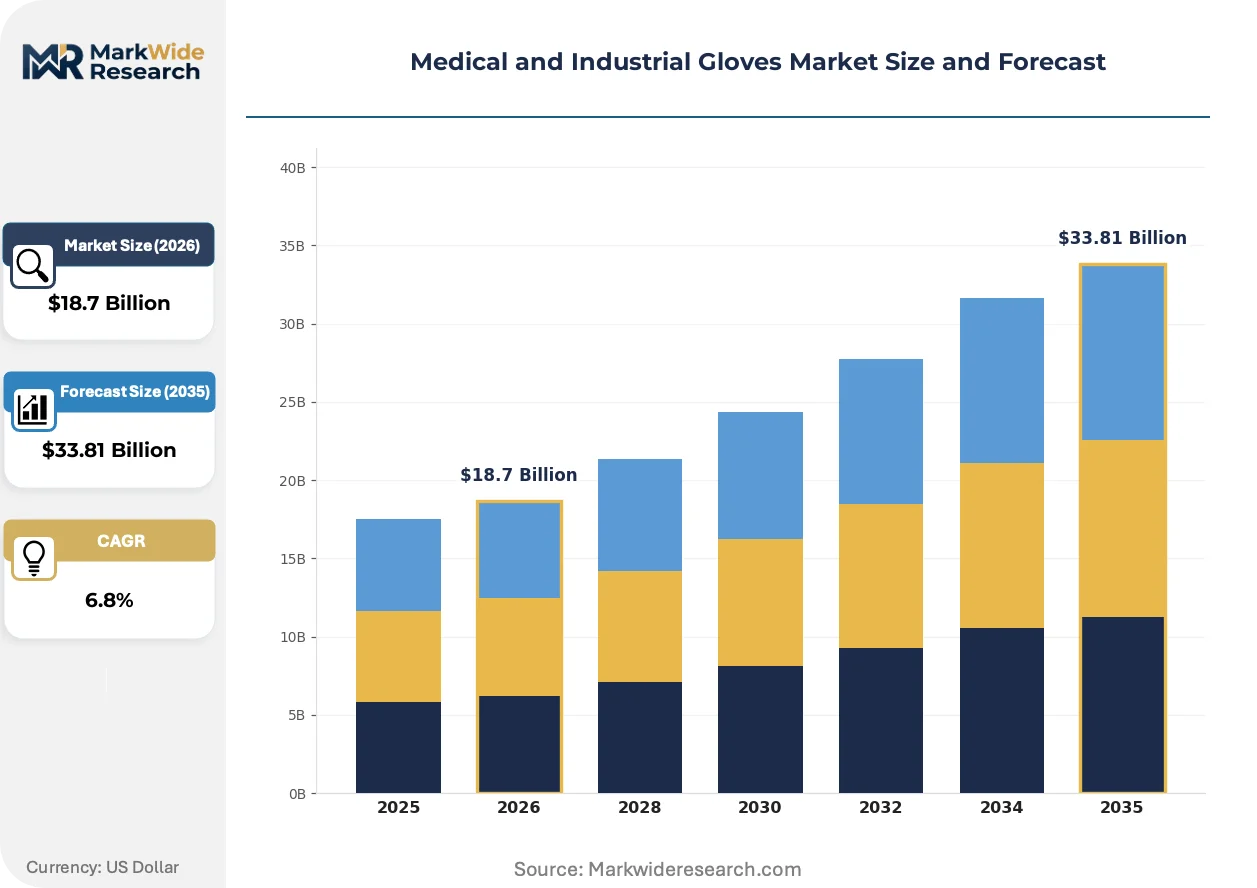
Market Dynamics
Healthcare systems are consolidating procurement around integrated suppliers capable of delivering compliance documentation alongside bulk nitrile volumes, compressing distributor margins and privileging manufacturers with captive rubber processing.
Growth Catalysts
- FDA Powder-Free Mandate:The US FDA's prohibition on powdered surgeon's gloves is eliminating legacy latex inventories and redirecting hospital procurement toward nitrile alternatives that meet ASTM D6319 puncture-resistance thresholds.
- Semiconductor Chemical Handling:Solvent-intensive battery and chip manufacturing is expanding demand for multilayer nitrile-neoprene blends that withstand aggressive etching agents in cleanroom environments.
- Klang Valley Production Cluster:Malaysia's integrated rubber processing corridor concentrates nitrile butadiene rubber supply with adjacent dipping lines, yielding cost structures unattainable by fragmented competitors.
Market Restraints
- Acrylonitrile Price Volatility:Nitrile butadiene rubber feedstock costs fluctuate with petrochemical cycles, compressing margins for non-integrated glove producers lacking captive acrylonitrile supply agreements.
- Single-Geography Supply Concentration:Overreliance on Malaysia's Klang Valley exposes buyers to monsoon-related logistics disruptions and concentrated regulatory intervention from the Department of Standards Malaysia.
- Biodegradability Gap:Nitrile's synthetic polymer structure resists landfill decomposition, creating compliance friction with EU Green Deal circular-economy mandates and extended producer responsibility frameworks.
Strategic Opportunities
- India's Healthcare Infrastructure Expansion:The country's PLI scheme for medical textiles is incentivizing domestic glove manufacturing to reduce import dependence from Southeast Asian suppliers.
- Automated Compliance Auditing:RFID-enabled glove inventory tracking is creating recurring revenue streams for suppliers embedding sensors in hospital supply chains.
- REACH-Compliant Bio-Based Alternatives:ECHA's tightening restrictions on synthetic polymer additives is opening market space for polyhydroxyalkanoate-based gloves in European food processing.
Industry Challenges
- 510(k) Clearance Timelines:Surgical glove manufacturers face 12-18 month FDA review cycles for new nitrile formulations, delaying product launches behind unregulated industrial variants.
- Cleanroom Certification Complexity:ISO 14644 compliance for semiconductor-grade gloves requires particle-count validation protocols that extend quality assurance headcount and capital equipment requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical and Industrial Gloves Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical, Examination, Industrial, Chemical-Resistant Material: Latex, Nitrile, Vinyl, Neoprene Application: Healthcare, Food Processing, Pharmaceutical, Manufacturing End User: Hospitals, Clinics, Laboratories, Factories |
| Companies Covered | Top Glove Corporation Bhd, Hartalega Holdings Berhad, Ansell Ltd., Kossan Rubber Industries Bhd, Supermax Corporation Berhad, Cardinal Health, 3M Company, Honeywell, Mölnlycke AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical and Industrial Gloves Market Shifts & Advancements
Material science advances and regulatory stringency are converging to redefine performance benchmarks across medical and industrial glove categories, with automation and traceability emerging as competitive differentiators.
Multilayer nitrile-neoprene laminates are hybridizing barrier properties to address aggressive chemical permeation in battery manufacturing. Semiconductor fabs are adopting these hybrids for solvent-handling operations at accelerated replacement cycles. The technology is hybridizing what were previously distinct industrial and chemical-resistant product lines into unified portfolios.
REACH Annex XVII restrictions on N-nitrosamines in rubber articles are forcing reformulation of accelerant packages in nitrile production. Glove manufacturers serving EU medical device markets are substituting carbamate-based curing systems for thiuram alternatives. The surgical glove segment bears the highest compliance burden, with notified body re-certification consuming 8-14 months.
Hospital systems are unbundling glove procurement from broadline distributor contracts to establish direct manufacturer relationships with embedded inventory management. IDN consolidation in the US is enabling this disintermediation by concentrating purchasing power. The shift is most visible in multi-hospital networks across Texas and Florida seeking guaranteed supply continuity post-pandemic.
Medical and Industrial Gloves Market Segmentation
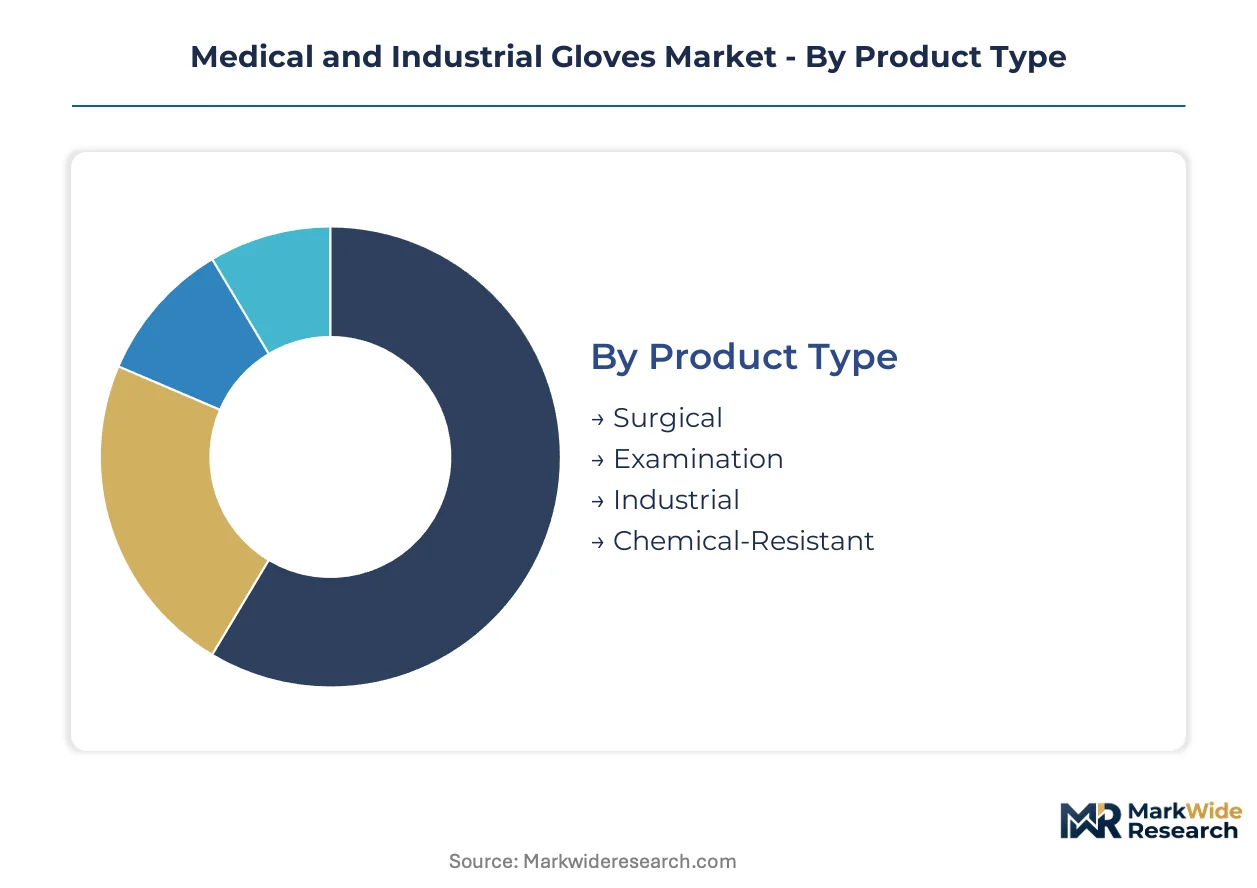
Segmentation in the glove market maps directly to regulatory pathways and procurement economics. Each dimension—product grade, material chemistry, and end-use environment—carries distinct certification requirements and margin profiles that reshape supplier positioning.
Product Type:
The maturity spectrum spans decades-old surgical formats against emerging chemical-resistant architectures.
- Examination:Nitrile-dominant single-use gloves meeting ASTM D6319 puncture-resistance thresholds. Hospital systems in Texas and Florida are consolidating procurement around bulk nitrile volumes with embedded RFID tracking for inventory compliance.
- Surgical:Higher-mil thickness formulations requiring FDA 510(k) clearance under Quality System Regulation. The 12-18 month review timeline for new nitrile formulations compresses innovation cycles relative to unregulated industrial variants.
- Industrial:General-purpose barrier protection for mechanical hazards in assembly operations. Malaysian Klang Valley producers leverage integrated rubber processing for cost-competitive supply to American distributors.
- Chemical-Resistant:Multilayer nitrile-neoprene laminates engineered for solvent permeation resistance. Semiconductor fabs in Germany and South Korea are adopting these for aggressive etching agent handling at accelerated replacement cycles.
Examination gloves retain volume leadership; chemical-resistant formats hold the steepest expansion curve.
Material:
Cost tier stratification separates premium elastomers from commodity alternatives.
- Nitrile:Synthetic nitrile butadiene rubber delivering latex-allergy mitigation and superior puncture resistance. Acrylonitrile feedstock volatility from petrochemical cycles compresses margins for non-integrated producers lacking captive supply agreements.
- Latex:Natural rubber formulations facing structural decline from FDA powder-free mandates and allergy liability exposure. Legacy inventories are clearing from North American hospital supply chains.
- Vinyl:Polyvinyl chloride compounds dominating food processing applications where cost sensitivity outweighs performance requirements. ECHA REACH restrictions on plasticizer additives are forcing reformulation for European market access.
- Neoprene:Chloroprene-based synthetics blended into multilayer industrial formats for chemical permeation resistance. Cleanroom certification under ISO 14644 extends quality assurance overhead for semiconductor-grade variants.
Nitrile commands revenue concentration; neoprene blends are gaining share fastest in industrial chemical handling.
Application:
Customer type divergence separates regulated medical environments from industrial hazard management.
- Healthcare:Infection control protocols in hospital systems are tightening procurement standards around examination-grade nitrile. IDN consolidation enables direct manufacturer relationships that disintermediate broadline distributors.
- Pharmaceutical:Aseptic manufacturing environments requiring sterile glove formats with low particulate shedding. FDA enforcement of 510(k) pathways creates compliance moats around surgical-grade suppliers.
- Manufacturing:Mechanical and chemical hazard protection across automotive and electronics assembly. OSHA Personal Protective Equipment standards mandate hazard-specific glove selection protocols.
- Food Processing:Cost-optimized vinyl and nitrile formats subject to FDA Food Contact Substance regulations. EU Green Deal circular-economy mandates are creating friction with nitrile's biodegradability limitations.
Healthcare anchors procurement volume; pharmaceutical applications are climbing the fastest on aseptic manufacturing expansion.
End User:
Supply concentration maps to geographic clustering of demand density and procurement sophistication.
- Hospitals:Multi-hospital networks with consolidated purchasing power negotiating direct contracts with Klang Valley manufacturers. Post-pandemic supply continuity concerns have unbundled glove procurement from broadline agreements.
- Laboratories:Research and diagnostic facilities requiring chemical-resistant portfolios for solvent handling. REACH Annex XVII N-nitrosamine restrictions are forcing accelerant reformulation for EU-serving suppliers.
- Clinics:Outpatient facilities with lower volume but higher SKU fragmentation in procurement. Automated compliance auditing is emerging as a service differentiator for integrated suppliers.
- Factories:Industrial workplaces under OSHA mandate for hazard-specific protective equipment. Semiconductor and battery manufacturing expansion is driving solvent-handling glove requirements.
Hospitals retain volume leadership; laboratories hold the steepest expansion curve on pharmaceutical R&D growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia's Klang Valley corridor concentrates over half of global nitrile butadiene rubber glove output, creating supply dependencies that reshape procurement strategies across hospital systems and industrial buyers worldwide.
United States
Texas and Florida hospital networks are unbundling glove procurement from broadline distributor contracts to secure direct manufacturer relationships with embedded RFID inventory tracking. FDA enforcement of the powder-free mandate under 21 CFR 878.4460 continues eliminating legacy latex inventories from acute care supply chains. Houston-based IDN consolidation enables multi-hospital purchasing power that compresses intermediary margins.
Germany
Semiconductor fabs in Dresden and Munich are driving demand for multilayer nitrile-neoprene gloves that withstand aggressive etching agents in ISO 14644 cleanroom environments. ECHA REACH Annex XVII restrictions on N-nitrosamines in rubber articles are forcing accelerant reformulation for EU medical device market access. Bavarian chemical-resistant glove specialists face 8-14 month notified body re-certification timelines.
China
Battery manufacturing expansion in Jiangsu and Guangdong provinces is accelerating solvent-handling glove requirements for lithium-ion cell production lines. NMPA enforcement of GB 10213 standards for single-use rubber gloves shapes domestic product specifications for hospital procurement. Yangtze River Delta integrated producers are backward integrating into acrylonitrile supply to hedge petrochemical feedstock volatility.
India
The PLI scheme for medical textiles is incentivizing domestic glove manufacturing capacity in Tamil Nadu and Gujarat to reduce import dependence from Southeast Asian suppliers. CDSCO medical device rules under the Drugs and Cosmetics Act create compliance pathways for surgical-grade nitrile producers. Maharashtra's pharmaceutical manufacturing belt is driving aseptic glove demand for sterile formulation operations.
South Korea
Memory chip and display panel fabrication in Gyeonggi-do and Chungcheong regions is expanding chemical-resistant glove procurement for photoresist and solvent handling. MFDS enforcement of medical device quality management standards shapes import requirements for examination-grade nitrile. Busan-Ulsan industrial clusters are adopting accelerated glove replacement cycles for cleanroom contamination control.
Medical and Industrial Gloves Market Competitive Landscape
Integrated Malaysian producers and specialized chemical-resistant specialists split the market along supply chain depth versus formulation expertise lines. Klang Valley manufacturers leverage captive nitrile butadiene rubber processing and adjacent dipping infrastructure to anchor cost structures unattainable by fragmented competitors. Three archetypes dominate: vertically integrated Southeast Asian volume producers, European precision-formulation specialists, and American healthcare-distributor hybrids. Competitive dynamics center on backward integration into acrylonitrile supply and strategic partnerships for cleanroom certification acceleration.
Within the integrated production tier, Top Glove Corporation Bhd and Hartalega Holdings Berhad exemplify scale-driven positioning anchored to Malaysia's rubber processing corridor. Kossan Rubber Industries Bhd occupies a position between volume manufacturing and specialized industrial formulations. Among diversified healthcare suppliers, Ansell Ltd. represents the chemical-resistant specialization archetype with pharmaceutical manufacturing focus. Cardinal Health exemplifies the American distributor-manufacturer hybrid model serving hospital system consolidation trends.
| Leading Market Players |
|---|
| Top Glove Corporation Bhd |
| Hartalega Holdings Berhad |
| Ansell Ltd. |
| Kossan Rubber Industries Bhd |
| Supermax Corporation Berhad |
| Cardinal Health |
| 3M Company |
| Honeywell |
| Mölnlycke AB |
| Others |
Supply & Pricing Matrix
Port Klang container freight corridors transmit acrylonitrile cost volatility directly into nitrile butadiene rubber pricing, amplifying spreads between integrated Klang Valley producers and non-captive competitors while hospital procurement consolidation compresses distributor markups.
Pricing Analysis
ASTM D6319 certification tiers dictate the pricing tier structure across examination-grade nitrile procurement. Three-tier pricing structure across premium, standard, and economy levels separates surgical-grade 510(k)-cleared formats from industrial variants and food-contact vinyl alternatives. Cost compression in standard examination gloves is intensifying because Malaysian integrated producers leverage captive rubber processing. Hospital IDNs exhibit lowest price sensitivity due to supply continuity premiums, while independent clinics face highest budget constraints.
Supply Chain Analysis
Export-control restrictions on nitrile butadiene rubber polymerization catalysts limit technology transfer to emerging producers. Supply concentrates in Malaysia, Thailand, and Vietnam for dipping-line capacity, while acrylonitrile feedstock draws from South Korean and Chinese petrochemical complexes. Single-source vulnerability runs through Klang Valley monsoon logistics disruptions. Distribution runs through American distributor-manufacturer hybrids and European chemical-resistant specialists serving semiconductor fabs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from pandemic inventory destocking cycles, with hospital procurement normalization and battery manufacturing expansion providing cyclical uplift momentum.
For Market Incumbents: Entrench position by deepening backward integration into acrylonitrile supply agreements and accelerating ISO 14644 cleanroom certification for semiconductor-grade formats. Emerging Indian PLI-subsidized competitors threaten Southeast Asian volume dominance. Certification investment in EU MDR compliance creates defensive moats against notified body re-certification delays.
For New Entrants and Emerging Players: India's Tamil Nadu and Gujarat manufacturing corridors under PLI scheme incentives represent the most penetrable entry point for surgical-grade nitrile capacity. REACH-compliant bio-based polyhydroxyalkanoate alternatives for European food processing open formulation white-space. Partner with Maharashtra pharmaceutical manufacturers for aseptic glove validation protocols.
For Investors and Strategic Acquirers: European precision-formulation specialists with pharmaceutical manufacturing focus offer acquisition exposure to chemical-resistant margin expansion. Long-term viability hinges on cleanroom certification acceleration capabilities and dual-carbon regulatory adaptation. Watch ECHA REACH Annex XVII enforcement intensity as inflection indicator for accelerant reformulation costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylonitrile Supply | Captive feedstock agreements with South Korean petrochemical producers hedge margin compression from price cycles. |
| ISO 14644 Cleanroom Certification Acceleration | Semiconductor fabs in Dresden and Gyeonggi-do demand validated particle-count protocols for solvent-handling gloves. |
| EU MDR Notified Body Re-Certification | Eight-to-fourteen-month review timelines for thiuram-to-carbamate accelerant substitution lock in compliance moats. |
| RFID-Enabled Inventory Management Embedding | Texas and Florida hospital IDNs unbundle procurement from broadline distributors for direct manufacturer relationships. |
| PLI Scheme Capacity Buildout in India | Tamil Nadu and Gujarat manufacturing reduces import dependence from Klang Valley suppliers for CDSCO-regulated surgical formats. |
Research Methodology
A standing panel of hospital procurement directors, GPO contracts managers, biomedical engineers, and rubber processing plant managers provided ongoing calibration across primary interviews combined with secondary validation from FDA 510(k) filings, Malaysian Department of Standards export certifications, and customs trade data. Bottom-up volume modeling triangulated against top-down macroeconomic elasticity checks.
Scenario-bracketing around acrylonitrile price cycles and monsoon logistics disruption probability shaped projections across the analysis window. Segmentation dimensions included product grade, material chemistry, end-use environment, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating semiconductor fab expansion rates and hospital IDN consolidation velocity.
Macroeconomic conditions sit as an overlay; deviation in petrochemical feedstock costs and freight corridor congestion would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and substitution elasticity. Material shifts in EU Green Deal biodegradability mandates or FDA powder-free mandate expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Disposable Oxygen Masks Market
Medical Supplies
United States Intravenous Solutions Market
Medical Supplies
Centrifuge Bottles Market
Medical Supplies
Tracheostomy Tray Market
Medical Supplies
Surgical Collagen Powders Market
Medical Supplies
Global Surgical Masks Market
Medical Supplies
US Disposable Face Mask Market
Medical Supplies
Middle East and Africa Medical Rubber and Balloon Products Market
Medical Supplies
Single Use Safety Lancet Market
Medical Supplies
Pressure Redistribution Pads Market
Medical Supplies
Italy Ostomy Care and Accessories Market
Medical Supplies
Cryogenic Vials and Tubes Market
Medical Supplies
Europe Medical Gloves Market
Medical Supplies
Global Dried Blood Spot Collection Cards Market
Medical Supplies
Colostomy Bags Market
Medical Supplies
Plastic Bandages Market