
 Asia-Pacific People Screening Market | 2026-2036
Asia-Pacific People Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific People Screening Market Insights
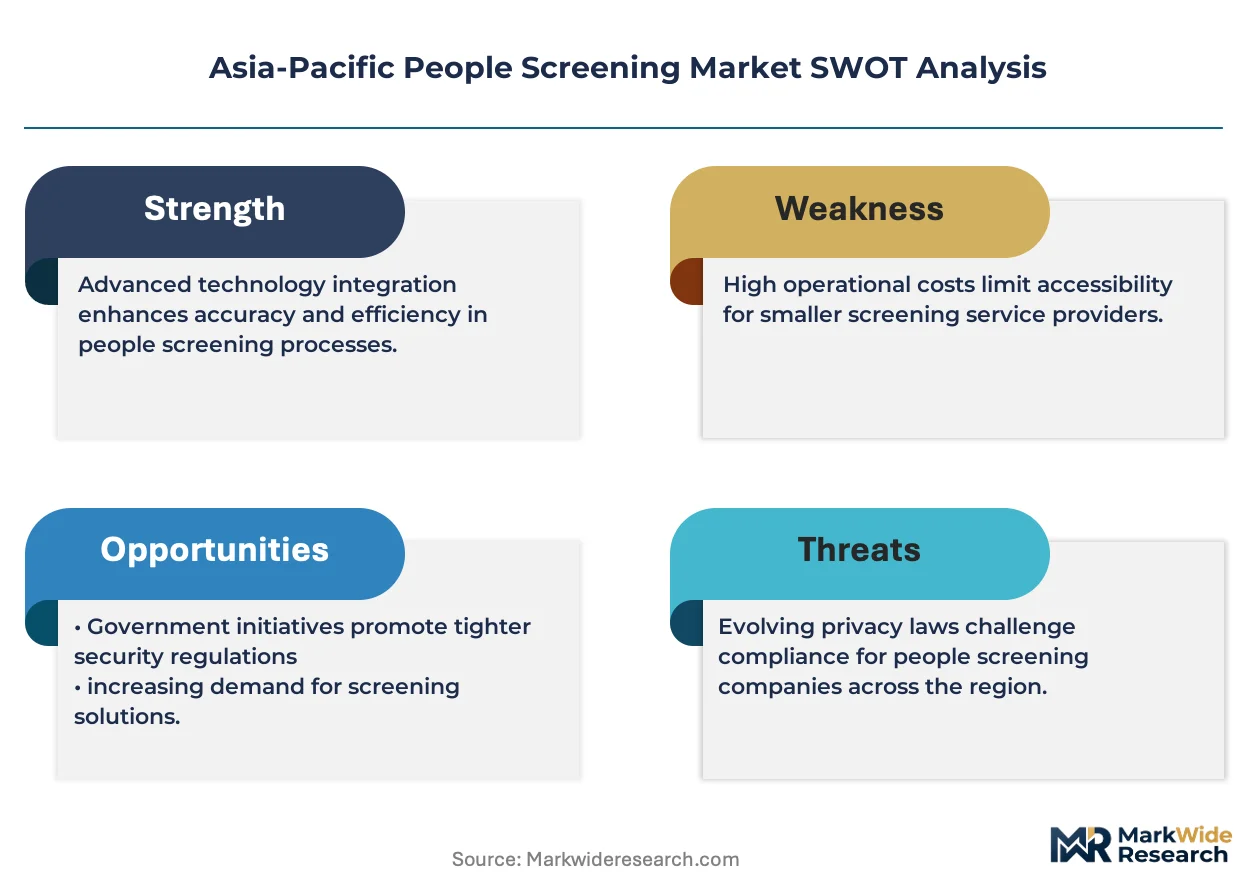
Transport security agencies is redrawing procurement priorities across the Asia-Pacific People Screening Market, shifting volume toward integrated biometric-border solutions. Nuctech Company Limited leverages its domestic manufacturing scale to anchor supply relationships with Chinese aviation authorities. Smiths Detection Group Ltd. competes on detection breadth across explosive and narcotics trace applications. CEIA SpA differentiates through millimeter-wave body scanner precision for high-throughput environments.
People screening encompasses the automated and manual inspection of individuals for concealed threats, contraband, or identity verification through technologies operating at frequencies from millimeter-wave to terahertz, with throughput rates typically exceeding 400 persons per hour at aviation checkpoints. The primary commercial purpose centers on threat interdiction while minimizing passenger processing friction in high-density transit corridors. Facial recognition systems within the Technology segment dominate capital deployment as airports replace legacy document checkpoints. Border Control applications capture the largest margin pools given sovereign funding durability and multi-year procurement cycles. Managed Services across the Service Type dimension is expanding fastest as operators outsource system upkeep and algorithm retraining to specialist vendors.
TRAI spectrum allocations shape millimeter-wave device certification timelines in India, while China's SAMR enforces GB standards on biometric data handling and equipment interoperability. Australia's TGA-equivalent infrastructure security framework mandates screening technology upgrades at designated critical transport nodes. Stakeholders must monitor divergent national data-localization requirements that fragment cloud-connected screening architectures across the region.
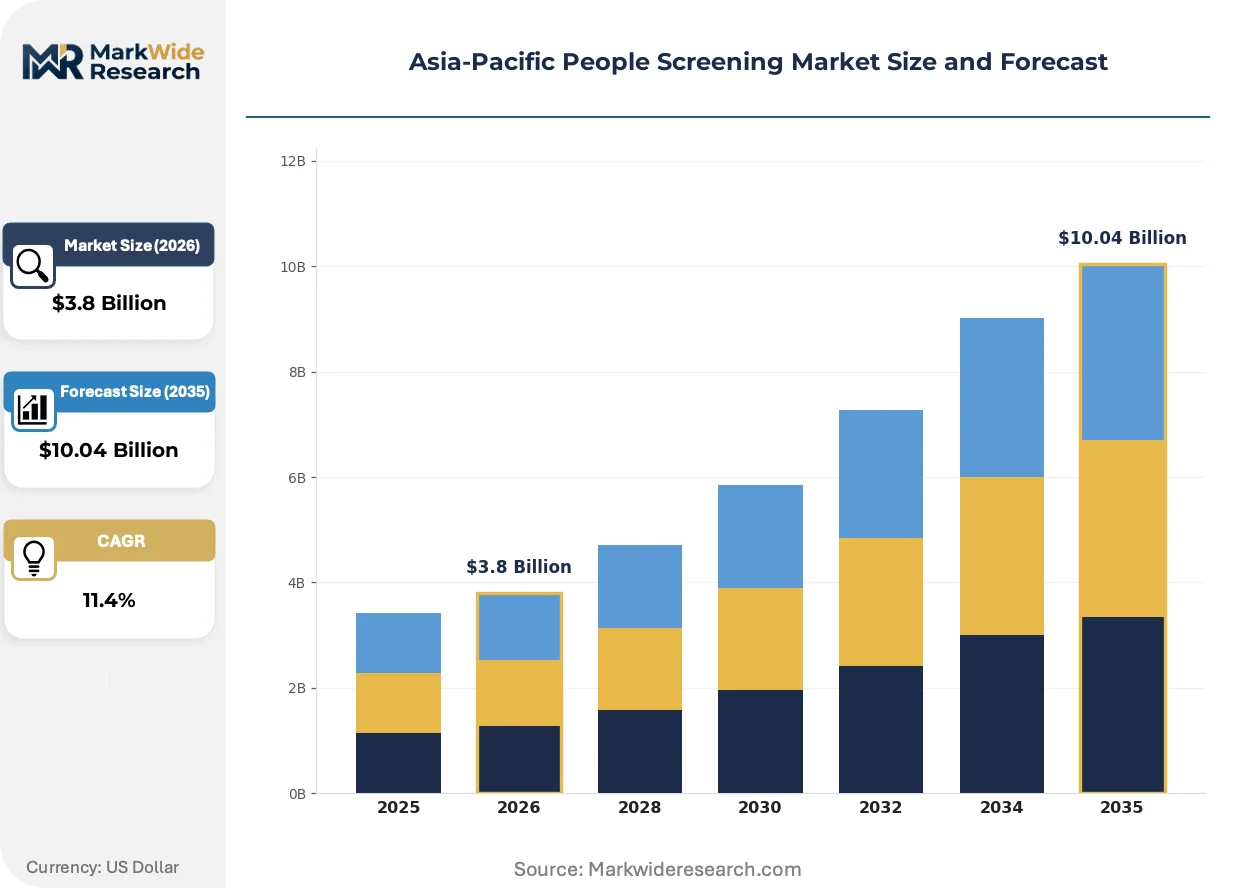
Market Dynamics
Biometric-border integration is compressing procurement cycles across Asia-Pacific aviation authorities, forcing vendors to bundle identity verification with threat detection hardware or exit tier-one airport tenders entirely.
Growth Catalysts
- India's BIS certification tightening:Security electronics manufacturers must recalibrate production lines to meet elevated electromagnetic compatibility thresholds, filtering out low-grade imports and consolidating qualified supplier pools.
- Millimeter-wave throughput gains:Aviation checkpoints in China's provincial hubs are replacing legacy metal detectors with walk-through scanners processing 600+ passengers hourly, reducing lane count requirements.
- Facial recognition capital redeployment:Southeast Asian airports are redirecting infrastructure budgets from document inspection booths toward camera-array corridors integrated with immigration databases.
Market Restraints
- Terahertz component supply concentration:High-frequency semiconductor fabrication for advanced body scanners clusters in South Korean and Taiwanese foundries, exposing equipment makers to single-source vulnerability.
- Data-localization compliance fragmentation:China's SAMR GB standards on biometric storage, India's TRAI spectrum rules, and Australia's critical infrastructure mandates create incompatible cloud-architecture requirements across adjacent markets.
- Copper and rare-earth magnet cost volatility:Electromagnetic screening coils and permanent-magnet assemblies face input price swings that compress hardware margins on fixed-price government contracts.
Strategic Opportunities
- Vietnam and Philippines airport privatization waves:Greenfield terminal developments in Hanoi, Ho Chi Minh City, and Manila bypass legacy system integration burdens, favoring turnkey biometric-integrated screening suites.
- Managed services outsourcing:Algorithm retraining, sensor calibration, and threat-library updates are migrating from in-house aviation security teams to specialist vendors under multi-year performance contracts.
- Railway corridor expansion:China's high-speed network and India's dedicated freight corridors are adopting aviation-grade passenger screening protocols, opening non-aviation volume channels for millimeter-wave equipment.
Industry Challenges
- Millimeter-wave algorithm training data scarcity:Threat detection accuracy depends on region-specific body-type and concealed-object datasets that vendors must build through extended field deployments before regulatory clearance.
- Legacy X-ray checkpoint integration friction:Biometric-border systems must interface with existing baggage screening infrastructure using incompatible data protocols, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific People Screening Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Biometric, Facial Recognition, Behavioral Analysis, Document Verification Application: Border Control, Employment Screening, Event Security, Access Control End User: Government, Corporations, Educational Institutions, Event Organizers Service Type: Consulting, Integration, Managed Services, Training |
| Companies Covered | Rapiscan Systems Inc., LINEV Systems, Smiths Detection Group Ltd., CEIA SpA, Teledyne ICM SA, Nuctech Company Limited, Thruvision Ltd., Vehant Technologies, Rohde & Schwarz, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific People Screening Market Trends and Innovations
Passive millimeter-wave imaging arrays are displacing active scanning architectures, while sovereign data-handling mandates force architectural redesigns. Procurement patterns are compressing toward bundled identity-threat detection platforms.
Passive millimeter-wave body scanners are fragmenting the high-throughput checkpoint market by eliminating mechanical rotation components and reducing maintenance intervals. China's tier-one airports and Japan's international terminals are piloting fixed-panel configurations that capture 360-degree imagery through distributed receiver arrays. The technology is fragmenting vendor competitive positions by rewarding semiconductor integration capabilities over mechanical engineering heritage.
Australia's critical infrastructure security framework is mandating screening technology refreshes at designated transport nodes, with compliance deadlines cascading through 2025-2027. The regulation forces airport operators to retire analog-metal-detector-primary configurations regardless of functional condition. Border control procurement pools absorb the largest compliance cost concentration, with sovereign funding streams insulating these segments from aviation authority budget volatility.
Aviation security directors are consolidating vendor relationships around single-source biometric-integrated platform providers, displacing multi-vendor best-of-breed procurement. The shift concentrates contract value with suppliers offering facial recognition, body scanning, and credential verification through unified data architectures. This pattern is most visible in China's provincial airport expansions, where operators prioritize commissioning speed over component-level optimization.
Asia-Pacific People Screening Market Segmentation
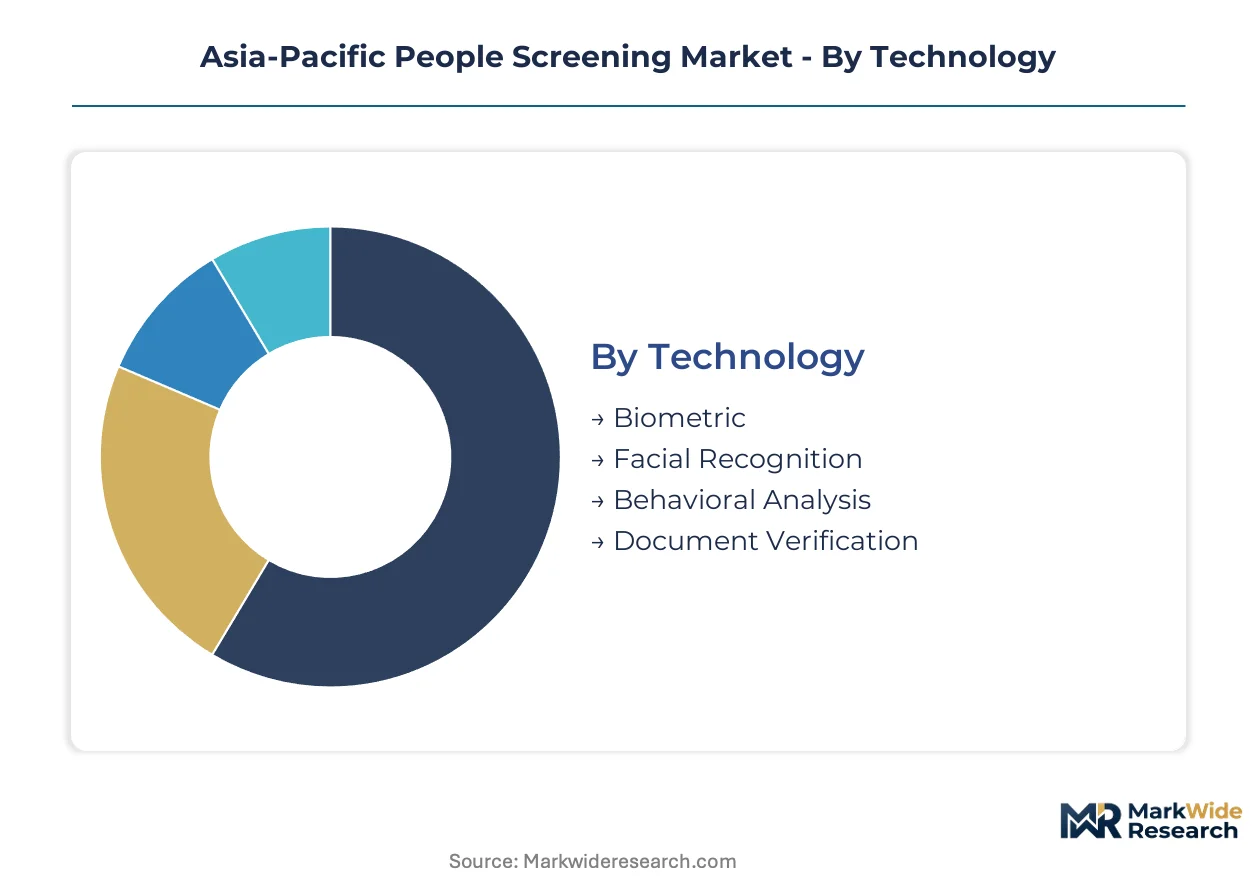
People screening procurement in Asia-Pacific fragments across four intersecting dimensions. Technology choices determine hardware refresh cycles, while application context dictates funding durability and compliance intensity.
Technology:
Facial recognition systems face mounting substitution pressure from multimodal biometric fusion, as single-factor identity verification loses tender eligibility at tier-one aviation hubs.
- Biometric:Fingerprint, iris, and vein pattern recognition systems form the foundational layer of integrated identity verification architectures. Chinese provincial airports and India's metro rail networks are deploying these modules as primary authentication gates, driven by SAMR and BIS mandates for multi-factor verification at critical infrastructure nodes.
- Facial Recognition:Camera-array corridors capture biometric templates through distributed sensor networks operating at aviation-scale throughput. Southeast Asian terminals in Bangkok, Singapore, and Jakarta redirect capital from document booths toward these installations, compressing passenger processing intervals while satisfying immigration database integration requirements.
- Behavioral Analysis:Gait and movement pattern detection augments physical screening with anomaly flagging.
- Document Verification:Automated passport and credential authentication retains relevance in hybrid checkpoint configurations.
Facial recognition retains volume leadership; behavioral analysis holds the steepest expansion curve.
Application:
Margin structures diverge sharply across deployment contexts, with sovereign-funded installations commanding premium pricing over commercial security procurement.
- Border Control:Immigration checkpoint installations absorb the largest capital allocations through multi-year government procurement cycles. Australia's critical infrastructure framework mandates technology refreshes at designated ports, while China's international terminals integrate facial recognition with national identity databases under SAMR interoperability standards.
- Employment Screening:Background verification and credential authentication systems serve corporate and government hiring workflows.
- Event Security:Temporary deployment scenarios for stadiums and convention centers favor rapid-installation biometric kiosks.
- Access Control:Facility entry management spans corporate campuses, government buildings, and educational institutions.
Border control commands the dominant revenue share; event security demonstrates the most volatile demand pattern.
End User:
Procurement sophistication varies dramatically across buyer categories, fragmenting vendor engagement strategies.
- Government:Aviation authorities, immigration departments, and critical infrastructure agencies drive standard-setting through technical specifications that cascade to downstream adopters. India's BIS certification requirements and Australia's transport security mandates establish compliance baselines that commercial buyers subsequently reference.
- Corporations:Enterprise campus security and financial services compliance departments purchase integrated access and visitor management platforms.
- Educational Institutions:University and school district deployments prioritize cost-optimized credential verification.
- Event Organizers:Temporary installation buyers prioritize rental and managed service models over capital acquisition.
Government end users anchor procurement volume standards; corporations are adopting fastest among non-sovereign buyers.
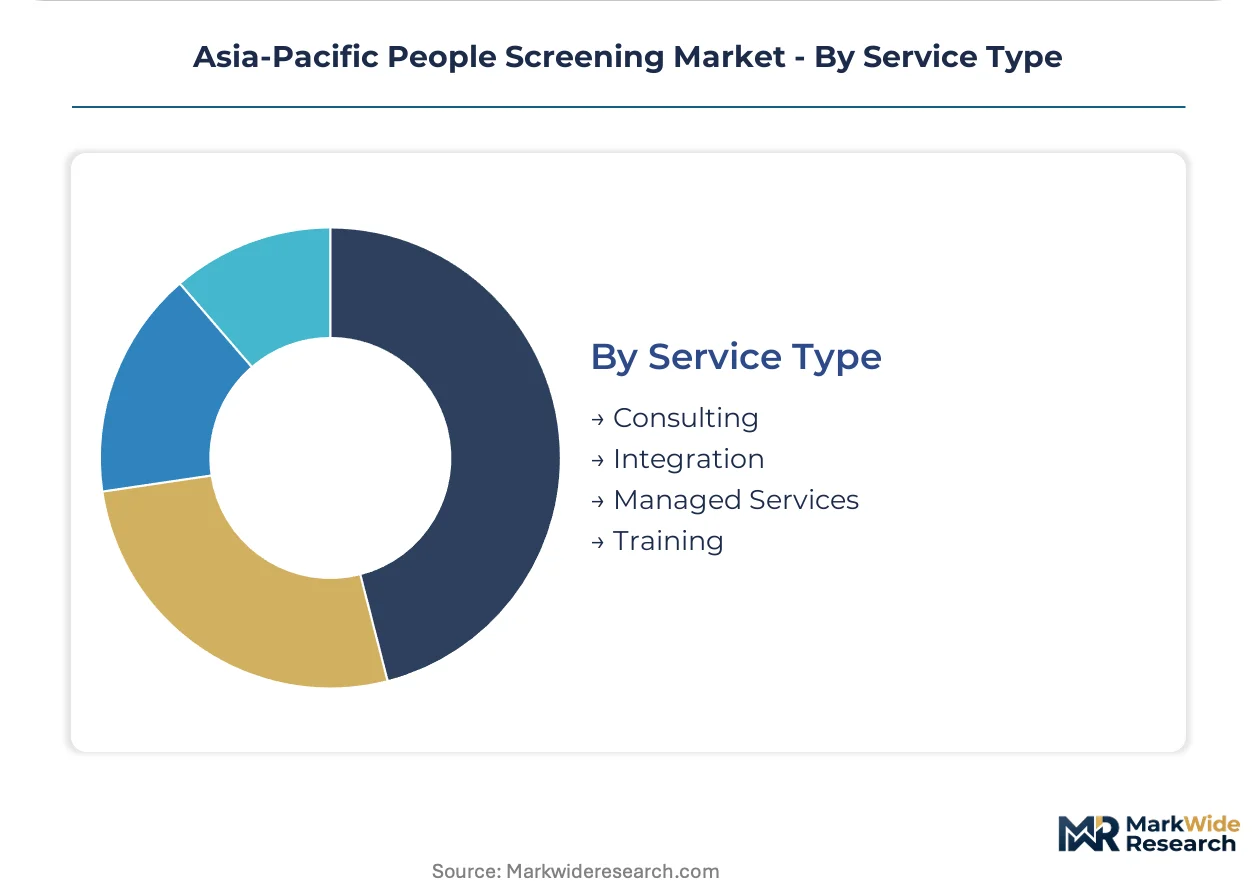
Service Type:
Revenue migration from hardware sales toward recurring service streams is restructuring vendor business models.
- Managed Services:Algorithm retraining, sensor calibration, and threat-library maintenance contracts are displacing in-house aviation security team functions. Chinese provincial airports and Southeast Asian terminals outsource system upkeep to specialist vendors under multi-year performance agreements, insulating operators from technical obsolescence risk.
- Integration:System commissioning and legacy infrastructure interfacing commands premium professional fees.
- Consulting:Compliance pathway guidance and procurement specification development serves pre-tender preparation.
- Training:Operator certification and security staff upskilling completes deployment cycles.
Managed services is climbing the fastest; integration commands the highest per-project margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's high-speed rail network and its tier-one aviation hubs constitute the primary infrastructure backbone underwriting regional demand concentration for people screening systems across the Asia-Pacific corridor.
China
Provincial airport expansions in Chengdu and Xi'an are deploying integrated biometric-identity platforms at immigration checkpoints. SAMR enforces GB standards on biometric data interoperability and equipment certification. The Yangtze River Delta cluster surrounding Shanghai anchors manufacturing scale for millimeter-wave scanner components.
India
Metro rail networks in Delhi, Mumbai, and Bangalore are adopting aviation-grade passenger screening protocols at interchange stations. BIS certification requirements for security electronics have tightened electromagnetic compatibility thresholds, filtering import volumes. The Delhi-Mumbai Industrial Corridor freight terminals are mandating credential verification systems for logistics workforce access.
Australia
Critical infrastructure security frameworks are forcing technology refreshes at designated ports and international terminals regardless of existing equipment condition. The national transport security regulator mandates compliance deadlines cascading through 2025-2027. Sydney and Melbourne international terminals concentrate procurement volume for integrated identity-threat detection platforms.
Japan
International terminal expansions at Narita and Kansai airports are piloting passive millimeter-wave imaging arrays with distributed receiver configurations. METI technical standards shape equipment certification timelines for biometric-border integration. The Tokyo-Osaka aviation corridor commands premium pricing for high-throughput checkpoint solutions.
Vietnam
Greenfield terminal developments at Long Thanh International Airport bypass legacy system integration burdens entirely. Airport privatization waves in Hanoi and Ho Chi Minh City favor turnkey biometric-integrated screening suites over component procurement. The southern economic region surrounding Ho Chi Minh City is capturing managed services outsourcing contracts for system maintenance.
Asia-Pacific People Screening Market Competitive Landscape
Concentration sits with diversified security technology conglomerates that bundle identity verification with threat detection hardware. The vendor base spans three tiers: domestic Chinese manufacturers leveraging sovereign procurement preferences, European specialists competing on detection breadth, and emerging Indian players capturing regional service contracts. Strategic moves center on biometric-border integration partnerships and multi-year managed services agreements that displace in-house aviation security functions.
Among the named participants, Nuctech Company Limited and Smiths Detection Group Ltd. exemplify the scale-driven archetype, while CEIA SpA occupies a position within the precision-specialist tier. Vehant Technologies represents the regional service-anchored model. These entities collectively illustrate the competitive segmentation between manufacturing-scale players and solution-integrators across the Asia-Pacific procurement landscape.
| Leading Market Players |
|---|
| Rapiscan Systems Inc. |
| LINEV Systems |
| Smiths Detection Group Ltd. |
| CEIA SpA |
| Teledyne ICM SA |
| Nuctech Company Limited |
| Thruvision Ltd. |
| Vehant Technologies |
| Rohde & Schwarz |
| Others |
Pricing and Supply Chain Analysis
India's BIS certification regime gates both supplier qualification and price differentiation simultaneously, elevating electromagnetic compatibility thresholds that filter low-grade imports while compressing hardware margins on compliant equipment. This regulatory filter concentrates pricing power with domestic manufacturers and qualified tier-one vendors who absorb recertification costs into premium positioning.
Pricing Analysis
Volume-discount tiering structures dominate procurement across Asia-Pacific aviation authorities, with three-tier pricing separating aviation-grade biometric-integrated platforms from provincial airport configurations and railway corridor deployments. Price differentiation hinges on certification grade — SAMR GB compliance and BIS electromagnetic thresholds — alongside after-sales service bundling for algorithm retraining and sensor calibration. Pricing pressure stems from copper and rare-earth magnet cost volatility compressing margins on fixed-price government contracts. Government end users exhibit lowest price sensitivity given sovereign funding durability, while event organizers and educational institutions drive procurement toward rental and managed service models.
Supply Chain Analysis
Inbound logistics costs through Shanghai-Ningbo and Shenzhen port clusters shape landed cost structures for millimeter-wave scanner components arriving from South Korean and Taiwanese foundries. High-frequency semiconductor fabrication concentrates in South Korea and Taiwan, exposing equipment makers to single-source vulnerability for terahertz receiver arrays. Raw material dependencies span copper for electromagnetic screening coils, rare-earth magnets for permanent-magnet assemblies, and gallium nitride substrates for millimeter-wave transmitters. Distribution runs through direct procurement relationships with aviation authorities and critical infrastructure agencies, bypassing traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as biometric-border integration compresses procurement cycles and forces bundled platform adoption before saturation in tier-one aviation hubs.
For Market Incumbents: Secure multi-year managed services contracts with Chinese provincial airports and Southeast Asian terminals to lock out algorithm-retraining competitors. Deepen backward integration into millimeter-wave semiconductor sourcing through South Korean foundry partnerships, mitigating terahertz component supply concentration risk from single-source vulnerability. For New Entrants and Emerging Players: Anchor in Vietnam's greenfield terminal developments at Long Thanh International Airport and Philippines airport privatization waves, where legacy system integration burdens are absent. Target railway corridor expansion in China's high-speed network and India's dedicated freight corridors as the most penetrable non-aviation volume channel, deploying rapid-installation biometric kiosks under turnkey performance contracts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed security technology conglomerates that have consolidated identity verification with threat detection hardware but lack managed services scale. Five-to-ten-year viability hinges on algorithm training data moats and sovereign procurement relationships. Watch for BIS certification expansion into railway and metro applications as the inflection signal for addressable market expansion beyond aviation.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric-Border Integration Partnership | Consolidates facial recognition, body scanning, and credential verification under unified SAMR-compliant data architectures at Chinese provincial airports. |
| Managed Services Outsourcing Agreement | Migrates algorithm retraining and sensor calibration from in-house aviation security teams to specialist vendors under multi-year performance contracts. |
| Millimeter-Wave Throughput Upgrade | Replaces legacy metal detectors with passive imaging arrays processing 600+ passengers hourly at China's provincial aviation hubs. |
| Railway Corridor Screening Deployment | Extends aviation-grade passenger screening protocols to China's high-speed network and India's dedicated freight corridors. |
| Regulatory Certification Investment | Recalibrates production lines to meet India's BIS electromagnetic compatibility thresholds and Australia's critical infrastructure mandates. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with aviation security directors, biometric system procurement officers, critical infrastructure compliance leads, and managed services vendors; combined with secondary validation through SAMR GB standard filings, BIS certification registries, airport authority tender documents, and customs trade data for screening equipment imports. Bottom-up and top-down triangulation cross-validated segment-level estimates against aggregate market sizing.
Across the analysis window, the forecasting framework modeled technology substitution curves, application-specific procurement cycles, end-user funding durability, and service-type revenue migration patterns. CAGRs derived from segment-level volume trajectories and value-per-unit trends, incorporating millimeter-wave scanner deployment rates, facial recognition camera-array installation pipelines, and managed services contract renewal velocities as industry-specific inputs.
Material uncertainties — regulatory timeline shifts, sovereign data-localization mandate divergence, and terahertz semiconductor supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions about certification pathway stability and infrastructure budget continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Safety
Bulletproof Vest Market
Personal Safety
Global Fall Protection Market
Personal Safety
Fall Detection System Market
Personal Safety
Concealable Vest Market
Personal Safety
Personal Safety Alarms Market
Personal Safety
Global Personal Emergency Response Systems (PERS) Market
Personal Safety
Pedestrian Protection Airbag Market
Personal Safety
China Travel Safety Kits Market
Personal Safety
Night Vision Goggles Market
Personal Safety
Life Jacket Market
Personal Safety
Child Safety Seat Market
Personal Safety
Rearward Facing Type Child Safety Seats Market
Personal Safety
Child Leash Market
Personal Safety
Smart Home Safety Market
Personal Safety
Road Safety Market
Personal Safety
Global Medical Alert System/Personal Emergency Response System Market