
 Personal Safety Apps for Women Market | 2026-2036
Personal Safety Apps for Women Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Safety Apps for Women Market Insights
The capital-intensity divergence between cloud-native startups and legacy telephony infrastructure is redrawing competitive boundaries in women's personal safety technology. Noonlight leverages direct emergency-service dispatch partnerships to sustain premium positioning. Life360 anchors its ecosystem through family-network effects and wearable integrations. bSafe differentiates via white-label deployments for corporate campus security.
Personal safety apps for women constitute mobile software platforms that combine real-time geolocation transmission, automated threat detection algorithms, and direct emergency-service routing to reduce response latency during harassment or assault incidents. These systems integrate GPS triangulation, accelerometer pattern recognition, and cloud-based dispatch protocols to serve both individual consumers and institutional buyers. Emergency Alert functionality dominates monetization through recurring subscription revenue, while Location Tracking features command higher per-user value in enterprise deployments. The Freemium model captures mass-market onboarding, yet Subscription-Based tiers concentrate margin pools among working professionals and university students.
The Federal Communications Commission mandates location-accuracy standards for wireless emergency calls, shaping technical baselines that FDA-cleared wearable integrations must satisfy. India's TRAI enforces data-localization rules that constrain cross-border server architectures, while the EU AI Act imposes algorithmic transparency requirements on automated threat-assessment features. Stakeholders must monitor how divergent data-sovereignty regimes between the United States, European Union, and India fragment development roadmaps and compliance costs.
Market Dynamics
The convergence of wearable biosensors with emergency dispatch APIs is compressing response latency thresholds and forcing platform providers to rebuild their technical stacks around real-time physiological signal processing rather than location-only alerting.
Growth Catalysts
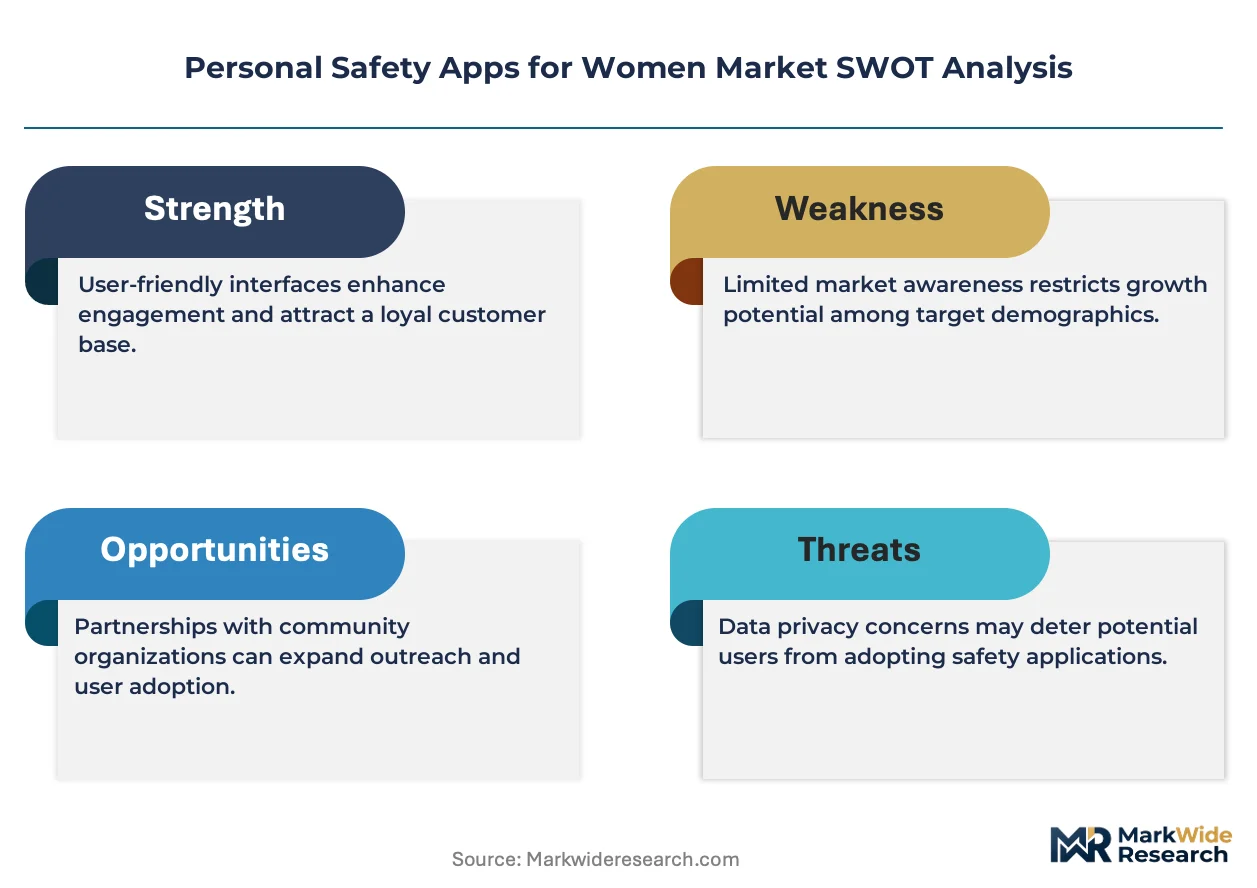
- India's PLI scheme for electronics manufacturing:Domestic subsidy pools are accelerating local app development and wearable integration partnerships, reducing import dependency for sensor hardware.
- University campus procurement mandates:North American higher-education institutions are expanding emergency alert system deployments, creating institutional subscription pipelines with multi-year contract structures.
- Smartphone penetration in urban India:Device density among working professionals is enabling freemium-to-subscription conversion at scale in safety-conscious metropolitan clusters.
Market Restraints
- Data-localization compliance costs:India's TRAI server-architecture rules fragment cloud infrastructure strategies and multiply operational overhead for cross-border platform operators.
- Cellular network dead zones:GPS triangulation reliability degrades in dense urban canyons and rural corridors, limiting functional coverage for location-dependent features.
- Algorithmic transparency requirements:The EU AI Act imposes documentation burdens on automated threat-assessment modules, extending development cycles for predictive safety features.
Strategic Opportunities
- Corporate campus white-label deployments:Enterprise security departments seek customizable safety platforms with HR system integration, opening B2B revenue streams beyond consumer subscriptions.
- FDA-cleared wearable integration:Medical-grade device certification creates premium positioning for platforms that route physiological distress signals directly to emergency services.
- Family-network effect monetization:Multi-user subscription tiers that bind parents, children, and elderly relatives into connected safety ecosystems reduce churn through social lock-in.
Industry Challenges
- Accelerometer pattern-recognition calibration:Distinguishing genuine distress gestures from accidental motion triggers requires extensive training-data collection across diverse demographic movement patterns.
- FCC location-accuracy certification timelines:Wireless emergency-call standards mandate precise geolocation validation that extends hardware-software integration testing by quarters.
- Cross-platform API fragmentation:iOS and Android background-location permission architectures diverge, forcing redundant development tracks for core safety functionality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Safety Apps for Women Market |
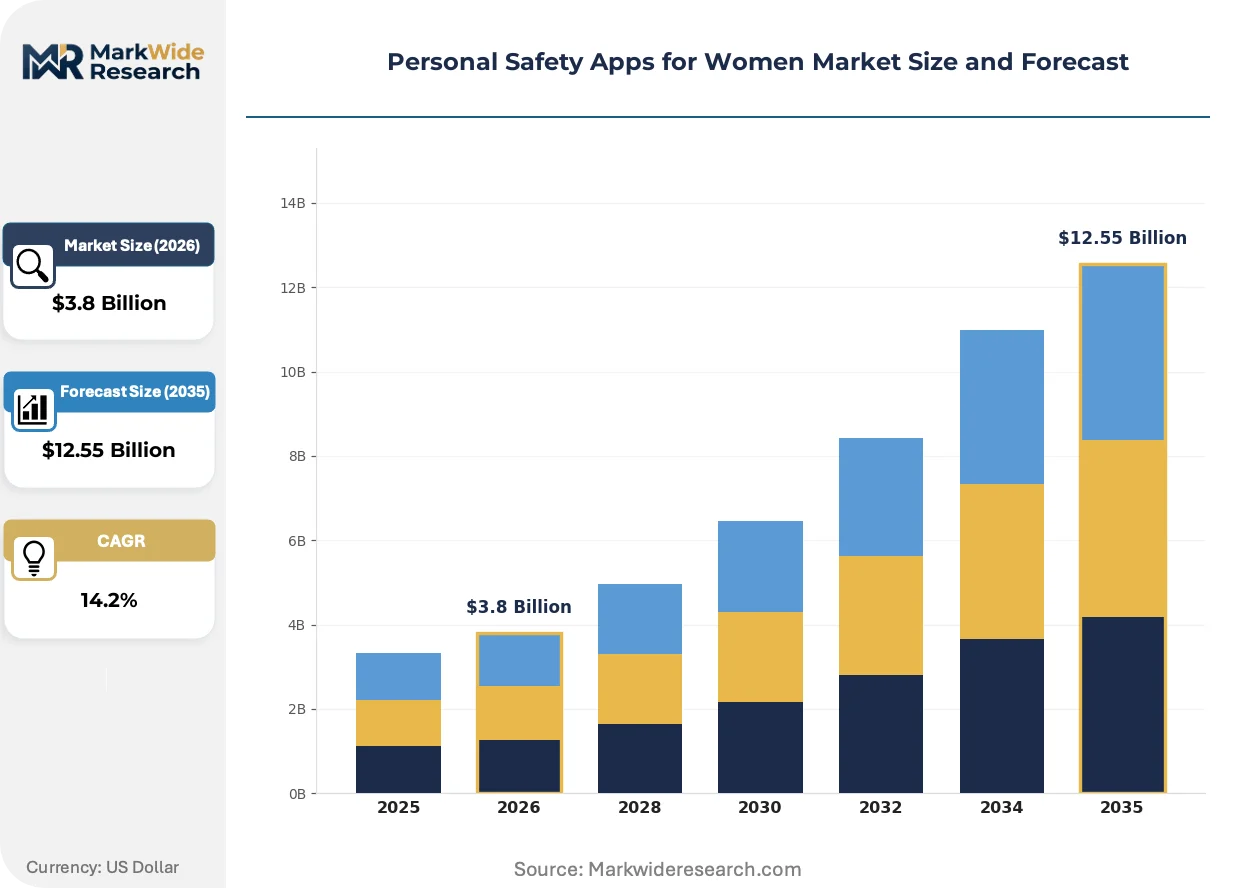
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | App Type: Emergency Alert, Location Tracking, Community Support, Safety Check-in Feature: GPS Integration, Voice Activation, Panic Button, Trip Monitoring Target User: Students, Working Professionals, Travelers, Stay-at-home Moms Monetization Model: Freemium, Subscription-Based, One-Time Purchase, Sponsored Content |
| Companies Covered | Circle of 6, UrSafe, Life360, Red Panic Button, Watch Over Me, Noonlight, Safetipin, Rave Guardian, bSafe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Safety Apps for Women Market Trends and Innovations
Wearable-native safety architectures are displacing smartphone-centric models as the default design assumption, compressing form-factor constraints and rewriting power-management requirements for continuous monitoring.
Biometric stress-detection sensors embedded in jewelry and clothing accessories are miniaturizing to sub-millimeter thickness while maintaining signal fidelity. University wellness programs and corporate HR departments are piloting these devices for duty-of-care compliance. This miniaturization is enabling 24/7 wearable adherence that smartphone-dependent apps cannot match, shifting competitive advantage toward hardware-software integrated platforms.
The EU AI Act's algorithmic transparency mandates are forcing disclosure of threat-assessment model training data and decision logic. Platform developers must now maintain auditable documentation trails for automated emergency classifications. Consumer-facing apps with predictive features face the steepest compliance burdens, while basic alert-only services evade classification as high-risk AI systems.
Subscription fatigue among working professionals is compressing free-to-paid conversion funnels, with users demanding tangible response-time guarantees before committing to recurring payments. Employer-sponsored safety benefits are displacing individual subscriptions as the dominant channel in North America and Western Europe. This channel shift is most visible in technology and professional-services sectors where duty-of-care litigation risk drives procurement urgency.
Personal Safety Apps for Women Market Segmentation
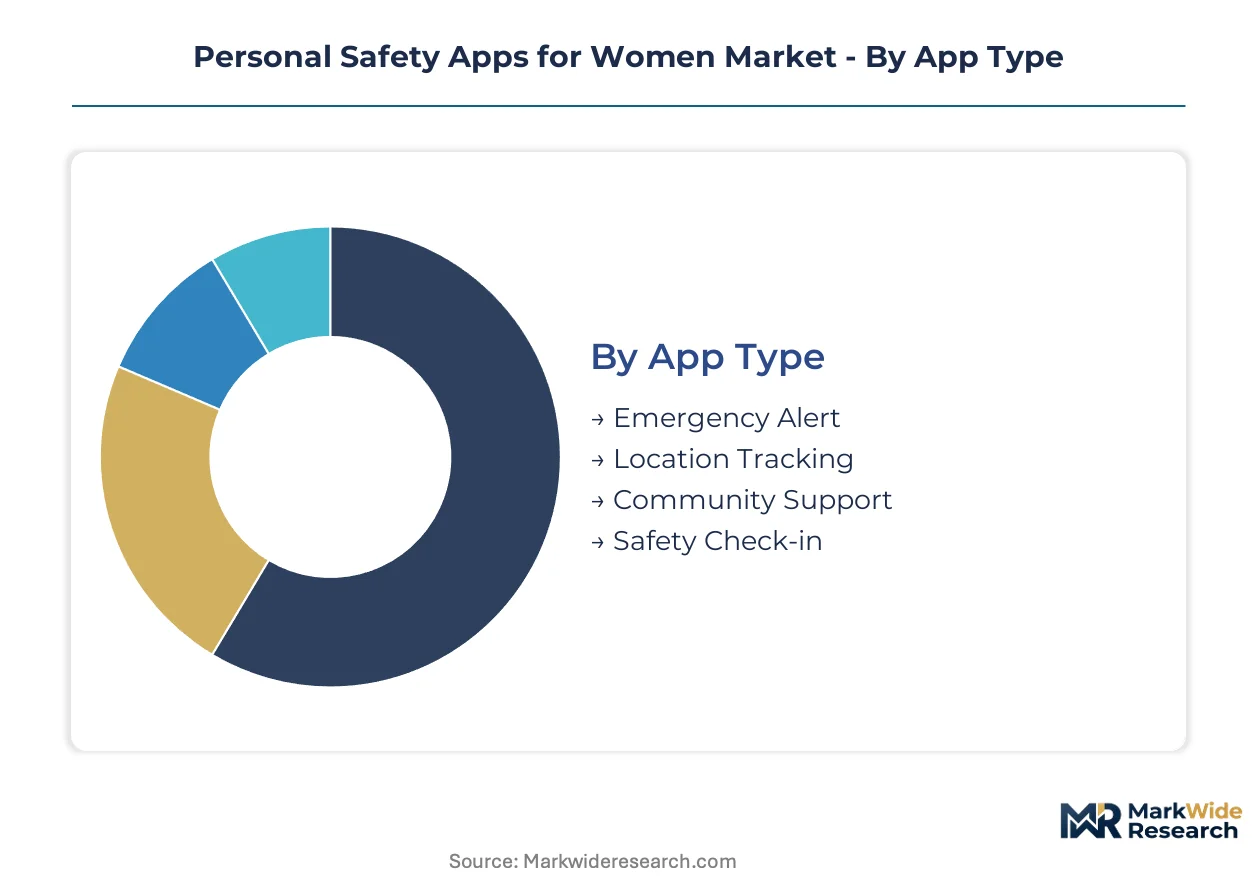
Personal safety apps fragment across four distinct dimensions, each carrying unique substitution risks from adjacent technologies. Emergency dispatch APIs compete with standalone location trackers. Wearable biosensors threaten smartphone-native feature sets. Understanding these pressure points clarifies where platform providers must defend technical differentiation.
App Type:
Emergency Alert platforms face acute substitution pressure from native smartphone SOS functions, while Community Support apps compete with encrypted messaging networks.
- Emergency Alert:Core functionality routes automated distress signals to pre-configured contacts and emergency services through cloud-based dispatch protocols. University campuses in the United States and corporate security departments in India concentrate procurement, driven by duty-of-care litigation exposure and TRAI-mandated localization requirements.
- Location Tracking:Continuous geolocation transmission enables real-time position monitoring with geofence breach notifications. Working professionals in urban India and parents monitoring adolescent children in Germany sustain demand, pressured by GDPR consent-management complexity and battery-drain tradeoffs.
- Community Support:Crowdsourced safety networks aggregate user-reported incidents and verified safe-zone mapping. Neighborhood watch digitization in Brazil and campus safety coalitions in Canada anchor adoption, though encrypted group messaging platforms erode differentiation.
- Safety Check-in:Scheduled welfare confirmations trigger automated alerts upon missed check-ins. Solo travelers in Southeast Asia and shift workers in Mexico City deploy these features, competing against calendar-integrated reminder systems.
Emergency Alert retains volume leadership; Location Tracking holds the steepest expansion curve.
Feature:
Cost tier stratification separates premium biometric-integrated modules from basic manual triggers, with voice-activated systems commanding subscription premiums.
- GPS Integration:Triangulation protocols combine satellite positioning with Wi-Fi and cellular tower data for redundancy. FCC location-accuracy mandates in the United States and dead-zone vulnerability in rural India shape deployment patterns, with hardware-software integration costs fragmenting vendor tiers.
- Voice Activation:Natural-language processing enables hands-free emergency triggering under duress. Jogging commuters in London and drivers in Los Angeles concentrate demand, though accent-diversity training gaps limit accuracy across demographic cohorts.
- Panic Button:Hardware or software triggers initiate immediate alert cascades with minimal user friction. Budget-conscious student populations in Indonesia and elderly users in Japan prefer this simplicity, facing commoditization from smartphone-native alternatives.
- Trip Monitoring:Route logging with deviation alerts supports journey-specific safety coverage. Ride-hailing passengers in South Africa and nighttime delivery workers in South Korea drive adoption, constrained by background-location permission restrictions on iOS.
Panic Button captures the widest user base; Voice Activation is climbing the fastest on subscription conversion rates.
Target User:
Application-specific needs diverge sharply across life-stage and mobility patterns, with institutional procurement displacing individual subscriptions among student cohorts.
- Students:Campus-bound safety requirements integrate with university emergency alert systems and residence-hall protocols. North American higher-education procurement mandates and India's urban campus expansion sustain institutional subscription pipelines.
- Working Professionals:Commute-centric protection demands shift-specific coverage with employer-sponsored benefit integration. Technology-sector HR departments in California and financial-services firms in Maharashtra are expanding duty-of-care coverage.
- Travelers:Temporary location coverage requires cross-border functionality with local emergency-service routing. Solo female tourists in Turkey and business travelers in the UAE prioritize offline-capable architectures.
- Stay-at-home Moms:Domestic safety monitoring emphasizes neighborhood incident awareness and family-network coordination. Suburban communities in Australia and gated developments in Saudi Arabia concentrate demand.
Students command institutional volume; Working Professionals deliver the highest per-user lifetime value.
Monetization Model:
Margin concentration follows subscription retention curves, with freemium conversion efficiency determining platform viability in price-sensitive markets.
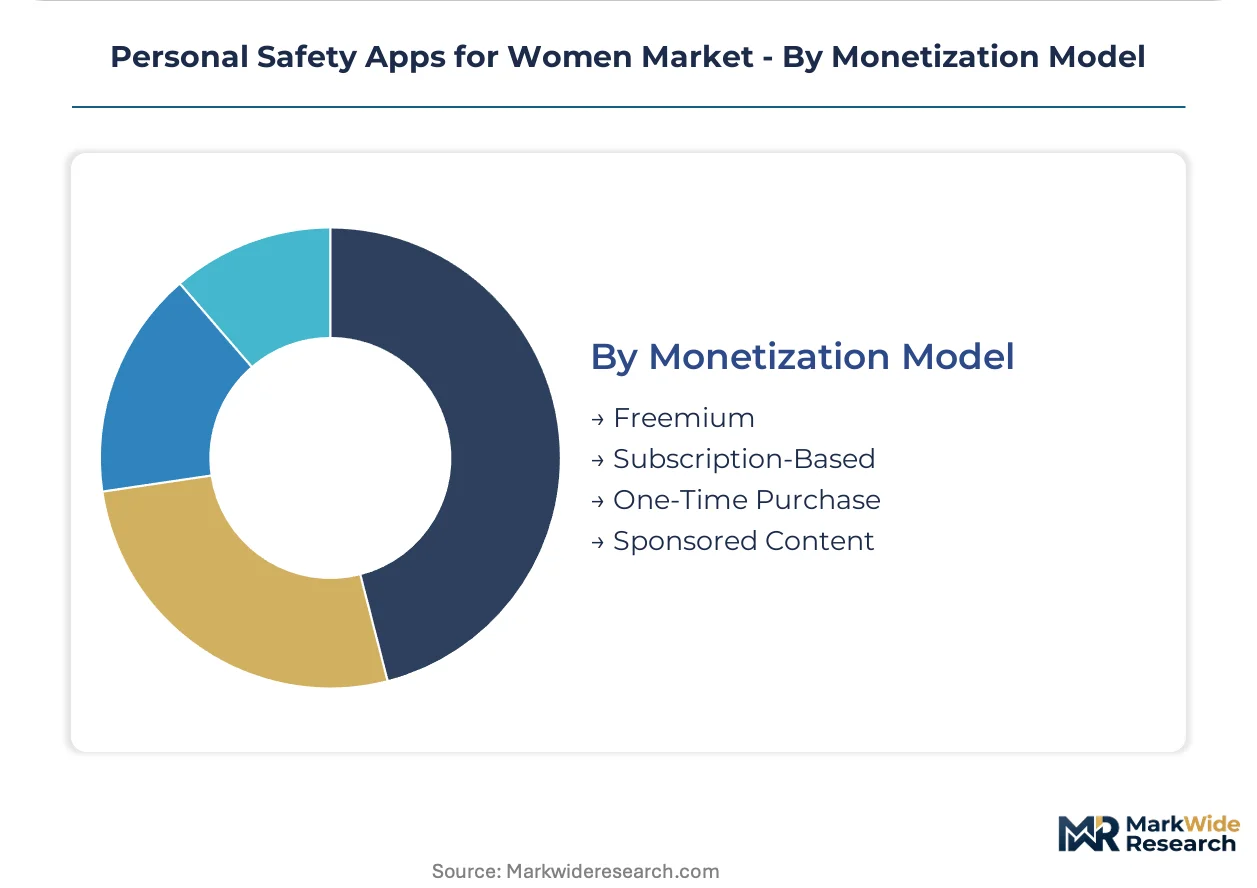
- Freemium:Basic alerting functionality with feature-gated upgrade paths captures mass-market onboarding. Smartphone penetration in urban India and Southeast Asian metropolitan clusters enables scale, though conversion rates compress under subscription fatigue.
- Subscription-Based:Recurring revenue tiers unlock advanced features including wearable integration and family-network expansion. Corporate benefits administrators in the United States and Western Europe are displacing individual payment decisions.
- One-Time Purchase:Perpetual licenses for hardware-software bundles appeal to privacy-conscious users avoiding data-sharing commitments. German and Swiss markets show residual preference for this model.
- Sponsored Content:Advertiser-funded access trades user attention for zero-direct-cost coverage, prevalent in emerging-market onboarding funnels with limited payment infrastructure.
Freemium dominates user acquisition volume; Subscription-Based captures margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity diverges sharply across geographies. Indian working professionals exhibit acute price sensitivity, compressing freemium conversion thresholds. US university procurement departments absorb premium pricing through institutional budgets with minimal elasticity.
United States
University campuses and corporate HR departments drive institutional subscription volume. FCC wireless emergency-call regulations mandate precise location-accuracy standards that shape technical baselines for platform providers. California technology firms and Massachusetts higher-education clusters concentrate employer-sponsored safety benefit procurement.
India
Urban working professionals and campus-bound students generate mass-market freemium adoption. TRAI data-localization rules fragment cloud infrastructure strategies and multiply compliance overhead for cross-border operators. Maharashtra and Karnataka metropolitan clusters anchor domestic app development accelerated by PLI electronics manufacturing subsidies.
Germany
Privacy-conscious consumers and corporate duty-of-care administrators sustain demand for hardware-software bundles with minimal data-sharing commitments. GDPR consent-management complexity elevates development costs for location-tracking features. Berlin and Munich technology corridors concentrate B2B safety platform procurement.
United Kingdom
Jogging commuters and nighttime service workers drive voice-activated emergency triggering adoption. EU AI Act algorithmic transparency requirements extend documentation burdens for predictive threat-assessment modules. London fintech and professional services sectors expand employer-sponsored safety benefit coverage.
Brazil
Neighborhood watch digitization and urban safety coalitions anchor community support app adoption. General functional descriptors for national communications regulation shape data-sovereignty constraints without specific named frameworks. São Paulo and Rio de Janeiro metropolitan areas concentrate crowdsourced incident reporting platform usage.
Personal Safety Apps for Women Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the market structure. Cloud-native platforms with direct emergency-service dispatch partnerships occupy premium positioning, while smartphone-native utilities compete on zero-marginal-cost distribution. The competitive landscape fragments across three strategic archetypes: integrated wearable-biosensor platforms, family-network ecosystem providers, and white-label enterprise security deployers. Dominant competitive moves include strategic partnerships with university procurement systems and portfolio diversification into employer-sponsored benefit channels.
Within the integrated dispatch tier, Noonlight and Life360 exemplify divergent ecosystem strategies. Noonlight anchors premium positioning through direct emergency-service routing infrastructure. Life360 occupies the family-network effect segment with multi-user subscription architectures that reduce churn through social lock-in. bSafe represents the white-label deployment archetype, serving corporate campus security departments with customizable platform configurations. These three companies collectively illustrate how capital-intensity divergence between cloud-native stacks and legacy telephony infrastructure redraws competitive boundaries.
| Leading Market Players |
|---|
| Circle of 6 |
| UrSafe |
| Life360 |
| Red Panic Button |
| Watch Over Me |
| Noonlight |
| Safetipin |
| Rave Guardian |
| bSafe |
| Others |
Pricing and Supply Chain Analysis
Multi-year university procurement contracts lock in subscription revenue visibility while insulating platform providers from spot-market churn volatility. These institutional offtake structures concentrate pricing power among vendors with FCC-compliant location-accuracy certification and direct emergency-service dispatch integration.
Pricing Analysis
After-sales revenue from wearable device servicing and extended family-network subscriptions drives lifetime value concentration. The dominant pricing structure operates on tiered SaaS tiers that stratify across premium biometric-integrated, standard GPS-alert, and economy manual-trigger levels. Price differentiation rests on FDA-cleared wearable certification and employer-sponsored benefit integration depth. Cost compression in the freemium tier is intensifying because smartphone-native SOS functions commoditize basic panic-button functionality. Indian working professionals exhibit acute price sensitivity, while US university procurement departments absorb premium pricing with minimal elasticity.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes elevates inbound logistics costs for wearable biosensor hardware sourced from contract manufacturers. Component supply concentrates in China, South Korea, and Taiwan for MEMS accelerometers, GPS modules, and Bluetooth low-energy chipsets. Raw material dependencies span lithium-polymer batteries, rare-earth magnets for haptic feedback, and medical-grade silicone for skin-contact sensors. Single-source vulnerability in MEMS foundry capacity threatens hardware-software integration timelines. Distribution runs through direct-to-consumer app stores, enterprise security procurement channels, and university IT vendor programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The personal safety apps market is entering a cyclical recovery phase as employer-sponsored benefit channels displace individual subscriptions and institutional procurement budgets expand post-pandemic duty-of-care litigation awareness.
For Market Incumbents: Secure direct emergency-service dispatch partnerships in additional metropolitan markets to defend against cloud-native entrants with superior API integration speed. Prioritize backward integration into wearable biosensor hardware to capture margin pools currently flowing to medical-device OEMs. FCC location-accuracy certification timelines represent a critical moat extension lever. For New Entrants and Emerging Players: FDA-cleared wearable fast-track pathways offer the most penetrable entry point for differentiated positioning against smartphone-native utilities. Target corporate campus white-label deployments in technology and professional-services sectors where HR benefits administrators control procurement decisions. A channel partnership with university procurement systems accelerates revenue ramp without consumer marketing spend. For Investors and Strategic Acquirers: Cloud-native platforms with existing emergency-service dispatch infrastructure represent the highest-conviction acquisition target archetype for medium-term ecosystem consolidation. Long-term viability hinges on family-network effect monetization and wearable-native architecture migration. Watch for inflection signals in employer-sponsored benefit penetration rates across North American technology corridors.| Strategic Initiative | Industry Significance |
|---|---|
| FDA-Cleared Wearable Integration | Medical-grade certification creates premium positioning against smartphone-native competitors in employer-sponsored channels. |
| University Procurement Partnership | Multi-year institutional contracts provide revenue visibility insulated from consumer subscription fatigue dynamics. |
| Corporate Campus White-Label Deployment | HR system integration opens B2B revenue streams with higher per-user lifetime value than individual subscriptions. |
| Family-Network Effect Monetization | Multi-user subscription tiers reduce churn through social lock-in across parents, children, and elderly relatives. |
| Direct Emergency-Service Dispatch Expansion | API partnerships with municipal 911 systems compress response latency and sustain premium pricing power. |
Research Methodology
A standing panel of app platform CTOs, university campus safety directors, corporate HR benefits administrators, and emergency-service dispatch integration specialists provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from SEC filings, Sensor Tower mobile analytics, FCC regulatory databases, and TRAI compliance disclosures. Bottom-up subscription volume estimates triangulated against top-down market sizing from hardware shipment data and institutional procurement records.
Consistency checks validated volume and value outputs against external benchmarks including hyperscaler partnership announcements, university IT budget disclosures, and wearable OEM revenue segmentation. The analytical framework modeled deployment across app type, feature tier, target user segment, and monetization model dimensions throughout the forecast period. CAGRs derived from logistic adoption curves calibrated to smartphone penetration trajectories and employer-sponsored benefit channel expansion patterns. Industry-specific inputs incorporated PLI scheme subsidy impact, GDPR consent-friction effects, and EU AI Act compliance cost burdens.
Underlying assumptions cover sustained smartphone penetration in urban India, stable FCC location-accuracy enforcement, and continued employer liability litigation trends, with deviation risk concentrated in data-localization regulatory fragmentation and wearable biosensor supply constraints. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Safety
Global Personal Emergency Response Systems (PERS) Market
Personal Safety
Concealable Vest Market
Personal Safety
Global Medical Alert System/Personal Emergency Response System Market
Personal Safety
Night Vision Goggles Market
Personal Safety
Body Armor and Personal Protection Market
Personal Safety
Child Leash Market
Personal Safety
Pepper Sprays Market
Personal Safety
Bulletproof Vest Market
Personal Safety
Child Safety Seat Market
Personal Safety
Smart Home Safety Market
Personal Safety
Fall Detection System Market
Personal Safety
Pedestrian Protection Airbag Market
Personal Safety
Personal Safety Alarms Market
Personal Safety
Global Fall Protection Market
Personal Safety
Asia-Pacific People Screening Market
Personal Safety
China Travel Safety Kits Market