
 Concealable Vest Market | 2026-2036
Concealable Vest Market Size, Share, and Industry Trends Forecast 2026-2036
Concealable Vest Market Analytics
NIJ Level IIIA certification is collapsing the boundary between concealability and stopping power that previously forced trade-offs. Point Blank Enterprises leverages captive manufacturing of aramid panels to sustain margin control across federal contracts. Safariland differentiates through modular carrier systems that anchor its position in specialized law enforcement channels. DuPont de Nemours extends its Kevlar supply dominance into finished vest partnerships, competing on material science leadership rather than assembly scale.
A concealable vest is a body-worn protective garment engineered to defeat ballistic threats while maintaining minimal external profile, typically constructed from woven aramid fibers or ultra-high molecular weight polyethylene layers compressed through heat-laminated molding processes. Its primary purpose is to provide covert protection for law enforcement, security personnel, and select civilian users without compromising mobility or operational discretion. Ballistic vests occupy the mature volume core of this market, while hybrid configurations integrating stab-resistant layers represent the fastest-expanding margin pool as agencies seek multi-threat coverage in single-platform procurement. UHMWPE material adoption is accelerating among premium-tier suppliers, though Kevlar retains cost advantages in high-volume government contract segments where budget constraints override weight-minimization priorities.
NIJ compliance standards administered by the US Department of Justice shape product eligibility for federal law enforcement procurement, while OSHA workplace safety directives extend vest requirements into private security contractor operations. The EU AI Act and GDPR frameworks indirectly influence smart vest development by constraining biometric sensor integration in cross-border equipment deployments. Stakeholders must monitor how proposed revisions to NIJ testing protocols for female-fit anatomical designs reshape R&D allocation and manufacturing retooling requirements across domestic suppliers.
Market Dynamics
NIJ standard revisions for female-fit anatomical testing are forcing manufacturers to retool production lines and redesign pattern libraries, compressing margins while opening certification gaps for first-movers.
Growth Catalysts
- Federal procurement mandates:US Department of Justice equipment grants to municipal police departments sustain volume demand through multi-year vest replacement cycles.
- Multi-threat protection requirements:Security contractors operating under OSHA workplace safety directives now specify hybrid ballistic-stab configurations for single-platform compliance.
- Aramid fiber processing advances:Heat-laminated molding process improvements reduce panel thickness without sacrificing NIJ Level IIIA stopping power.
Market Restraints
- Raw material concentration:Ultra-high molecular weight polyethylene supply chains cluster among Asian petrochemical processors, exposing finished goods producers to feedstock volatility.
- Certification timeline friction:NIJ compliance testing queues extend lead times for new product introductions, freezing R&D returns across domestic manufacturers.
- Weight-performance trade-off:Kevlar retains cost advantages in budget-constrained government segments, slowing UHMWPE penetration despite superior flexibility.
Strategic Opportunities
- Smart vest convergence:Biometric sensor integration with ballistic platforms creates new product categories, though EU AI Act and GDPR frameworks constrain cross-border deployment architectures.
- Private security expansion:Corporate executive protection programs in financial services and energy sectors generate premium-tier demand for custom-fitted concealability.
- Female officer underpenetration:Revised NIJ testing protocols for anatomically specific designs reward suppliers with existing female-fit pattern libraries.
Industry Challenges
- Specialized pattern-making expertise:Female-fit design requires anthropometric database development and skilled technical patterning talent scarce among traditional ballistic suppliers.
- Manufacturing retooling intensity:New NIJ mold specifications demand capital expenditure in compression equipment and quality assurance infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concealable Vest Market |
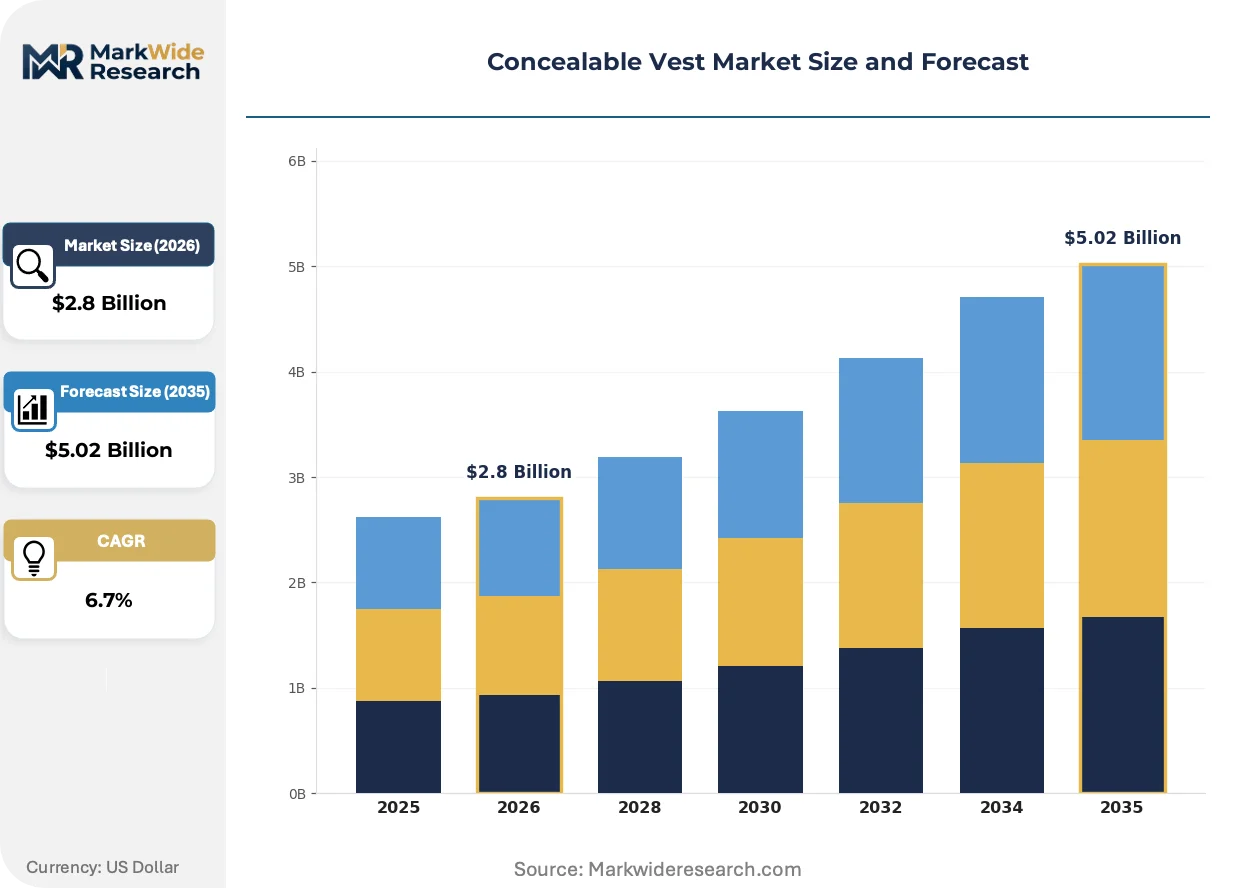
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ballistic Vests, Stab-Resistant Vests, Hybrid Vests, Concealment Garments Material: Kevlar, Twaron, UHMWPE, Aramid Fiber End User: Law Enforcement, Military Personnel, Private Security, Civilian Users Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Government Contracts |
| Companies Covered | Point Blank Enterprises, Inc., Armor Express, U.S. Armor Corporation, VestGuard UK Ltd., Safariland, LLC., MKU Limited, MARS Armor Ltd., EnGarde Body Armor, DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concealable Vest Market Evolving Landscape
Ballistic materials engineering is compressing the traditional compromise between stopping power and concealability, while procurement digitization and regulatory fragmentation reshape how protection equipment reaches end-users.
Ultra-high molecular weight polyethylene fiber is miniaturizing. Law enforcement agencies in premium-tier procurement channels adopt UHMWPE panels for plainclothes details where profile discretion governs operational effectiveness. The material is miniaturizing protective bulk to levels previously unattainable with woven aramid constructions, collapsing the weight-thickness-performance trade-off that structured market segmentation.
REACH substance restrictions in Europe are tightening chemical compliance requirements for ballistic material coatings and adhesives. Manufacturers serving cross-border contracts must reformulate lamination chemistries to maintain CE marking eligibility. Suppliers with integrated materials science capabilities absorb this friction more efficiently than assembly-focused competitors dependent on third-party component sourcing.
Agency procurement departments now unbundle vest acquisition from carrier system selection, treating ballistic panels as consumable inserts rather than integrated garments. This pattern fragments supplier relationships and elevates modular carrier specialists who anchor recurring revenue through attachment ecosystem lock-in. Municipal police departments in the United States exhibit the most pronounced unbundling behavior, driven by budget cycle accounting that separates capital equipment from operational consumables.
Concealable Vest Market Segmentation
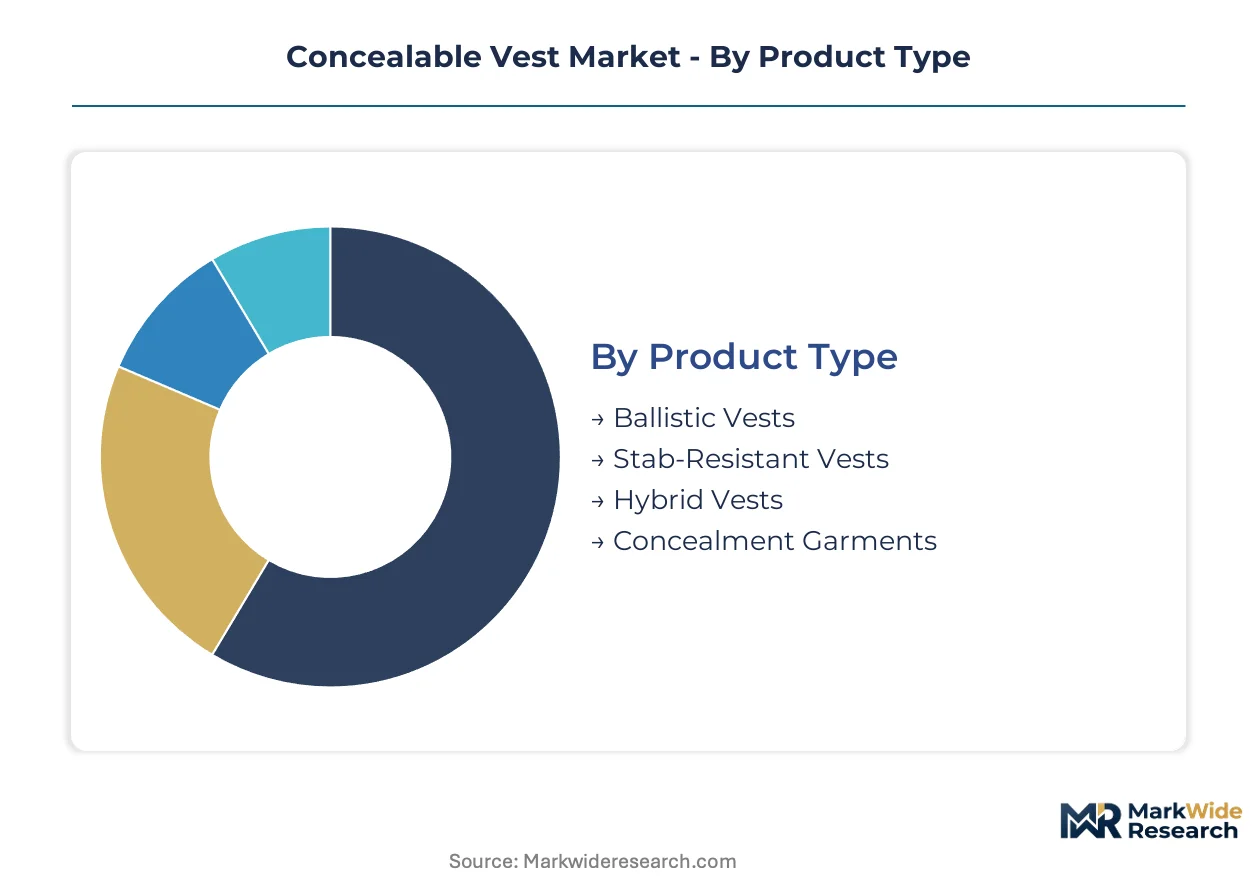
Segmentation in the concealable vest market reveals how procurement authority, material science trade-offs, and threat-profile specialization divide revenue pools. Understanding these fault lines exposes where suppliers can defend margin or capture volume.
Product Type:
Margin pools concentrate in configurations that solve multi-threat scenarios without requiring separate equipment purchases.
- Ballistic Vests:Woven aramid or UHMWPE panels engineered to defeat handgun and fragmentation threats per NIJ Level IIA through IIIA specifications. Municipal police departments in the United States sustain volume demand through federal equipment grant programs and replacement cycles.
- Hybrid Vests:Integrated platforms combining ballistic fiber layers with stab-resistant metal or composite meshes. Security contractors operating under OSHA directives drive specification intensity as single-platform compliance reduces equipment logistics overhead.
- Stab-Resistant Vests:Chain mail or laminated composite constructions prioritizing edged-weapon defeat over firearm protection. Correctional facilities and event security operations generate concentrated demand where blade exposure exceeds ballistic risk.
- Concealment Garments:Outerwear with integrated ballistic pockets designed for executive protection and plainclothes law enforcement. Financial services sector procurement in urban centers sustains premium-tier pricing for custom tailoring and profile discretion.
Ballistic vests hold installed capacity. Hybrid vests are rotating up the share rankings.
Material:
Cost structure divergence between petrochemical-derived fibers and aromatic polymer chemistry determines competitive positioning across government and premium channels.
- Kevlar:Para-aramid fiber with established NIJ certification history and domestic supply chain maturity. Federal procurement programs favor Kevlar for budget-constrained volume contracts where weight minimization remains secondary to unit cost control.
- UHMWPE:Ultra-high molecular weight polyethylene delivering equivalent stopping power at 30-40% reduced areal density. Plainclothes law enforcement details in premium-tier agencies specify UHMWPE for operational mobility and extended wear comfort.
- Twaron:Alternative para-aramid with comparable ballistic performance to Kevlar and slightly reduced moisture degradation susceptibility. European law enforcement procurement channels exhibit modest preference for Twaron in humid climate deployments.
- Aramid Fiber:Generic woven aromatic polyamide constructions serving price-sensitive institutional buyers. Private security firms with thin equipment budgets absorb aramid fiber vests as entry-level protection.
Kevlar dominates government contract flow. UHMWPE is climbing the fastest in plainclothes and executive protection specifications.
End User:
Procurement sophistication and threat calibration intensity vary dramatically across institutional and individual buyers.
- Law Enforcement:Municipal, county, and federal agencies with standardized NIJ compliance requirements and multi-year replacement schedules. Department of Justice equipment grants sustain predictable demand cycles with emphasis on female-fit anatomical designs.
- Private Security:Corporate executive protection teams and facility security contractors with hybrid threat profiles and OSHA workplace safety compliance obligations. Energy sector and financial services firms generate premium demand for custom-fitted concealability.
- Military Personnel:Specialized units requiring covert protection beneath civilian attire for intelligence and low-visibility operations. Procurement flows through defense logistics channels with distinct specification protocols from civilian law enforcement.
- Civilian Users:Individual purchasers in jurisdictions permitting personal ballistic protection, concentrated among high-risk profession holders and security-conscious urban residents. Online retail channels and specialty dealers serve fragmented demand with limited standardization.
Law enforcement holds installed capacity. Private security is rotating up the share rankings.
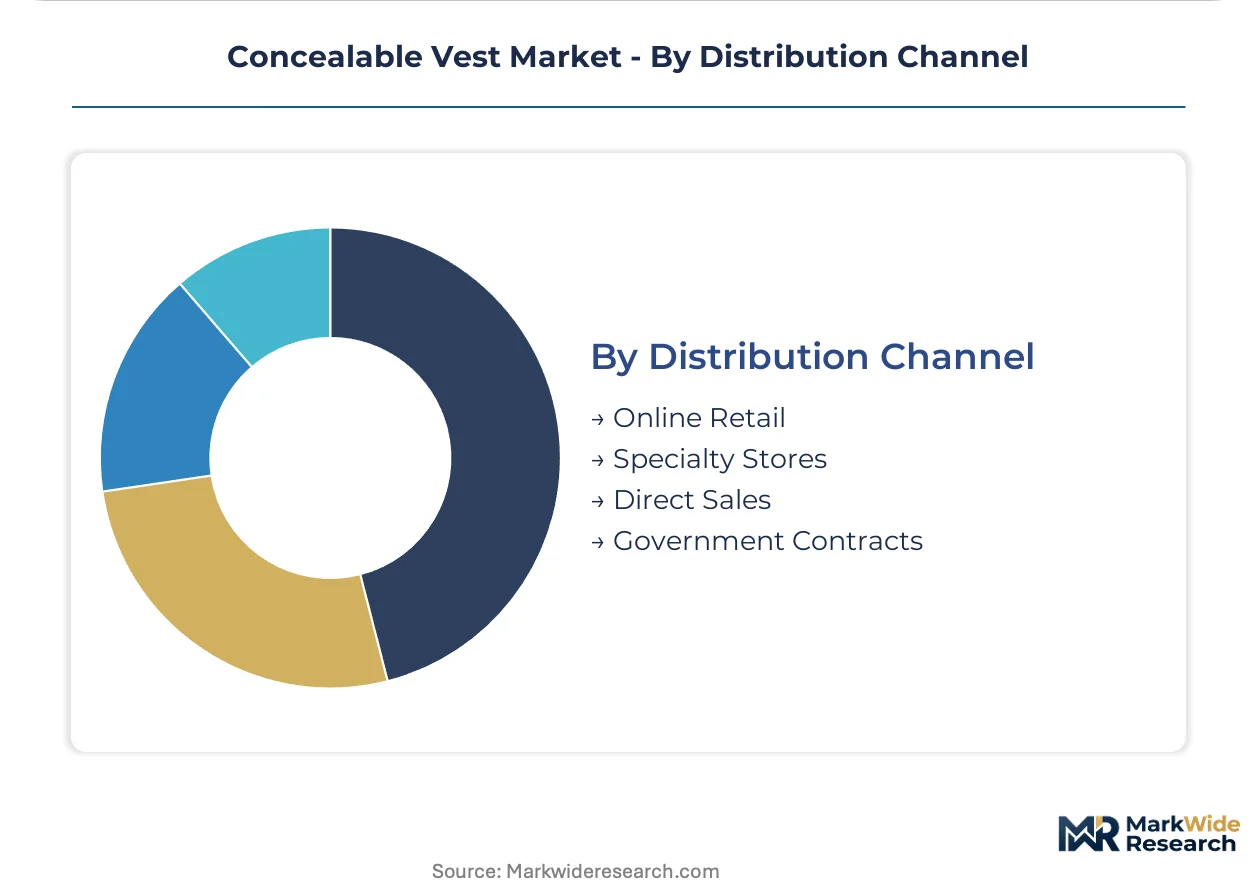
Distribution Channel:
Channel selection governs margin capture, certification documentation burden, and customer relationship durability.
- Government Contracts:Federal, state, and municipal procurement vehicles with NIJ compliance pre-qualification and multi-year award schedules. Domestic manufacturers with captive aramid processing capabilities anchor position through sole-source and competitive bidding mechanisms.
- Direct Sales:Manufacturer-to-agency relationships for large-volume law enforcement and private security accounts. Custom fitting services and replacement panel programs sustain recurring revenue attachment.
- Specialty Stores:Brick-and-mortar dealers with ballistic fitting expertise and immediate inventory availability. Regional police equipment suppliers and tactical retailers serve mid-size agencies and individual officers with personal purchase allowances.
- Online Retail:E-commerce platforms with standardized sizing and expedited fulfillment for individual buyers and small security firms. Limited fitting support constrains penetration in institutional segments requiring anatomical precision.
Government contracts hold installed capacity. Direct sales is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States manufacturers dominate export flows to European law enforcement agencies and Middle Eastern defense ministries, while Asian petrochemical processors anchor raw material supply chains feeding production networks across North America and Europe.
United States
Municipal police departments sustain replacement cycles through Department of Justice equipment grants, with federal procurement programs prioritizing female-fit anatomical designs under revised NIJ testing protocols. OSHA workplace safety directives extend vest requirements into private security contractor operations across Texas and California energy corridors. Point Blank Enterprises maintains captive aramid panel manufacturing in Florida to serve domestic federal contracts.
Germany
Federal police modernization programs and state-level law enforcement budgets drive specification intensity for multi-threat hybrid configurations. REACH substance restrictions tighten chemical compliance requirements for ballistic material coatings, forcing reformulation of lamination chemistries among suppliers serving cross-border contracts. Bavaria-based technical textile clusters absorb regulatory friction through integrated materials science capabilities.
United Kingdom
Metropolitan Police Service and regional constabularies prioritize stab-resistant layers for urban patrol operations where edged-weapon exposure exceeds ballistic risk. CE marking requirements and post-Brexit UKCA certification create dual compliance burdens for suppliers serving British agencies. VestGuard UK occupies a position among domestic specialists addressing this regulatory fragmentation.
India
Central Armed Police Forces and state police departments expand officer protection programs under Ministry of Home Affairs directives, with BIS standards gradually aligning with NIJ protocols for international procurement compatibility. MKU Limited anchors domestic production in Kanpur and Noida industrial corridors, serving paramilitary and export demand to African and Southeast Asian markets.
United Arab Emirates
Ministry of Interior procurement for federal police and private executive protection teams in Dubai and Abu Dhabi financial centers generates premium-tier demand for custom-fitted concealability. MOHAP medical device frameworks indirectly influence smart vest development timelines for biometric sensor integration. Regional security contractors source through re-export channels from European and North American suppliers.
Concealable Vest Market Competitive Landscape
Listed leaders compete with private specialists across federal contract access and materials science integration. The supplier base concentrates around three strategic tiers: integrated fiber-to-garment manufacturers with captive aramid processing, modular carrier system specialists anchoring recurring revenue through attachment ecosystems, and regional assemblers dependent on third-party component sourcing. Dominant competitive moves include backward integration into fiber production and strategic partnerships with law enforcement agencies for multi-year replacement programs.
Within the integrated manufacturing tier, Point Blank Enterprises and DuPont de Nemours exemplify contrasting approaches to value chain control, with the former representing captive panel production for margin defense across federal contracts and the latter occupying a position extending material science leadership into finished vest partnerships. Among specialized law enforcement channel players, Safariland anchors modular carrier system positioning, while MKU Limited and VestGuard UK sit within regional specialist archetypes serving domestic procurement with export capability. Armor Express and U.S. Armor Corporation represent mid-scale domestic fabricators competing on custom fitting services and replacement panel programs.
| Leading Market Players |
|---|
| Point Blank Enterprises, Inc. |
| Armor Express |
| U.S. Armor Corporation |
| VestGuard UK Ltd. |
| Safariland, LLC. |
| MKU Limited |
| MARS Armor Ltd. |
| EnGarde Body Armor |
| DuPont de Nemours, Inc. |
| Others |
Value Network & Pricing Analysis
Multi-year federal offtake agreements with municipal police departments lock in Kevlar panel supply from domestic weavers while freezing unit pricing visibility across replacement cycles. These contract structures tether finished vest manufacturers to captive aramid fiber sources, compressing margin flexibility when petrochemical feedstock volatility strikes UHMWPE channels.
Pricing Analysis
Next-generation UHMWPE panels command premium positioning against incumbent Kevlar constructions and legacy woven aramid generations. Three-tier pricing structure across premium, standard, and economy levels stratifies by NIJ certification tier and customization depth, with Level IIIA UHMWPE configurations at the top and generic Level II aramid fiber platforms at the base. Cost compression in standard-tier Kevlar contracts is intensifying because federal procurement officers exploit multi-source bidding leverage. Municipal police departments exhibit highest price sensitivity through grant-dependent budgeting, while executive protection teams in financial services show lowest sensitivity for custom-fitted concealment garments.
Supply Chain Analysis
Asian petrochemical processing clusters in South Korea, Japan, and China dominate ultra-high molecular weight polyethylene fiber precursor production, creating single-source vulnerability for premium-tier vest assemblers. Finished goods production draws from DuPont's domestic Kevlar facilities in Virginia and South Carolina, Teijin's Twaron operations in the Netherlands, and dispersed aramid weaving networks across the southeastern United States. Tariff exposure on UHMWPE feedstock imports threatens margin stability for manufacturers without backward integration into fiber production. Distribution runs through sole-source federal contracting vehicles, direct agency relationships, and regional police equipment dealers serving personal purchase allowances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against next-generation non-fiber ballistic solutions including shear-thickening fluid armor and active protection systems that threaten to displace passive fiber panels in specialized applications.
For Market Incumbents: Shield federal contract positions by deepening captive Kevlar weaving capacity in southeastern manufacturing corridors before NIJ female-fit retooling mandates accelerate. Secure pattern-making talent pools for anatomically specific designs ahead of competitor hiring waves. Vertical integration into compression molding equipment insulates against capital expenditure inflation driven by new NIJ mold specifications. For New Entrants and Emerging Players: Custom fitting services for female law enforcement officers represent a service-layer gap where incumbents under-serve due to anthropometric database deficits. Penetrate municipal agencies in Sun Belt states with growing officer diversity metrics and limited legacy supplier relationships. Lead with mobile measurement units and rapid-turn tailoring capabilities that bypass traditional six-week fitting cycles. For Investors and Strategic Acquirers: Modular carrier system specialists with attachment ecosystem lock-in present the most defensible acquisition target archetype as procurement unbundling fragments panel supply relationships. Long-term viability hinges on recurring revenue attachment rates rather than one-time vest sales. Watch biometric sensor integration patent filings as the inflection indicator for smart vest category formation.| Strategic Initiative | Industry Significance |
|---|---|
| Female-Fit Pattern Library Development | NIJ protocol revisions reward first-movers with existing anthropometric databases and technical talent. |
| UHMWPE Backward Integration | Captive fiber production insulates margin from Asian petrochemical processor pricing volatility. |
| Modular Carrier Ecosystem Expansion | Unbundled procurement elevates attachment revenue through holster and accessory lock-in. |
| Smart Vest Biometric Partnership | EU AI Act compliance requirements favor suppliers with embedded privacy-by-design architectures. |
| REACH-Compliant Lamination Reformulation | Integrated materials science capabilities absorb European chemical restriction friction more efficiently. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of NIJ compliance documentation, federal procurement databases, and OSHA workplace safety directives. Primary interviews engaged ballistic materials engineers at fiber-to-garment manufacturers, federal contracting officers at municipal police departments, technical pattern specialists, and private security procurement leads. Secondary validation incorporated Department of Justice equipment grant disclosures, SEC filings from listed materials suppliers, and customs trade data on aramid fiber imports. Bottom-up vest shipment analysis triangulates against top-down federal budget allocation modeling.
Segmentation dimensions modeled span product type hierarchy, material chemistry tier, end-user procurement sophistication, and distribution channel structure across the projection horizon. CAGRs derive from replacement cycle velocity analysis, federal funding trajectory assessment, and threat-profile evolution in urban law enforcement deployments. Female officer penetration rates and smart vest patent filing velocity serve as industry-specific forecast inputs.
Forecasts assume regulatory continuity in NIJ testing protocols and OSHA workplace safety regimes; material policy shifts would require re-modeling certification timeline assumptions and procurement specification baselines. Practitioners should keep alternative scenarios live as EU AI Act enforcement precedents and REACH substance restriction expansions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Safety
Night Vision Goggles Market
Personal Safety
Rearward Facing Type Child Safety Seats Market
Personal Safety
Personal Safety Alarms Market
Personal Safety
Global Self Defense Products Market
Personal Safety
Global Medical Alert System/Personal Emergency Response System Market
Personal Safety
Life Jacket Market
Personal Safety
Pepper Sprays Market
Personal Safety
Fall Detection System Market
Personal Safety
Smart Personal Safety and Security Device Market
Personal Safety
Child Leash Market
Personal Safety
Global Fall Protection Market
Personal Safety
Road Safety Market
Personal Safety
Asia-Pacific People Screening Market
Personal Safety
Child Safety Seat Market
Personal Safety
Bulletproof Vest Market
Personal Safety
Body Armor and Personal Protection Market