
 Rearward Facing Type Child Safety Seats Market | 2026-2036
Rearward Facing Type Child Safety Seats Market Size, Share, and Industry Trends Forecast 2026-2036
Rearward Facing Type Child Safety Seats Market Insights
Family fleet vehicle purchasing is broadening as a demand channel for rearward-facing child safety seats, with ride-share operators and corporate car-provision programs now specifying certified infant restraint systems for employee transport. Britax sustains strong European positioning through its R&D investment in side-impact absorption architectures. Graco competes aggressively on manufacturing scale across North American big-box retail channels. Maxi-Cosi leverages its integrated base technology to command premium positioning in urban specialty stores.
Rearward-facing child safety seats are restraint systems engineered to orient infants and toddlers toward the vehicle tail, distributing collision forces across the seat back and shell rather than the neck and spine; units typically incorporate energy-absorbing foam layers, five-point harness systems, and adjustable headrest mechanisms to accommodate growth from birth through approximately 15-24 months. Infant car seats dominate unit volume as hospital-discharge requirements in multiple jurisdictions mandate possession before newborn transport, while convertible car seats capture expanding share as parents seek extended rearward-facing utility through toddler age brackets. Side impact protection features command disproportionate margin contribution as safety-conscious buyers trade up from baseline configurations.
Federal regulators including NHTSA in the United States and ECE R129 (i-Size) frameworks in Europe are mandating extended rearward-facing duration and stricter frontal-impact deceleration thresholds, which forces manufacturers to redesign shell geometries and padding densities. Compliance with FMVSS 213 and forthcoming EU updates will determine market access for non-certified imports. Stakeholders must monitor regulatory divergence between testing protocols as a primary determinant of product development resource allocation and geographic launch sequencing.
Market Dynamics
Regulatory divergence between ECE R129 and FMVSS 213 is fragmenting product architectures, forcing manufacturers to maintain dual shell geometries and testing protocols rather than unified global platforms.
Growth Catalysts
- ECE R129 (i-Size) extension mandates:European regulators now require rearward-facing orientation through 15 months minimum, compelling replacement cycles for older forward-facing units and expanding addressable unit volume.
- Dual-income urban households:This buyer segment prioritizes certified safety systems and demonstrates higher willingness-to-pay for side-impact protection features in dense metropolitan driving environments.
- Energy-absorbing foam innovation:Advanced expanded polypropylene cores are reducing shell weight while improving deceleration performance, enabling easier installation and broader vehicle compatibility.
Market Restraints
- Petrochemical input volatility:Polypropylene and high-density polyethylene feedstock costs fluctuate with crude oil benchmarks, compressing margin stability for molded shell producers.
- Testing facility concentration:Certified crash-test infrastructure clusters in Germany, the United States, and Japan, creating bottlenecks for new market entrants seeking dual-regulation approval.
- Forward-facing convertible substitution:Some parents transition children earlier than recommended to extended-use convertible seats, reducing the effective rearward-facing duration window.
Strategic Opportunities
- Ride-share fleet specification:Corporate transport programs and mobility-as-a-service operators are drafting infant restraint requirements for employee and client transport, opening institutional procurement channels.
- Integrated base technology convergence:ISOFIX-compatible docking systems combined with load-leg stabilization are creating premium upgrade pathways for safety-conscious buyers.
- Underpenetrated secondary vehicle households:Families maintaining multiple vehicles often install seats in only the primary car, leaving significant attach rate expansion potential in second and third vehicle segments.
Industry Challenges
- Biomechanical engineer scarcity:Specialized expertise in pediatric injury kinematics and anthropomorphic test device calibration commands premium compensation and extends R&D timelines.
- Dual-certification capex burden:Parallel testing to ECE R129 and FMVSS 213 standards requires duplicate prototype builds and facility bookings, straining development budgets for mid-tier manufacturers.
- Regulatory harmonization delays:Divergent frontal-impact pulse specifications between European and American protocols prevent platform standardization and inflate per-unit engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rearward Facing Type Child Safety Seats Market |
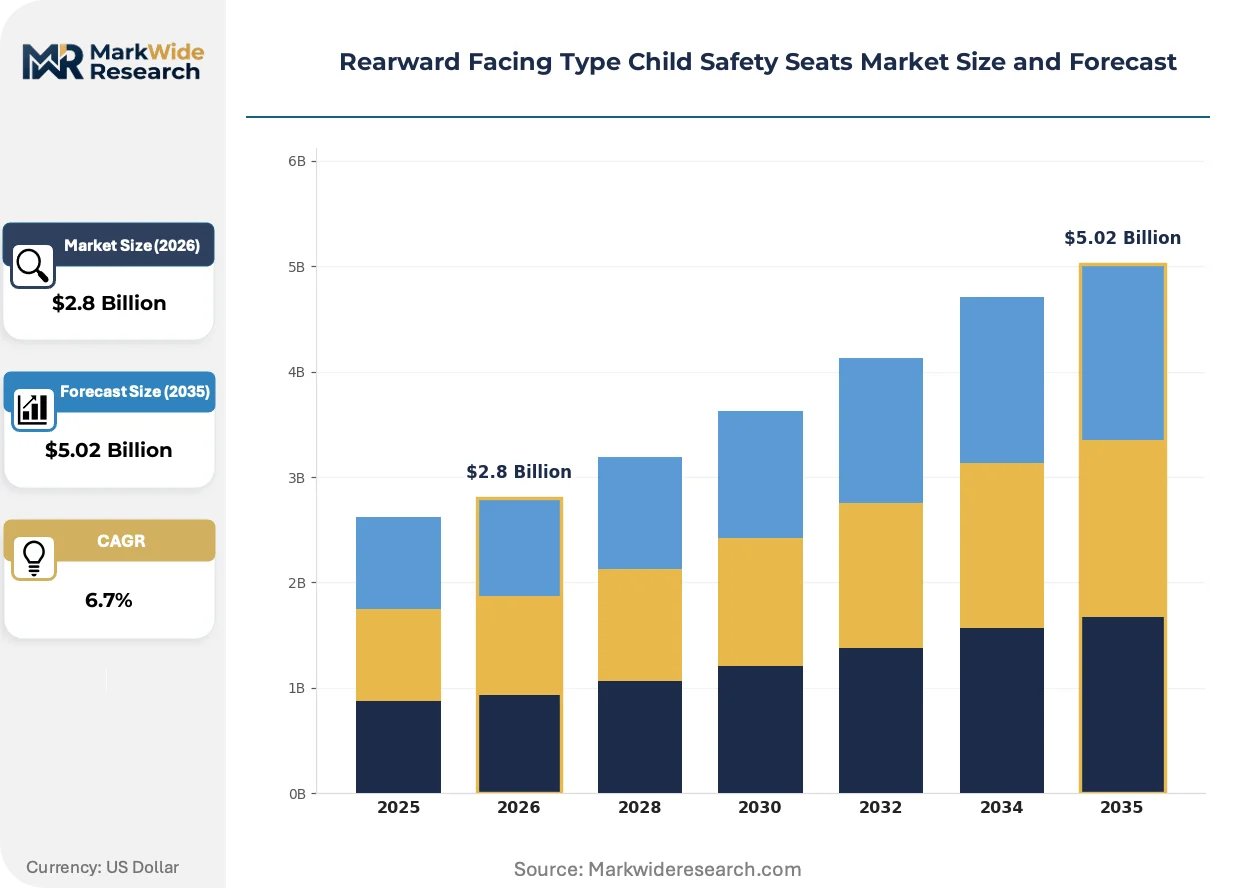
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infant Car Seats, Convertible Car Seats, Booster Seats, All-in-One Seats Installation Method: LATCH System, Seat Belt, Vehicle Anchor, Integrated Base Safety Features: Side Impact Protection, Energy-Absorbing Foam, Adjustable Headrest, Harness System Age Group: Newborns, Infants, Toddlers, Pre-schoolers |
| Companies Covered | Maxi-Cosi, Evenflo, Nuna, Britax, Graco, Cybex, Chicco, Recaro, Diono, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rearward Facing Type Child Safety Seats Market Trends and Innovations
Active safety integration and modular base architectures are compressing product lifecycles while elevating performance expectations beyond baseline regulatory minimums.
Sensor-embedded restraint systems are integrating pressure and position monitors that alert caregivers to harness slack or seat-angle deviations through smartphone connectivity. Urban specialty retailers are bundling these units with installation verification services. This convergence is integrating real-time feedback loops into what were previously passive mechanical systems, shifting competitive differentiation toward data-enabled peace-of-mind.
NHTSA is tightening FMVSS 213 frontal-impact deceleration thresholds and exploring side-impact test protocol additions that would mirror ECE R129 methodologies. Manufacturers serving both markets face dual redesign cycles. Convertible seat architectures in North America are most affected, as these platforms must accommodate both rearward-facing infant and forward-facing toddler configurations under stricter combined load cases.
Hospital discharge mandate compliance is concentrating initial purchase decisions around infant car seats with certified installation services. Parents increasingly complete pre-birth seat fitting at designated inspection stations rather than self-installing. Germany exhibits the highest penetration of professional fitting services, with municipal health insurers in some Länder subsidizing certified technician consultations as preventive care expenditure.
Rearward Facing Type Child Safety Seats Market Segmentation
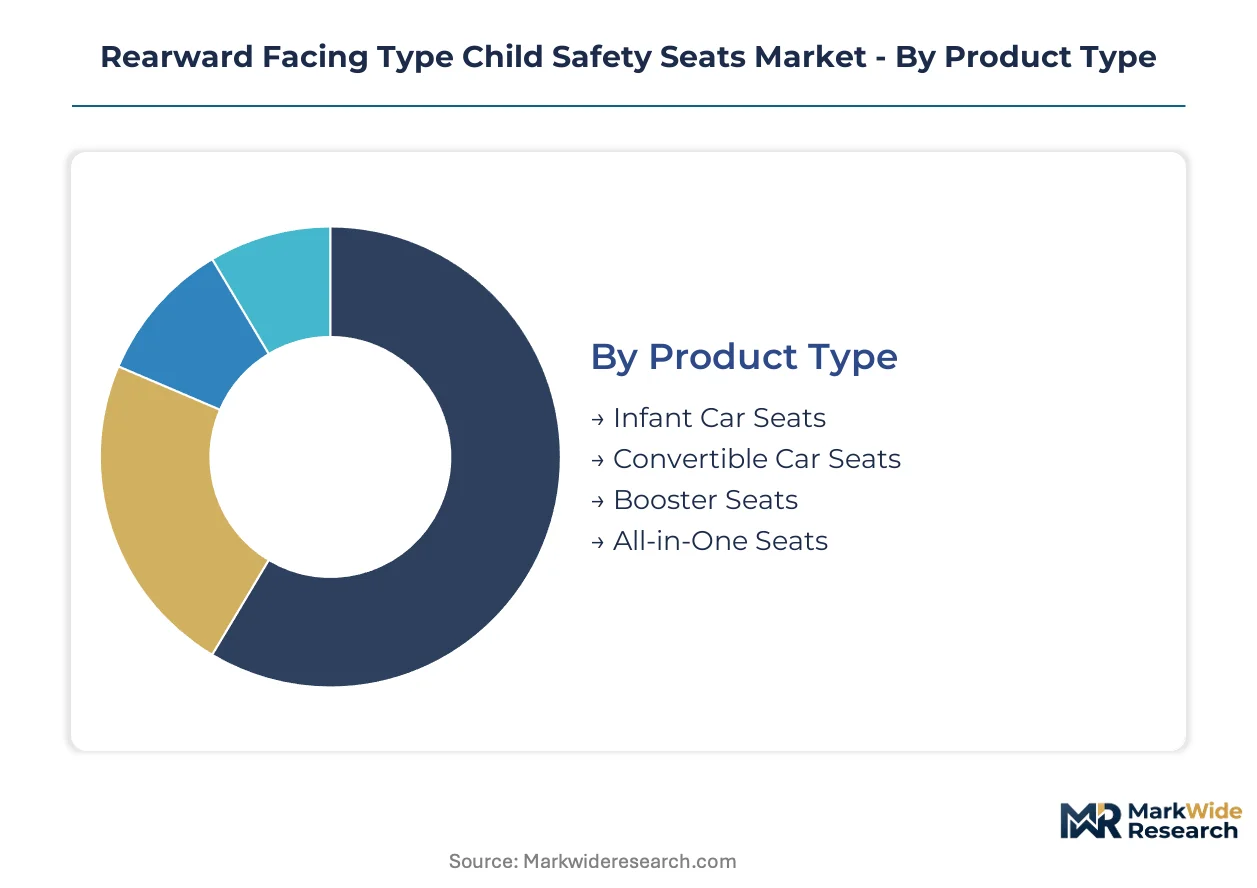
Rearward-facing child safety seats fragment across four distinct dimensions that shape procurement patterns and margin structures. Installation complexity, safety certification tiers, and age-appropriate sizing each create separate buyer decision trees that manufacturers must navigate simultaneously.
Product Type:
Parents weigh initial purchase cost against total usable lifespan when selecting seat architecture.
- Infant Car Seats:Dedicated rearward-only units with detachable bases dominate hospital-discharge compliance channels. Demand concentrates in Germany, where municipal health insurers subsidize certified installation services as preventive care expenditure.
- Convertible Car Seats:Dual-orientation platforms accommodate extended rearward-facing duration through toddler age brackets. Urban dual-income households in dense metropolitan driving environments prioritize these units for their multi-year utility horizon.
- Booster Seats:Forward-facing transition products for older children; limited rearward-facing relevance restricts penetration in this market segment.
- All-in-One Seats:Single-purchase solutions spanning newborn through booster stages; weight and installation complexity trade against convenience appeal.
Infant car seats lead on scale; convertible car seats lead on momentum.
Installation Method:
Vehicle interface standards determine retailer attach rates for professional fitting services.
- LATCH System:Lower Anchors and Tethers for Children hardware enables tool-free attachment in post-2002 vehicles. NHTSA-mandated universal anchor placement drives baseline compatibility across United States vehicle fleets.
- Seat Belt:Universal fallback routing through lap-shoulder belts accommodates older vehicle parc and rental fleet installations. Training requirements for correct locking-clip usage sustain technician consultation demand.
- Vehicle Anchor:Top-tether anchorage points for forward-facing mode conversion; rearward-facing configurations rarely deploy this interface.
- Integrated Base:ISOFIX-compatible docking with load-leg stabilization commands premium positioning in urban specialty retail channels.
LATCH and seat belt methods dominate volume; integrated base systems expand most quickly in premium urban segments.
Safety Features:
Certification tier and biomechanical performance separate price positioning in retail channels.
- Side Impact Protection:Reinforced shell wings and energy-dissipation structures address ECE R129 testing protocols. German buyers demonstrate highest willingness-to-pay for this feature among developed economies.
- Energy-Absorbing Foam:Expanded polypropylene cores reduce deceleration forces while trimming shell weight for easier handling. Polypropylene feedstock volatility from crude oil benchmarks compresses margin stability for molded component producers.
- Adjustable Headrest:Growth-accommodation mechanisms extend usable lifespan across multiple height percentiles.
- Harness System:Five-point restraint configurations with chest-clip positioning represent baseline regulatory compliance across FMVSS 213 and ECE R129 jurisdictions.
Harness systems lead on scale; side impact protection leads on momentum.
Age Group:
Regulatory minimums and pediatric biomechanics define product sizing and marketing focus.
- Newborns:Low birth-weight accommodation and premature-infant positioning inserts target neonatal transport requirements.
- Infants:Birth-to-15-month rearward-facing duration captures core regulatory compliance window under ECE R129 extension mandates.
- Toddlers:Extended rearward-facing up to 24 months or weight limits represents fastest-growing parental practice in safety-conscious segments.
- Pre-schoolers:Forward-facing transition age bracket; minimal rearward-facing relevance limits addressable market scope.
Infants lead on scale; toddlers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as producers migrate toward jurisdictions with streamlined certification reciprocity and lower per-unit compliance costs. Dual-testing burdens under divergent ECE R129 and FMVSS 213 protocols concentrate investment in countries offering consolidated approval pathways.
Germany
KBA-administered i-Size enforcement and municipal health insurer subsidies for certified installation services sustain premium-tier demand concentration. ECE R129 extension mandates through 15 months minimum compel replacement cycles across the installed base. Industrial clustering in Bavaria and Baden-Württemberg hosts specialized crash-test infrastructure and biomechanical engineering talent pools serving continental supply chains.
United States
NHTSA's tightening FMVSS 213 frontal-impact thresholds and exploration of side-impact protocol additions drive redesign cycles for convertible seat architectures. Hospital discharge mandates in multiple states concentrate initial purchase decisions around infant car seats with professional fitting services. Manufacturing and testing infrastructure clusters in Michigan and Ohio support domestic supply chain requirements.
China
Expanding dual-income urban households in tier-one cities generate demand for ISOFIX-compatible integrated base systems with load-leg stabilization. GB standards alignment with ECE R129 methodologies accelerates for export-oriented producers while domestic protocols evolve separately. Yangtze River Delta manufacturing zones concentrate molded shell production and expanded polypropylene component fabrication.
United Kingdom
Post-regulatory transition alignment with retained EU vehicle safety frameworks sustains i-Size certification requirements for market access. Urban specialty retail channels in London and Southeast England command premium positioning for side-impact protection features. Midlands-based distribution infrastructure supports national installation service networks and technician training programs.
Japan
METI-coordinated consumer safety campaigns elevate extended rearward-facing duration awareness among first-time parents. JIS standard harmonization efforts with ECE R129 protocols reduce dual-certification burdens for domestic manufacturers. Kanto region engineering centers concentrate anthropomorphic test device calibration and pediatric injury kinematics research capabilities.
Rearward Facing Type Child Safety Seats Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers expand across infant, convertible, and all-in-one architectures to capture replacement-cycle value. The vendor base organizes around three tiers: integrated-base technology specialists commanding urban premium channels, scale-driven fabricants serving big-box retail volumes, and regional compliance-focused assemblers addressing localized certification requirements. Strategic archetypes include safety-feature differentiation players, manufacturing-efficiency optimizers, and regulatory-navigation specialists. M&A activity and geographic certification expansion represent the dominant competitive moves as firms seek dual-standard approval capabilities.
Among European-anchored specialists, Britax and Maxi-Cosi exemplify divergent positioning archetypes within the premium tier. Britax occupies a position associated with side-impact absorption architecture investment, while Maxi-Cosi represents integrated base technology convergence with ISOFIX-compatible docking systems. Graco sits within the North American scale-driven segment, its positioning tied to manufacturing throughput and retail channel penetration rather than feature-premium extraction. These three anchors illustrate how geographic origin and stated capability focus stratify competitive space without requiring specific performance claims.
| Leading Market Players |
|---|
| Maxi-Cosi |
| Evenflo |
| Nuna |
| Britax |
| Graco |
| Cybex |
| Chicco |
| Recaro |
| Diono |
| Others |
Pricing and Supply Chain Analysis
Expanded polypropylene core adoption in molded shell production simultaneously trims per-unit material costs and concentrates supplier leverage among German and Chinese polymer compounders with certified automotive-grade capacity. This technology shift compresses margin structures for mid-tier seat fabricants while elevating pricing power for integrated-base specialists commanding urban specialty retail channels.
Pricing Analysis
Retailer markup layers in urban specialty channels capture premium extraction for ISOFIX-compatible systems with load-leg stabilization, while big-box volume channels operate on thinner distributor margins. Price differentiation rests on ECE R129 certification tier and side-impact protection feature bundling, with German buyers demonstrating lowest price sensitivity. Cost compression in standard-tier infant seats is intensifying because polypropylene feedstock volatility from crude oil benchmarks squeezes molded component producers. Fleet procurement channels for ride-share operators exhibit highest price sensitivity due to volume-scale negotiation leverage.
Supply Chain Analysis
Dual-certification gating under ECE R129 and FMVSS 213 concentrates compliant manufacturing in Germany, the United States, and China's Yangtze River Delta zones. Raw material dependencies draw from Saudi Arabian polypropylene feedstock, South Korean expanded foam cores, and Belgian high-performance textile webbing. Single-source vulnerability in certified crash-test infrastructure clusters creates approval bottlenecks for new market entrants. Distribution runs through Tier 1 automotive supplier networks and specialty juvenile-product retail chains with certified installation service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where ECE R129 certification costs in Germany run substantially above FMVSS 213 testing expenditures in the United States, creating margin expansion opportunities for dual-standard producers optimizing launch sequencing.
For Market Incumbents: Cement positioning in integrated-base technology convergence by acquiring ISOFIX-compatible docking specialists in urban European markets. Biomechanical engineer scarcity commands premium compensation and extends R&D timelines, threatening development velocity. Channel control through certified installation service networks in Germany and the United Kingdom defends margin position against scale-driven North American competitors.
For New Entrants and Emerging Players: Enter via underpenetrated secondary vehicle household segments where attach rates in second and third vehicles lag primary car installations significantly. The most penetrable geography is China's tier-one cities, where dual-income urban households generate demand for premium safety-feature bundling. A direct-to-fleet procurement angle targeting ride-share operator specifications bypasses entrenched retail channel barriers.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional compliance-focused assemblers with single-standard certification seeking dual-approval capex. Long-term viability across the projection horizon favors manufacturers with backward integration into expanded polypropylene core production and captive crash-test infrastructure. The signal to watch is NHTSA's finalization of side-impact protocol additions mirroring ECE R129 methodologies, which would trigger redesign cycles benefiting certified-testing-asset owners.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Standard Certification Investment | Parallel ECE R129 and FMVSS 213 approval unlocks access to German and United States hospital-discharge compliance channels simultaneously. |
| Integrated Base Technology Acquisition | ISOFIX-compatible docking with load-leg stabilization commands premium positioning in urban specialty retail channels. |
| Biomechanical Engineering Talent Recruitment | Pediatric injury kinematics expertise shortens R&D timelines for side-impact absorption architecture development. |
| Fleet Procurement Channel Development | Ride-share operator specifications open institutional volumes with multi-unit contract structures and reduced marketing expenditure. |
| Polypropylene Feedstock Integration | Upstream control over expanded foam core production insulates margin stability from crude oil benchmark volatility. |
Research Methodology
Bottom-up infant and convertible seat demand modeling reconciled against top-down polymer feedstock and molded shell production tracking forms the analytical core of this study. Primary interviews with product development executives at seat manufacturers, regulatory affairs leads navigating ECE R129 and FMVSS 213 protocols, category buyers at urban specialty retailers, and fleet procurement officers at ride-share operators combined with secondary validation from KBA enforcement disclosures, NHTSA FMVSS 213 docket filings, and German municipal health insurer preventive care expenditure records. Bottom-up and top-down triangulation reconciles unit shipment estimates against raw material consumption patterns.
Historical trendline analysis of replacement cycles, regulatory mandate adoption curves, and premium-feature penetration rates informs the projection framework. Segmentation dimensions modeled include product type architecture, installation method interface, safety certification tier, and age-appropriate sizing across metropolitan density classifications. CAGRs were derived from regression analysis of segment-level growth trajectories. Industry-specific forecast inputs incorporate ECE R129 extension mandate compliance deadlines and hospital discharge policy evolution across state and municipal jurisdictions.
Inputs from KBA enforcement databases and NHTSA compliance filings were available through the study window; gaps in real-time fleet procurement contract disclosure introduce uncertainty bands around institutional channel estimates. Forecasts reflect assumptions regarding regulatory harmonization timelines and petrochemical input cost stability. A model refresh is warranted upon material change in NHTSA side-impact protocol finalization or ECE R129 age-threshold extension mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Safety
Personal Safety Apps for Women Market
Personal Safety
Concealable Vest Market
Personal Safety
Road Safety Market
Personal Safety
Child Leash Market
Personal Safety
Asia-Pacific People Screening Market
Personal Safety
Global Personal Emergency Response Systems (PERS) Market
Personal Safety
Global Fall Protection Market
Personal Safety
Body Armor and Personal Protection Market
Personal Safety
Life Jacket Market
Personal Safety
Night Vision Goggles Market
Personal Safety
Pedestrian Protection Airbag Market
Personal Safety
Global Self Defense Products Market
Personal Safety
Smart Personal Safety and Security Device Market
Personal Safety
Child Safety Seat Market
Personal Safety
Bulletproof Vest Market
Personal Safety
Fall Detection System Market