
 Pedestrian Protection Airbag Market | 2026-2036
Pedestrian Protection Airbag Market Size, Share, and Industry Trends Forecast 2026-2036
Pedestrian Protection Airbag Market Insights
Silicone-coated fabric is shifting toward thinner, higher-tear-strength substrates in pedestrian protection airbag construction, reducing module weight while maintaining burst pressure integrity. Autoliv leverages captive weaving and coating operations to control material cost trajectories across European OEM programs. Continental anchors its competitive stance through integrated sensor-to-deployment electronics that compress reaction times below ten milliseconds. ZF Friedrichshafen specializes in hood-lifting pyrotechnic actuators paired with external airbag modules, creating bundled pedestrian safety architectures.
Pedestrian protection airbags are externally mounted cushioning devices engineered to deploy upon collision detection, typically utilizing multi-layer polyamide fabric with silicone elastomer coatings rated for sub-20-millisecond inflation at pressures between 150 and 300 kPa, designed to mitigate head and torso impact severity during vehicle-to-pedestrian contact events. Front airbags dominate current OEM fitment programs due to their integration with hood reinforcement structures and established crash-test validation protocols, while sensor-based technology commands premium positioning as camera-radar fusion enables predictive deployment before physical contact. Electric vehicles represent the fastest-growing vehicle-type segment, driven by platform-specific packaging freedom that accommodates bumper-integrated inflator modules absent internal combustion powertrain interference.
The European Union's General Safety Regulation and the UN ECE R127 pedestrian safety protocol mandate measurable head-impact performance, directly compelling OEMs to certify active protection systems including external airbags for type approval in EU member states. The US NHTSA Federal Motor Vehicle Safety Standard No. 127 and the China MIIT vehicle safety technical committee are advancing comparable performance requirements that will shape homologation pathways for export-oriented suppliers. Stakeholders must monitor regulatory divergence between predictive sensor-triggered and contact-only deployment standards, as this technical boundary will determine which technology architectures achieve multi-region scalability without redundant engineering.
Market Dynamics
Europe's General Safety Regulation is compressing homologation timelines for active pedestrian protection systems, forcing OEMs to integrate predictive sensor architectures with external airbag modules years ahead of voluntary adoption curves.
Growth Catalysts
- EU Regulatory Mandate:The General Safety Regulation mandates active pedestrian protection systems for type approval, compelling automakers to certify hood-mounted and A-pillar airbag modules across premium vehicle programs.
- Electric Vehicle Platform Freedom:Battery-electric architectures eliminate internal combustion powertrain interference, enabling bumper-integrated inflator module packaging that internal combustion vehicles cannot accommodate.
- German OEM Development Programs:BMW, Mercedes-Benz, and Volkswagen anchor supplier engineering efforts for next-generation external airbag systems, concentrating R&D investment and validation resources in Stuttgart, Munich, and Wolfsburg.
Market Restraints
- Silicone Elastomer Input Volatility:Specialized coating materials for multi-layer polyamide fabric substrates face supply concentration among European chemical processors, creating cost instability for module manufacturers.
- Sensor-Deployment Latency:Camera-radar fusion systems must compress reaction times below ten milliseconds for predictive deployment, a technical boundary that contact-only architectures do not face.
- Regional Regulatory Divergence:The UN ECE R127 protocol, US NHTSA Federal Motor Vehicle Safety Standard No. 127, and China MIIT technical requirements are advancing on non-identical timelines, fragmenting homologation pathways.
Strategic Opportunities
- China MIIT Compliance Window:The vehicle safety technical committee is advancing pedestrian protection performance requirements, creating first-mover positioning for suppliers that pre-certify to emerging GB standards.
- Sensor-Airbag Convergence:Integration of predictive trigger electronics with inflator control modules enables bundled safety architectures that command premium positioning in OEM procurement.
- Aftermarket Fleet Retrofit Channel:Urban commercial vehicle operators in high-pedestrian-density zones represent an untapped installation base for retrofit external airbag systems with simplified contact-only deployment logic.
Industry Challenges
- Sub-20-Millisecond Inflation Engineering:Module designers must maintain burst pressure integrity at 150-300 kPa across thinner, higher-tear-strength substrates without validated simulation tools for pedestrian biomechanics.
- Multi-Region Certification Parallelism:Engineering teams must manage redundant validation protocols for EU, US, and China type approval simultaneously, stretching technical documentation and testing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pedestrian Protection Airbag Market |
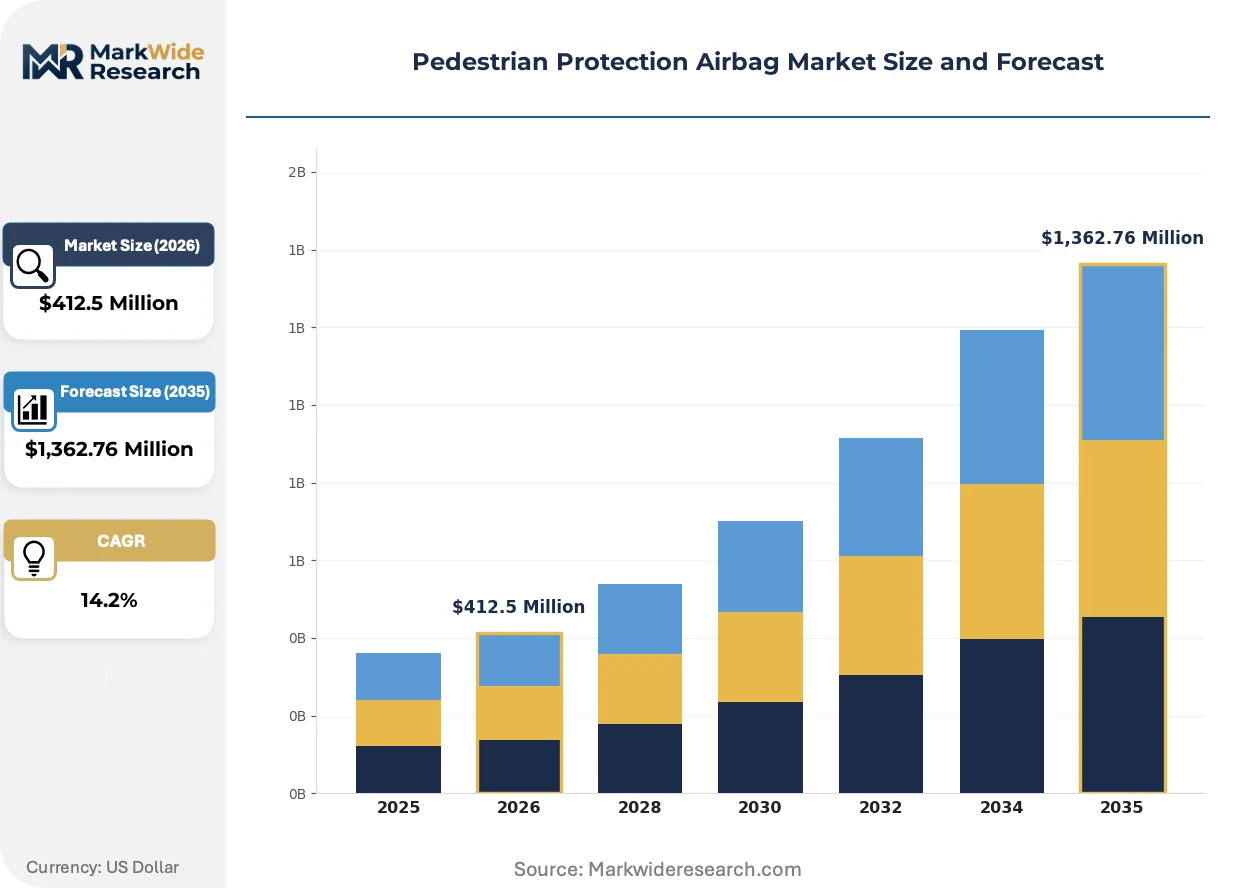
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,362.76 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Airbags, Side Airbags, Knee Airbags, Curtain Airbags Technology: Rapid Deployment, Sensor-Based, Passive Systems, Active Systems Vehicle Type: SUVs, Sedans, Hatchbacks, Electric Vehicles End User: OEMs, Aftermarket Suppliers, Tier-1 Manufacturers, Vehicle Designers |
| Companies Covered | ZF Friedrichshafen, Aptiv, Robert Bosch, Valeo, Hitachi Astemo, Autoliv, Denso, Marelli, Continental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pedestrian Protection Airbag Market Trends and Innovations
Predictive deployment architectures are displacing contact-only systems as the dominant technical pathway, compressing the window between collision detection and airbag inflation while raising the engineering bar for sensor fusion reliability.
Silicone-coated polyamide fabric is expanding into thinner substrate configurations that reduce module weight while maintaining pressure containment. Premium OEM programs in Germany are adopting these materials at accelerated validation cycles. This material evolution is expanding into hood reinforcement structures previously reserved for metal-only architectures, enabling integrated cushioning zones without hood deformation compromise.
The UN ECE R127 pedestrian safety protocol is tightening head-impact performance thresholds for type approval in EU member states. Automakers must now certify active protection systems including external airbags to maintain market access. European premium segments are responding with sensor-integrated architectures that trigger before physical contact, while value segments lag with contact-only systems that risk regulatory obsolescence.
Buyer concentration among German OEM procurement functions is consolidating supplier relationships around bundled safety system vendors. Tier-1 module specialists that lack captive weaving or coating operations are losing position to vertically integrated competitors. This consolidation is most visible in Stuttgart and Munich, where Mercedes-Benz and BMW have reduced their external airbag supplier bases to dual-source configurations from three or more incumbents.
Pedestrian Protection Airbag Market Segmentation
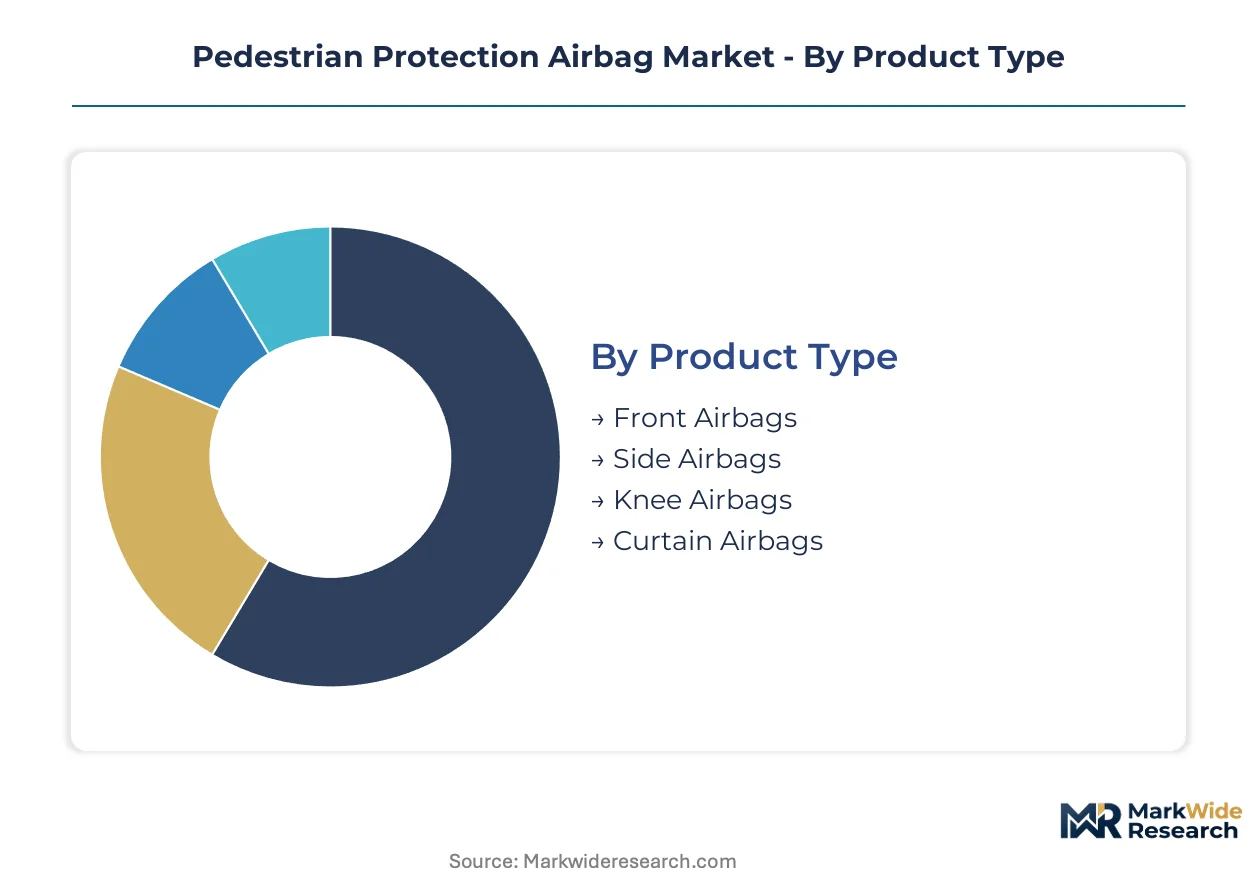
Segmentation in pedestrian protection airbags reveals how regulatory pressure and platform architecture reshape procurement priorities. OEMs select module configurations based on homologation pathways, vehicle packaging constraints, and sensor integration requirements.
Product Type:
Replacement cycles for external airbag modules accelerate as EU General Safety Regulation mandates trigger redesigns of hood and A-pillar architectures.
- Front Airbags:Hood-mounted cushioning modules deploy across the bumper-to-windshield zone using multi-layer polyamide fabric with silicone elastomer coatings rated for 150-300 kPa burst pressure. German premium OEMs in Stuttgart and Munich concentrate procurement here, driven by UN ECE R127 head-impact certification requirements.
- Side Airbags:A-pillar and fender-mounted configurations protect against lateral pedestrian contact during turning maneuvers. Demand clusters in Wolfsburg where Volkswagen anchors supplier validation programs for bundled sensor-airbag architectures.
- Knee Airbags:Lower extremity protection modules integrate with bumper reinforcement structures.
- Curtain Airbags:Vertical deployment systems extend coverage across windshield edges.
Front Airbags sits at the top of the volume ranking, with Side Airbags climbing the fastest.
Technology:
Cost tiers separate predictive architectures from contact-only systems, with sensor fusion commanding premium positioning in OEM procurement.
- Sensor-Based:Camera-radar fusion enables sub-10-millisecond predictive deployment before physical contact. European premium segments adopt these systems to meet EU General Safety Regulation active protection mandates.
- Rapid Deployment:Optimized inflator chemistry and gas generator geometry achieve sub-20-millisecond inflation without predictive sensing. Value-oriented programs in Germany specify these modules where regulatory thresholds permit contact-triggered architectures.
- Active Systems:Pyrotechnic hood-lifting actuators paired with airbag deployment.
- Passive Systems:Energy-absorbing structures without active deployment mechanisms.
Sensor-Based commands the premium tier, while Rapid Deployment expands most quickly in cost-sensitive segments.
Vehicle Type:
Application requirements vary sharply across platform architectures, with battery-electric designs offering packaging advantages absent in internal combustion vehicles.
- Electric Vehicles:Battery-electric platforms eliminate engine bay interference, enabling bumper-integrated inflator modules and hood-mounted architectures previously impractical. German OEM development programs in Munich and Stuttgart prioritize these configurations.
- SUVs:Higher hood profiles demand extended deployment zones to address head-impact geometry. Engineering validation concentrates in Wolfsburg where platform-sharing across VW Group brands creates volume concentration.
- Sedans:Lower hood lines enable compact module packaging with reduced inflation volume requirements.
- Hatchbacks:Short hood lengths constrain deployment zone geometry.
SUVs dominate current fitment volumes, with Electric Vehicles gaining share fastest as platform transitions accelerate.
End User:
Customer type determines specification rigor, with OEM procurement functions imposing validation standards that aftermarket channels cannot replicate.
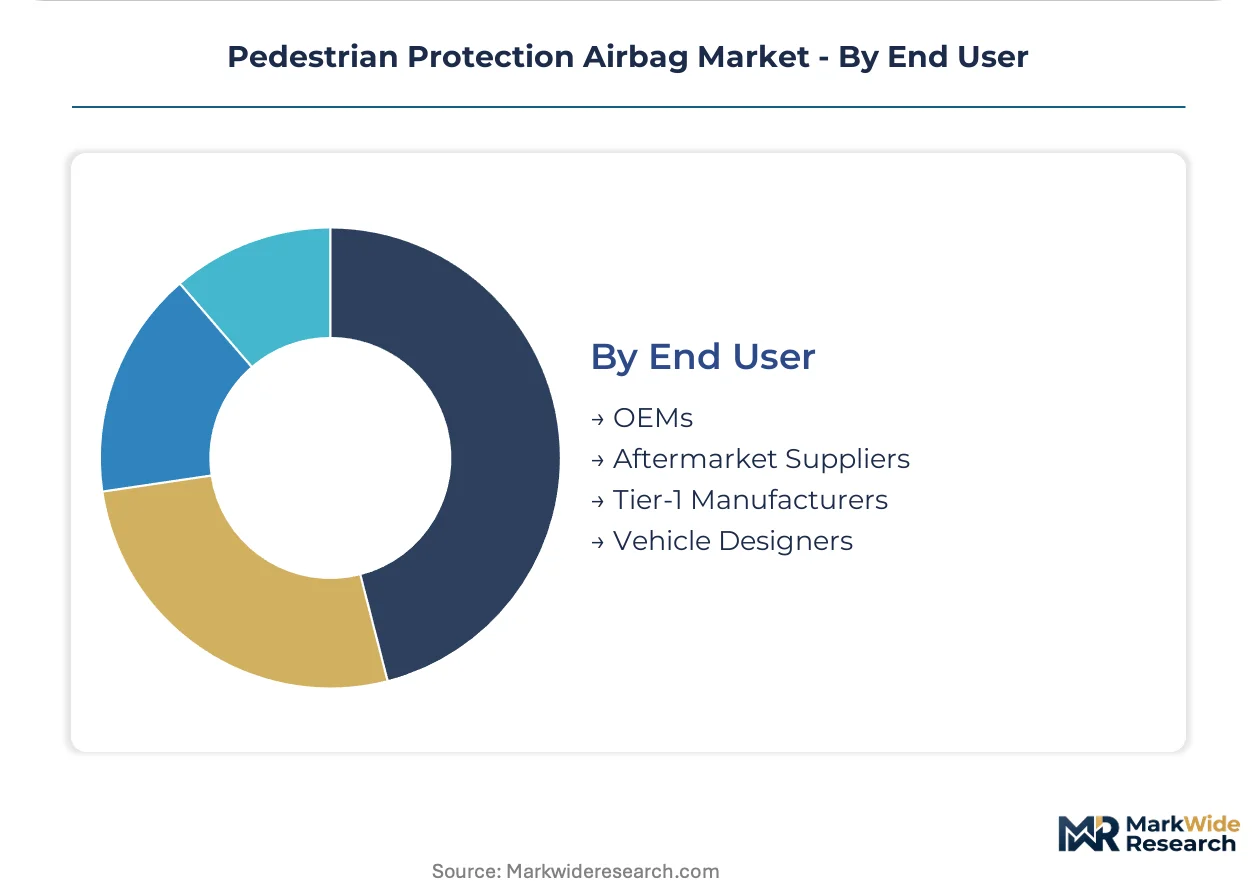
- OEMs:Vehicle manufacturers specify modules for type approval under UN ECE R127 and EU General Safety Regulation, requiring traceable validation documentation and multi-region homologation support. BMW, Mercedes-Benz, and Volkswagen procurement functions in Germany consolidate supplier relationships around bundled safety system vendors.
- Tier-1 Manufacturers:Module specialists supply integrated sensor-to-deployment architectures to OEM assembly plants. These suppliers face pressure to demonstrate captive weaving and coating capabilities or risk exclusion from dual-source configurations.
- Aftermarket Suppliers:Retrofit channel participants target urban commercial fleets with simplified contact-only deployment logic.
- Vehicle Designers:Engineering consultancies specify pedestrian protection architectures during platform development.
OEMs anchor the demand base, with Tier-1 Manufacturers facing the steepest capability requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors the pedestrian protection airbag development cluster, with German OEM procurement functions driving supplier consolidation across premium vehicle programs. Regulatory mandates in the European Union, United States, and China are compressing homologation timelines and reshaping regional competitive positioning.
Germany
BMW, Mercedes-Benz, and Volkswagen procurement teams in Munich, Stuttgart, and Wolfsurg are consolidating supplier relationships around bundled safety system vendors. The EU General Safety Regulation mandates active pedestrian protection systems for type approval, compelling hood-mounted and A-pillar module certification. Engineering validation concentrates in Stuttgart where Mercedes-Benz has reduced its external airbag supplier base to dual-source configurations.
United States
NHTSA Federal Motor Vehicle Safety Standard No. 127 is advancing pedestrian protection performance requirements that will shape homologation pathways for export-oriented suppliers. Domestic OEM engineering centers in Detroit and California are evaluating sensor-integrated architectures for predictive deployment. Regulatory divergence from EU protocols is fragmenting certification requirements for multi-region suppliers.
China
MIIT vehicle safety technical committee is advancing comparable pedestrian protection standards to the UN ECE R127 protocol, creating first-mover positioning for pre-certified suppliers. Electric vehicle platform transitions in Shanghai and Shenzhen are enabling bumper-integrated inflator module packaging absent internal combustion interference. GB standard development is accelerating validation cycles for domestic OEM procurement.
Japan
Hitachi Astemo and Denso anchor supplier development programs for camera-radar fusion systems that compress reaction times below ten milliseconds. METI industrial policy supports sensor-to-deployment electronics integration for predictive architectures. Engineering resources concentrate in Nagoya and Tokyo where tier-1 specialists face pressure to demonstrate captive material capabilities.
South Korea
Hyundai and Kia procurement functions in Seoul are specifying external airbag modules for SUV and electric vehicle platforms with extended deployment zones. MFDS automotive safety standards are aligning with UN ECE protocols for head-impact certification. The Seoul Capital Area hosts validation programs for hood-lifting pyrotechnic actuators paired with airbag deployment.
Pedestrian Protection Airbag Market Competitive Landscape
Global majors compete with regional champions across sensor integration and material supply dimensions, with procurement consolidation favoring vertically integrated module specialists. The supplier base organizes into three strategic archetypes: integrated safety system vendors with captive weaving operations, electronics-focused specialists in predictive trigger systems, and regional fabricators serving cost-sensitive programs. Dominant competitive moves include backward integration into silicone-coated polyamide substrates and strategic partnerships for camera-radar fusion technology.
Among German-based integrated system vendors, ZF Friedrichshafen and Continental occupy positions exemplifying bundled safety architectures that combine hood-lifting actuators with external airbag modules. Autoliv represents the vertically integrated archetype with captive weaving and coating operations controlling material cost trajectories across European OEM programs. These three companies anchor the premium-tier procurement landscape where dual-source configurations have replaced broader supplier bases.
| Leading Market Players |
|---|
| ZF Friedrichshafen |
| Aptiv |
| Robert Bosch |
| Valeo |
| Hitachi Astemo |
| Autoliv |
| Denso |
| Marelli |
| Continental |
| Others |
Pricing and Supply Chain Analysis
German OEM procurement consolidation around dual-source configurations is forcing module suppliers to absorb silicone elastomer cost volatility or risk contract termination, compressing margins for tier-1 specialists lacking captive weaving operations. This buyer-side pressure cascades through coating subcontractors and polyamide weavers, fragmenting pricing power across the value chain.
Pricing Analysis
Silicone elastomer cost pass-through dominates pricing negotiations between module manufacturers and European chemical processors. Pricing stratifies across sensor-integrated premium tiers, rapid-deployment standard tiers, and contact-only economy tiers, with certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from EU General Safety Regulation compliance costs, with value-oriented OEMs exhibiting highest price sensitivity and premium German brands demonstrating lowest.
Supply Chain Analysis
UN ECE R127 certification gating restricts qualified supply to Germany, Japan, and South Korea, where validated testing infrastructure exists. Production draws from specialized silicone-coated polyamide substrates, pyrotechnic inflator chemicals, and camera-radar fusion electronics. Single-source vulnerability concentrates in European silicone coating processors. Distribution runs through OEM direct procurement channels and tier-1 system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pedestrian protection airbags function as a stable compounder anchored by regulatory mandates that eliminate demand cyclicality. The EU General Safety Regulation creates irreversible fitment requirements across premium vehicle programs.
For Market Incumbents: Anchor market position through backward integration into silicone-coated polyamide substrates and captive weaving operations that neutralize input cost volatility. Defend against tier-1 specialists by accelerating sensor-to-deployment electronics convergence, compressing reaction times below ten milliseconds to meet predictive deployment mandates. For New Entrants and Emerging Players: Launch via aftermarket fleet retrofit channels targeting urban commercial vehicle operators in high-pedestrian-density zones, where simplified contact-only deployment logic suffices. White-space exists in China MIIT pre-certification for emerging GB standards, with first-mover positioning available for suppliers validating ahead of domestic OEM procurement cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated module specialists possessing captive material capabilities and validated UN ECE R127 certification. Long-term viability hinges on multi-region homologation capacity spanning EU, US, and China protocols. Monitor regulatory divergence between predictive sensor-triggered and contact-only deployment standards as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Airbag Electronics Convergence | Integration of predictive trigger modules with inflator control compresses deployment latency below ten milliseconds for EU compliance. |
| Captive Weaving and Coating Operations | In-house polyamide substrate production insulates Autoliv and integrated vendors from silicone elastomer cost volatility. |
| Multi-Region Homologation Parallelism | Simultaneous UN ECE R127, NHTSA FMVSS 127, and China MIIT certification enables scalable supplier positioning. |
| Electric Vehicle Platform Optimization | Bumper-integrated inflator modules exploit battery-electric packaging freedom absent internal combustion interference. |
| Aftermarket Fleet Retrofit Development | Simplified contact-only deployment systems target urban commercial operators outside OEM procurement channels. |
Research Methodology
Coverage spans Germany, United States, China, Japan, and South Korea, with primary inputs from each market cluster. The research combines interviews with OEM platform engineers, tier-1 supplier procurement managers, aftermarket distribution specialists, and regulatory affairs leads with secondary validation from UN ECE R127 certification databases, NHTSA FMVSS 127 draft filings, China MIIT technical committee disclosures, and vehicle production registration data. Bottom-up module shipment estimates triangulate against top-down OEM fitment projections.
Granularity extends to product type, technology tier, vehicle architecture, and end-user channel across the projection horizon. The analytical framework models sensor-based, rapid-deployment, active, and passive system segments alongside electric vehicle, SUV, sedan, and hatchback applications. CAGRs derive from regression analysis of historical fitment rates against regulatory mandate timelines, with electric vehicle platform transitions and German OEM procurement consolidation as key forecast inputs.
Several conditions sit outside the modeled scope, including potential regulatory delays in US NHTSA final rule issuance, silicone elastomer supply disruptions from European chemical processor consolidation, and breakthrough advances in pedestrian detection algorithms that could alter sensor hardware requirements. Deviation in predictive deployment standard adoption timing across major automotive markets would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Safety
Global Medical Alert System/Personal Emergency Response System Market
Personal Safety
Global Personal Emergency Response Systems (PERS) Market
Personal Safety
China Travel Safety Kits Market
Personal Safety
Smart Personal Safety and Security Device Market
Personal Safety
Concealable Vest Market
Personal Safety
Child Safety Seat Market
Personal Safety
Global Fall Protection Market
Personal Safety
Asia-Pacific People Screening Market
Personal Safety
Night Vision Goggles Market
Personal Safety
Bulletproof Vest Market
Personal Safety
Fall Detection System Market
Personal Safety
Road Safety Market
Personal Safety
Pepper Sprays Market
Personal Safety
Personal Safety Apps for Women Market
Personal Safety
Body Armor and Personal Protection Market
Personal Safety
Life Jacket Market