
 Pepper Sprays Market | 2026-2036
Pepper Sprays Market Size, Share, and Industry Trends Forecast 2026-2036
Pepper Sprays Market Intelligence
Multi-source procurement of oleoresin capsicum extracts is recalibrating how manufacturers secure active ingredient supply chains. SABRE - Security Equipment Corp leverages integrated in-house blending capabilities to control batch consistency. Fox Labs competes through concentrated formulation R&D, while Mace Brand anchors retail distribution across mass-market channels.
Pepper spray denotes an aerosolized or streamed self-defense device containing oleoresin capsicum, a lipophilic extract from Capsicum plants typically formulated at concentrations between 0.18% and 1.33% major capsaicinoids, designed to induce temporary ocular and respiratory incapacitation. Law enforcement end users dominate volume procurement through institutional tendering, while personal defense represents the fastest-expanding segment driven by direct-to-consumer online retail growth. Gel formulations command premium positioning due to reduced cross-contamination risk and targeted deployment accuracy.
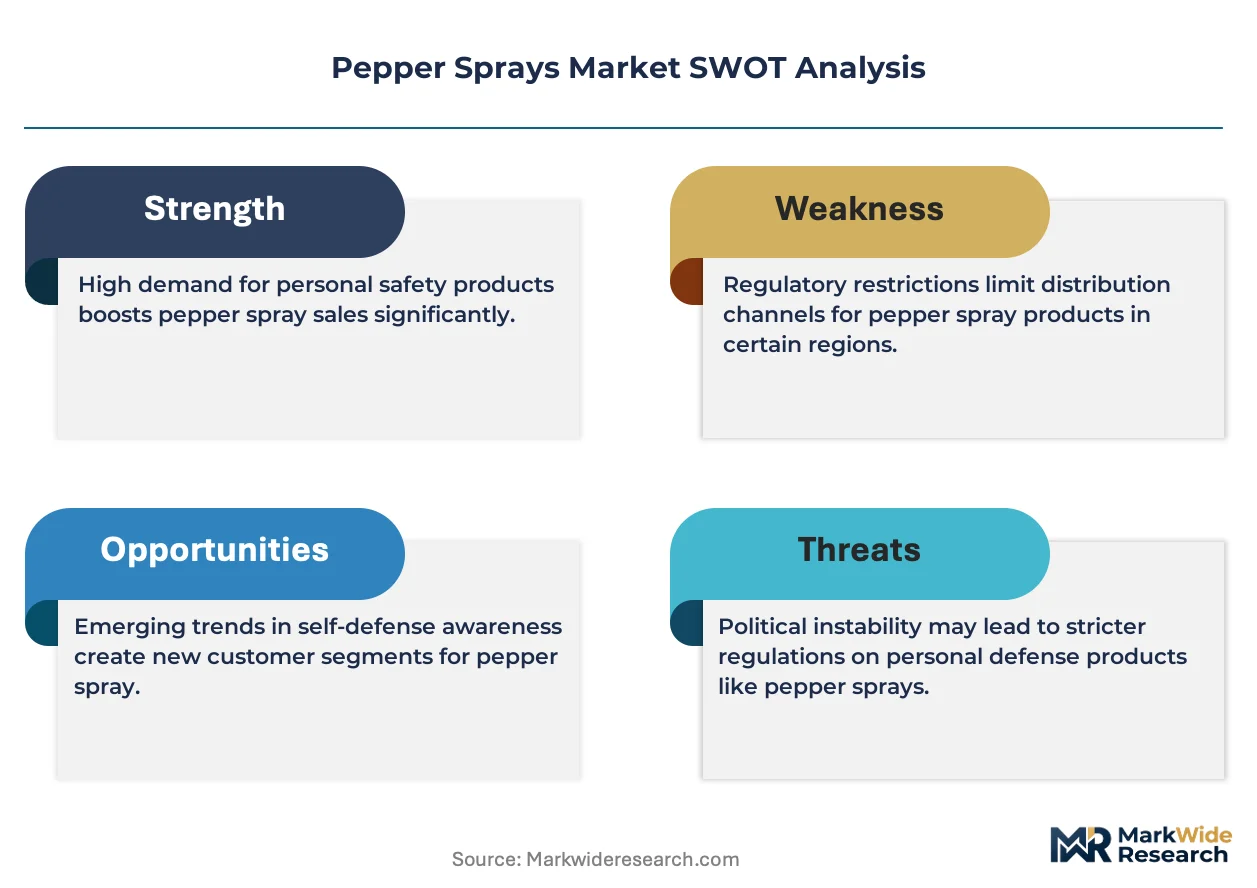
EPA regulates oleoresin capsicum devices as pesticides under FIFRA, requiring registration and label compliance before interstate commerce. CE marking under EU REACH frameworks governs aerosol propellant composition and canister pressure thresholds for European market access. ANSI standards for law enforcement less-lethal equipment further segment certification tiers. Stakeholders must monitor evolving state-level possession restrictions and propellant phase-out mandates to anticipate product reformulation cycles.
Market Dynamics
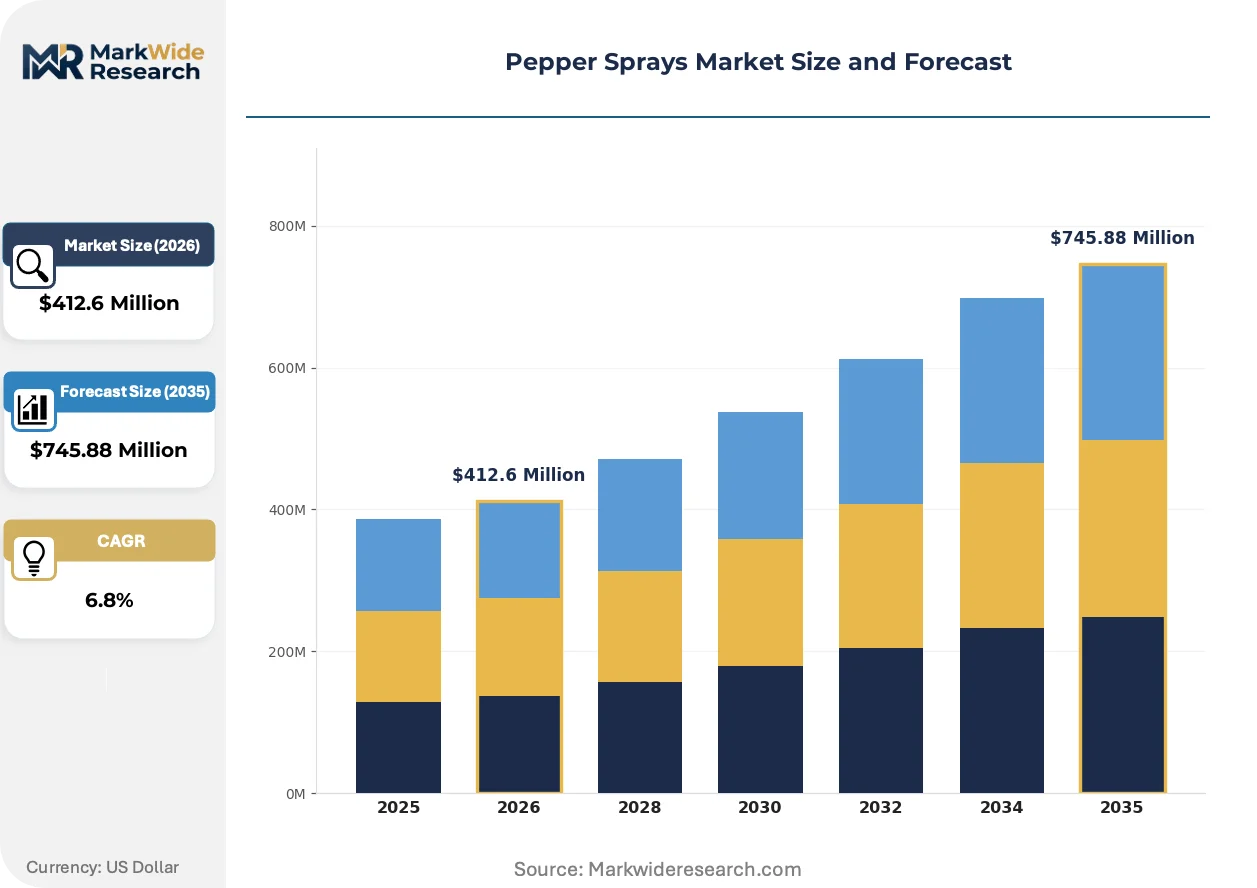
EPA registration requirements under FIFRA are compressing formulation cycles while civilian demand concentrates in metropolitan corridors with expanded concealed-carry frameworks. Manufacturers now face simultaneous pressure to tighten batch consistency and diversify oleoresin capsicum sourcing.
Growth Catalysts
- Concealed-carry regulatory expansion:Metropolitan jurisdictions across the United States are liberalizing personal defense device possession rules, directly enlarging the addressable consumer base for civilian-formulated products.
- Gel formulation technology:Reduced cross-contamination risk and targeted deployment accuracy are elevating premium positioning among law enforcement procurement officers evaluating less-lethal alternatives.
- Direct-to-consumer channel maturation:Online retail infrastructure now enables manufacturers to bypass traditional sporting goods intermediaries, capturing margin previously allocated to mass-market distributors.
Market Restraints
- Oleoresin capsicum supply concentration:Cultivation of high-Scoville Capsicum varieties clusters in specific subtropical growing regions, exposing blenders to climate-driven harvest volatility and price spikes.
- Propellant phase-out mandates:Environmental regulators in multiple jurisdictions are restricting hydrofluorocarbon aerosol carriers, forcing costly reformulation of existing canister architectures.
- Electroshock device substitution:Compact conducted electrical weapons are capturing share among urban commuters seeking reusable defense options with lower legal liability exposure.
Strategic Opportunities
- Underpenetrated European civilian segments:CE marking complexity has historically deterred North American manufacturers, creating first-mover advantage for firms mastering EU REACH aerosol compliance.
- Animal deterrent applications:Trail runners and rural property owners represent an adjacent demand pool currently served by diluted formulations with limited efficacy validation.
- Connected safety device convergence:Integration of GPS alert functionality and smartphone pairing is opening premium positioning at the intersection of personal defense and wearable technology.
Industry Challenges
- Toxicological assessment capacity scarcity:EPA registration demands extensive ocular and respiratory safety data, yet qualified contract research organizations with aerosol pesticide expertise operate at extended backlog.
- Batch-to-batch capsaicinoid variance:Natural extract sourcing introduces inherent potency inconsistency that conflicts with law enforcement procurement specifications requiring documented major capsaicinoid concentration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pepper Sprays Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stream, Gel, Foam, Spray End User: Law Enforcement, Personal Defense, Security Firms, Military Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Supermarkets Certification: ISO, CE, ANSI, NRCC |
| Companies Covered | Byrna, Counter Assault, Defense Technology, Fox Labs, Mace Brand, SABRE - Security Equipment Corp, UDAP Industries Inc., Zarc International Inc., J & L Self Defense Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pepper Sprays Market Strategic Shifts & Innovations
Formulation chemistry and delivery mechanisms are converging with digital connectivity and stricter environmental compliance, compressing traditional product lifecycles while opening premium tier positioning.
Micro-encapsulation technology is integrating oleoresin capsicum into polymer matrices that delay active release until target contact, extending shelf stability and reducing accidental self-exposure. Law enforcement agencies are piloting these formulations for crowd control scenarios where wind dispersion poses officer safety risks. The structural consequence is a bifurcation between legacy aerosol suppliers and specialty chemical firms with pharmaceutical coating expertise.
REACH regulatory expansion is tightening aerosol propellant composition thresholds across European member states, compelling reformulation toward compressed nitrogen or mechanical pump alternatives. Industrial consequence includes elevated R&D allocation for propellant-free architectures and accelerated obsolescence of existing CE-marked inventory. Manufacturers with integrated European blending facilities are responding faster than those dependent on transatlantic bulk shipment.
Subscription-based replenishment models are displacing single-unit retail purchases among urban professional women, the fastest-expanding demographic segment. Direct-to-consumer platforms now offer automated canister replacement tied to expiration date tracking and local legal compliance alerts. This behavioral shift is most visible in United States metropolitan corridors with high digital commerce penetration and complex municipal possession ordinances.
Pepper Sprays Market Segmentation
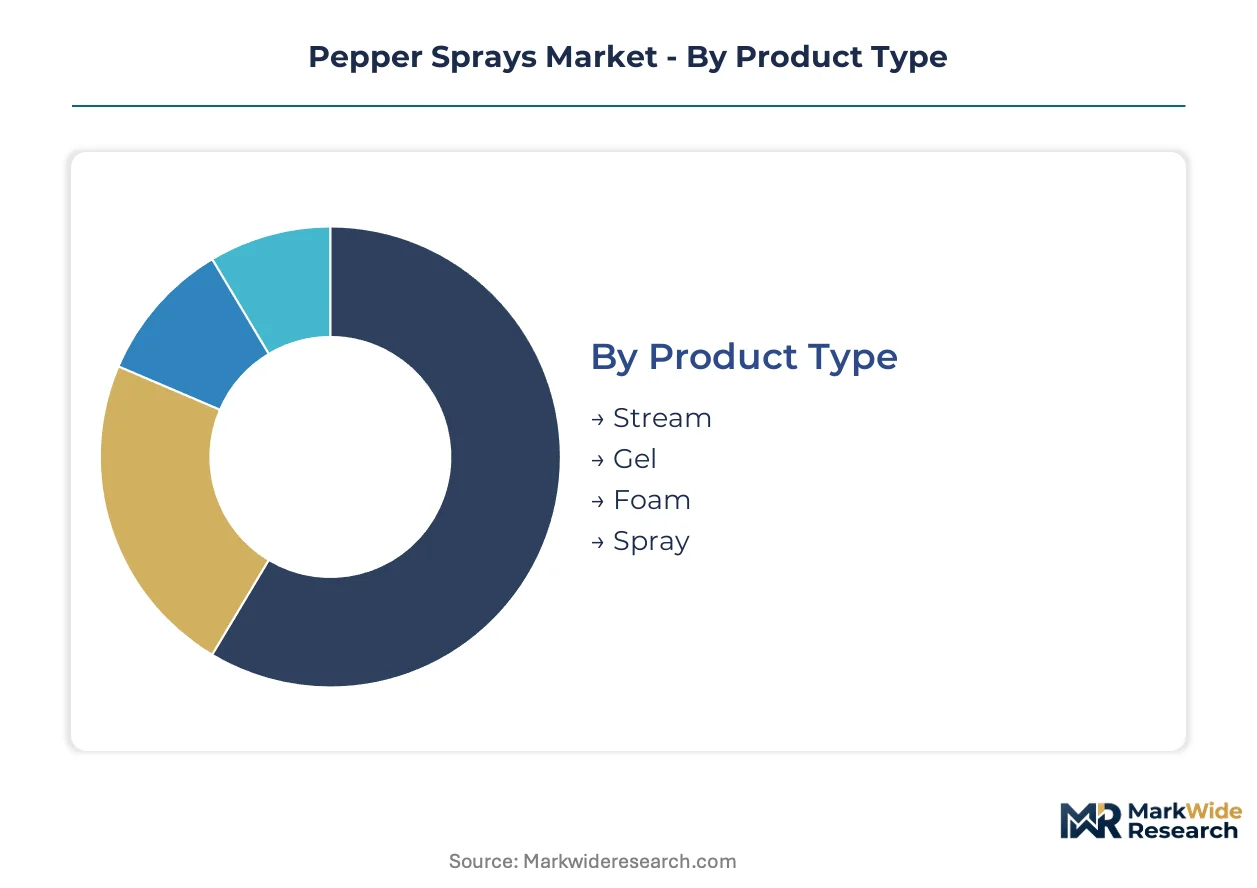
Product differentiation in pepper sprays hinges on deployment mechanics and environmental containment. Each segment carries distinct regulatory burdens and replacement-cycle profiles that reshape procurement economics across civilian and institutional buyers.
Product Type:
Upgrade cycles accelerate where formulation innovation reduces cross-contamination risk or improves target accuracy under stress conditions.
- Gel:Polymer-thickened oleoresin capsicum suspensions resist wind dispersal and adhere to facial surfaces on contact. Metropolitan law enforcement agencies in the United States prioritize gel for crowd control scenarios where officer safety demands precise trajectory control. Reduced blowback incidents justify premium positioning against legacy aerosol alternatives.
- Stream:Pressurized liquid projection delivers concentrated agent bursts with extended effective range. Security firms operating in confined indoor environments favor stream mechanics for minimized area saturation. Demand concentrates in commercial building protection contracts where ventilation system contamination carries liability exposure.
- Foam:Aerated formulations expand on target contact, creating visual marking and extended ocular coverage. Compact canister designs serve mobile security details requiring discrete carry profiles.
- Spray:Traditional aerosol mist disperses wide-area coverage for multiple threat engagement. Entry-level pricing sustains volume in mass-market civilian channels despite environmental susceptibility.
Gel sits at the top of the volume ranking, with foam climbing the fastest as security contractors adopt marking-enabled formulations.
End User:
Procurement sophistication varies sharply between institutional tendering and direct-to-consumer channels, fragmenting pricing architecture.
- Law Enforcement:Municipal and state agencies execute multi-year supply agreements with documented major capsaicinoid concentration requirements. EPA registration compliance and ANSI certification tiers dominate vendor selection criteria. Budget cycles extend 18-36 months, creating predictable replacement windows.
- Personal Defense:Urban commuters in concealed-carry jurisdictions drive the steepest expansion trajectory through subscription replenishment models. Digital commerce penetration enables manufacturers to bypass traditional retail intermediaries.
- Security Firms:Contract guarding operations balance agent efficacy against civil liability exposure in public-facing deployments. Training certification requirements vary by state, complicating standardization.
- Military:Non-lethal capability procurement integrates with broader riot control and area denial systems. Specification rigor exceeds civilian tiers with extended shelf-life demands.
Law Enforcement commands the procurement volume leadership, while Personal Defense gains share fastest through demographic expansion in professional urban women segments.
Distribution Channel:
Channel economics determine margin capture and regulatory compliance burden allocation between manufacturers and intermediaries.
- Online Retail:Direct-to-consumer platforms enable automated expiration tracking and jurisdiction-specific legal alert systems. Urban professional women in United States metropolitan corridors with complex municipal ordinances drive subscription model adoption.
- Specialty Stores:Sporting goods and outdoor retailers provide tactile evaluation and immediate fulfillment for first-time buyers. Staff training requirements elevate operational costs against digital alternatives.
- Direct Sales:Institutional tendering and enterprise security contracts bypass retail markup through manufacturer field representation. Relationship durability matters more than price in law enforcement procurement.
- Supermarkets:Mass-market placement captures impulse purchases with limited product education. Shelf space competition constrains premium formulation visibility.
Online Retail leads volume contribution, with Direct Sales expanding most quickly as security firms consolidate procurement through enterprise agreements.
Certification:
Compliance tier differentiation separates institutional-accessible products from consumer-grade alternatives with liability implications.
- ANSI:Law enforcement equipment standards specify performance testing for range, discharge duration, and major capsaicinoid concentration verification. Procurement officers in United States municipal agencies require ANSI compliance for tender eligibility.
- CE:European market access demands REACH aerosol propellant compliance and pressure threshold documentation. Manufacturers with integrated European blending facilities respond faster to regulatory shifts than transatlantic bulk shippers.
- ISO:Quality management certification supports enterprise and military procurement requiring documented batch consistency. Toxicological assessment capacity scarcity creates backlog advantages for pre-certified suppliers.
- NRCC:Canadian regulatory alignment with EPA FIFRA frameworks enables cross-border product standardization for North American manufacturers.
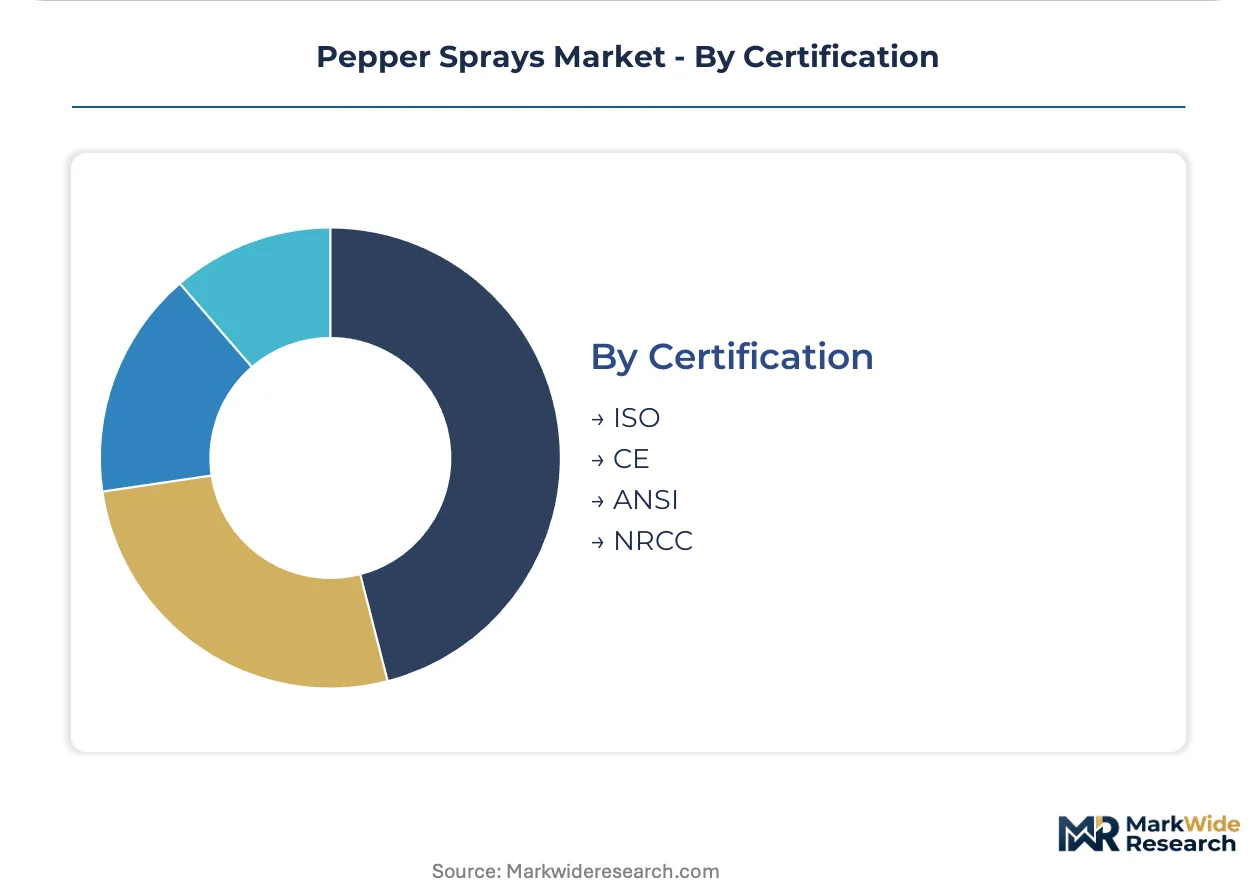
ANSI dominates institutional procurement specifications, with CE gaining priority fastest as European civilian liberalization creates first-mover opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States metropolitan corridors concentrate civilian procurement volume through direct-to-consumer platforms and expanded concealed-carry frameworks. EPA registration requirements under FIFRA govern interstate commerce, while state-level possession ordinances fragment municipal compliance.
United States
Urban professional women in metropolitan areas drive subscription-based replenishment adoption through automated expiration tracking. EPA FIFRA pesticide registration mandates batch consistency documentation for oleoresin capsicum formulations. Chicago, New York, and Los Angeles anchor demand concentration where municipal ordinances vary sharply.
Germany
Security firms and institutional buyers prioritize CE-marked formulations with REACH-compliant aerosol propellants. ECHA oversees chemical safety assessments under EU regulatory frameworks. Industrial procurement concentrates in North Rhine-Westphalia and Bavaria, where contract guarding operations standardize on documented pressure-threshold products.
Canada
Health Canada PMRA aligns pesticide registration with EPA FIFRA standards, enabling cross-border product standardization. NRCC certification supports federal and provincial law enforcement tendering. Ontario and Quebec host the dominant distribution infrastructure for North American manufacturers.
United Kingdom
Security sector procurement emphasizes ANSI-equivalent performance testing despite post-Brexit regulatory divergence. The Home Office governs personal defense device possession restrictions. Greater London and the Midlands concentrate contract guarding operations with enterprise-level procurement consolidation.
Australia
TGA and state-level weapons regulations create fragmented market access for civilian-formulated products. Victoria and New South Wales permit restricted personal defense possession with permit requirements. Sydney and Melbourne anchor demand through security firm procurement and outdoor recreation retail channels.
Pepper Sprays Market Key Industry Players
Global majors compete with regional champions across formulation chemistry and institutional tendering channels. The vendor base spans integrated blenders with captive oleoresin capsicum sourcing, specialty chemical firms with pharmaceutical coating expertise, and mass-market distributors with retail shelf dominance. Three archetypes predominate: vertically integrated manufacturers controlling batch consistency, formulation specialists pursuing concentrated capsaicinoid R&D, and channel-anchored brands with direct-to-consumer infrastructure. Competitive moves center on EPA registration capacity expansion and European blending facility integration.
Within the integrated manufacturing tier, SABRE - Security Equipment Corp and Fox Labs exemplify contrasting strategic positions. SABRE - Security Equipment Corp anchors North American procurement through in-house blending capabilities that govern batch-to-batch variance. Fox Labs occupies a position emphasizing concentrated formulation development. Mace Brand represents the mass-market channel archetype with retail distribution scale. These three entities illustrate how competitive positioning fragments across technical certification, formulation intensity, and consumer accessibility vectors.
| Leading Market Players |
|---|
| Byrna |
| Counter Assault |
| Defense Technology |
| Fox Labs |
| Mace Brand |
| SABRE - Security Equipment Corp |
| UDAP Industries Inc. |
| Zarc International Inc. |
| J & L Self Defense Products |
| Others |
Cost & Logistics Intelligence
Oleoresin capsicum extract costs cascade from subtropical cultivation zones through blending facilities to tiered retail positioning, with batch consistency premiums widening spreads between law enforcement procurement contracts and mass-market civilian canisters.
Pricing Analysis
Input-cost pass-through from capsaicinoid concentration volatility drives three-tier pricing stratification across premium gel formulations, standard stream deployments, and economy aerosol mist products. EPA registration tier and ANSI certification level command the widest price differentiation, while subscription replenishment models soften per-unit price sensitivity among urban professional women. Pricing pressure intensifies in the economy tier as imported alternatives compress margins, though law enforcement buyers exhibit lowest price sensitivity due to specification rigor and liability aversion.
Supply Chain Analysis
Domestic-content mandates under EPA FIFRA registration requirements are reshaping sourcing toward captive North American blending capacity. Oleoresin capsicum extraction concentrates in India, China, and select Central American growing regions, while canister manufacturing and propellant filling anchor in the United States and Germany. Supply chain risk centers on climate-driven harvest volatility in Capsicum cultivation belts, with distribution running through direct-to-consumer platforms, institutional tendering channels, and mass-market retail intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in gel formulation premiums and subscription model lifetime value capture, with EPA registration backlog creating scarcity rents for pre-certified suppliers.
For Market Incumbents: Extend ANSI-certified product lines into connected safety device convergence, integrating GPS alert functionality to defend against electroshock device substitution. Deepen in-house oleoresin capsicum blending capacity to control batch-to-batch variance that law enforcement procurement specifications increasingly document. Prioritize European blending facility integration to capture first-mover advantage as CE marking complexity historically deterred North American competitors. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription platforms targeting underpenetrated European civilian segments where REACH aerosol compliance mastery creates barrier advantages. Concentrate initial formulation development on animal deterrent applications for trail runners and rural property owners, an adjacent demand pool currently served by diluted formulations with limited efficacy validation. Exploit toxicological assessment capacity scarcity by partnering with pre-qualified contract research organizations holding aerosol pesticide expertise. For Investors and Strategic Acquirers: Consolidation pressure builds where EPA registration backlog advantages pre-certified suppliers with documented major capsaicinoid concentration capabilities. Long-term viability favors vertically integrated manufacturers with captive oleoresin capsicum sourcing and in-house blending infrastructure over formulation-dependent specialists. Watch for inflection signals in European civilian possession liberalization rates and state-level concealed-carry regulatory momentum.| Strategic Initiative | Industry Significance |
|---|---|
| EPA Registration Capacity Expansion | Backlog advantages for pre-certified suppliers accelerate tender eligibility capture in municipal law enforcement procurement. |
| European Blending Facility Integration | REACH aerosol propellant compliance mastery enables first-mover positioning in underpenetrated civilian segments. |
| Gel Formulation R&D Investment | Reduced cross-contamination risk justifies premium positioning in crowd control scenarios with officer safety demands. |
| Subscription Replenishment Model Launch | Automated expiration tracking tied to local legal compliance alerts captures lifetime value from urban professional women. |
| Connected Safety Device Convergence | GPS alert functionality and smartphone pairing opens premium tier positioning at personal defense and wearable technology intersection. |
Research Approach
Multiple input streams — executive interviews with formulation chemists and law enforcement procurement officers, regulatory filing analysis, and trade flow reconciliation — were triangulated against secondary validation from EPA FIFRA registration databases, ANSI certification records, and ECHA REACH aerosol propellant compliance documentation. Primary fieldwork engaged plant managers at oleoresin capsicum extraction facilities, security firm procurement leads, and direct-to-consumer platform operators. Bottom-up segment sizing across product type, end user, and distribution channel dimensions was cross-referenced with top-down market envelope constraints.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to anchor projection assumptions across the analysis window. Segmentation modeling incorporated deployment mechanics, certification tier, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves calibrated to oleoresin capsicum supply availability, concealed-carry regulatory momentum, and propellant phase-out mandate timelines. Forecast inputs included municipal law enforcement budget cycle patterns and digital commerce penetration rates in metropolitan corridors.
Several conditions sit outside the modeled scope, including abrupt regulatory bans on personal defense devices, breakthrough electroshock device cost reductions, and severe climate events disrupting Capsicum harvests in subtropical growing regions. Forecasts reflect assumptions about continued EPA registration requirement stability and gradual European civilian market liberalization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Safety
Night Vision Goggles Market
Personal Safety
Smart Personal Safety and Security Device Market
Personal Safety
Global Fall Protection Market
Personal Safety
Fall Detection System Market
Personal Safety
Global Medical Alert System/Personal Emergency Response System Market
Personal Safety
China Travel Safety Kits Market
Personal Safety
Concealable Vest Market
Personal Safety
Bulletproof Vest Market
Personal Safety
Smart Home Safety Market
Personal Safety
Body Armor and Personal Protection Market
Personal Safety
Child Leash Market
Personal Safety
Global Self Defense Products Market
Personal Safety
Asia-Pacific People Screening Market
Personal Safety
Life Jacket Market
Personal Safety
Pedestrian Protection Airbag Market
Personal Safety
Global Personal Emergency Response Systems (PERS) Market